
 Peer-To-Peer Lending Market | 2026-2036
Peer-To-Peer Lending Market Size, Share, and Industry Trends Forecast 2026-2036
Peer-To-Peer Lending Market Intelligence
Modular loan-product unbundling is restructuring how borrowers and capital providers interact on peer-to-peer platforms. LendingClub Bank leverages its bank charter to originate and hold loans on balance sheet, blending marketplace mechanics with traditional depository funding. Prosper Funding LLC sustains a pure marketplace model that specializes in unsecured consumer credit, while Upstart Network differentiates through AI-driven underwriting that navigates regulatory scrutiny on fair-lending algorithms.
Peer-to-peer lending denotes direct credit intermediation through digital platforms that match borrowers with non-bank investors, utilizing automated risk-scoring engines, fractional loan participation, and secondary market trading infrastructure to disintermediate conventional deposit-funded lending. Consumer lending platforms occupy the most mature segment with established secondary markets and standardized servicing protocols, whereas invoice financing represents the fastest-growing structural category as SMEs seek working-capital alternatives outside bank revolving facilities. Institutional investors increasingly dominate capital inflows into business lending pools, shifting platform economics toward wholesale funding relationships and away from retail fractional participation.
The Consumer Financial Protection Bureau enforces fair-lending and disclosure standards in the United States, while the Securities and Exchange Commission regulates platform note offerings as securities, creating dual compliance architecture that shapes product design and investor solicitation methods. The European Banking Authority coordinates national interpretations of the EU Crowdfunding Service Providers Regulation, producing fragmented licensing requirements that platforms must navigate across member states. Stakeholders should monitor how central bank digital currency pilots and instant payment rails reshape settlement velocity and disintermediation potential in retail credit markets.
Market Dynamics
Open banking API mandates across the European Union and United Kingdom are forcing peer-to-peer lending platforms to rebuild their onboarding and credit-decision infrastructure around real-time data access permissions rather than static borrower submissions.
Growth Catalysts
- EU Open Banking Framework:PSD2-mandated data sharing reduces verification friction for SME borrowers and cuts platform acquisition costs by eliminating manual document collection.
- Invoice Financing Automation:Embedded lending APIs within accounting software packages allow platforms to underwrite against live receivables data rather than historical financial statements.
- Institutional Capital Migration:Pension funds and insurance company investment mandates for private credit exposure are redirecting allocations from bank syndicated loans toward direct marketplace participation.
Market Restraints
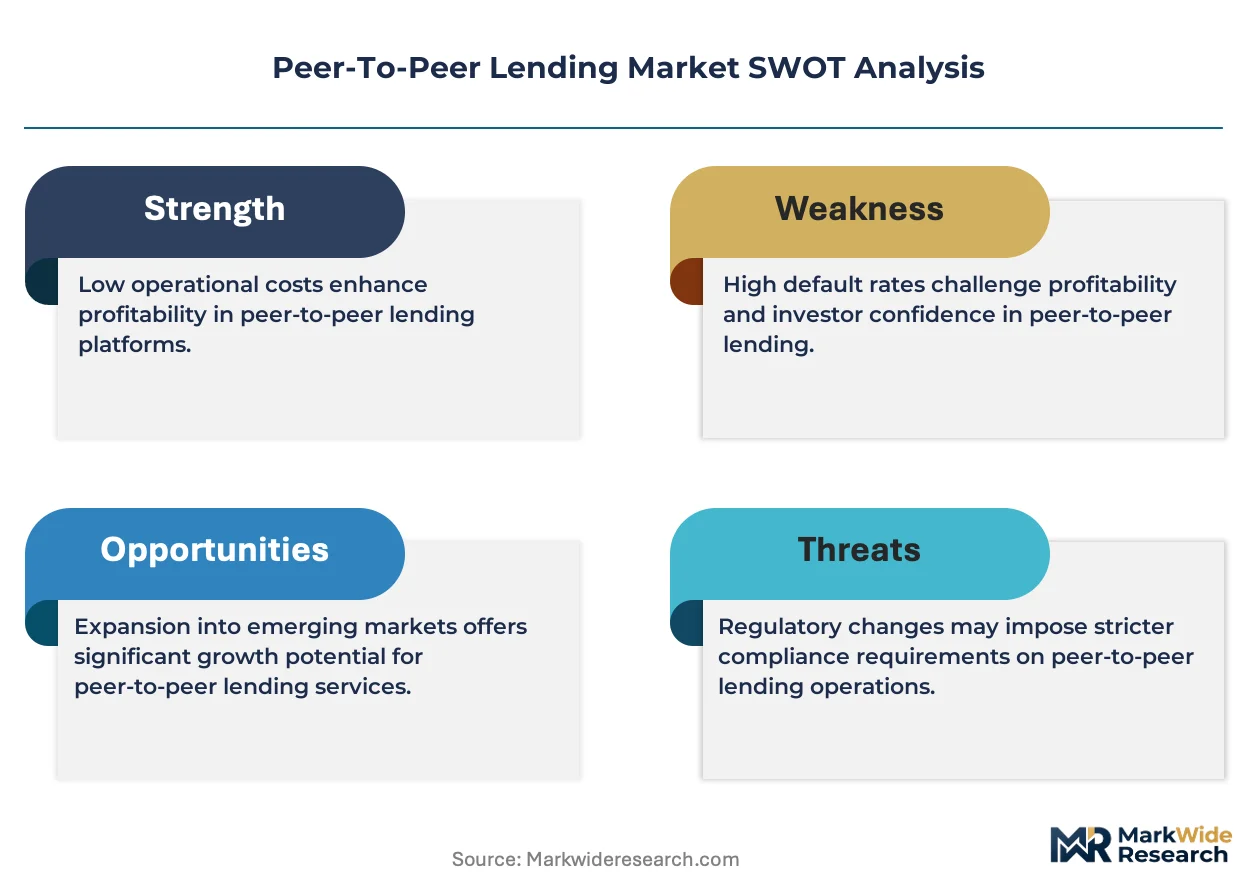
- Regulatory Arbitrage Compression:The SEC's treatment of platform notes as securities imposes disclosure and registration burdens that increase fixed compliance costs disproportionately for smaller marketplace operators.
- Bank Charter Advantage:Deposit-funded competitors with national bank charters access lower cost of capital through insured retail deposits, compressing net interest margin available to pure marketplace lenders.
- Credit Cycle Synchronization:Platform loan performance correlates tightly with consumer employment and small business revenue cycles, limiting diversification benefits during macroeconomic stress periods.
Strategic Opportunities
- Embedded Finance Partnerships:E-commerce platforms and vertical SaaS providers represent underserved distribution channels where lending APIs can be white-labeled at point of transaction.
- Carbon-Linked SME Products:Sustainability-linked loan structures tied to verified emissions reductions attract institutional capital pools with environmental mandate requirements.
- Instant Payment Rails:Central bank real-time settlement infrastructure enables same-day loan disbursement and repayment, reducing borrower working capital gaps and platform servicing overhead.
Industry Challenges
- Fair-Lending Algorithm Auditing:Regulatory scrutiny of machine learning credit models requires explainable AI frameworks and bias testing protocols that extend product development timelines.
- Secondary Market Liquidity Engineering:Fractional loan participation markets lack standardized pricing mechanisms and settlement infrastructure, constraining investor exit flexibility and portfolio rebalancing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Peer-To-Peer Lending Market |
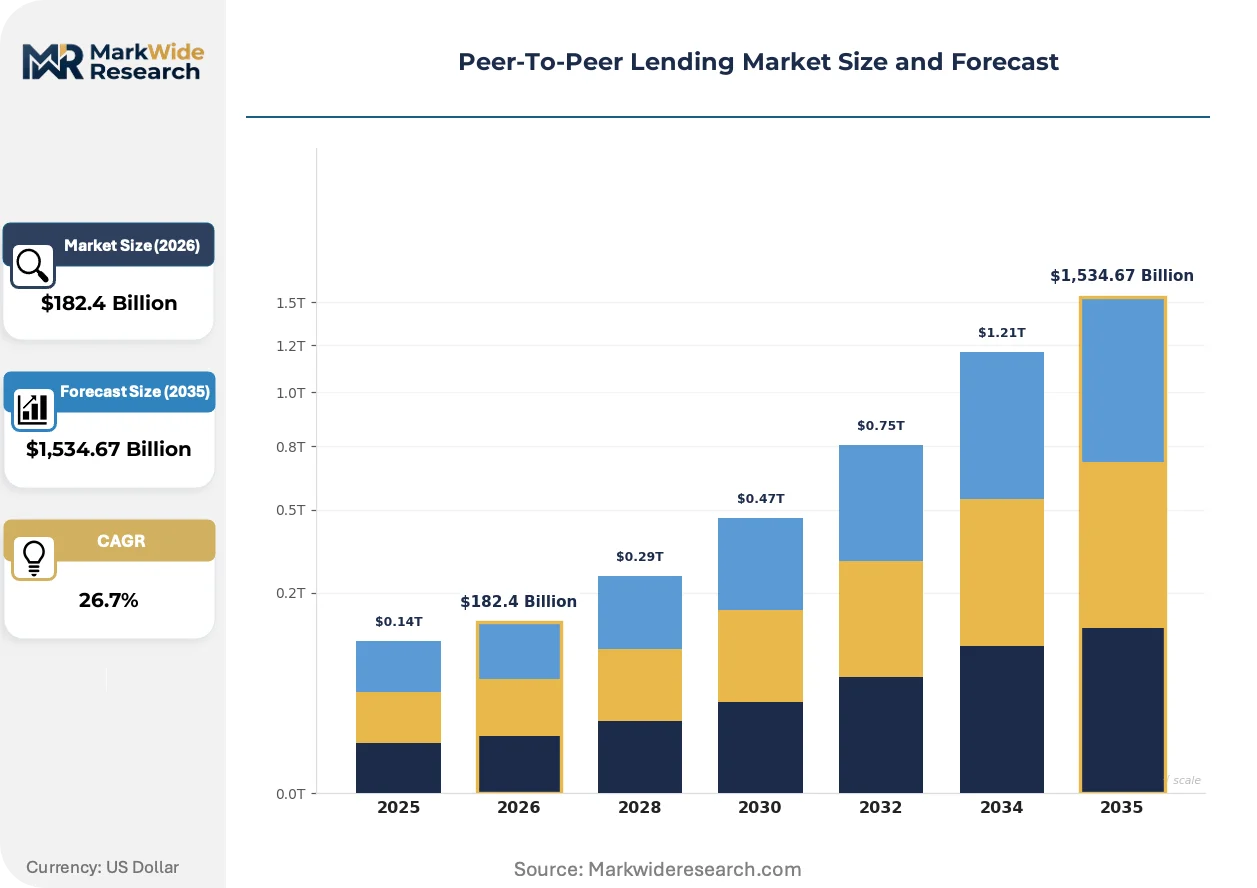
| Market Size in 2026 | $182.4 Billion |
| Market Size in 2035 | $1,534.67 Billion |
| CAGR (2026 – 2036) | 26.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Consumer Lending, Business Lending, Real Estate Lending, Student Loans, Invoice Financing Investor Type: Individual Investors, Institutional Investors, Venture Capitalists, Family Offices, Hedge Funds Loan Purpose: Debt Consolidation, Home Improvement, Medical Expenses, Business Expansion, Education Funding Credit Risk Category: Prime Borrowers, Near-Prime Borrowers, Subprime Borrowers, Secured Loans, Unsecured Loans |
| Companies Covered | LendingClub Bank, Prosper Funding LLC, Upstart Network, Lendermarket, PeerBerry, Proplend, RateSetter, AS Mintos Marketplace, Bondora Capital OÜ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Peer-To-Peer Lending Market Strategic Shifts & Innovations
Alternative data integration and automated underwriting pipelines are compressing the traditional credit assessment cycle from weeks to minutes, while regulatory technology investments consume an expanding share of platform operating budgets.
Machine learning models incorporating employment verification APIs, cash-flow analytics from bank transaction data, and behavioral signals from device metadata are rewriting how platforms price risk for thin-file borrowers previously excluded from prime credit tiers. Fintech lenders in the United States and United Kingdom have deployed these systems at scale, enabling instant approval decisions that match consumer expectations set by digital retail experiences. The structural consequence is a bifurcation between AI-native platforms and legacy scoring methodologies that rely on FICO-centric bureau reports.
The EU AI Act's risk-based classification framework for automated decision-making systems imposes documentation, human oversight, and transparency requirements on credit scoring algorithms deployed within the single market. Lenders must maintain technical files demonstrating bias mitigation and maintain appeal mechanisms for adverse decisions. Consumer lending platforms operating across Germany, France, and the Netherlands are restructuring their model governance functions to satisfy conformity assessment obligations before the enforcement timeline.
SME borrowers are consolidating their working capital relationships around platforms that bundle lending with payment processing, accounting integration, and treasury management tools rather than standalone credit products. This preference shift favors embedded finance models where credit is surfaced within operational software workflows rather than through dedicated marketplace destinations. The United Kingdom and United States exhibit the most pronounced migration, where vertical software penetration among small businesses creates natural distribution points for contextual lending offers.
Peer-To-Peer Lending Market Segmentation
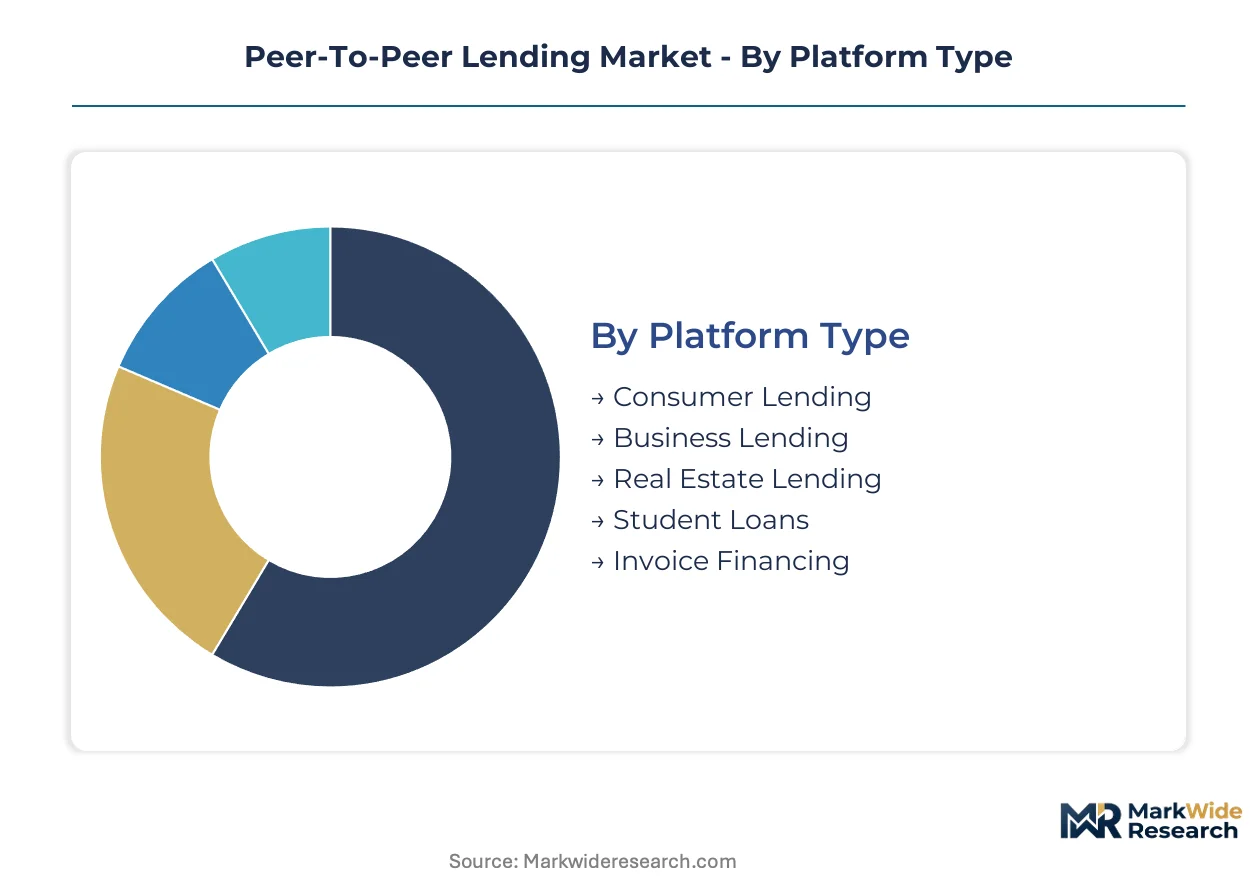
Segmentation in peer-to-peer lending determines platform architecture, regulatory treatment, and capital sourcing strategies. Each dimension shapes how borrowers access credit and how investors price risk across differentiated return profiles.
Platform Type:
Borrower acquisition economics and underwriting automation depth drive platform selection decisions across use cases.
- Consumer Lending:Unsecured personal credit products dominate transaction volumes with standardized scoring models and established secondary trading infrastructure. United States platforms originated this category and retain the deepest investor liquidity pools for fractional loan participation.
- Business Lending:SME working capital and growth financing commands expanding institutional capital allocations as traditional bank credit tightens for smaller enterprises. Open banking API mandates in the European Union and United Kingdom accelerate onboarding velocity through real-time cash flow verification.
- Real Estate Lending:Property-secured credit products offer investors collateral protection with loan-to-value covenants and geographic concentration limits.
- Student Loans:Education financing products face regulatory complexity around dischargeability and borrower protection standards in multiple jurisdictions.
- Invoice Financing:Embedded lending APIs within accounting software enable underwriting against live receivables data rather than historical financial statements.
Consumer Lending leads on scale; Invoice Financing leads on momentum.
Investor Type:
Capital source composition shifts platform economics toward wholesale funding relationships or retail fractional participation.
- Institutional Investors:Pension funds and insurance companies redirect private credit mandates from bank syndicated loans toward direct marketplace participation. These allocators demand standardized servicing protocols and portfolio-level risk reporting that smaller platforms struggle to provision.
- Individual Investors:Retail fractional participation built the peer-to-peer lending category but faces compression as platforms prioritize institutional capital efficiency.
- Venture Capitalists:Early-stage platform equity financing concentrates in technology-forward underwriting models and embedded finance distribution strategies.
- Family Offices:Direct lending allocations seek yield enhancement through specialty platforms with niche borrower verticals or geographic focus.
- Hedge Funds:Absolute return mandates exploit secondary market dislocations and distressed loan acquisition opportunities.
Institutional Investors lead on scale; Venture Capitalists lead on momentum.
Loan Purpose:
Borrower intent shapes underwriting data requirements, pricing tiers, and regulatory disclosure obligations.
- Debt Consolidation:Refinancing existing obligations attracts prime borrowers seeking rate reduction through platform efficiency advantages over incumbent bank channels.
- Business Expansion:Growth capital demand concentrates among SMEs excluded from traditional revolving credit facilities during monetary tightening cycles.
- Home Improvement:Property-secured renovation financing benefits from collateral valuation transparency and contractor payment verification protocols.
- Medical Expenses:Healthcare cost financing faces regulatory scrutiny around predatory pricing and borrower distress indicators.
- Education Funding:Tuition financing competes with government-subsidized loan programs and income-share agreement alternatives.
Debt Consolidation leads on scale; Business Expansion leads on momentum.
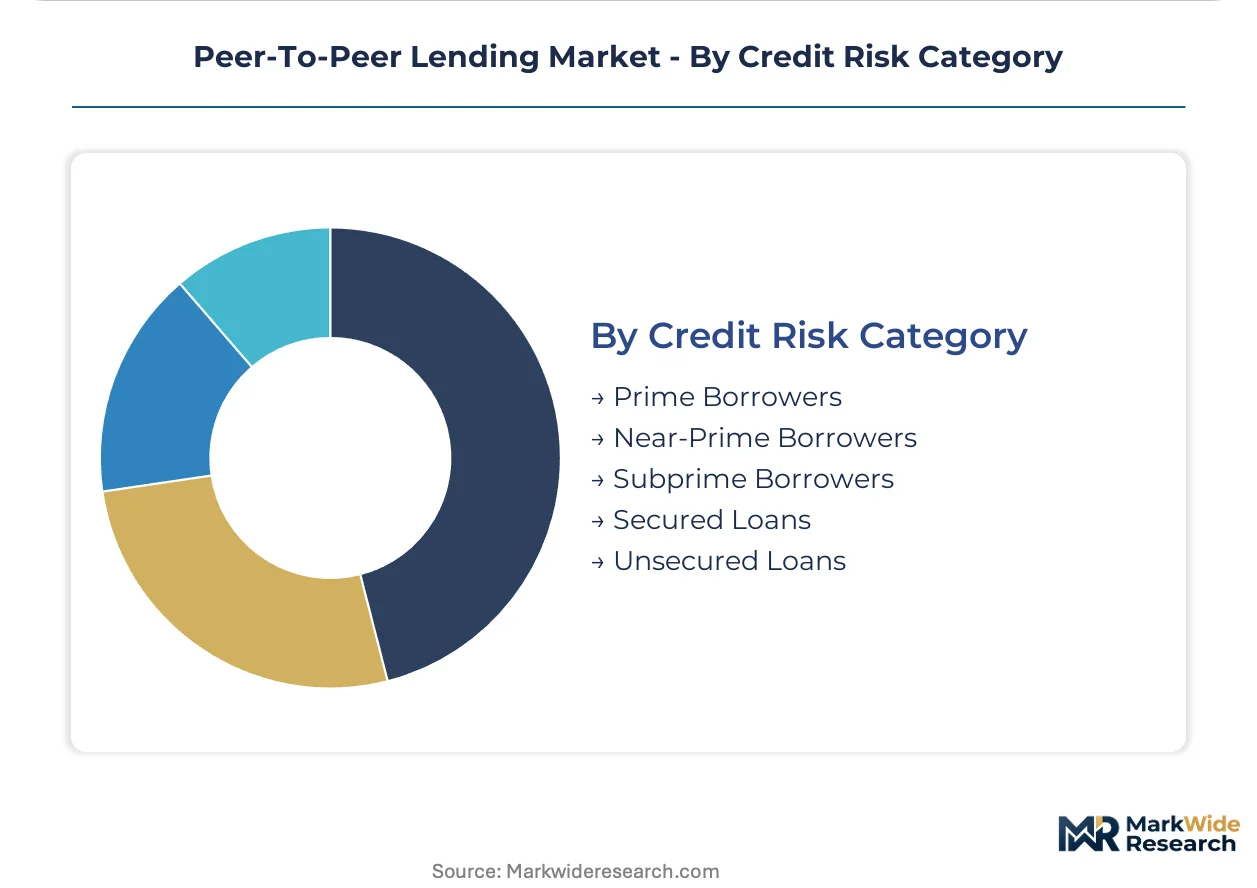
Credit Risk Category:
Risk tier segmentation determines pricing methodology, capital requirements, and investor return expectations.
- Prime Borrowers:High-FICO applicants with established credit histories command the tightest spreads and lowest default probability in platform portfolios. United States platforms compete aggressively for this segment through AI-driven instant approval experiences.
- Near-Prime Borrowers:Thin-file or recovering credit profiles attract alternative data underwriting models incorporating employment verification APIs and cash flow analytics.
- Subprime Borrowers:Higher-risk credit tiers face regulatory scrutiny on fair-lending algorithms and affordability assessment standards.
- Secured Loans:Collateral-backed products reduce loss severity but introduce asset valuation and liquidation complexity.
- Unsecured Loans:Pure credit risk products dominate marketplace volume with reliance on behavioral scoring and collection efficiency.
Prime Borrowers lead on scale; Near-Prime Borrowers lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Peer-to-peer lending originated in the United Kingdom with Zopa's 2005 launch, then scaled dramatically in the United States through marketplace platforms that attracted institutional capital. The industry now concentrates in jurisdictions with mature fintech infrastructure and permissive alternative lending regulations.
United States
SME working capital demand and consumer debt refinancing drive platform transaction volumes. The SEC regulates platform note offerings as securities under the Securities Act of 1933, creating compliance architecture that favors scaled operators. Silicon Valley and New York City host the deepest investor liquidity pools and underwriting technology clusters.
United Kingdom
Open banking API mandates under PSD2 accelerate onboarding velocity for SME borrowers. The Financial Conduct Authority supervises peer-to-peer platforms under the Financial Services and Markets Act 2000, with specific crowdfunding regulations introduced in 2014. London concentrates platform headquarters and institutional investor relationships.
Germany
Invoice financing demand from Mittelstand manufacturers seeking working capital alternatives propels platform adoption. BaFin licenses platforms under the Payment Services Supervision Act and EU Crowdfunding Service Providers Regulation. Berlin and Frankfurt host emerging fintech clusters specializing in B2B lending automation.
China
Small business credit gaps and consumer installment demand created massive addressable markets before regulatory tightening. The People's Bank of China and banking regulator imposed strict caps on platform leverage and interest rates in 2020. Shanghai and Shenzhen retain residual platform operations focused on supply chain finance.
Estonia
Cross-border marketplace lending to European consumers and SMEs operates from this Baltic jurisdiction with favorable e-residency frameworks. The Estonian Financial Supervision Authority licenses platforms under EU passporting arrangements. Tallinn serves as headquarters for several pan-European lending marketplaces leveraging digital infrastructure.
Peer-To-Peer Lending Market Key Industry Players
The competitive structure tilts toward bank-charter hybrids that blend marketplace mechanics with balance-sheet lending. Tiered concentration separates scaled national operators from regional specialists and technology-forward challengers. Two strategic archetypes dominate: deposit-funded marketplace banks and pure digital originators dependent on institutional capital partnerships. Consolidation through bank charter acquisitions and embedded finance distribution partnerships represent the prevailing competitive vectors.
Among United States-based operators, LendingClub Bank and Prosper Funding LLC exemplify divergent strategic paths—one leveraging a national bank charter for balance-sheet flexibility, the other sustaining pure marketplace mechanics. Upstart Network occupies a position within the AI-native underwriting tier, representing technology-forward challengers navigating regulatory scrutiny on algorithmic credit decisions. These three anchors illustrate how platform economics fragment across funding models and risk-scoring methodologies.
| Leading Market Players |
|---|
| LendingClub Bank |
| Prosper Funding LLC |
| Upstart Network |
| Lendermarket |
| PeerBerry |
| Proplend |
| RateSetter |
| AS Mintos Marketplace |
| Bondora Capital OÜ |
| Others |
Cost & Logistics Intelligence
Institutional capital allocators dominate capital inflows into peer-to-peer lending pools, anchoring platform economics to wholesale funding relationships rather than retail fractional participation. This buyer concentration compresses origination fees and servicing spreads as pension funds and insurance companies negotiate portfolio-level pricing.
Pricing Analysis
Three-tier pricing structure across premium, standard, and subprime borrower segments governs platform revenue models. Price differentiation hinges on AI underwriting sophistication and regulatory compliance investment, with FICO-centric legacy platforms commanding narrower spreads than alternative-data-native competitors. Pricing pressure stems from bank-charter hybrids accessing insured deposit funding at lower cost of capital. Subprime borrower segments exhibit highest price sensitivity, while prime borrowers with established credit histories demonstrate elasticity toward instant approval experiences over rate minimization.
Supply Chain Analysis
Direct-to-institutional-investor channels handle bulk capital deployment, while retail fractional participation markets feed through secondary trading infrastructure. Platform technology development concentrates in the United States, the United Kingdom, and Estonia, with regulatory technology vendors clustering in London and New York. Raw material dependencies include cloud computing infrastructure, employment verification APIs, and credit bureau data feeds. Single-source vulnerability in alternative data providers poses concentration risk. Distribution runs through embedded finance partnerships with vertical SaaS providers and accounting software platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Peer-to-peer lending platforms operate as margin-expansion stories where AI-driven automation reduces origination costs and institutional capital partnerships shift revenue mix toward higher-yielding near-prime segments.
For Market Incumbents: Anchor defensive positioning through bank charter acquisition or partnership to access insured deposit funding and compress cost of capital. Deepen vertical integration into loan servicing infrastructure to capture recurring revenue streams and reduce third-party dependency. The SEC's securities treatment of platform notes threatens smaller marketplace operators with disproportionate compliance burdens.
For New Entrants and Emerging Players: Capture white-space opportunity in carbon-linked SME lending products where sustainability mandates attract institutional capital pools with environmental investment criteria. Invoice financing APIs embedded within accounting software represent the most penetrable segment, with United Kingdom and United States small businesses showing strongest migration toward contextual lending offers. Pursue white-label distribution partnerships with vertical SaaS providers rather than standalone marketplace builds.
For Investors and Strategic Acquirers: Technology-forward regional banks pursuing fintech capability acquisition represent the most active strategic buyer category in this space. Target platforms with demonstrated AI-native underwriting and existing institutional capital relationships for acquisition. Watch central bank digital currency pilot progress as inflection indicator for settlement velocity disruption and platform disintermediation risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Bank Charter Acquisition | Deposit funding access compresses cost of capital versus pure marketplace models. |
| Embedded Finance Partnership | Vertical SaaS distribution reduces customer acquisition costs for SME lending. |
| AI Model Governance Investment | EU AI Act compliance documentation satisfies regulatory scrutiny on algorithmic decisions. |
| Institutional Capital Relationship | Pension fund allocations redirect from bank syndicated loans toward direct marketplace participation. |
| Instant Payment Rail Integration | Real-time settlement infrastructure enables same-day disbursement and reduces servicing overhead. |
Research Approach
Direct dialogue with peer-to-peer lending platform executives, institutional investor portfolio managers, regulatory affairs specialists, and embedded finance partnership leads grounded the qualitative foundation. Secondary validation drew from SEC filings, EU Crowdfunding Service Providers Regulation implementation reports, open banking API documentation, and central bank digital currency pilot disclosures. Bottom-up origination volume analysis triangulated against top-down capital flow estimates from pension fund and insurance company allocation surveys.
Segmented outputs across platform type, investor category, loan purpose, and credit risk tier informed the analytical framework throughout the projection horizon. CAGRs derived from historical origination trajectories, capital formation velocity, and regulatory implementation timelines. Near-prime borrower expansion and invoice financing automation served as primary demand-side forecast inputs, while open banking API penetration and institutional capital migration shaped supply-side modeling.
Underlying measurement precision varies by segment; consumer lending platforms with established secondary markets carry tighter precision than emerging invoice financing categories. Forecasts reflect assumptions around regulatory stability, credit cycle positioning, and technology adoption curves. Stress-testing of base assumptions around central bank digital currency deployment and AI Act enforcement timelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Loans and Leasing
Global Revenue-Based Financing Market
Loans and Leasing
France Car Loan Market
Loans and Leasing
Embedded Lending Market
Loans and Leasing
United Kingdom Auto Loan Market
Loans and Leasing
Commercial Vehicle Rental and Leasing Market
Loans and Leasing
Auto Finance Market
Loans and Leasing
China Mortgage/Loan Brokers Market
Loans and Leasing
Europe Car Loan Market
Loans and Leasing
Solar Lease Service Market
Loans and Leasing
Mexico Home Equity Lending Market
Loans and Leasing
Japan Mortgage/Loan Brokers Market
Loans and Leasing
Truck Financial Leasing Market
Loans and Leasing
Canada Home Equity Lending Market
Loans and Leasing
Battery Leasing Service Market
Loans and Leasing
Premium Finance Market
Loans and Leasing
US Auto Loan Market