
 North America Liability Insurance Market | 2026-2036
North America Liability Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
North America Liability Insurance Market Analytics
Canadian specialty underwriters is rebalancing capacity toward cyber liability lines after years of concentrating on traditional commercial packages. State Farm leverages its captive agency network to sustain dominant personal lines penetration across the U.S. Midwest. Berkshire Hathaway anchors its position through underwriting discipline and vast float generation at its core insurance subsidiaries.
North America liability insurance constitutes risk-transfer contracts that indemnify policyholders against third-party claims for bodily injury, property damage, or financial loss, with terms governed by occurrence or claims-made triggers, coverage limits, and retroactive dates. These instruments enable businesses and individuals to continue operations without catastrophic balance-sheet impairment from unpredictable legal exposure. Professional liability coverage leads premium growth as technology firms and healthcare practices face intensifying litigation frequency. Corporations drive high-limit and excess liability demand, while small businesses gravitate toward packaged general liability solutions with streamlined underwriting.
The U.S. Department of Labor and state insurance commissioners shape market conduct through workers compensation mandates, rate filing approvals, and solvency surveillance that directly determine product availability and pricing latitude. Canada's Office of the Superintendent of Financial Institutions imposes capital adequacy requirements that filter into coverage terms and market entry barriers for foreign carriers. Stakeholders must monitor how artificial intelligence in claims adjudication interacts with evolving state-level biometric privacy statutes to anticipate coverage gaps and emerging E&O exposures.
Market Dynamics
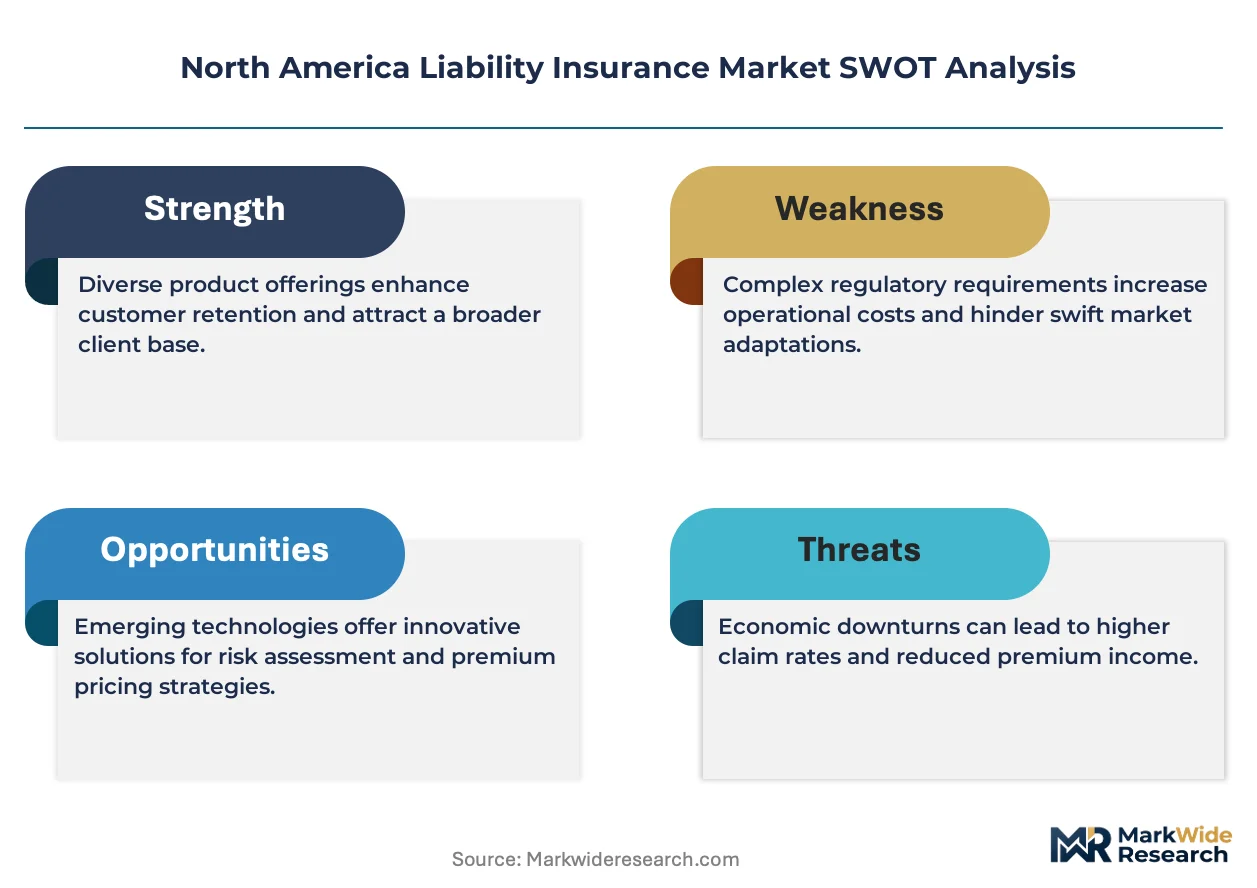
The North America liability insurance market is experiencing structural pressure from artificial intelligence deployment in claims adjudication, which is compressing settlement timelines while exposing carriers to algorithmic bias litigation and regulatory scrutiny under emerging biometric privacy statutes.
Growth Catalysts
- OSHA workplace safety mandates:The U.S. Department of Labor's evolving enforcement protocols are compelling employers across manufacturing and logistics to expand workers compensation and general liability limits, directly expanding premium pools in industrial corridors.
- Healthcare malpractice frequency:Rising litigation against physician practices and hospital systems is accelerating professional liability uptake, particularly in states with favorable plaintiff venues like Florida and Illinois.
- Cyber liability line expansion:Canadian specialty underwriters are reallocating capacity from traditional commercial packages toward cyber coverage, responding to ransomware exposure in Toronto's financial services cluster.
Market Restraints
- Reinsurance cost volatility:Catastrophe bond spreads and retrocession pricing swings are compressing underwriting margins for primary carriers writing high-limit excess liability.
- California regulatory friction:Proposition 103's rate approval delays and prior-approval requirements are constraining pricing responsiveness in the country's largest state market.
- Social inflation in jury awards:Nuclear verdict escalation in trucking and product liability cases is forcing capacity withdrawal from long-haul transportation risks.
Strategic Opportunities
- Mexico nearshoring corridor:Manufacturing relocation to Baja California and Nuevo León is generating directors and officers liability demand for cross-border operations with U.S. parent company exposure.
- Parametric trigger innovation:Convergence of IoT sensor networks with blockchain-based smart contracts enables automated indemnity payments for predefined cyber business interruption events.
- Embedded distribution channels:Partnerships with vertical SaaS platforms serving legal, accounting, and healthcare practice management software are creating frictionless professional liability purchase points at policy renewal junctures.
Industry Challenges
- Actuarial talent scarcity:The shortage of professionals skilled in machine learning model validation and AI-driven reserving methodologies is delaying product development cycles for algorithmic underwriting tools.
- Legacy system integration friction:Policy administration platforms built on decades-old architectures require expensive middleware development to interface with real-time data feeds from telematics and cyber monitoring services.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Liability Insurance Market |
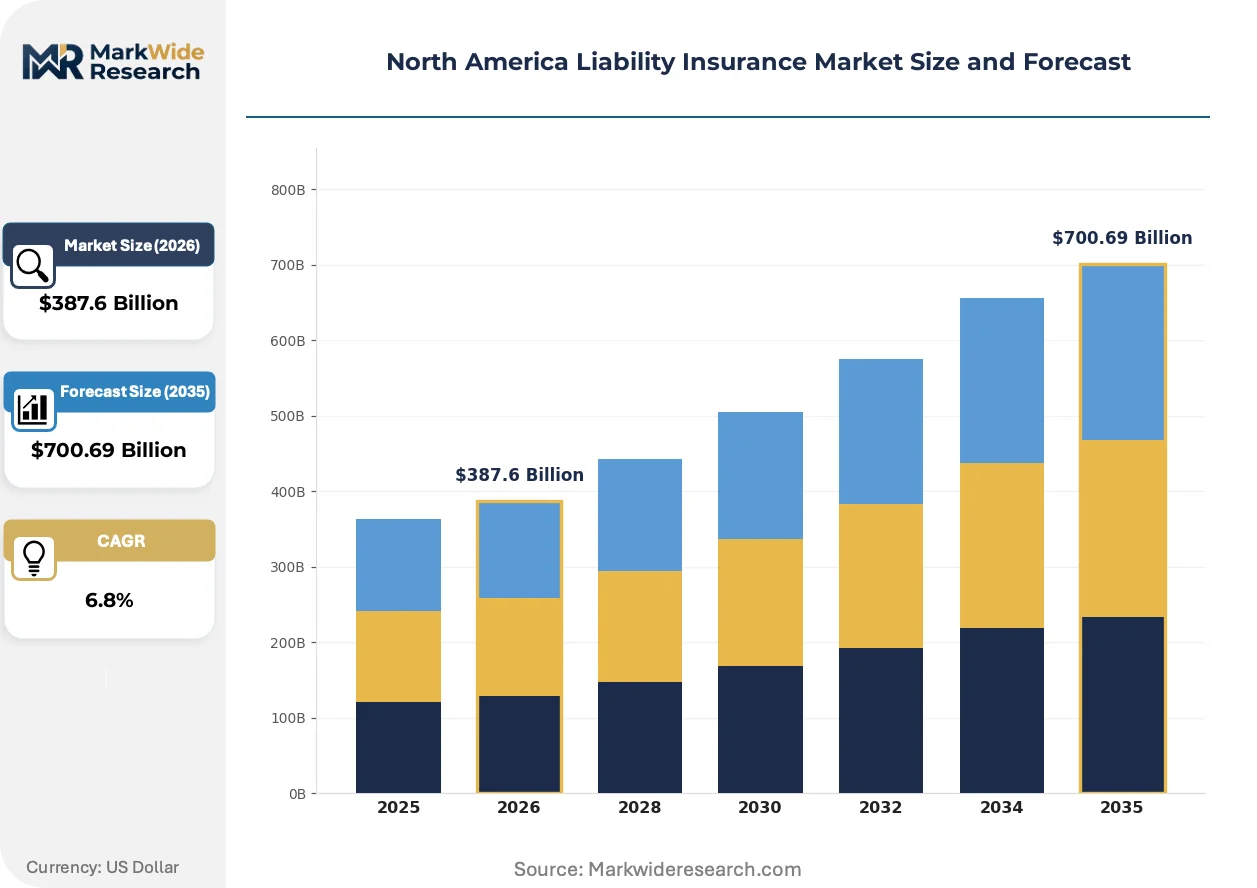
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $700.69 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: General Liability, Professional Liability, Product Liability, Employer's Liability Customer Type: Individual Consumers, Small Businesses, Corporations, Nonprofits Industry Vertical: Construction, Healthcare, Retail, Technology Coverage Limit: Low Limit, Medium Limit, High Limit, Excess Liability |
| Companies Covered | State Farm, Berkshire Hathaway, Progressive, Allstate, Liberty Mutual, Travelers, USAA, Chubb Limited, Nationwide, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Liability Insurance Market Evolving Landscape
Artificial intelligence is fundamentally restructuring how liability carriers assess, price, and settle claims, creating competitive separation between technology-enabled underwriters and those dependent on traditional manual processes.
Predictive analytics engines are integrating structured claims data with unstructured legal document analysis to forecast litigation outcomes and optimize reserve adequacy. Mid-market commercial carriers in Texas and Ohio are deploying these tools most aggressively, compressing claim cycle times from months to weeks. This capability is integrating actuarial science with legal strategy, enabling dynamic pricing adjustments that reflect real-time litigation risk rather than historical loss ratios.
The U.S. Department of Labor's forthcoming heat illness prevention standard and state-level biometric privacy statutes in Illinois, Texas, and Washington are expanding the scope of employer liability beyond traditional physical injury. Carriers are responding with endorsement modifications that explicitly address thermal stress claims and facial recognition data breaches. Technology sector employers with distributed workforces face the most acute compliance burden, driving demand for integrated employment practices liability and cyber coverage.
Corporate risk managers are consolidating vendor relationships and demanding multi-line packaged solutions with unified data dashboards. This concentration is displacing single-line specialists in the middle market, particularly among professional services firms with 50-500 employees. The shift is most visible in New York and California, where broker consolidation and direct carrier platforms are compressing commission structures and accelerating policy lifecycle digitization.
North America Liability Insurance Market Segmentation
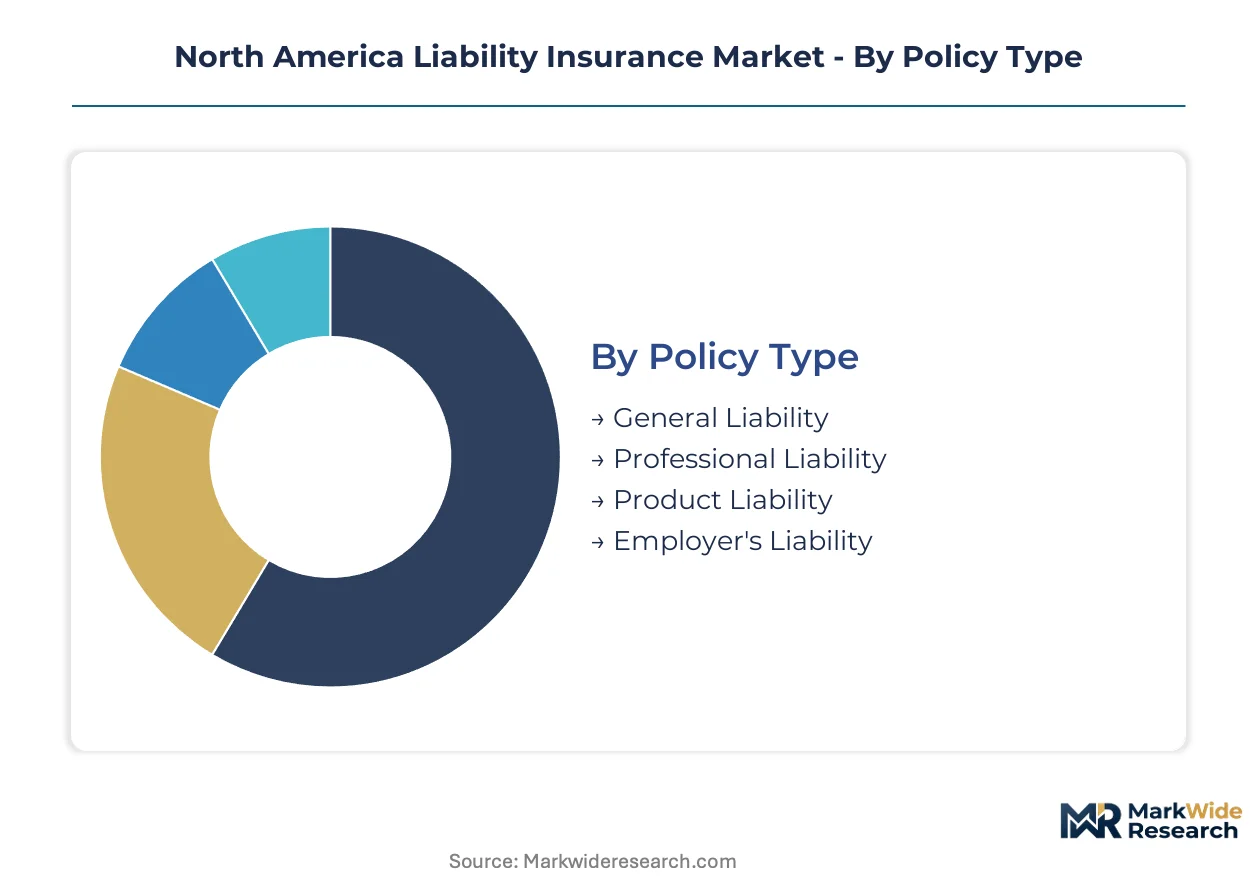
Liability insurance segmentation reflects how risk profiles, regulatory exposure, and purchasing power fragment across buyer types. Carriers calibrate underwriting appetite, distribution channels, and pricing models against these divisions to optimize capital deployment.
Policy Type:
Replacement cycles vary sharply across policy structures, with claims-made contracts demanding more frequent coverage reviews than occurrence-based alternatives.
- General Liability:Occurrence-triggered contracts covering bodily injury and property damage from business operations. Demand concentrates in Texas construction corridors where OSHA enforcement intensity drives limit expansion.
- Professional Liability:Claims-made coverage indemnifying against errors, omissions, and negligence in professional services. California technology clusters and Illinois healthcare systems are driving uptake amid intensifying malpractice and D&O litigation frequency.
- Product Liability:Defective product claims coverage with long-tail exposure stretching across manufacturing and distribution chains.
- Employer's Liability:Workplace injury claims outside statutory workers compensation, critical for self-insured retention programs in manufacturing-heavy Midwestern states.
Volume placements concentrate in General Liability; the faster expansion belongs to Professional Liability.
Customer Type:
Cost tiers separate buyers by premium scale and servicing complexity, from automated direct-to-consumer platforms to captive brokers managing multinational programs.
- Corporations:Complex risk profiles requiring layered excess programs and manuscripted endorsements. Fortune 1000 manufacturing and energy firms in Ohio and Louisiana anchor premium concentration through high-limit placements.
- Small Businesses:Packaged BOP solutions with streamlined underwriting and embedded cyber endorsements. Toronto's professional services corridor and Austin's startup ecosystem are accelerating digital distribution adoption.
- Individual Consumers:Personal umbrella and homeowners liability extensions sold through agency networks.
- Nonprofits:Mission-driven organizations with unique D&O and volunteer liability exposures requiring specialized nonprofit program administrators.
Premium concentration sits with Corporations; Small Businesses are climbing the fastest as embedded distribution lowers purchase friction.
Industry Vertical:
Application-specific risk characteristics dictate coverage structure, with sectoral regulation and litigation patterns driving product differentiation.
- Healthcare:Physician practices, hospital systems, and allied health providers facing malpractice frequency escalation. Florida and Illinois plaintiff-friendly venues are accelerating limit expansion and claims-made trigger adoption.
- Technology:Software firms, data centers, and platform operators confronting cyber liability and D&O exposure. Silicon Valley and Seattle cloud infrastructure clusters are driving integrated cyber-EPLI packaged solutions.
- Construction:Contractor default, wrap-up liability, and completed operations coverage for project-specific exposures.
- Retail:Premises liability, product recall, and employment practices coverage for storefront and e-commerce operations.
Placement volume concentrates in Healthcare; Technology is gaining share fastest on cyber line expansion.
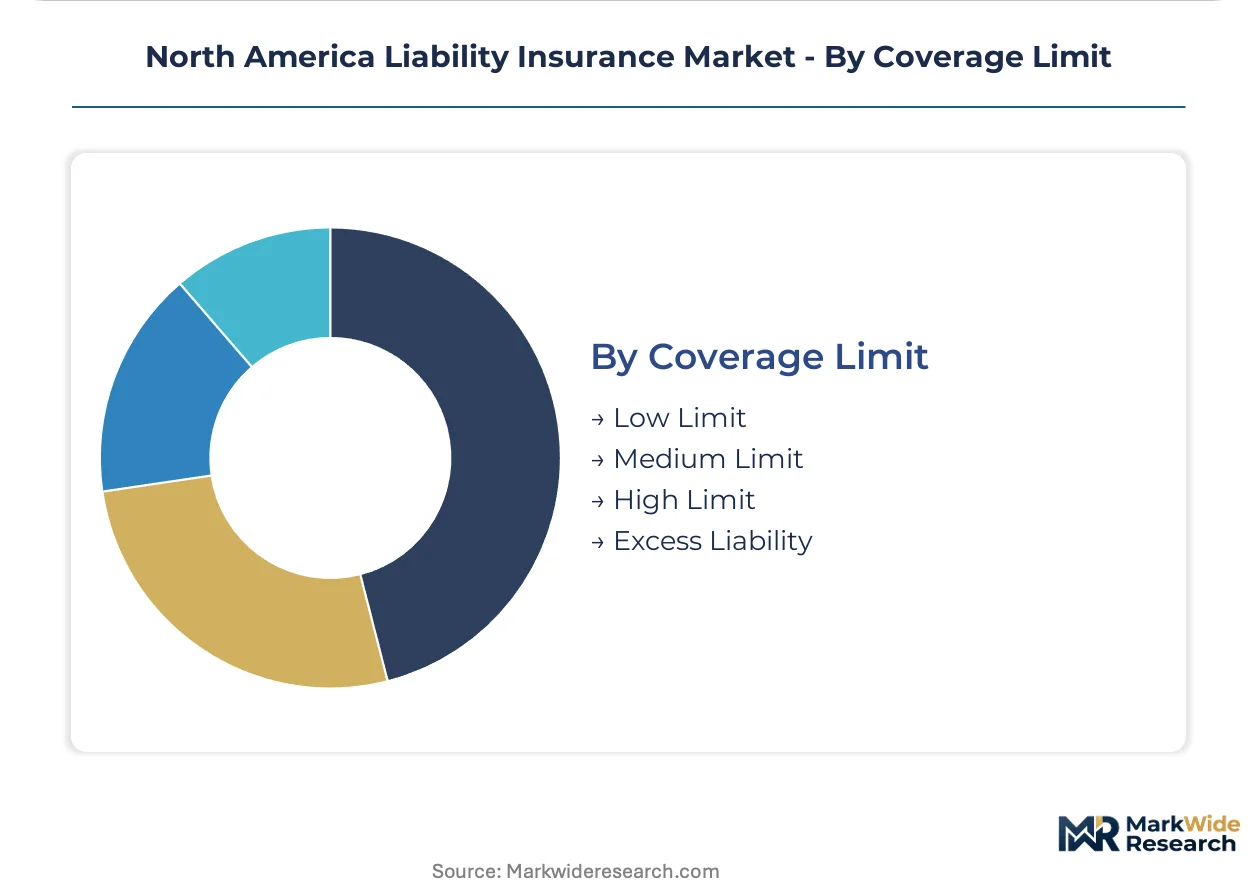
Coverage Limit:
Margin profiles stratify across limit tiers, with excess layers commanding specialized reinsurance relationships and primary layers competing on distribution efficiency.
- High Limit:Umbrella and excess programs starting at $10 million attachment points for Fortune 1000 manufacturing and energy risks. Houston petrochemical corridors and Detroit automotive supply chains anchor capacity demand.
- Excess Liability:Super-catastrophic layers above $100 million requiring alternative capital and catastrophe bond sponsorship. Bermuda and London market reinsurers dominate this segment for North American industrial risks.
- Medium Limit:$1-10 million primary and umbrella solutions for mid-market commercial accounts.
- Low Limit:Standard $1-2 million general liability baselines for small business packaged policies.
Capacity deployment concentrates in High Limit placements; Excess Liability shows steepest expansion trajectory on alternative capital inflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas petrochemical corridors and Illinois manufacturing belts anchor North American liability underwriting capacity, with regional variation in regulatory intensity and industrial specialization driving premium dispersion across sub-markets.
United States
California's technology corridor generates concentrated directors and officers liability demand from startup density, while Florida's plaintiff-friendly venues accelerate healthcare malpractice limit expansion. OSHA workplace safety mandates from the U.S. Department of Labor compel manufacturing and logistics employers across Ohio and Michigan to strengthen workers compensation and general liability coverage. Houston's energy sector anchors high-limit excess liability placements for petrochemical and offshore risks.
Canada
Toronto's financial services cluster drives cyber liability line expansion as ransomware exposure escalates among banks and asset managers. The Office of the Superintendent of Financial Institutions imposes capital adequacy requirements that filter into coverage terms and create entry barriers for foreign carriers. Canadian specialty underwriters are reallocating capacity from traditional commercial packages toward cyber coverage, rebalancing underwriting portfolios.
Mexico
Manufacturing relocation to Baja California and Nuevo León generates directors and officers liability demand for cross-border operations with U.S. parent company exposure. Nearshoring momentum in automotive and electronics assembly creates professional liability uptake for Mexican subsidiaries requiring D&O protection aligned with U.S. securities litigation standards. Mexico City anchors commercial insurance distribution for multinational corporate programs.
North America Liability Insurance Market Competitive Landscape
Global majors compete with regional champions across distribution architecture and underwriting specialization, producing a tiered structure where scale-driven personal lines carriers coexist with commercial-focused specialists. The market fragments across captive agency networks, direct-to-consumer platforms, and broker-mediated wholesale channels. Three archetypes dominate: mutual insurers with exclusive agent forces, diversified conglomerates generating investment float, and commercial specialists with manuscript endorsement capabilities. Competitive intensity centers on embedded distribution partnerships and parametric product innovation.
Among mutual insurers with captive distribution, State Farm and USAA exemplify the agency-network archetype, leveraging exclusive producer relationships to sustain personal lines penetration. Berkshire Hathaway anchors the diversified conglomerate tier, generating underwriting discipline and investment float through core insurance subsidiaries. Chubb Limited occupies the commercial specialist position, serving mid-market and large corporate accounts with high-limit excess programs and tailored professional liability solutions.
| Leading Market Players |
|---|
| State Farm |
| Berkshire Hathaway |
| Progressive |
| Allstate |
| Liberty Mutual |
| Travelers |
| USAA |
| Chubb Limited |
| Nationwide |
| Others |
Value Network & Pricing Analysis
High-limit manuscripted endorsements diverge sharply from commoditized small-business packaged policies, with this bifurcation driving carriers to maintain dual distribution architectures and tiered actuarial staffing models that separate bespoke underwriting desks from automated direct platforms.
Pricing Analysis
Warranty-style claims servicing and loss-control advisory bundling separate premium-tier professional liability programs from stripped-down direct-market alternatives. The market operates on a contract-based long-term structure with annual renewal cycles and retrospective rating adjustments. Price differentiation rests on manuscript endorsement complexity and dedicated claims handler assignment versus automated triage. Cost compression in small-business packaged lines is intensifying because embedded distribution partnerships are compressing acquisition expense ratios. Individual consumers and micro-enterprises exhibit the highest price sensitivity, while Fortune 1000 risk managers prioritize coverage certainty over premium minimization.
Supply Chain Analysis
State-level rate filing qualifications and surplus lines eligibility certifications gate carrier participation across U.S. jurisdictions, fragmenting capacity deployment. Geographic supply concentrates in the United States, Bermuda, and London for excess liability reinsurance, with Canadian domestic carriers filling primary layers. Raw material dependencies include actuarial talent pools, legal analytics data subscriptions, and catastrophe bond sponsorship capacity. Single-source vulnerability runs through concentrated Bermuda reinsurer relationships for super-catastrophic layers. Distribution runs through captive agency networks, wholesale brokers, and direct-to-consumer platforms serving distinct buyer archetypes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance arena where OSHA workplace safety mandates and state-level biometric privacy statutes erect formidable barriers to entry that favor carriers with established regulatory affairs infrastructure and rate filing expertise.
For Market Incumbents: Lock in distribution exclusivity through deeper embedded partnerships with vertical SaaS platforms serving legal, accounting, and healthcare practice management markets. Fortify manuscript endorsement capabilities against emerging algorithmic underwriting entrants by investing in proprietary litigation outcome prediction models that justify premium tiering.
For New Entrants and Emerging Players: Capture underserved cyber liability demand among mid-market professional services firms in Toronto and Austin where incumbent carriers still rely on traditional broker channels. Penetrate through API-first distribution integrations that trigger coverage offers at software renewal junctures.
For Investors and Strategic Acquirers: Re-rating potential sits with specialty underwriters possessing established Bermuda reinsurance relationships given alternative capital inflows into catastrophe bond structures. Target carriers with demonstrated machine learning reserving capabilities and embedded distribution contracts. Monitor OSHA enforcement intensity indices and state legislative tracking for biometric privacy statute expansion as inflection signals.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Distribution Partnership | API integration with vertical SaaS platforms creates frictionless purchase points at policy renewal junctures for professional liability lines. |
| Parametric Product Development | IoT sensor networks combined with blockchain smart contracts enable automated indemnity for predefined cyber business interruption events. |
| Alternative Capital Sponsorship | Catastrophe bond issuance expands capacity for super-catastrophic excess liability layers above $100 million attachment points. |
| Machine Learning Reserving Investment | Predictive analytics engines integrating structured claims data with legal document analysis optimize reserve adequacy and compress cycle times. |
| Regulatory Affairs Infrastructure Expansion | Dedicated state filing teams accelerate rate approval responsiveness in prior-approval jurisdictions like California under Proposition 103. |
Research Methodology
Document review covered NAIC rate filing databases, OSHA enforcement records, and state insurance commissioner bulletins, complemented by interviews with commercial insurance underwriters, reinsurance brokers, corporate risk managers, and insurance regulatory attorneys. Secondary validation drew from SEC 10-K insurance segment disclosures, A.M. Best financial strength reports, and catastrophe bond issuance prospectuses. Bottom-up premium pool estimates triangulated against top-down macroeconomic liability exposure indicators.
Model outputs projected premium volume and limit deployment across policy type, customer scale tier, industry vertical, and geographic regulatory cluster over the projection horizon. Segmentation dimensions included claims-made versus occurrence triggers, primary versus excess layer attachment points, and embedded versus traditional distribution channels. CAGRs were derived from historical loss ratio trends, litigation frequency indices, and regulatory expansion scenarios. Forecast inputs incorporated OSHA enforcement budget allocations and state legislative tracking for biometric privacy statute adoption.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to social inflation in jury awards and reinsurance cost volatility. Projections reflect assumptions regarding OSHA rulemaking timelines and state-level rate approval efficiency. A model refresh is warranted upon material change in nuclear verdict frequency indices or alternative capital flow patterns into insurance-linked securities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Auto Compulsory Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Agriculture Reinsurance Market
Insurance
Digital Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
Liability Insurance Market
Insurance
Employee Benefit Broker Market
Insurance
Road Assistance Insurance Market
Insurance
Europe Online Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
AI in Insurance Market
Insurance
US Travel Insurance Market
Insurance
Japan Liability Insurance Market
Insurance
Single Trip Travel Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
Global Vehicle Insurance Market