
 Middle East and Africa Venture Capital Market | 2026-2036
Middle East and Africa Venture Capital Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Venture Capital Market Foresight
Fintech is consolidating as the dominant end-use vertical across Gulf-based venture portfolios. Wamda Capital leverages its Cairo-Dubai network to sustain pre-seed throughput across North African technology startups. Saudi Venture Capital Company anchors Riyadh's domestic fund-of-funds architecture, while Aramco Ventures competes for industrial technology positions through strategic corporate mandates.
Middle East and Africa venture capital denotes risk-financing instruments deployed into private, early-growth enterprises across emerging economies, typically structured as limited partnerships with seven-to-twelve year horizons and carried-interest compensation for general partners. These vehicles channel institutional liquidity into illiquid equity positions, with fund structures varying by liquidity profile and investor governance requirements. Equity funds dominate committed capital volumes across the region, while fintech and healthcare verticals attract disproportionate allocation due to demographic tailwinds and regulatory sandbox enablement. Seed-stage deployment concentrates in UAE and Egyptian technology clusters, whereas growth-stage financing gravitates toward Saudi Arabian enterprise software and South African health-tech platforms.
Saudi Arabia's Capital Market Authority governs domestic fund registration and foreign limited partner admission, while the UAE Securities and Commodities Authority supervises Dubai International Financial Centre and Abu Dhabi Global Market fund structures. Egypt's Financial Regulatory Authority oversees non-banking financial instruments including venture vehicles, creating fragmented but deepening oversight across the region's primary capital formation nodes. Stakeholders must monitor evolving sharia-compliance standards for fund structures and cross-border repatriation protocols as sovereign participation reshapes term-sheet conventions.
Market Dynamics
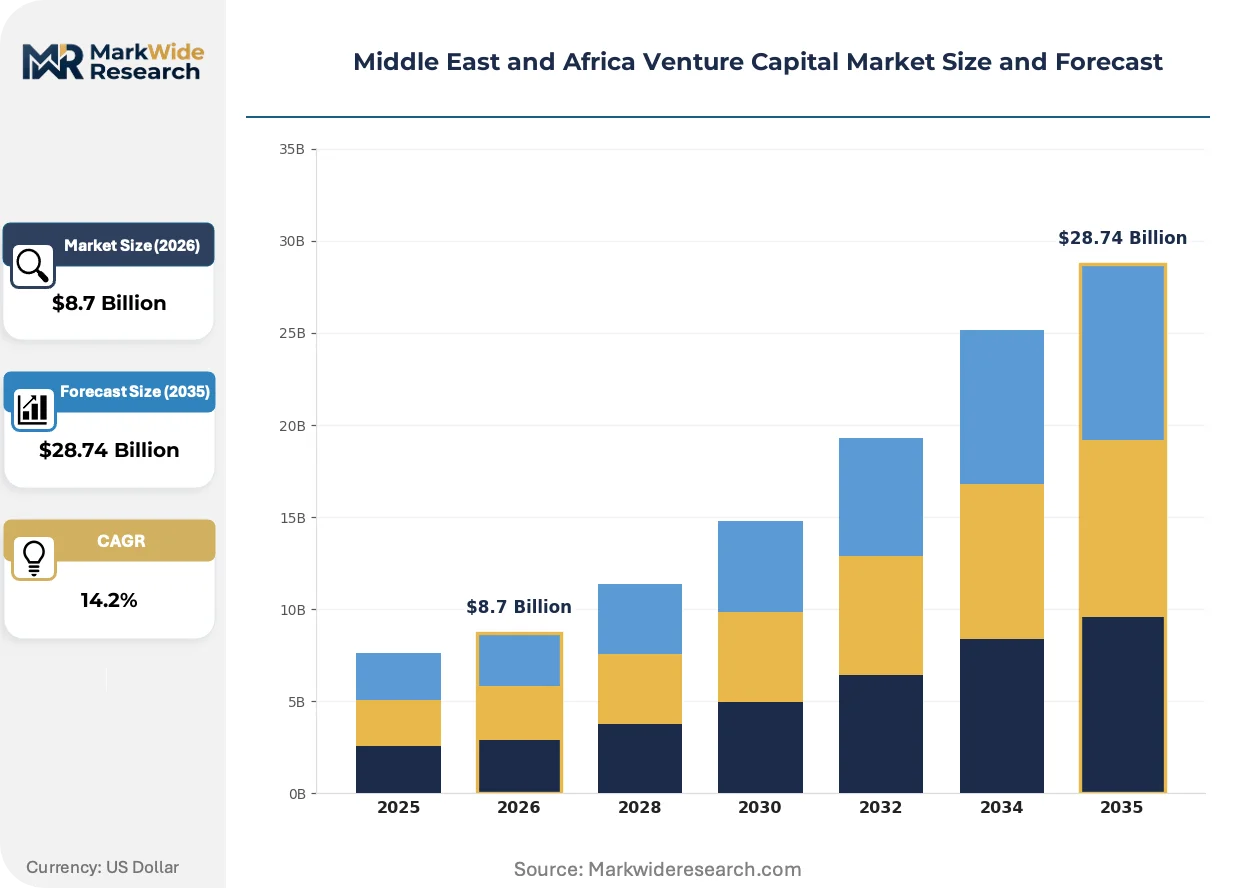
Sovereign wealth deployment is compressing fund-formation timelines across the Middle East and Africa venture capital landscape, as state-backed limited partners rewrite liquidity terms and governance standards for general partner structures.
Growth Catalysts
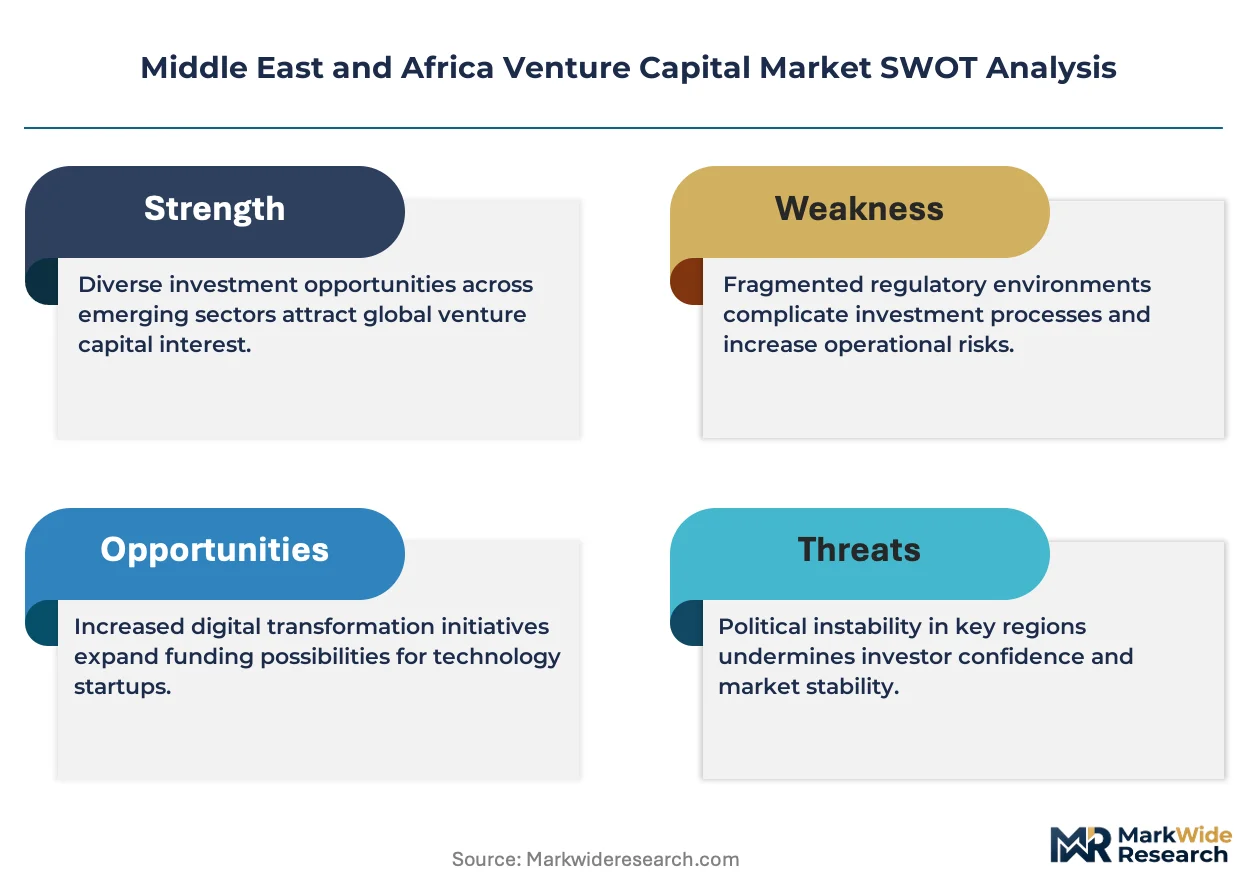
- Saudi Arabia's Capital Market Authority reforms:Foreign limited partner admission protocols now permit direct fund registration without local sponsor requirements, accelerating institutional capital inflows into Riyadh-based vehicles.
- Fintech sandbox enablement:The UAE's regulatory sandbox architecture permits live testing of payment infrastructure and digital banking models, reducing pre-revenue validation cycles for seed-stage deployments.
- Demographic tailwinds:Egypt's youth cohort expansion and unbanked population concentration create addressable market depth for financial inclusion startups, sustaining Cairo's pre-seed throughput.
Market Restraints
- Foreign exchange repatriation friction:Egypt's central bank maintains non-convertible currency protocols that trap realized returns in local pound instruments, extending exit timelines for offshore limited partners.
- Sharia-compliance structuring costs:Islamic finance certification requirements for fund vehicles add 15-25 basis points to annual management fees, compressing net internal rates of return.
- Deal flow concentration risk:Seed-stage deployment clusters disproportionately in Dubai International Financial Centre and Cairo technology corridors, creating geographic crowding and valuation inflation.
Strategic Opportunities
- South African health-tech vertical:Cross-border institutional capital targets Cape Town and Johannesburg digital health platforms addressing NHI scheme procurement modernization.
- Abu Dhabi Global Market fund structures:The emirate's common law jurisdiction permits carried interest crystallization mechanisms unavailable in onshore UAE frameworks, attracting general partner relocations.
- Climate technology convergence:Industrial decarbonization mandates across GCC sovereign wealth portfolios create dedicated allocation pools for clean energy venture vehicles.
Industry Challenges
- General partner talent scarcity:Experienced fund managers with track records spanning multiple fund cycles remain concentrated in Dubai and Riyadh, constraining ecosystem depth in secondary markets.
- Portfolio company governance gaps:Early-stage startups across Egyptian and Nigerian clusters lack standardized board structures and financial reporting frameworks, complicating institutional due diligence.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Venture Capital Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed, Early Stage, Growth Stage, Late Stage Industry Vertical: Technology, Healthcare, Fintech, Agritech Fund Structure: Equity Funds, Debt Funds, Hybrid Funds, Fund of Funds Investor Type: Angel Investors, Private Equity, Institutional Investors, Corporates |
| Companies Covered | Wamda Capital, Middle East Venture Partners (MEVP), Global Ventures, Partech Partners, Beco Capital, Saudi Venture Capital Company (SVC), 500 Global, STV, Aramco Ventures, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Venture Capital Market Shifts & Advancements
Technology infrastructure and regulatory architecture are jointly compressing investment decision cycles across Middle East and Africa venture markets, while sovereign participation rewrites traditional limited partner dynamics.
Blockchain-based cap table management is electrifying fund administration workflows across UAE-based venture vehicles. General partners at Dubai International Financial Centre structures adopt distributed ledger verification for shareholder registry maintenance, reducing audit preparation cycles from weeks to days. This infrastructure compression enables quarterly rather than annual portfolio reporting to sovereign limited partners.
Saudi Arabia's Capital Market Authority introduced revised fund registration guidelines that eliminate prior approval requirements for foreign-managed vehicles seeking domestic limited partner commitments. The regulatory relaxation permits offshore general partners to compete directly with Riyadh-registered managers for institutional allocations. Egyptian and South African regulators face comparable pressure to harmonize admission standards or lose capital flows to the kingdom.
Direct sourcing from founder networks is displacing traditional intermediary-dependent deal origination across Cairo and Lagos technology clusters. Seed-stage investors now prioritize operator-investor platforms and alumni syndicates over conventional investment banking relationships. This channel shift concentrates high-quality pre-seed flow with funds maintaining dedicated community infrastructure rather than transaction-focused outreach teams.
Middle East and Africa Venture Capital Market Segmentation
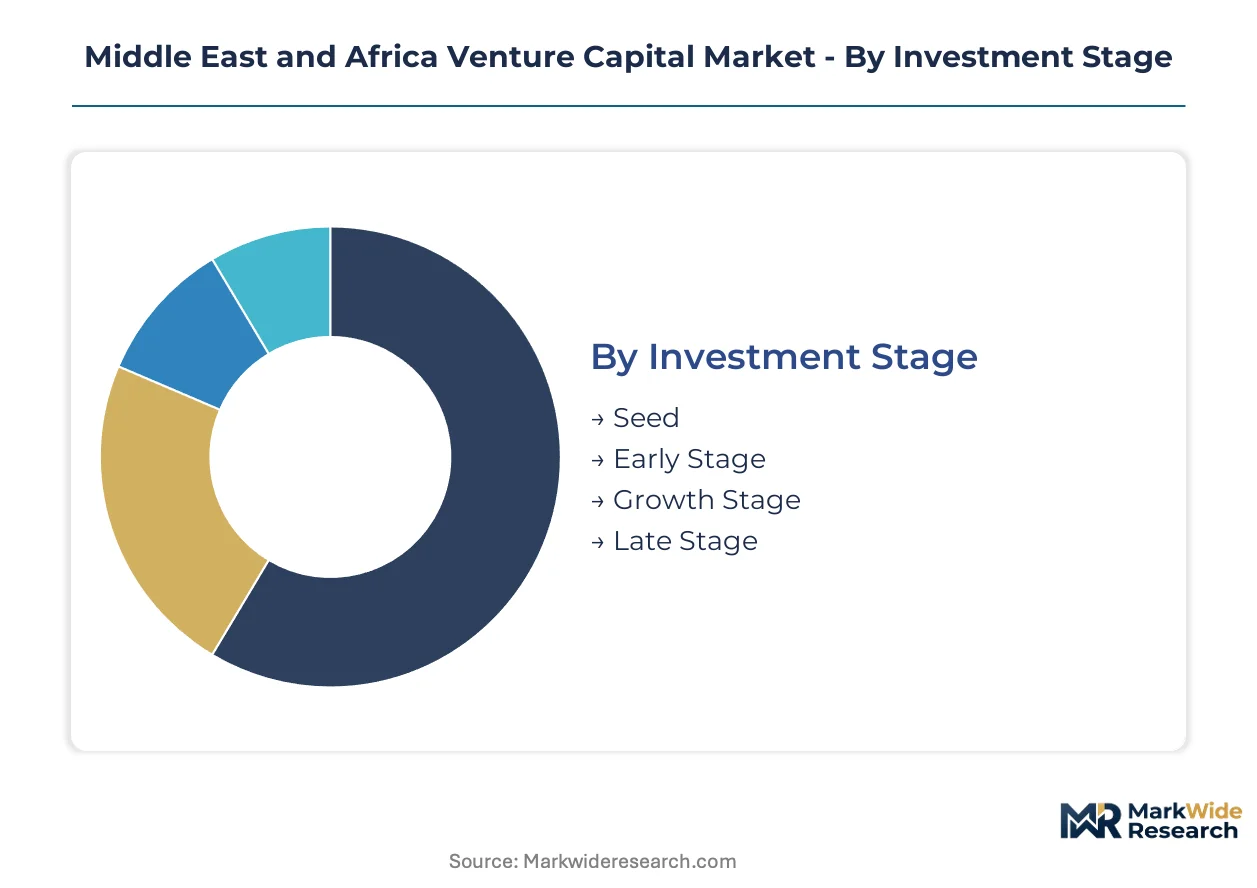
Venture capital deployment across the Middle East and Africa fragments across investment horizons, sector exposures, and capital structures. Sovereign wealth participation compresses fund-formation timelines unevenly across these dimensions, creating tiered liquidity profiles that reshape portfolio construction strategies for general partners.
Investment Stage:
Volume deployment concentrates in seed and early-stage vehicles, while premium fee structures and larger ticket sizes characterize growth and late-stage mandates.
- Seed:Pre-revenue financing for technology startups with unproven unit economics. Cairo and Dubai International Financial Centre clusters absorb the majority of regional seed commitments, driven by sovereign wealth mandates targeting ecosystem development.
- Early Stage:Post-revenue deployment into Series A and B rounds with validated customer acquisition metrics. Egyptian fintech startups and UAE enterprise software ventures attract disproportionate allocation due to regulatory sandbox enablement and demographic tailwinds.
- Growth Stage:Expansion capital for scaling operations across multiple geographies.
- Late Stage:Pre-IPO or strategic acquisition financing with institutional governance requirements.
Mature deployment sits with Early Stage. Newer deployment is concentrated in Seed.
Industry Vertical:
Margin profiles diverge sharply between regulated financial services and capital-intensive healthcare infrastructure versus asset-light technology platforms.
- Fintech:Digital payments, lending infrastructure, and banking-as-a-service models targeting unbanked populations. Saudi Arabia's Capital Market Authority reforms and UAE regulatory sandbox architectures accelerate licensing timelines, compressing path-to-revenue cycles for payment startups.
- Healthcare:Digital health platforms, diagnostics networks, and pharmaceutical supply chain optimization. South African health-tech ventures addressing National Health Insurance procurement modernization attract cross-border institutional capital with longer hold periods.
- Technology:Enterprise software, cybersecurity, and cloud infrastructure targeting GCC enterprise adoption.
- Agritech:Precision farming, supply chain digitization, and climate-adaptive crop technologies.
Institutional capital gravitates toward Healthcare. Fintech climbs the fastest as sovereign wealth vehicles deepen technology allocations.
Fund Structure:
Cost tier differentiation separates plain-vanilla equity vehicles from sharia-compliant and hybrid structures with elevated structuring expenses.
- Equity Funds:Standard limited partnership structures with carried interest crystallization upon exit events. Abu Dhabi Global Market common law jurisdiction permits distribution waterfall mechanisms unavailable in onshore UAE frameworks, attracting general partner relocations.
- Fund of Funds:Diversified exposure across underlying venture vehicles with reduced due diligence burden for limited partners. Saudi Venture Capital Company anchors Riyadh's domestic fund-of-funds architecture, channeling sovereign allocations into emerging managers.
- Debt Funds:Venture debt and revenue-based financing with collateralized structures.
- Hybrid Funds:Convertible instruments and equity-debt combinations with flexible repayment terms.
Concentrated deployment sits with Equity Funds. Emerging deployment is expanding most quickly in Fund of Funds as sovereign wealth vehicles outsource manager selection.
Investor Type:
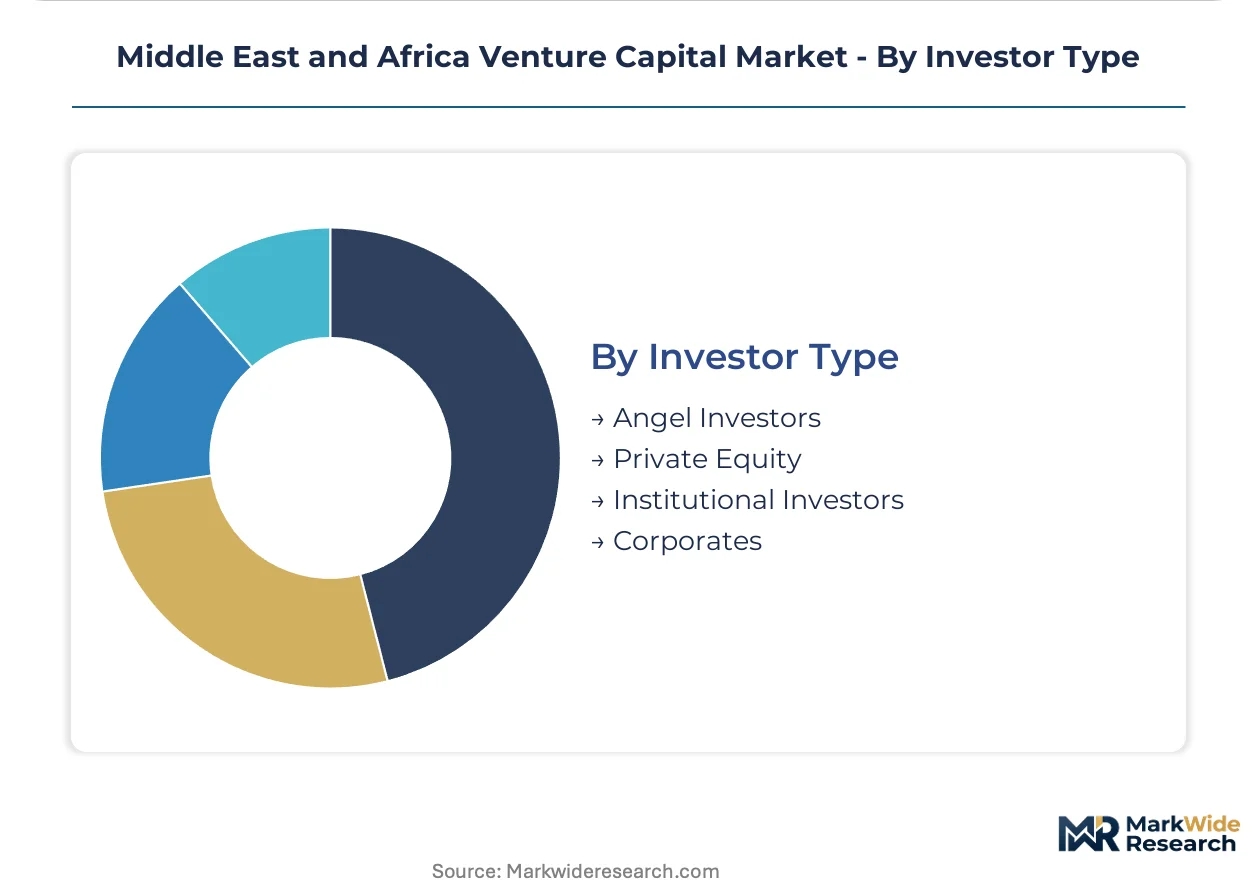
Customer type segmentation separates individual wealth deployment from institutional mandates with divergent liquidity horizons and governance requirements.
- Institutional Investors:Pension funds, endowments, and sovereign wealth vehicles with multi-decade liability profiles. Saudi Arabia's Public Investment Fund and UAE sovereign wealth vehicles rewrite term-sheet conventions through direct co-investment rights and board observation seats.
- Corporates:Strategic venture arms deploying balance sheet capital for ecosystem positioning and technology access. Aramco Ventures competes for industrial technology positions through mandate-specific allocations to energy transition and decarbonization startups.
- Angel Investors:Individual wealth deployment into pre-seed rounds with informal governance structures.
- Private Equity:Buyout and growth equity firms with longer hold periods and control-oriented strategies.
Dominant capital formation sits with Institutional Investors. Corporate participation is gaining share fastest as GCC industrial conglomerates build captive innovation pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Abu Dhabi Global Market's common law jurisdiction attracts fund managers seeking carried interest crystallization mechanisms unavailable in onshore UAE frameworks. Sovereign wealth deployment compresses fund-formation timelines unevenly across national regulatory environments.
United Arab Emirates
Dubai International Financial Centre and Abu Dhabi Global Market absorb the majority of regional seed commitments through sovereign wealth mandates targeting ecosystem development. The UAE Securities and Commodities Authority supervises fund structures with regulatory sandbox architectures that permit live testing of payment infrastructure. Blockchain-based cap table management electrifies fund administration workflows across UAE-based venture vehicles.
Saudi Arabia
Riyadh's domestic fund-of-funds architecture channels sovereign allocations into emerging managers through Saudi Venture Capital Company mandates. The Capital Market Authority introduced revised fund registration guidelines that eliminate prior approval requirements for foreign-managed vehicles. Aramco Ventures competes for industrial technology positions through mandate-specific allocations to energy transition startups.
Egypt
Cairo's pre-seed throughput sustains early-stage deal flow driven by youth cohort expansion and unbanked population concentration. The Financial Regulatory Authority oversees non-banking financial instruments including venture vehicles with fragmented but deepening oversight. Direct sourcing from founder networks displaces traditional intermediary-dependent deal origination across Cairo technology clusters.
South Africa
Cape Town and Johannesburg digital health platforms attract cross-border institutional capital addressing National Health Insurance procurement modernization. The country's national financial regulator maintains oversight frameworks for venture vehicles with longer hold periods for healthcare infrastructure. Portfolio company governance gaps complicate institutional due diligence across early-stage startups lacking standardized board structures.
Middle East and Africa Venture Capital Market Competitive Landscape
Top-tier vendors anchor sovereign-backed fund-of-funds architecture, while mid-tier specialist managers compete for emerging manager mandates. The competitive landscape fragments across geographic specialization and sector focus rather than scale concentration. Strategic archetypes include Cairo-Dubai network operators, Riyadh-based domestic fund architects, and industrial corporate venture arms. Dominant competitive moves encompass regulatory jurisdiction shopping for fund domiciliation and sovereign co-investment right negotiations.
Within the network-operator tier, Wamda Capital leverages its Cairo-Dubai positioning to sustain pre-seed throughput across North African technology startups. Saudi Venture Capital Company anchors Riyadh's domestic fund-of-funds architecture, channeling sovereign allocations into emerging managers. Aramco Ventures occupies the corporate strategic archetype, competing for industrial technology positions through mandate-specific allocations.
| Leading Market Players |
|---|
| Wamda Capital |
| Middle East Venture Partners (MEVP) |
| Global Ventures |
| Partech Partners |
| Beco Capital |
| Saudi Venture Capital Company (SVC) |
| 500 Global |
| STV |
| Aramco Ventures |
| Others |
Supply & Pricing Matrix
Blockchain-based cap table management is compressing fund administration costs across UAE-based venture vehicles while simultaneously concentrating technical infrastructure procurement with Dubai International Financial Centre and Abu Dhabi Global Market service providers. This technology shift lowers operational overhead for general partners but creates geographic dependency in fund-formation supply chains.
Pricing Analysis
Lead-time-driven pricing stratification distinguishes fund structures across the Middle East and Africa venture capital landscape. Abu Dhabi Global Market common law vehicles command premium placement fees for accelerated carried interest crystallization timelines, while Egyptian Financial Regulatory Authority-registered funds trade at discounted management fee multiples due to extended foreign exchange repatriation cycles. Price differentiation rests on regulatory sandbox access and sharia-compliance certification tier. Cost compression in seed-stage deployment is intensifying as sovereign wealth vehicles consolidate manager mandates. Family offices and high-net-worth individuals exhibit the highest price sensitivity, whereas institutional limited partners prioritize governance rights over fee minimization.
Supply Chain Analysis
Saudi Arabia's domestic-content mandates for fund administration services are reshaping sourcing patterns for legal, audit, and compliance functions. Geographic supply concentration centers on the United Arab Emirates, Saudi Arabia, and Egypt as primary fund domiciliation jurisdictions. Raw material dependencies include sharia-compliance certification from AAOIFI-accredited bodies, blockchain infrastructure from DIFC-registered technology providers, and cross-border legal structuring from ADGM-qualified counsel. Single-source vulnerability sits with centralized regulatory sandbox architecture in Dubai. Distribution runs through sovereign wealth fund-of-funds platforms, corporate venture arms, and emerging manager feeder vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa venture capital market is transitioning from intermediary-dependent deal origination to direct founder-network sourcing, with blockchain-enabled fund administration displacing legacy manual cap table management.
For Market Incumbents: Anchor fund-formation capabilities in Abu Dhabi Global Market or Dubai International Financial Centre jurisdictions to preserve carried interest crystallization advantages. Defend against emerging manager compression by deepening sovereign co-investment relationships and securing exclusive regulatory sandbox access for portfolio companies. Vertical integration into blockchain-based administration infrastructure reduces third-party dependency and protects margin structures. For New Entrants and Emerging Players: Direct sourcing platforms and alumni syndicate networks offer the most penetrable entry route into Cairo and Lagos pre-seed deal flow. Target Egyptian fintech and South African health-tech verticals where institutional capital demand exceeds qualified general partner supply. A founder-operator positioning with dedicated community infrastructure outperforms transaction-focused outreach teams for high-quality flow access. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by GCC sovereign wealth vehicles and cross-border secondary sales to global venture funds. Long-term viability favors managers with demonstrated track records across multiple fund cycles and established sovereign limited partner relationships. The signal to watch is regulatory harmonization pressure from Saudi Arabia's Capital Market Authority reforms, which may trigger competitive liberalization in Egyptian and South African admission standards.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Jurisdiction Relocation | ADGM common law framework permits distribution waterfall mechanisms unavailable in onshore UAE structures. |
| Sovereign Co-Investment Platform | Direct participation rights from Saudi Public Investment Fund rewrite traditional limited partner governance conventions. |
| Blockchain Cap Table Infrastructure | Distributed ledger verification reduces audit preparation cycles from weeks to days for DIFC-registered vehicles. |
| Founder Network Community Buildout | Operator-investor platforms displace investment banking relationships in Cairo technology clusters. |
| Sharia-Compliance Certification Investment | Islamic finance accreditation opens sovereign wealth allocation pools across GCC fund-of-funds architecture. |
Research Methodology
Regulatory filings from the UAE Securities and Commodities Authority, Saudi Capital Market Authority, and Egyptian Financial Regulatory Authority formed the secondary backbone for fund structure and admission protocol analysis. Primary interviews with general partners at Dubai International Financial Centre and Abu Dhabi Global Market-registered vehicles, sovereign wealth fund allocation officers, and Cairo-based seed-stage founders combined with secondary validation from fund registration databases and sharia-compliance certification records. Bottom-up deployment data triangulated against top-down committed capital estimates from sovereign wealth disclosure filings.
Historical trendline analysis of fund-formation timelines, carried interest crystallization patterns, and regulatory admission standard evolution informed the projection framework. Segmentation dimensions modeled include investment stage, industry vertical, fund structure, and investor type across the analysis window. CAGRs derived from regression analysis of committed capital growth trajectories, with sovereign wealth allocation intensity and regulatory sandbox enablement as key forecast inputs.
The model holds under continued regulatory modernization momentum and stable sovereign wealth technology allocation preferences; deviation in foreign exchange repatriation policy or sharia-compliance standard fragmentation would shift fund domiciliation patterns and return expectations. Forecasts reflect documented assumptions about limited partner liquidity horizons and general partner talent availability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
Equity Crowdfunding Market
Venture Capital
Business Incubator Market
Venture Capital
Europe Venture Capital Market
Venture Capital
Micro VC Funds Market
Venture Capital
US Venture Capital Investment Market
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Asia-Pacific Venture Capital Investment Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
North America Venture Capital Market
Venture Capital
Angel Funds Market
Venture Capital
Impact Investing Market
Venture Capital
Crowdfunding Market
Venture Capital
United States Venture Capital Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
Venture Capital Investment Market
Venture Capital
Micro Venture Capital VC Funds Market