
 Venture Capital Investment Market | 2026-2036
Venture Capital Investment Market Size, Share, and Industry Trends Forecast 2026-2036
Venture Capital Investment Market Intelligence
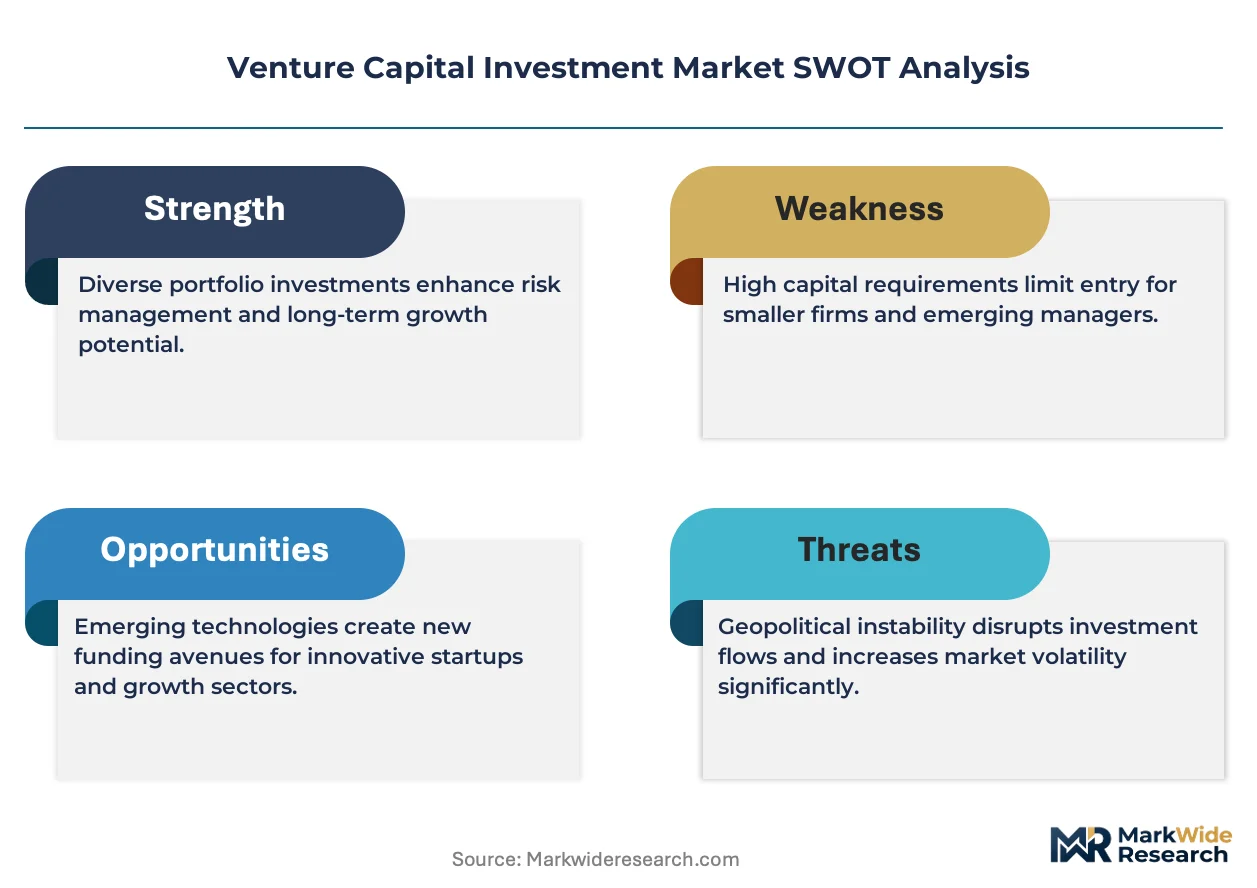
Modular fund structuring is pivoting how limited partners configure their venture exposure, unbundling traditional commitments into stage-specific sleeves and co-investment sidecars. Sequoia Capital leverages its concentrated portfolio model to sustain outsized ownership stakes in breakout companies. Andreessen Horowitz anchors its competitive position through an in-house operational services platform that extends beyond capital provision. Benchmark competes on a deliberately small fund size that specializes in early governance involvement rather than capital scale.
Venture capital denotes equity financing provided to privately held companies exhibiting high growth potential, typically structured through limited partnerships with ten-to-twelve-year lifecycles and carried-interest compensation for general partners. The asset class functions as primary commercial fuel for innovation-driven enterprises lacking access to public markets or traditional debt collateral. Growth-stage deployment now dominates aggregate capital flow as institutional investors channel larger checks into proven revenue models rather than seed-stage speculation. Closed-end fund structures capture the majority of committed capital due to their finite horizons aligning manager incentives with realized returns. Institutional investors represent the fastest-expanding participant category as pension funds and sovereign wealth vehicles increase allocation targets to private markets.
The SEC governs fund formation and investor qualification through Investment Advisers Act exemptions and Rule 506(b) private placement safe harbors, directly constraining capital formation velocity and retail market access. EU AIFMD compliance requirements for non-EU managers shape cross-border fundraising feasibility and determine which firms establish European regulated entities. Stakeholders must monitor evolving carried-interest taxation proposals and emerging SEC private fund adviser rulemakings that could restructure fee disclosure and restricted activity frameworks.
Market Dynamics
Capital deployment velocity now hinges on generative AI infrastructure buildouts, with limited partners redirecting commitments toward compute-intensive frontier models and their enabling semiconductor layers.
Growth Catalysts
- SEC Accredited Investor Threshold Adjustments:Proposed amendments to net-worth and income tests expand the eligible limited-partner pool for Rule 506(b) private placements, accelerating fund-raise timelines for emerging managers.
- Artificial Intelligence Compute Clusters:Massive capital absorption by GPU-dependent training operations creates dedicated fund vehicles targeting hyperscaler supply chains and specialized data-center real estate.
- Sovereign Wealth Fund Reallocation:Gulf state investment authorities channel petrodollar reserves into Silicon Valley venture structures, prioritizing enterprise software and climate-tech sleeves.
Market Restraints
- Carried-Interest Taxation Uncertainty:Pending US legislative proposals to reclassify general-partner profit shares as ordinary income threaten net-return projections and fund-level IRR modeling.
- Valuation Mark-to-Market Illiquidity:Absence of active secondary trading for pre-IPO equity forces stale pricing across portfolio holdings, complicating institutional rebalancing.
- LP Concentration in Mega-Funds:Top-decile firms capture disproportionate commitment flows, starving sub-scale managers of anchor capital and compressing strategy diversity.
Strategic Opportunities
- India DPIIT Startup Recognition:Regulatory streamlining under the Department for Promotion of Industry and Internal Trade reduces compliance friction for foreign venture capital deployment into SaaS and fintech.
- Climate-Tech Tax Credit Stacking:The US Inflation Reduction Act enables layered incentive capture across carbon-capture, hydrogen, and battery-supply-chain investments, improving risk-adjusted returns.
- Specialized Secondaries Vehicles:Tailored fund structures acquire LP stakes in vintage years six through eight, unlocking liquidity for pension systems without forcing premature exits.
Industry Challenges
- Technical Due-Diligence Bandwidth:Deep-science investments in synthetic biology and quantum hardware demand specialized PhD-level evaluation capacity that generalist firms struggle to staff.
- Cross-Border Data Localization:EU GDPR and emerging national data-sovereignty laws fragment cloud infrastructure requirements, complicating due diligence for software investments with international user bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Venture Capital Investment Market |
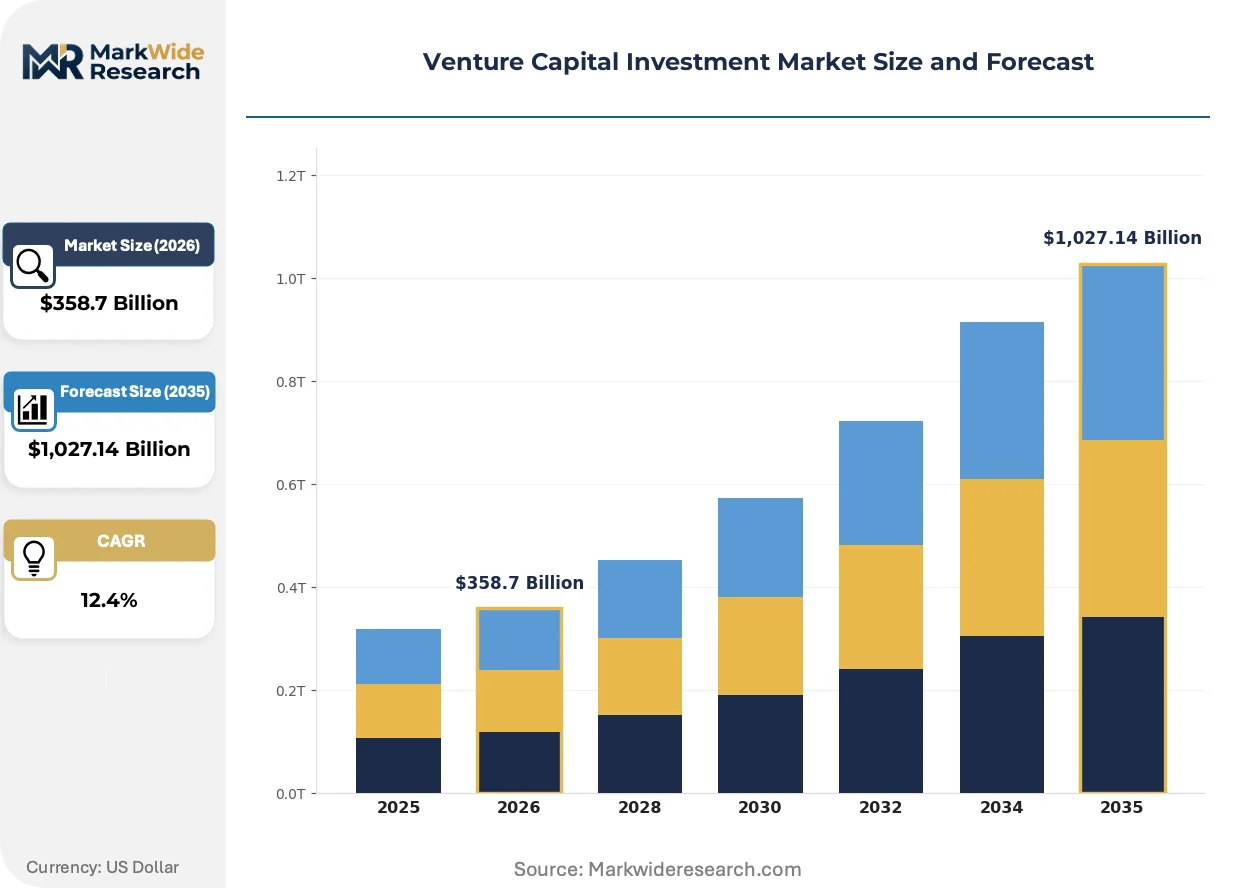
| Market Size in 2026 | $358.7 Billion |
| Market Size in 2035 | $1,027.14 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed Stage, Early Stage, Growth Stage, Late Stage Fund Structure: Closed-End Fund, Open-End Fund, Hybrid Fund, Fund of Funds Investor Type: Institutional Investors, High Net Worth Individuals, Family Offices, Corporate Investors Asset Class: Equity, Convertible Notes, Preferred Shares, Mezzanine Debt |
| Companies Covered | Sequoia Capital, Andreessen Horowitz, Accel, General Catalyst Partners, Benchmark, New Enterprise Associates, Lightspeed Venture Partners, Kleiner Perkins, Dragoneer Investment Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Venture Capital Investment Market Strategic Shifts & Innovations
Fund architecture is fragmenting into purpose-built vehicles as limited partners demand granular exposure control over stage, sector, and liquidity profile rather than traditional bundled commitments.
Artificial intelligence due-diligence tooling is consolidating sourcing, pattern-matching, and portfolio-monitoring functions into unified platforms. Growth-equity and buyout teams at multi-strategy firms deploy these systems to compress evaluation cycles from weeks to days. The technology is consolidating competitive advantage around data-rich incumbents with proprietary training datasets from historical deal flow.
The SEC's private fund adviser rulemaking mandates quarterly statement standardization and restricted-activity disclosure for all SEC-registered advisers. Compliance departments at US-domiciled firms restructure side-letter negotiation protocols and fee-calculation methodologies to meet documentation requirements. Early-stage managers with limited operational infrastructure face disproportionate implementation burdens relative to scaled platforms.
Institutional limited partners now segment chief-investment-officer mandates into discrete sleeves by liquidity horizon, with separate teams overseeing evergreen structures, vintage-year commitments, and direct co-investment programs. Pension systems in California and New York rotate personnel across these desks to build specialized expertise rather than generalist coverage. This organizational redesign is most visible among public-employee retirement systems with venture allocations exceeding five percent of total portfolio value.
Venture Capital Investment Market Segmentation
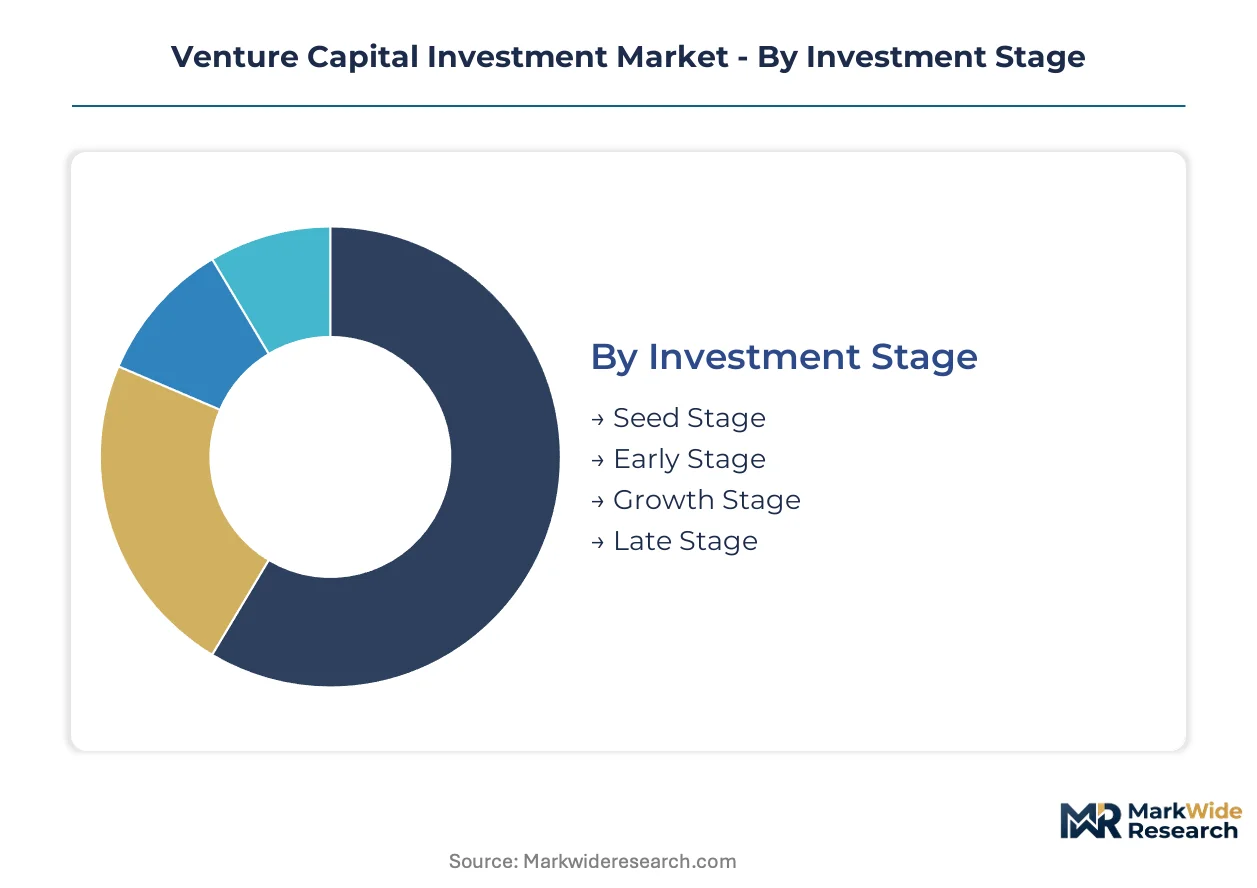
Venture capital segmentation determines capital allocation efficiency, risk-return profiles, and regulatory compliance pathways. Distinct investor categories and fund structures create tiered access to deal flow quality and liquidity timing. Understanding these divisions enables limited partners to construct exposure matrices aligned with liability duration and return thresholds.
Investment Stage:
Capital deployment timing spans a customization continuum from speculative pre-revenue bets to standardized pre-IPO bridge financing, with governance intensity and valuation precision inversely correlated.
- Growth Stage:Deployment targets companies with validated revenue models and scalable unit economics, typically Series C through E rounds. Institutional limited partners in the United States and Gulf sovereign wealth vehicles concentrate commitments here, drawn by reduced technical risk and shorter paths to liquidity events.
- Seed Stage:Initial institutional financing rounds precede product-market fit validation, emphasizing team quality and addressable market sizing over financial metrics. Silicon Valley and New York metropolitan area managers dominate sourcing networks, though Bangalore and Tel Aviv clusters are gaining traction.
- Early Stage:Series A and B rounds bridge initial traction and scaled operations, demanding operational due-diligence bandwidth from general partners.
- Late Stage:Pre-IPO and secondary transactions emphasize valuation discipline and exit pathway certainty over growth acceleration.
Most installed capacity flows through Growth Stage. Expansion is steepest in Seed Stage.
Fund Structure:
Legal architecture determines investor redemption rights, fee crystallization timing, and cross-border regulatory treatment, with cost-tier implications for operational overhead and compliance burden.
- Closed-End Fund:Finite ten-to-twelve-year lifecycles align general-partner incentives with realized returns through carried-interest crystallization at exit. The SEC's Investment Advisers Act exemptions and Rule 506(b) safe harbors govern formation, constraining retail participation to accredited investor thresholds.
- Fund of Funds:Diversified vehicles allocate across multiple underlying managers, offering limited partners reduced due-diligence burden and vintage-year diversification. Pension systems and insurance company balance sheets in the United States and European jurisdictions favor this structure for sub-scale allocation teams.
- Open-End Fund:Evergreen structures permit continuous capital raising and periodic redemptions, matching liability profiles of insurance company general accounts.
- Hybrid Fund:Blended vehicles combine closed-end core commitments with open-end sleeve flexibility for opportunistic deployment.
Capital commitment volume concentrates in Closed-End Fund vehicles. Regulatory innovation is advancing most quickly around Hybrid Fund structures.
Investor Type:
Participant sophistication and capital durability create distinct demand patterns across the maturity spectrum, with volume concentration and strategic intent shaping manager selection criteria.
- Institutional Investors:Pension funds, sovereign wealth vehicles, and insurance company general accounts deploy through formal alternatives allocation frameworks. California Public Employees' Retirement System and New York State Common Retirement Fund exemplify the organizational segmentation into dedicated venture desks with specialized personnel rotation protocols.
- Corporate Investors:Strategic balance-sheet deployment seeks technology access, market intelligence, and potential acquisition pipeline development. Technology and healthcare conglomerates in the United States and European Union dominate this category, with CVC arms increasingly competing for lead positions alongside traditional financial sponsors.
- Family Offices:Multi-generational wealth vehicles offer flexible capital with reduced liquidity constraints and concentrated decision-making authority.
- High Net Worth Individuals:Personal balance-sheet exposure, often through feeder vehicles or direct co-investment programs, captures carry-reduced access to top-tier managers.
Institutional Investors anchor aggregate commitment volume. Strategic participation through Corporate Investors is gaining share fastest.
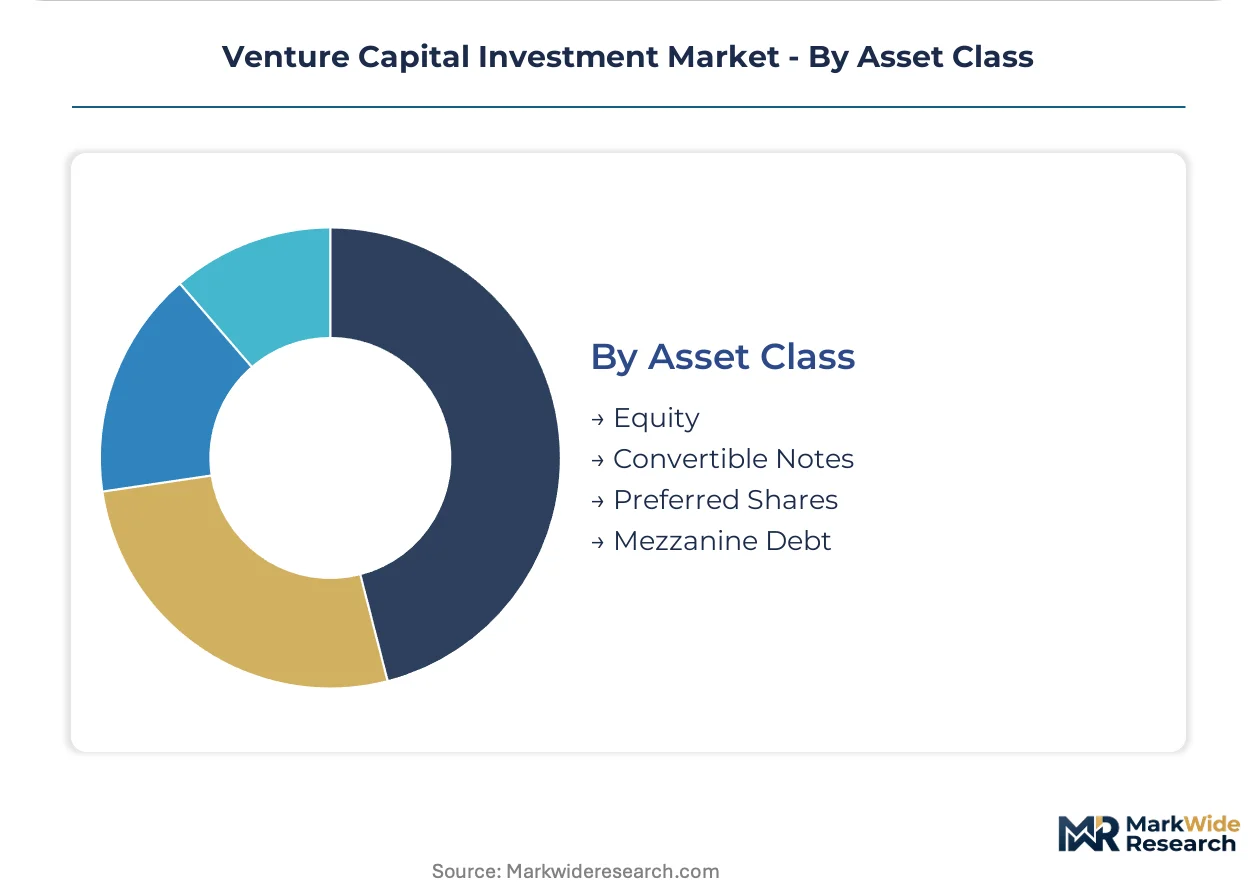
Asset Class:
Security-type selection reflects risk appetite, governance requirements, and downstream capitalization pathway assumptions, with margin implications for upside participation and downside protection.
- Preferred Shares:Senior equity instruments with liquidation preference, anti-dilution provisions, and protective covenants dominate institutional venture structuring. Delaware corporate law and NVCA model document standards provide jurisdictional predictability for cross-border limited partner bases.
- Convertible Notes:Debt instruments converting to equity upon qualified financing rounds minimize valuation negotiation friction for seed-stage transactions. Y Combinator SAFE instruments and their variants have displaced traditional note structures in United States accelerator ecosystems.
- Equity:Common stock participation aligns founder and investor interests without preference stack complexity, typical in founder-friendly early rounds.
- Mezzanine Debt:Subordinated financing with equity participation features serves late-stage bridge scenarios and pre-IPO recapitalizations.
Transaction volume flows predominantly through Preferred Shares. Structural innovation is accelerating around Convertible Notes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Venture capital traces its institutional origins to post-war United States, where the American Research and Development Corporation pioneered limited-partnership structures for technology financing in 1946. This model diffused through Boston's Route 128 corridor before consolidating in Northern California during the 1970s semiconductor boom.
United States
Silicon Valley and the New York metropolitan corridor concentrate the deepest LP commitment pools and most mature exit ecosystems. SEC Rule 506(b) private placement frameworks govern fund formation, constraining retail access to accredited investor thresholds. The San Francisco Bay Area sustains unmatched density of serial founders and technical talent, while Boston's Kendall Square anchors life-science venture specialization.
China
Domestic venture deployment pivots toward semiconductor self-sufficiency and artificial intelligence applications under Beijing's strategic technology priorities. The Ministry of Industry and Information Technology channels state-guided capital through government guidance funds into hard-tech domains. The Yangtze River Delta, particularly Shanghai and Hangzhou, hosts the most active early-stage ecosystems outside the United States.
India
SaaS and fintech ventures attract accelerating foreign capital as DPIIT startup recognition streamlines compliance for offshore investors. SEBI's Alternative Investment Fund regulations provide the primary regulatory architecture for domestic fund formation. Bangalore and the Delhi-NCR corridor concentrate technical talent and founder density, with Mumbai anchoring financial-services venture deployment.
United Kingdom
London's venture ecosystem leverages deep pools of institutional capital and proximity to European talent flows despite post-Brexit regulatory friction. The Financial Conduct Authority's regime for alternative investment fund managers shapes cross-border fundraising feasibility. The Golden Triangle of London, Oxford, and Cambridge sustains specialized strength in deep-tech and life-science formation.
Israel
Defense technology spinouts and cybersecurity formation drive venture absorption, with Tel Aviv ranking among the densest startup ecosystems globally on a per-capita basis. The Israel Innovation Authority provides matched funding and R&D tax incentives that de-risk early technical development. Herzliya Pituach and the surrounding coastal plain concentrate venture-backed company headquarters and multinational R&D centers.
Venture Capital Investment Market Key Industry Players
Premium-margin players sit above commodity-margin players across track-record access and LP relationship durability. The market structures around a concentrated top decile capturing disproportionate commitment flows, with mid-scale managers facing acute anchor-capital scarcity. Three archetypes dominate: concentrated portfolio builders, operational platform operators, and governance-intensive specialists. Competitive moves center on side-car vehicle construction for co-investment access and in-house talent platform development to differentiate beyond capital provision.
Within the concentrated portfolio tier, Sequoia Capital and Andreessen Horowitz exemplify divergent strategic architectures. Sequoia's concentrated ownership model sustains outsized stakes in breakout companies through disciplined pro-rata enforcement and concentrated deployment. Andreessen Horowitz occupies a position defined by operational platform scale, embedding in-house recruiting, marketing, and business development functions that extend beyond traditional capital provision. Benchmark represents the governance-intensive specialist archetype, deliberately constraining fund size to enable deep founder involvement at formation stage. These three firms anchor the competitive topology, with their structural choices shaping LP expectations for emerging manager evaluation.
| Leading Market Players |
|---|
| Sequoia Capital |
| Andreessen Horowitz |
| Accel |
| General Catalyst Partners |
| Benchmark |
| New Enterprise Associates |
| Lightspeed Venture Partners |
| Kleiner Perkins |
| Dragoneer Investment Group |
| Others |
Cost & Logistics Intelligence
LP demand for granular exposure control is forcing fund managers to unbundle traditional bundled commitments into stage-specific sleeves and co-investment sidecars, compressing management fee crystallization timelines and reshaping how general partners structure carried-interest waterfalls.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs venture capital fund economics, with brand premium and vintage-year track record serving as primary price differentiation drivers. Pricing pressure stems from LP concentration in mega-funds starving sub-scale managers of anchor capital. Institutional pension systems exhibit lowest price sensitivity due to liability-matching requirements, while family offices demonstrate highest sensitivity to fee load given direct co-investment alternatives.
Supply Chain Analysis
Domestic-content mandates in India's DPIIT startup recognition framework and China's MIIT semiconductor self-sufficiency directives are reshaping sourcing patterns for technical due-diligence talent and cross-border deal flow. Capital deployment draws from United States, China, and India as primary nodes, with GPU-dependent compute clusters and specialized PhD-level evaluation capacity as critical inputs. Single-source vulnerability concentrates in Silicon Valley technical talent pipelines. Distribution runs through closed-end limited partnerships with ten-to-twelve-year lifecycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Venture capital has entered a late-cycle quality phase where LP commitments concentrate in managers demonstrating operational platform depth rather than pure track-record access, with artificial intelligence infrastructure deployment serving as the premium specification threshold separating tier-one from tier-two franchises.
For Market Incumbents: Hedge against technical due-diligence bandwidth scarcity by building in-house PhD-level evaluation capacity in synthetic biology and quantum hardware. Anchor capital retention demands proactive side-car vehicle construction for co-investment access, defending against emerging managers offering reduced fee loads. For New Entrants and Emerging Players: Begin with climate-tech tax credit stacking opportunities under the US Inflation Reduction Act, where layered incentive capture across carbon-capture and battery-supply-chain investments offers the most penetrable white space. Target India DPIIT-recognized SaaS formations with streamlined compliance pathways for foreign capital deployment. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized secondaries vehicles acquiring LP stakes in vintage years six through eight, unlocking liquidity for pension systems without forcing premature exits. Long-term viability favors firms with proprietary AI due-diligence tooling consolidating sourcing and pattern-matching functions. Watch for SEC private fund adviser rulemaking implementation burdens disproportionately impacting early-stage managers as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Operational Platform Buildout | Andreessen Horowitz's in-house recruiting and marketing functions extend competitive moat beyond capital provision. |
| Concentrated Portfolio Construction | Sequoia Capital's disciplined pro-rata enforcement sustains outsized ownership stakes in breakout companies. |
| Governance-Intensive Specialization | Benchmark's deliberately small fund size enables deep founder involvement at formation stage. |
| Hybrid Fund Architecture Innovation | Blended closed-end core commitments with open-end sleeve flexibility advance regulatory innovation. |
| AI Due-Diligence Tooling Integration | Unified platforms compressing evaluation cycles from weeks to days consolidate advantage around data-rich incumbents. |
Research Approach
Coverage spans United States, China, India, and United Kingdom, with primary inputs from each market combining interviews with general partners, limited partner chief investment officers, and regulatory compliance leads with secondary validation against SEC Investment Advisers Act filings, SEBI Alternative Investment Fund registrations, EU AIFMD compliance disclosures, and sovereign wealth fund annual reports. Bottom-up deal flow databases triangulate against top-down capital commitment surveys.
Granularity-level modeling operates at fund structure, investment stage, investor type, and asset class dimensions across the analysis window, with artificial intelligence compute cluster deployment and climate-tech tax credit capture as industry-specific forecast inputs. CAGRs derive from vintage-year cash flow patterning and exit pathway probability weighting.
Several conditions sit outside the modeled scope, including pending US legislative proposals to reclassify carried-interest taxation and evolving SEC accredited investor threshold adjustments. Forecasts reflect assumptions about regulatory stability and LP allocation target persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
Business Incubator Market
Venture Capital
Impact Investing Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
Angel Funds Market
Venture Capital
Asia Pacific Venture Capital Market
Venture Capital
Micro VC Funds Market
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Europe Venture Capital Market
Venture Capital
Asia-Pacific Venture Capital Investment Market
Venture Capital
United States Venture Capital Market
Venture Capital
Crowdfunding Market
Venture Capital
North America Venture Capital Market
Venture Capital
Micro Venture Capital VC Funds Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
Middle East and Africa Venture Capital Market