
 Micro Venture Capital VC Funds Market | 2026-2036
Micro Venture Capital VC Funds Market Size, Share, and Industry Trends Forecast 2026-2036
Micro Venture Capital VC Funds Market Insights
The buyer base for micro venture capital is broadening beyond traditional institutional limited partners to encompass family offices, corporate venture arms, and high-net-worth individuals seeking early-stage exposure. First Round Capital leverages its thematic focus on software and healthcare to sustain deal flow quality across multiple vintage years. 500 Global anchors its competitive position through geographic diversification, operating accelerator programs across emerging startup ecosystems. SV Angel differentiates by concentrating on founder-network density rather than sector breadth.
Micro venture capital funds are pooled investment vehicles that deploy capital of typically under $100 million into pre-seed through Series B companies, employing convertible instruments, priced equity rounds, and SAFE agreements to acquire minority stakes. These funds generate returns through portfolio company exits via acquisition or initial public offering, with carried interest structures aligning general partner compensation to limited partner distributions. Funds under $25 million in size dominate by count, though the $25-$50 million segment captures disproportionate management fee yield per dollar deployed. Early-stage startup focus leads deployment velocity, while sector-specific strategies concentrate technical due diligence capabilities and co-investment access.
The SEC defines accredited investor thresholds that gate micro VC fundraising in the United States, while the JOBS Act Rule 506(c) permits general solicitation to verified qualified purchasers. The EU's AIFMD imposes transparency and leverage constraints on fund managers marketing to European limited partners, shaping cross-border capital formation. The UK's FCA prudential regime for smaller authorized funds influences structuring decisions for managers accessing London-based family offices. Stakeholders must monitor evolving securities definitions and cross-border marketing passports to preserve capital-raising flexibility.
Market Dynamics
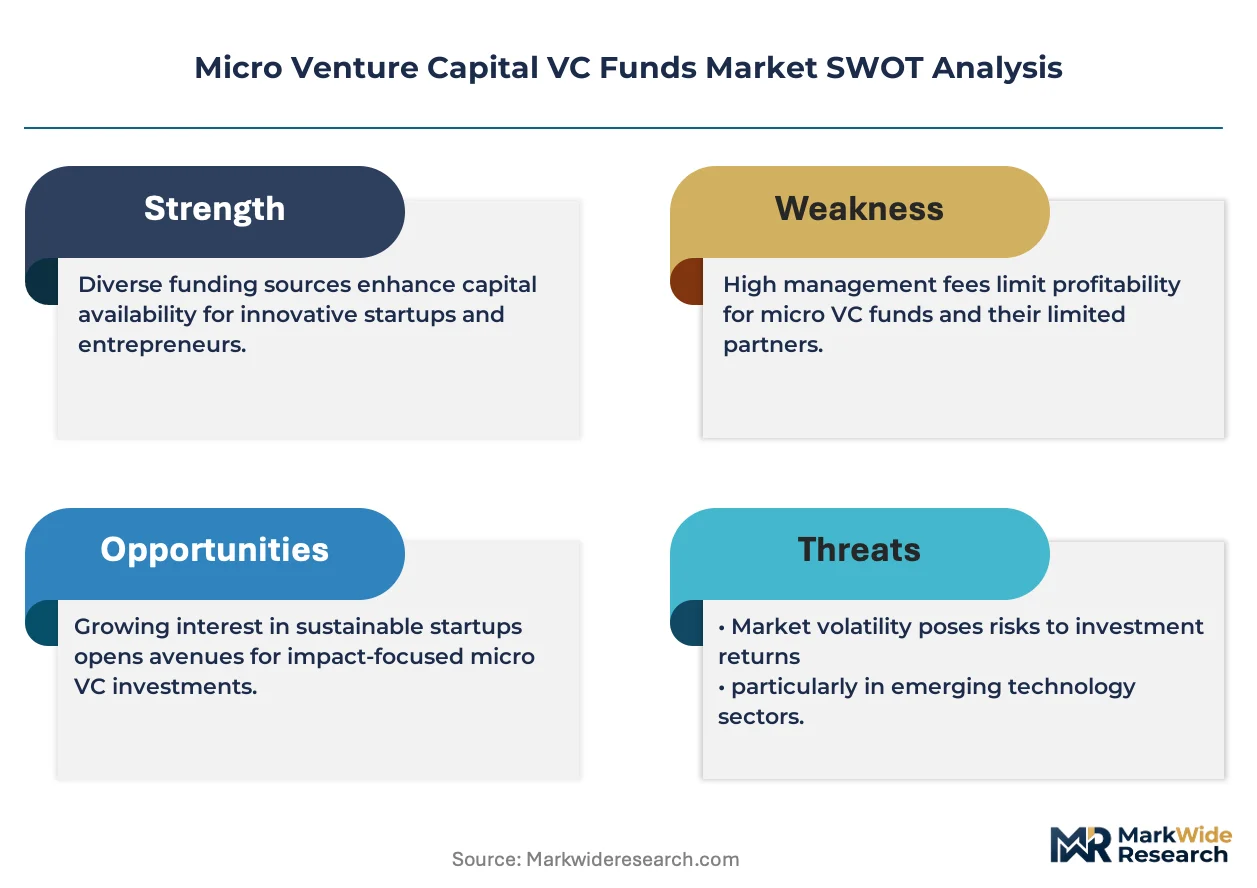
Capital formation rules are fragmenting across jurisdictions, forcing micro VC managers to restructure fundraising vehicles and compliance stacks to access diversified limited partner bases. The SEC's evolving accredited investor definitions and the EU's AIFMD marketing constraints are creating divergent operational templates for sub-$100 million funds.
Growth Catalysts
- JOBS Act Rule 506(c):General solicitation to verified qualified purchasers is expanding the addressable investor pool beyond traditional institutional LPs in the United States.
- Software-as-a-Service penetration:Recurring revenue models in enterprise software are compressing time-to-Series A, accelerating deployment velocity for seed-stage specialists.
- Family office direct indexing:Single-family offices seeking early-stage exposure without fund-of-fees are channeling capital into sub-$50 million vehicles.
Market Restraints
- Management fee compression:The $25 million fund size threshold produces insufficient fee yield to cover operational infrastructure and partner compensation.
- Cross-border marketing friction:AIFMD transparency and leverage constraints limit European LP access for US-domiciled managers without passport arrangements.
- Valuation benchmark opacity:Absence of liquid comparables for pre-revenue startups extends due diligence cycles and delays first close timelines.
Strategic Opportunities
- India's startup ecosystem maturation:SEBI's Alternative Investment Fund regulations and PLI scheme spillovers are creating compliant structures for sector-specific micro VC deployment.
- Climate-tech verticalization:IRA production tax credits and EU Green Deal alignment requirements are spawning dedicated decarbonization seed funds.
- SAFE instrument standardization:Y Combinator's post-money SAFE templates are reducing legal friction and accelerating pre-seed round velocity across emerging markets.
Industry Challenges
- Technical due diligence bandwidth:Deep sector specialization in synthetic biology or quantum computing requires scarce PhD-level investment talent.
- Carried interest crystallization timing:Extended IPO windows and acquisition regulatory reviews are deferring GP compensation and eroding retention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro Venture Capital VC Funds Market |
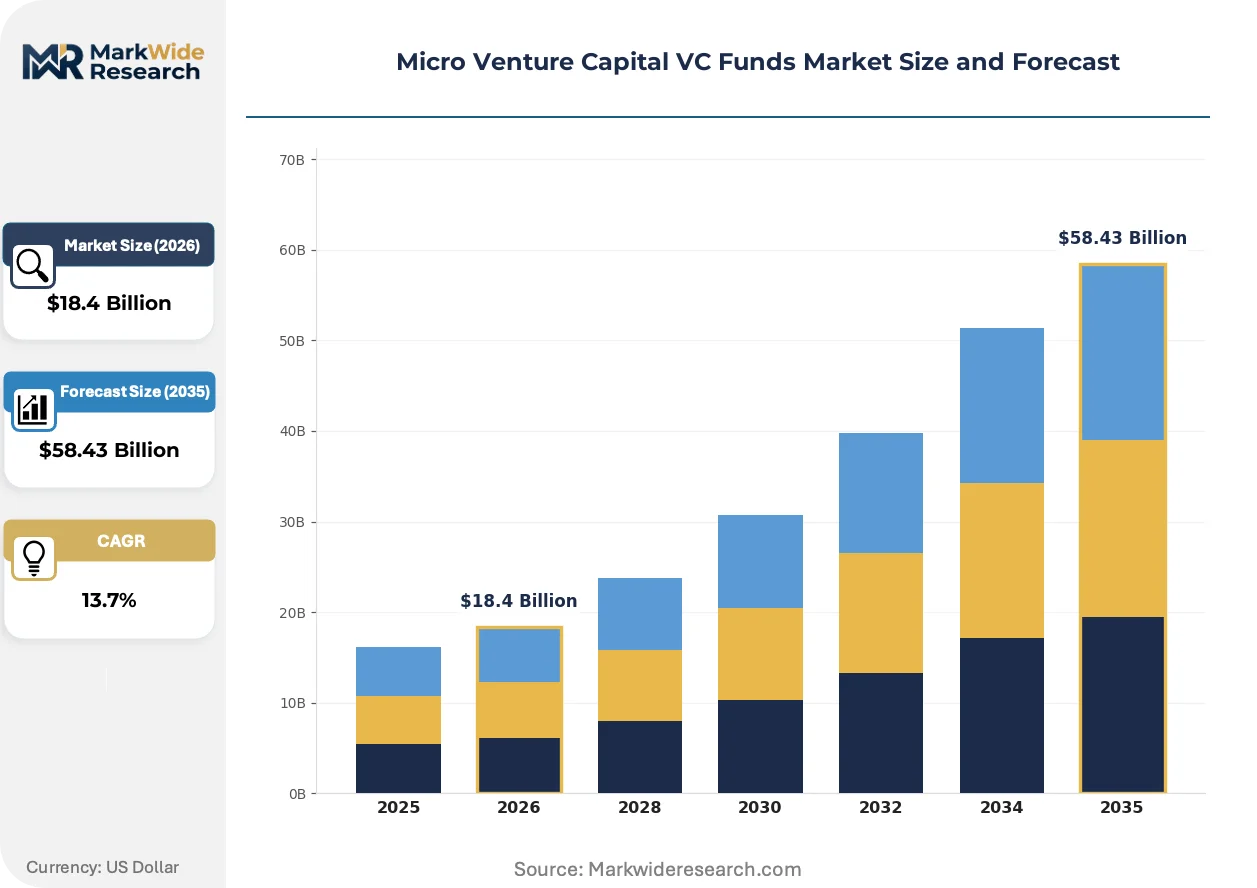
| Market Size in 2026 | $18.4 Billion |
| Market Size in 2035 | $58.43 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fund Focus: Early-Stage Startups, Seed Financing, Growth Capital, Impact Investing, Sector-Specific, Diversified Investor Type: High Net Worth Individuals, Family Offices, Angel Investors, Corporate Investors, Institutional Investors Fund Size: Under $10 Million, $10-$25 Million, $25-$50 Million, $50-$100 Million, Over $100 Million Investment Stage: Pre-Seed, Seed, Series A, Series B, Bridge Financing |
| Companies Covered | First Round Capital, 500 Global, Y Combinator, SV Angel, Bee Partners, Founder Collective, Initialized Capital, Lowercase Capital, MatchStick Ventures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro Venture Capital VC Funds Market Trends and Innovations
Fund administration infrastructure is automating compliance and capital call workflows, compressing operational overhead for lean partnership structures. This shift is enabling smaller teams to manage larger portfolios without proportional headcount expansion.
Blockchain-native cap table management is rewriting how micro VCs track ownership dilution across SAFE stacks and convertible notes. Emerging fund managers in Singapore and Estonia are adopting these tools to reduce administrative drag and improve LP reporting granularity. The technology is compressing back-office costs and redirecting partner time toward sourcing.
The EU's CSRD sustainability disclosure requirements are mandating ESG integration into fund-level reporting for managers marketing to European institutional LPs. This is forcing US-based micro VCs to build carbon accounting and diversity metrics into portfolio monitoring systems. Climate-tech and health-focused funds are responding fastest, embedding impact measurement into term sheet structures.
Angel syndicate platforms are consolidating individual high-net-worth capital into SPV structures that compete directly with traditional micro VC first checks. This channel disintermediation is most visible in the San Francisco Bay Area and London, where operator-angels with exit experience are bypassing fund fees to lead seed rounds directly. Micro VCs are responding by offering portfolio services and follow-on reserves as differentiation.
Micro Venture Capital VC Funds Market Segmentation
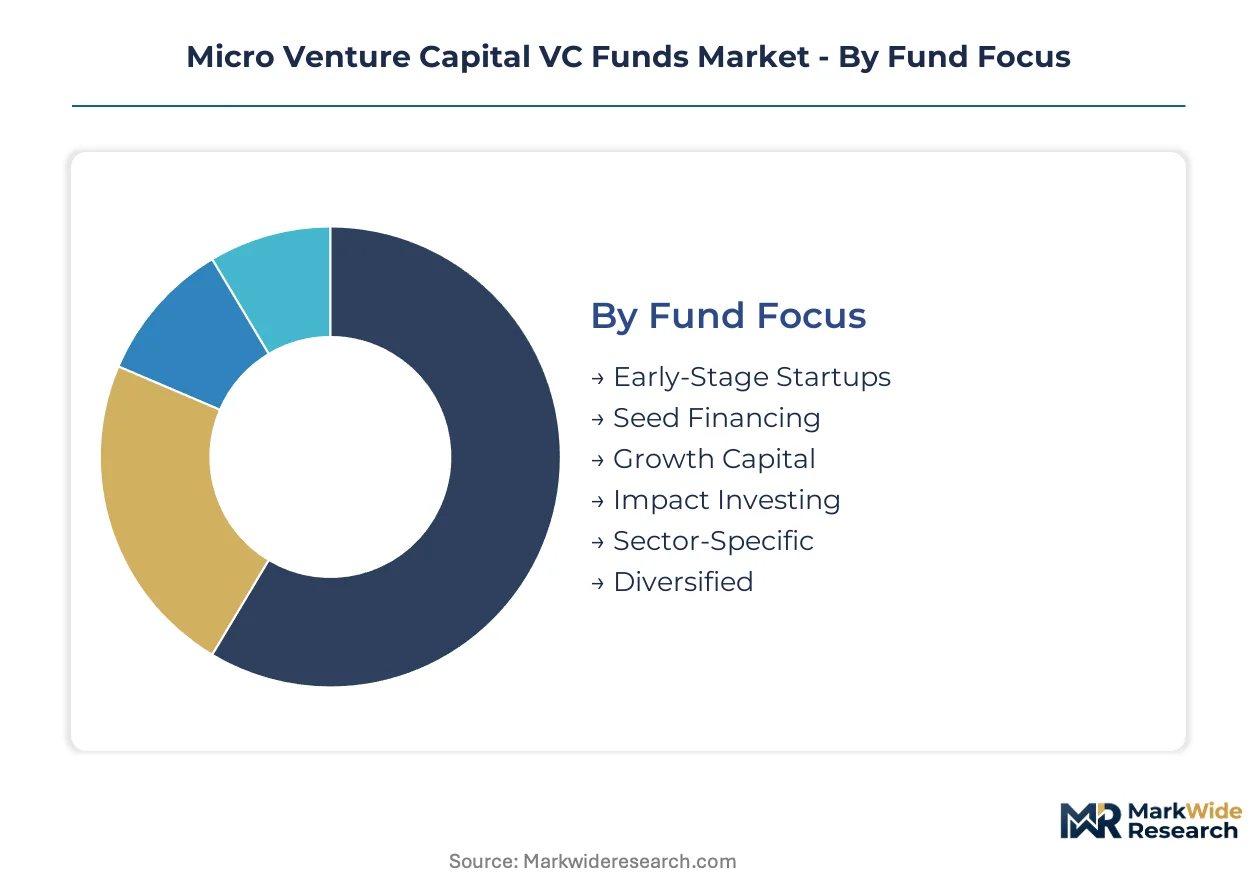
Segmentation in micro venture capital reveals how fund managers align capital structures with investor risk appetites and startup maturity stages. Distinct deployment velocities, fee economics, and regulatory treatment separate these categories. Understanding these divisions illuminates why certain fund sizes dominate by count while others capture disproportionate management yield.
Fund Focus:
Investor risk tolerance and technical due diligence capabilities differentiate buyers across fund focus categories, with family offices gravitating toward sector-specific vehicles while institutions prefer diversified exposure.
- Early-Stage Startups:Deploys capital into companies with minimal revenue traction, typically employing SAFE instruments and convertible notes. Demand concentrates in San Francisco and New York where technical founder density supports portfolio construction at velocity.
- Seed Financing:Targets companies post-product-market fit validation, using priced equity rounds with standardized term sheets. The JOBS Act Rule 506(c) general solicitation provisions are expanding eligible investor pools for these vehicles.
- Growth Capital:Provides expansion financing to revenue-generating companies approaching Series B metrics. Institutional LPs dominate allocations here given lower risk profiles and shorter path to liquidity.
- Impact Investing:Integrates ESG measurement into portfolio monitoring, with EU CSRD disclosure requirements mandating carbon accounting for European LP-facing funds. Climate-tech and health verticals lead deployment.
- Sector-Specific:Concentrates technical due diligence capabilities in domains like synthetic biology or quantum computing, requiring scarce PhD-level investment talent. First Round Capital exemplifies this approach in software and healthcare.
- Diversified:Spreads risk across multiple sectors and geographies, with 500 Global operating accelerator programs across emerging startup ecosystems to sustain deal flow quality.
Diversified funds lead volumes today; sector-specific vehicles are gaining share fastest.
Investor Type:
Capital commitment size and governance involvement separate these buyer categories, with direct indexing preferences reshaping how family offices access early-stage exposure.
- High Net Worth Individuals:Individual accredited investors seeking portfolio diversification through sub-$50 million vehicles, often accessing deals via angel syndicate platforms that consolidate capital into SPV structures.
- Family Offices:Single-family and multi-family offices channeling capital directly into micro VC funds to avoid fund-of-fees, with particular concentration in London and Singapore where regulatory frameworks accommodate alternative investment structures.
- Angel Investors:Operator-angels with exit experience leading seed rounds directly, bypassing traditional fund fees in San Francisco Bay Area and London corridors. Micro VCs respond with portfolio services and follow-on reserves as differentiation.
- Corporate Investors:Strategic venture arms seeking technology optionality and market intelligence, typically co-investing alongside financial sponsors rather than anchoring standalone funds.
- Institutional Investors:Pension funds, endowments, and foundations allocating to established managers with multiple vintage years, prioritizing governance rights and transparency infrastructure.
Institutional investors anchor capital commitments today; family offices are expanding allocations most rapidly.
Fund Size:
Fee economics and operational scalability distinguish these tiers, with the $25 million threshold marking a critical inflection point for sustainable infrastructure coverage.
- Under $10 Million:Lean partnership structures relying on fund administration automation to compress operational overhead, often focusing on single geography or sector to reduce due diligence bandwidth requirements.
- $10-$25 Million:Emerging manager vehicles with first-time GPs, frequently employing carried interest crystallization structures to align compensation with LP distributions despite extended IPO windows.
- $25-$50 Million:Captures disproportionate management fee yield per dollar deployed, enabling dedicated back-office staff and partner-level compensation without institutional scale requirements. SV Angel operates within this tier.
- $50-$100 Million:Approaching traditional venture capital scale while retaining micro VC flexibility, with sufficient reserves for meaningful follow-on participation through Series B.
- Over $100 Million:Exceeds conventional micro VC definition, competing directly with established venture funds for institutional LP allocations and requiring differentiated sourcing strategies.
Funds under $25 million dominate by count; the $25-$50 million segment delivers superior fee efficiency.
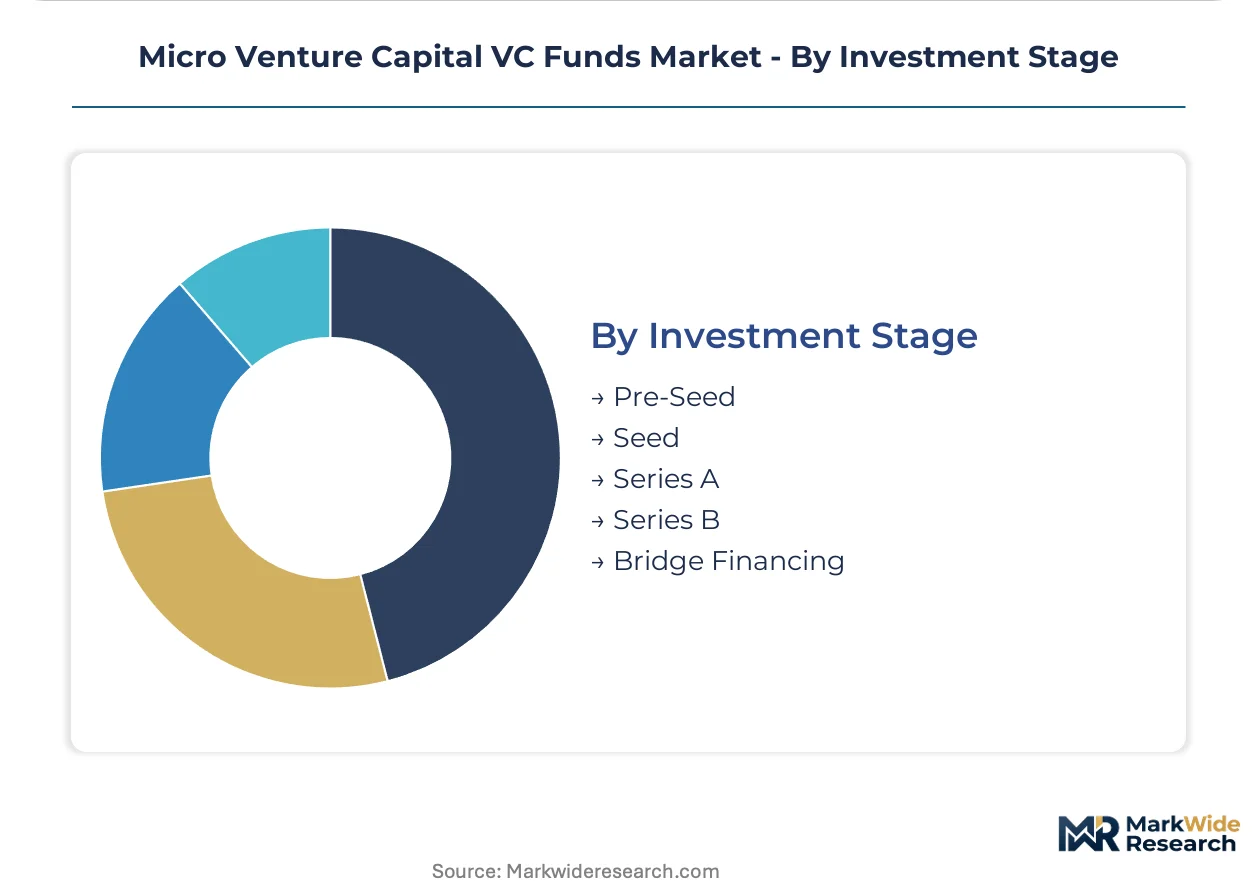
Investment Stage:
Valuation methodology and ownership target differentiation separate these deployment phases, with SAFE instrument standardization compressing legal friction at the earliest stages.
- Pre-Seed:Capitalizes companies at formation or prototype phase, with Y Combinator's post-money SAFE templates reducing documentation overhead and accelerating round velocity across emerging markets.
- Seed:Targets companies with initial traction and defined use-of-proceeds, where recurring revenue models in enterprise software compress time-to-Series A and accelerate deployment velocity for specialists.
- Series A:Priced equity rounds with institutional lead investors, requiring micro VCs to demonstrate value-add beyond capital through portfolio services and network access.
- Series B:Expansion financing with established metrics thresholds, where micro VCs with follow-on reserves compete against growth-stage specialists for allocation.
- Bridge Financing:Interim capital between priced rounds, often structured as convertible notes with valuation caps that create complex cap table dynamics requiring blockchain-native tracking tools.
Seed-stage deployment leads transaction volume today; pre-seed specialization is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States deploys capital at roughly triple the velocity of Germany, yet both markets face converging regulatory pressure on fund marketing disclosures. India and Singapore are capturing spillover demand as managers restructure vehicles for cross-border LP access.
United States
Family offices in New York and San Francisco are channeling capital directly into sub-$50 million vehicles to avoid fund-of-fees. SEC Rule 506(c) under the JOBS Act permits general solicitation to verified qualified purchasers, expanding addressable investor pools beyond traditional institutional LPs. The San Francisco Bay Area maintains the densest concentration of seed-stage software startups, compressing time-to-Series A for specialized managers.
United Kingdom
London-based family offices are accelerating allocations to micro VC structures as direct indexing preferences reshape early-stage exposure. The FCA prudential regime for smaller authorized funds influences structuring decisions for managers accessing capital from British limited partners. The London-Southeast corridor dominates European seed-stage transaction volume, with operator-angels bypassing traditional fund fees to lead rounds directly.
Germany
Corporate venture arms in Munich and Berlin are co-investing alongside financial sponsors rather than anchoring standalone funds, seeking technology optionality and market intelligence. EU AIFMD transparency and leverage constraints limit European LP access for non-EU domiciled managers without passport arrangements. The Berlin-Brandenburg cluster is emerging as a secondary hub for pre-seed synthetic biology and climate-tech specialization.
India
SEBI's Alternative Investment Fund regulations and PLI scheme spillovers are creating compliant structures for sector-specific micro VC deployment. Single-family offices in Mumbai and Bangalore are expanding allocations most rapidly, drawn by software-as-a-Service penetration and recurring revenue model adoption. The Maharashtra-Karnataka corridor concentrates technical founder density sufficient to sustain portfolio construction at velocity.
Singapore
Blockchain-native cap table management tools are compressing back-office costs for emerging fund managers seeking to reduce administrative drag. The Monetary Authority of Singapore's regulatory sandbox framework accommodates alternative investment structures targeting Southeast Asian startup ecosystems. The city-state serves as a restructuring hub for US and European managers seeking Asian LP access without AIFMD friction.
Micro Venture Capital VC Funds Market Competitive Landscape
US-based managers anchor the high-velocity tier; European and Asian specialists hold differentiated positions through regulatory arbitrage and sector concentration. The market structure remains fragmented across fund sizes, with no single manager capturing institutional-scale dominance. Three archetypes prevail: thematic sector specialists, geographic diversifiers, and founder-network density concentrators. Competitive moves center on fund administration automation to compress operational overhead, and strategic partnerships with angel syndicate platforms to defend deal flow access.
Within the thematic specialist tier, First Round Capital exemplifies sustained deal flow quality through software and healthcare concentration across multiple vintage years. 500 Global occupies a position as the geographic diversifier archetype, operating accelerator programs across emerging startup ecosystems to sustain portfolio construction velocity. SV Angel anchors the founder-network density approach, concentrating capital deployment through relationship-intensive sourcing rather than sector breadth. These three represent distinct strategic postures available to sub-$100 million vehicles competing for limited partner allocations.
| Leading Market Players |
|---|
| First Round Capital |
| 500 Global |
| Y Combinator |
| SV Angel |
| Bee Partners |
| Founder Collective |
| Initialized Capital |
| Lowercase Capital |
| MatchStick Ventures |
| Others |
Pricing and Supply Chain Analysis
Family offices seeking direct early-stage exposure without fund-of-fees are concentrating capital commitments in sub-$50 million vehicles, anchoring a two-tier pricing model that separates premium manager access from emerging GP economics. This buyer archetype concentration compresses fee negotiations at the lower fund-size threshold while elevating carried interest crystallization terms as the primary price differentiation mechanism.
Pricing Analysis
Capacity additions in Singapore and Estonia are reshaping price floors for fund administration services as blockchain-native cap table tools compress back-office costs. Three-tier pricing structure across premium, standard, and economy levels separates established multi-vintage managers from first-time GPs and lean syndicate structures. Pricing pressure stems from angel syndicate platforms consolidating high-net-worth capital into SPV structures that compete directly for seed-stage allocations. First-time GPs exhibit highest price sensitivity, while institutional LPs anchor premium tier commitments.
Supply Chain Analysis
PhD-level investment talent scarcity in the San Francisco Bay Area and Boston corridors constrains technical due diligence bandwidth for sector-specific fund strategies. Fund formation draws from Delaware and Cayman Islands domicile structures, SEC Rule 506(c) compliance infrastructure, and EU AIFMD marketing passport arrangements. Single-source vulnerability concentrates in administrator relationships for sub-$25 million vehicles. Distribution runs through placement agent networks, direct family office relationships, and emerging digital fundraising platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where Singapore's regulatory sandbox framework accommodates alternative investment structures at compliance costs below EU AIFMD thresholds, enabling US managers to access Asian LP capital without European marketing friction.
For Market Incumbents: Deploy fund administration automation to compress operational overhead and defend against angel syndicate platform disintermediation. Incumbents should anchor follow-on reserves as competitive differentiation while building carbon accounting infrastructure to satisfy EU CSRD disclosure requirements for European LP-facing funds. For New Entrants and Emerging Players: Capture India's startup ecosystem maturation by structuring SEBI-compliant Alternative Investment Funds targeting software-as-a-Service penetration in the Maharashtra-Karnataka corridor. Climate-tech verticalization offers the most penetrable segment, with decarbonization seed funds aligning to IRA production tax credit spillovers. For Investors and Strategic Acquirers: Corporate venture arms are the most active acquirer in this space, seeking technology optionality through co-investment structures rather than standalone fund anchoring. Acquisition targets should display sector-specific technical due diligence capabilities and demonstrated follow-on reserve deployment. Watch SAFE instrument standardization velocity across emerging markets as inflection indicator for pre-seed round accessibility.| Strategic Initiative | Industry Significance |
|---|---|
| Fund Administration Automation | Blockchain-native cap table tools in Singapore compress back-office costs for lean partnership structures. |
| Geographic Diversification | 500 Global's accelerator programs across emerging ecosystems sustain portfolio construction velocity. |
| Sector-Specific Concentration | First Round Capital's software and healthcare focus sustains deal flow quality across vintage years. |
| Founder-Network Density | SV Angel's relationship-intensive sourcing model differentiates through capital deployment selectivity. |
| Regulatory Arbitrage Structuring | Singapore's sandbox framework enables US managers to access Asian LP capital without AIFMD friction. |
Research Methodology
Bottom-up fund formation modeling reconciled against top-down capital deployment tracking forms the analytical core of this study. Primary interviews with general partners, limited partners at family offices, fund administrators, and regulatory compliance officers combined with secondary validation against SEC Form D filings, SEBI Alternative Investment Fund registrations, and EU AIFMD marketing disclosures. Top-down triangulation incorporates capital call velocity data and portfolio company exit tracking.
Historical trendline analysis across fund size tiers, investment stages, and geographic domiciles established baseline growth patterns. The projection horizon models fund focus categories, investor type segmentation, and regional regulatory framework clusters. CAGRs derive from vintage year performance reconciliation against capital formation rule changes. Forecast inputs include JOBS Act accreditation expansion velocity and SAFE instrument adoption rates.
Accredited investor definition revisions, cross-border marketing passport availability, and IPO window duration are the dominant revision risks. Forecasts reflect assumptions about regulatory stability and capital formation accessibility. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
Asia-Pacific Venture Capital Investment Market
Venture Capital
Micro VC Funds Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
North America Venture Capital Market
Venture Capital
Crowdfunding Market
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
United States Venture Capital Market
Venture Capital
Venture Capital Investment Market
Venture Capital
Business Incubator Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
Asia Pacific Venture Capital Market
Venture Capital
Impact Investing Market
Venture Capital
US Venture Capital Investment Market
Venture Capital
Europe Venture Capital Market
Venture Capital
Angel Funds Market
Venture Capital
Global Art Crowdfunding Market