
 Asia-Pacific Venture Capital Investment Market | 2026-2036
Asia-Pacific Venture Capital Investment Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Venture Capital Investment Market Insights
Enterprise software is repositioning the Asia-Pacific venture capital landscape toward vertical SaaS and AI infrastructure. Peak XV Partners leverages its India-Southeast Asia network to sustain early-stage dealflow across fintech and climate tech. DCM Ventures anchors cross-border capital between China and Indonesia through dedicated growth funds. East Ventures competes on seed-stage velocity, deploying smaller checks at higher frequency than regional peers.
Venture capital investment denotes equity financing provided to private companies exhibiting high growth potential, typically exchanged for minority ownership stakes with expected holding periods of five to ten years before exit via IPO or acquisition. The asset class functions as primary growth fuel for unlisted firms unable to access public debt or equity markets. Seed stage deployment leads absolute deal count across the region, though growth stage funding commands the dominant share of total capital deployed. Institutional investor participation is accelerating as pension funds and sovereign vehicles increase alternative allocation targets. Sector focus tilts heavily toward technology, with healthcare and energy attracting selective specialist capital.
India's SEBI regulates Alternative Investment Funds through strict registration and disclosure mandates that shape fund formation timelines. Singapore's MAS oversees fund managers through licensing frameworks that determine market access for foreign capital pools. Australia's ASIC enforces retail investor protections that constrain certain venture fund marketing channels. Stakeholders must monitor evolving cross-border data localization rules that threaten SaaS valuation multiples across multiple jurisdictions.
Market Dynamics
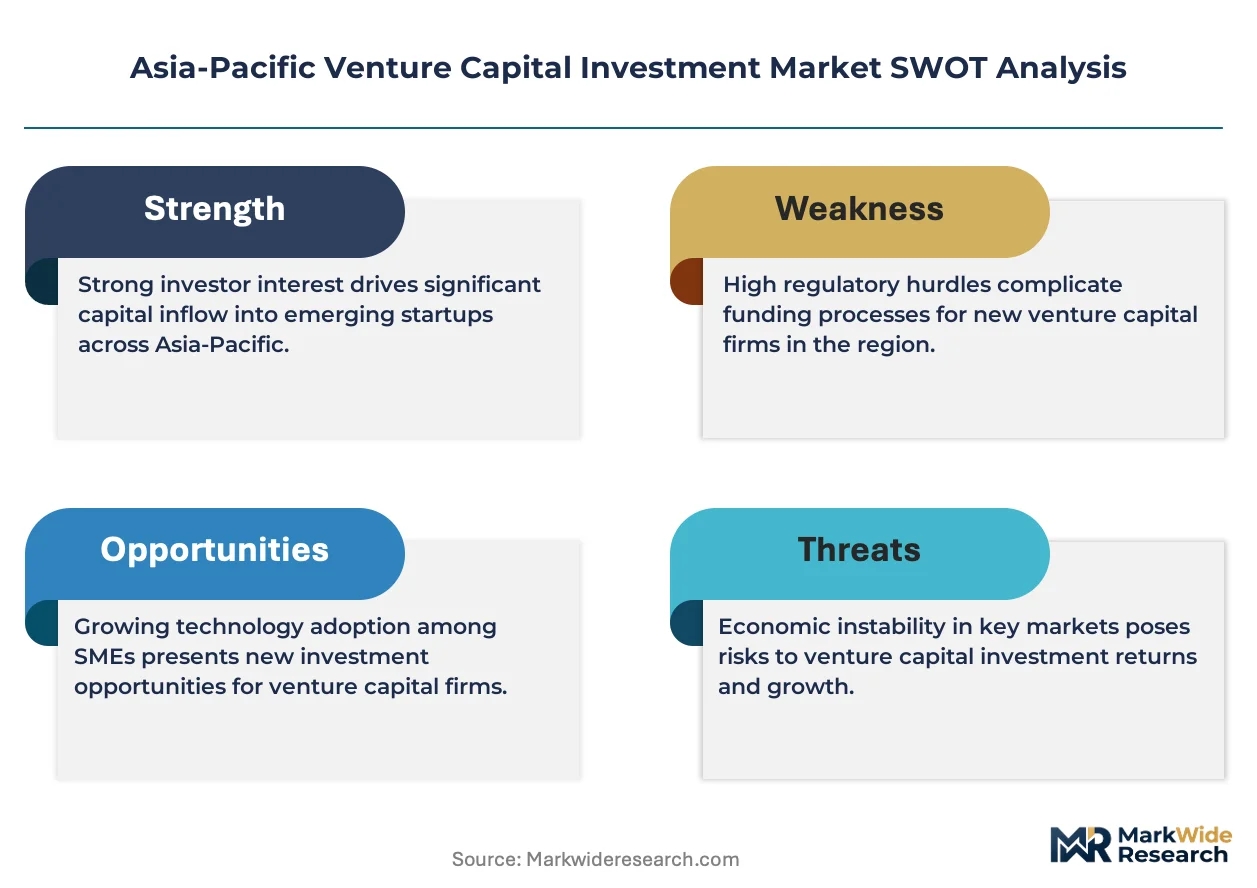
Sovereign wealth funds across Southeast Asia are compressing fund-raising timelines for growth-stage vehicles, redirecting institutional capital toward climate tech and semiconductor infrastructure. This concentration of state-backed liquidity is altering term-sheet negotiations and valuation benchmarks.
Growth Catalysts
- India's PLI scheme for electronics manufacturing:Production-linked incentives are channeling domestic institutional capital toward semiconductor design and advanced packaging startups. SEBI-registered AIFs are accelerating deployment timelines.
- Singapore's MAS licensing frameworks:Streamlined fund manager authorization is attracting foreign capital pools seeking Southeast Asia exposure. The regulatory clarity reduces formation friction for cross-border vehicles.
- Embedded finance platforms:Fintech infrastructure across Indonesia and Vietnam is generating recurring revenue models that attract growth-stage checks from regional family offices.
Market Restraints
- Cross-border data localization mandates:India's draft data protection rules and Vietnam's cybersecurity law are fragmenting SaaS architecture and compressing valuation multiples for regional software plays.
- Limited secondary market liquidity:The absence of structured secondaries across Southeast Asia extends holding periods and traps capital in aging fund vintages.
- Currency volatility:Rupee and rupiah fluctuations against the dollar are eroding IRR calculations for USD-denominated funds deploying local currency.
Strategic Opportunities
- Climate tech infrastructure:Grid-scale battery storage and carbon accounting software in Australia and South Korea are attracting specialist capital as METI and CEA accelerate clean energy procurement mandates.
- AI infrastructure at the edge:Convergence of chip design and sovereign cloud requirements is creating deployment opportunities in Taiwan and Japan beyond traditional data center hubs.
- Philippines fintech penetration:Underbanked SME segments are driving demand for working capital platforms that bypass traditional correspondent banking networks.
Industry Challenges
- Technical due diligence capacity:Deep-tech semiconductor and quantum computing investments require specialized evaluation expertise that remains concentrated in Silicon Valley and Shenzhen, forcing regional GPs to outsource critical assessment functions.
- Founder vesting enforcement:Weak contractual precedent across Indonesia and Thailand complicates equity clawback provisions when founding teams fracture.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Venture Capital Investment Market |
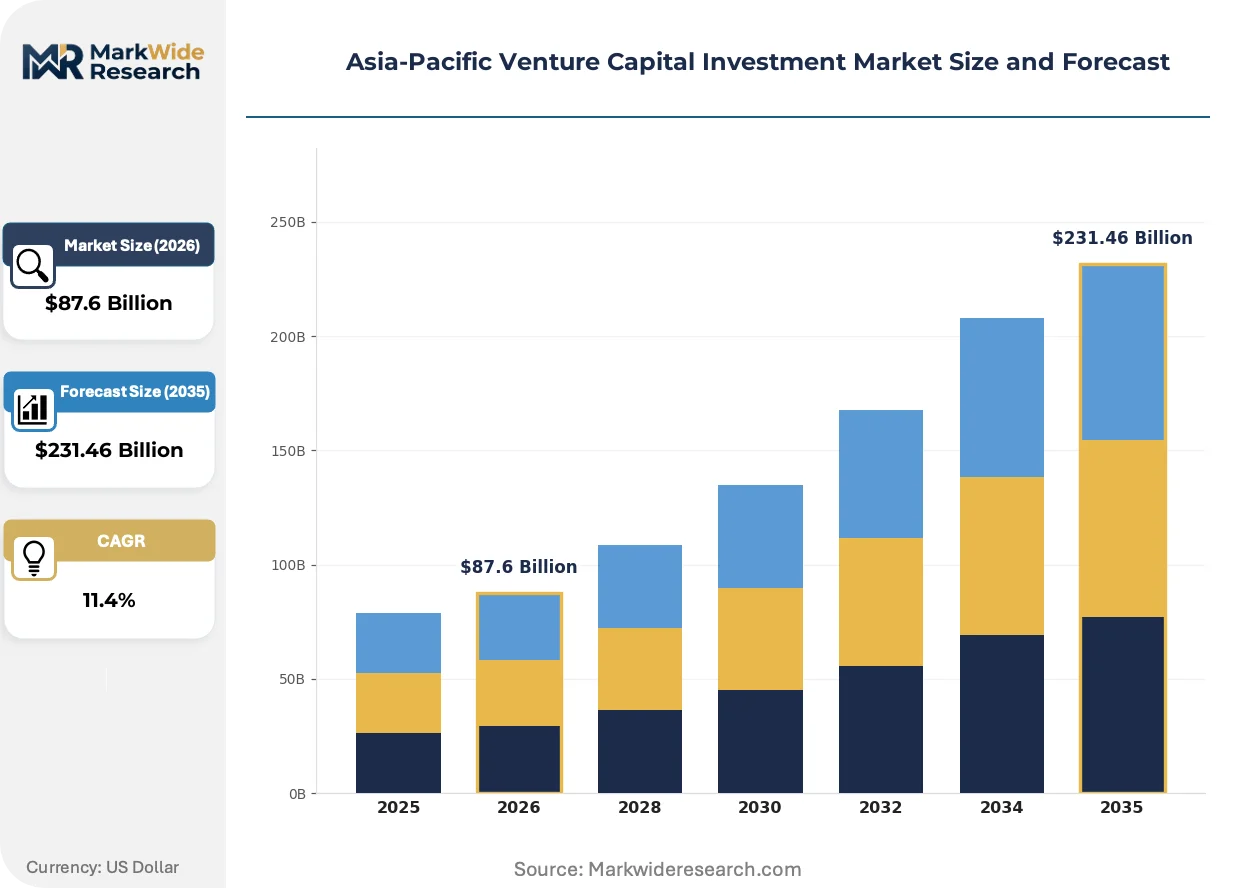
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $231.46 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed Stage, Early Stage, Growth Stage, Later Stage Investor Type: Corporate Investors, Angel Investors, Private Equity Firms, Institutional Investors Sector Focus: Technology, Healthcare, Energy, Consumer Goods Funding Size: Micro, Small, Medium, Large |
| Companies Covered | Incubate Fund, DCM Ventures, East Ventures, Golden Gate Ventures, Vertex Ventures Southeast Asia & India, Venture United, Gaorong Capital, Peak XV Partners, Shanda Capital, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Venture Capital Investment Market Trends and Innovations
Capital deployment patterns across the Asia-Pacific venture landscape are fragmenting as AI infrastructure and climate hardware absorb larger check sizes. Fund managers are restructuring carry and management fee terms to align with extended holding periods.
Generative AI infrastructure is converging with sovereign cloud requirements as governments from Seoul to Canberra mandate domestic data processing for sensitive workloads. Defense contractors and national research agencies are becoming anchor limited partners for specialized funds. This convergence is compressing the timeline for edge computing deployment and displacing generic cloud migration strategies.
India's SEBI is tightening disclosure requirements for Category II AIFs investing in unlisted debt, forcing fund managers to restructure side-pocket arrangements and enhance quarterly reporting granularity. The regulatory friction is most acute for credit-focused vehicles targeting real estate and infrastructure developers. Several Singapore-domiciled funds are restructuring as Mauritius-based entities to preserve treaty benefits.
Institutional limited partners are unbundling manager selection from direct co-investment rights, demanding separate fee structures for proprietary deal access. Korean pension funds and Australian superannuation vehicles are building in-house venture teams to originate opportunities independently. This behavioral shift is most visible in growth-stage semiconductor and battery material investments where ticket sizes exceed fifty million dollars.
Asia-Pacific Venture Capital Investment Market Segmentation
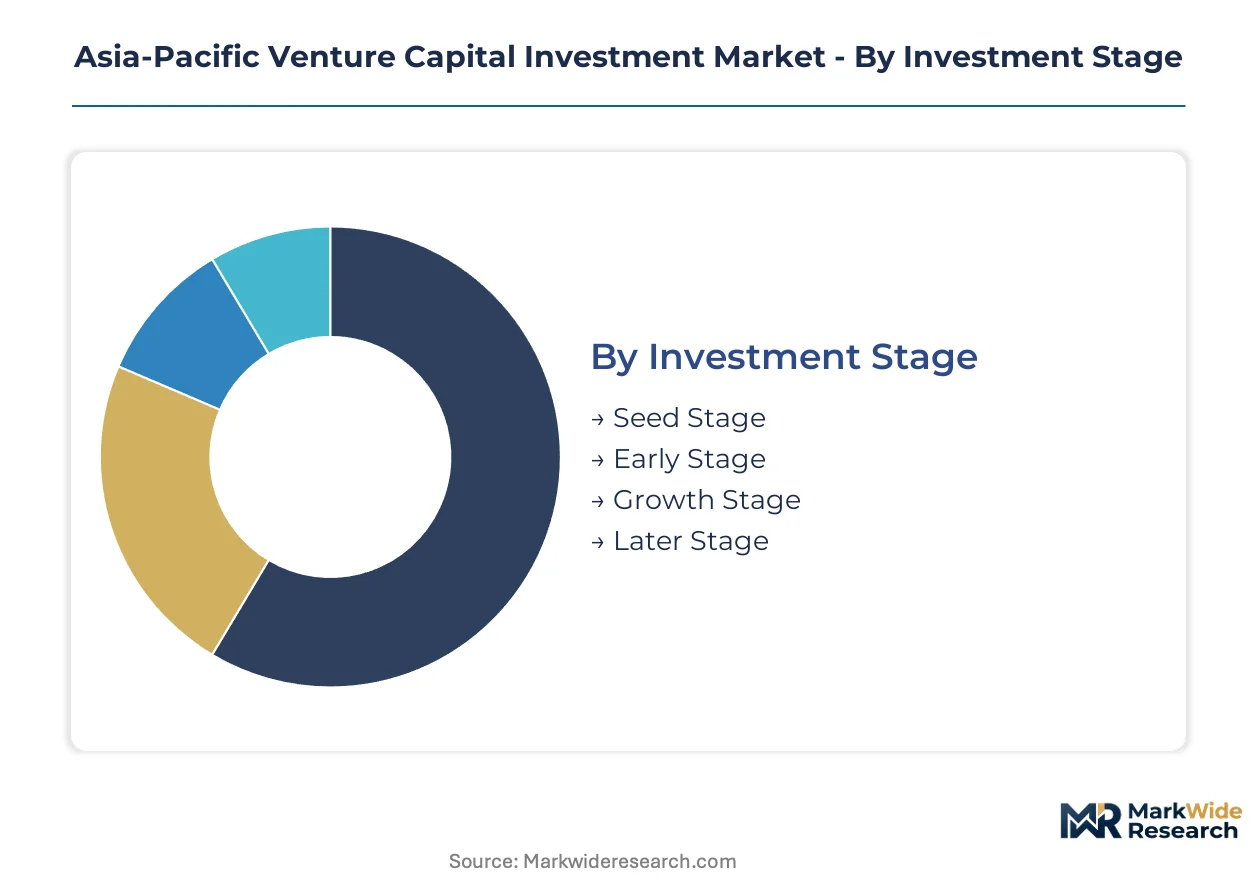
Segmentation reveals how capital deployment patterns diverge across risk profiles and check sizes in the Asia-Pacific venture landscape. Fund managers structure dedicated vehicles around stage-specific holding periods and sector expertise to optimize portfolio construction.
Investment Stage:
Standalone venture funds target discrete stages with specialized due diligence protocols, while multi-stage vehicles embed stage-agnostic deployment across integrated capital stacks.
- Seed Stage:Deployments below two million dollars support product-market fit validation and initial team expansion. Concentrated demand flows from Singapore-based accelerators and Jakarta's founder networks as SEBI-registered AIFs compress first-check timelines for Indian deeptech ventures.
- Growth Stage:Checks ranging ten to fifty million dollars fuel geographic expansion and revenue scaling. Deployment concentrates in Vietnam's embedded finance platforms and South Korean battery material startups as sovereign wealth funds anchor dedicated growth vehicles.
- Early Stage:Series A and B rounds bridge technical validation toward commercial traction.
- Later Stage:Pre-IPO and secondary transactions target liquidity preparation and acquisition readiness.
Volume placements concentrate in Growth Stage; the faster expansion belongs to Seed Stage.
Investor Type:
Cost-tier stratification separates high-frequency small checks from concentrated institutional allocations with divergent fee tolerance and governance requirements.
- Institutional Investors:Pension funds and sovereign wealth vehicles deploy through fund-of-funds and direct co-investment structures. Korean NPS and Australian superannuation funds are building in-house venture teams to originate semiconductor and climate infrastructure opportunities independently.
- Corporate Investors:Strategic balance sheet deployment targets vertical integration and technology acquisition pathways. Japanese trading houses and Indian conglomerates are establishing captive venture arms to secure AI infrastructure and supply chain software stakes.
- Angel Investors:High-net-worth individuals deploy personal capital at earliest formation stages.
- Private Equity Firms:Buyout shops are extending into growth equity through dedicated technology sleeves.
Check concentration sits with Institutional Investors; velocity leadership belongs to Angel Investors.
Sector Focus:
Application-driven segmentation maps capital intensity and regulatory exposure across divergent margin profiles and exit pathway clarity.
- Technology:Enterprise SaaS, AI infrastructure, and fintech platforms absorb the dominant share of regional deployment. Singapore's MAS licensing clarity and India's data localization mandates are fragmenting architecture choices and compressing valuation multiples for cross-border software plays.
- Energy:Grid-scale storage and carbon accounting software attract specialist capital as METI and Australia's CEA accelerate procurement mandates. Battery material startups in South Korea and solar financing platforms in the Philippines are commanding premium entry valuations.
- Healthcare:Biotech and digital health face extended holding periods and regulatory complexity.
- Consumer Goods:E-commerce enablement and direct-to-brand platforms draw selective family office interest.
Capital deployment concentrates in Technology; steepest expansion trajectory belongs to Energy.
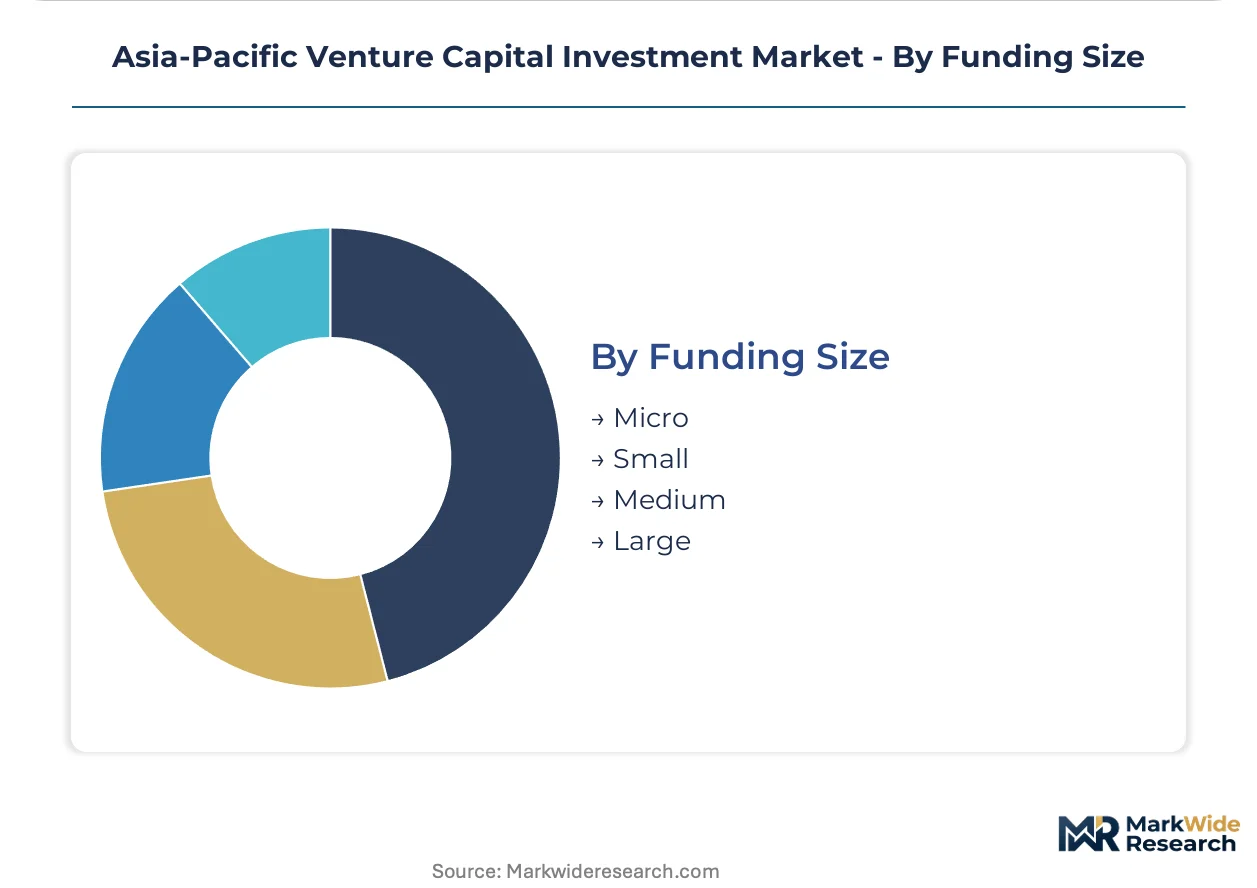
Funding Size:
Customer-type segmentation distinguishes micro-grants for first-time founders from institutional-scale allocations requiring dedicated portfolio management infrastructure.
- Large:Checks exceeding fifty million dollars target semiconductor foundries and climate infrastructure with sovereign anchor participation. Taiwan's chip design ecosystem and Australia's grid battery deployments are absorbing the majority of regional large-ticket deployment.
- Medium:Twenty to fifty million dollar rounds support Series C expansion and cross-border market entry.
- Small:Five to twenty million dollar checks dominate Series A and B activity across Southeast Asia.
- Micro:Sub-five million dollar deployments concentrate in accelerator cohorts and university spinout programs.
Deal flow volume concentrates in Small; gaining share fastest belongs to Large.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jurong Innovation District and Singapore's one-north precinct concentrate venture deployment infrastructure across Southeast Asia. Sovereign wealth vehicles anchor dedicated growth funds through streamlined MAS licensing frameworks. This spatial concentration compresses fundraising timelines for climate tech and semiconductor vehicles.
India
Domestic institutional capital flows toward semiconductor design startups under SEBI-registered AIF structures. The PLI scheme for electronics manufacturing accelerates deployment timelines for advanced packaging ventures. Bangalore and Hyderabad anchor deeptech formation activity as Peak XV Partners sustains early-stage dealflow across climate tech.
Singapore
Sovereign wealth fund corridors channel state-backed liquidity toward growth-stage term-sheet negotiations. MAS licensing clarity attracts foreign capital pools seeking Southeast Asia exposure through streamlined fund manager authorization. One-north and Marina Bay financial districts concentrate family office deployment into embedded finance platforms.
Indonesia
Embedded finance infrastructure generates recurring revenue models that attract regional family office capital. The country's national financial services authority shapes fintech licensing requirements that determine market access for foreign investors. Jakarta's founder networks drive seed-stage velocity as East Ventures deploys smaller checks at higher frequency than regional peers.
South Korea
Battery material startups command premium entry valuations as METI accelerates clean energy procurement mandates. The national pension service builds in-house venture teams to originate semiconductor opportunities independently. Seoul Capital Area and Busan-Ulsan corridors anchor grid-scale storage deployment specialist capital.
Vietnam
Underbanked SME segments drive demand for working capital platforms bypassing traditional correspondent banking networks. Cybersecurity law fragments SaaS architecture and compresses valuation multiples for regional software plays. Ho Chi Minh City and Hanoi concentrate fintech penetration as DCM Ventures anchors cross-border capital between China and Indonesia.
Asia-Pacific Venture Capital Investment Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with early-stage velocity specialists competing against growth-stage concentration vehicles. The regional landscape fragments across seed-stage deployment frequency and large-ticket sovereign anchoring. Three archetypes dominate: India-Southeast Asia network funds, cross-border China-Indonesia capital bridges, and seed-stage velocity operators. Competitive moves concentrate on fund formation timeline compression and direct co-investment right unbundling.
Among India-Southeast Asia network specialists, Peak XV Partners exemplifies the early-stage dealflow archetype through sustained climate tech and fintech deployment. DCM Ventures occupies a position representing cross-border capital bridge structures between China and Indonesia through dedicated growth funds. East Ventures sits within the seed-stage velocity tier, deploying smaller checks at higher frequency than regional peers. These three entities collectively represent the dominant competitive positioning patterns across the regional venture landscape.
| Leading Market Players |
|---|
| Incubate Fund |
| DCM Ventures |
| East Ventures |
| Golden Gate Ventures |
| Vertex Ventures Southeast Asia & India |
| Venture United |
| Gaorong Capital |
| Peak XV Partners |
| Shanda Capital |
| Others |
Pricing and Supply Chain Analysis
Benchmark interest rate spreads across Singapore dollar and Indian rupee debt markets cascade through fund formation economics into management fee tiers. Sovereign wealth fund anchoring compresses fundraising timelines for growth vehicles while currency volatility erodes IRR calculations for USD-denominated funds deploying local currency.
Pricing Analysis
Short lead-time deployment commands premium carry structures as family offices compete for allocation into oversubscribed Indonesia growth rounds. Pricing stratifies across sovereign-anchored, institutional fund-of-funds, and retail-accessible feeder structures based on ticket size minimums and co-investment rights. Cost compression in seed-stage management fees is intensifying as East Ventures and comparable velocity operators deploy at higher frequency with smaller checks. Emerging fund managers exhibit the highest price sensitivity due to regulatory compliance burdens and formation friction.
Supply Chain Analysis
Direct-to-sovereign channels handle hyperscale institutional demand while fund-of-funds structures aggregate smaller allocations into feeder vehicles. Capital formation concentrates in Singapore, India, and South Korea as SEBI-registered AIFs and MAS-licensed managers anchor regional deployment. Raw material dependencies include technical due diligence expertise from Silicon Valley, Shenzhen semiconductor evaluation capacity, and climate infrastructure procurement networks from Tokyo to Canberra. Single-source vulnerability sits with cross-border data localization mandates fragmenting SaaS architecture across India and Vietnam. Distribution runs through sovereign wealth corridors, institutional consultant gatekeepers, and direct GP-LP relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around sovereign-anchored growth vehicles as cross-border regulatory fragmentation forces smaller managers into subscale positions.
For Market Incumbents: Acquire technical due diligence capabilities in semiconductor and quantum computing evaluation to reduce outsourcing dependency on Silicon Valley and Shenzhen specialists. Anchor India-Southeast Asia network funds should deepen climate infrastructure origination capacity as METI and CEA procurement mandates accelerate. Regulatory headwinds from SEBI disclosure tightening and Vietnam cybersecurity law fragmentation threaten SaaS valuation multiples and demand proactive side-pocket restructuring. For New Entrants and Emerging Players: Begin with Philippines fintech penetration targeting underbanked SME working capital platforms that bypass traditional correspondent banking networks. White-space opportunities concentrate in grid-scale battery storage origination across Australia's CEA procurement corridors and South Korean METI-mandated clean energy deployment. Go-to-market positioning should emphasize sovereign cloud convergence with generative AI infrastructure at the edge in Taiwan and Japan. For Investors and Strategic Acquirers: Distressed-cycle entries favor Mauritius-restructured vehicles preserving treaty benefits as Singapore-domiciled funds face SEBI Category II AIF disclosure friction. Long-term viability over the analysis window favors managers with demonstrated sovereign LP anchoring and cross-border China-Indonesia capital bridge structures. Watch for inflection in secondary market liquidity development across Southeast Asia as structured exit pathways mature.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign LP Anchoring | Mas-licensed fund managers attract state-backed liquidity compressing fundraising timelines for growth vehicles. |
| Technical Due Diligence Buildout | In-house semiconductor evaluation capacity reduces dependency on Silicon Valley and Shenzhen outsourcing. |
| Cross-Border Vehicle Restructuring | Mauritius-domiciled structures preserve treaty benefits as SEBI disclosure requirements tighten. |
| Climate Infrastructure Specialization | Grid-scale battery and carbon accounting software align with METI and CEA procurement mandates. |
| Edge Computing Deployment | Sovereign cloud convergence with generative AI infrastructure creates opportunities beyond traditional data center hubs. |
Research Methodology
SEBI regulatory filings, MAS fund manager licensing databases, and sovereign wealth fund annual reports formed the secondary backbone for fund formation timeline and capital flow analysis. Primary interviews with venture capital general partners, institutional limited partner allocation officers, and regulatory compliance consultants validated deployment patterns and fee structure evolution. Bottom-up and top-down triangulation reconciled deal-level databases with macroeconomic capital flow indicators across the Asia-Pacific corridor.
Bottom-up modeling aggregated individual fund vintages by stage and sector while top-down analysis calibrated against aggregate alternative allocation targets from Korean NPS and Australian superannuation vehicles. Segmentation dimensions included investment stage, investor type, sector focus, and funding size tier across the projection horizon. CAGRs derived from historical deployment velocity and sovereign liquidity injection patterns. Industry-specific forecast inputs incorporated PLI scheme acceleration timelines and cross-border data localization regulatory trajectories.
Underlying measurement precision varies by segment; growth-stage and sovereign-anchored vehicles carry tighter precision than seed-stage velocity operators. Forecasts reflect assumptions around sovereign wealth fund allocation continuity and regulatory stability across SEBI and MAS jurisdictions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
Angel Funds Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
North America Venture Capital Market
Venture Capital
Impact Investing Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
Micro VC Funds Market
Venture Capital
Europe Venture Capital Market
Venture Capital
United States Venture Capital Market
Venture Capital
Crowdfunding Market
Venture Capital
US Venture Capital Investment Market
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Venture Capital Investment Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
Micro Venture Capital VC Funds Market
Venture Capital
Asia Pacific Venture Capital Market