
 North America Venture Capital Market | 2026-2036
North America Venture Capital Market Size, Share, and Industry Trends Forecast 2026-2036
North America Venture Capital Market Analytics
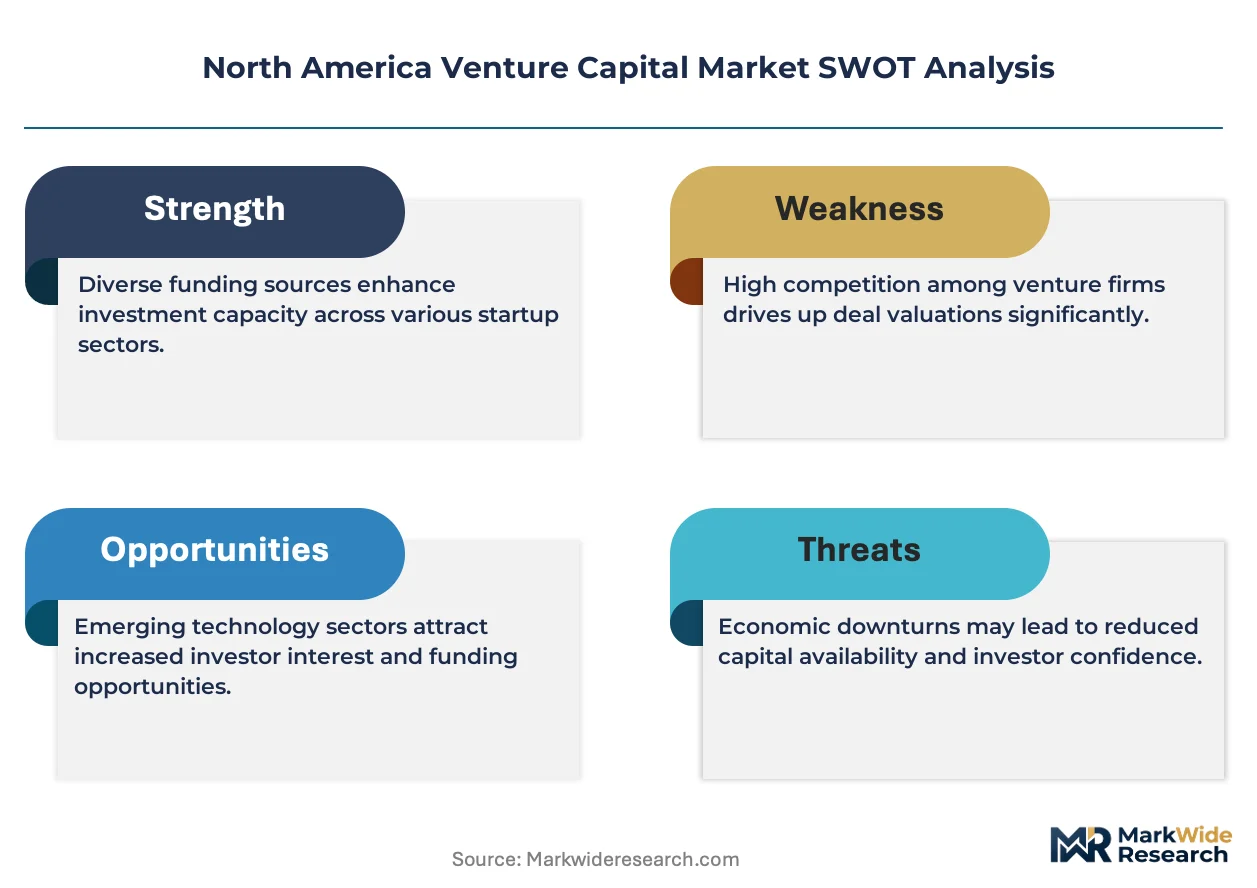
The Inflation Reduction Act is realigning venture deployment toward clean energy and decarbonization startups across the United States. Andreessen Horowitz leverages dedicated climate funds to capture first-mover positions in carbon removal and grid storage. Sequoia Capital anchors its thesis on software-defined energy systems and industrial automation. Khosla Ventures specializes in hard-tech bets spanning fusion, advanced materials, and sustainable aviation.
Venture capital denotes equity financing provided to private companies exhibiting high growth potential, typically structured through limited partnerships with ten-to-fifteen-year horizons and carried-interest compensation for general partners. Early-stage funding commands premium valuations in artificial intelligence infrastructure and biotechnology platforms where technical validation precedes revenue generation. Growth-stage deployment concentrates in fintech verticals where regulatory clarity and unit economics maturity attract institutional limited partners. Fund structure preferences shift toward concentrated venture funds over accelerator vehicles as limited partners prioritize governance control and direct board influence.
The Securities and Exchange Commission shapes disclosure requirements and accredited-investor thresholds governing fund formation and capital solicitation across the United States. The Internal Revenue Service structures carried-interest taxation and qualified small business stock exemptions that directly influence fund economics and entrepreneur incentives. Canadian securities commissions coordinate provincial harmonization efforts affecting cross-border fund marketing and investor eligibility. Stakeholders must monitor evolving antitrust scrutiny of platform acquisitions and pending retirement-account access rules that could reshape retail capital inflows into private markets.
Market Dynamics
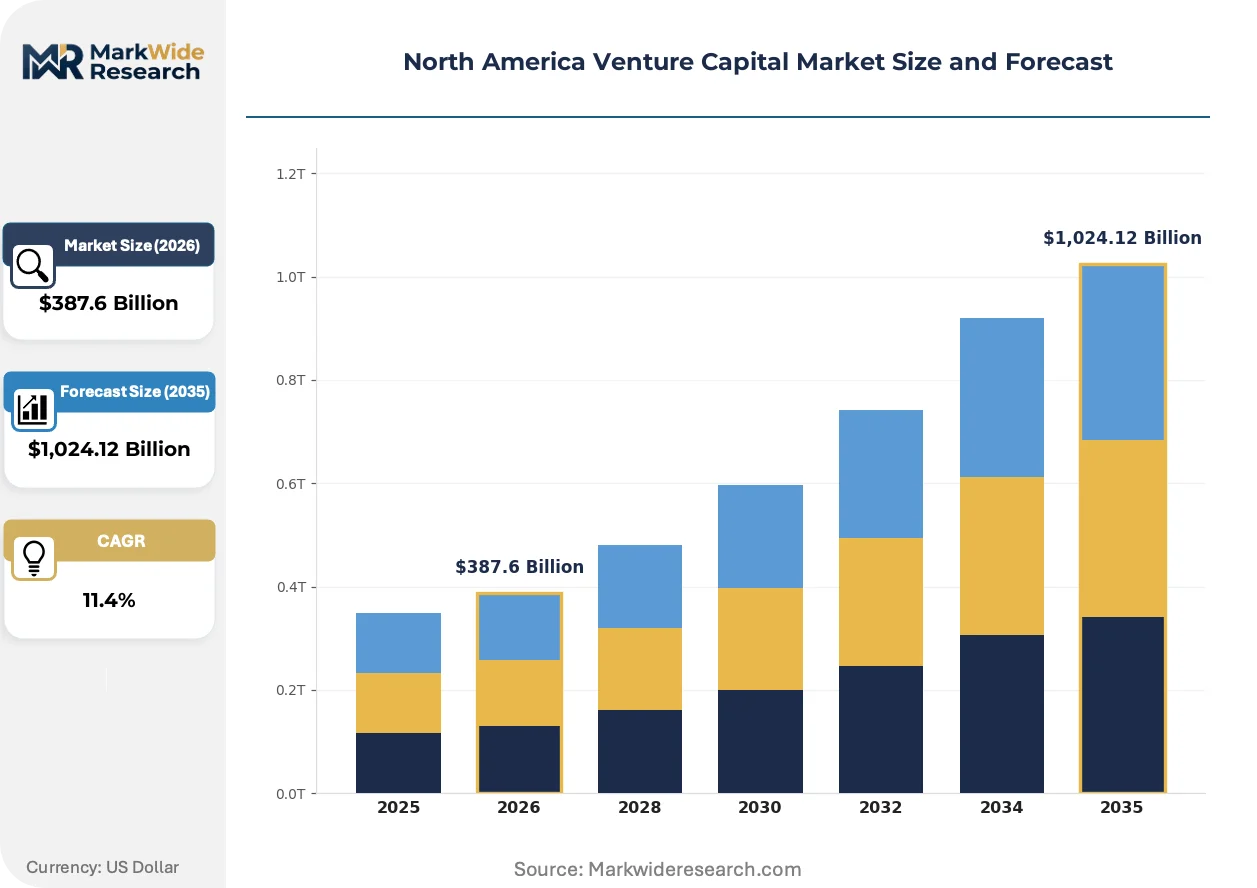
The Inflation Reduction Act's production tax credits and loan guarantee programs are redirecting institutional limited partner commitments toward climate-tech and decarbonization startups, compressing capital formation timelines for clean energy ventures while elevating valuations in grid storage and carbon removal.
Growth Catalysts
- IRA Tax Credits:The Inflation Reduction Act's Section 45Q and 48C provisions subsidize carbon capture and clean hydrogen production, pulling pension fund allocations into hard-tech climate portfolios.
- Healthcare AI Infrastructure:FDA breakthrough device pathways accelerate regulatory validation for diagnostic algorithms, shortening time-to-revenue for biotechnology platforms and attracting crossover capital from public equity investors.
- Texas Energy Grid:ERCOT market volatility and interconnection queue reforms create arbitrage opportunities for battery storage developers, concentrating venture deployment in the ERCOT footprint.
Market Restraints
- LP Commitment Concentration:Public pension systems in California and New York represent oversized fund-of-funds exposure, creating redemption cascade risk during public market drawdowns.
- Technical Validation Gaps:Fusion energy and direct air capture startups face decade-long commercialization horizons that exceed standard ten-year fund lifecycles, forcing GP-side letter renegotiations.
- Accredited Investor Thresholds:SEC income and net worth requirements exclude retail capital from qualified purchaser funds, capping downstream liquidity for secondary transactions.
Strategic Opportunities
- Defined Contribution Access:Pending Department of Labor guidance on private market allocations within 401(k) plans could unlock retail capital inflows into venture fund vehicles.
- Mexico Nearshoring:Manufacturing relocation from China to Monterrey and Tijuana creates demand for supply chain software and industrial automation startups serving cross-border production.
- AI-Drug Convergence:Generative chemistry platforms combined with CRISPR screening compress preclinical timelines, opening white space in rare disease therapeutics previously abandoned by large pharma.
Industry Challenges
- Technical Talent Scarcity:Deep learning researchers and battery electrochemists command compensation premiums that dilute founder equity stakes and accelerate cash burn.
- Carried Interest Taxation:Congressional proposals to reclassify carried interest as ordinary income threaten GP economics and fund formation incentives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Venture Capital Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $1,024.12 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed Stage, Early Stage, Growth Stage, Late Stage Fund Structure: Venture Funds, Corporate Funds, Angel Funds, Accelerator Funds Investment Type: Equity, Convertible Notes, Debt, Preferred Shares Industry Vertical: Technology, Healthcare, Fintech, Consumer Services |
| Companies Covered | Andreessen Horowitz, Sequoia Capital, Accel, General Catalyst, Khosla Ventures, Lightspeed Venture Partners, Greylock Partners, Tiger Global Management, Bain Capital Ventures, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Venture Capital Market Evolving Landscape
Software-defined infrastructure is displacing hardware-heavy deployment models across energy and life science verticals, enabling venture-backed startups to scale with asset-light balance sheets and recurring revenue profiles that attract institutional capital.
Generative AI is expanding into clinical trial design and regulatory submission preparation, compressing documentation timelines for biotechnology startups seeking FDA IND clearance. Mid-stage healthcare funds now mandate AI-native operations as a diligence threshold. This capability compression is collapsing the traditional three-year preclinical-to-clinic gap.
The SEC's proposed climate disclosure rules and the EU's CSRD are forcing portfolio companies to install carbon accounting infrastructure earlier in their lifecycle. Startups in the Series B phase now face investor mandates for Scope 3 data collection that previously applied only to public issuers. This regulatory pull-through is elevating demand for emissions measurement software.
Limited partners are consolidating commitments into concentrated flagship vehicles rather than spraying capital across accelerator and seed-stage programs. Canadian pension funds and US university endowments now prioritize direct board observation rights and side-letter governance provisions over diversified spray-and-pray exposure. This behavioral shift is starving micro-VCs and elevating concentration risk in mega-fund portfolios.
North America Venture Capital Market Segmentation
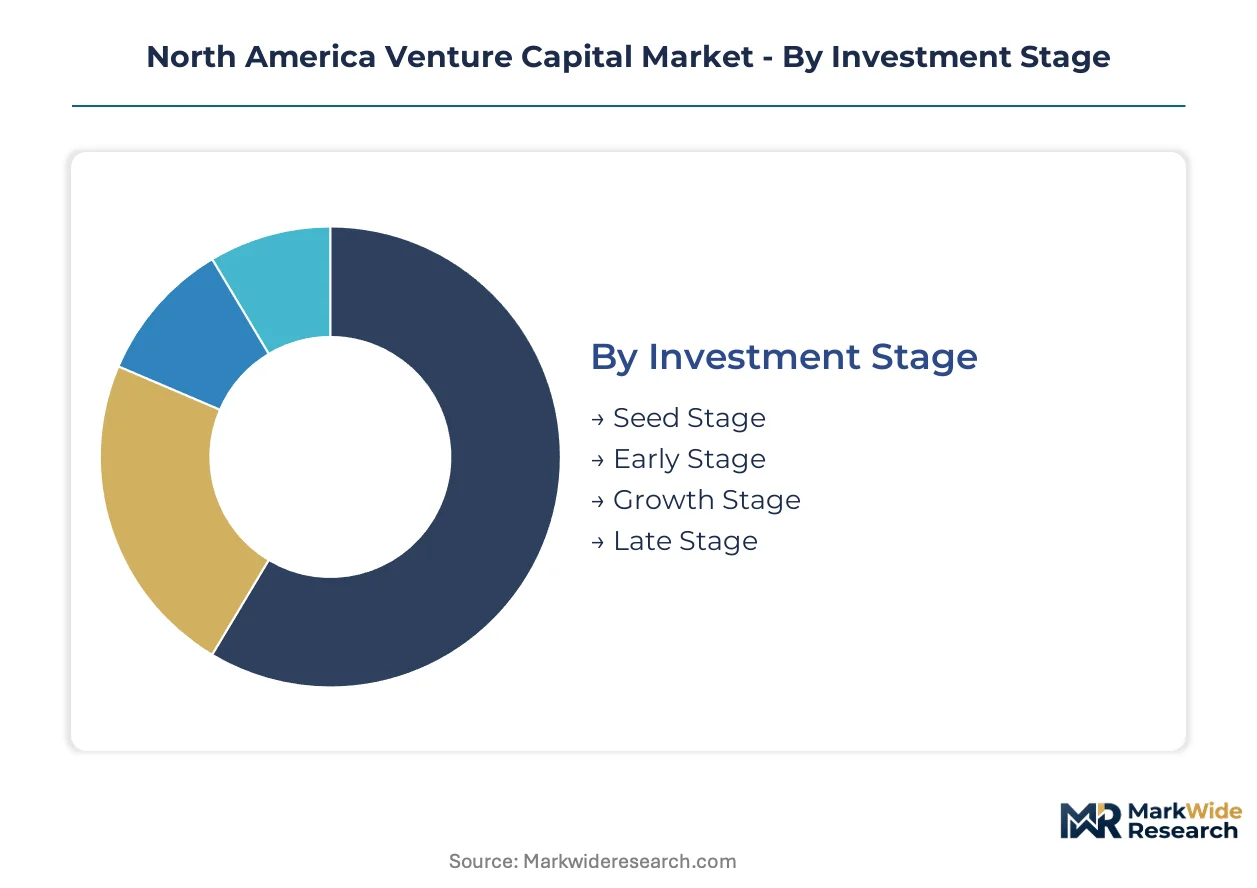
Venture capital deployment patterns diverge sharply across funding stages, vehicle structures, and sector exposures. Understanding these fault lines reveals where SEC accredited-investor thresholds, IRA tax credit eligibility, and FDA regulatory pathways concentrate capital formation.
Investment Stage:
SEC disclosure requirements and qualified purchaser thresholds vary dramatically by stage, with seed rounds facing minimal filing burdens while late-stage rounds trigger Hart-Scott-Rodino antitrust reviews.
- Seed Stage:First institutional capital deployed at pre-revenue or minimal revenue milestones. Angel syndicates and micro-VCs dominate California and New York formations, though technical talent scarcity in battery electrochemistry and deep learning compresses founder equity to sub-15% stakes by Series A.
- Early Stage:Post-product-market-fit financing where FDA breakthrough device designation or IRA Section 48C qualification becomes a diligence threshold. Andreessen Horowitz and Sequoia Capital concentrate here for climate-tech and healthcare AI infrastructure.
- Growth Stage:Expansion capital for proven unit economics.
- Late Stage:Pre-IPO financing where public crossover investors enter.
Leading the category by volume: Growth Stage. Expanding most quickly: Early Stage.
Fund Structure:
Vehicle governance and fee structures segment LP commitment preferences, with concentrated flagship funds capturing endowment and pension allocations while accelerator vehicles face starvation.
- Venture Funds:Traditional ten-to-fifteen-year limited partnerships with 2% management fees and 20% carried interest. Canadian pension funds and US university endowments now mandate direct board observation rights through side letters.
- Corporate Funds:Balance-sheet deployment by strategic parents seeking technology optionality.
- Angel Funds:High-net-worth individual syndicates operating below SEC registration thresholds.
- Accelerator Funds:Cohort-based programming with standardized terms.
Dominant by committed capital: Venture Funds. Steepest decline trajectory: Accelerator Funds.
Investment Type:
Security selection determines liquidation preference stacks and tax treatment under IRS qualified small business stock exemptions.
- Equity:Common or preferred stock with voting rights.
- Convertible Notes:Debt instruments converting at qualified financing rounds.
- Debt:Venture lending with warrants.
- Preferred Shares:Senior liquidation preference with anti-dilution protection.
Most frequent in seed rounds: Convertible Notes. Dominant in growth rounds: Preferred Shares.
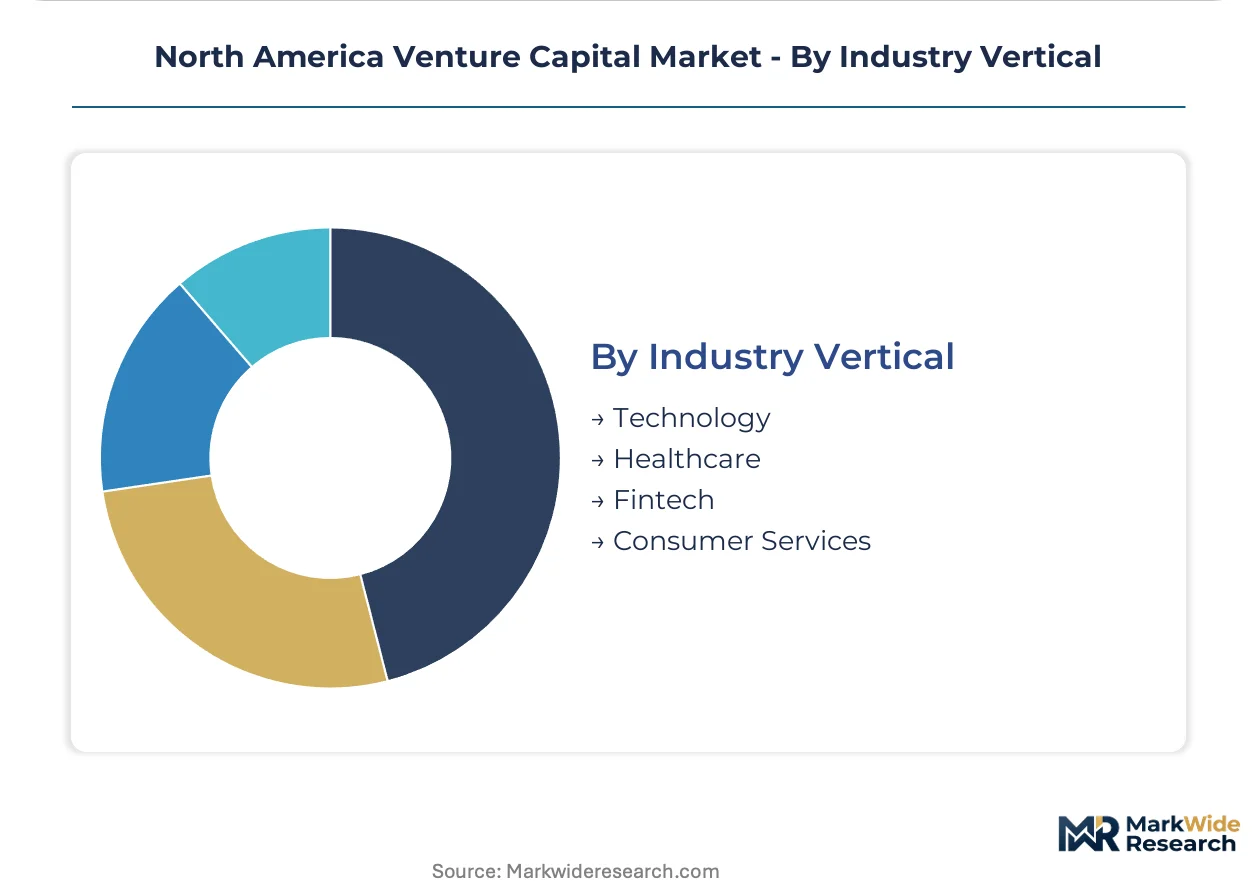
Industry Vertical:
Sector concentration reflects regulatory tailwinds from IRA production tax credits and FDA accelerated approval pathways.
- Technology:Software-defined infrastructure and generative AI platforms.
- Healthcare:Biotechnology and diagnostic algorithms leveraging FDA breakthrough device pathways.
- Fintech:Regulatory clarity in payments and lending attracts institutional LPs.
- Consumer Services:Subscription and marketplace models.
Largest allocation share: Technology. Gaining share fastest: Healthcare.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
San Francisco anchors venture deployment concentration across North America, with the Bay Area metropolitan corridor commanding disproportionate capital formation relative to population. The region's startup density creates network effects that compound founder talent pools and institutional limited partner access. Three sovereign jurisdictions shape regulatory frameworks governing fund formation and capital deployment across the continent.
United States
Institutional limited partners concentrate commitments in California and New York fund formations, driven by pension system scale and endowment density. The SEC governs accredited-investor thresholds and disclosure requirements for fund solicitation under Regulation D. Texas emerges as a secondary hub, with Austin and Dallas-Fort Worth capturing migration of Bay Area technical talent and energy-tech venture formation.
Canada
Ontario and Quebec pension systems anchor sovereign wealth allocations to venture vehicles, with Toronto's financial district housing domestic fund management infrastructure. Provincial securities commissions coordinate harmonization of offering memorandum standards under National Instrument 45-106. Vancouver's technology corridor specializes in cleantech and quantum computing startups leveraging federal SR&ED tax incentives.
Mexico
Monterrey and Mexico City metropolitan areas attract cross-border venture attention as manufacturing relocation accelerates from Asia. The Comisión Nacional Bancaria y de Valores governs foreign fund registration and investor eligibility for private capital vehicles. Tijuana's industrial corridor creates demand for supply chain software startups serving US-Mexico-Canada Agreement trade flows.
North America Venture Capital Market Competitive Landscape
Premium-margin players sit above commodity-margin players across fund vintage performance and carried-interest realization timelines. The North American venture capital structure concentrates among established multi-billion-dollar flagship vehicles with decade-plus track records, while micro-VCs and accelerator programs face commitment starvation from institutional limited partners. Three archetypes dominate: multi-stage generalists with sector-agnostic deployment, thesis-driven specialists concentrating in climate or healthcare verticals, and crossover vehicles bridging private and public market exposure. Dominant competitive moves include side-letter governance renegotiation for board observation rights and concentrated flagship fund formation over diversified seed-stage spraying.
Within the multi-stage generalist tier, Andreessen Horowitz and Sequoia Capital occupy positions exemplifying scale-driven platform strategies with dedicated vertical funds. Khosla Ventures represents the hard-tech specialist archetype, anchoring concentrated bets in fusion and advanced materials that exceed standard fund lifecycles. These three entities collectively illustrate how regulatory tailwinds from the Inflation Reduction Act and FDA breakthrough pathways reshape competitive positioning across the sector.
| Leading Market Players |
|---|
| Andreessen Horowitz |
| Sequoia Capital |
| Accel |
| General Catalyst |
| Khosla Ventures |
| Lightspeed Venture Partners |
| Greylock Partners |
| Tiger Global Management |
| Bain Capital Ventures |
| Others |
Value Network & Pricing Analysis
Institutional limited partners in California and New York pension systems anchor fee negotiations through concentrated flagship commitments, driving venture funds toward carried-interest structures that align GP economics with decade-long liquidity horizons rather than transactional pricing models.
Pricing Analysis
Value-based pricing anchored to fund IRR thresholds and DPI realization timelines dominates LP-GP negotiations, with management fees compressing toward 1.5% for established managers while emerging funds absorb 2.5% to cover operational overhead. Price differentiation rests on track record vintage performance and side-letter governance provisions rather than sector specialization alone. Pricing pressure intensifies as Canadian pension funds and university endowments consolidate commitments into fewer relationships, squeezing micro-VCs and accelerator vehicles. Seed-stage vehicles face acute price sensitivity from LPs prioritizing direct board observation rights over diversified exposure.
Supply Chain Analysis
Direct-to-institutional-LP channels handle sovereign wealth and pension fund allocations, bypassing fund-of-funds intermediaries that previously aggregated retail-scale capital. Geographic supply concentration centers on the United States for fund formation and Delaware domiciliation, with Canada anchoring provincial pension system deployment and Mexico emerging for nearshoring-linked venture exposure. Raw material dependencies include technical talent pipelines from Stanford and MIT, LP commitment flows from CalPERS and Ontario Teachers', and regulatory clarity from SEC no-action letters. Single-source vulnerability concentrates in Bay Area founder density, where electrochemist and deep learning researcher scarcity inflames compensation premiums. Distribution runs through concentrated flagship vehicles with side-letter governance rather than diversified seed-stage spraying.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Venture capital deployment is becoming a vertical-integration race, with general partners pursuing downstream control through direct board observation rights and side-letter provisions that bypass traditional fund-of-funds intermediaries.
For Market Incumbents: Cement fund-raising dominance by locking multi-year LP commitments through governance renegotiation before regulatory shifts on accredited-investor thresholds reshape retail access. Anchor flagship vehicles in climate-tech and healthcare AI verticals where IRA tax credits and FDA breakthrough pathways extend fund lifecycles. Defend against emerging crossover vehicles by concentrating technical talent recruitment in battery electrochemistry and generative chemistry platforms.
For New Entrants and Emerging Players: Digital-channel LP engagement through transparent portfolio data dashboards offers a route to bypass incumbent relationship moats. Target Texas energy-tech formations and Mexico nearshoring software as the most penetrable white spaces, where ERCOT market volatility and USMCA trade flows create founder demand unmet by Bay Area incumbents. Pursue sector-specific micro-VC structures in industrial automation and supply chain software rather than competing for diluted AI infrastructure allocations.
For Investors and Strategic Acquirers: The window for entry favors hard-tech specialists with decade-long commercialization horizons that exceed standard fund lifecycles. Prioritize acquisition targets in carbon removal and grid storage where IRA Section 45Q and 48C subsidies compress capital formation timelines. Watch for Department of Labor guidance on defined contribution plan access as the inflection signal for retail capital inflows.
| Strategic Initiative | Industry Significance |
|---|---|
| Side-Letter Governance Renegotiation | Direct board observation rights from CalPERS and Ontario Teachers' reshape LP-GP power dynamics. |
| Climate-Tech Vertical Fund Formation | IRA Section 45Q tax credits pull pension allocations into carbon removal and clean hydrogen portfolios. |
| Healthcare AI Infrastructure Concentration | FDA breakthrough device pathways shorten time-to-revenue for diagnostic algorithm platforms. |
| Texas Energy-Tech Geographic Expansion | ERCOT market volatility and interconnection queue reforms create battery storage arbitrage opportunities. |
| Mexico Nearshoring Supply Chain Software | USMCA trade flows and Monterrey manufacturing relocation generate cross-border automation demand. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, with primary interviews conducted across fund general partners, institutional limited partner allocation heads, securities commission staff, and venture-backed startup CFOs. SEC Form ADV disclosures, Canadian National Instrument 45-106 filings, and Mexican CNBV registration databases supplied fund formation and capital flow metrics. Bottom-up triangulation across disclosed fund sizes and top-down validation through pension system annual reports reconciled deployment estimates.
Data-stream reconciliation across seed, early, growth, and late-stage deployment volumes generated consistent progression patterns across the projection horizon. Segmentation modeling incorporated investment stage, fund structure, investment type, and industry vertical dimensions alongside geographic regulatory cluster differentiation. CAGRs derived from vintage-year cash flow modeling and DPI realization curve analysis, with IRA tax credit eligibility and FDA regulatory pathway timelines serving as scenario inputs.
The model holds under sustained institutional LP commitment concentration and stable accredited-investor thresholds; deviation in SEC retail access rulemaking or congressional carried-interest reclassification would shift fund formation incentives. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
Venture Capital Investment Market
Venture Capital
Micro Venture Capital VC Funds Market
Venture Capital
Business Incubator Market
Venture Capital
Asia Pacific Venture Capital Market
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
Crowdfunding Market
Venture Capital
Micro VC Funds Market
Venture Capital
Impact Investing Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
Europe Venture Capital Market
Venture Capital
US Venture Capital Investment Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
United States Venture Capital Market
Venture Capital
Angel Funds Market