
 Fintech Credit Management Blockchain Market | 2026-2036
Fintech Credit Management Blockchain Market Size, Share, and Industry Trends Forecast 2026-2036
Fintech Credit Management Blockchain Market Insights
Platform licensing revenue is reconfiguring margin pools away from traditional loan servicing fees toward blockchain-native credit infrastructure. Figure Technologies leverages decentralized identity verification to anchor its position in home equity credit markets. Nexo competes through yield-bearing collateralized products that sustain user retention across volatile cycles. Digital Asset Holdings controls enterprise-grade smart contract templates that dominate institutional trade finance workflows.
Fintech credit management blockchain denotes distributed ledger systems engineered to automate credit origination, collateral tracking, and default recovery through immutable transaction records and programmable settlement logic. These networks typically operate on permissioned architectures with sub-second finality thresholds, serving commercial lenders seeking to reduce reconciliation overhead and counterparty exposure. Public blockchain deployment models currently occupy the fastest-expanding segment as interoperability protocols mature, though private blockchain implementations retain margin concentration among regulated neobanks requiring audit trails. Credit scoring solutions lead the solution offering category, while peer-to-peer lending applications exhibit the steepest adoption curve among non-bank originators.
The SEC enforces custody and disclosure standards for blockchain-based lending products, while the EU's MiCA framework mandates reserve transparency for tokenized credit instruments. Singapore's Monetary Authority coordinates sandbox exemptions that shape product development timelines for regional fintech credit platforms. Stakeholders must monitor how jurisdictional divergence in stablecoin collateral rules affects cross-border loan origination architecture.
Market Dynamics
Permissioned blockchain architectures with sub-second finality are displacing legacy credit infrastructure as commercial lenders prioritize reconciliation automation and counterparty exposure reduction. This structural migration concentrates margin pools around protocol-native licensing revenue rather than traditional loan servicing fees.
Growth Catalysts
- EU MiCA Reserve Transparency Mandates:Tokenized credit instruments face mandatory disclosure requirements that accelerate institutional platform adoption across European lending markets.
- Decentralized Identity Verification:Home equity originators deploy cryptographic credentialing to compress verification cycles and reduce fraud exposure in collateralized lending workflows.
- Singapore's Regulatory Sandbox:The Monetary Authority coordinates exemption frameworks that compress product development timelines for regional credit protocol developers.
Market Restraints
- Interoperability Protocol Immaturity:Cross-chain settlement standards remain underdeveloped, fragmenting liquidity pools and complicating collateral tracking across distributed networks.
- Jurisdictional Stablecoin Divergence:Collateral reserve rules vary sharply between the SEC custody framework and Singapore's payment token guidelines, forcing redundant compliance architecture.
- Oracle Reliability Constraints:Off-chain data feeds for credit scoring algorithms exhibit latency and manipulation vulnerabilities that limit automated liquidation confidence.
Strategic Opportunities
- Trade Finance Smart Contract Templates:Institutional workflows for commodity-backed lending remain underpenetrated by programmable settlement logic, creating whitespace for enterprise-grade protocol deployment.
- Yield-Bearing Collateralized Products:User retention mechanics that sustain engagement across volatile cycles represent an emerging product category distinct from traditional fixed-income structures.
- Cross-Border Loan Origination Architecture:Regulatory arbitrage between MiCA disclosure standards and SEC custody rules creates structural openings for multi-jurisdictional credit protocols.
Industry Challenges
- Smart Contract Audit Talent Scarcity:Formal verification expertise for financial-grade distributed applications commands premium compensation and extends security review timelines.
- Legacy Core Banking Integration:Mainframe credit systems require expensive middleware development to interface with blockchain-native origination platforms without disrupting operational continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fintech Credit Management Blockchain Market |
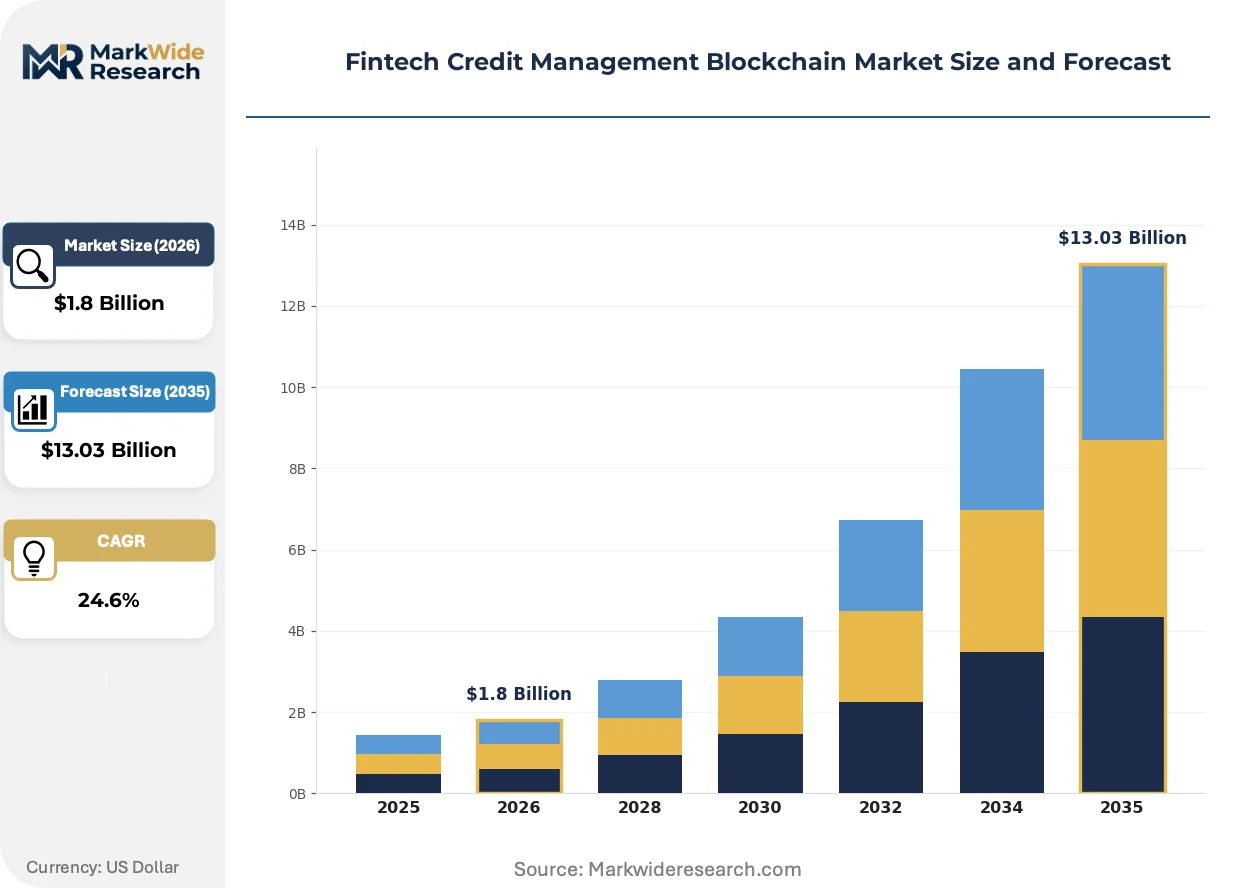
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Offering: Credit Scoring, Fraud Detection, Risk Assessment, Loan Origination, Payment Verification Deployment Model: Public Blockchain, Private Blockchain, Consortium Blockchain, Hybrid Blockchain Application: Micro Lending, Peer-to-Peer Lending, Invoice Financing, Trade Finance, Digital Wallets End User: Neobanks, Credit Unions, Microfinance Institutions, Payment Facilitators |
| Companies Covered | Figure Technologies, BlockFi, Nexo, tZERO, Circle Internet Financial, Coinbase, Digital Asset Holdings, AlphaPoint Corporation, Unchained Capital, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fintech Credit Management Blockchain Market Trends and Innovations
Programmable settlement logic is compressing traditional credit infrastructure as lenders automate collateral tracking and default recovery through immutable transaction records. This transformation accelerates most visibly where regulatory clarity permits institutional experimentation.
Zero-knowledge proof circuits are digitizing credit scoring workflows by enabling privacy-preserving verification of borrower credentials without exposing underlying data. Commercial banks in Southeast Asia pilot these architectures to reduce default exposure while maintaining regulatory audit trails. The technology is digitizing compliance documentation that previously required manual reconciliation across correspondent banking relationships.
Singapore's Monetary Authority coordinates sandbox exemptions that shape product development timelines for regional fintech credit platforms. These frameworks compress go-to-market cycles for experimental collateral structures while maintaining prudential oversight. Neobanks with regulatory clarity advantages capture disproportionate flow from traditional lenders awaiting jurisdictional precedent.
Institutional procurement of credit infrastructure is fragmenting as chief technology officers evaluate blockchain-native alternatives against incremental legacy upgrades. Large commercial lenders in Singapore and the EU pilot parallel systems rather than committing to full migration, extending sales cycles for platform vendors. This behavior concentrates near-term revenue in professional services and integration consulting rather than pure software licensing.
Fintech Credit Management Blockchain Market Segmentation
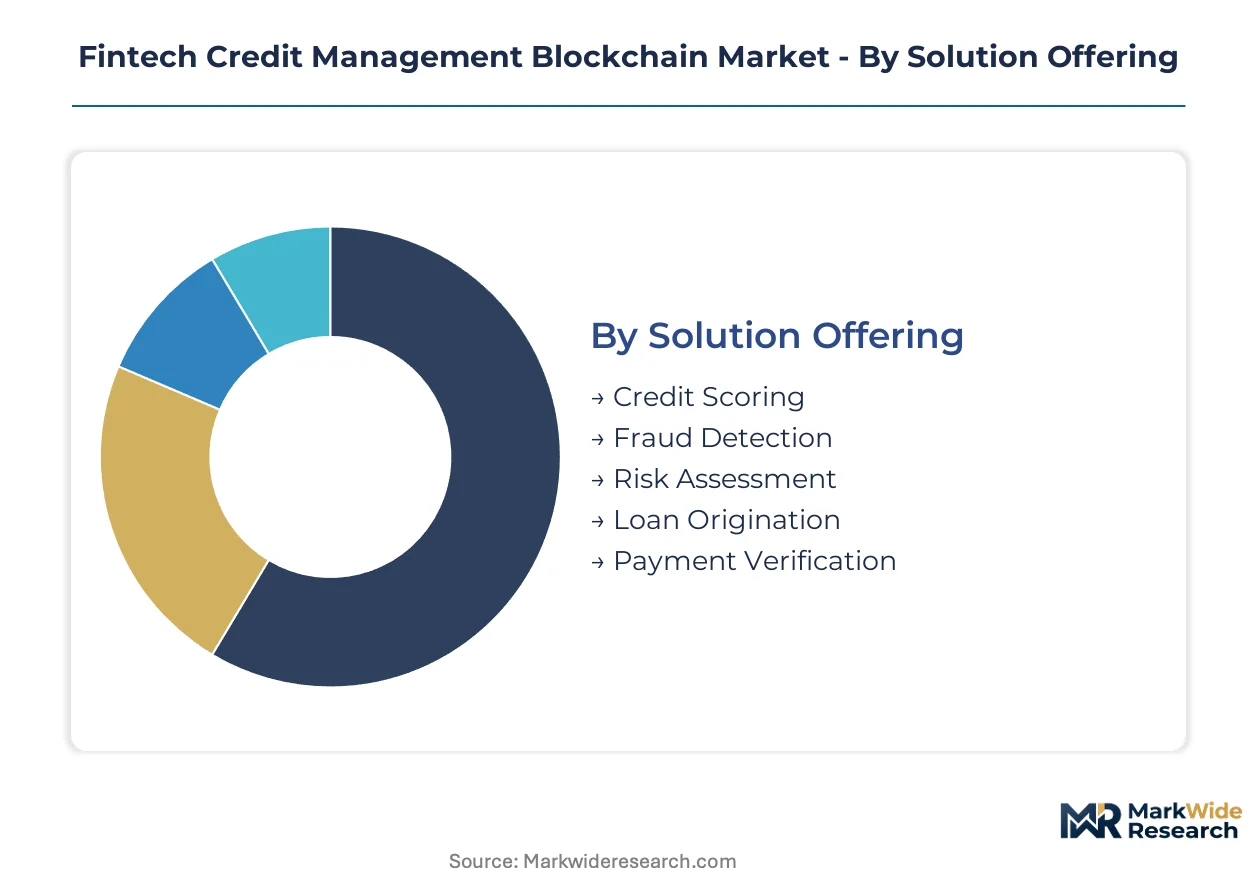
Segmentation reveals how blockchain credit infrastructure fragments across technical architectures, use cases, and institutional buyer profiles. Understanding these divisions exposes where margin pools concentrate and which deployment patterns accelerate adoption cycles.
Solution Offering:
After-sales service intensity varies sharply across solution types, with credit scoring platforms demanding continuous algorithm recalibration while payment verification modules require less intensive ongoing support.
- Credit Scoring:Distributed ledger systems aggregate immutable transaction histories and alternative data streams to generate borrower risk profiles without centralized credit bureau dependency. Demand concentrates among neobanks in Singapore seeking to undercut traditional bureau costs while maintaining regulatory audit trails. Momentum accelerates where zero-knowledge proof circuits enable privacy-preserving verification.
- Fraud Detection:Smart contract logic automates pattern recognition across cross-border payment flows, flagging anomalous collateral movements in real time. Southeast Asian commercial banks deploy these systems to reduce reconciliation overhead in correspondent banking relationships. The segment attracts procurement investment where regulatory sandboxes permit experimental data sharing protocols.
- Risk Assessment:Programmable evaluation frameworks automate collateral valuation and counterparty exposure calculation.
- Loan Origination:End-to-end digitization of credit workflows from application to disbursement through immutable documentation trails.
- Payment Verification:Settlement finality confirmation through distributed consensus mechanisms rather than correspondent bank confirmation.
Credit Scoring holds the largest share; momentum sits with Fraud Detection.
Deployment Model:
Cost tier segmentation separates enterprise-grade private implementations from lower-infrastructure public alternatives, with hybrid architectures occupying the middle ground on both capital expenditure and operational complexity.
- Private Blockchain:Permissioned architectures with sub-second finality thresholds serve regulated neobanks requiring granular audit trail control and configurable validator sets. EU institutions prioritize these deployments to satisfy MiCA reserve transparency mandates without exposing proprietary borrower data. Procurement concentrates where chief technology officers prioritize operational continuity over interoperability.
- Public Blockchain:Open validator networks reduce infrastructure capital requirements for microfinance institutions and peer-to-peer originators lacking dedicated IT departments. Singapore's fintech corridor attracts developers building on public layers due to sandbox exemptions that compress compliance timelines. The model climbs fastest where interoperability protocols mature sufficiently to bridge liquidity fragmentation.
- Consortium Blockchain:Multi-party governance structures distribute infrastructure costs across competing lenders within single jurisdictions.
- Hybrid Blockchain:Sensitive operations execute on private layers while settlement and collateral tokenization leverage public chain finality.
Private Blockchain dominates institutional procurement; Public Blockchain gains share fastest as interoperability standards harden.
Application:
Volume concentration patterns distinguish high-frequency, low-ticket micro lending from capital-intensive trade finance workflows with extended settlement horizons and complex collateral documentation requirements.
- Trade Finance:Programmable settlement logic automates commodity-backed lending workflows through smart contract templates that trigger disbursement upon verified shipping documentation. Institutional procurement from Singapore and EU commodity traders drives adoption where legacy letter-of-credit systems create reconciliation bottlenecks. The application exhibits steepest expansion trajectory among enterprise-grade protocol vendors.
- Peer-to-Peer Lending:Disintermediated credit matching protocols connect retail lenders directly with borrowers through algorithmic risk pricing and automated collateral liquidation. Demand clusters in jurisdictions with permissive regulatory sandboxes that reduce licensing friction for non-bank originators. User retention mechanics concentrate development investment around yield-bearing product structures.
- Micro Lending:Small-ticket, short-duration credit for underbanked populations through mobile-first blockchain interfaces.
- Invoice Financing:Accounts receivable tokenization and secondary market trading for working capital acceleration.
- Digital Wallets:Integrated credit access within payment infrastructure through embedded lending protocols.
Trade Finance commands premium pricing; Peer-to-Peer Lending expands most quickly among non-bank originators.
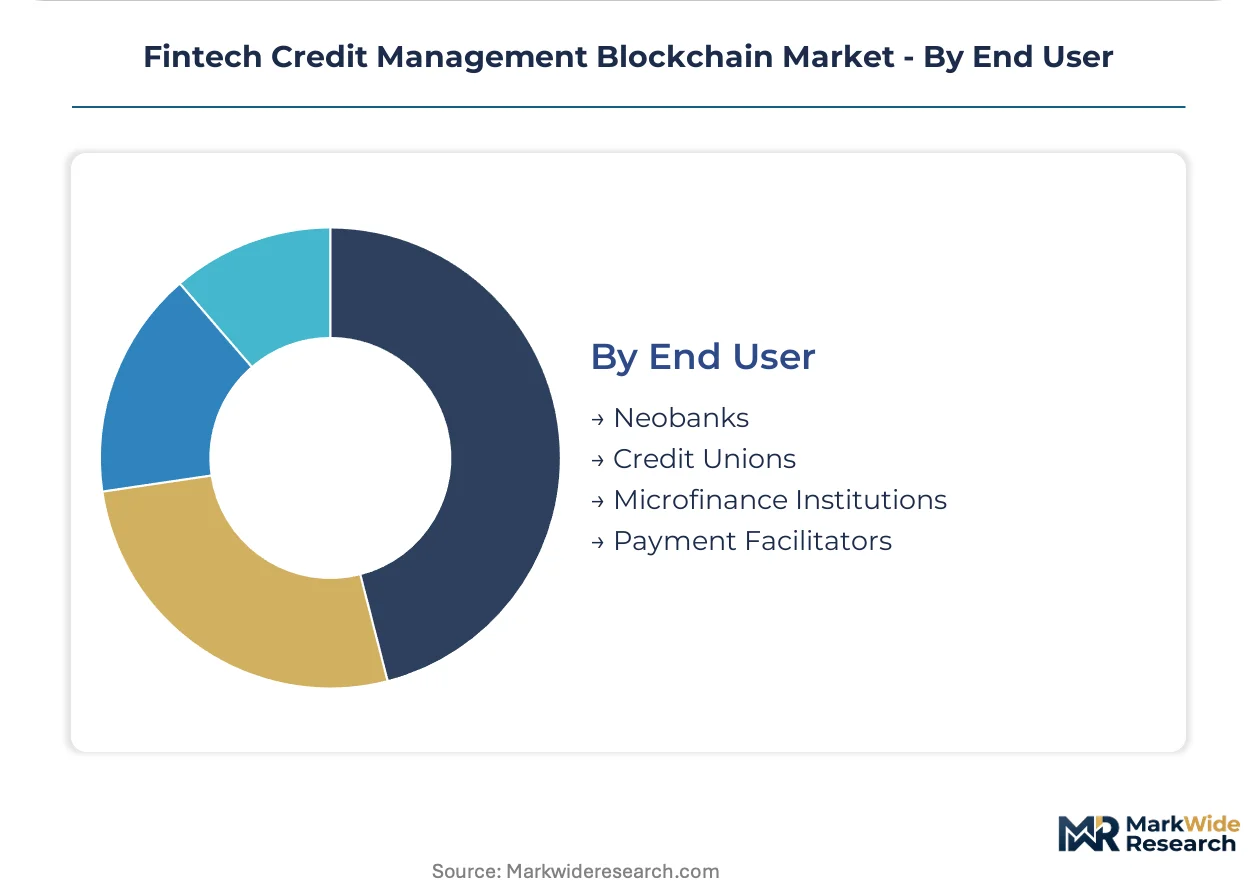
End User:
Customer type segmentation separates digitally native challengers from legacy institutions with mainframe dependency, determining sales cycle length and integration consulting intensity.
- Neobanks:Cloud-native institutions procure blockchain-native credit infrastructure without legacy core banking migration burden, compressing implementation timelines relative to incumbent competitors. Singapore's regulatory clarity attracts disproportionate platform development targeting this segment. Procurement prioritizes yield-bearing collateralized products that differentiate deposit offerings.
- Credit Unions:Member-owned institutions leverage blockchain credit scoring to reduce bureau dependency and redirect fee savings toward member dividends. Pilot programs concentrate in jurisdictions with permissive sandbox frameworks that limit regulatory uncertainty. The segment exhibits conservative procurement patterns favoring proven private blockchain implementations.
- Microfinance Institutions:Mission-driven lenders deploy low-infrastructure public blockchain solutions to reach underbanked populations.
- Payment Facilitators:Transaction processors embed credit origination within merchant settlement workflows.
Neobanks drive near-term revenue concentration; Microfinance Institutions represent the longest adoption runway.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between jurisdictions with regulatory clarity and those navigating fragmented compliance frameworks. Singapore deploys blockchain credit infrastructure for trade finance automation, while the United States emphasizes custody compliance for institutional lending products. The European Union concentrates investment around MiCA-mandated reserve transparency for tokenized instruments.
Singapore
The Monetary Authority's sandbox exemptions compress development timelines for credit protocol developers targeting home equity and trade finance workflows. Neobanks and commodity traders cluster in the fintech corridor, leveraging sub-second finality permissioned networks to automate collateral tracking. The regulatory framework attracts disproportionate platform investment from regional originators seeking jurisdictional clarity.
United States
SEC custody and disclosure standards shape procurement decisions for blockchain-based lending products, concentrating institutional adoption among compliance-heavy architectures. Commercial banks pilot parallel systems against legacy infrastructure, extending sales cycles for platform vendors. Figure Technologies and Unchained Capital occupy positions in home equity credit markets through decentralized identity verification.
Germany
The EU's MiCA framework mandates reserve transparency for tokenized credit instruments, accelerating institutional platform adoption across European lending markets. Frankfurt-based financial institutions prioritize private blockchain implementations to satisfy audit trail requirements without exposing proprietary borrower data. The regulatory clarity drives procurement concentration among regulated neobanks.
United Kingdom
Post-Brexit regulatory divergence creates structural openings for credit protocols navigating between MiCA disclosure standards and domestic custody rules. London's financial services cluster experiments with hybrid blockchain architectures for cross-border loan origination. Fintech credit platforms target yield-bearing collateralized products to differentiate deposit offerings.
Japan
METI coordination of financial technology standards shapes enterprise blockchain procurement for institutional lenders. Tokyo-based banks evaluate consortium architectures to distribute infrastructure costs across competing institutions while maintaining operational continuity with legacy core systems. The regulatory environment favors conservative private blockchain implementations over public network experimentation.
Fintech Credit Management Blockchain Market Competitive Landscape
Capability concentration sits with protocol-native infrastructure specialists; scale advantage sits with established fintech platforms with existing user bases. The vendor base organizes around three strategic archetypes: decentralized identity verification specialists, yield-bearing collateralized product providers, and enterprise-grade smart contract template vendors. Competitive moves concentrate in strategic partnerships with regulated neobanks and technology licensing agreements for legacy core banking integration.
Within the enterprise infrastructure tier, Digital Asset Holdings exemplifies the smart contract template archetype dominating institutional trade finance workflows. Figure Technologies and Nexo occupy positions at the intersection of decentralized identity and yield-bearing product structures. Nexo represents the retention-focused model sustaining user engagement across volatile market cycles. These three anchors illustrate how competitive positioning fragments across technical specialization rather than consolidating around full-stack dominance.
| Leading Market Players |
|---|
| Figure Technologies |
| BlockFi |
| Nexo |
| tZERO |
| Circle Internet Financial |
| Coinbase |
| Digital Asset Holdings |
| AlphaPoint Corporation |
| Unchained Capital |
| Others |
Pricing and Supply Chain Analysis
Regulatory chokepoint exposure around MiCA reserve transparency mandates and SEC custody divergence determines both pricing tier spreads and supply chain shape across fintech credit management blockchain infrastructure. Vendors absorbing multi-jurisdictional compliance costs command premium positioning, while those anchored to single-regime architectures face margin compression from redundant audit architecture.
Pricing Analysis
Long-term licensing contracts with annual renegotiation clauses dominate enterprise procurement, though project-based implementation fees capture upfront integration complexity. Three-tier pricing structure across premium, standard, and economy levels separates protocol-native infrastructure from middleware-dependent and open-source alternatives. Price differentiation rests on formal verification certification depth and after-sales algorithm recalibration intensity. Cost compression in the standard tier is intensifying because neobanks consolidate vendor panels around proven sandbox graduates. Microfinance institutions exhibit highest price sensitivity due to capital constraints, while commodity traders in Singapore show lowest sensitivity given trade finance automation savings.
Supply Chain Analysis
Contract manufacturing concentration for specialized hardware security modules sits with Thales, Gemalto, and Utimaco facilities across Germany, France, and the Netherlands. Smart contract audit talent draws from Estonia, Switzerland, and Singapore where cryptographic research clusters feed protocol development. Supply chain risk centers on single-source vulnerability for zero-knowledge proof circuit verification expertise, where fewer than twelve qualified firms globally handle financial-grade implementations. Distribution runs through direct enterprise sales teams for institutional deployments and API marketplace integrations for developer-centric protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward neobanks and commodity traders with regulatory clarity advantages, fragmenting procurement panels as legacy lenders delay commitment pending jurisdictional precedent.
For Market Incumbents: Insulate core revenue streams by deepening formal verification partnerships with sandbox-authorized audit firms before talent scarcity intensifies. Acquire middleware specialists capable of legacy core banking integration to extend platform stickiness against challenger protocols. The threat of yield-bearing collateralized products from retention-focused competitors demands defensive certification investment in MiCA-aligned reserve transparency architecture. For New Entrants and Emerging Players: Build out white-space positions in trade finance smart contract templates for commodity-backed lending workflows, where institutional penetration remains underdeveloped. Target microfinance institutions in Southeast Asia with low-infrastructure public blockchain solutions, leveraging Singapore's sandbox exemptions as jurisdictional credibility anchor. A developer-centric go-to-market angle through API-first documentation and sandbox pre-certification compresses sales cycles relative to enterprise direct approaches. For Investors and Strategic Acquirers: The market sits at a protocol standardization phase that favors enterprise-grade smart contract template vendors with institutional workflow integration depth. Long-term viability across a five-to-ten year window rests on regulatory arbitrage capabilities between MiCA disclosure standards and SEC custody frameworks. Acquisition priority sits with firms holding formal verification expertise and existing Monetary Authority sandbox authorizations. The signal to watch is cross-chain interoperability protocol maturation, which would accelerate public blockchain share expansion and compress private implementation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Authorization | Monetary Authority exemptions compress compliance timelines for protocol developers targeting Singapore's fintech corridor. |
| Formal Verification Partnership | Smart contract audit scarcity commands premium positioning among financial-grade distributed application vendors. |
| Legacy Core Banking Integration | Middleware development capabilities extend platform stickiness with commercial lenders piloting parallel systems. |
| Zero-Knowledge Proof Circuit Deployment | Privacy-preserving verification architectures differentiate credit scoring offerings for Southeast Asian neobanks. |
| Yield-Bearing Product Structure Launch | User retention mechanics sustain engagement across volatile cycles distinct from fixed-income alternatives. |
Research Methodology
The analysis maps credit scoring platforms, fraud detection systems, loan origination protocols, and trade finance smart contract templates, each validated through protocol developers, neobank CTOs, commodity trader treasury heads, and regulatory sandbox administrators. Primary interviews with these stakeholders combined with secondary validation from SEC disclosure filings, Monetary Authority sandbox authorization records, EU MiCA regulatory texts, and enterprise blockchain procurement databases. Bottom-up deployment counts and top-down infrastructure spending estimates were triangulated to anchor market sizing.
Assumptions around regulatory clarity timelines, interoperability protocol maturation curves, and stablecoin collateral reserve convergence were held fixed across baseline scenarios while stress-tested for divergence. Segmentation dimensions modeled include solution offering type, deployment model architecture, application workflow, and end-user institutional profile. CAGRs were derived from regression analysis against historical fintech infrastructure adoption patterns, incorporating smart contract audit capacity constraints and sandbox authorization throughput as industry-specific inputs.
Stress conditions across MiCA implementation timelines, SEC enforcement intensity, and cross-chain settlement standardization were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect these assumptions and could revise materially if jurisdictional divergence in stablecoin rules widens or oracle reliability constraints trigger automated liquidation failures. Quarterly review of sandbox authorization volumes, formal verification talent compensation trends, and interoperability protocol testnet activity is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
North America AI in Fintech Market
FinTech
Fintech-As-A-Service Market
FinTech
Advanced Authentication in Financial Services Market
FinTech
Latin America Fintech Market
FinTech
Asia-Pacific Financial Analytics Market
FinTech
Smart Finance Connectivity Market
FinTech
Global Fintech Market
FinTech
Vietnam Fintech Market
FinTech
North America Fintech Market
FinTech
Europe AI in Fintech Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
Robo-Advisory Services Market
FinTech
Saudi Arabia Fintech Market
FinTech
Autonomous Finance Market
FinTech
Financial App Market
FinTech
Business Analytics in Fintech Market