
 Micro VC Funds Market | 2026-2036
Micro VC Funds Market Size, Share, and Industry Trends Forecast 2026-2036
Micro VC Funds Market Analysis
Technical founder talent is rotating toward sector-specific micro VC vehicles, tightening the supply of generalist operators who can evaluate deep-tech opportunities. SV Angel leverages its Y Combinator proximity to sustain deal-flow dominance in Bay Area seed rounds. Quiet Capital anchors Pacific Northwest coverage with a thesis-driven approach to enterprise software. Ulu Ventures competes through data science integration into early-stage selection, differentiating its portfolio construction from intuition-driven peers.
Micro VC funds are investment vehicles deploying capital pools under one hundred million dollars into pre-seed through Series A companies, typically taking minority equity stakes with board observation rights rather than control positions. These funds concentrate portfolio construction around concentrated ownership thresholds and active founder coaching, serving as the primary institutional capital layer between angel syndicates and growth-stage venture. Seed Stage deployment commands the dominant volume share across Investment Stage categories, while Pre-Series A vehicles capture widening spreads as valuation compression extends diligence timelines. Closed-End Funds retain structural primacy in Fund Structure segmentation due to LP preference for fixed-term liquidity, though Co-Investment Funds are gaining traction as limited partners seek direct exposure alongside established managers.
The SEC's accredited investor definitions and Investment Advisers Act exemptions frame fund-raising eligibility and reporting burdens for US-domiciled managers, while the EU's AIFMD and national regulator frameworks govern European fund marketing and passport rights. These regulatory architectures shape fund size ceilings, investor solicitation channels, and cross-border capital mobility. Stakeholders must monitor evolving LP due diligence standards around ESG integration and succession planning as fund vintage density intensifies competition for institutional commitments.
Market Dynamics
LP capital is concentrating into sub-$100 million vehicles as institutional investors seek specialized exposure to pre-seed technology formation, compressing fundraising timelines for generalist seed managers and elevating governance standards across fund formation.
Growth Catalysts
- Accredited Investor Expansion:The SEC's amended accredited investor definitions under the Investment Advisers Act broaden eligible LP pools, enabling managers to solicit capital from sophisticated non-institutional investors previously excluded from private fund access.
- Enterprise Software Demand:Vertical SaaS penetration across healthcare, logistics, and financial services creates addressable company formation at seed stage, with technical founders requiring structured capital beyond angel syndicates.
- Bay Area Cluster Density:San Francisco's concentrated founder talent and exit liquidity sustain deal-flow velocity for locally anchored micro VC vehicles, reinforcing geographic specialization in portfolio construction.
Market Restraints
- Management Fee Compression:The standard 2% management fee structure faces downward pressure as LPs negotiate reduced economics for sub-scale fund sizes, squeezing operating budgets for lean partnership teams.
- Valuation Stagnation:Extended holding periods for seed-stage equity compress IRR calculations, particularly for 2019-2021 vintage funds marked at elevated entry multiples now facing markdown pressure.
- Regulatory Solicitation Friction:The SEC's private fund adviser rules impose quarterly reporting and audit requirements that disproportionately burden sub-$50 million managers lacking compliance infrastructure.
Strategic Opportunities
- Climate Technology Formation:The Inflation Reduction Act's production tax credits and loan guarantee programs catalyze hardware and software startup formation in clean energy, carbon accounting, and industrial decarbonization.
- Co-Investment Vehicle Structures:Sidecar arrangements enabling direct LP participation in specific portfolio companies attract family office capital seeking fee-efficient exposure alongside established manager judgment.
- Data Science Integration:Quantitative sourcing platforms and automated diligence workflows reduce partner time per investment decision, allowing smaller teams to evaluate higher deal volumes without proportional headcount expansion.
Industry Challenges
- Technical Due Diligence Scarcity:Deep-tech opportunities in semiconductors, synthetic biology, and climate hardware require specialized scientific advisory networks that most micro VC partnerships lack in-house.
- Succession Planning Deficits:Concentrated key-person risk in founder-led funds creates LP hesitancy for multi-vintage commitments when senior partners lack documented transition protocols.
- Cross-Border Regulatory Complexity:European AIFMD compliance and national marketing restrictions complicate US-based manager efforts to access EU institutional capital pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Micro VC Funds Market |
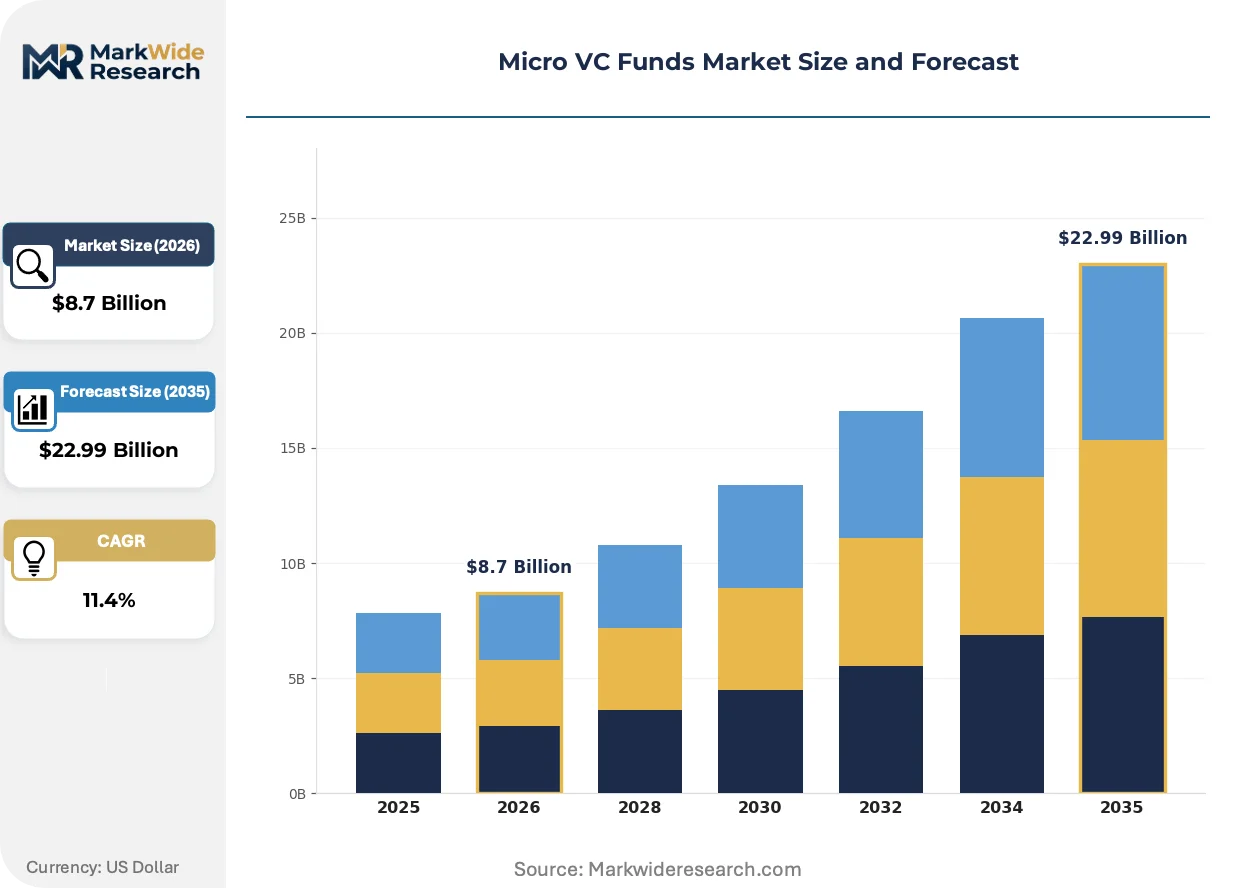
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investor Type: Angel Investors, Institutional Investors, Family Offices, Corporate Venture Investment Stage: Seed Stage, Series A, Pre-Series A, Bridge Financing Fund Structure: Closed-End Funds, Open-End Funds, Co-Investment Funds, Fund-of-Funds Sector Focus: Tech Startups, Consumer Products, Healthcare Innovations, Others |
| Companies Covered | Helios Capital, Quiet Capital, White Star Capital, Ulu Ventures, Hinge Capital, SV Angel, K5 Ventures, Kickstart, Switch Ventures, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Micro VC Funds Market Emerging Trajectories
Fund formation is pivoting toward sector-specific thesis concentration and operational value-add models, displacing the generalist spray-and-pray approach that dominated the 2015-2020 seed landscape.
Automated portfolio monitoring platforms are displacing quarterly manual reporting workflows. Micro VC managers deploy real-time dashboards tracking portfolio company cash burn, hiring velocity, and customer acquisition metrics. This transparency infrastructure compresses information asymmetry between general partners and limited partners, enabling proactive intervention before distress materializes.
The SEC's private fund adviser reforms are reshaping disclosure obligations for US-domiciled vehicles. Quarterly statements now require standardized performance metrics and fee/expense reporting that previously varied across manager presentations. Smaller funds respond by outsourcing compliance to specialized fund administrators, passing incremental costs to LPs through modified limited partnership agreements.
Technical founders increasingly select lead investors based on platform service depth rather than brand recognition alone. Recruiting support, customer introduction networks, and follow-on financing facilitation now dominate selection criteria in competitive seed rounds. This behavioral shift concentrates capital into vehicles with dedicated operating partners and functional specialist staff, disadvantaging lean two-partner structures.
Micro VC Funds Market Segmentation
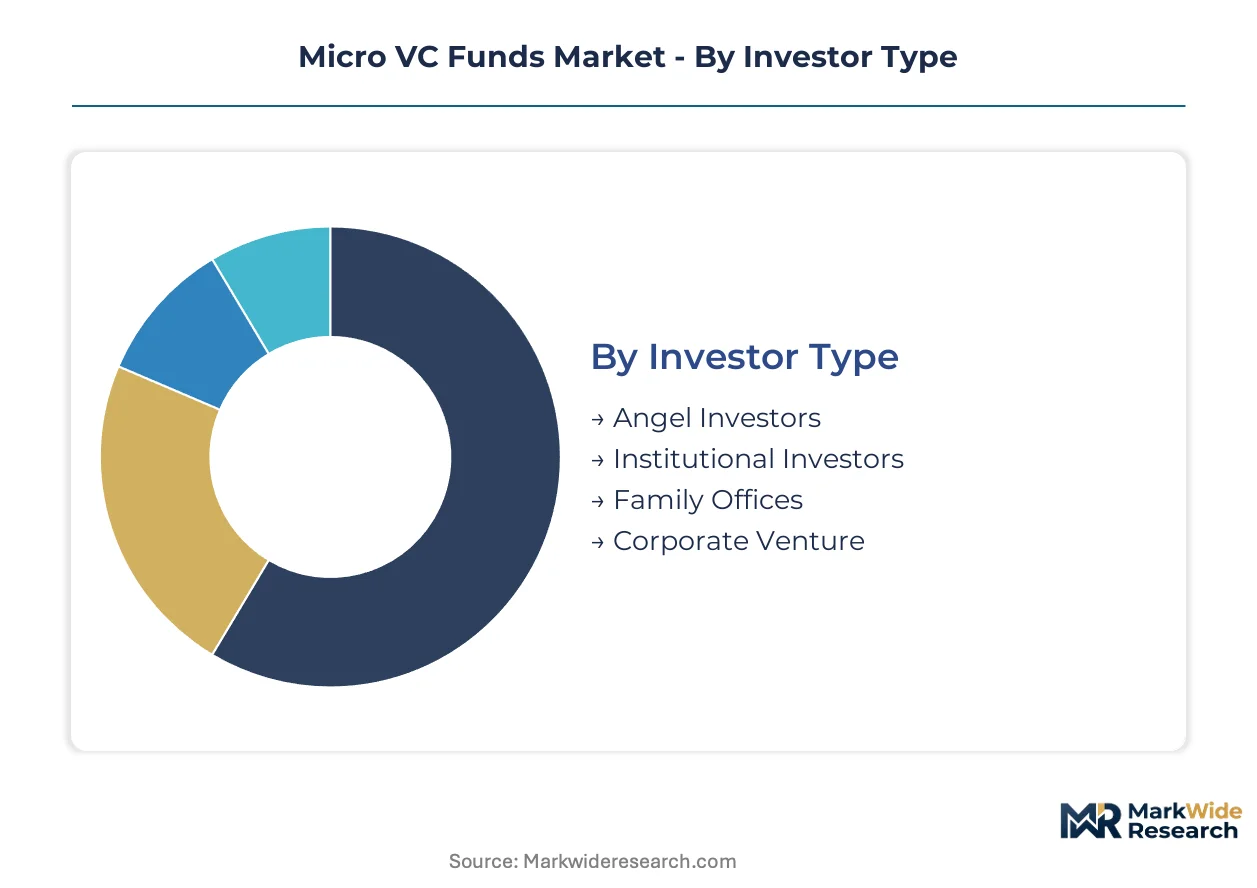
Micro VC fund segmentation reveals how capital pools align with investor sophistication, risk tolerance, and operational capabilities. Structural distinctions across these dimensions determine fundraising access, fee economics, and portfolio construction flexibility for emerging managers.
Investor Type:
Margin pools concentrate with institutional limited partners demanding governance rigor and reporting infrastructure that smaller vehicles struggle to provision.
- Institutional Investors:Pension funds, endowments, and foundations deploy capital through formal investment committees with multi-vintage commitment horizons. Their due diligence standards around ESG integration and succession planning compress fundraising timelines for generalist managers while elevating fee transparency requirements.
- Family Offices:Single and multi-family offices seek direct co-investment rights and sidecar exposure to specific portfolio companies. Their preference for fee-efficient structures accelerates adoption of bespoke vehicle formations outside standard limited partnership agreements.
- Angel Investors:High-net-worth individuals rotating capital from public markets into private fund access through SEC accredited investor pathways. Their participation broadens eligible LP pools but introduces concentration risk in founder-led vehicles lacking institutional governance.
- Corporate Venture:Strategic balance sheet deployment from technology and healthcare incumbents seeking optionality on acquisition targets. Their investment horizons align with product roadmap integration rather than pure financial return maximization.
Institutional investors command the dominant share of committed capital, while family offices are expanding their allocation fastest through direct co-investment vehicles.
Investment Stage:
Volume concentration sits at earliest-stage deployment where valuation entry points and ownership thresholds maximize return multiples.
- Seed Stage:First institutional capital into pre-revenue or early-revenue technology companies, typically $500K to $3M initial checks. Bay Area cluster density sustains deal-flow velocity for locally anchored managers competing on platform service depth rather than brand alone.
- Pre-Series A:Bridge financing between angel syndicates and priced institutional rounds, capturing widening valuation spreads as diligence timelines extend. Technical founder talent rotation toward sector-specific vehicles tightens supply of generalist operators capable of evaluating these opportunities.
- Series A:Priced rounds with lead investors taking board seats and governance control, often marking the transition from micro VC to multi-stage venture participation. Micro VC funds rarely lead these rounds but maintain pro-rata rights through sidecar arrangements.
- Bridge Financing:Extension capital for portfolio companies navigating delayed milestone achievement or compressed runway scenarios. These deployments test manager reserve allocation discipline and founder coaching capabilities under distress conditions.
Seed Stage captures the dominant volume share, while Pre-Series A deployment is climbing the fastest as valuation compression extends entry timelines.
Fund Structure:
Liquidity preference and fee transparency differentiate structural economics across limited partner constituencies.
- Closed-End Funds:Fixed-term vehicles with 10-year lifecycles and defined distribution waterfalls, retaining structural primacy due to LP preference for terminal liquidity events. SEC quarterly reporting requirements impose compliance burdens disproportionately on sub-$50 million managers lacking dedicated infrastructure.
- Co-Investment Funds:Sidecar vehicles enabling direct LP participation in specific portfolio companies alongside general partner judgment. These structures attract family office capital seeking fee reduction and concentrated exposure without manager selection risk.
- Open-End Funds:Evergreen capital pools with periodic redemption rights and continuous fundraising, rare in micro VC due to venture asset illiquidity and J-curve dynamics. European AIFMD compliance complexity further constrains their formation for US-domiciled managers.
- Fund-of-Funds:Diversified exposure across multiple micro VC managers, typically deployed by institutional investors lacking direct sourcing capabilities or sector specialization. Fee layering concerns limit their penetration in sub-$100 million vehicle categories.
Closed-End Funds maintain structural dominance, while Co-Investment Funds are gaining share fastest as LPs seek direct exposure alongside established manager judgment.
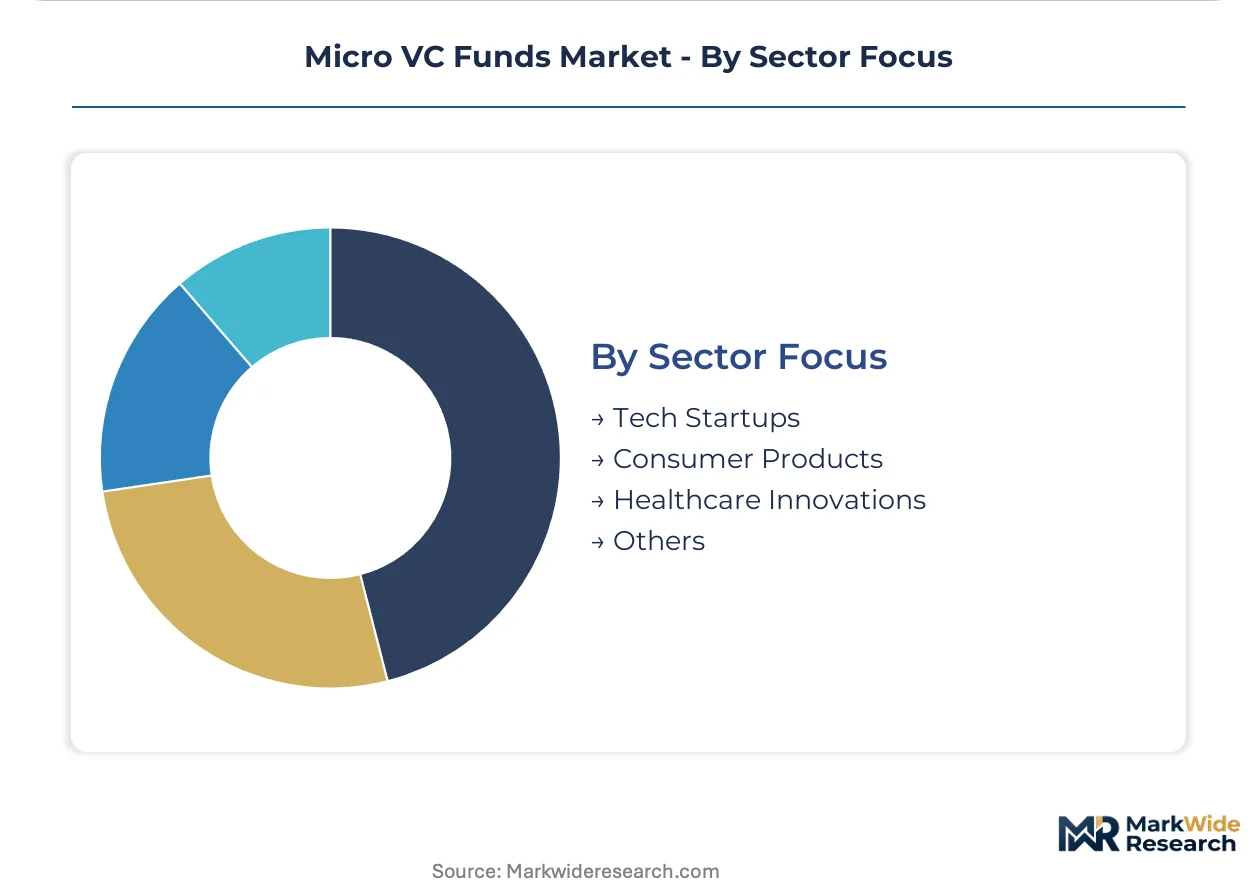
Sector Focus:
Technical due diligence requirements and exit liquidity depth determine margin capture across vertical specializations.
- Tech Startups:Enterprise software, developer tools, and infrastructure automation commanding concentrated capital deployment. Automated portfolio monitoring platforms now displace manual reporting workflows for managers in this segment.
- Healthcare Innovations:Digital health, therapeutic platforms, and medical devices requiring specialized scientific advisory networks most micro VC partnerships lack in-house. FDA regulatory pathways and reimbursement validation extend holding periods beyond standard venture timelines.
- Consumer Products:Direct-to-commerce brands and consumer marketplace platforms with shorter path to revenue but compressed exit multiples. These investments test manager platform service depth around customer acquisition and supply chain facilitation.
- Others:Climate technology, fintech infrastructure, and defense-adjacent hardware catalyzed by Inflation Reduction Act production tax credits and loan guarantee programs. Deep-tech opportunities in semiconductors and synthetic biology concentrate in specialized vehicles with technical founder networks.
Tech Startups retain the dominant allocation share, while Healthcare Innovations is expanding most quickly as technical founder talent rotates toward sector-specific vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Micro VC fund deployment concentrates in jurisdictions with dense founder talent pools and permissive securities frameworks, though capital access patterns diverge sharply between established venture clusters and emerging formation zones.
United States
Bay Area and New York Metro anchor the dominant share of seed-stage deployment, with technical founders clustering around Y Combinator and similar accelerators. The SEC's accredited investor amendments under the Investment Advisers Act expanded eligible LP pools beyond traditional institutional boundaries. Austin and Seattle venture density is accelerating as operating costs in San Francisco compress fund expense ratios.
United Kingdom
London's fintech and enterprise software formation attracts concentrated micro VC attention, with managers competing on platform service depth rather than brand alone. The Financial Conduct Authority's regulatory perimeter shapes fund marketing permissions and retail investor solicitation boundaries. Cambridge and Oxford university spinout pipelines supply technical founder talent to sector-specific vehicles.
Germany
Berlin's startup density and Munich's deep-tech formation create bifurcated demand for generalist and specialized micro VC vehicles. BaFin oversight of alternative investment funds imposes disclosure requirements that favor established managers with compliance infrastructure. The Rhine-Ruhr industrial corridor supplies enterprise software customers for B2B-focused seed portfolios.
Israel
Tel Aviv's cybersecurity and defense-adjacent startup formation draws specialized micro VC capital seeking technical due diligence leverage. The Israel Securities Authority governs fund solicitation to domestic and international investors. Herzliya Pituach and Jerusalem tech clusters concentrate founder talent with military unit alumni networks.
India
Bangalore and Delhi-NCR host expanding micro VC formation targeting SaaS and fintech opportunities at price points below US comparables. SEBI's AIF regulations categorize venture funds by investment strategy and investor eligibility. Mumbai's financial services incumbents increasingly deploy balance sheet capital through strategic co-investment structures.
Micro VC Funds Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in micro VC fund formation, with concentrated ownership of Bay Area deal flow separating top-quartile performers from capital-constrained followers. The market structure rewards geographic proximity to founder clusters and operational platform depth over pure financial scale. Two strategic archetypes dominate: thesis-driven sector specialists and network-anchored generalists. Competitive intensity manifests through sidecar vehicle creation and LP co-instruction rights rather than fee compression alone.
Among network-anchored vehicles, SV Angel exemplifies proximity-driven deal flow capture through accelerator ecosystem integration. Quiet Capital occupies a position within the thesis-driven tier, representing Pacific Northwest specialization in enterprise software formation. Ulu Ventures anchors the data-science-integrated archetype, demonstrating quantitative selection methodology adoption among sub-$100 million vehicles.
| Leading Market Players |
|---|
| Helios Capital |
| Quiet Capital |
| White Star Capital |
| Ulu Ventures |
| Hinge Capital |
| SV Angel |
| K5 Ventures |
| Kickstart |
| Switch Ventures |
| Others |
Supply Flow & Price Mechanics
Ninety-day fundraising timelines for sub-$50 million vehicles compress manager pricing power against institutional limited partners demanding fee transparency. This liquidity pressure concentrates capital into established vehicles with proven track records, while newer managers absorb elevated compliance costs that squeeze management fee economics. The resulting fee compression reshapes partnership staffing models and platform service depth.
Pricing Analysis
Closed-end fund structures with 10-year lifecycles and defined distribution waterfalls dominate micro VC pricing architecture. Fee differentiation separates established managers commanding 2% management fees and 20% carried interest from emerging vehicles accepting 1.5% management fees to secure inaugural commitments. Pricing pressure intensifies as limited partners negotiate reduced economics for sub-scale fund sizes, particularly for sub-$50 million vehicles lacking compliance infrastructure. Family offices exhibit highest price sensitivity through direct co-investment vehicle demands, while pension funds prioritize governance rigor over marginal fee reduction.
Supply Chain Analysis
Strait of Hormuz transit risk and correspondent banking friction choke capital flows into emerging market micro VC formation. Supply of institutional limited partner commitments concentrates in the United States, the United Kingdom, and Germany, with Bay Area and New York Metro anchoring dominant seed-stage deployment velocity. Raw material dependencies include technical founder talent pipelines, accelerator ecosystem relationships, and scientific advisory networks. Single-source vulnerability manifests through concentrated key-person risk in founder-led funds lacking documented succession protocols. Distribution runs through formal investment committees at pension funds and endowments, with family offices increasingly accessing deals through sidecar arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Micro VC fund formation sits in early-cycle expansion as accredited investor definition amendments broaden eligible limited partner pools beyond traditional institutional boundaries. Specialized sector vehicles capture widening spreads as technical founder talent rotates away from generalist managers.
For Market Incumbents: Consolidate deal-flow dominance through accelerator ecosystem integration and dedicated operating partner staffing. SV Angel's Y Combinator proximity model demonstrates sustained competitive moats against emerging entrants lacking platform service depth. Vertical integration into automated portfolio monitoring infrastructure compresses information asymmetry and elevates governance standards for institutional limited partners. Defensive capacity addition in climate technology and healthcare innovation verticals addresses technical due diligence scarcity threatening generalist positioning.
For New Entrants and Emerging Players: Differentiate on data science integration into early-stage selection methodology, following Ulu Ventures' quantitative sourcing platform approach. Target Pre-Series A deployment where valuation compression extends entry timelines and generalist operator supply tightens. Austin and Seattle venture clusters offer penetrable geography with accelerating founder density and compressed operating costs versus Bay Area saturation. Go-to-market angle should emphasize sector-specific thesis concentration in enterprise software or climate technology formation.
For Investors and Strategic Acquirers: Carve-out targets emerge from corporate venture balance sheet deployments seeking liquidity from strategic optionality positions. Long-term viability favors vehicles with documented succession protocols and multi-vintage track records spanning valuation cycles. Acquisition target archetype includes sub-$100 million funds with concentrated sector expertise and established scientific advisory networks. Signal to watch: management fee compression rates accelerating beyond 25 basis points per fundraising cycle as limited partner negotiation power intensifies.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Service Depth Expansion | Recruiting support and customer introduction networks now dominate founder selection criteria in competitive seed rounds. |
| Data Science Integration | Quantitative sourcing platforms reduce partner time per investment decision without proportional headcount expansion. |
| Co-Investment Vehicle Formation | Sidecar arrangements attract family office capital seeking fee-efficient exposure alongside established manager judgment. |
| Sector-Specific Thesis Concentration | Technical founder talent rotation tightens supply of generalist operators capable of evaluating deep-tech opportunities. |
| Automated Portfolio Monitoring Deployment | Real-time dashboards tracking cash burn and hiring velocity compress information asymmetry between general partners and limited partners. |
Methodological Framework
Cross-validation between primary interviews with general partners, limited partners, and fund administrators anchors the qualitative findings against secondary validation from SEC filings, Form ADV disclosures, and Preqin fund performance databases. Conversations with institutional investment committee members, family office portfolio managers, and fund formation attorneys inform capital allocation pattern analysis. Secondary sources include the Investment Advisers Act regulatory filings, EU AIFMD compliance documentation, and venture capital association market reports. Bottom-up triangulation across individual fund track records and top-down aggregation across vintage year performance produce convergent estimates.
Sensitivity analysis around accredited investor definition changes and management fee compression scenarios tests forecast robustness across the projection horizon. Segmentation dimensions modeled include fund structure, investment stage, investor type, and sector focus. CAGRs derive from vintage year cash flow pattern analysis and exit liquidity timeline distributions. Industry-specific forecast inputs capture regulatory solicitation friction impacts and technical founder talent pipeline velocity.
Material uncertainties — regulatory amendment timing, valuation compression severity, and limited partner commitment cycle shifts — sit outside the modeled envelope. Forecasts reflect documented assumptions around SEC enforcement patterns and EU marketing passport availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
US Venture Capital Investment Market
Venture Capital
Micro Venture Capital VC Funds Market
Venture Capital
North America Venture Capital Market
Venture Capital
Crowdfunding Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
Asia Pacific Venture Capital Market
Venture Capital
Business Incubator Market
Venture Capital
Venture Capital Investment Market
Venture Capital
Angel Funds Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
United States Venture Capital Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
Europe Venture Capital Market
Venture Capital
Impact Investing Market
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Equity Crowdfunding Market