
 US Venture Capital Investment Market | 2026-2036
US Venture Capital Investment Market Size, Share, and Industry Trends Forecast 2026-2036
US Venture Capital Investment Market Insights
LP capital deployment is pivoting toward concentrated commitments from sovereign wealth funds and mega-endowments while emerging family offices fragment the lower-middle market. Sequoia Capital leverages its crossover fund structure to anchor late-stage rounds across enterprise software. Andreessen Horowitz sustains vertical specialization through dedicated bio and crypto practice teams. Accel competes on seed-stage velocity with its early-track program in Palo Alto and Cambridge.
US venture capital investment denotes institutional private equity financing provided to high-growth private companies, typically structured as limited partnerships with ten-year fund lives, 2% management fees, and 20% carried interest waterfalls. The primary commercial purpose is generating asymmetric returns through portfolio company equity appreciation ahead of IPO or strategic acquisition. Growth-stage deployment leads aggregate dollar volume as mega-rounds concentrate in artificial intelligence infrastructure and defense technology. Seed-stage activity shows the fastest expansion in absolute deal count, though average check sizes remain compressed relative to Series C infusions. Industry vertical segmentation reveals technology commanding the deepest LP allocations, with healthcare biotechnology capturing premium valuations through FDA breakthrough designations.
The SEC defines accredited investor thresholds under Regulation D, while ERISA governs pension fund participation in alternative assets, and the IRS oversees carried interest taxation through Section 1061. These frameworks shape fund domicile selection, LP composition limits, and general partner compensation structures. Stakeholders must monitor proposed SEC private fund adviser rulemaking for its structural impact on disclosure obligations and side-letter standardization.
Market Dynamics
LP capital concentration into mega-funds is compressing mid-market formation, while the SEC's evolving accredited investor thresholds reshape fund-raising strategies across California, New York, and Massachusetts corridors.
Growth Catalysts
- Artificial Intelligence Infrastructure:Foundation model development is absorbing concentrated capital allocations from sovereign wealth vehicles and university endowments seeking asymmetric exposure to compute-intensive startups.
- Qualified Purchaser Threshold Expansion:SEC amendments to Regulation D are broadening the eligible LP base, enabling fund managers to access deeper capital pools for Series C and growth-stage deployment.
- Defense Technology Demand:Pentagon modernization priorities and Inflation Reduction Act manufacturing incentives are channeling institutional commitments into dual-use hardware and software ventures.
Market Restraints
- Carried Interest Taxation Uncertainty:IRS Section 1061 holding-period requirements are compressing general partner compensation structures and discouraging rapid portfolio turnover strategies.
- Valuation Mark-to-Market Volatility:Absent liquid secondary markets, late-stage private company pricing relies on sparse comparable transactions, creating NAV reporting inconsistencies for pension fund LPs.
- ERISA Fiduciary Constraints:Department of Labor guidance on alternative asset prudence is lengthening investment committee due diligence timelines for corporate defined-benefit plans.
Strategic Opportunities
- Texas and Florida LP Expansion:State income tax migration patterns are concentrating new family office formation in Austin, Miami, and Dallas, creating underpenetrated capital sources outside traditional coastal hubs.
- Climate Technology Convergence:Intersection of battery chemistry, grid software, and carbon accounting platforms is opening thematic fund strategies that cross traditional sector boundaries.
- SBIC Leverage Programs:Small Business Administration licensing frameworks offer subordinated debt capacity that magnifies dry powder for seed-stage managers targeting underserved geographies.
Industry Challenges
- Technical Talent Scarcity:Deep learning research scientists command compensation packages that consume disproportionate burn rates at pre-revenue AI startups, compressing runway timelines.
- Side-Letter Standardization Friction:Bespoke LP governance terms and information-rights provisions are creating administrative complexity that delays fund closings and elevates legal spend.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Venture Capital Investment Market |
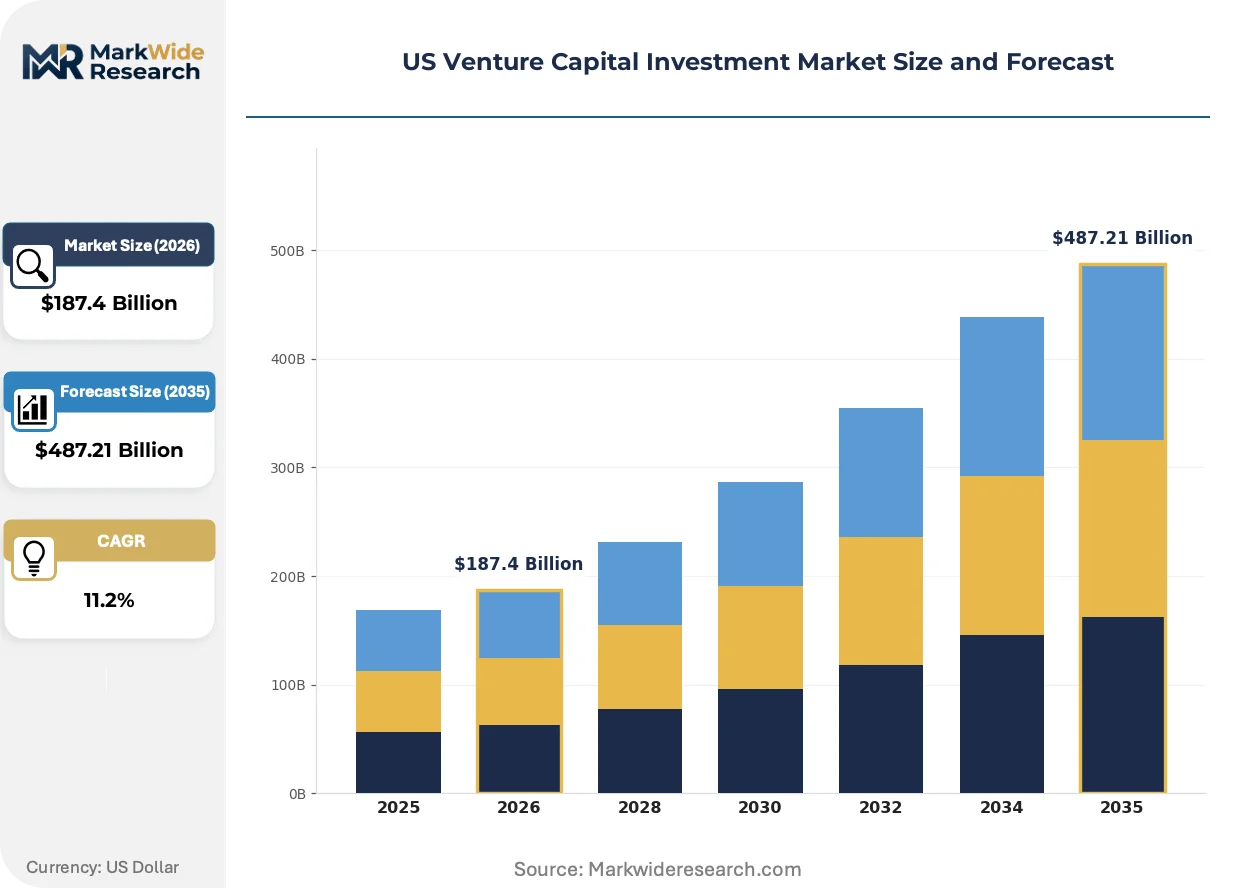
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $487.21 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed Stage, Early Stage, Growth Stage, Late Stage Funding Type: Equity Financing, Convertible Notes, Debt Financing, SAFE Industry Vertical: Technology, Healthcare, Consumer Products, Financial Services Investor Type: Venture Capital Firms, Angel Investors, Corporate Investors, Family Offices |
| Companies Covered | Sequoia Capital, Andreessen Horowitz, Accel, Tiger Global Management, New Enterprise Associates, Bessemer Venture Partners, Lightspeed Venture Partners, Kleiner Perkins, General Catalyst, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Venture Capital Investment Market Trends and Innovations
Crossover fund structures and vertical specialization are fragmenting traditional stage-based deployment models, while regulatory technology and LP data infrastructure reshape operational workflows.
Generative artificial intelligence is rewriting due diligence velocity and portfolio company operational scaling. Growth-stage managers deploy large language models to automate market-sizing and competitive mapping tasks. Enterprise software startups integrate copilot interfaces into core workflows, compressing sales cycles and elevating revenue-per-employee metrics that attract follow-on capital.
The SEC's private fund adviser rulemaking is mandating quarterly statement standardization and audit requirements for advisers with over one billion dollars in assets under management. Compliance technology vendors are capturing spend from fund administrators scrambling to meet disclosure deadlines. Smaller managers in Boston and Chicago are consolidating to achieve scale thresholds or exiting to larger platforms.
Institutional limited partners are unbundling manager relationships and constructing direct co-investment capabilities in-house. Endowments with dedicated private markets teams are bypassing fund fees on select late-stage rounds, compressing economics for general partners. This behavior is most visible among Ivy League institutions and large public pension systems with staff counts exceeding fifty investment professionals.
US Venture Capital Investment Market Segmentation
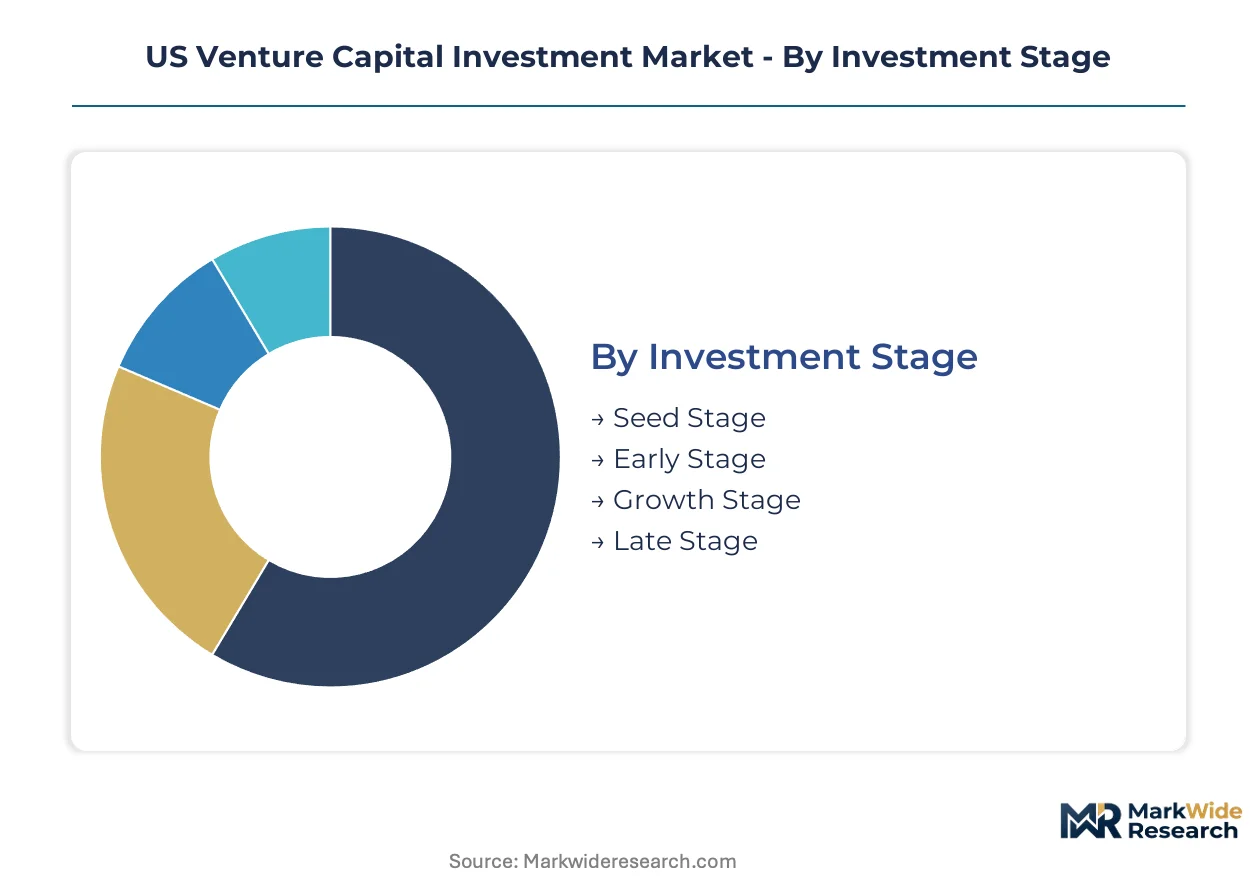
Investment stage delineation shapes fund structure, fee schedules, and LP return expectations across the US venture capital landscape. Funding type selection determines founder dilution trajectories and governance rights allocation. Industry vertical and investor type classifications reveal capital concentration patterns and competitive positioning strategies.
Investment Stage:
Technical maturity and revenue visibility define risk-return profiles across the deployment spectrum.
- Seed Stage:Pre-product or pre-revenue companies receive initial institutional capital, typically structured as SAFE instruments or convertible notes. Demand concentrates in Austin and Miami startup clusters where technical talent migration from coastal hubs is accelerating company formation velocity.
- Early Stage:Post-revenue ventures with product-market fit validation attract Series A and B rounds. California's Bay Area maintains the deepest LP allocations here, driven by Sequoia Capital and Andreessen Horowitz dedicated seed-track programs that compress due diligence timelines.
- Growth Stage:Scaling enterprises with repeatable unit economics absorb concentrated sovereign wealth fund commitments. Pentagon modernization priorities are channeling institutional capital into defense technology ventures at this maturity threshold.
- Late Stage:Pre-IPO companies attract crossover fund structures that blur public-private valuation methodologies. Absent liquid secondary markets, NAV reporting inconsistencies create friction for pension fund LP portfolio construction.
Mature deployment sits with Growth Stage. Newer deployment is concentrated in Seed Stage.
Funding Type:
Cost tier positioning reflects founder control preferences and LP liquidity requirements.
- Equity Financing:Direct ownership stakes with pro-rata rights and board seats represent the standard institutional structure. Premium valuations in healthcare biotechnology with FDA breakthrough designations command this instrument.
- Convertible Notes:Debt instruments that convert at discounted valuations upon qualified financing rounds. Early-stage managers in Boston's Route 128 corridor deploy these to defer pricing negotiations until technical milestones mature.
- Debt Financing:Revenue-based or asset-backed lending structures preserve founder equity. Venture debt providers are expanding capacity for enterprise software startups with predictable recurring revenue streams.
- SAFE:Simple agreements for future equity minimize legal complexity and accelerate closings. Y Combinator's standardized documentation has proliferated this instrument across accelerator-backed formations.
Established structures dominate Equity Financing. Instrument innovation is expanding fastest in SAFE adoption.
Industry Vertical:
Application focus determines regulatory exposure and exit pathway availability.
- Technology:Enterprise software and artificial intelligence infrastructure command the deepest LP allocations. Foundation model development is absorbing concentrated capital from university endowments seeking asymmetric compute-intensive exposure.
- Healthcare:Biotechnology and medical device ventures capture premium valuations through regulatory milestone achievements. FDA breakthrough designations accelerate capital deployment timelines for clinical-stage assets.
- Consumer Products:Direct-to-commerce and physical goods startups face compressed multiples relative to software. Inflation Reduction Act manufacturing incentives are partially offsetting margin pressure for domestic production.
- Financial Services:Fintech and insurtech ventures navigate SEC and state regulatory fragmentation. Embedded finance APIs are attracting corporate venture capital from incumbent banking institutions.
Technology verticals anchor mature LP commitments. Healthcare biotechnology is climbing the fastest on valuation expansion.
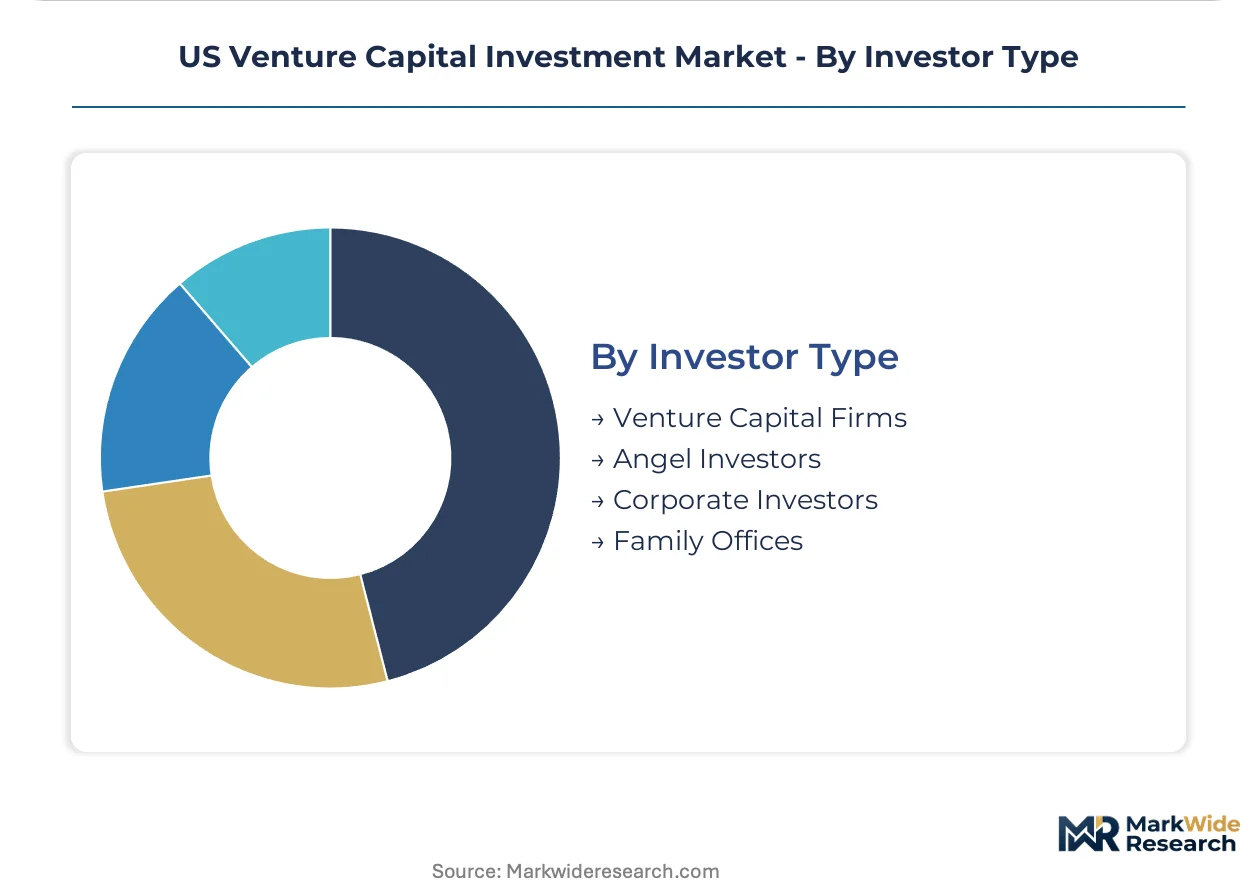
Investor Type:
Customer type segmentation reveals capital source concentration and governance sophistication.
- Venture Capital Firms:Institutional limited partnerships with ten-year fund lives and 2/20 fee structures. Mega-fund formation is compressing mid-market manager economics across California, New York, and Massachusetts corridors.
- Angel Investors:High-net-worth individuals deploying personal capital at seed stage. Texas and Florida income tax migration is concentrating new angel formation in Austin, Miami, and Dallas.
- Corporate Investors:Strategic venture arms seeking technology access and acquisition optionality. Enterprise software copilot integrations are elevating corporate venture participation in AI infrastructure.
- Family Offices:Single and multi-family entities with flexible mandate structures and longer hold periods. Fragmentation across emerging offices is reshaping lower-middle market fundraising dynamics.
Established LP bases reside with Venture Capital Firms. Capital source diversification is expanding most quickly through Family Office formation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Institutional capital deployment concentrates in coastal metropolitan clusters where fund managers, limited partners, and technical talent co-locate. State tax policies and regulatory frameworks shape formation velocity across sub-national markets.
California
Bay Area fund managers anchor the deepest LP allocation pools, with sovereign wealth vehicles and university endowments channeling commitments into artificial intelligence infrastructure. SEC Regulation D amendments broaden accredited investor eligibility, expanding the eligible capital base for Series C rounds. Palo Alto and San Francisco host the densest concentration of seed-stage velocity programs, where dedicated early-track initiatives compress due diligence timelines for technical founders.
New York
Financial services integration drives fintech and insurtech venture formation, with embedded finance APIs attracting corporate venture capital from incumbent banking institutions. ERISA fiduciary guidance from the Department of Labor lengthens investment committee due diligence for corporate defined-benefit plans participating in alternative assets. Manhattan and Brooklyn clusters concentrate growth-stage deployment, where crossover fund structures blur public-private valuation methodologies for pre-IPO companies.
Massachusetts
Healthcare biotechnology captures premium valuations through FDA breakthrough designations, accelerating capital deployment timelines for clinical-stage assets. IRS Section 1061 holding-period requirements compress general partner compensation structures and discourage rapid portfolio turnover strategies. Cambridge and Boston's Route 128 corridor host dedicated seed-track programs, where convertible note deployment defers pricing negotiations until technical milestones mature.
Texas
State income tax migration patterns concentrate new family office formation, creating underpenetrated capital sources outside traditional coastal hubs. Small Business Administration SBIC licensing frameworks offer subordinated debt capacity that magnifies dry powder for seed-stage managers. Austin and Dallas clusters absorb technical talent migration from coastal hubs, accelerating company formation velocity in enterprise software and defense technology.
Florida
Angel investor formation accelerates in Miami and Tampa, where flexible mandate structures and longer hold periods reshape lower-middle market fundraising dynamics. SEC private fund adviser rulemaking mandates quarterly statement standardization, driving compliance technology spend among fund administrators. Southeast corridor clusters attract emerging managers consolidating to achieve scale thresholds or exiting to larger platforms.
US Venture Capital Investment Market Competitive Landscape
California-based managers anchor the mega-fund tier; New York and Massachusetts specialists hold concentrated positions in sector-specific strategies. Market structure exhibits tiered consolidation, with ten to fifteen firms capturing the majority of institutional commitments above one billion dollars. Three archetypes dominate: crossover-structured generalists, vertically specialized sector funds, and seed-stage velocity operators. Competitive moves center on fund size expansion to capture sovereign wealth allocations, and vertical practice team buildout to differentiate sourcing capabilities.
Within the mega-fund archetype, Sequoia Capital and Andreessen Horowitz occupy positions representing scale-driven deployment models. Accel exemplifies the seed-stage velocity operator, with geographic positioning across Palo Alto and Cambridge. These three firms collectively represent the structural segmentation between crossover generalists and early-stage specialists competing for institutional limited partner commitments.
| Leading Market Players |
|---|
| Sequoia Capital |
| Andreessen Horowitz |
| Accel |
| Tiger Global Management |
| New Enterprise Associates |
| Bessemer Venture Partners |
| Lightspeed Venture Partners |
| Kleiner Perkins |
| General Catalyst |
| Others |
Pricing and Supply Chain Analysis
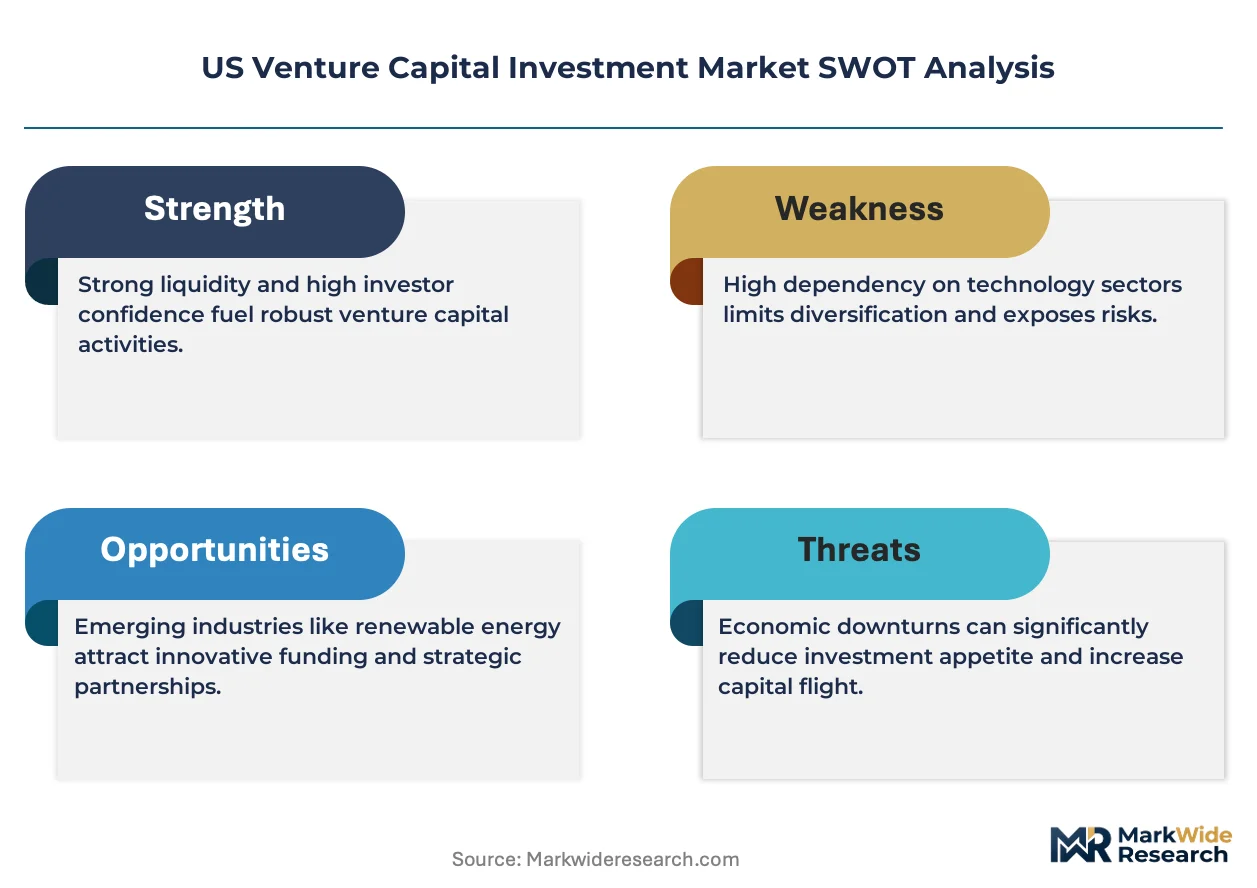
Bloomberg Terminal data feeds and PitchBook pricing benchmarks cascade through LP fee negotiations into management fee tiers across seed, growth, and mega-fund structures. Carried interest waterfalls compress when IRS Section 1061 holding-period requirements extend realization timelines, forcing GPs to absorb duration risk that institutional LPs refuse to price.
Pricing Analysis
Volume-versus-margin splits concentrate LP capital into mega-funds above one billion dollars where management fees scale efficiently, while mid-market managers face fee compression from sovereign wealth fund concentration. Pricing stratifies across premium-tier crossover funds with dedicated practice teams, standard multi-stage generalists, and economy seed-stage operators with lean cost bases. Cost compression in seed-stage deployment is intensifying because technical talent scarcity inflates pre-revenue burn rates. Corporate defined-benefit plans exhibit highest price sensitivity due to ERISA fiduciary constraints, while family offices show lowest sensitivity given flexible mandate structures.
Supply Chain Analysis
Regional distribution of capital commitment flows centers on hub-and-spoke patterns with primary nodes in California's Bay Area, New York City, and Boston's Route 128 corridor feeding secondary markets in Austin, Miami, and Dallas. LP capital draws from sovereign wealth vehicles in the Middle East and Asia, university endowments across the US, and fragmented family offices in Texas and Florida. Single-source vulnerability concentrates in mega-fund GP relationships where ten to fifteen firms capture majority institutional commitments above one billion dollars. Distribution runs through prime broker networks and fund administrator platforms that standardize quarterly reporting for SEC compliance.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US venture capital market sits in a technology-transition phase where generative artificial intelligence infrastructure is displacing legacy enterprise software deployment models. Foundation model development absorbs capital that previously flowed to SaaS metrics-driven rounds.
For Market Incumbents: Cement crossover fund scale advantages by locking in sovereign wealth fund anchor commitments before SEC private fund adviser rulemaking elevates compliance costs for sub-billion-dollar managers. Anchor Sequoia Capital and Andreessen Horowitz positioning through dedicated bio and crypto practice teams defends against vertical specialist encroachment. Prioritize side-letter standardization to reduce administrative friction that delays fund closings.
For New Entrants and Emerging Players: Accelerators and university technology transfer offices offer the most penetrable channel partnerships for seed-stage velocity programs targeting technical founder migration to Austin and Miami. White-space sits in climate technology convergence strategies crossing battery chemistry, grid software, and carbon accounting boundaries. Go-to-market leverage rests on SBIC licensing frameworks that magnify dry powder through Small Business Administration subordinated debt capacity.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated platform plays in Texas and Florida where state income tax migration concentrates underpenetrated family office capital. Long-term viability across the next decade hinges on direct co-investment capability buildout that bypasses fund fees on select late-stage rounds. Watch Ivy League endowment LP unbundling behavior as the signal for GP economics compression inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Crossover Fund Structure Launch | Blurs public-private valuation methodologies for pre-IPO defense technology ventures. |
| Vertical Practice Team Buildout | Differentiates sourcing capabilities in FDA breakthrough-designated biotechnology assets. |
| SBIC Licensing Acquisition | Magnifies seed-stage dry powder through SBA subordinated debt leverage programs. |
| Direct Co-Investment Platform | Bypasses GP fees for pension funds with investment staff exceeding fifty professionals. |
| Regulatory Technology Integration | Automates SEC quarterly statement standardization for advisers above one billion AUM. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with fund formation attorneys, LP due diligence officers, GP compensation consultants, and SEC examination staff. SEC private fund adviser rulemaking dockets, ERISA fiduciary guidance releases, and IRS Section 1061 technical memoranda provided regulatory framework inputs. Bottom-up triangulation across individual fund raise announcements and top-down reconciliation against aggregate capital deployment flows validated market sizing.
Data-stream reconciliation across investment stage, funding type, industry vertical, and investor type segmentation dimensions produced volume and value outputs over the projection horizon. CAGRs derived from regression analysis against historical capital commitment velocity, LP allocation shift patterns, and regulatory threshold adjustments. Forecast inputs incorporated sovereign wealth fund mandate evolution, endowment private markets staffing expansion, and state tax migration demographics.
Caveats apply where SEC accredited investor threshold amendments, IRS carried interest taxation revisions, or ERISA fiduciary guidance updates could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
North America Venture Capital Market
Venture Capital
Angel Funds Market
Venture Capital
Crowdfunding Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
Europe Venture Capital Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
United States Venture Capital Market
Venture Capital
Asia-Pacific Venture Capital Investment Market
Venture Capital
Micro Venture Capital VC Funds Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
Asia Pacific Venture Capital Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
Business Incubator Market
Venture Capital
Micro VC Funds Market
Venture Capital
Impact Investing Market