
 Impact Investing Market | 2026-2036
Impact Investing Market Size, Share, and Industry Trends Forecast 2026-2036
Impact Investing Market Outlook
GIIN certification is collapsing as the minimum threshold for institutional capital deployment, separating credible impact managers from marketing-driven entrants. BlackRock leverages its Aladdin platform to integrate impact metrics across fixed-income and alternative portfolios. TPG sustains differentiation through its Rise Fund methodology, which quantifies social and environmental outcomes alongside financial returns. Brookfield Asset Management anchors its climate transition strategy through real asset allocations in renewable infrastructure and sustainable real estate.
Impact investing deploys capital into enterprises, funds, and organizations that generate measurable social and environmental outcomes alongside financial returns, with performance tracked through standardized metrics such as IRIS+ indicators and SDG alignment frameworks. The practice serves institutional and retail investors seeking to align portfolio construction with climate transition, equitable development, and resource efficiency objectives. Equity strategies command the deepest capital pools among investment strategy segments, while real assets attract infrastructure-focused sovereign wealth funds seeking inflation-linked yields. Clean energy dominates sector focus allocations as grid decarbonization accelerates, though sustainable agriculture gains traction among family offices addressing food security and land-use transformation.
EU Green Deal taxonomy and SFDR disclosure rules from the European Commission reshape product design and marketing boundaries for fund managers operating across member states. SEC climate disclosure proposals and IRA clean energy tax credits in the United States redirect institutional flows toward verified green assets. Stakeholders must monitor regulatory fragmentation between jurisdictional standards as the primary determinant of cross-border fund distribution feasibility and investor protection frameworks.
Market Dynamics
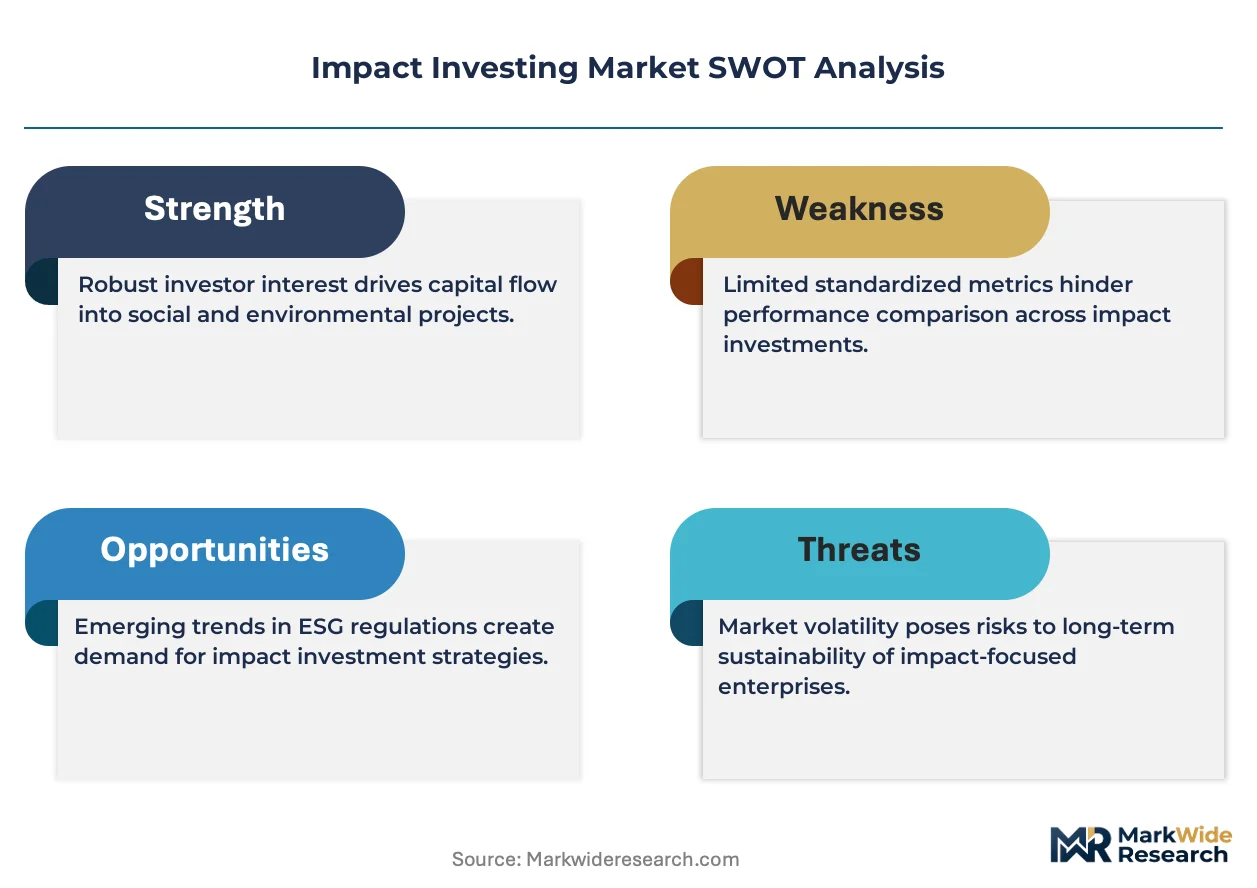
The EU Green Deal taxonomy and SFDR disclosure rules are compressing fund distribution timelines while forcing asset managers to restructure product architectures around verifiable environmental thresholds rather than marketing claims.
Growth Catalysts
- SFDR Article 9 Funds:The European Commission's sustainability disclosure regime creates mandatory transparency layers that institutional capital now treats as non-negotiable entry criteria for portfolio allocation decisions.
- Grid Decarbonization Infrastructure:Sovereign wealth funds from Norway to Singapore redirect capital flows into renewable energy assets as inflation-linked yield vehicles with measurable carbon displacement metrics.
- IRIS+ Standardization:The GIIN's harmonized indicator framework collapses measurement fragmentation across healthcare access and financial inclusion portfolios in sub-Saharan Africa.
Market Restraints
- Verification Cost Escalation:Third-party impact auditing and continuous monitoring obligations consume 80-150 basis points annually from fund operating budgets.
- Regulatory Arbitrage Friction:Divergent taxonomy definitions between EU Green Deal requirements and SEC climate disclosure proposals fragment cross-border product registration.
- Patient Capital Mismatch:Seven-to-ten-year lock-up structures inherent to healthcare and education access investments conflict with quarterly liquidity expectations of conventional institutional mandates.
Strategic Opportunities
- India PLI-Aligned Manufacturing:Production-linked incentive schemes for solar module and battery cell manufacturing create domestic impact investment entry points with tariff-protected offtake certainty.
- Natural Capital Accounting:Integration of biodiversity and water-stress metrics into agricultural land-use portfolios opens uncrowded thematic exposure beyond carbon-centric strategies.
- Blended Finance Structures:Development finance institution first-loss tranches enable commercial capital deployment into frontier market microfinance with risk-adjusted return profiles.
Industry Challenges
- Impact Measurement Talent Scarcity:Shortage of professionals combining quantitative finance training with sector-specific outcome evaluation expertise in climate and health metrics.
- Legacy System Integration:Asset managers struggle to embed IRIS+ and SDG alignment data into existing Aladdin and BlackRock-style portfolio management infrastructures without workflow disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Impact Investing Market |
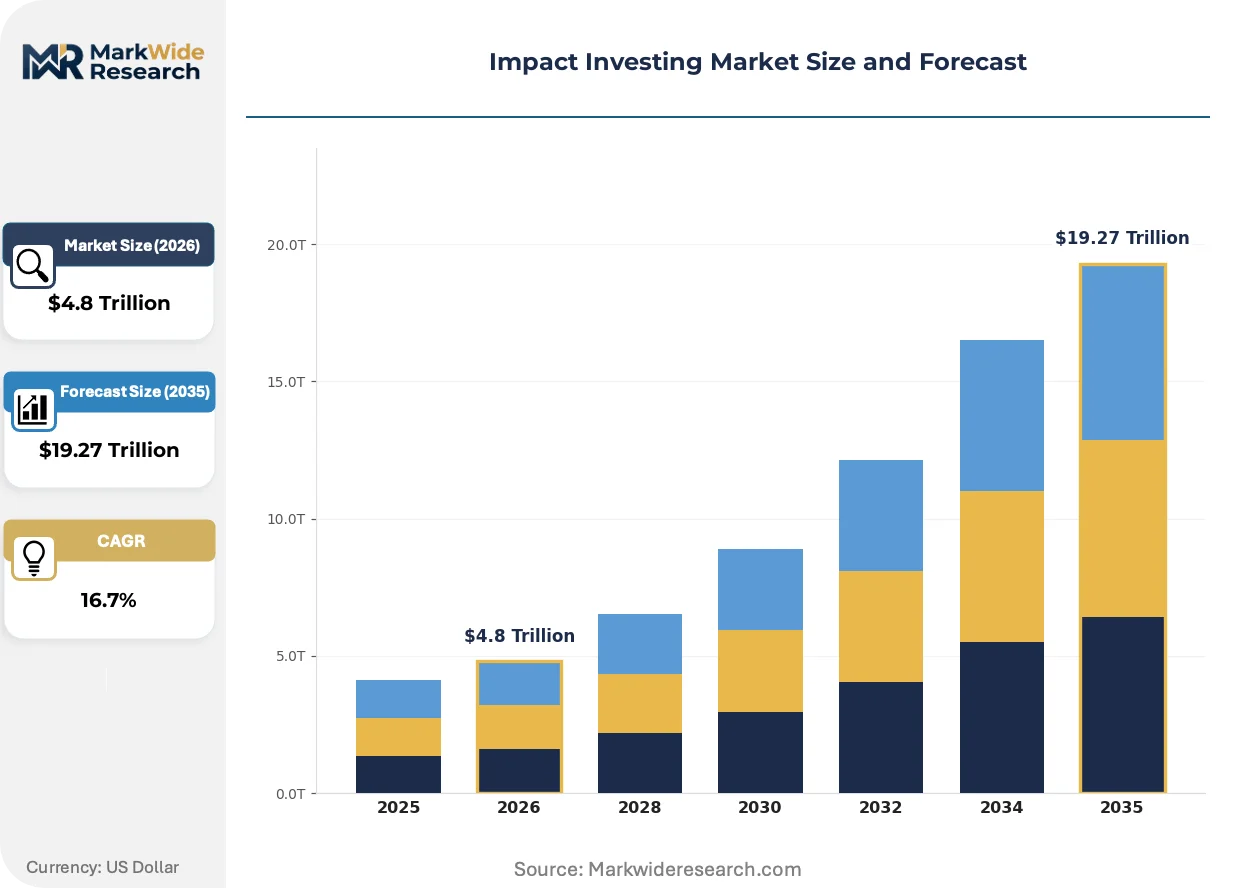
| Market Size in 2026 | $4.8 Trillion |
| Market Size in 2035 | $19.27 Trillion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Strategy: Equity, Debt, Real Assets, Funds Sector Focus: Clean Energy, Education, Healthcare, Sustainable Agriculture Fund Type: Venture Capital, Private Equity, Hedge Funds, Community Investments Investor Type: Institutional Investors, High Net Worth Individuals, Family Offices, Foundations |
| Companies Covered | Brookfield Asset Management, TPG, EQT, Meridiam, Goldman Sachs Asset Management, BlackRock, Actis, Enterprise Community Partners, LeapFrog Investments, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Impact Investing Market Strategic Shifts
Standardized impact measurement protocols are compressing the gap between marketing disclosure and verified outcome reporting, forcing technology architecture investments that separate scalable fund managers from compliance-lagged competitors.
Blockchain-enabled verification infrastructure is bifurcating the fund administration landscape. Smart contract-based impact attestation allows real-time outcome tracking for carbon credit and microfinance portfolios. Institutional limited partners in Dutch and Danish pension systems now mandate distributed ledger transparency layers. The technology is bifurcating capital flows toward managers with automated reporting capabilities and away from manual audit-dependent structures.
CSRD corporate sustainability reporting requirements from the European Commission expand mandatory disclosure scopes to private portfolio companies. Asset managers must now capture Scope 3 emissions and workforce diversity metrics across unlisted holdings. Clean energy infrastructure funds face the steepest compliance burden given construction-phase data gaps. Portfolio companies are responding by embedding sustainability data collection into ERP system implementations.
Subscription-based impact verification services are displacing traditional one-off audit engagements. Pension fund procurement teams in Sweden and the Netherlands now favor continuous monitoring contracts over annual attestation cycles. This compresses pricing power for legacy accounting firms while elevating technology-native verification platforms. The shift is most visible in agricultural land-use portfolios where seasonal outcome variability demands real-time sensor data integration.
Impact Investing Market Segmentation
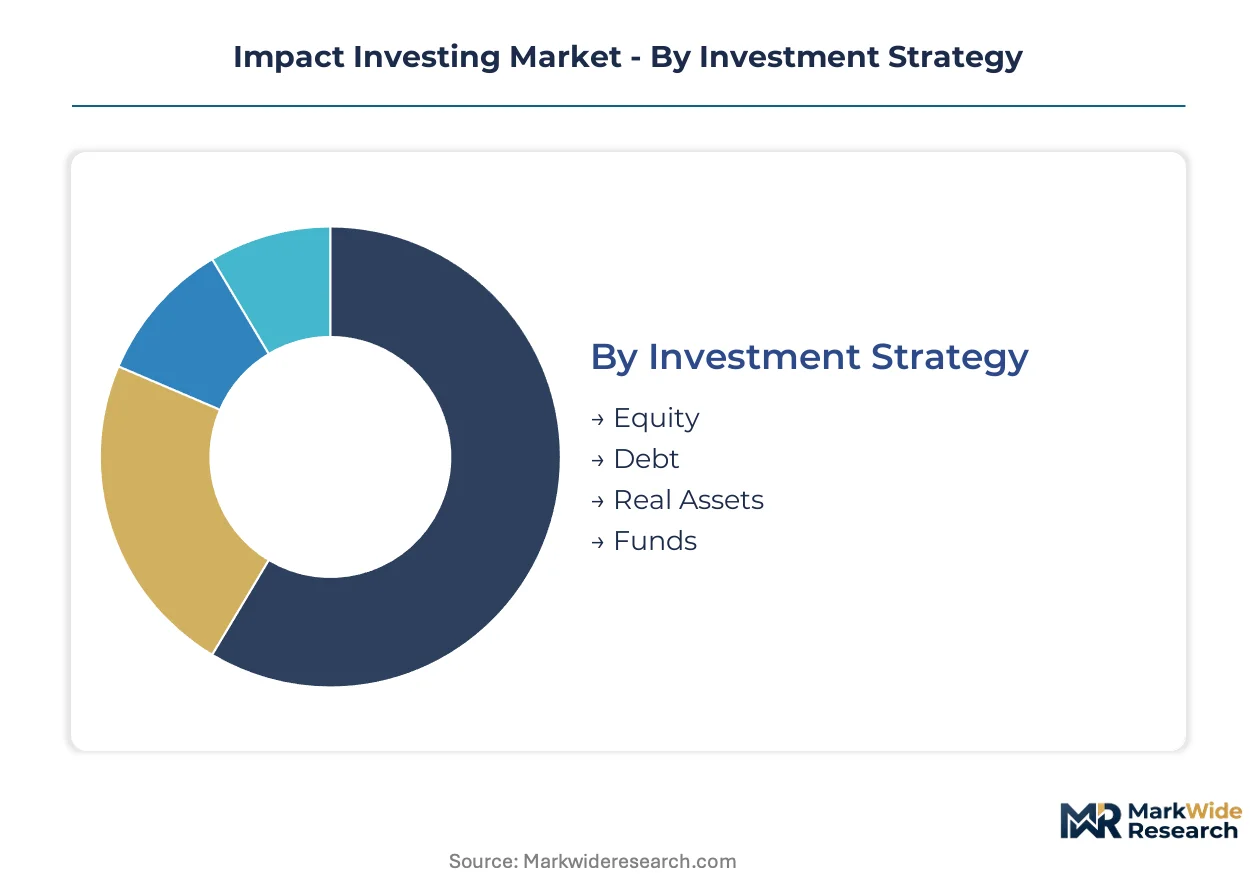
Impact investing requires precise segmentation to match capital structures with outcome measurement frameworks. Each category channels through distinct distribution pathways and regulatory compliance layers.
Investment Strategy:
Equity strategies flow through fund-of-funds platforms and direct co-investment vehicles, while real assets concentrate in infrastructure-focused sovereign wealth mandates.
- Equity:Direct ownership stakes in private enterprises with board-level governance rights enabling outcome accountability. Demand concentrates in sub-Saharan Africa where LeapFrog Investments and regional managers deploy patient capital into financial inclusion and healthcare access portfolios.
- Real Assets:Physical infrastructure and property holdings with inflation-linked yield characteristics and measurable carbon displacement metrics. Norway's sovereign wealth fund and Singapore's GIC anchor allocations here as grid decarbonization accelerates renewable energy deployment.
- Debt:Fixed-income instruments with interest rate structures tied to sustainability performance targets.
- Funds:Pooled vehicles offering diversification across sectors and geographies with standardized IRIS+ reporting.
Equity dominates installed base. Real assets are where expansion concentrates.
Sector Focus:
Clean energy commands premium valuations due to IRA tax credit eligibility and EU Green Deal taxonomy alignment, while sustainable agriculture trades at lower multiples with longer outcome verification cycles.
- Clean Energy:Solar, wind, and grid storage assets with construction-phase data gaps creating compliance burdens under CSRD requirements. Brookfield Asset Management anchors climate transition strategies through renewable infrastructure allocations.
- Sustainable Agriculture:Land-use transformation and food security investments with seasonal outcome variability demanding real-time sensor data integration. Family offices in the Netherlands and Sweden favor continuous monitoring contracts over annual attestation cycles here.
- Healthcare:Access and affordability enterprises in frontier markets with seven-to-ten-year lock-up structures.
- Education:Workforce development and skills training platforms with outcome metrics tied to employment placement rates.
Clean energy leads capital deployment. Sustainable agriculture is gaining share fastest among family offices addressing biodiversity metrics.
Fund Type:
Venture capital structures accommodate highest risk-return profiles with concentrated manager selection, while community investments trade liquidity for local development mandates.
- Venture Capital:Early-stage equity in technology-enabled impact enterprises with high failure rates and outsized return potential. TPG's Rise Fund methodology quantifies social and environmental outcomes alongside financial returns in this segment.
- Private Equity:Growth and buyout strategies with operational value creation through ESG integration. SFDR Article 9 compliance now serves as non-negotiable entry criteria for Dutch and Danish pension system allocations.
- Hedge Funds:Liquid strategies with impact screens and shareholder engagement tactics.
- Community Investments:Place-based capital with below-market return expectations and deep local stakeholder integration.
Private equity dominates fee generation. Venture capital is where manager differentiation concentrates.
Investor Type:
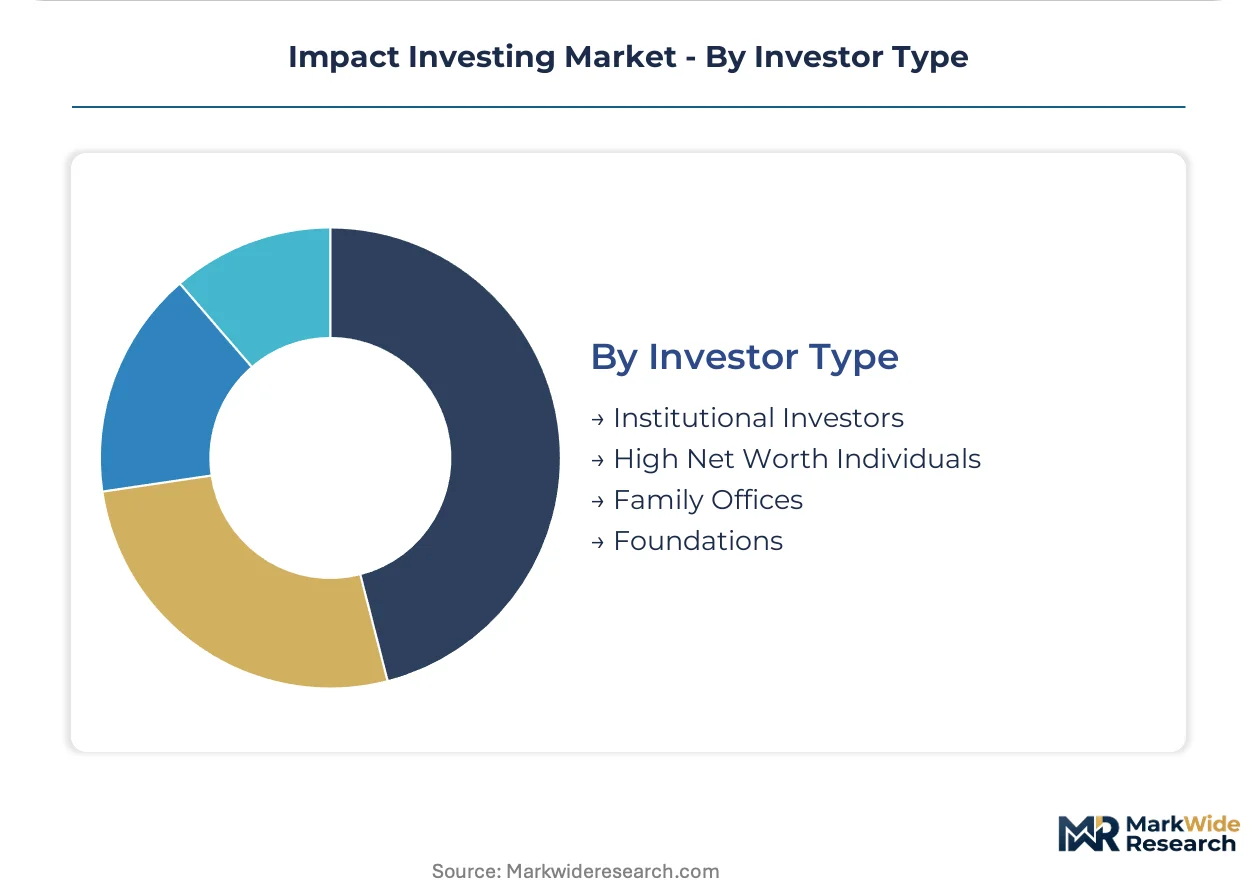
Institutional capital moves through consultant-advised fund commitments with strict SFDR and SEC climate disclosure compliance, while family offices execute direct deals with flexible mandate structures.
- Institutional Investors:Pension funds and insurance companies with fiduciary duty constraints and quarterly reporting obligations. BlackRock's Aladdin platform integrates impact metrics across fixed-income and alternative portfolios for this channel.
- Family Offices:Single and multi-family entities with generational wealth transfer objectives and patient capital capacity. Natural capital accounting and biodiversity metrics open uncrowded thematic exposure beyond carbon-centric strategies here.
- High Net Worth Individuals:Retail-advised allocations through donor-advised funds and impact brokerage platforms.
- Foundations:Mission-related investing with program-related investment carve-outs and public benefit corporation structures.
Institutional investors dominate capital volume. Family offices are where thematic innovation concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal taxonomy requirements and IRA clean energy tax credits are redirecting institutional capital toward verifiable green assets across multiple jurisdictions. Sovereign wealth funds from Norway to Singapore now mandate climate-aligned portfolio construction. Regulatory fragmentation between EU SFDR disclosure rules and SEC climate proposals shapes cross-border fund distribution feasibility.
United States
IRA clean energy tax credits attract pension fund allocations into verified green infrastructure assets. SEC climate disclosure proposals reshape product marketing boundaries for fund managers operating across state lines. New York and California house the densest concentrations of impact fund managers integrating IRIS+ metrics into portfolio management systems.
Germany
Institutional capital from Dutch and Danish pension systems flows through Frankfurt-based fund platforms demanding SFDR Article 9 compliance. The country's national financial regulator enforces sustainability disclosure standards that compress fund distribution timelines. Munich and Hamburg anchor renewable energy fund administration clusters serving Nordic institutional limited partners.
United Kingdom
Family offices in London execute direct deals with flexible mandate structures around natural capital accounting. The Financial Conduct Authority implements disclosure requirements that align with EU Green Deal taxonomy thresholds. The City of London concentrates hedge fund managers deploying liquid strategies with impact screens and shareholder engagement tactics.
India
Production-linked incentive schemes for solar module manufacturing create domestic impact investment entry points with tariff-protected offtake certainty. The Securities and Exchange Board of India governs alternative investment fund structures channeling patient capital into financial inclusion. Mumbai and Bangalore host regional fund managers deploying capital into healthcare access and education enterprises.
Singapore
Sovereign wealth vehicles redirect capital flows into renewable energy assets as inflation-linked yield vehicles with measurable carbon displacement metrics. The Monetary Authority of Singapore supervises fund structures accommodating blended finance with development finance institution first-loss tranches. The city-state serves as Asia-Pacific distribution hub for infrastructure-focused mandates targeting grid decarbonization.
Impact Investing Market Competitive Environment
Listed leaders compete with private specialists across platform scale and outcome measurement depth. BlackRock leverages listed asset scale to integrate impact metrics across fixed-income and alternative portfolios through technology infrastructure. Private specialists including TPG and Brookfield Asset Management compete through proprietary outcome quantification methodologies. Strategic archetypes separate technology-integrated platforms, methodology-driven specialists, and real asset anchors. Competitive moves concentrate on M&A for measurement capabilities and strategic partnerships for regulatory compliance across jurisdictions.
Within the methodology-driven specialist tier, TPG and LeapFrog Investments exemplify firms quantifying social and environmental outcomes alongside financial returns. Brookfield Asset Management anchors the real asset archetype through renewable infrastructure and sustainable real estate allocations. BlackRock occupies a position representing technology-integrated scale platforms serving institutional capital with fiduciary duty constraints.
| Leading Market Players |
|---|
| Brookfield Asset Management |
| TPG |
| EQT |
| Meridiam |
| Goldman Sachs Asset Management |
| BlackRock |
| Actis |
| Enterprise Community Partners |
| LeapFrog Investments |
| Others |
Value Chain & Pricing Dynamics
EU Green Deal taxonomy certification gates both fund manager qualification and fee differentiation simultaneously, compressing pricing power for non-compliant entrants while elevating verified impact strategies. SFDR Article 9 compliance now separates premium fee tiers from standard mandates as institutional limited partners treat disclosure rigor as non-negotiable allocation criteria.
Pricing Analysis
Certification level (SFDR Article 9 vs Article 8 vs non-compliant) creates the primary spread between fee tiers, with verified impact funds commanding 50-150 basis point premiums over marketing-driven entrants. Pricing stratifies across premium, standard, and economy tiers based on outcome measurement depth, with continuous IRIS+ monitoring justifying elevated management fees. Cost compression in standard-tier mandates is intensifying because verification cost escalation consumes 80-150 basis points from operating budgets. Pension fund procurement teams exhibit lowest price sensitivity, while donor-advised fund retail channels demand fee compression.
Supply Chain Analysis
Strategic stockpiling of impact measurement talent and regulatory compliance infrastructure dominates inventory strategy as fund managers race to embed IRIS+ and SDG alignment into legacy systems. Geographic supply concentration centers on the United States for technology-integrated platforms, the United Kingdom for natural capital accounting specialists, and Singapore for blended finance structuring. Raw material dependencies include carbon accounting software, blockchain-enabled verification infrastructure, and development finance institution first-loss guarantees. Single-source vulnerability runs through third-party impact auditing providers. Distribution runs through consultant-advised institutional fund commitments and direct family office relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market rewards scarce capability in quantitative finance training combined with sector-specific outcome evaluation expertise, creating acquisition premiums for teams bridging climate metrics and healthcare access measurement. Firms lacking this hybrid skill base face compression toward commodity fee structures.
For Market Incumbents: Compound differentiation through proprietary outcome quantification methodologies that resist replication, while securing vertical integration into blockchain-enabled verification infrastructure before regulatory mandates harden. Threat substitution from technology-native platforms elevates urgency. Certification investment in CSRD compliance capabilities serves as the priority lever for European distribution retention. For New Entrants and Emerging Players: Anchor in sustainable agriculture and natural capital accounting where biodiversity metrics remain uncrowded versus carbon-centric strategies dominated by incumbents. Sub-Saharan Africa healthcare access and Indian PLI-aligned solar manufacturing represent the most penetrable geographies. Go-to-market execution through development finance institution co-investment structures de-risks frontier market entry. For Investors and Strategic Acquirers: SFDR Article 9 expansion reshapes the acquisition landscape toward methodology-driven specialists with proven IRIS+ integration and proprietary impact databases. Long-term viability centers on firms with patient capital structures matching seven-to-ten-year healthcare and education lock-ups. The signal to watch is pension fund procurement team adoption of continuous monitoring contracts over annual attestation cycles.| Strategic Initiative | Industry Significance |
|---|---|
| IRIS+ Integration Investment | Embedding harmonized indicators into Aladdin-style platforms separates scalable managers from compliance-lagged competitors. |
| Blended Finance Structuring | Development finance institution first-loss tranches unlock commercial capital deployment into frontier market microfinance. |
| Blockchain Verification Deployment | Smart contract-based impact attestation satisfies Dutch and Danish pension system transparency mandates. |
| Natural Capital Capability Buildout | Biodiversity and water-stress metrics open uncrowded thematic exposure beyond saturated carbon strategies. |
| SFDR Article 9 Certification | Compliance serves as non-negotiable entry criteria for Nordic institutional limited partner allocations. |
Study Parameters
A spread of perspectives from impact fund managers, institutional limited partners, development finance institution officers, and regulatory compliance consultants converged on the working assumptions shaping this analysis. Primary interviews with portfolio construction heads at pension funds and sovereign wealth vehicles combined with secondary validation from SEC climate disclosure filings, EU SFDR regulatory texts, GIIN annual reports, and IRIS+ indicator documentation. Bottom-up fund flow analysis triangulated against top-down regulatory impact modeling.
Segmentation dimensions modeled span investment strategy, sector focus, fund type, and investor type across the analysis window, with geographic regulatory cluster as an additional impact investing-specific dimension. CAGRs were derived through scenario-weighted growth trajectory analysis incorporating policy incentive elasticity and capital deployment velocity. Forecast inputs included IRA tax credit utilization rates and EU Green Deal taxonomy alignment thresholds.
Decision-makers should treat outputs as directional under assumptions of sustained regulatory enforcement and institutional mandate expansion; material deviation would warrant model refresh. Revision becomes warranted when regulatory fragmentation between EU and SEC standards crosses thresholds that fragment cross-border fund distribution feasibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
Crowdfunding Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
United States Venture Capital Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Micro VC Funds Market
Venture Capital
North America Venture Capital Market
Venture Capital
Europe Venture Capital Market
Venture Capital
Business Incubator Market
Venture Capital
Angel Funds Market
Venture Capital
Venture Capital Investment Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
Asia-Pacific Venture Capital Investment Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
US Venture Capital Investment Market
Venture Capital
Asia Pacific Venture Capital Market