
 Equity Crowdfunding Market | 2026-2036
Equity Crowdfunding Market Size, Share, and Industry Trends Forecast 2026-2036
Equity Crowdfunding Market Insights
A capital-intensity divergence between venture-backed platform incumbents and lean software-native entrants is redrawing competitive boundaries in equity crowdfunding. StartEngine leverages its broker-dealer infrastructure to sustain compliance advantages across multiple U.S. states. Republic differentiates through thematic investment verticals and curated startup pipelines. Wefunder occupies the regulatory frontier with its history of SEC no-action letter navigation.
Equity crowdfunding denotes the sale of private company securities to a dispersed pool of investors through internet-mediated platforms, typically operating under securities law exemptions that cap individual investment amounts and mandate disclosure thresholds. The mechanism pools capital from non-institutional sources into registered or exempt offerings, enabling early-stage ventures to bypass traditional venture capital gatekeeping. Seed-stage deployment through the Investment Stage segment leads volume flows, while the Equity-Based Platform Type category captures the dominant share of fee generation. The Funding Model dimension shows All-Or-None structures maturing as the baseline expectation, with Syndicate Funding variants representing the fastest-growing configuration as lead investors aggregate follow-on capital.
SEC Regulation Crowdfunding and FINRA oversight shape platform registration, disclosure cadence, and investor protection protocols in the United States. The JOBS Act amendments and state-level blue sky harmonization efforts determine market access breadth for both issuers and retail participants. Stakeholders must monitor pending SEC rulemakings on accredited investor definition expansion and the interplay between federal preemption and state enforcement discretion.
Market Dynamics
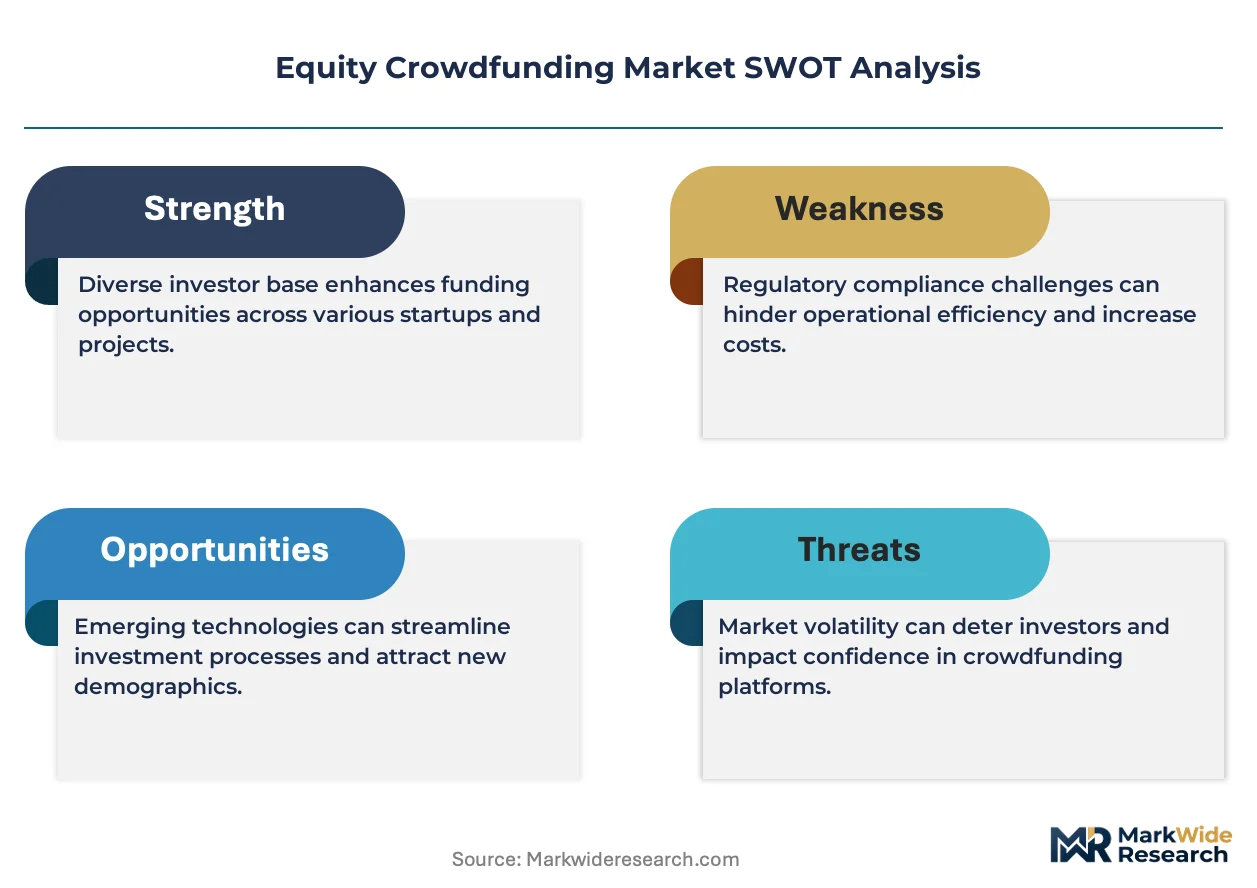
Platform compliance costs are compressing margins for smaller operators while broker-dealer licensing advantages concentrate deal flow among infrastructure-heavy incumbents. This regulatory capital barrier is forcing lean entrants toward white-label software models or niche thematic verticals.
Growth Catalysts
- SEC Regulation Crowdfunding amendments:Expanded annual offering limits and streamlined disclosure requirements reduce issuer friction, accelerating platform onboarding velocity for seed-stage ventures.
- Retail investor account proliferation:Brokerage API integrations enable seamless crowdfunding wallet funding from mainstream trading accounts, collapsing activation barriers for non-accredited participants.
- Revenue-based financing hybridization:Platforms are blending equity with revenue-share instruments, attracting SaaS and D2C founders seeking non-dilutive capital structures.
Market Restraints
- State-level blue sky compliance:Non-preempted securities filings in jurisdictions like New York and California impose redundant legal review costs on multi-state offerings.
- Due diligence capacity constraints:Platform analyst teams face throughput ceilings as issuer volume scales faster than specialized fintech underwriting talent pools.
- Secondary market illiquidity:Absence of regulated resale venues locks retail capital for 12-month holding periods, depressing repeat participation rates.
Strategic Opportunities
- Community development financial institutions:CDFI certification unlocks federal tax credit allocations for platforms channeling capital into underserved census tracts.
- Qualified Opportunity Zone alignment:Issuer location targeting in designated QOZs attracts tax-advantaged investor segments seeking capital gains deferral.
- Tokenized equity infrastructure:Blockchain-native cap table management converges with SEC-compliant transfer agents, enabling automated dividend distribution and proxy voting.
Industry Challenges
- FINRA membership examination backlogs:New platform applicants face 18-24 month queue delays for broker-dealer approval, freezing market entry timelines.
- Form C disclosure litigation exposure:Issuer misrepresentation claims trigger platform intermediary liability, necessitating enhanced E&O coverage and escrow holdback structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Equity Crowdfunding Market |
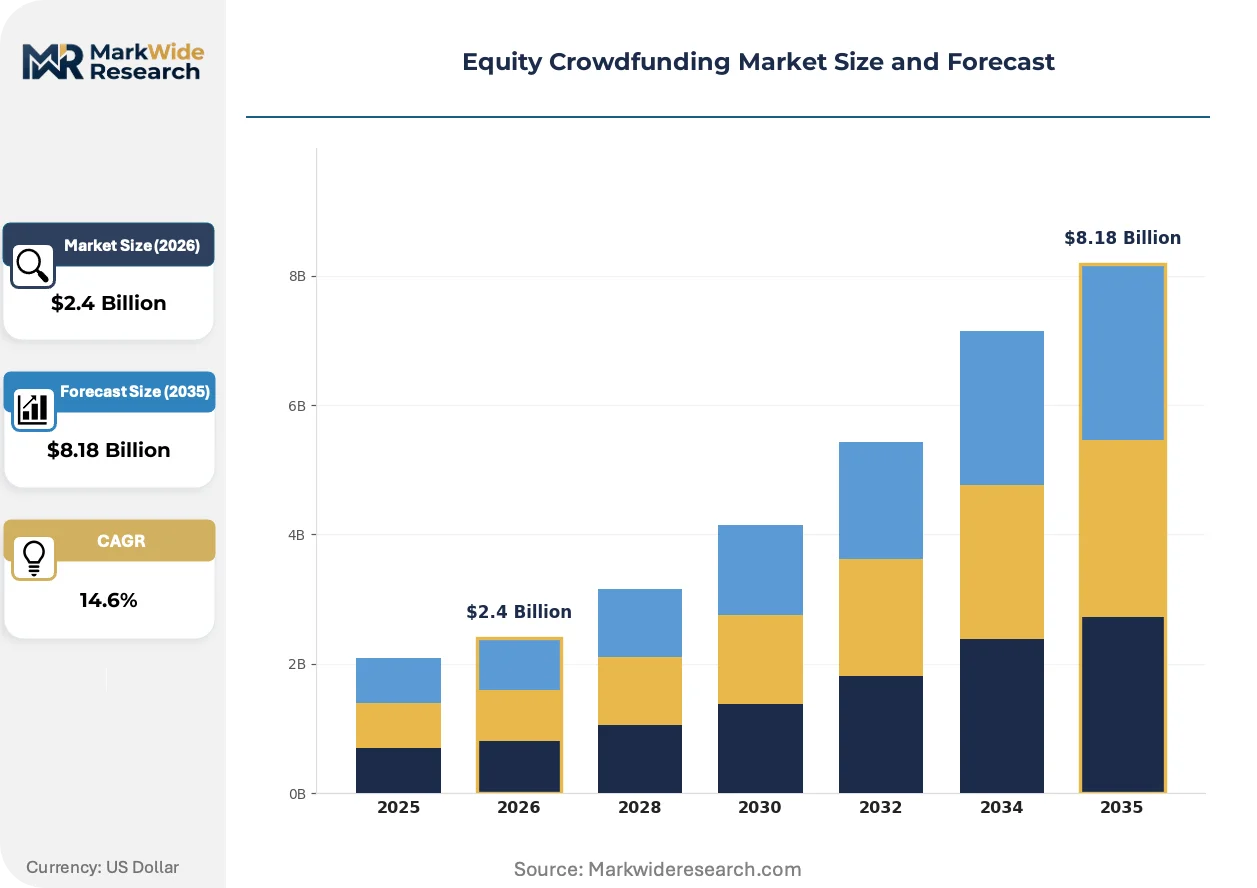
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $8.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed, Early Growth, Expansion, Pre-IPO, Buyout Investor Type: Angel Investors, Venture Capitalists, Private Equity Firms, High Net Worth Individuals, Family Offices Funding Model: All-Or-None, Keep-It-All, Mini-Max, Target Funding, Syndicate Funding Platform Type: Reward-Based, Debt-Based, Donation-Based, Equity-Based, Royalty-Based |
| Companies Covered | Wefunder, StartEngine, Republic, SeedInvest, Netcapital, Equifund, Microventures, OurCrowd, Honeycomb, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Equity Crowdfunding Market Trends and Innovations
Automated investment tooling and alternative asset integration are compressing the traditional boundary between crowdfunding platforms and full-service wealth management. These shifts are redefining investor acquisition economics and retention mechanics.
Blockchain-based cap table infrastructure is bifurcating platform architectures into compliance-native and crypto-native stacks. Early-stage issuers with distributed team structures are adopting smart contract-enabled equity management for automated vesting schedules and waterfall calculations. This technology is compressing administrative overhead for platforms serving high-velocity startup portfolios.
FINRA's updated membership application processing guidelines are accelerating broker-dealer approvals for platforms with established compliance automation. The regulatory consequence is a widening capability gap between licensed operators and registration-pending entrants. Seed-stage vertical platforms are responding by pursuing strategic partnerships with existing broker-dealers rather than building captive infrastructure.
Retail allocation behavior is fragmenting across thematic investment preferences rather than geographic proximity to issuers. Sustainability-focused and underrepresented-founder verticals are displacing generalist startup browsing as the primary discovery pathway. This pattern is most pronounced among Millennial and Gen Z account holders on U.S.-domiciled platforms with curated deal filtering tools.
Equity Crowdfunding Market Segmentation
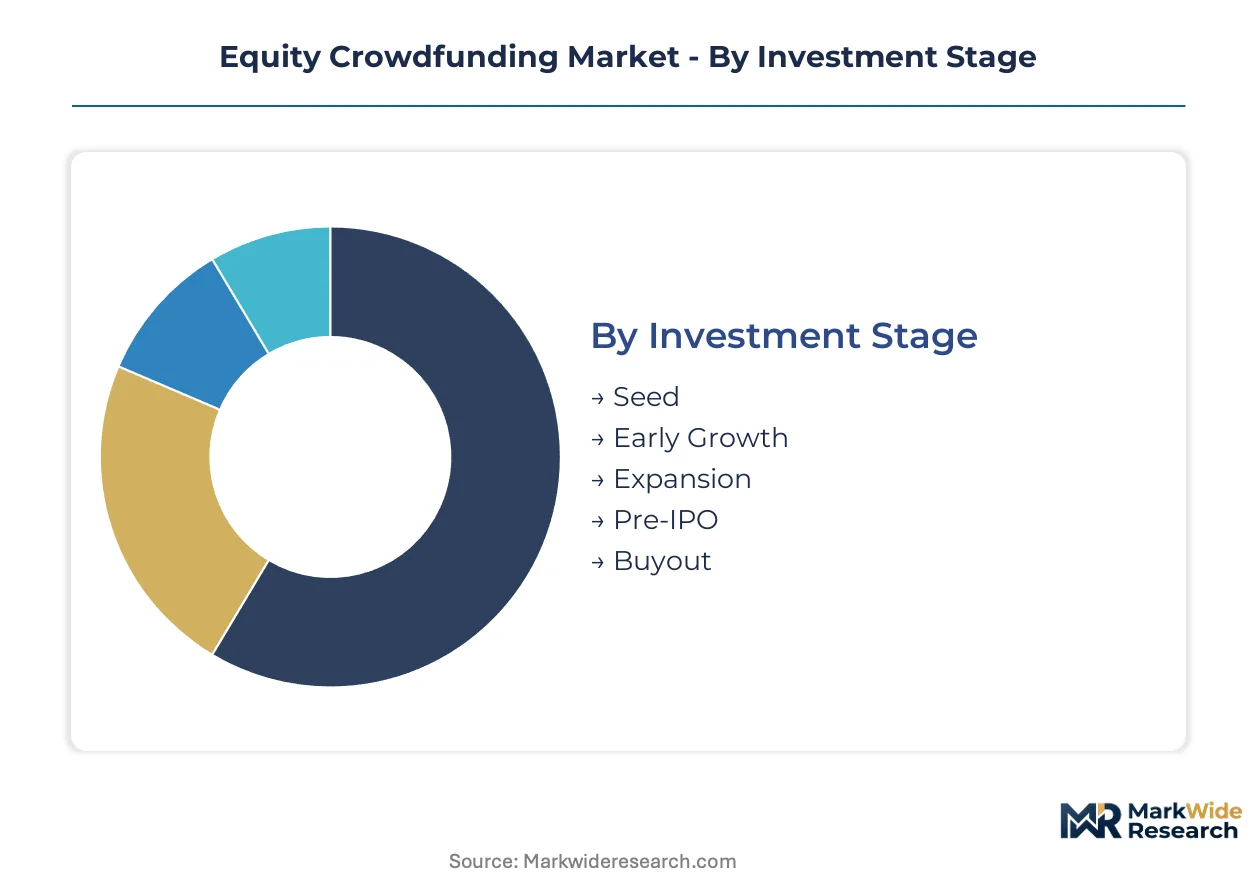
Equity crowdfunding segmentation reveals how capital formation mechanics diverge across risk tolerances, regulatory frameworks, and liquidity horizons. Platform operators configure compliance infrastructure and fee structures around these dimensional splits.
Investment Stage:
Pre-IPO and buyout segments face acute substitution pressure from traditional private placement channels, while seed-stage crowdfunding maintains structural cost advantages over venture capital gatekeeping.
- Seed:Initial capital raises for pre-revenue ventures under Regulation Crowdfunding exemption limits. Demand concentrates among U.S. technology founders seeking non-dilutive alternatives to angel syndicate terms, driven by streamlined Form C disclosure requirements.
- Early Growth:Post-MVP deployment for revenue-generating startups scaling customer acquisition. U.S. SaaS and D2C operators dominate this tier, attracted by revenue-based financing hybrid structures that preserve founder equity.
- Expansion:Growth-stage capital for market penetration and operational scaling.
- Pre-IPO:Late-stage private financing before public offering registration.
- Buyout:Acquisition financing for existing business ownership transitions.
Seed retains volume leadership; Early Growth holds the steepest expansion curve.
Investor Type:
Cost-tier stratification separates accredited participants with bespoke deal access from retail investors capped by annual investment limits under SEC frameworks.
- Angel Investors:Individual accredited backers deploying personal capital into curated platform offerings. U.S. metropolitan technology corridors anchor participation, constrained by holding period illiquidity and lack of secondary exit venues.
- Venture Capitalists:Institutional funds using crowdfunding for downstream deal flow intelligence. Concentrated in U.S. coastal innovation clusters, driven by regulatory data rooms enabling pre-emptive rights negotiation.
- Private Equity Firms:Buyout specialists seeking platform-sourced proprietary deal flow.
- High Net Worth Individuals:Retail participants above income thresholds accessing expanded allocation limits.
- Family Offices:Multi-generational wealth vehicles diversifying into direct private company exposure.
Angel Investors dominate platform registration counts; Venture Capitalists command the largest average check sizes.
Funding Model:
Application-driven selection favors All-Or-None structures for milestone-credible issuers while Keep-It-All accommodates working capital flexibility for operational businesses.
- All-Or-None:Capital returned to investors if minimum threshold unmet. U.S. real estate and hardware ventures prefer this structure, motivated by SEC safe harbor provisions that reduce fraud litigation exposure.
- Syndicate Funding:Lead investors aggregate follow-on capital through platform-mediated SPVs. Concentrated among U.S. fintech and climate technology verticals, propelled by carried interest mechanics that align lead and LP incentives.
- Keep-It-All:Issuers retain all committed capital regardless of target achievement.
- Mini-Max:Flexible thresholds with tiered disclosure obligations.
- Target Funding:Single fixed objective with standard escrow release protocols.
All-Or-None structures anchor platform transaction volume; Syndicate Funding is gaining share fastest among institutional-facing operators.
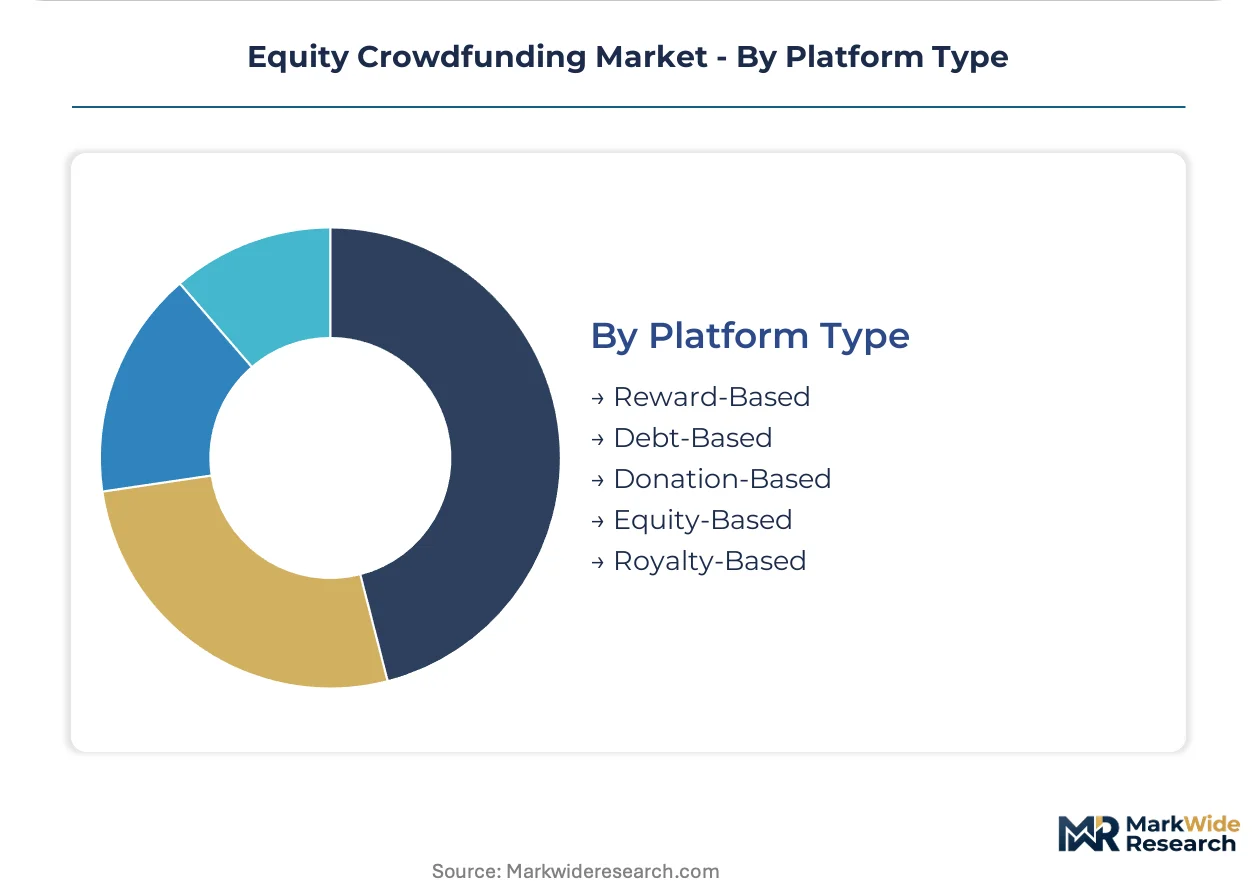
Platform Type:
Margin concentration in Equity-Based platforms reflects fee premiums on securities transactions versus non-financial reward or donation alternatives.
- Equity-Based:SEC-registered intermediaries facilitating security issuance under Regulation Crowdfunding. U.S. broker-dealer licensing requirements create regulatory moats that compress competitor entry economics.
- Debt-Based:Revenue-share and loan instrument platforms serving cash-flow-positive issuers. U.S. small business operators drive adoption, drawn to non-dilutive capital structures and fixed repayment schedules.
- Reward-Based:Pre-sale product crowdfunding without securities component.
- Donation-Based:Non-financial contribution platforms for social impact projects.
- Royalty-Based:Intellectual property and revenue participation agreements.
Equity-Based platforms generate the dominant fee share; Debt-Based configurations are expanding most quickly among revenue-generating issuer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The equity crowdfunding sector exhibits pronounced capital flow asymmetry, with the United States generating substantial platform fee exports while European and Asian markets remain net importers of regulatory frameworks and compliance technology.
United States
Retail investor account growth on SEC-registered platforms drives transaction volume expansion. The JOBS Act amendments and Regulation Crowdfunding offering limit increases reduce issuer onboarding friction. Silicon Valley and New York City anchor deal flow concentration, with Austin and Miami emerging as secondary issuance hubs for technology and real estate verticals.
United Kingdom
Seed-stage technology founders favor platform-mediated capital over traditional angel syndicate structures. The Financial Conduct Authority's crowdfunding regulations mandate appropriateness tests and disclosure standards that elevate compliance costs. London's fintech corridor hosts the dominant share of platform headquarters, while Manchester and Edinburgh sustain regional issuer pipelines.
Germany
SME manufacturers utilize equity crowdfunding for Industry 4.0 equipment financing. BaFin's crowd investing regulations impose prospectus requirements above threshold limits, compressing small-issuer participation. Berlin and Munich concentrate platform operations, with Stuttgart's automotive supplier ecosystem generating specialized industrial deal flow.
Australia
ASIC's crowd-sourced funding framework enables proprietary limited companies to access retail capital pools. Mining technology and agricultural technology verticals dominate issuer profiles. Sydney and Melbourne host platform infrastructure, with Perth sustaining resources-focused issuance activity.
Canada
Provincial securities regulators coordinate through the Canadian Securities Administrators for harmonized crowdfunding exemptions. Clean technology and life science startups leverage platform access as venture capital availability tightens. Toronto anchors platform concentration, with Vancouver and Montreal supporting sector-specific issuer verticals.
Equity Crowdfunding Market Competitive Landscape
Concentration sits with broker-dealer licensed platforms that have absorbed multi-year FINRA examination timelines. Market structure exhibits tiered segmentation between infrastructure-heavy incumbents with captive compliance technology and lean software-native entrants reliant on white-label regulatory partnerships. Strategic archetypes include vertically integrated broker-dealer operators, thematic vertical specialists, and regulatory frontier navigators with SEC no-action letter precedents. Dominant competitive moves encompass strategic partnerships with registered broker-dealers to bypass licensing queues and portfolio diversification into revenue-based financing instruments.
Within the broker-dealer tier, StartEngine and Republic occupy positions as archetypal infrastructure-heavy operators, with Wefunder exemplifying the regulatory frontier specialist model. These entities anchor the competitive landscape through divergent capital intensity strategies and compliance automation capabilities.
| Leading Market Players |
|---|
| Wefunder |
| StartEngine |
| Republic |
| SeedInvest |
| Netcapital |
| Equifund |
| Microventures |
| OurCrowd |
| Honeycomb |
| Others |
Pricing and Supply Chain Analysis
All-Or-None escrow structures lock in committed capital visibility for U.S. platforms while compressing fee transparency for retail participants navigating SEC disclosure thresholds. This contract pattern ties issuer onboarding costs to broker-dealer licensing overhead, amplifying margin pressure for infrastructure-light entrants competing against FINRA-registered incumbents.
Pricing Analysis
Platform operators anchor pricing around success-based fee tiers tied to capital raised under Regulation Crowdfunding exemptions. Fee differentiation hinges on broker-dealer infrastructure ownership versus white-label regulatory partnerships, with licensed operators commanding premium placement rates. Cost compression in the seed-stage segment intensifies as lean software entrants undercut established players on onboarding fees. Retail investors exhibit highest price sensitivity to carry and administrative charges, while institutional co-investors prioritize deal flow quality over fee minimization.
Supply Chain Analysis
Strategic stockpiling of compliance talent dominates platform operations as FINRA examination backlogs extend broker-dealer licensing timelines. Supply concentration rests on the United States for regulatory technology infrastructure, the United Kingdom for alternative investment fund administration, and India for back-office analytics support. Critical dependencies include proprietary cap table software, KYC/AML verification APIs, and escrow banking partnerships. Single-source vulnerability concentrates in FINRA membership processing queues. Distribution runs through direct digital onboarding supplemented by registered investment advisor referral networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equity crowdfunding platforms increasingly monetize through recurring compliance automation subscriptions rather than transactional success fees alone. This service-attach layer expands faster than core securities placement revenue as issuers seek ongoing cap table management and investor relations tooling.
For Market Incumbents: Secure exclusive data room integrations with venture capital firms to preempt downstream acquisition intelligence leakage to competing platforms. Deepen broker-dealer infrastructure moats through proprietary Form C automation that accelerates disclosure cadence beyond white-label regulatory partnerships. Threat substitution emerges from blockchain-native cap table providers encroaching on compliance-native platform architectures. For New Entrants and Emerging Players: Differentiate on thematic vertical specialization targeting underrepresented-founder pipelines where generalist platforms lack curation depth. White-space penetration concentrates in revenue-based financing hybrids for SaaS operators seeking non-dilutive alternatives to equity dilution. Geographic entry prioritizes secondary U.S. innovation corridors—Austin, Miami, Denver—where broker-dealer saturation lags coastal hubs. Go-to-market leverage rests on strategic partnerships with existing FINRA-registered intermediaries to bypass 18-24 month licensing queues. For Investors and Strategic Acquirers: Thematic vertical platforms with captive issuer pipelines in climate technology and healthcare innovation represent the most defensible acquisition archetype for long-term positioning. Viability across a decade horizon hinges on regulatory technology ownership that withstands SEC exemption framework evolution. Monitor FINRA membership application processing velocity as the critical inflection signal—acceleration indicates regulatory capacity expansion that would erode incumbent licensing scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Broker-Dealer Licensing Acceleration | FINRA membership compression unlocks multi-state offering capacity before competitors clear examination queues. |
| Thematic Vertical Platform Launch | Curated deal flow in climate technology attracts ESG-mandated capital pools underserved by generalist platforms. |
| Revenue-Based Financing Hybridization | Non-dilutive instrument expansion captures SaaS founders avoiding traditional equity crowdfunding dilution terms. |
| Blockchain Cap Table Integration | Smart contract automation reduces administrative overhead for platforms serving high-velocity startup portfolios. |
| Strategic Broker-Dealer Partnership | White-label regulatory access enables market entry without absorbing multi-year FINRA examination timelines. |
Research Methodology
Initial hypotheses were tested against primary input from platform chief compliance officers, securities attorneys specializing in Regulation Crowdfunding, FINRA examination consultants, and seed-stage startup founders actively raising capital. These perspectives were refined through secondary validation against SEC no-action letter databases, Form C disclosure filings, and broker-dealer registration tracking systems. Bottom-up transaction volume estimates from platform fee disclosures triangulated with top-down market sizing derived from JOBS Act regulatory impact assessments.
Variance decomposition across the projection horizon isolates growth contributions from retail account proliferation, issuer onboarding velocity, and fee structure evolution. Segmentation dimensions modeled include investment stage, investor type classification, funding model configuration, and platform regulatory architecture. CAGRs were derived through logarithmic transformation of value progression across the analysis window. Industry-specific forecast inputs incorporate FINRA membership approval rate assumptions and state-level blue sky harmonization progression.
Forecasts assume regulatory continuity in SEC Regulation Crowdfunding frameworks and FINRA oversight protocols; material policy shifts around accredited investor definition expansion or federal preemption scope would require re-modeling. Secondary market illiquidity duration and platform intermediary liability exposure represent specific risk factors that could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Asia Pacific Venture Capital Market
Venture Capital
Angel Funds Market
Venture Capital
Europe Venture Capital Market
Venture Capital
Crowdfunding Market
Venture Capital
Micro VC Funds Market
Venture Capital
Impact Investing Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
Micro Venture Capital VC Funds Market
Venture Capital
North America Venture Capital Market
Venture Capital
Asia-Pacific Venture Capital Investment Market
Venture Capital
United States Venture Capital Market
Venture Capital
Venture Capital Investment Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
Business Incubator Market
Venture Capital
US Venture Capital Investment Market