
 Business Incubator Market | 2026-2036
Business Incubator Market Size, Share, and Industry Trends Forecast 2026-2036
Business Incubator Market Analytics
Market Context
North America is rewriting competitive dynamics in business incubation through expanded public-private program capacity. Y Combinator leverages its alumni network density to sustain deal-flow advantages across successive venture cycles. Techstars anchors multi-city programming through standardized curriculum and corporate partnership templates. 500 Global competes via emerging-market portfolio exposure that differentiates its risk-return profile from Silicon Valley-centric rivals.
Technical Definition and Segment Structure
A business incubator constitutes an organized program delivering physical infrastructure, advisory services, capital access, and network integration to early-stage ventures with limited operational history, typically structured around cohort-based progression metrics and milestone-driven funding gates. Physical facilities retain the largest revenue share among service types, though virtual support offerings are expanding fastest as distributed-team norms reduce geographic dependency for program participation. Technology dominates industry vertical allocation, while healthcare incubation commands premium fee structures due to specialized regulatory navigation requirements and longer capital-formation timelines. Accelerator models under the support model dimension concentrate the highest valuation outcomes per cohort slot, whereas co-working spaces occupy the volume-driven, margin-compressed tier of the market.
Regulatory Environment and Outlook
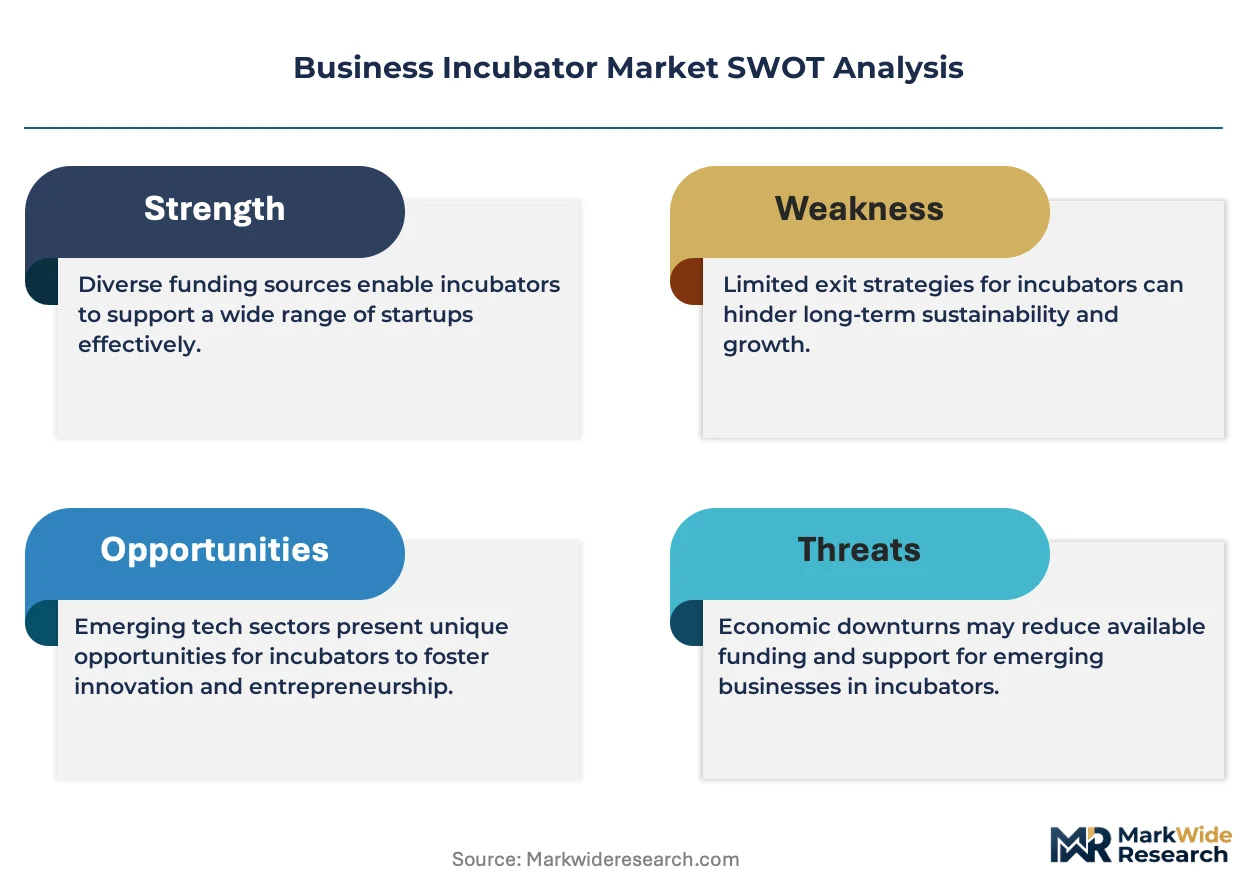
The Small Business Administration and state-level economic development authorities in the United States shape incubator eligibility through grant qualification criteria and tax-incentive portability rules, while the SEC's evolving accredited-investor definitions directly affect funding-assistance program design. The EU AI Act and GDPR compliance training modules are becoming mandatory add-ons for European programs serving data-centric startups, altering curriculum resource allocation. Stakeholders must monitor how national innovation agency budget reallocations between physical and virtual infrastructure will reshape program economics and competitive positioning.
Market Dynamics
Federal small-business initiatives and venture-density clusters in Austin, Boston, and San Francisco are compressing program design cycles and forcing incumbent operators to recalibrate cohort selection criteria around revenue-ready metrics rather than pre-seed concepts.
Growth Catalysts
- SEC Accredited-Investor Expansion:Relaxed wealth thresholds under SEC amendments broaden the pool of program-eligible startups seeking funding-assistance tracks, particularly in fintech and climate-tech verticals.
- Technology Startup Density:Artificial intelligence and machine learning ventures now dominate application pipelines, pulling curriculum resources toward GPU infrastructure access and MLOps training modules.
- Hybrid Infrastructure Mandates:National innovation agency funding rules now require physical-digital program blends, accelerating virtual platform investments among legacy facility-dependent operators.
Market Restraints
- Real Estate Cost Escalation:Prime facility locations in venture-dense metros absorb disproportionate operating budgets, compressing per-cohort margins below sustainable thresholds for non-endowed programs.
- Specialized Talent Scarcity:Regulatory navigation expertise for healthcare and fintech verticals concentrates among a narrow advisor pool, creating bidding wars for qualified program staff.
- Program Saturation:Proliferation of unaccredited operators in major metros dilutes brand differentiation and complicates startup selection decisions.
Strategic Opportunities
- Second-Tier Metro Expansion:Cities including Raleigh, Nashville, and Salt Lake City offer lower facility costs and under-tapped university research pipelines for specialized deep-tech programming.
- Corporate Venture Integration:Fortune 500 R&D budgets seek external innovation pipelines, creating white-label incubator opportunities with guaranteed offtake mechanisms.
- IRA Climate-Tech Incentives:Inflation Reduction Act tax credits and loan guarantees for clean-energy ventures expand addressable market for sector-specific program tracks.
Industry Challenges
- Outcome Measurement Standardization:Absence of unified cohort-success metrics complicates public-funding justification and alumni-network valuation.
- Cross-Border Regulatory Fragmentation:Startups with international expansion plans face conflicting data-localization and securities-registration requirements across state and federal jurisdictions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Business Incubator Market |
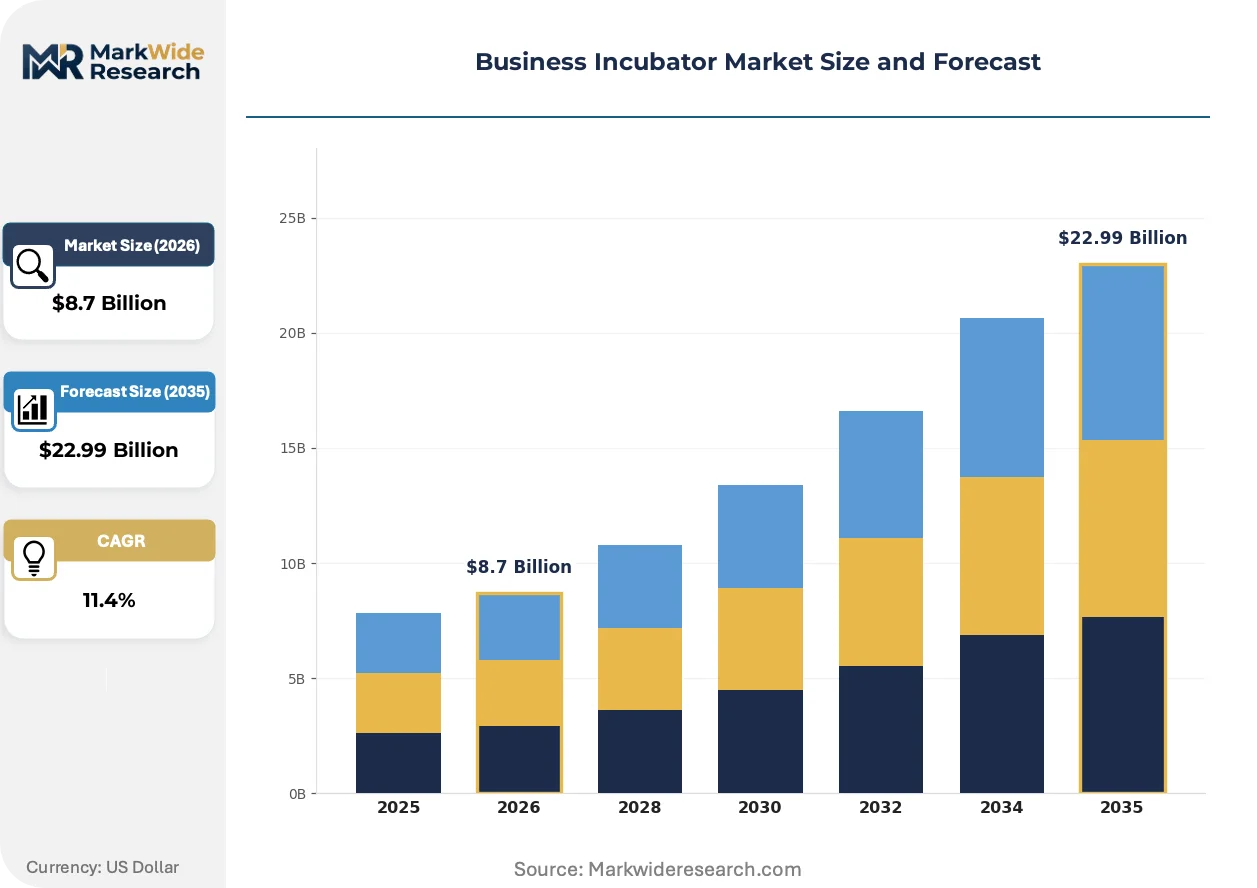
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Physical Facilities, Virtual Support, Mentorship, Funding Assistance Industry Vertical: Technology, Healthcare, Education, Manufacturing Target Client Type: Startups, SMEs, Entrepreneurs, Nonprofits Support Model: Accelerator, Incubator, Co-working Space, Hackathon |
| Companies Covered | Seedcamp, Idealab, Y Combinator, Betaworks, Capital Factory, Techstars, Station F, DMZ, 500 Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Business Incubator Market Evolving Landscape
Program architecture is pivoting from standardized curriculum delivery toward modular, milestone-driven support stacks that adapt to venture stage rather than forcing uniform progression timelines.
Artificial intelligence tooling is hybridizing traditional advisory functions by automating pitch-deck analysis, financial-model stress-testing, and investor-match algorithms. Early-stage ventures in SaaS and biotech verticals are adopting these platforms fastest, compressing the advisor-to-founder ratio requirements that previously constrained cohort scaling economics.
The SEC's evolving accredited-investor definitions and state-level economic development authority grant criteria are rewriting program eligibility frameworks. Operators must now integrate compliance training modules directly into onboarding sequences, particularly affecting fintech and digital-asset startup tracks where securities-law exposure is highest.
Startup selection committees are weighting revenue-generating capacity over purely technical innovation, reflecting LP pressure for faster path-to-liquidity timelines. This behavioral shift is most visible in SaaS and climate-tech verticals, where annual recurring revenue thresholds now gate entry to top-tier accelerator slots previously reserved for pre-revenue technical teams.
Business Incubator Market Segmentation
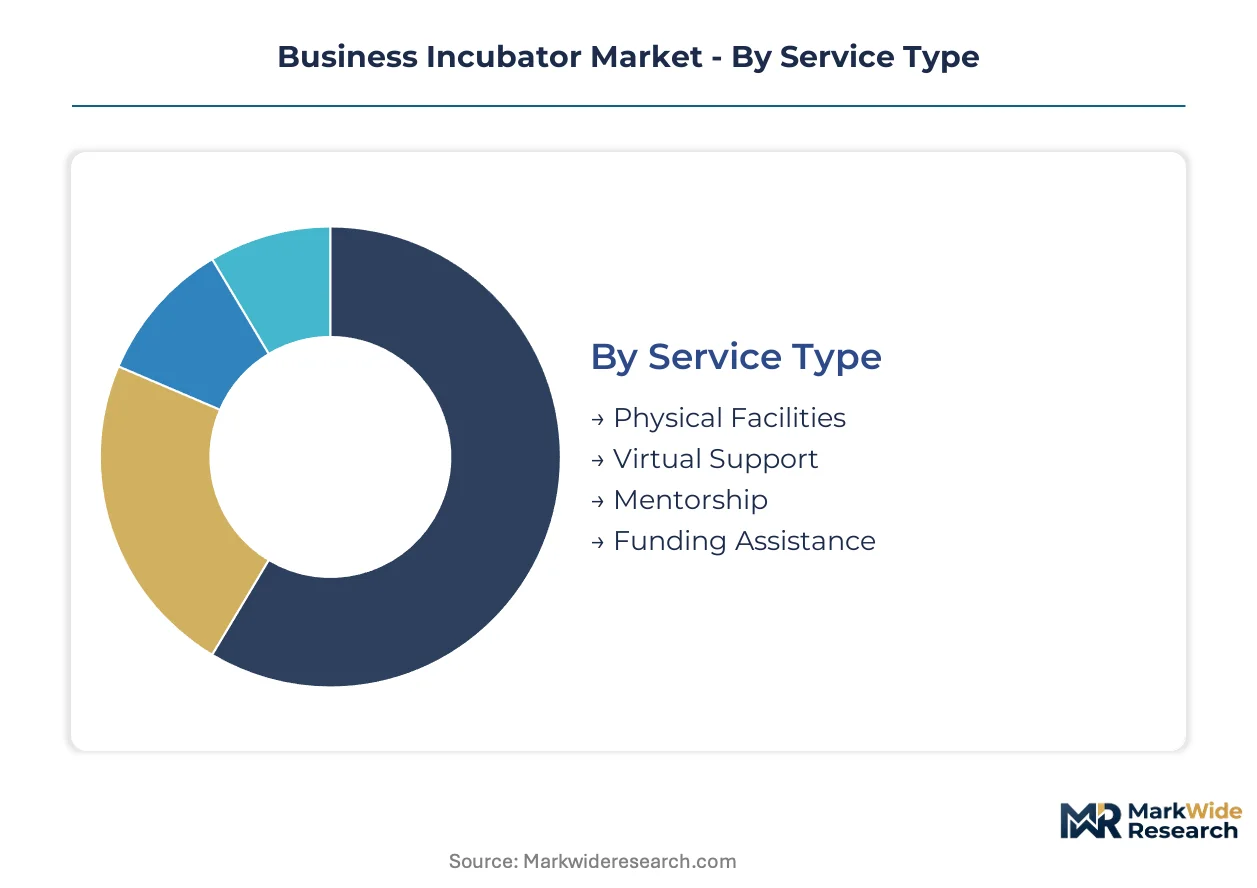
Program operators configure incubator architecture around distinct service delivery modes, vertical specialization depth, and client maturity profiles. Segmentation discipline separates facility-dependent legacy models from capital-light virtual platforms reshaping unit economics.
Service Type:
Cost tier determines operational leverage and margin structure across physical-digital delivery spectrums.
- Physical Facilities:Real estate-intensive programs providing dedicated laboratory, manufacturing, and office infrastructure with on-site technical staff. Demand concentrates in venture-dense U.S. metros where proximity to university research parks and corporate R&D campuses accelerates dealflow velocity.
- Virtual Support:Cloud-based mentorship, pitch coaching, and investor networking delivered through proprietary platforms with reduced geographic dependency. Startups in second-tier U.S. cities and distributed-team configurations are adopting these platforms fastest as remote-work norms stabilize.
- Mentorship:Advisor-matching systems pairing founders with domain specialists across fundraising, product-market fit, and regulatory navigation.
- Funding Assistance:Direct capital deployment, SAFE note structuring, and LP relationship management integrated into program progression milestones.
Physical Facilities holds installed capacity. Virtual Support is rotating up the share rankings.
Industry Vertical:
Application-specific regulatory complexity and capital-formation timelines differentiate programming requirements and fee structures.
- Technology:Artificial intelligence, SaaS, and semiconductor ventures dominating application pipelines with standardized curriculum modules around GPU infrastructure access and MLOps training. Austin and San Francisco clusters pull disproportionate cohort allocation as federal small-business initiatives amplify local program density.
- Healthcare:Biotech and medical device startups requiring specialized FDA navigation expertise and extended capital-formation timelines. Programs serving this vertical command premium fee structures due to specialized advisor scarcity and longer runway requirements.
- Education:EdTech ventures addressing K-12 and workforce reskilling markets with distinct procurement pathway training.
- Manufacturing:Hard-tech and climate-hardware startups accessing prototyping equipment and supply-chain integration support.
Technology commands current enrollment share. Healthcare is climbing the fastest as biotech venture formation accelerates.
Target Client Type:
Customer maturity and capitalization stage dictate program design intensity and funding-gate sequencing.
- Startups:Pre-revenue and early-revenue ventures with limited operational history seeking structured launch support and first institutional capital. Technology and climate-tech founders in Boston and Austin represent the expanding application pool as SEC accredited-investor expansion broadens eligibility.
- SMEs:Established small enterprises pursuing product-line extension or digital transformation through external innovation partnerships.
- Entrepreneurs:Solo founders and academic spinout teams requiring co-founder matching and initial incorporation support.
- Nonprofits:Mission-driven organizations adapting commercial venture methodologies to social enterprise and public-benefit corporation structures.
Startups dominate current intake volume. SMEs are gaining share fastest as corporate venture integration creates white-label program demand.
Support Model:
Maturity and outcome-velocity expectations segment program architecture from high-touch acceleration to volume-driven co-working.
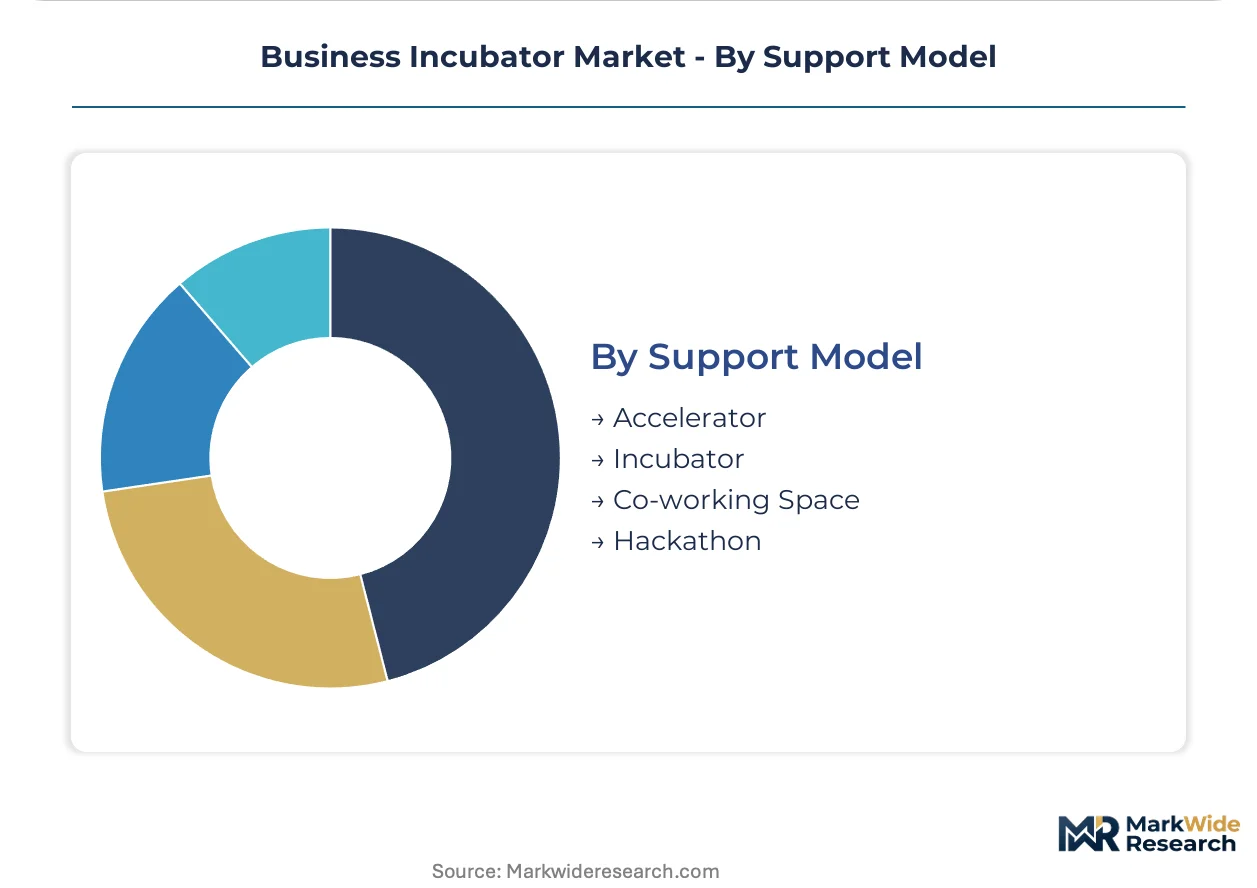
- Accelerator:Cohort-based, time-bound programs with milestone-driven funding gates and intensive mentorship density. Y Combinator and Techstars models concentrate the highest valuation outcomes per slot as LP pressure compresses path-to-liquidity timelines.
- Incubator:Longer-duration, less structured support with flexible progression metrics and extended runway provisions.
- Co-working Space:Facility-access models with minimal programmatic content occupying the volume-driven, margin-compressed tier.
- Hackathon:Short-duration, competition-format events generating prototype validation and talent identification without sustained engagement.
Accelerator holds premium positioning. Incubator is rotating up as hybrid infrastructure mandates extend program duration flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC accredited-investor expansion and Small Business Administration grant criteria are anchoring program design evolution in the United States. Federal innovation funding rules now mandate hybrid physical-digital delivery, reshaping operator economics across venture-dense metros.
United States
Federal small-business initiatives and IRA climate-tech incentives are pulling cohort allocation toward clean-energy and fintech verticals. SEC amendments to accredited-investor thresholds broaden startup eligibility for funding-assistance tracks. Austin, Boston, and San Francisco clusters compress program design cycles around revenue-ready selection metrics.
United Kingdom
Seed-stage venture formation in London and Cambridge is concentrating demand for structured launch support and first institutional capital access. Financial Conduct Authority regulations on securities crowdfunding affect program funding-gate sequencing for fintech startups. The London-Southeast corridor anchors the highest application pipeline density for technology and SaaS programming.
Germany
Industrial digitalization mandates and Mittelstand innovation partnerships are expanding SME-facing incubator demand. EU AI Act compliance training requirements alter curriculum resource allocation for data-centric startup tracks. Berlin-Brandenburg and Munich clusters pull disproportionate deep-tech and climate-hardware cohort allocation.
France
Station F's operating model is reshaping competitive expectations for facility scale and corporate partnership density in Paris. GDPR compliance modules are becoming mandatory add-ons for programs serving data-centric ventures. The Île-de-France region concentrates the highest enrollment share for artificial intelligence and machine learning startup pipelines.
Canada
DMZ's programming template is influencing curriculum standardization expectations across Toronto and Waterloo innovation corridors. Federal economic development agency funding rules now require physical-digital program blends for grant eligibility. Ontario and British Columbia clusters are gaining share fastest as second-tier metro expansion strategies redirect operator investment from U.S. coastal premiums.
Business Incubator Market Competitive Landscape
Capability concentration sits with alumni-network-dense accelerators; scale advantage sits with multi-city standardized platforms. The market structures around three tiers: premium cohort-based accelerators, mid-tier hybrid incubators, and volume-driven co-working operators. Strategic archetypes include network-leveraged deal-flow specialists, corporate-integrated innovation pipelines, and emerging-market portfolio diversifiers. Competitive moves center on geographic expansion into second-tier metros and curriculum modularization for milestone-driven progression.
Within the premium accelerator tier, Y Combinator and Techstars exemplify contrasting scale strategies. Y Combinator occupies a position defined by alumni network density and successive venture-cycle deal-flow advantages. Techstars anchors multi-city programming through standardized curriculum templates and corporate partnership replication. 500 Global sits within the emerging-market portfolio diversification archetype, differentiating risk-return exposure from Silicon Valley-centric rivals.
| Leading Market Players |
|---|
| Seedcamp |
| Idealab |
| Y Combinator |
| Betaworks |
| Capital Factory |
| Techstars |
| Station F |
| DMZ |
| 500 Global |
| Others |
Value Network & Pricing Analysis
Prime facility real estate in venture-dense U.S. metros commands disproportionate operating budget allocation, compressing per-cohort margins and forcing operators toward virtual platform investments that reshape downstream margin pools.
Pricing Analysis
Geographic price spreads between Austin and San Francisco facility-based programs exceed threefold, with premium accelerator slots in coastal clusters commanding elevated fees tied to alumni-network density and LP relationship access. Three-tier pricing structure across premium accelerator, hybrid incubator, and volume co-working levels differentiates service intensity and milestone-gating rigor. Cost compression in facility-dependent tiers is intensifying because real estate escalation outpaces program revenue growth. Early-stage startups in second-tier metros exhibit highest price sensitivity, while revenue-ready ventures in top-tier accelerators demonstrate inelastic demand for network-access premiums.
Supply Chain Analysis
Export-control regimes limiting GPU and semiconductor flows to Chinese data-centric startups are reshaping curriculum infrastructure sourcing for AI-focused programs. Supply chain configuration draws from U.S. cloud hyperscaler partnerships, Israeli cybersecurity training modules, and Canadian university research pipelines. Raw material dependencies center on proprietary platform software, specialized advisor talent pools, and venture capital relationship networks. Single-source vulnerability concentrates in alumni-network-dependent dealflow channels. Distribution runs through direct application portals, university partnership pipelines, and corporate venture referral networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where modular curriculum stacks and API-integrated service marketplaces are displacing standardized program delivery, with Y Combinator's alumni-network interoperability setting ecosystem expectations.
For Market Incumbents: Build data-network-effect moats by embedding portfolio-performance analytics into LP reporting interfaces and automating investor-match algorithms that compound with each cohort cycle. Consolidate advisor talent pools through exclusive regional partnerships before specialized regulatory expertise bidding wars escalate. Threat substitution from corporate white-label programs demands preemptive capacity addition in Raleigh and Nashville corridors. For New Entrants and Emerging Players: Second-tier U.S. metros including Salt Lake City and Columbus offer underpenetrated demand for climate-tech and healthcare specialization tracks with lower facility cost bases. Corporate venture integration creates white-space opportunity for sector-specific program operators with guaranteed offtake mechanisms. Go-to-market traction accelerates through university research park anchor tenancy rather than independent facility development. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hybrid incubator platforms seeking geographic rollup capacity and curriculum IP consolidation. Long-term viability hinges on recurring revenue share from portfolio company exits rather than upfront program fees. Acquisition target archetype combines modular platform technology with dense regional advisor networks. Signal to watch: SEC accredited-investor threshold adjustments altering funding-assistance program addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-connected service marketplaces enable modular curriculum stacking across hybrid delivery modes. |
| Geographic Expansion | Second-tier metro entry captures lower facility costs and under-tapped university research pipelines. |
| Strategic Partnership | Corporate venture integration creates white-label opportunities with guaranteed startup offtake mechanisms. |
| Acquisition of Specialist Firm | Regulatory navigation expertise consolidation addresses healthcare and fintech advisor talent scarcity. |
| Product Launch | AI-powered pitch-deck analysis and investor-match tools compress advisor-to-founder ratio constraints. |
Research Methodology
Initial hypotheses were tested against primary input from incubator program directors, venture capital general partners, startup founders, and economic development authority grant officers and refined through secondary validation against SEC accredited-investor rulemakings, Small Business Administration funding databases, National Science Foundation innovation metrics, and university research commercialization disclosures. Bottom-up cohort economics modeling triangulated with top-down federal funding allocation analysis.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning service type, industry vertical, target client maturity, and support model intensity. CAGRs derived from historical program capacity expansion rates and federal budget trajectory modeling. Forecast inputs incorporated IRA climate-tech incentive allocation timelines and SEC securities-law amendment implementation pacing.
Practitioners should monitor SEC accredited-investor threshold revisions, national innovation agency budget reallocations between physical and virtual infrastructure, and real estate cost trajectories in venture-dense metros for early signals. Forecasts reflect assumptions around stable remote-work norms and continued federal small-business initiative funding. Material shifts in SEC securities-law frameworks or federal innovation agency mandate priorities would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
Venture Capital Investment Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
US Venture Capital Investment Market
Venture Capital
Crowdfunding Market
Venture Capital
Impact Investing Market
Venture Capital
North America Venture Capital Market
Venture Capital
United States Venture Capital Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
Europe Venture Capital Market
Venture Capital
Asia-Pacific Venture Capital Investment Market
Venture Capital
Micro Venture Capital VC Funds Market
Venture Capital
Micro VC Funds Market
Venture Capital
Asia Pacific Venture Capital Market