
 Bitcoin Exchange Market | 2026-2036
Bitcoin Exchange Market Size, Share, and Industry Trends Forecast 2026-2036
Bitcoin Exchange Market Insights
Asset-light custody outsourcing and white-label exchange infrastructure is narrowing the capital barrier for new entrants. Coinbase Exchange anchors its position through deep liquidity pools and regulatory licenses across multiple states. Kraken differentiates via advanced staking infrastructure and institutional-grade API architecture. Binance competes through vertical integration spanning spot, derivatives, and payment rails.
A Bitcoin exchange constitutes a digital marketplace that matches buy and sell orders for Bitcoin using order-book engines with sub-millisecond latency and cold-wallet reserves exceeding hot-wallet balances by typical security ratios. Centralized exchanges dominate transaction volume due to fiat on-ramp integration and margin lending depth, while decentralized exchanges capture growing share among privacy-sensitive users seeking non-custodial settlement. Peer-to-peer platforms occupy niche demand corridors in jurisdictions with capital control restrictions.
The SEC enforces registration requirements for spot Bitcoin ETF custodians, while the EU's MiCA framework mandates reserve transparency and consumer protection protocols for exchanges serving European residents. The FCA in the United Kingdom imposes anti-money laundering audits that filter out undercapitalized operators. Stakeholders must monitor how jurisdictional arbitrage between these regimes reshapes venue location decisions and user access patterns.
Market Dynamics
Spot Bitcoin ETF approval by the SEC has triggered institutional capital migration toward regulated custodians, compressing margins for offshore venues while concentrating liquidity in US-licensed order books.
Growth Catalysts
- MiCA Reserve Transparency:The EU's Markets in Crypto-Assets framework mandates proof-of-reserve disclosures that reduce counterparty risk and attract pension fund allocations.
- Lightning Network Integration:Layer-2 settlement rails enable sub-cent transaction fees that unlock micropayment use cases for content streaming and machine-to-machine commerce.
- Argentina:Capital control restrictions and peso volatility drive peer-to-peer Bitcoin adoption as households seek dollar-equivalent savings instruments.
Market Restraints
- Cold Storage Infrastructure Costs:Multi-signature hardware security modules and geographically distributed vaults require capital outlays that exclude undercapitalized entrants.
- US Banking Access:FDIC-insured institutions maintain de facto bans on correspondent relationships with unregistered exchanges, fragmenting fiat on-ramp availability.
- Proof-of-Work Energy Scrutiny:Environmental disclosure requirements in the EU and select US states impose compliance burdens on mining-adjacent exchange products.
Strategic Opportunities
- White-Label Infrastructure:Asset-light custody outsourcing allows fintechs and neobanks to launch branded exchange services without proprietary security engineering.
- Staking-Enabled Savings Products:Yield-bearing Bitcoin wrappers attract retail depositors from traditional savings accounts, particularly in high-inflation corridors.
- India:Regulatory clarity from RBI and SEBI on crypto asset classification would unlock remittance corridor demand from the diaspora.
Industry Challenges
- Qualified Custodian Certification:SEC registration timelines for institutional-grade cold storage operators extend 18-24 months, delaying product launches.
- Cross-Chain Settlement Complexity:Bitcoin bridging to Ethereum and Solana ecosystems introduces smart contract audit requirements that strain engineering bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bitcoin Exchange Market |
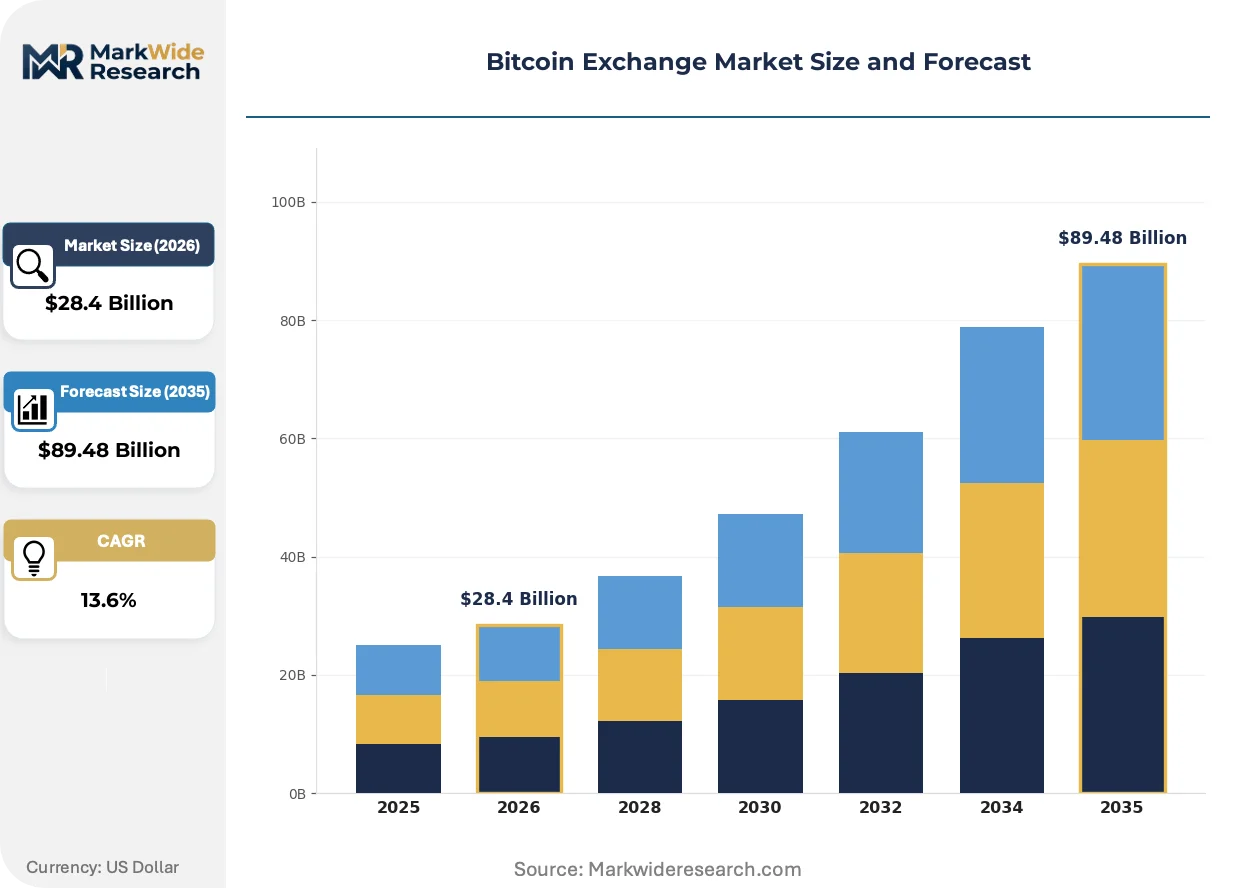
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $89.48 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Exchange Type: Centralized Exchange, Decentralized Exchange, Peer-to-Peer Platform, Hybrid Exchange Transaction Method: Fiat to Crypto, Crypto to Crypto, Margin Trading, Staking User Type: Retail Investors, Institutional Investors, Traders, Miners Security Features: Two-Factor Authentication, Cold Storage, Multi-Signature, Insurance Coverage |
| Companies Covered | Binance, Coinbase Exchange, Upbit, HTX, Crypto.com Exchange, Bitfinex, Kraken, BingX, BitMart, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bitcoin Exchange Market Trends and Innovations
Institutional custody architecture and regulatory arbitrage strategies are bifurcating the exchange landscape into compliant onshore venues and privacy-preserving offshore alternatives.
Multi-party computation (MPC) wallet infrastructure eliminates single points of failure by distributing private key shards across geographically separated hardware enclaves. Institutional treasury departments at technology firms are migrating assets from traditional cold storage to MPC-enabled custodians. This migration is rendering obsolete the legacy model of exchange-operated omnibus wallets that commingle customer funds.
The SEC's qualified custodian rule amendments impose segregation requirements on spot Bitcoin ETF administrators. Asset managers must now demonstrate independent verification of cold wallet balances through third-party attestations. European fund sponsors face parallel demands under MiCA reserve transparency protocols, accelerating compliance spend among mid-tier venues.
Self-custody hardware wallets are experiencing demand rotation from retail speculators toward high-net-worth individuals in jurisdictions with unstable banking systems. Distributors in Turkey and Nigeria report inventory depletion cycles compressing from quarterly to monthly replenishment. This behavioral shift pressures centralized exchanges to develop non-custodial on-ramp partnerships or cede wallet market share to device manufacturers.
Bitcoin Exchange Market Segmentation
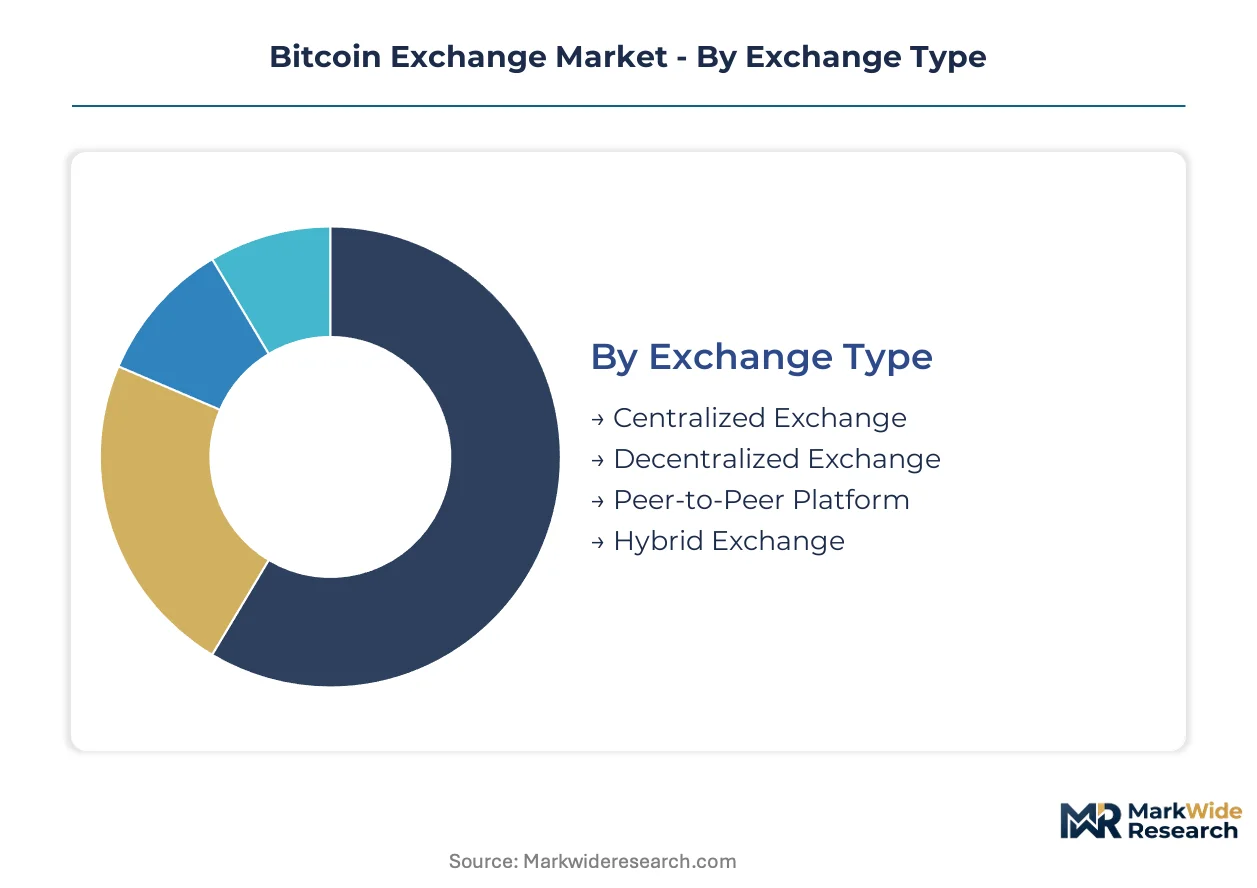
Exchange architecture determines custody risk profiles, regulatory exposure, and revenue model sustainability. Segment boundaries are blurring as centralized venues add non-custodial options and decentralized protocols integrate fiat on-ramps.
Exchange Type:
Mature infrastructure dominates transaction volume while emerging models capture privacy-sensitive and capital-controlled corridors.
- Centralized Exchange:Order-book engines with sub-millisecond matching and segregated cold storage hold the majority of global Bitcoin trading volume. Demand concentrates in the United States following spot ETF approval, where qualified custodian requirements filter out undercapitalized operators.
- Decentralized Exchange:Non-custodial settlement via automated market makers eliminates counterparty risk but introduces smart contract audit dependencies. Privacy-sensitive users in Germany and Switzerland drive adoption as MiCA transparency mandates push activity toward non-custodial alternatives.
- Peer-to-Peer Platform:Escrow-mediated direct trades serve Argentina and Nigeria where banking restrictions limit fiat on-ramp access.
- Hybrid Exchange:Off-chain order matching with on-chain settlement blends speed and self-custody for sophisticated retail segments.
Centralized Exchange handles the majority of throughput; Decentralized Exchange is expanding most quickly on share.
Transaction Method:
Revenue concentration follows entry-point friction, with low-barrier fiat gateways outperforming specialized derivatives products.
- Fiat to Crypto:Bank transfer and card payment integration generates the highest customer acquisition costs but locks in recurring deposit behavior. United States pension fund allocations through regulated ETFs are compressing margins for offshore fiat on-ramp providers.
- Crypto to Crypto:Spot and perpetual swap pairs attract algorithmic traders seeking arbitrage across venue price discrepancies. Singapore and Hong Kong licensing frameworks favor venues with deep altcoin liquidity pools.
- Margin Trading:Collateralized leverage up to 100x amplifies liquidation risk and regulatory scrutiny in Japan and South Korea.
- Staking:Yield-bearing Bitcoin wrappers compete with traditional savings products in Turkey and Brazil where local currency depreciation accelerates deposit migration.
Fiat to Crypto commands the dominant revenue share; Staking is climbing the fastest as interest-rate differentials widen.
User Type:
Customer lifetime value stratifies sharply across sophistication tiers, driving divergent platform investment priorities.
- Retail Investors:Mobile-first interfaces with simplified custody dominate acquisition spend. Dollar-cost averaging tools and recurring buy programs in India and Indonesia show strongest activation metrics.
- Institutional Investors:API co-location, sub-account segregation, and third-party audit trails are non-negotiable requirements. Treasury departments at technology firms in the United States are mandating MPC-enabled custodians over legacy cold storage.
- Traders:Latency-sensitive participants require WebSocket feeds and custom order types unavailable on retail-focused venues.
- Miners:Hash-rate hedging and immediate fiat conversion needs create demand for over-the-counter desks with mining-pool relationships.
Retail Investors account for the largest user base; Institutional Investors are gaining share fastest on wallet inflows.
Security Features:
Compliance differentiation now hinges on provable controls rather than marketing claims, with audit attestation costs rising.
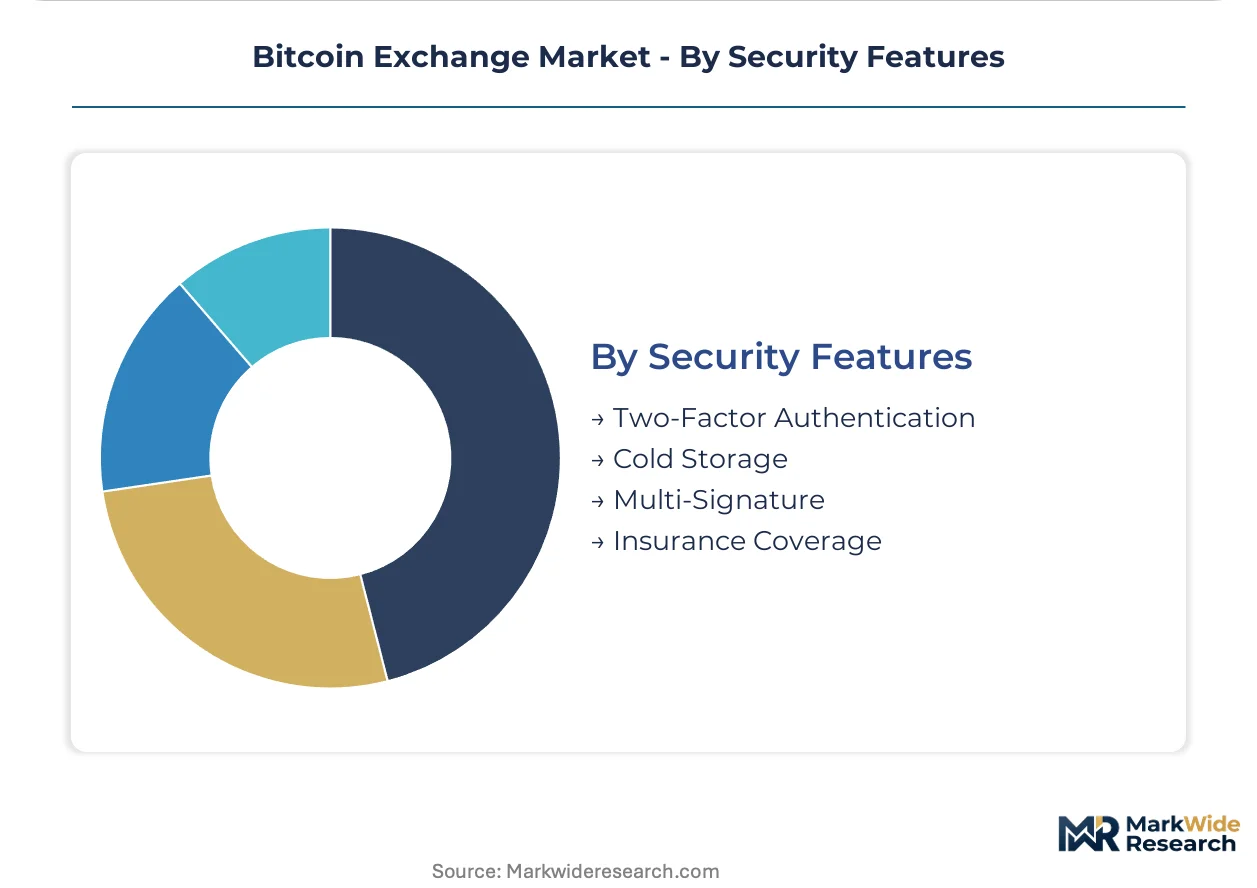
- Two-Factor Authentication:TOTP and hardware key standards have become baseline hygiene rather than competitive differentiator.
- Cold Storage:Geographically distributed vaults with multi-signature schemes remain the institutional standard despite MPC displacement in advanced segments.
- Multi-Signature:M-of-N key distribution across hardware security modules satisfies qualified custodian definitions under SEC guidance.
- Insurance Coverage:Crime and specie policies from Lloyd's syndicates and Bermuda carriers cover a minority of global hot wallet balances.
Cold Storage underpins the majority of protected assets; Insurance Coverage is the fastest-moving feature on procurement priority lists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Net capital flows into regulated Bitcoin venues favor import-dependent economies with convertible currencies, while export-reliant jurisdictions with capital controls sustain peer-to-peer arbitrage corridors. The United States absorbs the majority of institutional inflows through ETF channels. European MiCA compliance costs are repatriating order book liquidity to domestic venues.
United States
Pension fund allocations and corporate treasury adoption drive demand concentration. The SEC enforces qualified custodian rules that filter out undercapitalized operators. New York and Chicago host the deepest regulated liquidity pools, with ETF custodians clustering around federally chartered banking relationships.
Germany
MiCA reserve transparency mandates attract institutional capital seeking counterparty risk reduction. BaFin licensing requirements impose capital adequacy standards that exclude offshore venues. Frankfurt anchors compliance infrastructure, while Berlin hosts privacy-sensitive users migrating toward non-custodial alternatives.
Singapore
Family office wealth and proprietary trading desks sustain deep altcoin liquidity demand. The Monetary Authority of Singapore grants payment institution licenses that enable fiat on-ramp integration. The Marina Bay financial district concentrates API co-location facilities serving latency-sensitive participants.
Argentina
Peso volatility and capital control restrictions sustain peer-to-peer Bitcoin adoption as dollar-equivalent savings. The central bank maintains strict foreign exchange limits that fragment formal banking access. Buenos Aires anchors escrow-mediated trading volumes, with Córdoba emerging as secondary corridor activity.
Japan
Retail savings migration and margin trading restrictions shape venue specialization. The Financial Services Agency enforces segregation requirements that elevate compliance costs for foreign operators. Tokyo concentrates exchange headquarters, while Osaka hosts derivative clearing infrastructure.
Bitcoin Exchange Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in custody engineering and liquidity provision. The vendor base stratifies across three tiers: vertically integrated global venues, regional license-holders with fiat banking relationships, and white-label infrastructure providers. Dominant competitive moves include jurisdictional licensing expansion and MPC custody technology acquisition. Strategic partnerships between neobanks and custody outsourcers narrow capital barriers for new entrants.
Among vertically integrated global operators, Binance and Coinbase Exchange exemplify contrasting archetypes. Binance represents maximal scope across spot, derivative, and payment rail integration. Coinbase Exchange anchors the compliance-first segment through multi-state regulatory licenses and institutional-grade cold storage infrastructure. Kraken occupies a specialized position in advanced staking infrastructure and API architecture serving sophisticated traders.
| Leading Market Players |
|---|
| Binance |
| Coinbase Exchange |
| Upbit |
| HTX |
| Crypto.com Exchange |
| Bitfinex |
| Kraken |
| BingX |
| BitMart |
| Others |
Pricing and Supply Chain Analysis
Cold-wallet security module manufacturing concentrates in Switzerland and South Korea, anchoring cost structures for institutional-grade custody infrastructure and concentrating margin capture with qualified custodians possessing direct hardware procurement relationships.
Pricing Analysis
Institutional treasury buyers anchor pricing structures around custody fee schedules that stratify across insurance-backed segregated storage, MPC-enabled multi-party computation tiers, and unqualified omnibus wallet arrangements. Price differentiation hinges on SOC 2 Type II certification status and Lloyd's of London crime policy coverage limits. Cost compression in retail-facing fiat on-ramp tiers is intensifying because spot Bitcoin ETF sponsors negotiate volume-based custody discounts. Retail speculators exhibit highest price sensitivity, while pension fund allocators prioritize counterparty risk mitigation over basis point optimization.
Supply Chain Analysis
Upstream hardware security module fabrication feeds from semiconductor foundries in Taiwan, Switzerland, and the United States, with assembly concentrated in Germany and Singapore. Raw material dependencies span tamper-resistant microcontroller substrates, electromagnetic shielding alloys, and cryptographic accelerator chips. Single-source vulnerability in FIPS 140-2 Level 4 certified component supply creates procurement bottlenecks for qualified custodian applicants. Distribution runs through direct OEM relationships for tier-one exchanges, with white-label infrastructure providers sourcing via systems integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spot Bitcoin ETF approval constitutes a regulatory inflection compressing offshore venue margins while concentrating liquidity in compliant onshore order books, creating asymmetric growth trajectories across custody infrastructure tiers.
For Market Incumbents: Insulate market position by accelerating MPC custody technology acquisition to displace legacy cold storage architectures, and deepen correspondent banking relationships with federally chartered institutions before SEC qualified custodian rule amendments tighten depository requirements. Unregistered offshore venues represent the primary substitution threat. Vertical integration into staking infrastructure serves as the critical defensive lever.
For New Entrants and Emerging Players: White-label custody outsourcing for neobanks and fintechs in India and Indonesia represents the most penetrable entry point, with Lightning Network payment rail integration offering differentiated go-to-market positioning against incumbent fiat on-ramp providers. Argentina's peer-to-peer corridor and Turkey's yield-bearing savings product demand constitute secondary white-space targets.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed custody infrastructure specialists possessing MiCA licensing progress and pending SEC qualified custodian applications. Long-term viability hinges on regulatory license moats rather than trading volume market share. Institutional wallet inflow velocity serves as the critical inflection indicator to monitor.
| Strategic Initiative | Industry Significance |
|---|---|
| MiCA Licensing Completion | Unlocks European pension fund allocations through compliant reserve transparency protocols. |
| MPC Custody Acquisition | Eliminates single points of failure and satisfies institutional treasury migration requirements. |
| Lightning Network Integration | Enables sub-cent settlement fees for micropayment and machine-to-machine commerce use cases. |
| White-Label Infrastructure Partnership | Allows neobanks to launch branded exchange services without proprietary security engineering. |
| Qualified Custodian Certification | SEC registration enables spot Bitcoin ETF administration and institutional capital capture. |
Research Methodology
Cross-validation between primary interviews and secondary regulatory filings anchors the qualitative findings. Conversations with exchange compliance officers, custody infrastructure engineers, institutional treasury managers, and MiCA licensing consultants informed operational dynamics. Secondary sources include SEC registration statements, BaFin licensing databases, EBA technical standards, and ETF sponsor custody disclosure documents. Bottom-up transaction volume estimates triangulate against top-down addressable wealth calculations.
Calibration against historical license approval timelines and custody technology adoption curves shapes the analytical framework. Segmentation dimensions span exchange architecture type, custody security tier, user sophistication level, and jurisdictional regulatory cluster. CAGRs derive from wallet inflow velocity projections and institutional allocation policy diffusion patterns. Spot ETF flow data and qualified custodian application backlogs serve as industry-specific forecast inputs throughout the projection horizon.
Practitioners should monitor SEC enforcement actions against unregistered venues and MiCA reserve audit failure incidents for early signals of regulatory regime shifts. Cross-checking against on-chain wallet balance attestations and third-party custody verification reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Assets and Cryptocurrency Finance
Global Cryptocurrency Custody Software Market
Digital Assets and Cryptocurrency Finance
Crypto Trading Platform Market
Digital Assets and Cryptocurrency Finance
Smart Contracts Platforms Market
Digital Assets and Cryptocurrency Finance
Digital Currency Wallet Market
Digital Assets and Cryptocurrency Finance
Spain Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Online Trading Platform Market
Digital Assets and Cryptocurrency Finance
Crypto Asset Management Platform Market
Digital Assets and Cryptocurrency Finance
Digital Finance Market
Digital Assets and Cryptocurrency Finance
United States Crypto ATM Market
Digital Assets and Cryptocurrency Finance
Virtual Currency Market
Digital Assets and Cryptocurrency Finance
Music NFT Market
Digital Assets and Cryptocurrency Finance
Tokenization Solution Market
Digital Assets and Cryptocurrency Finance
Cryptocurrency Exchanges Market
Digital Assets and Cryptocurrency Finance
Crypto ATM Market
Digital Assets and Cryptocurrency Finance
US and Europe Crypto Asset Management Market
Digital Assets and Cryptocurrency Finance
Global Smart Contracts Market