
 Asia Pacific Venture Capital Market | 2026-2036
Asia Pacific Venture Capital Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Venture Capital Market Outlook
Singapore's Green Finance Action Plan is expanding the pool of ESG-mandated institutional capital available to regional venture funds. Hillhouse Capital Group leverages its cross-border platform to anchor late-stage rounds in Chinese healthcare technology. GGV Capital sustains early-stage dominance across Southeast Asian fintech through dedicated local partnerships. Tiger Global Management competes on speed and check size, deploying growth capital at scale across India and Australia.
Venture capital denotes equity financing provided to private companies exhibiting high growth potential, typically structured through limited partnerships with carried interest waterfalls and milestone-based capital calls. The asset class functions as primary growth fuel for technology commercialization, bridging the gap between angel funding and public market access. Growth Stage deployment captures the largest capital allocation as companies achieve product-market fit and require expansion financing. Early Stage investment registers the fastest velocity as micro-VC proliferation and angel syndicate platforms democratize access across second-tier cities. Institutional Investors supply the dominant LP base, though Corporate Venture participation deepens as conglomerates seek strategic optionality in adjacent sectors.
Singapore's Monetary Authority enforces risk-based fund licensing under the Securities and Futures Act, shaping manager registration requirements and investor protection standards across ASEAN-domiciled vehicles. India's SEBI governs Alternative Investment Fund categories with distinct investment conditions and disclosure obligations for domestic venture structures. Australia's ASIC administers wholesale investor thresholds that filter retail participation and concentrate capital among sophisticated LPs. Stakeholders must monitor evolving cross-border tax treaty negotiations and local substance requirements that determine optimal fund structuring jurisdiction.
Market Dynamics
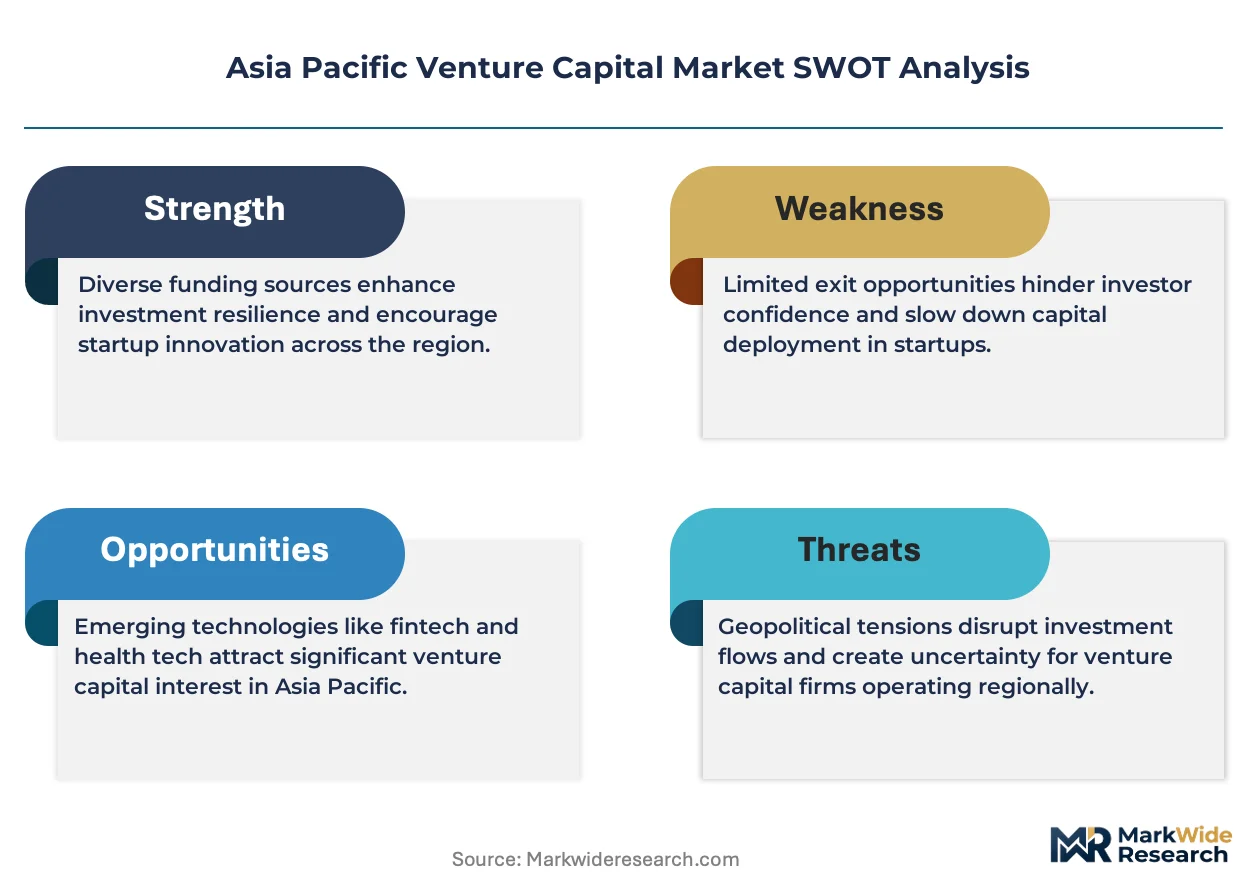
Cross-border capital mobility restrictions are fragmenting LP commitment patterns across the Asia Pacific venture landscape, forcing fund managers to restructure domiciles and local substance requirements.
Growth Catalysts
- Singapore's Variable Capital Company framework:The jurisdiction's fund structure reforms reduce setup timelines and operational costs for ASEAN-domiciled vehicles, attracting manager relocations from Hong Kong and Australia.
- India's semiconductor PLI scheme:Domestic manufacturing incentives redirect institutional capital toward deeptech and hardware startups, creating new deal flow categories beyond software-as-a-service.
- Southeast Asian digital payment infrastructure:Real-time settlement rails and e-wallet interoperability mature across Indonesia, Vietnam, and Philippines, enabling fintech platforms to achieve unit economics that attract growth-stage checks.
Market Restraints
- LP concentration in sovereign wealth funds:Malaysia's Khazanah, Singapore's Temasek, and Australia's Future Fund supply disproportionate primary capital, creating redemption cascade risks during macroeconomic stress.
- Valuation markdown friction:Secondary market illiquidity for pre-IPO equity prevents accurate portfolio marking, delaying capital recycling and distorting IRR calculations across vintage years.
- Currency mismatch in USD-denominated funds:Indian and Indonesian portfolio companies generate local-currency revenues while reporting to dollar-based LPs, compressing realized multiples during rupee or rupiah depreciation cycles.
Strategic Opportunities
- Vietnam's underpenetrated Series B+ landscape:Ho Chi Minh City and Hanoi ecosystems show concentrated angel and seed activity but sparse growth-stage capital, creating first-mover advantages for dedicated funds.
- Climate tech regulatory tailwinds:Singapore's Green Finance Action Plan and Australia's Net Zero Economy Authority create mandated ESG allocation floors that expand available LP capital for clean energy venture vehicles.
- AI infrastructure convergence with biotech:Computational biology platforms combining large language models with protein folding accelerate drug discovery timelines, opening new investment theses for cross-over funds.
Industry Challenges
- Technical due diligence capacity gaps:Frontier technology sectors including quantum computing and synthetic biology require specialized scientific advisory networks that most generalist partners lack.
- Cross-border data localization compliance:China's Cybersecurity Law, India's Digital Personal Data Protection Act, and Indonesia's data sovereignty requirements fragment cloud architecture decisions and diligence processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Venture Capital Market |
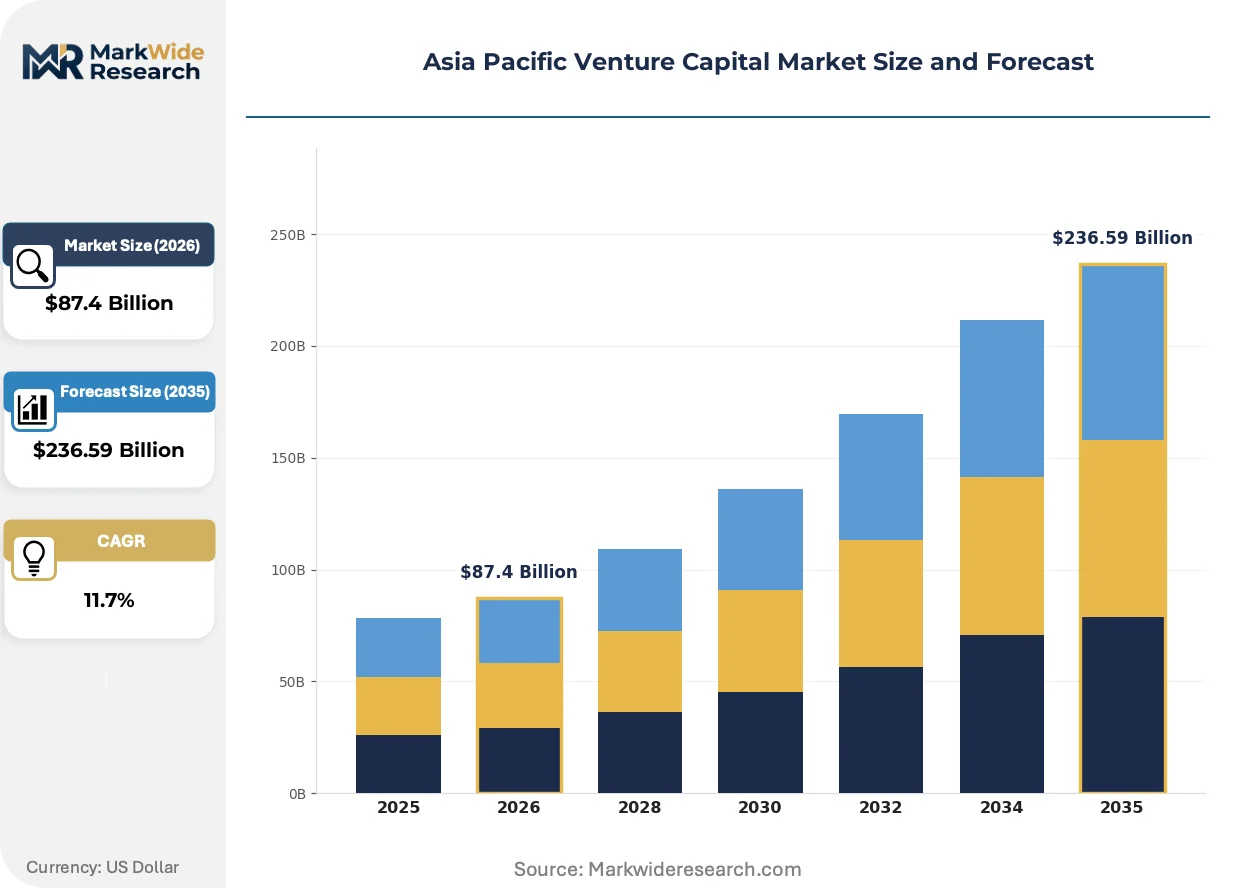
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $236.59 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed, Early Stage, Growth Stage, Late Stage Investor Type: Institutional Investors, Angel Investors, Corporate Venture, Fund of Funds Industry Vertical: Technology, Healthcare, Consumer Products, Fintech Funding Size: Small Cap, Medium Cap, Large Cap, Mega Cap |
| Companies Covered | Hillhouse Capital Group, GGV Capital, Qiming Venture Partners, East Ventures, General Atlantic, Tiger Global Management, Jungle Ventures, Monk's Hill Ventures, Alpha JWC Ventures, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Venture Capital Market Strategic Shifts
Fund architecture is pivoting toward specialized single-sector vehicles and continuation fund structures as LPs demand granular exposure control and extended holding periods for illiquid winners.
Tokenized fund interests are expanding into secondary transaction workflows, enabling fractional LP stake sales without full fund restructurings. Southeast Asian fund administrators pilot blockchain-based cap table management to reduce settlement friction. This infrastructure is compressing secondary market clearing timelines from quarters to weeks for compliant jurisdictions.
Australia's ASIC wholesale investor threshold reforms tighten access criteria for retail-adjacent capital, concentrating commitments among sophisticated LPs with minimum portfolio size requirements. The regulatory revision redirects fund marketing resources toward institutional relationship management. New Zealand and Singapore regulators monitor the Australian framework for potential harmonization.
Corporate venture arms now originate direct co-investment rights rather than passive LP commitments, unbundling traditional fund fee structures. Japanese trading houses and Korean chaebol subsidiaries lead this behavioral shift across Asia Pacific. The model concentrates capital deployment decisions inside strategic parent entities rather than external GP relationships.
Asia Pacific Venture Capital Market Segmentation
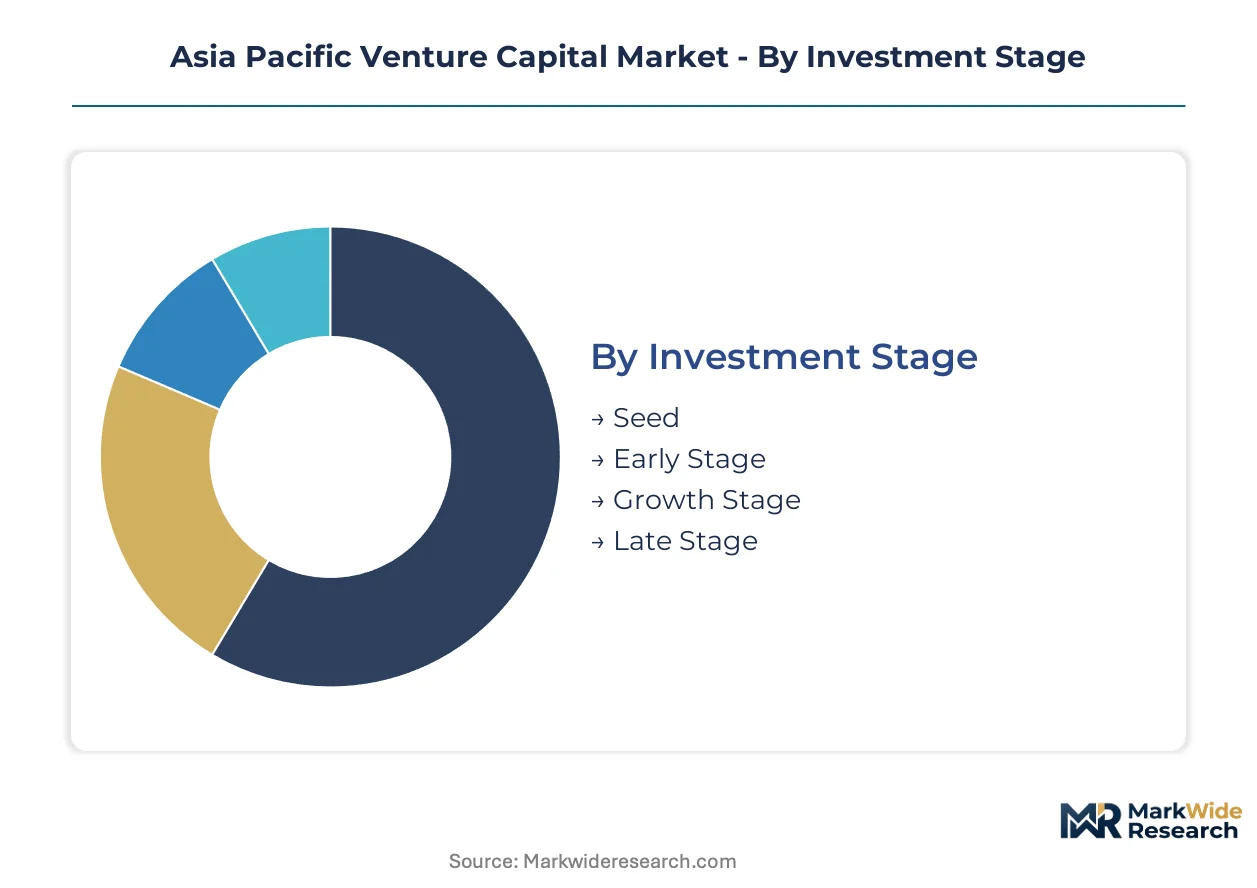
Investment stage classification determines capital call structures, carried interest waterfalls, and LP reporting cadences across Asia Pacific venture funds. Segment boundaries shift as micro-VC proliferation blurs traditional round definitions and regulatory thresholds vary across Singapore, India, and Australia.
Investment Stage:
SEBI's Category I AIF regulations in India and MAS licensing frameworks in Singapore impose distinct disclosure obligations and investor qualification thresholds at each stage tier.
- Growth Stage:Deployment captures the largest capital allocation as portfolio companies achieve product-market fit and require expansion financing for geographic scaling. Singapore-based managers concentrate here as ASEAN fintech platforms mature toward profitability and attract sovereign wealth co-investment. Leading the category by volume: Growth Stage. Expanding most quickly: Early Stage.
- Early Stage:Micro-VC proliferation and angel syndicate platforms democratize access across second-tier Indian cities and Indonesian tech hubs. Vietnam's Ho Chi Minh City ecosystem shows concentrated activity but sparse growth-stage follow-on, creating velocity bottlenecks.
- Seed:Government grant matching programs in Australia and Singapore supplement private capital at formation rounds.
- Late Stage:Cross-over funds from public markets deploy pre-IPO checks as secondary liquidity remains constrained.
Stage migration patterns: capital concentrates in Growth as fintech unit economics mature across Southeast Asia.
Investor Type:
LP composition shapes fund governance, with sovereign wealth concentration creating redemption cascade risks during macroeconomic stress.
- Institutional Investors:Pension funds, endowments, and insurance subsidiaries supply the dominant commitment base across Asia Pacific venture structures. Australia's Future Fund and Singapore's GIC anchor mega-cap vehicles with minimum ticket sizes exceeding $50 million.
- Corporate Venture:Japanese trading houses and Korean chaebol subsidiaries now originate direct co-investment rights rather than passive LP commitments. This behavioral shift concentrates deployment decisions inside strategic parent entities and unbundles traditional fund fee structures.
- Angel Investors:Syndicate platforms aggregate high-net-worth individuals across India's tier-2 technology clusters.
- Fund of Funds:Diversification vehicles gain traction among European and North American LPs seeking Asia Pacific exposure without direct manager selection.
Dominant capital source: Institutional Investors. Fastest governance evolution: Corporate Venture.
Industry Vertical:
Vertical specialization determines technical due diligence capacity requirements and scientific advisory network depth.
- Fintech:Real-time settlement rails and e-wallet interoperability mature across Indonesia, Vietnam, and Philippines, enabling platforms to achieve unit economics that attract growth-stage checks. Singapore's Payment Services Act licensing creates regulatory clarity that concentrates manager attention on licensed versus unlicensed models.
- Technology:India's PLI scheme for electronics and semiconductors redirects institutional capital toward deeptech and hardware startups beyond software-as-a-service. SEBI's Category I AIF conditions favor domestic manufacturing alignment.
- Healthcare:Computational biology platforms combining large language models with protein folding accelerate drug discovery timelines.
- Consumer Products:E-commerce penetration variance across ASEAN creates geographic arbitrage opportunities for brand-building capital.
Revenue concentration: Fintech. Steepest expansion trajectory: Technology.
Funding Size:
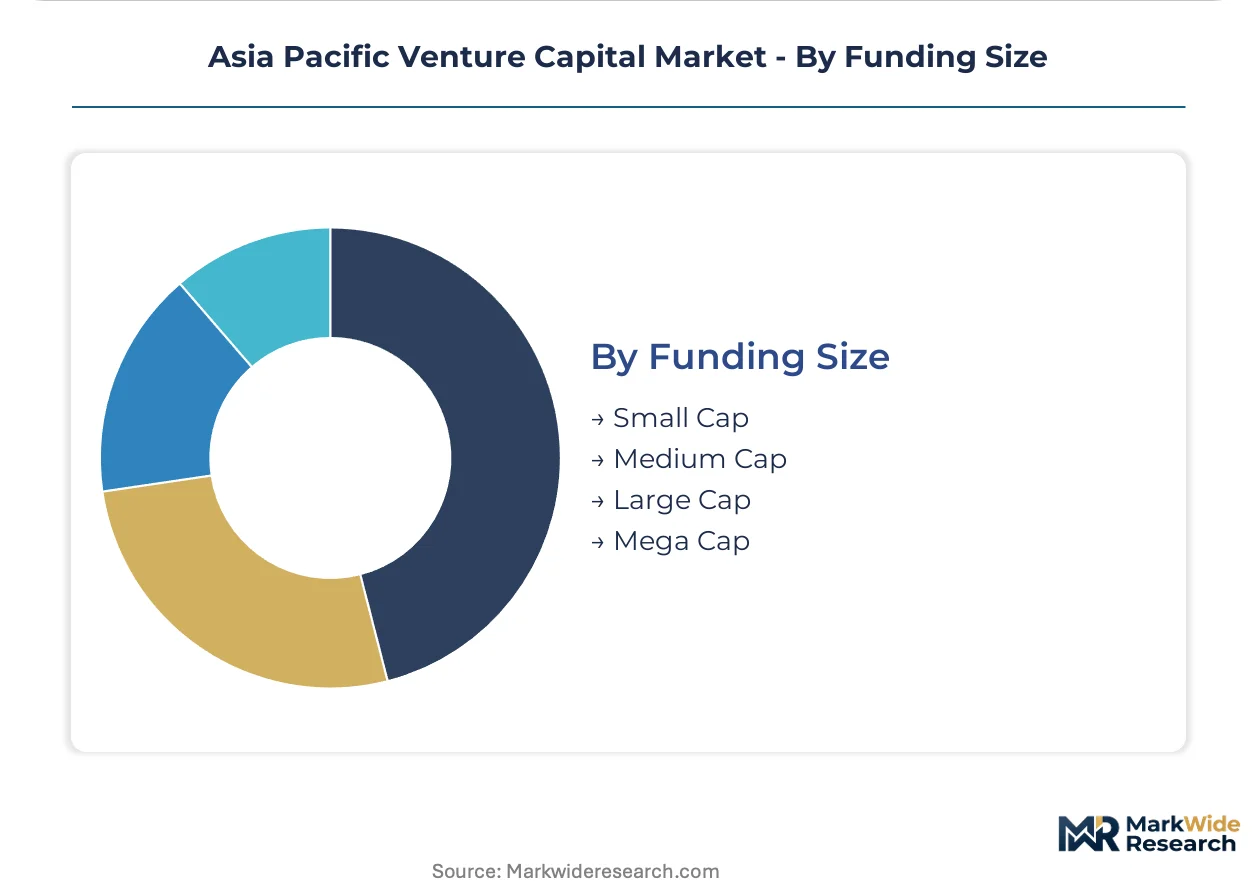
Check size thresholds determine manager registration requirements under Singapore's Securities and Futures Act and Australia's wholesale investor frameworks.
- Large Cap:Tiger Global Management and Hillhouse Capital Group compete on speed and deployment scale across India and Australia. These rounds attract sovereign wealth co-investment and concentrate in sectors with clear regulatory pathways.
- Mega Cap:Single-check deployments exceeding $100 million require bespoke fund structures and extended holding period provisions. Singapore's Variable Capital Company framework reduces setup timelines for these vehicles.
- Medium Cap:Series B and C rounds show supply-demand imbalance in Vietnam's underpenetrated landscape.
- Small Cap:Angel and seed activity proliferates across Indonesian second-tier cities with limited growth-stage follow-on.
Capital deployment concentration: Large Cap. Gaining share fastest: Mega Cap.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Marina Bay financial district anchors venture capital deployment across Southeast Asia, with fund domicile activity concentrating in the city-state's Variable Capital Company structures.
Singapore
Sovereign wealth funds Temasek and GIC supply anchor capital for mega-cap venture vehicles. The Monetary Authority of Singapore enforces risk-based fund licensing under the Securities and Futures Act, shaping manager registration requirements. Marina Bay and Raffles Place host the highest density of ASEAN-domiciled fund administrators and legal structuring specialists.
India
Domestic manufacturing incentives redirect institutional capital toward deeptech and hardware startups beyond software-as-a-service. SEBI governs Alternative Investment Fund categories with distinct investment conditions for domestic venture structures. Bengaluru and Mumbai clusters show concentrated Series B and C activity in fintech and enterprise software.
Australia
Pension funds and insurance subsidiaries supply the dominant commitment base for Asia Pacific venture exposure. ASIC administers wholesale investor thresholds that filter retail participation and concentrate capital among sophisticated LPs. Sydney and Melbourne ecosystems show deepening corporate venture participation from mining and financial services conglomerates.
Vietnam
Ho Chi Minh City and Hanoi show concentrated angel and seed activity but sparse growth-stage capital, creating velocity bottlenecks for scaling companies. The country's national financial regulator maintains evolving frameworks for foreign investment fund registration. Saigon Hi-Tech Park anchors hardware and semiconductor startup formation with limited Series B follow-on availability.
Indonesia
Real-time settlement rails and e-wallet interoperability mature across Jakarta and Surabaya, enabling fintech platforms to achieve unit economics that attract growth-stage checks. The central bank oversees payment system licensing that determines regulatory clarity for venture-backed models. The capital region concentrates venture deployment while second-tier cities show proliferating seed activity with limited follow-on infrastructure.
Asia Pacific Venture Capital Market Competitive Environment
The competitive structure tilts toward cross-border platform operators with dedicated local partnerships. Manager specialization fragments across sector-focused vehicles and stage-specific strategies, with fee compression pressuring traditional two-and-twenty models. Two archetypes dominate: sovereign wealth-backed mega-cap deployers and micro-VC specialists with hyper-local network density. Competitive moves concentrate on manager relocation to Singapore's Variable Capital Company framework and direct co-investment right origination that unbundles traditional fund structures.
Within the cross-border platform tier, Hillhouse Capital Group and GGV Capital exemplify archetypes with regional headquarters strategies and dedicated local partnership networks. Tiger Global Management occupies a position on the speed-and-scale vector, competing through rapid deployment timelines across India and Australia. These three firms represent distinct competitive postures: healthcare technology specialization, early-stage ecosystem cultivation, and growth-capital velocity.
| Leading Market Players |
|---|
| Hillhouse Capital Group |
| GGV Capital |
| Qiming Venture Partners |
| East Ventures |
| General Atlantic |
| Tiger Global Management |
| Jungle Ventures |
| Monk's Hill Ventures |
| Alpha JWC Ventures |
| Others |
Value Chain & Pricing Dynamics
Horizontal platform consolidation across Singapore's fund administrator ecosystem anchors both supply positioning and fee-setting power for ASEAN-domiciled venture vehicles. The concentration of legal structuring specialists and compliance infrastructure in Marina Bay creates captive sourcing advantages that resist margin compression.
Pricing Analysis
Outcome-linked management fee structures dominate as LPs demand performance-aligned compensation rather than fixed two-and-twenty models. Three-tier pricing stratifies across mega-cap sovereign-backed funds, mid-market growth specialists, and micro-VC seed vehicles. Fee compression runs through the mid-market tier as corporate venture arms bypass traditional GP relationships. Early-stage funds face acute price sensitivity from angel syndicate platforms aggregating high-net-worth capital.
Supply Chain Analysis
Single-source vulnerability sits with Singapore's Variable Capital Company framework as the dominant fund domicile structure across Southeast Asia. Capital formation draws from Singapore, India, and Australia as primary LP jurisdictions. Regulatory restriction risk concentrates in cross-border data localization requirements from India's Digital Personal Data Protection Act and Indonesia's data sovereignty mandates. Distribution runs through institutional relationship networks rather than retail-adjacent channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific venture capital market sits in a technology-transition phase as tokenized fund interests and blockchain-based cap table management displace legacy paper-based secondary transaction workflows.
For Market Incumbents: To counter fee compression from corporate venture direct co-investment models, anchor defensive positioning through captive supply of specialized technical due diligence capacity in quantum computing and synthetic biology. Deepen vertical integration into Singapore's Variable Capital Company administrator ecosystem to control setup timelines and operational cost structures.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in Vietnam's Series B+ landscape offers white-space entry with first-mover positioning in Ho Chi Minh City's underpenetrated growth-stage ecosystem. Target Indonesia's second-tier cities for seed-stage velocity with dedicated local partnership networks. Pursue climate tech regulatory tailwinds from Singapore's Green Finance Action Plan as the primary go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in continuation fund structures and tokenized secondary transactions rather than traditional IPO or M&A routes. Long-term viability favors managers with cross-border platform operations and dedicated scientific advisory networks in computational biology. Watch AI infrastructure convergence with biotech as the inflection signal for crossover fund deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Fund Domicile Relocation to VCC Structure | Singapore's Variable Capital Company framework reduces setup timelines and operational costs for ASEAN vehicles. |
| Technical Due Diligence Network Buildout | Specialized scientific advisory capacity in quantum computing and synthetic biology differentiates frontier technology deployment. |
| Direct Co-Investment Right Origination | Japanese trading houses and Korean chaebol subsidiaries bypass traditional GP fee structures through strategic parent entities. |
| Tokenized Fund Interest Infrastructure | Blockchain-based cap table management compresses secondary market clearing timelines from quarters to weeks. |
| Climate Tech Vehicle Formation | Singapore's Green Finance Action Plan and Australia's Net Zero Economy Authority create mandated ESG allocation floors. |
Study Parameters
Independent corroboration across fund manager interviews, LP commitment data, and regulatory filing analysis underwrites the qualitative findings. Primary fieldwork engaged venture capital partners, fund administrators, sovereign wealth fund investment officers, and securities regulator policy leads across Singapore, India, Australia, and Vietnam. Secondary validation drew from SEBI Alternative Investment Fund registrations, MAS licensing disclosures, ASIC wholesale investor framework documentation, and ASEAN fund structuring precedent databases. Bottom-up deal flow analysis and top-down capital formation estimates were triangulated to anchor projections.
Comparable-period anchoring to historical vintage year performance and capital call patterns structured the forecast window across the analysis window. Segmentation dimensions modeled include investment stage, investor type, industry vertical, and funding size tier, with regulatory jurisdiction clustering as an additional venture-specific dimension. CAGRs were derived from trend extrapolation of capital deployment velocity and LP commitment growth trajectories. Industry-specific inputs incorporated sovereign wealth fund allocation shifts and corporate venture direct investment origination rates.
Inputs from regulatory filings and fund administrator disclosures were available through the study window; gaps in pre-IPO secondary transaction pricing introduce uncertainty bands around IRR calculations. Forecasts reflect assumptions about cross-border capital mobility and tax treaty stability that external macroeconomic or geopolitical shocks could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Micro VC Funds Market
Venture Capital
Crowdfunding Market
Venture Capital
United States Venture Capital Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
Impact Investing Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
Angel Funds Market
Venture Capital
Business Incubator Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
Micro Venture Capital VC Funds Market
Venture Capital
Europe Venture Capital Market
Venture Capital
Venture Capital Investment Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
North America Venture Capital Market
Venture Capital
Asia-Pacific Venture Capital Investment Market