
 LAMEA Venture Capital Investment Market | 2026-2036
LAMEA Venture Capital Investment Market Size, Share, and Industry Trends Forecast 2026-2036
LAMEA Venture Capital Investment Market Insights
Fintech is consolidating as the dominant end-use vertical across LAMEA venture portfolios, displacing traditional consumer goods allocations. TLcom Capital leverages its Lagos-Nairobi dual headquarters to anchor early-stage technology bets. Partech Africa sustains one of the region's largest dedicated fund structures. Novastar Ventures specializes in climate-adjacent agribusiness models across East Africa.
LAMEA venture capital investment denotes equity financing provided to private, high-growth companies across Latin America, Africa, and the Middle East, typically structured through limited partnership vehicles with ten-year fund lives and carried interest waterfalls. These investments serve as primary growth capital for technology commercialization, healthcare scale-up, and financial infrastructure buildout in underbanked economies. Growth-stage fintech deployments command the deepest capital pools, while seed-stage healthcare ventures record the fastest deployment velocity. Closed-ended funds dominate institutional capital commitment structures, though syndicate vehicles are gaining traction among high-net-worth participants seeking deal-by-deal exposure.
South Africa's FSCA, Nigeria's SEC, and the UAE's FSRA each enforce distinct alternative investment fund licensing regimes that dictate cross-border capital mobility and local sponsor requirements. Egypt's FRA recently introduced venture capital-specific exemptions that reduce minimum capital thresholds for fund managers. Stakeholders must monitor regulatory divergence between francophone and anglophone African jurisdictions when structuring pan-regional feeder vehicles.
Market Dynamics
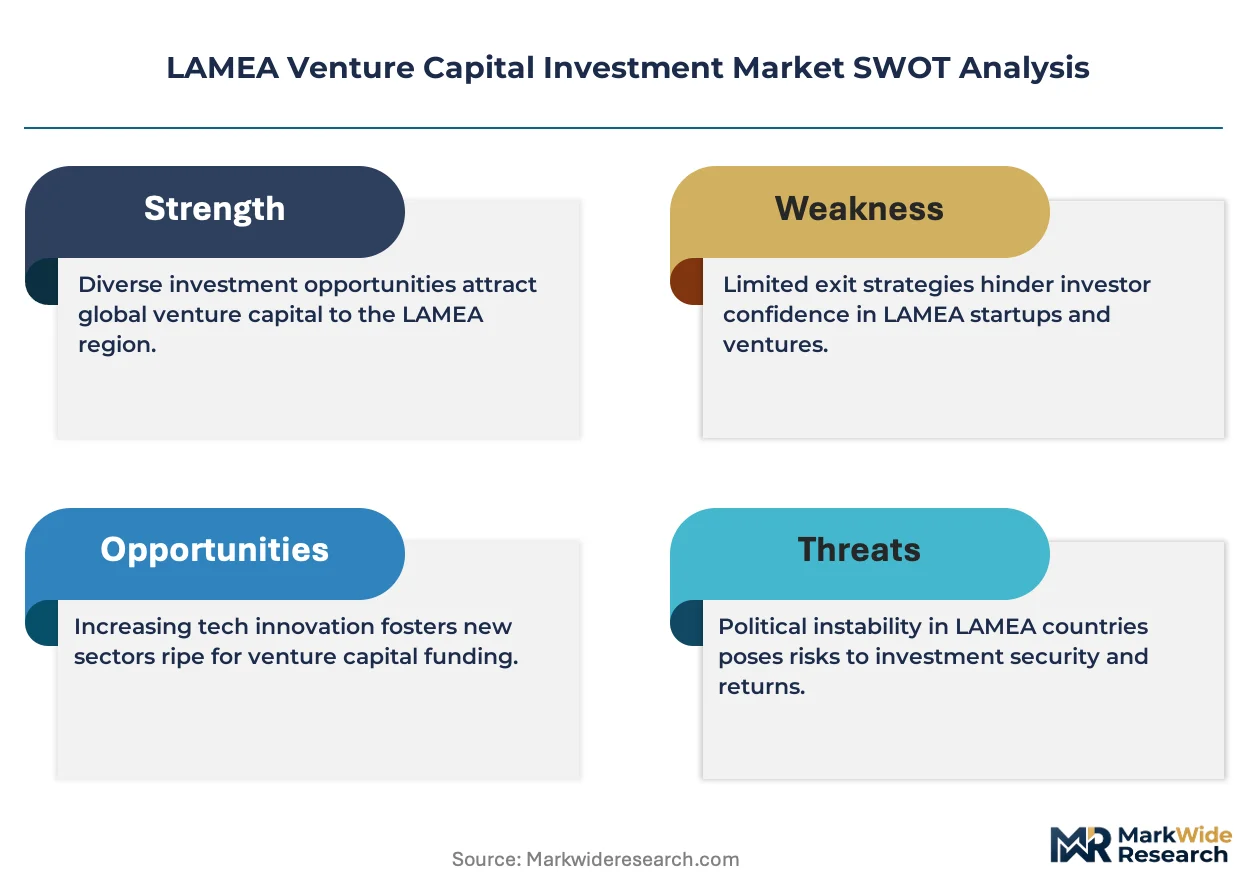
Capital allocation across LAMEA venture markets is concentrating around regulatory arbitrage opportunities, where fund managers exploit divergent licensing frameworks to optimize fund domicile and deployment velocity.
Growth Catalysts
- UAE FSRA licensing framework:The Abu Dhabi Global Market's streamlined alternative investment fund regime attracts managers seeking passporting rights across Gulf Cooperation Council jurisdictions.
- Mobile money infrastructure:East Africa's mature agent networks enable fintech ventures to acquire customers at sub-dollar unit economics, compressing payback periods for seed-stage investors.
- Cairo-Lagos-Nairobi corridor:This geographic triangle generates the highest density of Series A rounds, with local general partners leveraging operational presence to source proprietary deal flow.
Market Restraints
- Currency mismatch risk:Dollar-denominated fund structures face mark-to-market volatility when portfolio companies report in naira, rand, or Egyptian pounds.
- Exit pathway scarcity:The absence of developed secondary markets and limited IPO activity across Johannesburg, Lagos, and Cairo stock exchanges traps capital in illiquid positions.
- Local sponsor requirements:Nigeria's SEC mandates domestic fund management partnerships, forcing foreign general partners into joint venture structures that dilute governance control.
Strategic Opportunities
- Egypt FRA venture exemptions:Reduced minimum capital thresholds for fund managers unlock retail capital participation previously restricted to institutional limited partners.
- Climate-smart agriculture:Blended finance structures combining development finance institution capital with commercial venture returns address smallholder productivity gaps across Kenya and Ethiopia.
- Embedded finance integration:Convergence of banking-as-a-service APIs with vertical software platforms enables non-financial enterprises to originate credit products.
Industry Challenges
- Technical due diligence capacity:The scarcity of engineers capable of evaluating machine learning infrastructure at seed-stage ventures forces reliance on external technical advisors, elongating investment committees.
- Cross-border tax treaty fragmentation:Inconsistent double taxation agreements between francophone and anglophone African states complicate holding company structures for pan-regional portfolio companies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LAMEA Venture Capital Investment Market |
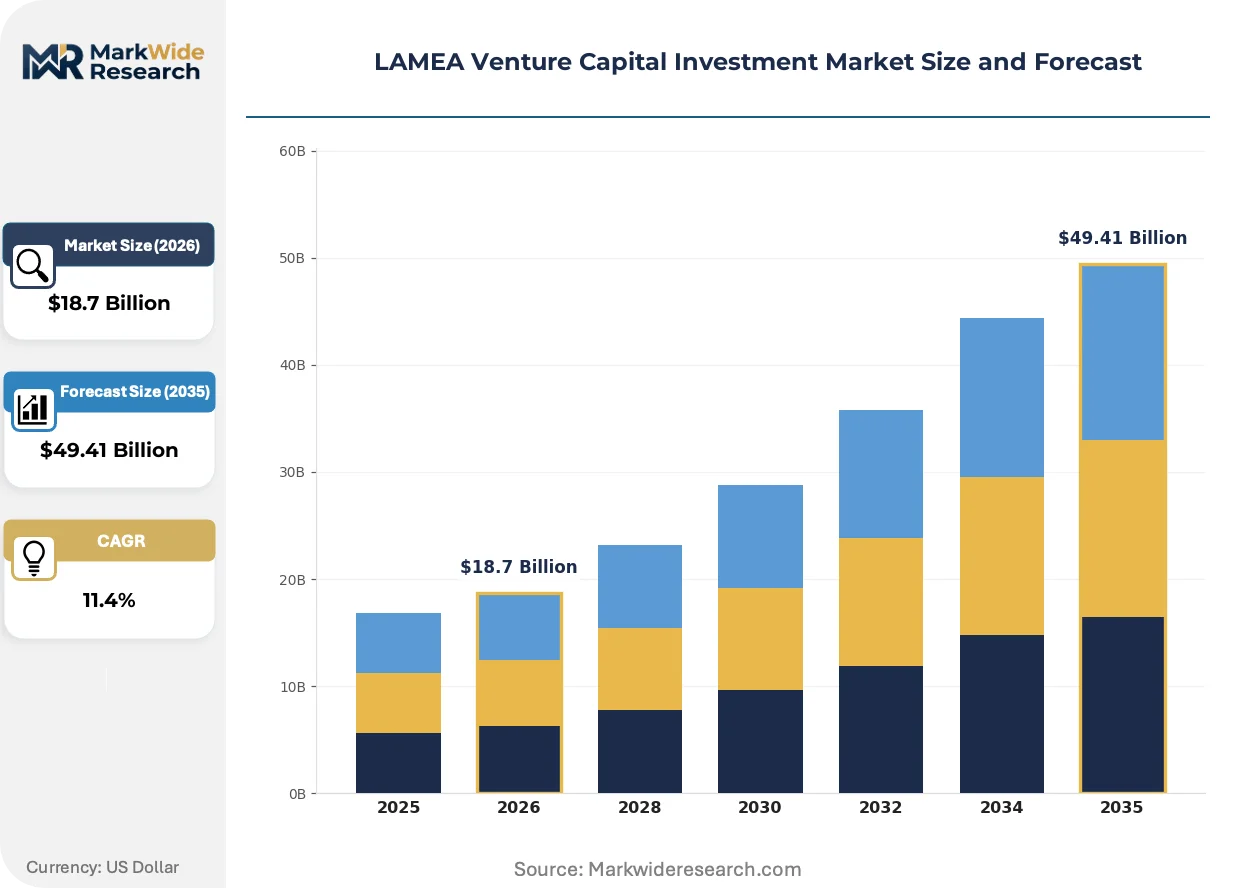
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed Stage, Early Stage, Growth Stage, Late Stage Industry Vertical: Technology, Healthcare, FinTech, Consumer Goods Fund Structure: Closed-Ended Funds, Open-Ended Funds, Fund of Funds, Syndicate Investor Type: Institutional Investors, High-Net-Worth Individuals, Family Offices, Corporates |
| Companies Covered | Partech Africa, 500 Global, TLcom Capital, Knife Capital, Launch Africa, Verod Capital, Novastar Ventures, E4E Africa, Savannah Fund, Others |
| Regions Covered | LAMEA: Brazil, Mexico, Argentina, Saudi Arabia, UAE, South Africa, Nigeria, Egypt, Rest of LAMEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LAMEA Venture Capital Investment Market Trends and Innovations
Blockchain-based capital formation mechanisms are reshaping how LAMEA ventures access growth financing, with tokenized securities and smart contract-enabled cap tables reducing administrative overhead for cross-border shareholder registries.
Decentralized finance protocols are decentralizing venture capital access for LAMEA startups by enabling programmable investment vehicles that automate capital calls and distribution waterfalls. Early-stage fintech founders in Nigeria and Kenya are adopting these structures to tap diaspora investor pools without traditional fund administrator overhead. The structural consequence is a compression in minimum viable fund sizes, allowing specialist managers to launch sub-fifteen-million-dollar vehicles profitably.
South Africa's FSCA recently introduced conduct standards for retail-facing alternative investment funds, requiring enhanced disclosure of fee structures and performance benchmarking. The regulation forces fund managers to standardize reporting formats previously customized per limited partner. Growth-stage healthcare ventures with South African exposure are restructuring side letter provisions to comply with these transparency mandates.
Institutional limited partners are shortening due diligence cycles by mandating pre-negotiated term sheet templates and standardized governance rights across their LAMEA venture commitments. This behavioral shift displaces bespoke negotiation processes that previously consumed six to nine months per close. Sovereign wealth funds from the Gulf Cooperation Council are driving this standardization most aggressively in their Cairo and Lagos deployments.
LAMEA Venture Capital Investment Market Segmentation
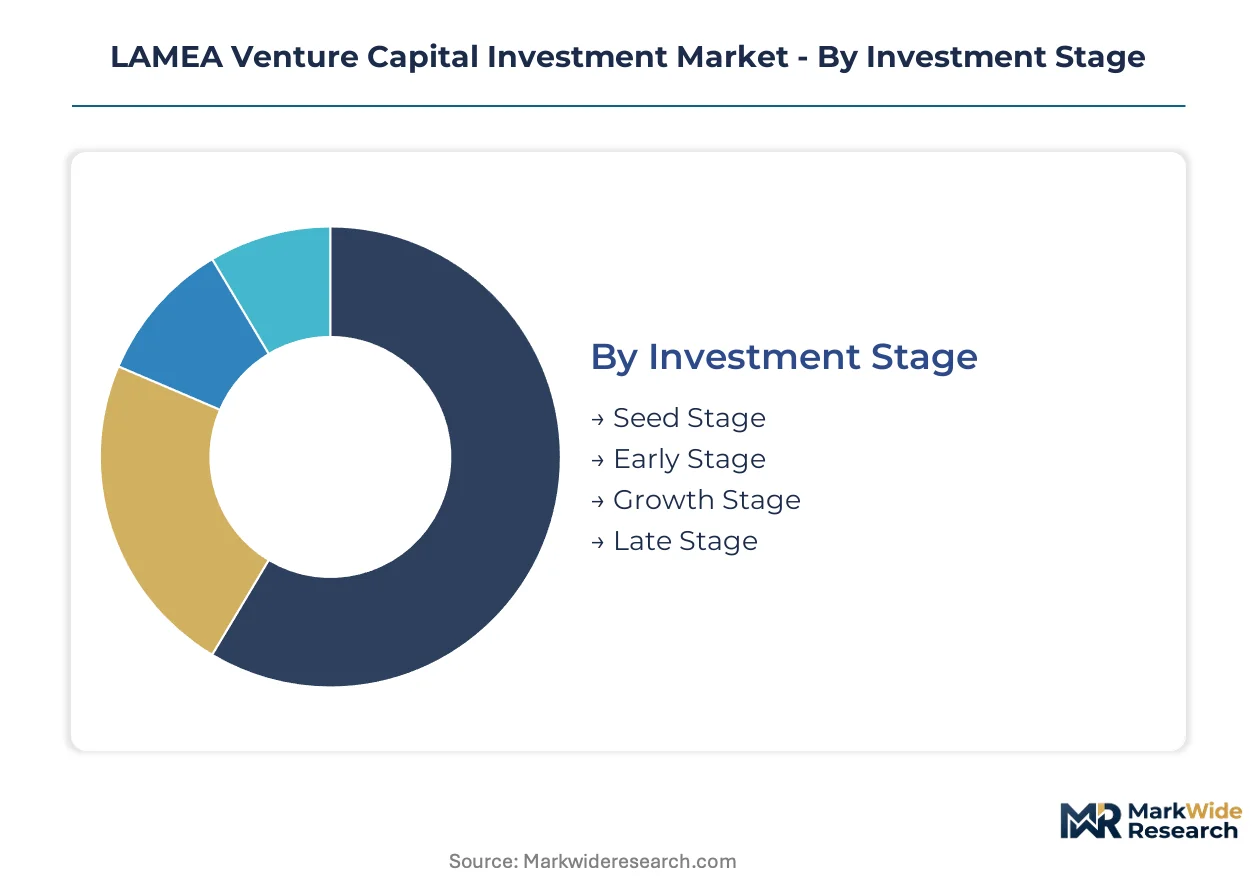
LAMEA venture capital segmentation reveals how capital deployment strategies diverge across risk-return profiles and regulatory constraints. Fund managers structure vehicles around investor liquidity preferences and local licensing requirements. Understanding these segment boundaries enables precise allocation timing across Cairo, Lagos, and Nairobi deal flow corridors.
Investment Stage:
Technology maturation curves dictate capital intensity and governance rights at each financing layer.
- Seed Stage:Initial equity injections of under two million dollars finance product development and team expansion. Egyptian software ventures attract the densest seed-stage deployment velocity as Cairo's technical talent pools deepen. Regulatory sandboxes in Nigeria and Kenya compress time-to-first-revenue for fintech prototypes.
- Early Stage:Series A and B rounds scale customer acquisition and operational infrastructure. Lagos-Nairobi corridor companies command premium valuations due to mobile money integration capabilities. Local general partners leverage operational presence to source proprietary deal flow before foreign entrants.
- Growth Stage:Capital pools deepen for market expansion and acquisition financing. Regional champions in South Africa and UAE attract sovereign wealth fund commitments.
- Late Stage:Pre-IPO and secondary transactions prepare ventures for public market exits. Johannesburg Stock Exchange listings remain the primary liquidity pathway.
Growth Stage leads on scale; Seed Stage leads on momentum.
Industry Vertical:
End-use demand concentration shapes portfolio construction and technical due diligence requirements.
- FinTech:Digital payments, lending infrastructure, and banking-as-a-service platforms dominate LAMEA venture allocations. M-Pesa agent networks across Kenya and Tanzania enable sub-dollar customer acquisition economics. Nigeria's SEC crowdfunding framework accelerates retail capital participation in payment ventures.
- Technology:Enterprise software and cloud infrastructure attract B2B-focused fund managers. South African developers command premium valuations due to mature technical ecosystems.
- Healthcare:Telemedicine platforms and pharmaceutical distribution networks address underbanked medical access. East African markets show steepest expansion trajectory for seed-stage health ventures.
- Consumer Goods:E-commerce enablement and last-mile logistics attract capital seeking offline-to-online conversion. Egyptian and Nigerian urban corridors concentrate demand.
FinTech leads on scale; Healthcare leads on momentum.
Fund Structure:
Vehicle architecture determines capital mobility, fee structures, and investor eligibility thresholds.
- Closed-Ended Funds:Ten-year limited partnership vehicles with fixed capital commitments dominate institutional allocations. South Africa's FSCA licensing framework mandates local sponsor partnerships for foreign general partners. These structures optimize carried interest waterfalls and governance control for Cairo and Lagos deployments.
- Open-Ended Funds:Continuous subscription vehicles accommodate high-net-worth investors seeking deal-by-deal liquidity. UAE FSRA passporting rights enable cross-border capital mobility across Gulf Cooperation Council jurisdictions.
- Fund of Funds:Diversified exposure vehicles allocate across multiple underlying managers. Development finance institutions favor these structures for pan-African geographic spread.
- Syndicate:Deal-specific vehicles aggregate high-net-worth capital for individual transactions. Blockchain-enabled smart contracts reduce administrative overhead for diaspora investor participation.
Closed-Ended Funds lead on scale; Syndicate leads on momentum.
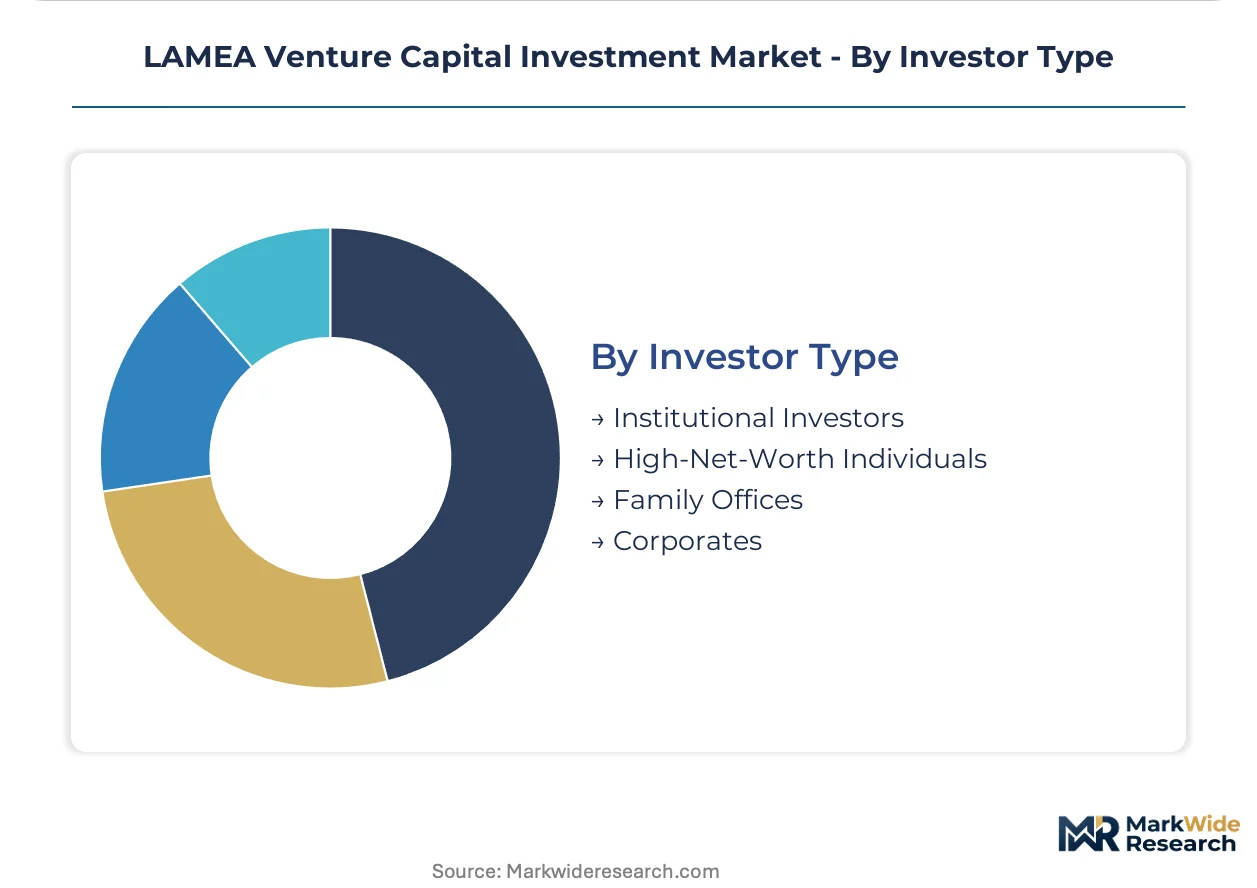
Investor Type:
Capital source diversity influences term sheet negotiation dynamics and holding period expectations.
- Institutional Investors:Pension funds, endowments, and development finance institutions commit the deepest capital pools. Nigeria's SEC mandates domestic fund management partnerships that dilute foreign general partner governance control. These limited partners drive standardization of reporting formats and governance rights.
- High-Net-Worth Individuals:Family capital and entrepreneur wealth seek direct deal exposure. Egypt's FRA venture exemptions reduce minimum thresholds for retail participation.
- Family Offices:Multi-generational wealth vehicles favor patient capital with extended holding periods. Gulf Cooperation Council family offices concentrate deployments in UAE and Egyptian ventures.
- Corporates:Strategic investors pursue technology acquisition and market entry objectives. South African financial services groups anchor fintech venture programs.
Institutional Investors lead on scale; High-Net-Worth Individuals lead on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Cairo-Lagos-Nairobi corridor concentrates the densest venture deployment velocity across LAMEA. This geographic triangle generates the highest density of Series A rounds as local general partners leverage operational presence to source proprietary deal flow. Regulatory divergence between francophone and anglophone jurisdictions shapes fund domicile decisions.
Nigeria
Lagos anchors West African fintech capital formation with M-Pesa-style agent networks enabling sub-dollar customer acquisition. The country's SEC crowdfunding regulations accelerate retail participation in payment ventures. Yaba technology cluster houses the densest concentration of seed-stage software ventures attracting local and diaspora capital.
South Africa
Johannesburg and Cape Town command premium valuations for enterprise software due to mature technical ecosystems. The FSCA licensing framework for alternative investment funds mandates local sponsor partnerships for foreign general partners. Sandton financial district concentrates growth-stage healthcare ventures restructuring side letters for transparency compliance.
Egypt
Cairo's technical talent pools deepen seed-stage deployment velocity for software ventures across the Nile Delta corridor. The FRA recently introduced venture capital-specific exemptions reducing minimum capital thresholds for fund managers. New Cairo and 6th of October City industrial zones attract climate-smart agriculture ventures with blended finance structures.
Kenya
Nairobi's mobile money infrastructure enables fintech ventures to compress payback periods for seed-stage investors. Regulatory sandboxes administered by the central bank accelerate time-to-first-revenue for fintech prototypes. Konza Technopolis anchors East Africa's deepest pool of technical due diligence capacity for machine learning ventures.
United Arab Emirates
Abu Dhabi Global Market attracts managers seeking passporting rights across Gulf Cooperation Council jurisdictions through streamlined alternative investment fund regimes. Dubai International Financial Centre concentrates sovereign wealth fund commitments for growth-stage regional champions. Sharjah and Ras Al Khaimah free zones enable syndicate vehicles for diaspora investor participation.
LAMEA Venture Capital Investment Market Competitive Landscape
Portfolio diversification dominates the current landscape as fund managers construct pan-regional exposure across Cairo, Lagos, and Nairobi corridors. The market structures around three tiers: Africa-dedicated specialists with operational headquarters in Lagos or Nairobi, emerging market generalists with LAMEA allocation mandates, and development finance institution-backed vehicles with blended return requirements. Strategic archetypes include dual-headquartered operators leveraging local presence, single-market specialists capturing regulatory arbitrage, and fund-of-funds vehicles offering diversified geographic exposure. Competitive intensity concentrates on proprietary deal flow generation and regulatory licensing velocity.
Among Africa-dedicated specialists, Partech Africa and TLcom Capital exemplify the dual-headquartered archetype with operational presence across multiple jurisdictions. Novastar Ventures occupies a position within the climate-adjacent agribusiness specialization tier. These three anchors represent distinct strategic positioning: Partech Africa sustains one of the region's largest dedicated fund structures, TLcom Capital leverages its Lagos-Nairobi presence for early-stage technology bets, and Novastar Ventures concentrates on productivity gaps across East African smallholder markets.
| Leading Market Players |
|---|
| Partech Africa |
| 500 Global |
| TLcom Capital |
| Knife Capital |
| Launch Africa |
| Verod Capital |
| Novastar Ventures |
| E4E Africa |
| Savannah Fund |
| Others |
Pricing and Supply Chain Analysis
US dollar index volatility cascades through LAMEA venture fund economics, compressing management fee realizations for naira-denominated operations while elevating carried interest thresholds for rand-based portfolio companies. This currency-driven cost structure forces fund managers to tier capital commitment minimums across Lagos, Nairobi, and Cairo investor pools.
Pricing Analysis
Input-cost pass-through from regulatory compliance expenses reshapes fee structures across LAMEA venture vehicles. Closed-ended funds operate on a two-twenty model with premium tiers for sub-fifteen-million-dollar specialist vehicles commanding higher management fees. Standard fund structures face pricing pressure from blockchain-enabled syndicate vehicles that automate administrative overhead. Institutional limited partners show lowest price sensitivity due to governance standardization mandates, while high-net-worth retail participants through Egypt's FRA exemptions exhibit highest sensitivity to minimum commitment thresholds.
Supply Chain Analysis
Nigeria's SEC local sponsor mandates and South Africa's FSCA domestic partnership requirements are reshaping general partner sourcing strategies toward joint venture structures. Capital formation concentrates in UAE, Nigeria, and Kenya as primary fund domicile jurisdictions. Technical due diligence capacity depends on engineer availability in Cairo and Nairobi talent pools. Single-source vulnerability sits with diaspora investor channels through blockchain-enabled syndicates. Distribution runs through sovereign wealth fund commitments and development finance institution allocations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LAMEA venture capital operates as a late-cycle quality story where institutional limited partners now prioritize governance standardization and transparency compliance over raw return multiples. This demand shift toward premium fund administration specifications favors managers with pre-negotiated term sheet templates and FSCA-aligned reporting infrastructure.
For Market Incumbents: Cement proprietary deal flow advantages through operational headquarters in the Cairo-Lagos-Nairobi corridor before foreign entrants establish local presence. Deepen technical due diligence capacity by anchoring machine learning evaluation teams in Nairobi's Konza Technopolis. Defend against blockchain-enabled syndicate disruption by standardizing side letter provisions for retail-facing transparency mandates.
For New Entrants and Emerging Players: Diaspora investor platforms represent the most penetrable channel for sub-fifteen-million-dollar fund launches without traditional administrator overhead. Target Egypt's FRA venture exemptions for retail capital participation previously restricted to institutional limited partners. Enter through climate-smart agriculture verticals in Ethiopian and Kenyan smallholder markets where blended finance structures reduce competitive intensity.
For Investors and Strategic Acquirers: Asymmetric upside sits with dual-headquartered specialists possessing Lagos-Nairobi operational presence and established regulatory licensing velocity. Long-term viability centers on managers navigating divergent francophone and anglophone African tax treaty frameworks. Watch for inflection signals in secondary market development across Johannesburg Stock Exchange listings as liquidity pathway indicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Licensing Velocity | UAE FSRA passporting rights enable cross-border capital mobility across Gulf Cooperation Council jurisdictions. |
| Dual Headquarters Establishment | Lagos-Nairobi operational presence secures proprietary Series A deal flow before foreign general partner entry. |
| Blockchain-Enabled Syndicate Launch | Smart contract automation reduces administrative overhead for diaspora investor participation in seed-stage vehicles. |
| Climate-Smart Agriculture Vertical | Blended finance structures combining DFI capital with commercial returns address East African smallholder productivity gaps. |
| Technical Due Diligence Capacity Buildout | Konza Technopolis engineering pools evaluate machine learning infrastructure for Cairo and Nairobi portfolio companies. |
Research Methodology
Coverage spans Latin America, Africa, and the Middle East, with primary inputs from each region's venture capital corridors. The study combines primary interviews with fund managers, limited partner allocation heads, regulatory affairs specialists, and portfolio company founders with secondary validation from SEC filings, FSCA licensing registries, and sovereign wealth fund disclosure documents. Bottom-up deployment velocity analysis across Cairo, Lagos, and Nairobi triangulates against top-down fund formation data from ADGM and DIFC regulatory filings.
Granularity-level modeling operates at investment stage, industry vertical, fund structure, and investor type dimensions with geographic disaggregation across Nigeria, South Africa, Egypt, Kenya, and UAE regulatory clusters. CAGRs derive from deployment velocity trajectories and capital commitment pipeline analysis across the projection horizon. Forecast inputs incorporate mobile money penetration rates, crowdfunding regulatory exemption scopes, and diaspora remittance channel activation.
The model assumes a particular technology adoption path for blockchain-enabled capital formation mechanisms; alternative pathways for decentralized finance protocol integration would alter the outlook for syndicate vehicle economics and minimum viable fund size compression. Forecasts reflect assumptions regarding regulatory harmonization velocity between francophone and anglophone jurisdictions and sovereign wealth fund allocation persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
Crowdfunding Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
Impact Investing Market
Venture Capital
Micro VC Funds Market
Venture Capital
Angel Funds Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
North America Venture Capital Market
Venture Capital
Europe Venture Capital Market
Venture Capital
United States Venture Capital Market
Venture Capital
Venture Capital Investment Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
Micro Venture Capital VC Funds Market
Venture Capital
Business Incubator Market
Venture Capital
Asia Pacific Venture Capital Market
Venture Capital
Asia-Pacific Venture Capital Investment Market