
 Europe Venture Capital Market | 2026-2036
Europe Venture Capital Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Venture Capital Market Foresight
Artificial intelligence infrastructure is narrowing the gap between seed-stage experimentation and scalable enterprise deployment across European startups. Eurazeo leverages its multi-stage platform to bridge growth financing for AI-native companies from Paris to Berlin. Index Ventures anchors deep tech deal flow through dedicated quantum computing and semiconductor practices. Balderton Capital specializes in B2B software, competing aggressively for enterprise automation founders against US-based rivals.
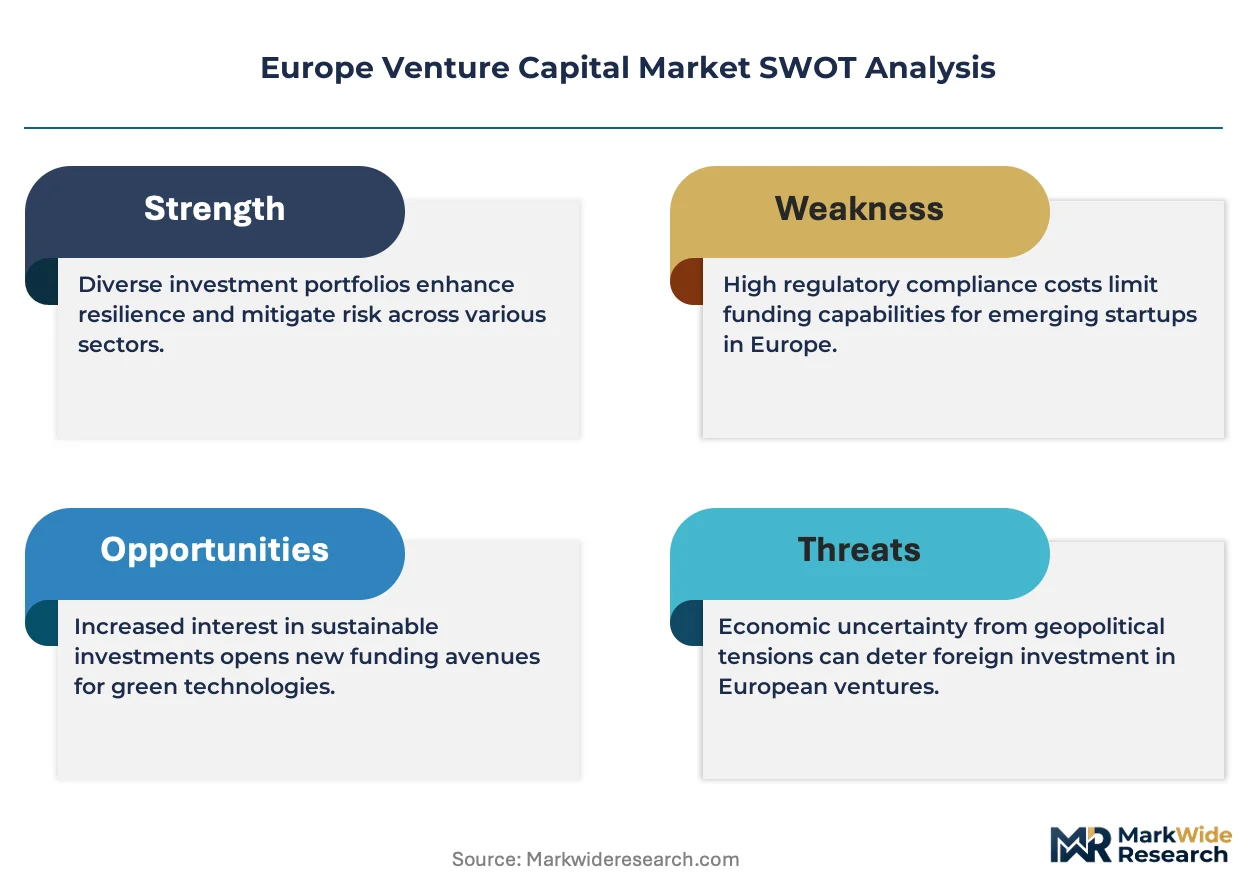
Europe venture capital denotes equity financing provided by professional investors to early-stage, high-growth private companies, typically structured through limited partnerships with ten-to-twelve-year fund lives and carried-interest compensation for general partners. Investment stage segmentation reveals growth-stage deals commanding the largest capital allocations as managers chase proven unit economics over speculative seed bets. Industry vertical segmentation shows fintech retaining the deepest LP commitment pools despite healthtech posting faster deployment velocity across Nordic ecosystems. Fund structure segmentation indicates hybrid vehicles gaining favor as investors blend venture returns with downside protection through debt-like instruments.
The European Securities and Markets Authority enforces AIFMD transparency requirements that shape cross-border fundraising compliance for managers operating from Luxembourg and Dublin. ESG disclosure standards under CSRD and the EU Green Deal taxonomy now filter eligible portfolio companies, restricting capital access to climate-adverse business models. Stakeholders must monitor how MiFID III revisions alter retail investor participation in venture fund structures.
Market Dynamics
CSRD disclosure mandates and the EU Green Deal taxonomy are redirecting institutional capital toward sustainability-aligned portfolios, compressing fundraising timelines for climate-adverse business models while elevating deep tech startups in carbon removal and circular economy sectors.
Growth Catalysts
- EU Green Deal capital redirection:The taxonomy's technical screening criteria filter eligible portfolio companies, channeling limited partner commitments toward ventures with measurable decarbonization pathways.
- Deep tech maturation:Quantum computing and semiconductor startups in the Netherlands and Germany are attracting dedicated fund allocations as unit economics prove scalable beyond laboratory validation.
- Founder relocation patterns:Post-Brexit migration from London to Paris, Berlin, and Amsterdam is concentrating deal flow in jurisdictions offering harmonized EU market access and streamlined AIFMD compliance.
Market Restraints
- Ten-to-twelve-year fund life illiquidity:Limited partners face extended capital lock-up periods that constrain portfolio rebalancing during monetary tightening cycles.
- AIFMD cross-border friction:Divergent national interpretations of transparency requirements between Luxembourg and Dublin create fundraising compliance overhead for multi-jurisdiction managers.
- Seed-stage valuation compression:Speculative pre-revenue bets face heightened scrutiny as institutional investors prioritize proven unit economics over TAM-based projections.
Strategic Opportunities
- Nordic healthtech acceleration:Sweden and Denmark post faster deployment velocity than continental averages, with specialized LP pools targeting digital therapeutics and precision medicine infrastructure.
- Hybrid vehicle structures:Investors are blending venture returns with downside protection through debt-like instruments, expanding addressable LP segments beyond traditional risk-tolerant endowments.
- MiFID III retail participation:Pending revisions to EU retail investor access rules could unlock mass-affluent capital for venture fund structures previously restricted to institutional commitments.
Industry Challenges
- Technical talent scarcity:Quantum computing and semiconductor design expertise concentrates in ETH Zurich, TU Munich, and TU Delft clusters, creating bidding wars for specialized engineering teams.
- CSRD compliance timeline compression:Portfolio companies face accelerated ESG data infrastructure buildouts to meet disclosure deadlines, diverting management bandwidth from core product development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Venture Capital Market |
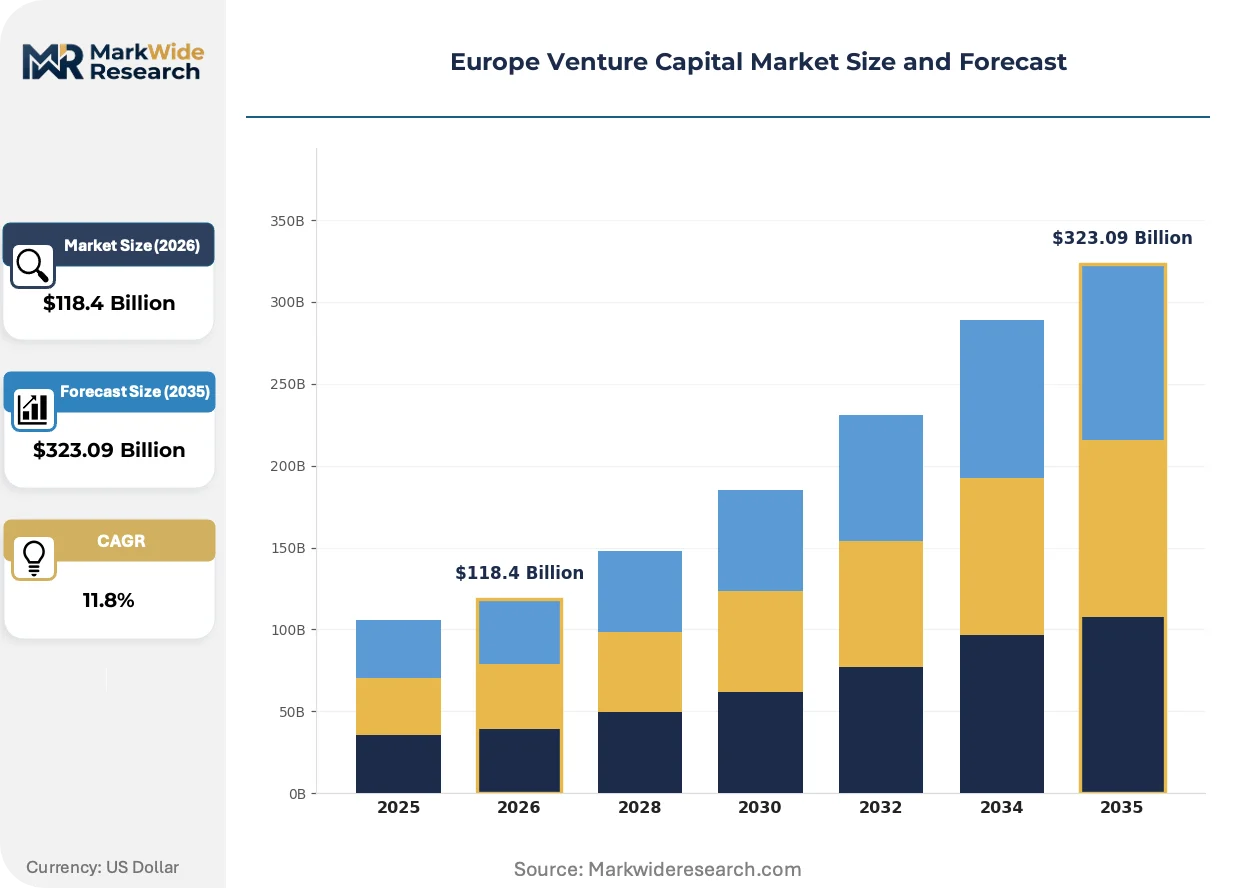
| Market Size in 2026 | $118.4 Billion |
| Market Size in 2035 | $323.09 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Investment Stage: Seed, Early Stage, Growth Stage, Late Stage Industry Vertical: Fintech, Healthtech, Edtech, Agtech Fund Structure: Private Equity, Hedge Fund, Hybrid Fund, Fund of Funds Investor Type: Angel Investors, Institutional Investors, Family Offices, Corporate Investors |
| Companies Covered | Eurazeo, Global Founders Capital, HV Capital, Sequoia Capital, Index Ventures, Accel, Balderton Capital, Seedcamp, Octopus Ventures, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Venture Capital Market Shifts & Advancements
Artificial intelligence infrastructure is collapsing the gap between experimental seed-stage prototypes and enterprise-grade deployment, while regulatory frameworks harden around sustainability disclosure and algorithmic accountability.
GPU clusters and specialized inference hardware are migrating from cloud-rental models toward captive infrastructure ownership as AI-native startups seek predictable compute economics. German and French founders building large language model applications are prioritizing dedicated server deployments over variable AWS pricing. This migration from opex-heavy scaling to capex-controlled expansion is reshaping growth-stage capital requirements and facility strategies.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on high-risk AI applications in healthcare and financial services. Portfolio companies deploying automated credit scoring or diagnostic algorithms must now budget for notified body engagement and technical documentation audits. Healthtech ventures in France and the Netherlands are restructuring product roadmaps to secure CE marking under the new AI-specific annexes before Series B fundraising.
Institutional limited partners are embedding sustainability-linked side letters into fund documentation, tying carried interest to portfolio-level carbon intensity reduction targets. Danish and Swedish pension funds lead this contractual innovation, pressuring general partners to build climate KPI tracking infrastructure from first close. This behavioral shift is filtering manager selection toward teams with embedded ESG data capabilities and science-based target-setting methodologies.
Europe Venture Capital Market Segmentation
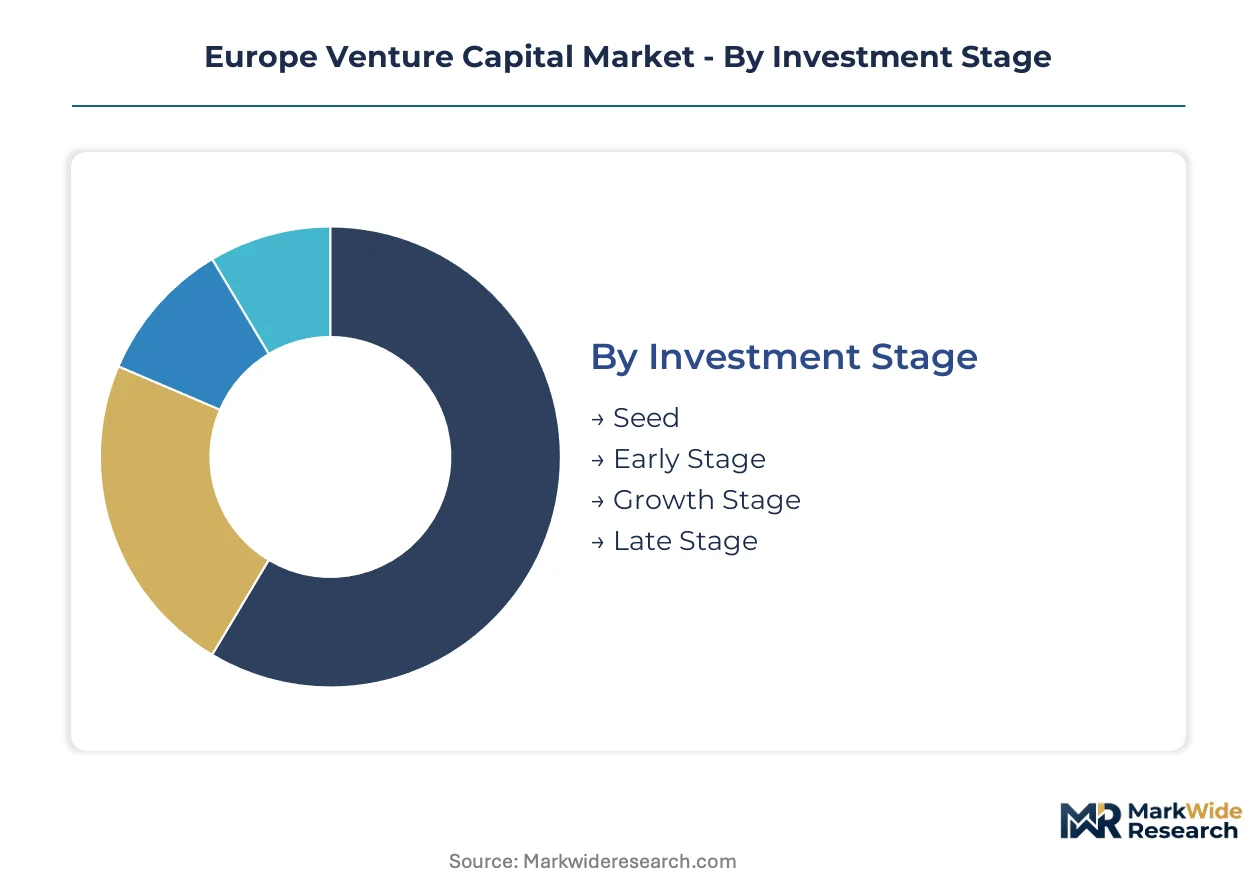
Investment stage, industry vertical, fund structure, and investor type collectively determine capital allocation efficiency and risk-return profiles across European venture markets. Each segmentation dimension reveals distinct liquidity timelines, regulatory exposure, and portfolio construction strategies that general partners must navigate.
Investment Stage:
Capital deployment intensity varies across the company maturity spectrum, from pre-revenue experimentation to pre-IPO scaling.
- Seed:First institutional financing rounds typically range from €500K to €3M, targeting product-market fit validation in climate tech and AI infrastructure. Founders in Berlin and Paris face heightened scrutiny on TAM-based projections as LPs prioritize capital preservation.
- Early Stage:Series A and B rounds concentrate in Dutch semiconductor design and German quantum computing ventures where laboratory validation has achieved repeatable unit economics. Amsterdam-based deep tech startups attract dedicated allocations from multi-stage platforms.
- Growth Stage:Expansion capital for proven revenue models.
- Late Stage:Pre-IPO and secondary transactions for mature ventures.
Established volume favors Growth Stage; emerging adoption favors Seed.
Industry Vertical:
Regulatory tailwinds and technical talent availability concentrate deal flow into specific sectors across Nordic and continental ecosystems.
- Fintech:Embedded banking and B2B payment infrastructure retains the deepest LP commitment pools despite valuation corrections. French ventures leveraging EU open banking directives attract growth-stage capital from Paris-based managers.
- Healthtech:Digital therapeutics and precision medicine infrastructure post faster deployment velocity than continental averages. Swedish and Danish startups target CE marking under MDR and EU AI Act annexes before Series B fundraising.
- Edtech:Workforce reskilling platforms aligned with EU Green Deal retraining mandates.
- Agtech:Carbon removal and circular economy ventures benefiting from CSRD disclosure-driven capital redirection.
Capital concentration remains heaviest in Fintech; Healthtech is climbing the fastest.
Fund Structure:
Vehicle architecture determines investor eligibility, fee structures, and liquidity provisions across Luxembourg and Dublin domiciles.
- Private Equity:Buyout and growth equity strategies with longer hold periods.
- Hedge Fund:Liquid alternatives with venture exposure through secondary transactions.
- Hybrid Fund:Blended vehicles combining equity participation with debt-like instruments are gaining favor as investors seek downside protection beyond traditional endowment risk profiles. These structures expand addressable LP segments across German insurance allocators.
- Fund of Funds:Diversified exposure through manager selection rather than direct company investment.
LP demand concentrates in Hybrid Fund structures; Fund of Funds faces allocation pressure from direct co-investment preferences.
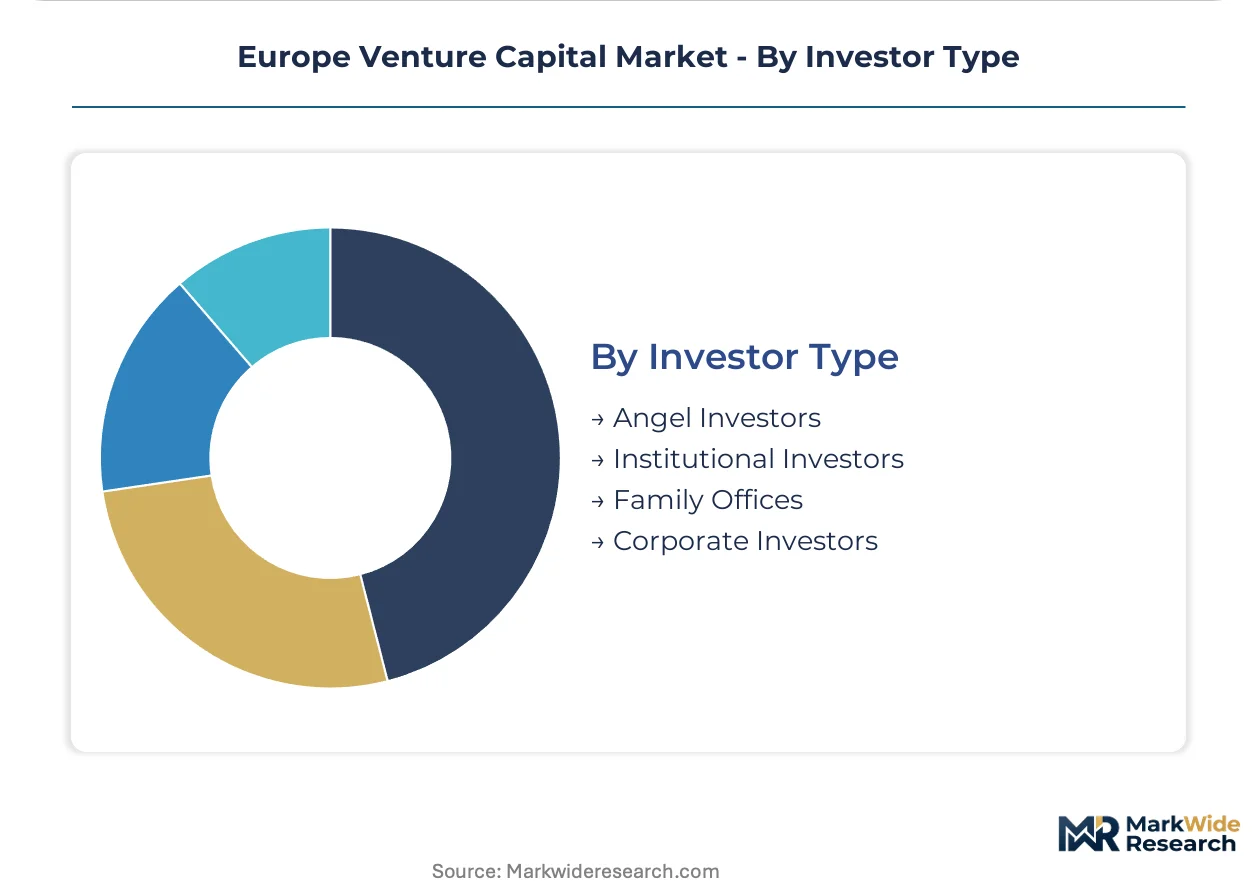
Investor Type:
Capital source diversity shapes governance rights, investment horizons, and value-add expectations throughout fund lifecycles.
- Angel Investors:Individual high-net-worth backers providing pre-seed capital and founder mentorship. German serial entrepreneurs in Munich and Hamburg clusters dominate technical due diligence for deep tech opportunities.
- Institutional Investors:Pension funds and insurance companies embedding sustainability-linked side letters into fund documentation. Danish and Swedish LPs lead contractual innovation tying carried interest to portfolio carbon intensity targets.
- Family Offices:Multi-generational wealth deploying patient capital with flexible liquidity terms.
- Corporate Investors:Strategic CVC arms seeking technology access and commercial partnerships.
Governance influence concentrates with Institutional Investors; deployment velocity accelerates through Corporate Investors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German venture capital flows into Dutch semiconductor startups and French AI infrastructure ventures, creating cross-border deal corridors that bypass London's post-Brexit friction. Institutional limited partners in Copenhagen and Stockholm channel commitments toward Paris and Berlin managers seeking harmonized EU market access.
Germany
Quantum computing startups in Munich and Berlin attract dedicated growth-stage allocations as laboratory validation achieves repeatable unit economics. The national implementation of EU AI Act conformity assessment procedures shapes healthtech product roadmaps before Series B fundraising. TU Munich and TU Delft clusters concentrate technical talent for semiconductor design, intensifying bidding wars for specialized engineering teams across Bavaria and Baden-Württemberg.
France
AI-native founders building large language model applications prioritize captive GPU infrastructure over variable cloud pricing, reshaping growth-stage capital requirements. Open banking directives under PSD2 channel fintech deal flow toward embedded banking ventures in Paris. Station F and Paris-Saclay clusters anchor multi-stage platform deployment from Eurazeo and Index Ventures, bridging seed experimentation to enterprise deployment.
Netherlands
Amsterdam-based deep tech startups attract dedicated allocations from multi-stage platforms as AIFMD compliance costs concentrate fundraising in Dublin and Luxembourg domiciles. The national semiconductor strategy aligns with EU Chips Act funding, accelerating ASML-adjacent venture formation in Eindhoven. TU Delft engineering pipelines feed specialized hardware ventures targeting carbon removal and circular economy applications.
United Kingdom
Post-Brexit founder migration compresses London's seed-stage deal volume as relocation to EU jurisdictions accelerates. FCA regulatory divergence from ESMA frameworks creates fundraising friction for managers retaining UK domiciles while serving continental LPs. Cambridge and Oxford clusters retain technical talent for biotechnology ventures, though Series B capital increasingly sources from Paris and Berlin rather than London growth equity.
Sweden
Digital therapeutics and precision medicine infrastructure post faster deployment velocity than continental averages, drawing specialized LP pools from Danish pension funds. MDR and EU AI Act CE marking requirements compress healthtech product development timelines before institutional fundraising. Stockholm's Kista Science City concentrates healthtech venture formation alongside enterprise software exits to strategic acquirers.
Europe Venture Capital Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where multi-stage platforms command growth-stage allocation while seed-focused specialists defend pre-revenue access. The vendor base organizes around three strategic archetypes: Paris-headquartered multi-stage generalists, London-anchored early-stage specialists, and sector-focused deep tech practitioners. Dominant competitive moves include sustainability-linked side letter embedding and hybrid fund structure innovation blending equity with debt-like instruments.
Within the multi-stage platform tier, Eurazeo and Index Ventures occupy positions bridging Paris-Berlin deal corridors, while Balderton Capital exemplifies the B2B software specialist archetype competing for enterprise automation founders. Sequoia Capital's European presence represents the transatlantic scale player archetype, anchoring late-stage allocation capacity that domestic European managers rarely match independently.
| Leading Market Players |
|---|
| Eurazeo |
| Global Founders Capital |
| HV Capital |
| Sequoia Capital |
| Index Ventures |
| Accel |
| Balderton Capital |
| Seedcamp |
| Octopus Ventures |
| Others |
Supply & Pricing Matrix
The Rhine-Alpine freight corridor's cost volatility shapes capital deployment economics across European venture markets, concentrating pricing power with Luxembourg-domiciled fund administrators while forcing Berlin and Paris managers to absorb downstream compliance premiums.
Pricing Analysis
Cost-plus contracts indexed to ECB reference rates dominate management fee structures across Luxembourg and Dublin fund vehicles. Three-tier pricing separates institutional limited partners from family offices and retail-eligible feeders, with CSRD disclosure mandates compressing margins for sub-scale managers. Pricing pressure stems from AIFMD compliance overhead as seed-stage general partners compete for diminishing allocator attention. Corporate venture capital arms exhibit lowest price sensitivity; independent first-time funds face acute fee compression.
Supply Chain Analysis
Tariff exposure between UK and EU jurisdictions dominates fundraising friction for London-anchored managers serving continental limited partners. Capital formation concentrates in Luxembourg, Dublin, and Amsterdam as fund domicile choices; technical talent pipelines feed from ETH Zurich, TU Munich, and TU Delft clusters. Single-source vulnerability rests on specialized legal and fund administration capacity in Luxembourg. Distribution runs through placement agent networks and direct sovereign wealth relationships across Nordic pension systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across regulatory jurisdictions and founder relocation patterns creates niche opportunities for specialized managers with embedded compliance infrastructure and deep tech domain expertise.
For Market Incumbents: Entrench market position through captive technical talent pipelines at TU Munich and TU Delft clusters, countering bidding wars that erode portfolio company operating margins. Prioritize sustainability-linked side letter standardization to preempt Danish and Swedish pension fund contractual innovation. Defensive consolidation through hybrid fund structure patenting protects against German insurance allocator encroachment.
For New Entrants and Emerging Players: Nordic healthtech acceleration in Sweden and Denmark represents the most penetrable entry point, with faster deployment velocity than continental averages and specialized limited partner pools seeking digital therapeutics exposure. Paris-based AI infrastructure ventures offer secondary entry as Eurazeo and Index Ventures concentrate on growth-stage bridge financing. Go-to-market leverage through embedded ESG data capabilities from first close differentiates against legacy general partners.
For Investors and Strategic Acquirers: Multi-stage platforms with harmonized EU market access and streamlined AIFMD compliance offer superior long-term viability across a five-to-ten year deployment horizon. Signal to monitor: MiFID III retail participation rule finalization as mass-affluent capital unlock indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Fund Structure Launch | Blending equity with debt-like instruments expands German insurance allocator access beyond traditional endowment risk profiles. |
| Sustainability-Linked Side Letter Standardization | Preemptive contractual innovation secures Danish and Swedish pension fund commitments before competitor adoption. |
| Technical Talent Pipeline Captivity | Direct ETH Zurich and TU Delft recruiting agreements secure quantum computing and semiconductor design expertise. |
| CSRD Compliance Infrastructure Buildout | Portfolio-level carbon intensity tracking satisfies EU Green Deal taxonomy filtering before disclosure deadline compression. |
| MiFID III Retail Channel Preparation | Mass-affluent vehicle structuring captures regulatory unlock ahead of continental competitor response. |
Research Methodology
The analysis maps seed-stage, early-stage, growth-stage, and late-stage investment segments, each validated through general partner interviews, limited partner allocation officers, fund administration executives, and regulatory compliance specialists. Primary fieldwork combined with secondary validation against AIFMD regulatory filings, ESMA transparency reports, and national venture capital association datasets. Bottom-up deal flow analysis and top-down allocator commitment tracking triangulate market sizing.
Assumptions held fixed include regulatory framework stability under CSRD and EU AI Act implementation timelines, while monetary policy trajectory and founder relocation velocity varied across sensitivity scenarios. Segmentation dimensions modeled encompass investment stage, industry vertical, fund structure, and investor type alongside geographic domicile clustering. CAGRs derived from historical deployment velocity and forward commitment pipeline analysis. Forecast inputs include limited partner rebalancing behavior and technical talent pipeline graduation rates.
Practitioners should monitor ECB rate trajectory, MiFID III final rule publication, and EU AI Act conformity assessment cost inflation for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Venture Capital
Crowdfunding Market
Venture Capital
Venture Capital Investment Market
Venture Capital
North America Venture Capital Market
Venture Capital
United States Venture Capital Market
Venture Capital
Equity Crowdfunding Market
Venture Capital
North America Venture Capital Investment Market
Venture Capital
Asia-Pacific Venture Capital Investment Market
Venture Capital
Global Art Crowdfunding Market
Venture Capital
Asia Pacific Venture Capital Market
Venture Capital
Micro VC Funds Market
Venture Capital
Middle East and Africa Venture Capital Market
Venture Capital
US Venture Capital Investment Market
Venture Capital
Business Incubator Market
Venture Capital
Impact Investing Market
Venture Capital
LAMEA Venture Capital Investment Market
Venture Capital
Micro Venture Capital VC Funds Market