
 Logging Cable Market | 2026-2036
Logging Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Logging Cable Market Foresight
Steel armor producers in the United States are expanding drawn-wire capacity to serve Permian Basin operators. NOV Inc. leverages backward integration into wire rope manufacturing for downhole telemetry products. WireCo anchors North American distribution through oilfield service channels. Cortland Limited specializes in synthetic rope alternatives that compete with traditional steel logging cables in corrosive environments.
Logging cable consists of multi-conductor armored wireline engineered to transmit power, data, and telemetry signals between surface equipment and downhole instruments in boreholes ranging from 5,000 to 30,000 feet depth. The construction typically incorporates galvanized steel armor over copper conductors with polyethylene insulation to withstand hydrostatic pressure, tensile loading, and chemical exposure during well intervention. Fiber optic product types command premium positioning as distributed temperature and acoustic sensing displace electrical conductor systems in high-temperature shale formations. Copper material grades dominate volume shipments, though aluminum substitutes gain traction where weight reduction offsets conductivity trade-offs. The mining industry vertical represents the fastest-growing application segment outside petroleum, with automated mineral exploration rigs demanding ruggedized data transmission cables.
API standards govern mechanical performance benchmarks for logging cable deployed in US oilfields, while ISO 10425 harmonizes international wire rope specifications for offshore service. OSHA regulations mandate inspection intervals and retirement criteria for cables under tension in elevated derrick operations. The EU Machinery Directive and CE marking requirements shape product access for European geothermal and geotechnical drilling contractors. Stakeholders must monitor fiber optic reliability in supercritical CO2 environments and assess stranded conductor designs against solid-core alternatives as well depths extend beyond current mechanical limits.
Market Dynamics
Horizontal drilling complexity in the Permian Basin is forcing armored conductor redesigns, as operators push well depths beyond 25,000 feet where mechanical fatigue and hydrostatic pressure converge into a single failure mode.
Growth Catalysts
- API 9A compliance mandates:US oilfield service companies must replace legacy wireline inventory to meet tensile strength specifications, creating replacement demand across North Dakota and Texas drilling corridors.
- Fiber optic telemetry adoption:Distributed temperature sensing in high-temperature shale formations requires fiber optic logging cables that withstand supercritical CO2 environments.
- Mining automation surge:Automated mineral exploration rigs in Australia and Canada deploy ruggedized multi-conductor cables for real-time data transmission from remote drill sites.
Market Restraints
- Galvanized steel input volatility:Drawn-wire capacity expansion lags demand swings, squeezing armor producer margins when zinc prices spike.
- Single-source fiber dependence:Specialty optical fiber for downhole sensing concentrates among limited suppliers, creating supply vulnerability for cable assemblers.
- Aluminum conductivity trade-offs:Weight-reduced conductor designs sacrifice signal integrity, limiting substitution in deep-well telemetry applications.
Strategic Opportunities
- Geothermal drilling expansion:European contractors under EU Green Deal funding are retrofitting oilfield cable designs for high-temperature geothermal boreholes.
- Synthetic rope substitution:Cortland Limited's corrosion-resistant alternatives open offshore and sour-gas applications where steel armor degrades rapidly.
- OSHA inspection automation:Predictive retirement criteria based on real-time tension monitoring could unbundle cable lifecycle services from equipment sales.
Industry Challenges
- ISO 10425 harmonization delays:Divergent fatigue testing protocols between API and international standards complicate product certification for offshore suppliers.
- Legacy copper conductor integration:Hybrid designs blending fiber and electrical conductors require new splice techniques that field crews have not yet standardized.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Logging Cable Market |
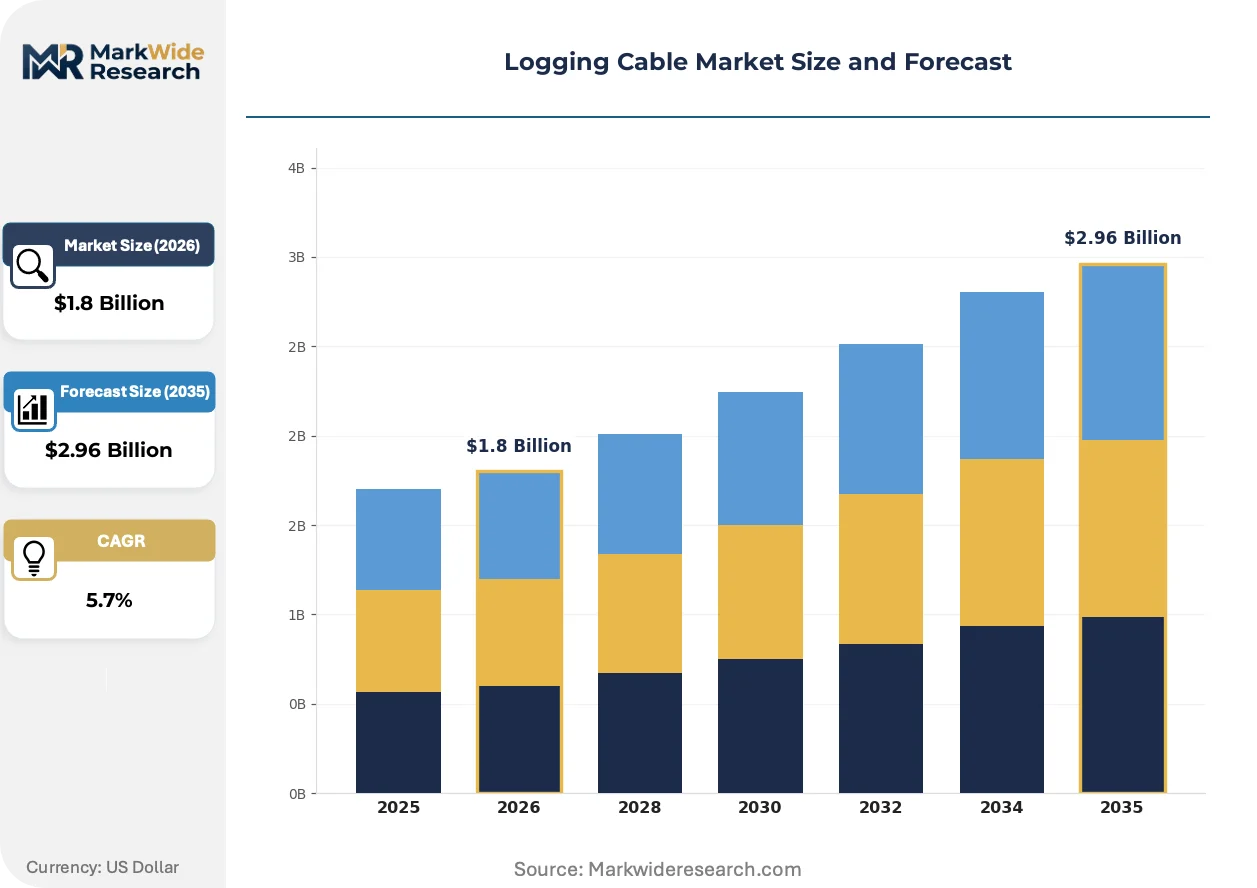
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Optic, Coaxial, Twisted Pair, Ribbon Material: Copper, Aluminum, PVC, Steel Application: Telecommunications, Data Transmission, Broadcasting, Automation Industry Vertical: Construction, Mining, Forestry, Utilities |
| Companies Covered | Cortland Limited, Camesa, Inc., Jiangsu Langshan, Grupo Condumex, TEMCO, WireCo, NOV Inc., TE Connectivity, Sandvik AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Logging Cable Market Shifts & Advancements
Distributed sensing architectures are compressing the traditional separation between telemetry hardware and cable infrastructure, collapsing procurement decisions into unified system specifications.
Fiber optic sensing is rewriting how operators monitor wellbore conditions. The technology transmits distributed temperature and acoustic data along the entire cable length without discrete sensors. Permian Basin shale operators now specify fiber-integrated armored conductors for horizontal laterals exceeding 15,000 feet. This convergence is compressing the addressable market for pure electrical conductor systems in high-temperature formations.
OSHA's updated derrick safety inspection intervals are tightening cable retirement criteria for tension-bearing operations. The regulation forces operators to document fatigue cycles and hydrostatic exposure with greater granularity. Onshore US service companies are responding by embedding RFID tracking into armor wire during manufacturing, creating auditable lifecycle records that satisfy both OSHA and internal risk protocols.
Buyer consolidation among supermajor oilfield service providers is compressing supplier negotiation cycles. Halliburton and Schlumberger procurement teams now mandate five-year total-cost-of-ownership guarantees that bundle cable replacement, inspection, and telemetry integration. This bundling is most visible in the Permian Basin, where integrated wireline service contracts have displaced component-level cable purchasing among the largest horizontal drilling programs.
Logging Cable Market Segmentation
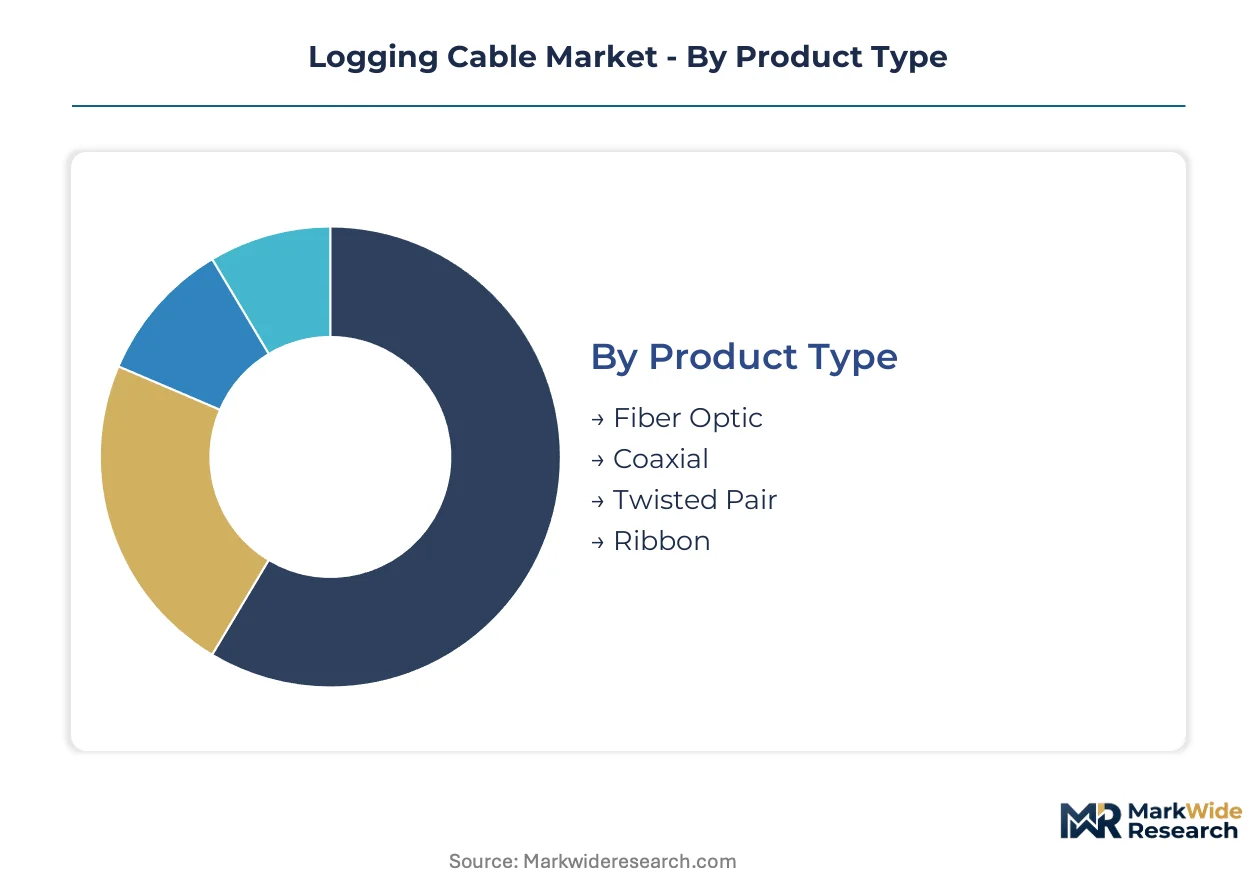
Logging cable procurement decisions increasingly collapse into unified system specifications as distributed sensing architectures erase traditional boundaries between telemetry hardware and conductor infrastructure. Segment boundaries now reflect functional integration requirements rather than discrete component categories.
Product Type:
Standardization dominates fiber optic and coaxial constructions for Permian Basin deployment, while twisted pair and ribbon formats retain customization flexibility for specialized geotechnical applications.
- Fiber Optic:Armored optical conductors transmit distributed temperature and acoustic data along the entire cable length without discrete sensors. Permian Basin operators specify these for horizontal laterals exceeding 15,000 feet where electrical systems fail under thermal stress.
- Coaxial:Central conductor shielded by dielectric and metallic braid delivers power and telemetry through unified geometry. North Dakota wireline service companies favor this construction for API 9A compliance in deep vertical wells where signal integrity trumps weight reduction.
- Twisted Pair:Paired conductors with controlled impedance suit legacy logging tool compatibility and field-splice repairability in remote mining operations.
- Ribbon:Flat conductor arrays enable compact drum storage and rapid deployment for shallow geotechnical surveys requiring frequent relocation.
Most installed capacity flows through coaxial and fiber optic constructions. Expansion is steepest in fiber optic as distributed sensing displaces electrical telemetry in high-temperature shale formations.
Material:
Copper and steel armor command premium positioning for deep-well mechanical reliability, while aluminum and PVC alternatives compete on weight and corrosion resistance in shallow or sour-gas environments.
- Copper:Oxygen-free high-conductivity grades dominate conductor cores for power transmission and analog signal fidelity across 25,000-foot well depths. Galvanized steel armor over copper conductors remains the default specification for OSHA-regulated derrick operations in Texas and North Dakota.
- Steel:Drawn-wire armor provides tensile strength and crush resistance under hydrostatic pressure. US producers are expanding capacity to serve Permian Basin demand, though zinc price volatility squeezes margins during supply shocks.
- Aluminum:Weight-reduced conductor designs sacrifice conductivity for handling efficiency in automated mining rigs and shallow geothermal drilling.
- PVC:Jacketing material for synthetic rope alternatives in corrosive offshore environments where galvanized steel degrades rapidly.
Steel armor and copper conductors absorb the majority of material procurement spend. Aluminum substitution is climbing fastest where automated handling systems offset conductivity trade-offs.
Application:
Telecommunications and data transmission applications drive volume through oilfield service channels, while broadcasting and automation represent emerging demand from adjacent industrial verticals.
- Telecommunications:Downhole telemetry for well logging and intervention commands requires bidirectional signal paths through armored multi-conductor cables. Horizontal drilling complexity in the Permian Basin is forcing redesigns as operators push depths beyond 25,000 feet.
- Data Transmission:Real-time formation evaluation and directional drilling feedback demand high-bandwidth fiber optic links. Mining automation in Australia and Canada deploys ruggedized cables for remote drill site connectivity.
- Broadcasting:Seismic acquisition and geophysical survey operations use specialized logging cables for energy source synchronization and receiver array control.
- Automation:Automated mineral exploration rigs require ruggedized multi-conductor cables for machine-to-machine communication and remote operation.
Telecommunications and data transmission absorb the bulk of current production. Automation applications are expanding most quickly as mining and construction verticals adopt oilfield-derived cable technologies.
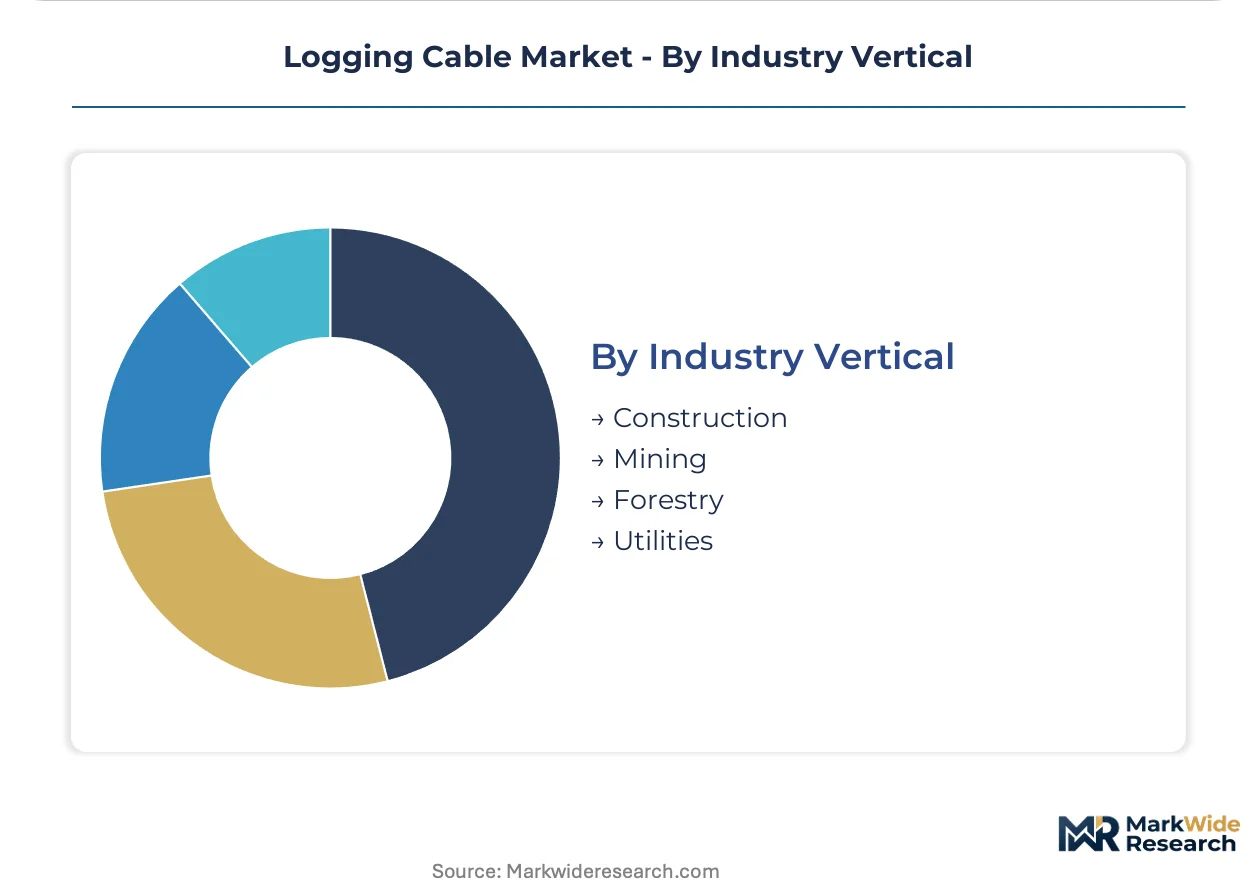
Industry Vertical:
Construction and mining verticals present contrasting procurement patterns—construction favors standardized inventory for project-based deployment, while mining demands customized durability specifications for continuous operation.
- Construction:Geotechnical drilling and foundation investigation use logging cables for soil sampling and instrumentation deployment. European contractors under EU Green Deal funding are retrofitting oilfield designs for geothermal boreholes.
- Mining:Automated mineral exploration rigs in Australia and Canada represent the fastest-growing application segment outside petroleum, demanding ruggedized data transmission for remote operation. Cortland Limited's synthetic rope alternatives compete here against steel armor in corrosive environments.
- Forestry:Limited penetration for terrain mapping and environmental monitoring cables, typically repurposed from geophysical survey inventories.
- Utilities:Underground cable route investigation and pipeline integrity assessment use adapted logging cable technologies for electromagnetic and acoustic sensing.
Construction and mining verticals dominate non-petroleum demand. Mining is gaining share fastest as automation investments accelerate in Australia and Canada.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping logging cable procurement as manufacturers migrate toward jurisdictions with streamlined certification pathways. The divergence between API-centric North American compliance and ISO-harmonized European standards creates cost-of-compliance gaps that influence supplier location decisions.
United States
OSHA-mandated derrick safety inspections drive replacement demand across Texas and North Dakota drilling corridors. The EPA oversees chemical exposure standards for cable jacketing materials in offshore applications. Houston anchors the densest cluster of wireline service companies, where Halliburton and Schlumberger procurement teams consolidate cable purchasing under integrated service contracts.
China
GB standards and MIIT regulations govern domestic wire rope manufacturing for mining and petroleum applications. The country's dual carbon goals accelerate fiber optic substitution in high-temperature geothermal projects. Jiangsu province hosts concentrated drawn-wire capacity serving both domestic shale operators and export markets.
Germany
REACH compliance and CE marking requirements shape product access for European geothermal drilling contractors under EU Green Deal funding. The KBA regulates transport safety for cable drum handling equipment. North Rhine-Westphalia's industrial belt supports specialized steel armor producers supplying North Sea offshore platforms.
Australia
Automated mineral exploration rigs in Western Australia and Queensland deploy ruggedized multi-conductor cables for remote operation. The TGA framework influences safety equipment standards for drilling contractors. Perth-based operators source corrosion-resistant alternatives for iron ore and lithium extraction sites.
Saudi Arabia
SFDA and national oil company procurement standards govern wireline equipment for onshore and offshore petroleum development. The country's Vision 2030 diversification program funds geothermal exploration requiring high-temperature cable adaptations. Eastern Province drilling clusters absorb premium armored conductor shipments for Ghawar field operations.
Logging Cable Market Competitive Landscape
United States producers anchor one tier; Chinese and European specialists hold differentiated positions in cost-optimized and premium-niche segments respectively. The vendor base concentrates around vertically integrated oilfield service conglomerates and independent wire rope fabricators. Three archetypes dominate: armor producers with captive steel drawing capacity, cable assemblers sourcing specialty optical fiber, and synthetic rope innovators targeting corrosive environments. Capacity expansion and backward integration into wire manufacturing represent the dominant competitive moves.
Within the integrated oilfield service tier, NOV Inc. and WireCo exemplify scale-driven positioning through captive supply chain control. Cortland Limited occupies the synthetic alternative archetype, representing corrosion-resistant specialization against traditional steel armor. Jiangsu Langshan anchors Chinese manufacturing presence, exemplifying cost-optimized fabrication for mining and petroleum export markets. These three entities collectively illustrate the geographic and technological segmentation defining competitive dynamics.
| Leading Market Players |
|---|
| Cortland Limited |
| Camesa, Inc. |
| Jiangsu Langshan |
| Grupo Condumex |
| TEMCO |
| WireCo |
| NOV Inc. |
| TE Connectivity |
| Sandvik AB |
| Others |
Supply & Pricing Matrix
Supermajor oilfield service procurement teams in Texas and North Dakota negotiate integrated wireline contracts that compress component-level cable purchasing into bundled service agreements, flattening traditional tiered pricing structures into total-cost-of-ownership guarantees.
Pricing Analysis
Distributor margins collapse under direct OEM contracting as Halliburton and Schlumberger procurement teams mandate five-year total-cost-of-ownership guarantees bundling cable replacement, inspection, and telemetry integration. Price differentiation hinges on API 9A certification grade and fiber optic integration depth. Cost compression in standard electrical conductor tiers intensifies because galvanized steel input volatility squeezes armor producer margins when zinc prices spike. Automated mining rig operators in Australia exhibit highest price sensitivity, while Permian Basin shale operators prioritize mechanical reliability over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from OSHA-regulated derrick operators mandate qualified backup suppliers for critical armored conductor shipments, forcing cable assemblers to maintain redundant fiber optic and steel armor vendor relationships. Manufacturing concentrates in the United States, China, and Germany. Drawn-wire capacity expansion for galvanized steel armor rests on zinc price stability and scrap steel availability. Single-source vulnerability concentrates in specialty optical fiber for downhole sensing. Distribution runs through oilfield service channels anchored in Houston, with WireCo and NOV Inc. controlling captive supply networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
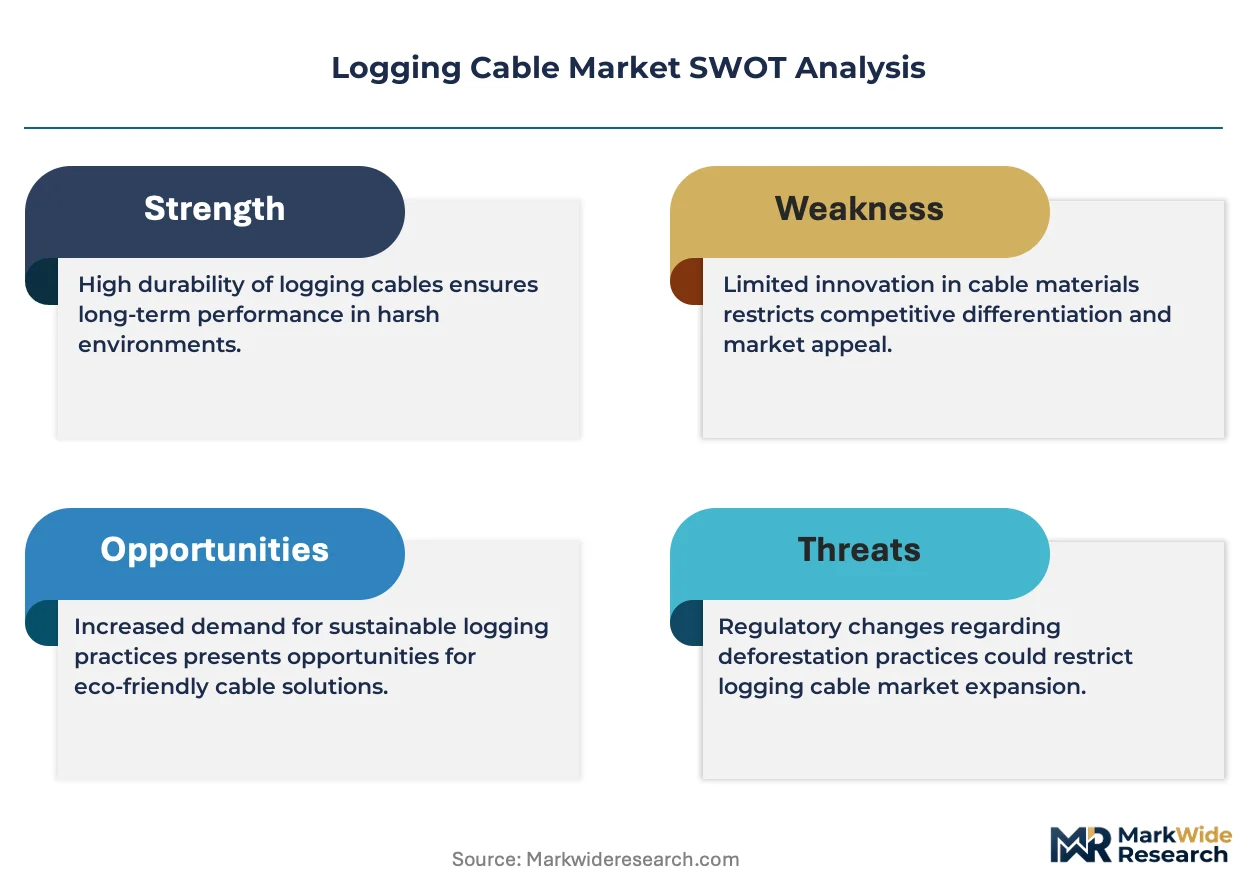
This market functions as a regulatory compounder where OSHA's updated derrick safety inspection intervals tighten cable retirement criteria and force replacement demand across North American drilling corridors.
For Market Incumbents: Cement API 9A certification leadership through backward integration into wire rope manufacturing, mirroring NOV Inc.'s captive supply chain control. Expand drawn-wire capacity in Texas to serve Permian Basin operators directly and neutralize galvanized steel input volatility through upstream control over zinc procurement. For New Entrants and Emerging Players: Launch via corrosion-resistant synthetic rope distribution partnerships targeting Australian iron ore and lithium extraction sites where Cortland Limited has proven offshore viability. White-space concentrates in geothermal drilling retrofit contracts under EU Green Deal funding, where European contractors demand high-temperature cable adaptations. For Investors and Strategic Acquirers: Oilfield service conglomerates are the most active acquirers in this space, seeking cable assemblers with fiber optic integration capabilities to complete distributed sensing system portfolios. Acquisition targets with stranded conductor splice expertise and RFID-enabled lifecycle tracking command premium positioning. Watch fiber optic reliability data in supercritical CO2 environments as the inflection signal for technology substitution velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Wire Manufacturing | NOV Inc. demonstrates how captive steel drawing capacity insulates margin from zinc price volatility. |
| Fiber Optic Product Line Expansion | Permian Basin operators now specify fiber-integrated armored conductors for horizontal laterals exceeding 15,000 feet. |
| Corrosion-Resistant Synthetic Rope Development | Cortland Limited's PVC-jacketed alternatives open offshore and sour-gas applications where galvanized steel degrades rapidly. |
| RFID-Enabled Lifecycle Tracking Systems | OSHA-mandated inspection documentation creates auditable retirement records that satisfy regulatory and internal risk protocols. |
| Geothermal Cable Retrofit Partnerships | European contractors under EU Green Deal funding adapt oilfield designs for high-temperature geothermal boreholes. |
Research Methodology
Direct dialogue with wireline service company procurement directors, drilling contractor operations managers, steel armor plant managers, and fiber optic cable engineers grounds qualitative assessment in field-level decision dynamics. Secondary validation draws from API standards documentation, OSHA regulatory filings, SEC 10-K disclosures from listed oilfield service companies, and customs data on galvanized steel wire rope imports. Bottom-up demand modeling triangulates against top-down market sizing from petroleum drilling activity indicators.
Bottom-up segmentation analysis constructs volume and value estimates across product type, material grade, application function, and industry vertical dimensions. The analytical framework projects replacement demand cycles, fiber optic substitution curves, and mining automation adoption rates throughout the forecast period. CAGR derivation rests on well depth extension trends, horizontal drilling complexity indices, and regulatory compliance mandate schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under zinc price volatility extremes and single-source fiber supply disruptions. Forecasts reflect assumptions regarding OSHA enforcement consistency, API 9A compliance deadlines, and Permian Basin drilling activity persistence. Deviation in galvanized steel input costs or specialty optical fiber supplier consolidation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Construction and Mining Equipment Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Crawler Excavator Market
Mining Equipment
Global Automated Mining Equipment Market
Mining Equipment
Underground Mining Market
Mining Equipment
Global Underground Mining Loader Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
North America Underground Mining Equipment Market
Mining Equipment
Mine Hoisting Systems Market