
 DTH Drill Rig Market | 2026-2036
DTH Drill Rig Market Size, Share, and Industry Trends Forecast 2026-2036
DTH Drill Rig Market Analytics
A capital-intensity divergence between integrated manufacturers and component assemblers is rotating competitive advantage toward firms with captive supply of high-pressure compressors and drill string metallurgy. Sandvik sustains technology leadership through in-house tungsten carbide insert production. Boart Longyear anchors its position with a dense service network across hard-rock mining belts. Epiroc differentiates via automated rod-handling systems that reduce operator exposure in deep-hole applications.
A down-the-hole drill rig employs a percussion hammer mounted at the bottom of the drill string, delivering impact energy directly to the bit through high-pressure air or fluid at pressures typically exceeding 17 bar, enabling efficient penetration in consolidated rock formations for blasthole drilling, water well construction, and mineral exploration. The Down-The-Hole product category commands the dominant revenue share due to its irreplaceable performance in granite and basalt formations where top-hammer rigs lose efficiency beyond 25-meter depths. Hydraulic technology leads unit shipments while electric drive systems are gaining traction in underground mines seeking to eliminate diesel particulate exposure and comply with ventilation cost constraints.
MSHA ventilation regulations in the United States and EU F-Gas restrictions on hydrofluorocarbon-based compressor fluids are reshaping powertrain specifications and refrigerant choices for rig cooling systems. China's GB standards for non-road mobile machinery emissions and Australia's DMP guidelines for ground vibration control add compliance layers that favor certified OEMs over gray-market imports. Stakeholders must monitor the pace of battery-electric retrofit availability and the alignment of automation protocols with mine-site digital infrastructure investments.
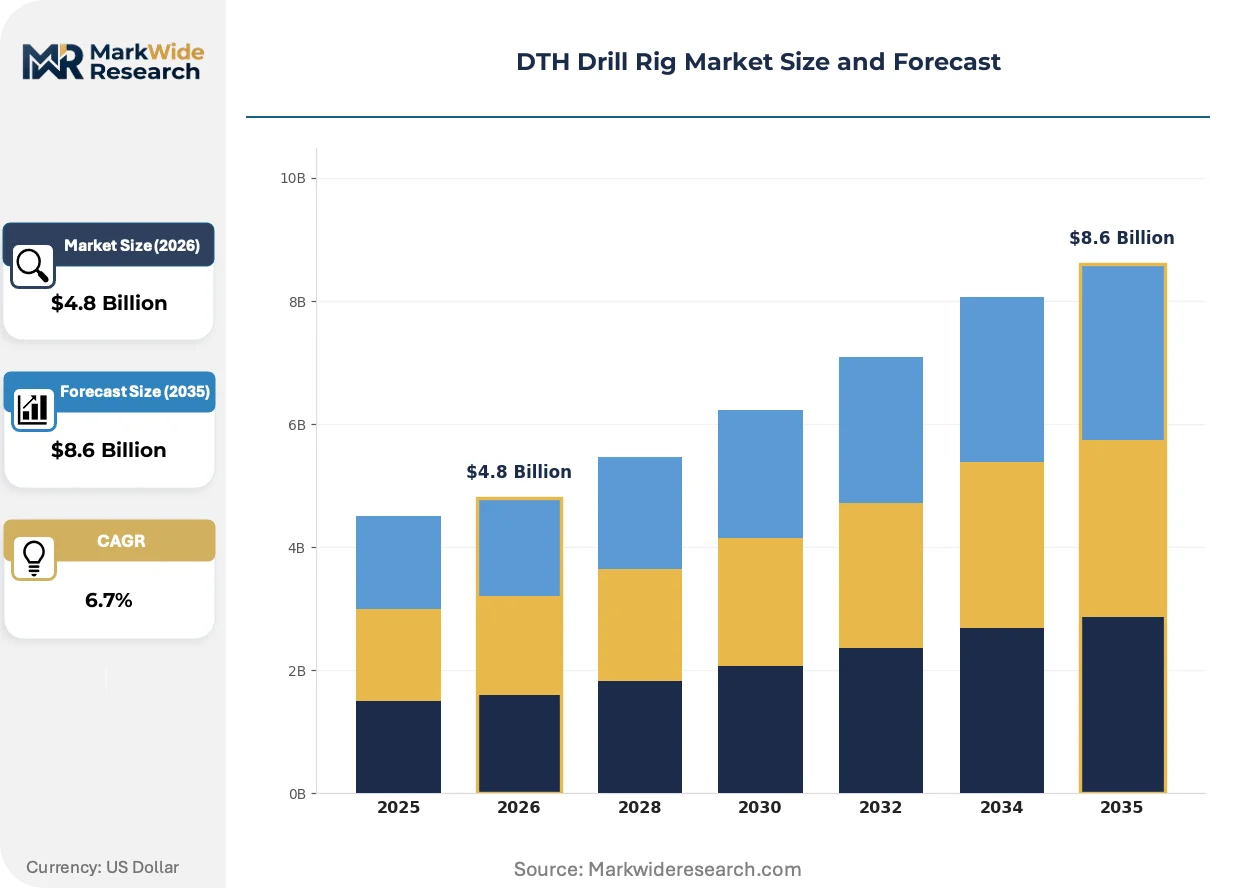
Market Dynamics
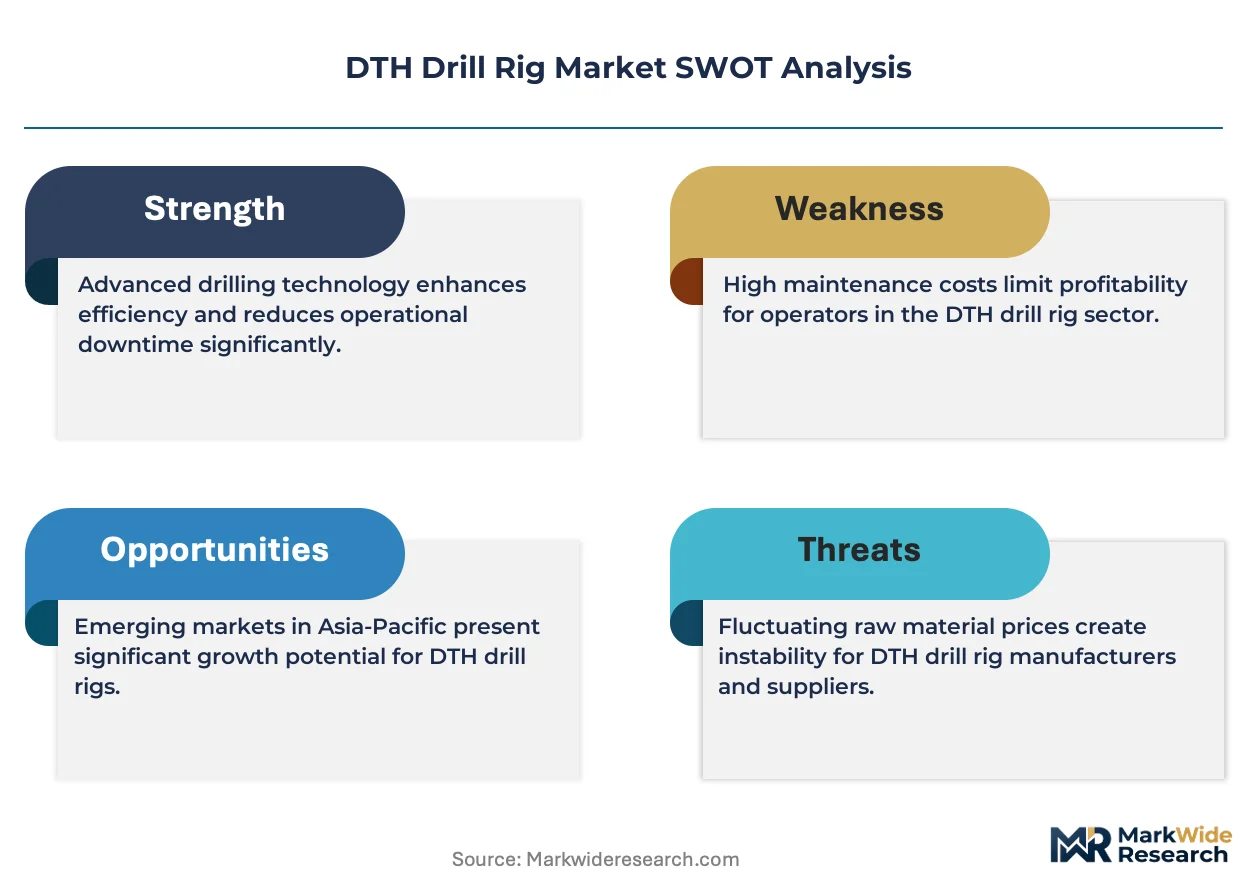
High-pressure compressor technology and tungsten carbide metallurgy are consolidating competitive advantage among integrated manufacturers, while tier-2 assemblers face margin compression from captive supply constraints.
Growth Catalysts
- Copper-lithium extraction acceleration:China's western provinces are deploying DTH rigs for deep-hole blasthole drilling in granite formations where top-hammer systems fail beyond 25-meter depths.
- EPA Tier 4 Final and MSHA ventilation mandates:Underground mines in the United States are replacing diesel fleets with electric-drive systems to eliminate particulate exposure and reduce ventilation infrastructure costs.
- Automated rod-handling adoption:Deep-hole applications in Australian hard-rock belts are integrating mechanized pipe handling to reduce operator injury risk and accelerate drilling cycles.
Market Restraints
- Tungsten carbide supply concentration:Captive production of drill bit inserts limits procurement options for non-integrated rig manufacturers, compressing margins at the component level.
- EU F-Gas Regulation phase-down:Hydrofluorocarbon-based compressor cooling fluids face quota reductions, forcing refrigerant transitions that extend equipment certification timelines.
- High-pressure compressor capital intensity:The 17-bar-plus air delivery systems required for efficient DTH penetration demand substantial upfront investment, constraining fleet expansion by mid-tier contractors.
Strategic Opportunities
- Battery-electric retrofit availability:Underground operators in Canada and Scandinavia are piloting diesel-to-electric conversions to preempt ventilation infrastructure upgrades.
- Digital infrastructure alignment:Automation protocols that integrate with mine-site fleet management systems create differentiation for OEMs serving tier-1 mining houses.
- Water well construction in water-stressed regions:Deep aquifer access projects in the Middle East and North Africa are specifying DTH rigs for consolidated basalt formations.
Industry Challenges
- Drill string metallurgy skill scarcity:Heat treatment and threading expertise for high-torque connections is concentrated among aging specialists in traditional manufacturing clusters.
- Multi-jurisdictional certification complexity:Simultaneous compliance with China's GB non-road emissions, Australia's DMP vibration guidelines, and MSHA ventilation rules extends product launch timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DTH Drill Rig Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Top-Hammer, Down-The-Hole, Rotary, MWD End User: Construction, Mining, Oil & Gas, Geotechnical Deployment: Onshore, Offshore, Underground, Surface Technology: Electric, Hydraulic, Pneumatic, Automated |
| Companies Covered | Boart Longyear, Junjin CSM, Sandvik, Soilmec, Sinodrills, Atlas Copco, Furukawa Rock Drill, Bauer Maschinen, Epiroc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DTH Drill Rig Market Evolving Landscape
Powertrain electrification and automation protocol standardization are restructuring equipment specifications and supplier relationships across underground and surface mining operations.
Electric drive systems for DTH rigs are bifurcating the underground equipment market. Battery-electric and tethered electric configurations eliminate diesel particulate exposure in confined headings. Tier-1 mining houses in Canada and Sweden are mandating zero-emission fleets for new mine developments. The technology is compressing demand for conventional diesel-hydraulic rigs in ventilation-constrained environments while creating parallel aftermarket retrofit demand.
EU F-Gas Regulation restrictions on hydrofluorocarbon refrigerants are forcing compressor cooling system redesigns. OEMs must transition to alternative refrigerants with lower global warming potential. Underground rig deployments in Germany and Poland face extended type-approval timelines as manufacturers validate thermal performance under new fluid chemistries.
Service unbundling is fragmenting traditional procurement relationships. Mining contractors in Western Australia are separating rig acquisition from consumables supply and maintenance execution. Independent service providers with regional compressor fleets and rod inventories are capturing aftermarket revenue previously retained by OEMs, compressing manufacturer margin capture in mature mining districts.
DTH Drill Rig Market Segmentation
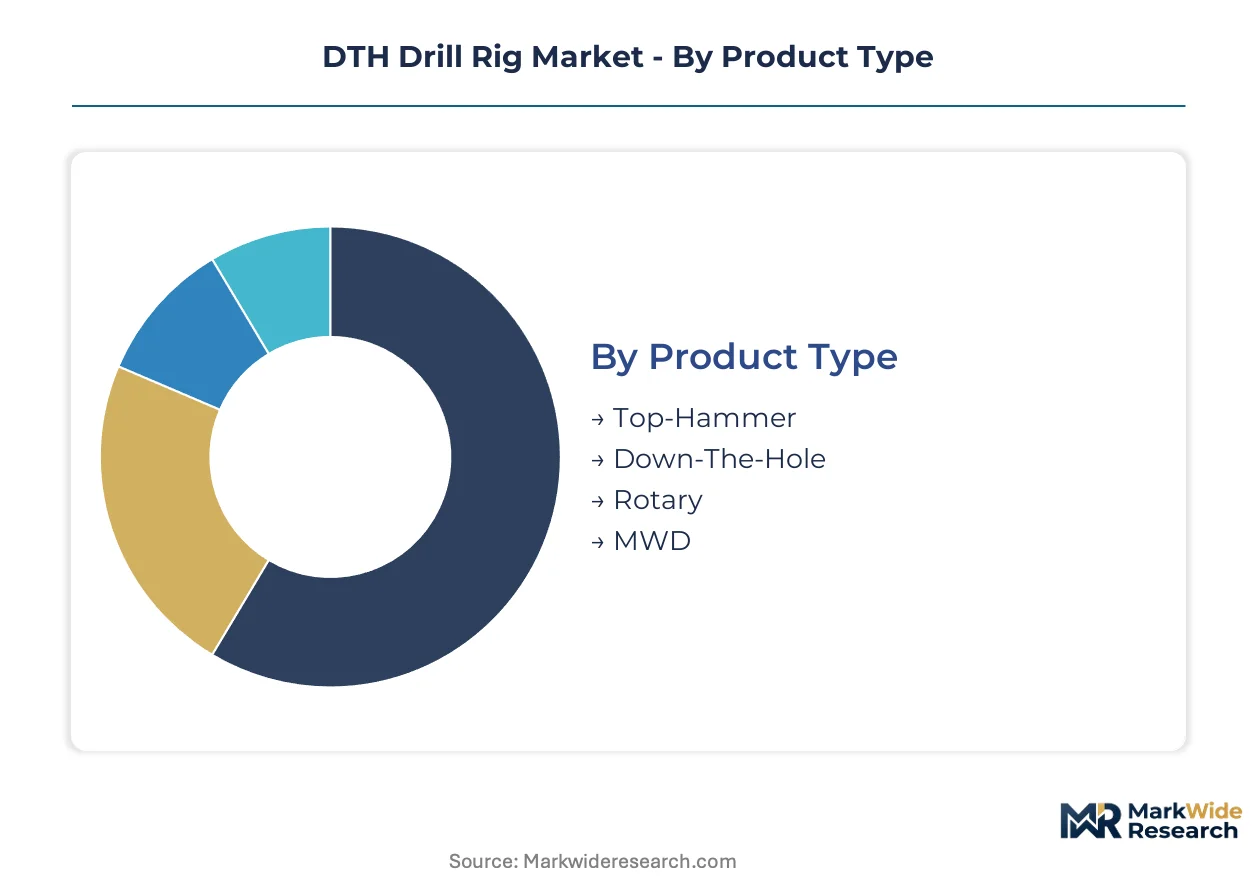
Equipment specification diverges sharply across deployment contexts, with compressor integration and powertrain architecture driving channel differentiation. Procurement patterns cluster around integrated solutions for tier-1 mining houses versus component-based sourcing for mid-tier contractors.
Product Type:
Channel flow splits between turnkey rig packages for fleet operators and modular component sales to independent drilling contractors with captive compressor assets.
- Down-The-Hole:Percussion hammer mounted at the drill string bottom delivers impact energy through high-pressure air exceeding 17 bar, enabling efficient penetration in granite and basalt. Australian hard-rock mining belts deploy these systems for blasthole depths beyond 25 meters where top-hammer rigs lose efficiency. Demand concentrates in China's western provinces for copper-lithium extraction.
- Top-Hammer:Surface-mounted percussion mechanism transmits impact through the drill string, optimized for shallow holes under 25 meters in softer formations. Construction and quarrying operations in Sweden and Finland specify these rigs for urban infrastructure drilling where noise and vibration constraints apply.
- Rotary:Continuous rotation without percussion suits unconsolidated formations and large-diameter water well construction. Deployment spans Middle Eastern aquifer access projects in Saudi Arabia and UAE basalt formations.
- MWD:Measurement-while-drilling systems integrate real-time telemetry for directional control in deep exploration boreholes. Oil and gas operators in Norway's North Sea fields specify these for deviated well trajectories.
Down-The-Hole dominates installed base. MWD is where expansion concentrates.
End User:
Application intensity varies by sector, with mining commanding the highest utilization rates and construction showing seasonal procurement patterns.
- Mining:Hard-rock extraction drives the most demanding duty cycles, with Australian operators renewing fleets amid declining ore grades. EPA Tier 4 Final and MSHA ventilation mandates are accelerating electric-drive adoption in US underground operations.
- Construction:Foundation piling and tunnel portal drilling create intermittent demand spikes. Scandinavian infrastructure projects are specifying zero-emission rigs for urban tunneling contracts.
- Oil & Gas:Geothermal and carbon storage exploration are displacing traditional hydrocarbon applications. Canadian operators in Alberta's oil sands are repurposing rigs for geothermal gradient drilling.
- Geotechnical:Site investigation and slope stability monitoring require portable, rapid-deployment units. Swiss alpine tunnel projects deploy compact DTH rigs for probe drilling ahead of tunnel boring machines.
Mining anchors revenue concentration. Geotechnical is climbing the fastest as infrastructure resilience spending accelerates.
Deployment:
Environmental constraints reshape powertrain specifications, with underground settings demanding ventilation-compliant solutions and surface operations prioritizing mobility.
- Underground:Confined headings require electric or battery-electric powertrains to eliminate diesel particulate exposure. Canadian and Swedish tier-1 mining houses are mandating zero-emission fleets for new developments.
- Surface:Open-pit and quarry operations favor diesel-hydraulic mobility with rapid setup cycles. Western Australian iron ore producers are unbundling rig acquisition from consumables supply.
- Onshore:Remote mineral exploration demands air-transportable modular rigs with self-contained compressor packages. Mongolia's copper-gold exploration belt specifies these for seasonal campaigns.
- Offshore:Platform-based drilling for geothermal and carbon capture applications requires corrosion-resistant specifications. North Sea installations face EU F-Gas Regulation compliance for cooling systems.
Surface commands unit volume. Underground is gaining share fastest as ventilation regulations tighten.
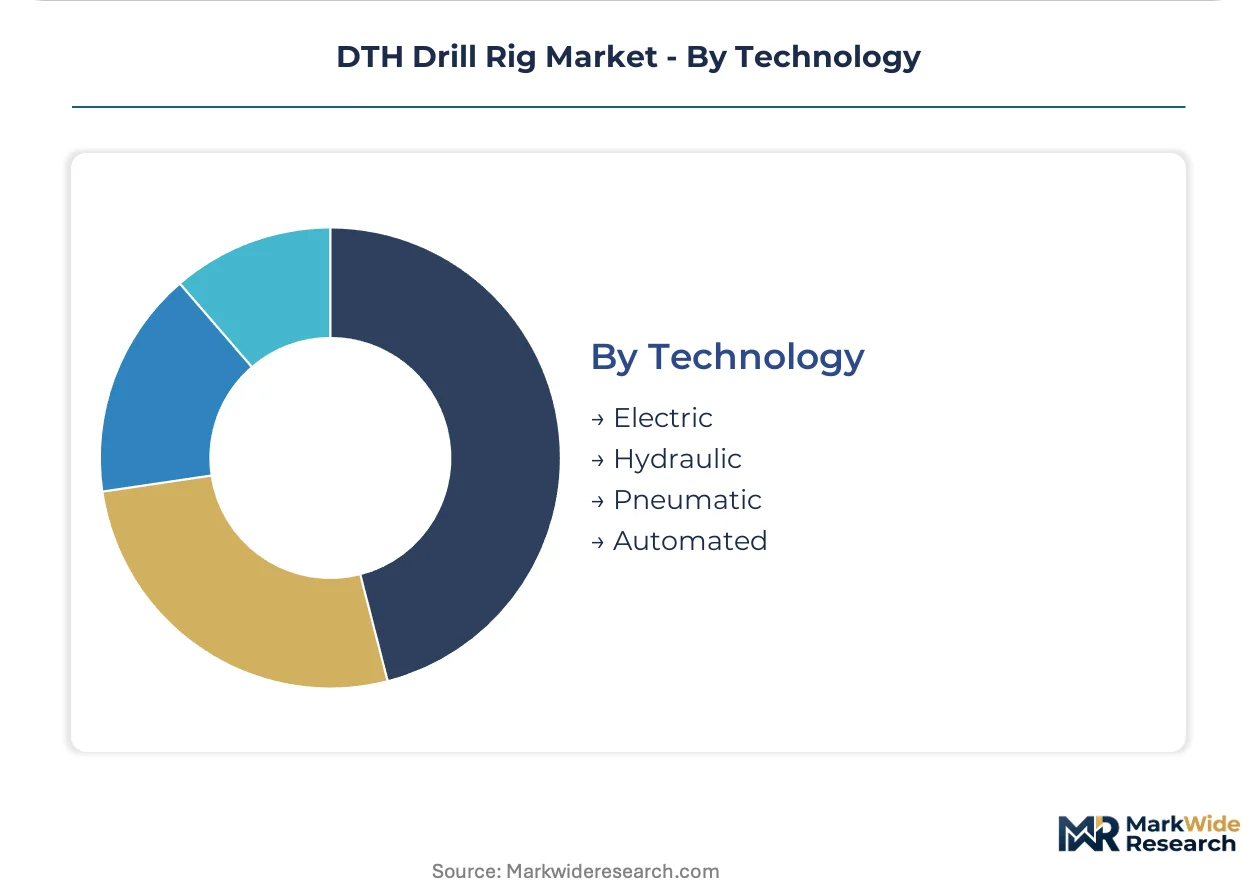
Technology:
Powertrain transition is bifurcating the supplier base between established hydraulic specialists and emerging electric-drive integrators.
- Hydraulic:Mature technology dominates current installed base with proven reliability in harsh conditions. Mid-tier contractors in Chile's copper belt continue specifying these for cost-sensitive fleet expansion.
- Electric:Tethered and battery configurations eliminate emissions for ventilation-constrained environments. German and Polish underground operations face extended type-approval timelines under EU F-Gas refrigerant transitions.
- Pneumatic:Compressed air power suits explosive atmospheres and simple maintenance protocols. South African platinum mines specify these for gassy seam conditions.
- Automated:Rod-handling systems reduce operator exposure and accelerate drilling cycles in deep-hole applications. Australian hard-rock belts are integrating these with mine-site fleet management systems.
Hydraulic retains installed base dominance. Automated systems are where technology investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mid-tier contractors in Chile and Peru exhibit the highest price elasticity, deferring fleet renewal until ore prices recover, while Australian tier-1 mining houses prioritize technology integration over capital cost minimization.
Australia
Western Australia's Pilbara iron ore belt drives fleet replacement cycles as declining ore grades force deeper blasthole drilling. The Department of Mines and Petroleum enforces ground vibration guidelines that favor certified OEM deployments over gray-market imports. Kalgoorlie's gold mining district concentrates demand for automated rod-handling systems that reduce operator exposure in deep-hole applications.
China
Xinjiang and Tibet's copper-lithium extraction zones deploy DTH rigs for granite penetration beyond 25-meter depths where conventional systems fail. GB standards for non-road mobile machinery emissions tighten engine certification timelines for underground deployment. Chengdu's equipment manufacturing cluster supplies high-pressure compressor packages to western provincial operators.
United States
Nevada's gold-silver belt and Arizona's copper porphyry deposits sustain replacement demand amid MSHA ventilation mandates. EPA Tier 4 Final certification requirements accelerate electric-drive adoption in underground headings to eliminate diesel particulate exposure. Elko's mining service hub concentrates aftermarket maintenance execution for surface and underground fleets.
Sweden
Kiruna's iron ore operations and Boliden's polymetallic mines mandate zero-emission fleets for new underground developments. EU F-Gas Regulation phase-downs extend type-approval timelines for compressor cooling system redesigns. Sandviken's engineering corridor anchors captive tungsten carbide insert production for drill bit manufacturing.
Canada
Ontario's Sudbury Basin nickel operations and British Columbia's copper-gold belts pilot battery-electric retrofits to preempt ventilation infrastructure upgrades. Health Canada and provincial mining regulators align on diesel particulate exposure limits for confined headings. Vancouver's mining finance cluster channels capital toward electrification pilot programs in tier-1 operations.
DTH Drill Rig Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive supply of high-pressure compressors and drill string metallurgy determining margin capture. The upper tier commands premium positioning through in-house tungsten carbide production and dense service networks. Three archetypes dominate: vertically integrated metallurgy specialists, automation-focused system integrators, and regional component assemblers facing procurement constraints. Competitive moves concentrate on strategic partnerships for compressor technology access and geographic expansion into China's western mining provinces.
Within the integrated metallurgy tier, Sandvik and Epiroc occupy positions defined by captive supply chain control. Boart Longyear anchors the service-intensive archetype with network density across hard-rock mining belts. Junjin CSM and Sinodrills represent the Asia-Pacific fabrication cluster serving cost-sensitive regional demand. These named entities exemplify how technology leadership, service infrastructure, and manufacturing scale respectively structure competitive positioning without asserting specific strategic actions or market shares.
| Leading Market Players |
|---|
| Boart Longyear |
| Junjin CSM |
| Sandvik |
| Soilmec |
| Sinodrills |
| Atlas Copco |
| Furukawa Rock Drill |
| Bauer Maschinen |
| Epiroc |
| Others |
Value Network & Pricing Analysis
EPA Tier 4 Final and MSHA ventilation mandates gate both supplier qualification and price differentiation simultaneously, compressing margins for non-certified assemblers while enabling premium capture by integrated OEMs with captive compressor production. Certification timelines extend procurement cycles, concentrating purchasing power among tier-1 mining houses that bundle rig acquisition with long-term service contracts.
Pricing Analysis
Aftermarket parts and compressor overhaul contracts drive lifetime value capture, with service revenue often exceeding initial equipment margins over a rig's operational life. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales bundling intensity. Cost compression in the mid-tier is intensifying because independent service providers with regional compressor fleets are unbundling maintenance from OEM packages. Mid-tier contractors in Chile and Peru exhibit the highest price elasticity, deferring renewal until ore prices recover, while Australian tier-1 mining houses prioritize automation integration over capital cost minimization.
Supply Chain Analysis
Inbound logistics costs for tungsten carbide feedstock and high-pressure compressor castings are rising on Shanghai-Rotterdam and Shanghai-Los Angeles trade lanes, extending lead times for European and North American rig manufacturers. Supply concentrates in China for drill bit inserts, Sweden for hardened steel drill string components, and Germany for precision compressor valves. Raw material dependencies span tungsten carbide powder, high-grade alloy steel, and specialized refrigerants for cooling systems. Single-source vulnerability concentrates in tungsten carbide insert production, where captive supply limits procurement options. Distribution runs through OEM-direct channels for tier-1 mining houses and independent drilling contractors with captive compressor assets for mid-tier operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Heat treatment and threading expertise for high-torque drill string connections is concentrated among aging specialists in traditional manufacturing clusters, creating a bottleneck that constrains fleet expansion and elevates qualified supplier premiums.
For Market Incumbents: Secure captive supply of high-pressure compressor packages and tungsten carbide insert production to defend against margin compression from independent service providers unbundling aftermarket revenue. Extend certification investment across EPA Tier 4 Final, MSHA ventilation, and EU F-Gas Regulation compliance to maintain tier-1 mining house access. Capacity addition in China's western provinces anchors proximity to copper-lithium extraction acceleration. For New Entrants and Emerging Players: Lead with battery-electric retrofit availability for Canadian and Scandinavian underground operators seeking to preempt ventilation infrastructure upgrades. Target water well construction in Middle Eastern and North African basalt formations where DTH performance is irreplaceable. Build go-to-market around independent compressor fleet partnerships that bypass OEM-direct procurement relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across automated rod-handling system integration, favoring OEMs with software-defined drilling capabilities over pure hardware fabricators. Long-term viability across the projection horizon rests on alignment with mine-site digital infrastructure investments and zero-emission fleet mandates. Acquisition target archetype: regional component assemblers with compressor technology access pathways. Watch battery-electric retrofit certification timelines as the inflection indicator for aftermarket value migration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Carbide Production | Captive insert supply secures margin capture against independent bit manufacturers in Australian hard-rock belts. |
| Battery-Electric Retrofit Certification | EPA Tier 4 Final alignment opens tier-1 mining house procurement in ventilation-constrained US underground operations. |
| Automated Rod-Handling System Deployment | Mine-site fleet management integration reduces operator exposure and accelerates drilling cycles in Kalgoorlie gold districts. |
| Regional Compressor Fleet Partnership | Independent service unbundling captures aftermarket revenue previously retained by OEMs in Western Australian iron ore belts. |
| EU F-Gas Regulation Compliance Program | Alternative refrigerant validation extends type-approval timelines for German and Polish underground rig deployments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with maintenance directors at tier-1 mining houses, plant engineers at underground operations, OEM procurement teams, and aftermarket service heads. Secondary validation drew from MSHA ventilation enforcement records, EPA Tier 4 Final certification databases, EU F-Gas Regulation quota filings, and Australian Department of Mines and Petroleum vibration guideline compliance reports. Bottom-up rig shipment tallies by province and top-down mining capital expenditure patterns were triangulated to anchor volume estimates.
Across the analysis window, the forecasting framework modeled equipment type, powertrain architecture, deployment environment, and end-use sector intensity to segment demand. CAGRs were derived from rig replacement cycle analysis, ore grade decline trajectories, and regulatory compliance deadlines. Industry-specific inputs included high-pressure compressor availability constraints and battery-electric retrofit certification timelines.
The analysis sits within stated boundaries; outcomes outside sustained copper-lithium price levels, accelerated electrification mandates, or tungsten carbide supply disruption would require recalibration. Forecasts reflect assumptions regarding regulatory enforcement consistency and tier-1 mining house technology adoption rates. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Drilling Rigs Market
Mining Equipment
Global Dozers Market
Mining Equipment
Mining Drill Bits Market
Mining Equipment
Reverse Circulation Drill Pipes Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
Underground Mining Diamond Drilling Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Rock Duster Market
Mining Equipment
Mine Ventilation System Market
Mining Equipment
Commonwealth of Independent States (CIS) Underground Mining Equipment Market
Mining Equipment
Africa Mining Market
Mining Equipment
Surface Drilling Rig Market
Mining Equipment
Smart Mining Market
Mining Equipment
Global Autonomous Mining Equipment Market