
 Global Underground Mining Loader Market | 2026-2036
Global Underground Mining Loader Market Size, Share, and Industry Trends Forecast 2026-2036
Global Underground Mining Loader Market Outlook
Direct sales channels from OEMs to tier-one mining houses is reshaping how underground mining loaders reach end users, bypassing traditional dealer networks in favor of lifecycle service contracts. Sandvik AB leverages its aftermarket parts density to lock in multi-year fleet agreements across Scandinavian and African base-metal operations. Caterpillar Inc. sustains manufacturing scale through integrated powertrain production at its Decatur, Illinois facility. Epiroc AB differentiates through its mine automation platform, which controls loader fleets from surface operations centers.
An underground mining loader is a trackless rubber-tired vehicle engineered to excavate, haul, and dump fragmented rock in confined subterranean headings, typically operating in drifts as narrow as three meters with payloads ranging from six to twenty-one metric tons. Its primary industrial purpose is continuous muck removal from development and production faces in metalliferous and coal mines, where conveyor infrastructure proves uneconomical. Diesel-powered Load Haul Dump units still dominate installed bases in emerging mining jurisdictions, though electric-powered LHD configurations capture the fastest growth as ventilation-on-demand systems reduce operating costs. Automation technology segments command premium positioning where labor scarcity and safety mandates converge, particularly in deep Canadian and Australian operations where remote operation centers eliminate underground exposure.
EPA emissions standards for nonroad diesel engines and the EU F-Gas Regulation constrain powertrain options available to OEMs serving North American and European mine operators, while China's GB standards and MEE enforcement accelerate local electric-loader development. ISO 19296 safety specifications for underground mining machinery establish baseline design requirements that shape R&D allocation across major suppliers. Stakeholders must monitor battery energy density breakthroughs and charging infrastructure standardization as determinants of fleet electrification pace and competitive positioning in deep-mine applications.
Market Dynamics
Battery-electric propulsion systems are compressing ventilation infrastructure requirements in deep-shaft operations, while automation platforms eliminate labor exposure at the extraction face. This dual technical shift is restructuring fleet procurement criteria across metalliferous mining jurisdictions.
Growth Catalysts
- EPA Tier 4 Final emissions standards:Nonroad diesel engine limits in US underground operations accelerate electric-loader replacement cycles in Appalachian coal and Arizona copper districts.
- Ventilation-on-demand systems:Automated airflow management in Canadian and Australian deep mines reduces operating costs by half versus continuous diesel ventilation.
- ISO 19296 safety specifications:Unified machinery design standards enable OEMs to engineer single platforms for multiple export markets.
Market Restraints
- Lithium-ion cell supply concentration:Battery pack production clusters in East Asian manufacturing regions create procurement vulnerability for European and North American loader assembly.
- EU F-Gas Regulation:Thermal management system constraints limit high-ambient-temperature deployment of electric drivetrains in Southern European base-metal operations.
- Deep-mine energy density limitations:Current battery chemistry caps operational shift duration in vertical shafts exceeding 1,500 meters.
Strategic Opportunities
- Indonesian nickel-cobalt expansion:Battery metal demand from electric vehicle supply chains drives fleet investment in Southeast Asian underground sulfide operations.
- Swedish Sustainable Mining Initiative:Government-backed decarbonization incentives position Scandinavian base-metal producers as early adopters of fully autonomous electric fleets.
- Tele-remote operation centers:Surface-based loader control infrastructure opens equipment-as-a-service revenue models for OEM service divisions.
Industry Challenges
- Automation systems integration:Retrofitting legacy diesel fleets with tele-remote capability requires proprietary communication protocol reconciliation.
- Underground charging infrastructure:Standardized high-power connector deployment lags behind vehicle platform availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Underground Mining Loader Market |
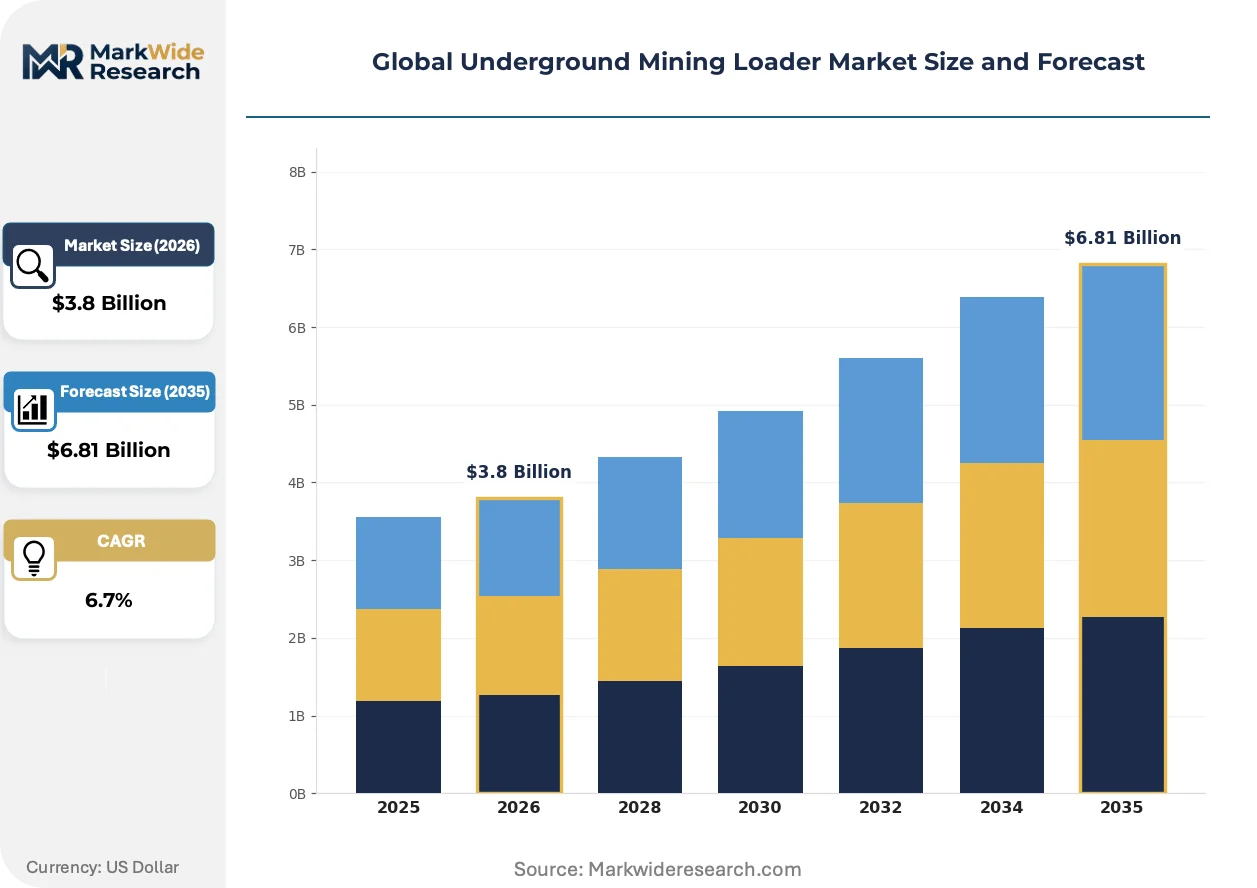
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Load Haul Dump, Scooptram, Continuous Loader, LHD Technology: Diesel-Powered, Electric-Powered, Hybrid, Automation End User: Coal Mining, Metal Mining, Mineral Mining, Quarrying Installation: Fully Underground, Semi-Underground, Above Ground, Others |
| Companies Covered | Sandvik AB, Hitachi Construction Machinery Co. Ltd, Caterpillar Inc., Boart Longyear, XCMG Group, Komatsu Ltd., Volvo Construction Equipment, J.H. Fletcher & Co, Epiroc AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Underground Mining Loader Market Strategic Shifts
Digital twin technology and predictive maintenance platforms are converging with electrified drivetrains to redefine equipment lifecycle economics. This integration is compressing traditional ownership models.
Tele-remote operation centers are virtualizing the loader operator function across multiple underground headings simultaneously. Tier-one mining houses in Western Australia and Ontario deploy single surface controllers for five-to-seven machine fleets. This architecture is virtualizing labor deployment, reducing underground headcount exposure while compressing unit labor costs per tonne moved.
The EU F-Gas Regulation constrains hydrofluorocarbon-based cooling systems in battery thermal management. OEM engineering teams pivot to CO2-based heat pump architectures for European market compliance. Deep-shaft electric loaders bound for German potash and Polish copper operations incorporate these redesigned climate circuits.
Lifecycle service contracts displace spot procurement in tier-one mining house fleets. Sandvik and Epiroc capture multi-year agreements bundling equipment, maintenance, and parts logistics. Australian Pilbara iron ore and Chilean copper operators lead this transition, unbundling capital expenditure into operational expenditure streams.
Global Underground Mining Loader Market Segmentation
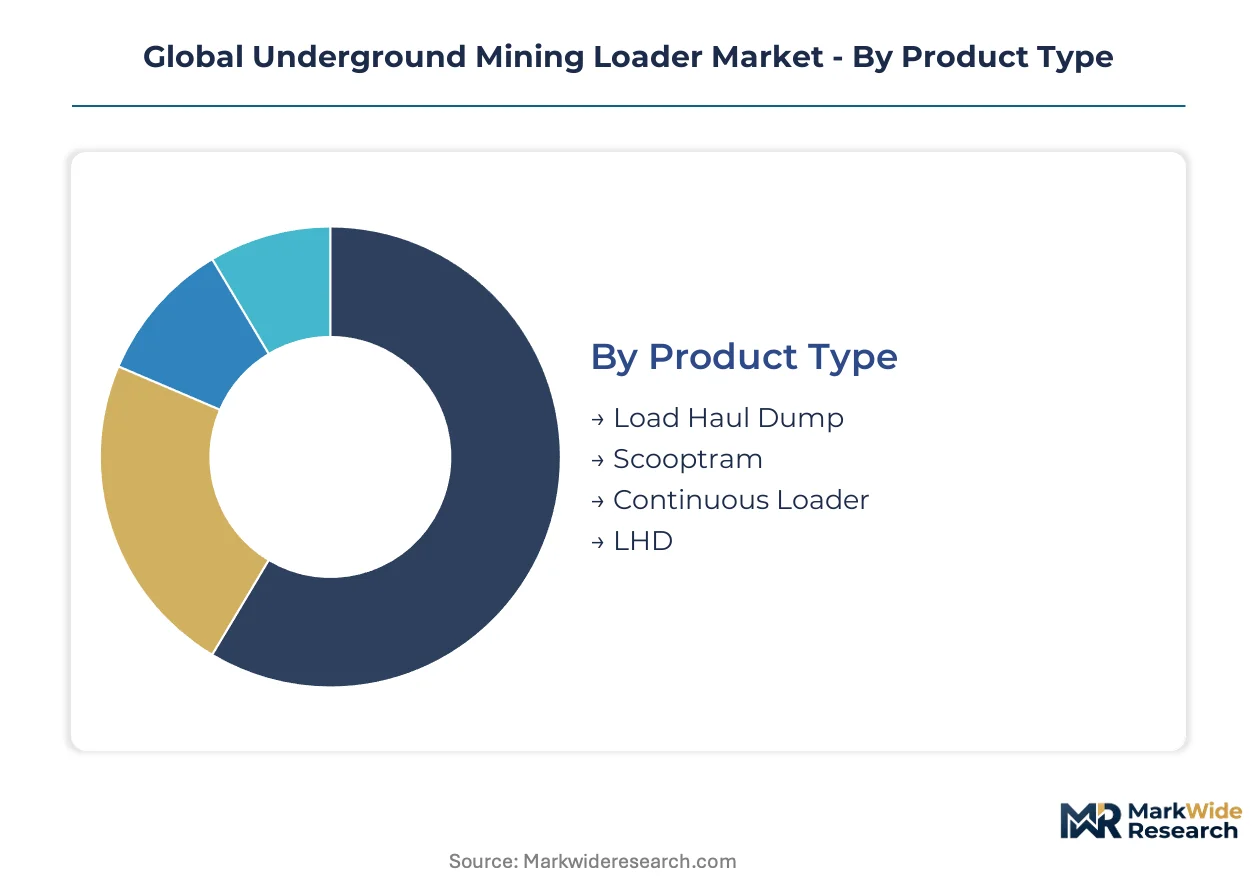
Underground mining loader procurement varies sharply by operational depth, ventilation constraints, and automation readiness. Segment boundaries determine powertrain selection, payload sizing, and service contract structures across metalliferous and coal extraction environments.
Product Type:
Equipment configuration splits across payload capacity and muck-handling mechanism, with narrow-vein specialists diverging from bulk production platforms.
- Load Haul Dump:Rubber-tired articulated chassis with front-mounted bucket designed for three-pass loading of 30-tonne haul trucks. Australian Pilbara iron ore operators and Chilean copper block caving mines specify LHD units for continuous face clearance where conveyor decline angles prove uneconomical.
- Scooptram:Compact loader architecture optimized for drifts as narrow as 2.4 meters with payloads below 10 tonnes. Canadian narrow-vein gold camps and Swedish polymetallic operations deploy Scooptram fleets where mechanized cut-and-fill mining requires agile tramming in confined stoping horizons.
- Continuous Loader:Chain or bucket-wheel mechanism for uniform material flow without discrete loading cycles. Room-and-pillar coal operations in Appalachia and Polish copper flat deposits utilize continuous loading where seam consistency permits mechanized cutting integration.
- LHD:Generic designation overlapping with purpose-built Load Haul Dump configurations, often applied to mid-tier payload ranges between 6 and 14 tonnes. African base-metal contractors and Indonesian nickel sulfide contractors standardize on LHD procurement for fleet interchangeability across multiple orebody geometries.
Load Haul Dump holds installed capacity. Scooptram is rotating up the share rankings in narrow-vein metalliferous applications.
Technology:
Propulsion architecture determines ventilation infrastructure investment, energy cost structure, and regulatory compliance trajectory across mining jurisdictions.
- Diesel-Powered:EPA Tier 4 Final or equivalent diesel engines with exhaust aftertreatment including diesel particulate filters and selective catalytic reduction. Diesel drivelines retain dominance in emerging mining jurisdictions with limited electrical grid infrastructure and in shallow operations where ventilation capital remains modest.
- Electric-Powered:Battery-electric or tethered cable-electric systems eliminating diesel combustion underground. Canadian deep-shaft nickel operations and Australian gold mines below 1,500 meters vertical depth specify electric-powered loaders to compress ventilation-on-demand capital and eliminate diesel particulate exposure.
- Hybrid:Diesel-electric series architecture with onboard battery buffering for tramming power peaks and cable-free operation in development headings. Hybrid configurations bridge infrastructure gaps in transitional mine depths where full electrification remains capital-constrained.
- Automation:Tele-remote or fully autonomous operation platforms with surface-based control centers and machine-to-machine coordination protocols. Western Australian iron ore underground expansions and Ontario base-metal operations deploy automation to eliminate labor exposure at the extraction face.
Diesel-Powered retains fleet share leadership. Electric-Powered is expanding most quickly as battery energy density improves and charging infrastructure standardizes.
End User:
Orebody geology and commodity pricing cycles dictate loader utilization rates, fleet renewal timing, and automation investment thresholds.
- Metal Mining:Copper, nickel, zinc, and polymetallic sulfide extraction in steeply dipping or massive orebodies. Sudbury Basin nickel-copper operations and Chilean porphyry copper mines drive premium-specification loader demand with automation integration and 20-tonne-plus payload requirements.
- Coal Mining:Metallurgical and thermal coal extraction in seam deposits ranging from 1.2 to 4.5 meters thickness. Appalachian longwall development and Australian Bowen Basin underground operations specify flameproof diesel or battery-electric loaders with methane monitoring integration.
- Mineral Mining:Potash, salt, trona, and industrial mineral extraction in flat-lying sedimentary deposits. German potash mines and Saskatchewan solution mining operations utilize low-ground-pressure loaders for uniform seam extraction without roof disturbance.
- Quarrying:Dimension stone and aggregate extraction in shallow underground chambers. Italian Carrara marble and Portuguese limestone operations deploy compact loaders for selective block extraction with minimal overbreak.
Metal Mining commands equipment specification leadership. Coal Mining is rotating up the share rankings as metallurgical coal prices recover and longwall automation penetrates.
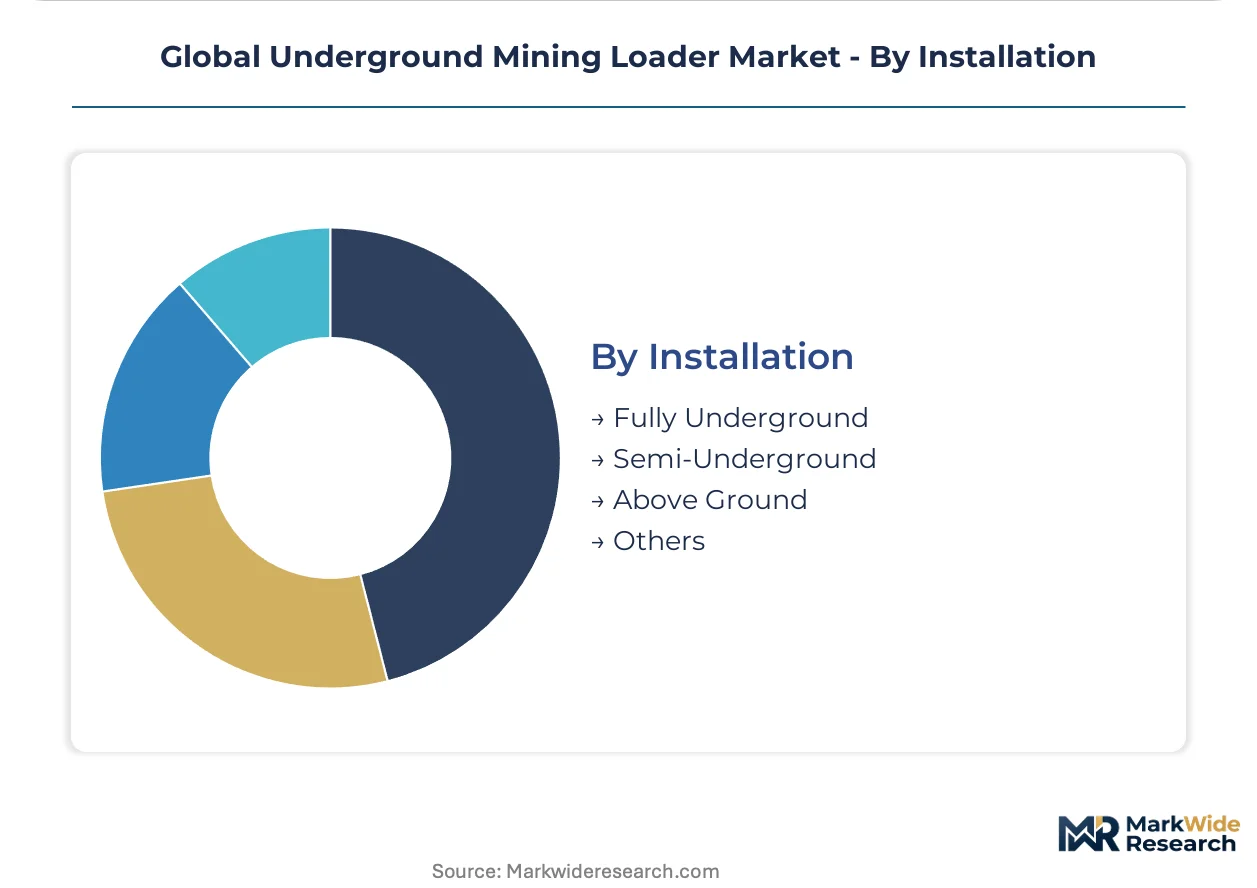
Installation:
Vertical positioning relative to surface determines ventilation design, materials handling logistics, and emergency egress requirements.
- Fully Underground:Operations with shaft or decline access exceeding 500 meters vertical depth with all production infrastructure sub-surface. Fully underground installations in South African platinum reefs and Russian diamond pipes drive demand for battery-electric loaders with rapid charging and automated haulage integration.
- Semi-Underground:Adit or shallow decline access with surface proximity permitting natural ventilation assistance and simplified materials transport. Semi-underground configurations in Turkish chromite and Iranian zinc-lead mines balance capital efficiency against orebody depth.
- Above Ground:Surface stockpile rehandling, portal maintenance, and coarse ore pad operations utilizing underground-rated equipment for interchangeability. Above ground deployment at Peruvian copper concentrators and Mongolian copper-gold projects extends loader utilization across surface and underground fleets.
- Others:Specialized applications including submarine mining, coastal tunneling, and underground storage cavern construction. Others category captures Norwegian submarine olivine extraction and Swiss hydroelectric cavern excavation with modified loader specifications.
Fully Underground dominates capital allocation. Semi-Underground is climbing the fastest as near-surface orebodies in frontier jurisdictions attract development investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's ventilation-on-demand mandates and Australia's automation subsidies are redirecting capital toward electric and autonomous loader fleets. Chile's diesel particulate regulations tighten annually. Sweden's decarbonization incentives accelerate battery-electric procurement.
Australia
Western Australia's Pilbara iron ore belt drives demand for 20-tonne payload loaders with integrated automation platforms. The country's Clean Energy Finance Corporation offers concessional loans for electrified mining equipment. Surface-based tele-remote operation centers in Perth control underground fleets across multiple mine sites simultaneously.
Chile
Copper block caving operations in the Atacama Desert specify electric-powered loaders to comply with progressively stricter diesel emissions limits. The Ministry of Mining's environmental enforcement accelerates fleet replacement cycles. Antofagasta and Calama industrial corridors concentrate procurement activity for northern sulfide deposits.
Canada
Ontario's Sudbury Basin nickel-copper mines deploy battery-electric loaders below 1,500 meters vertical depth to halve ventilation operating costs. Provincial occupational health regulations mandate particulate exposure reductions. Automation integration in Greater Sudbury operations eliminates underground labor exposure at extraction faces.
Sweden
The Sustainable Mining Initiative provides government-backed grants for fully autonomous electric fleet trials in polymetallic base-metal operations. REACH-aligned chemical safety standards constrain diesel exhaust aftertreatment options. Kiruna and Garpenberg mining clusters pioneer zero-emission underground extraction methodologies.
United States
Appalachian metallurgical coal operations and Arizona porphyry copper mines face EPA Tier 4 Final compliance deadlines for nonroad diesel engines. The Inflation Reduction Act's clean energy tax credits extend to electrified mining equipment procurement. Decatur, Illinois anchors domestic powertrain manufacturing for integrated loader assembly.
Global Underground Mining Loader Market Competitive Environment
On the supply side, the industry is consolidating around integrated powertrain and automation platform providers. Two distinct strategic archetypes dominate: full-lifecycle service contractors bundling equipment with multi-year maintenance agreements, and specialized automation technology licensors. Competitive maneuvering concentrates on vertical integration into battery pack assembly and geographic expansion through regional service hub establishment.
Among Scandinavian-based full-line suppliers, Sandvik AB and Epiroc AB occupy positions anchoring the premium service-contract tier. Caterpillar Inc. exemplifies the scale-driven integrated manufacturer archetype with captive powertrain production. These three entities represent the dominant competitive anchors shaping procurement patterns across tier-one mining house accounts.
| Leading Market Players |
|---|
| Sandvik AB |
| Hitachi Construction Machinery Co. Ltd |
| Caterpillar Inc. |
| Boart Longyear |
| XCMG Group |
| Komatsu Ltd. |
| Volvo Construction Equipment |
| J.H. Fletcher & Co |
| Epiroc AB |
| Others |
Value Chain & Pricing Dynamics
Antofagasta-Calama logistics corridors linking Chilean copper operations to Pacific port infrastructure compress freight cost differentials between battery-electric and diesel loader platforms, concentrating procurement leverage among tier-one mining houses while forcing OEMs to absorb thermal management certification premiums for high-altitude deployment.
Pricing Analysis
Certification level (ISO 19296/CE/EPA Tier 4 Final-grade) creates the primary spread between premium battery-electric platforms and standard diesel configurations. Contract-based long-term fleet agreements dominate, bundling equipment, maintenance, and parts logistics into operational expenditure streams. Price differentiation rests on automation integration depth and ventilation cost reduction guarantees. Cost compression in mid-tier diesel segments intensifies as EPA compliance deadlines accelerate replacement cycles. Contract mining operators exhibit highest price sensitivity; integrated majors prioritize lifecycle cost over capital outlay.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from East Asian battery cell manufacturers anchor working capital structures for European and North American loader assemblers. Lithium-ion cell production clusters in China, South Korea, and Japan. Raw material dependencies span lithium carbonate, cobalt sulfate, and high-grade copper winding. Single-source vulnerability in battery thermal management semiconductors creates procurement fragility. Distribution runs through direct OEM-to-miner channels bypassing traditional dealer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
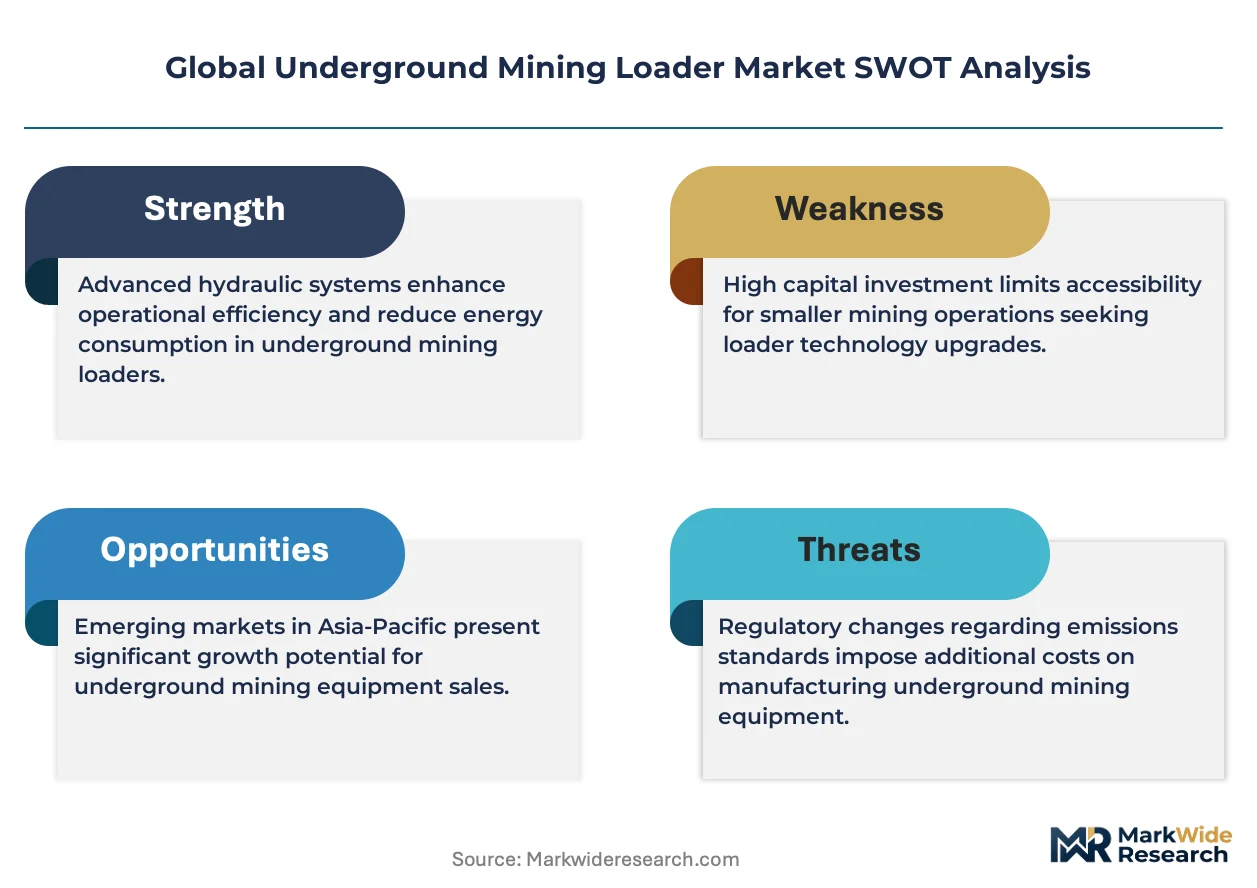
Underground mining loader electrification sits in early-cycle expansion as ventilation-on-demand mandates in Canada and Australia accelerate battery-electric fleet penetration ahead of pure economics.
For Market Incumbents: Harden aftermarket parts density in Sudbury Basin and Pilbara iron ore clusters to lock in multi-year lifecycle contracts against emerging automation specialists. Deepen captive battery pack assembly capabilities to offset East Asian cell supply concentration. Prioritize certification investment for EU F-Gas Regulation thermal management compliance. For New Entrants and Emerging Players: Indonesian nickel-cobalt sulfide operations present underpenetrated fleet opportunities as battery metal demand from electric vehicle supply chains drives underground expansion. Target narrow-vein Scooptram configurations in Canadian gold camps where agile tramming requirements outpace incumbent platform adaptation. Pursue equipment-as-a-service revenue models through tele-remote operation center partnerships. For Investors and Strategic Acquirers: Regional automation technology licensors with proprietary machine-to-machine coordination protocols represent compelling acquisition targets as tier-one mining houses consolidate supplier relationships. Long-term viability hinges on charging infrastructure standardization pace. Watch battery energy density breakthroughs at 1,500-meter-plus vertical depths as inflection indicator for deep-mine electric fleet economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Pack Assembly | Captive lithium-ion production reduces East Asian supply vulnerability for OEMs serving Canadian and Australian deep-shaft operations. |
| Tele-Remote Operation Center Deployment | Surface-based loader control infrastructure unlocks equipment-as-a-service revenue streams across Western Australian iron ore expansions. |
| ISO 19296 Safety Certification Investment | Unified machinery design standards enable single-platform engineering for EPA, EU, and Chinese regulatory compliance. |
| Charging Infrastructure Partnership | Standardized high-power connector deployment lags behind vehicle availability, creating first-mover advantage in deep-mine applications. |
| Lifecycle Service Contract Expansion | Multi-year agreements bundling maintenance and parts logistics displace spot procurement in Chilean copper and Pilbara iron ore fleets. |
Study Parameters
A spread of perspectives from mine operations directors, OEM procurement teams, aftermarket service heads, and ventilation system engineers converged on the working assumptions. Primary interviews with tier-one mining house fleet managers and battery-electric platform R&D directors combined with secondary validation from EPA enforcement databases, EIA mining equipment trade data, ISO standards documentation, and SEC filings from listed suppliers. Bottom-up unit demand modeling and top-down market sizing triangulation anchored volume estimates.
Demand-supply balance dynamics shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include propulsion architecture, payload capacity tier, automation readiness level, and regional regulatory cluster. CAGRs derived from equipment replacement cycle analysis, electrification penetration curves, and automation adoption rates. Forecast inputs incorporated battery energy density improvement trajectories and ventilation-on-demand capital cost reductions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese battery-electric platform entrants or autonomous haulage specialists would shift outcomes. Macroeconomic commodity price volatility, regulatory enforcement acceleration, or solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Horizontal Shaft Impact Crusher Market
Mining Equipment
North America Drill Pipe Market
Mining Equipment
Stone Crushing Equipment Market
Mining Equipment
North America Mining Equipment Market
Mining Equipment
Kazakhstan Mining Market
Mining Equipment
Smart Mining Market
Mining Equipment
Magnetic Sweepers Market
Mining Equipment
Drilling Jumbo Market
Mining Equipment
Asia-Pacific Drill Pipe Market
Mining Equipment
Rock Duster Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Mining Equipment Rental Market
Mining Equipment
Mobile Blasting Systems Market
Mining Equipment
DTH Drill Market
Mining Equipment
Russia Mining Equipment Market