
 Automation in Mining Market | 2026-2036
Automation in Mining Market Size, Share, and Industry Trends Forecast 2026-2036
Automation in Mining Market Insights
Underground metal extraction is pivoting toward fully autonomous fleets as operators confront depth-related hazards and labor shortages. Komatsu Ltd. anchors its position through integrated haulage ecosystems spanning drill-to-port workflows. Sandvik AB specializes in narrow-vein automation for hard-rock environments where conventional mechanization fails. Caterpillar dominates surface autonomous truck deployments across high-volume iron ore and copper terraces.
Automation in mining encompasses sensor-fused machinery, centralized control architectures, and algorithm-driven decision layers that execute extraction, transport, and processing sequences with minimal human intervention. These systems typically integrate LiDAR-based perception stacks, 5G mesh networks, and sub-10-centimeter GPS correction signals to maintain continuous operation in GPS-denied underground drifts. Autonomous Vehicles command the largest installed base among product types, though Control Systems capture disproportionate margin pools through recurring software licensing. Artificial Intelligence applications in predictive maintenance and ore-grade estimation are expanding faster than hardware-centric segments, while Surface Mining retains the dominant share of autonomous fleet hours logged.
ISO 17757 governs autonomous machine safety protocols, while the US Mine Safety and Health Administration and Australia's Work Health and Safety Act impose escalating liability on operators retaining manual processes in hazardous zones. The EU Machinery Directive and CE marking requirements restrict market access for non-compliant control system imports into European mining jurisdictions. Stakeholders must weigh retrofit compatibility against greenfield autonomy architecture when committing capital cycles that span multiple regulatory revision periods.
Market Dynamics
Autonomous haulage fleets are overtaking conventional mechanized operations as depth-related hazards and labor shortages force capital reallocation toward integrated control platforms. Western Australia's Pilbara district anchors procurement momentum, with ISO 17757 compliance mandates compressing decision timelines for fleet modernization.
Growth Catalysts
- ISO 17757 Safety Mandates:Australia's Work Health and Safety Act imposes escalating liability on operators retaining manual processes in hazardous underground zones, redirecting capital toward certified autonomous systems.
- 5G Mesh Deployment:Sub-10-centimeter GPS correction signals combined with LiDAR perception stacks enable continuous operation in GPS-denied underground drifts across Chilean copper operations.
- Canada's Labor Shortage:Underground metal extraction operations in Ontario and Quebec confront acute skilled operator deficits, accelerating procurement of autonomous drill-to-port workflows.
Market Restraints
- Retrofit Cost Burden:Legacy fleet compatibility requirements impose capital penalties of 40-60% above greenfield autonomy architecture, freezing upgrade cycles at mid-tier operators.
- Control System Concentration:Proprietary software licensing pools concentrate margin capture among integrated platform vendors, limiting component-level supplier diversification.
- EU Machinery Directive Friction:CE marking requirements restrict market access for non-compliant control system imports into European mining jurisdictions, segmenting procurement pools.
Strategic Opportunities
- AI-Grade Estimation Convergence:Predictive maintenance algorithms fused with ore-grade sensing create recurring revenue streams beyond hardware installation, capturing disproportionate margin pools.
- India's Underground Hard-Rock Gap:Narrow-vein automation penetration remains below 15% in domestic zinc and lead operations, presenting first-mover positioning for specialized vendors.
- Peru's Regulatory Tailwind:The Ministry of Energy and Mines is drafting autonomous equipment safety protocols aligned with ISO 17757, preempting future compliance windows.
Industry Challenges
- Subsurface Integration Complexity:Autonomous vehicle fleets must interface with legacy ventilation and dewatering systems in decades-old Chilean copper shafts, extending commissioning timelines.
- Certification Bottlenecks:TGA-type functional safety assessments for collision avoidance systems lack harmonized protocols across Australian states, fragmenting approval pathways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automation in Mining Market |
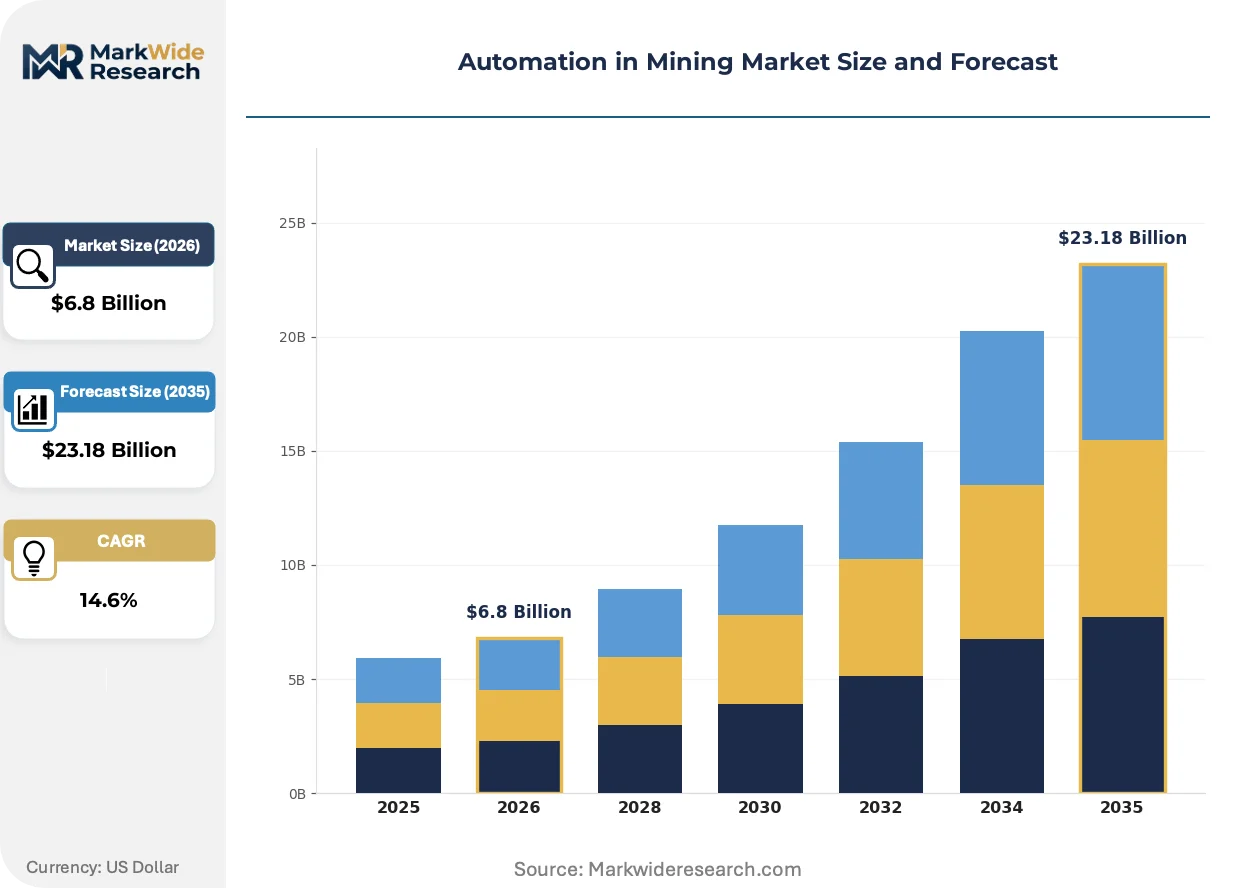
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $23.18 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drilling Equipment, Haulage Systems, Autonomous Vehicles, Control Systems Technology: Artificial Intelligence, Robotics, IoT, Autonomous Navigation Application: Surface Mining, Underground Mining, Material Handling, Mineral Processing End User: Mining Corporations, Engineering Firms, Regulatory Bodies, Service Providers |
| Companies Covered | Caterpillar, Komatsu Ltd., Sandvik AB, Hexagon AB, Rockwell Automation, Atlas Copco, Epiroc AB, Autonomous Solutions Inc., RPMGlobal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automation in Mining Market Trends and Innovations
Algorithm-driven decision layers are compressing the boundary between extraction and processing, with centralized control architectures displacing distributed operator stations. Three forces dominate this transition.
LiDAR-based perception stacks is overtaking radar-dependent obstacle detection in underground haulage applications. Hard-rock operators in Canada's Abitibi belt deploy these systems at depth below 1,200 meters where GPS denial is absolute. The technology is overtaking conventional proximity sensors by enabling centimeter-scale positioning in dust-saturated drifts, collapsing the safety buffer between autonomous trucks and rib walls.
REACH-aligned supply chain disclosure requirements are penetrating mining equipment procurement specifications across EU member states. Original equipment manufacturers must now document conflict mineral content and carbon intensity across autonomous vehicle subassemblies. German and Finnish underground contractors have advanced compliance deadlines by 18 months, forcing component suppliers to accelerate certification documentation or forfeit contract eligibility.
After-sales service unbundling is fragmenting traditional maintenance contracts in Australian iron ore operations. Rio Tinto-type operators now procure autonomous fleet hardware, software licensing, and predictive analytics as separate line items, compressing vendor lock-in durations. This pattern concentrates most visibly in Western Australia's Pilbara district, where tier-1 miners negotiate direct sensor supplier relationships bypassing integrated platform vendors.
Automation in Mining Market Segmentation
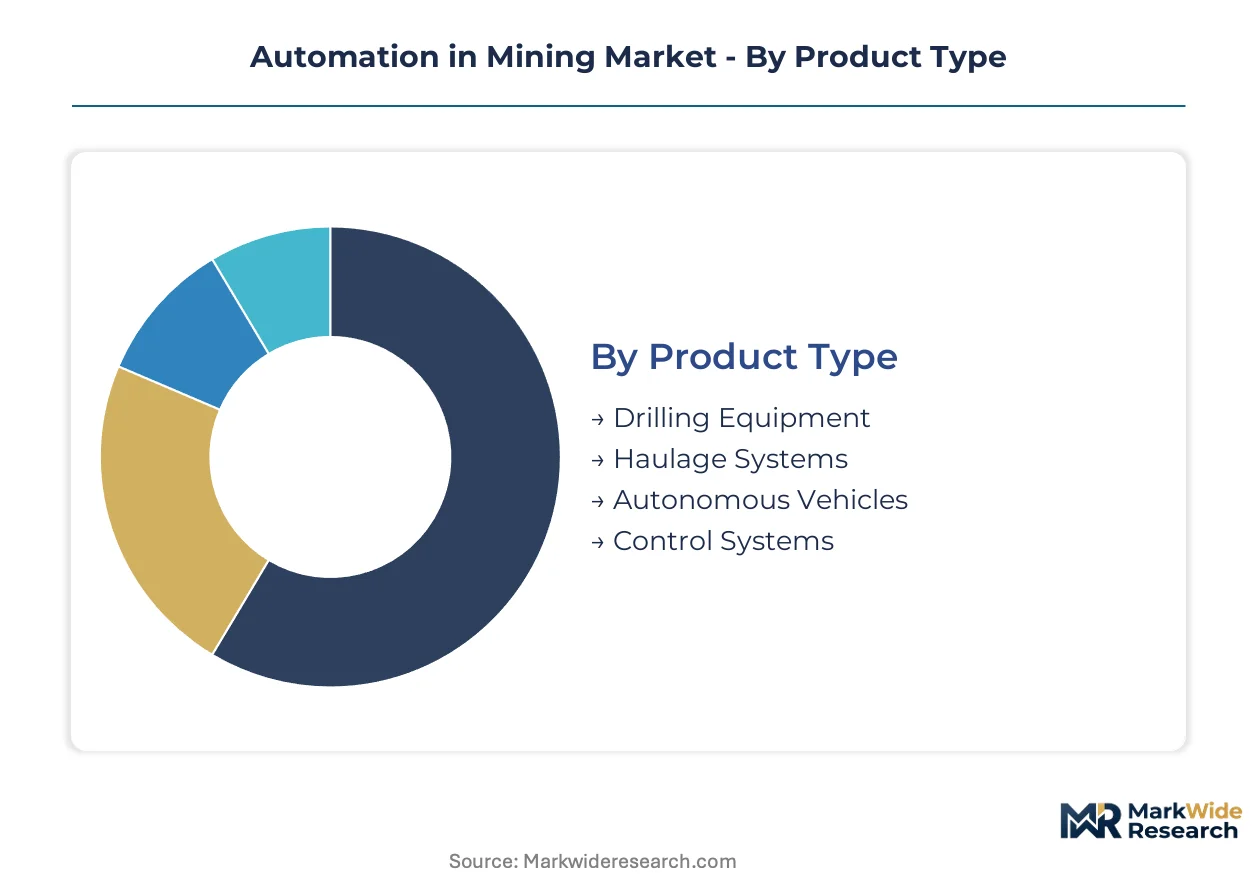
Segmentation in mining automation reveals how capital flows diverge between hardware-heavy extraction tools and software-centric control layers. Procurement patterns split sharply between surface operators prioritizing fleet scale and underground specialists demanding narrow-vein precision.
Product Type:
Standardization dominates haulage and drilling equipment, while control systems and autonomous vehicles demand heavy customization for site-specific geology and legacy infrastructure integration.
- Autonomous Vehicles:LiDAR-fused haul trucks and loaders execute continuous operation in GPS-denied underground drifts across Western Australia's Pilbara iron ore terraces and Chilean copper shafts. Western Australia's tier-1 operators log the majority of autonomous fleet hours globally, though retrofit compatibility with legacy ventilation systems extends commissioning timelines in decades-old operations.
- Control Systems:Centralized architectures integrating algorithm-driven decision layers command disproportionate margin pools through recurring software licensing. Australia's Work Health and Safety Act and ISO 17757 compliance mandates compress procurement timelines as operators face escalating liability for retaining manual processes in hazardous zones.
- Drilling Equipment:Sensor-fused drill rigs with real-time ore-grade sensing anchor drill-to-port workflows in Canada's Abitibi belt.
- Haulage Systems:Conveyors and rail-based transport integrate with autonomous vehicle fleets in high-volume surface copper terraces.
Leading the category by volume: Autonomous Vehicles. Growing fastest: Control Systems.
Technology:
Cost tiers separate mature IoT deployments from emerging AI layers, with robotics occupying a mid-tier position between proven connectivity and speculative autonomy.
- Artificial Intelligence:Predictive maintenance algorithms and ore-grade estimation models generate recurring revenue streams beyond hardware installation. These applications expand more quickly than hardware-centric segments as operators fuse machine learning with LiDAR perception stacks for centimeter-scale positioning in dust-saturated drifts.
- Autonomous Navigation:Sub-10-centimeter GPS correction signals combined with 5G mesh networks enable continuous operation where satellite denial is absolute. Chilean copper operations at depth below 1,200 meters deploy these systems to collapse safety buffers between autonomous trucks and rib walls.
- Robotics:Narrow-vein automation for hard-rock environments addresses labor shortages in Ontario and Quebec underground operations.
- IoT:Sensor mesh networks provide baseline connectivity for equipment health monitoring across Australian iron ore districts.
Dominating deployment scale: IoT. Expanding most quickly: Artificial Intelligence.
Application:
Volume concentration favors surface operations, though margin capture concentrates in underground applications where depth-related hazards justify premium automation spend.
- Surface Mining:High-volume iron ore and copper terraces in Western Australia's Pilbara district anchor the dominant share of autonomous fleet hours logged. Tier-1 operators procure autonomous fleet hardware, software licensing, and predictive analytics as separate line items, compressing vendor lock-in durations.
- Underground Mining:Narrow-vein automation penetration remains below 15% in India's domestic zinc and lead operations, presenting first-mover positioning for specialized vendors. Hard-rock operators confront acute skilled operator deficits in Ontario and Quebec, accelerating procurement of fully autonomous fleets.
- Material Handling:Automated stockyard management integrates with port logistics in Australian bulk export operations.
- Mineral Processing:Algorithm-driven ore sorting and grinding optimization compress extraction-to-processing boundaries.
Capturing the largest fleet hours: Surface Mining. Gaining share fastest: Underground Mining.
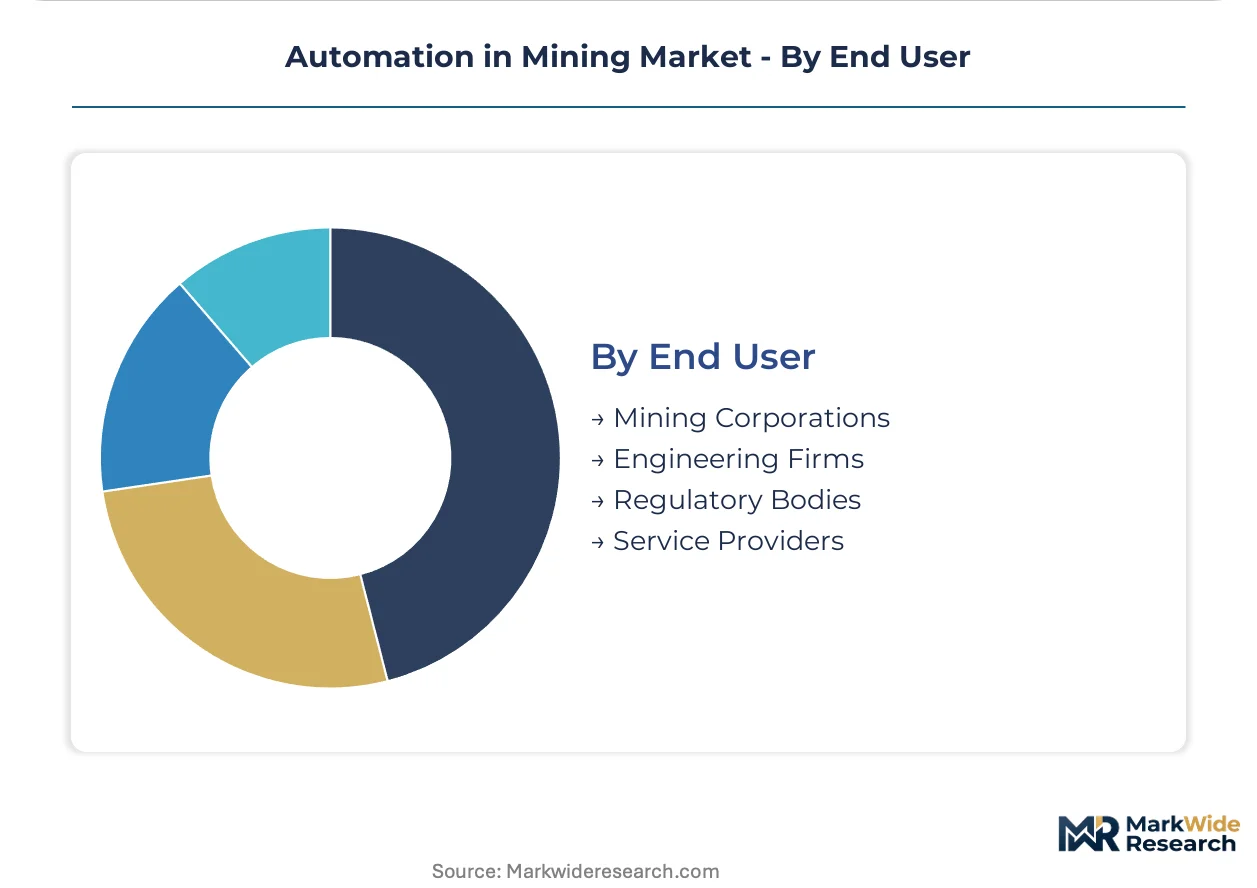
End User:
Customer type determines procurement authority, with mining corporations controlling capital cycles and regulatory bodies imposing compliance windows that redirect spending toward certified systems.
- Mining Corporations:Tier-1 operators in Western Australia's Pilbara district and Chilean copper belts control procurement momentum for integrated haulage ecosystems. These entities negotiate direct sensor supplier relationships, bypassing integrated platform vendors to fragment traditional maintenance contracts.
- Regulatory Bodies:Australia's Work Health and Safety Act, Canada's provincial mining regulators, and Peru's Ministry of Energy and Mines impose escalating liability on operators retaining manual processes. Peru's drafting of autonomous equipment safety protocols aligned with ISO 17757 preempts future compliance windows.
- Engineering Firms:EPC contractors manage retrofit compatibility assessments for legacy fleet modernization projects.
- Service Providers:Predictive analytics vendors and maintenance specialists capture recurring revenue through unbundled after-sales contracts.
Controlling capital allocation: Mining Corporations. Steepest expansion trajectory: Regulatory Bodies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Autonomous fleet procurement concentrates in mineral-exporting economies where labor safety mandates intersect with high-volume extraction operations. Equipment deployment lags in import-dependent jurisdictions lacking domestic ore processing infrastructure.
Australia
Western Australia's Pilbara iron ore district anchors the dominant share of autonomous haulage hours logged globally. The country's Work Health and Safety Act imposes escalating liability on operators retaining manual processes in hazardous underground zones. Tier-1 miners in the Pilbara negotiate direct sensor supplier relationships, fragmenting traditional maintenance contracts and compressing vendor lock-in durations.
Chile
Copper operations at depth below 1,200 meters deploy sub-10-centimeter GPS correction signals combined with 5G mesh networks for continuous autonomous operation. The Ministry of Energy and Mines is drafting autonomous equipment safety protocols aligned with ISO 17757, preempting future compliance windows. Northern copper belts concentrate retrofit integration challenges as legacy ventilation systems extend commissioning timelines in decades-old shafts.
Canada
Underground metal extraction in Ontario and Quebec confronts acute skilled operator deficits, accelerating procurement of fully autonomous drill-to-port workflows. Provincial mining regulators impose certification requirements that redirect capital toward certified autonomous systems. The Abitibi belt deploys LiDAR-based perception stacks at depth where GPS denial is absolute, collapsing safety buffers between autonomous trucks and rib walls.
India
Narrow-vein automation penetration remains below 15% in domestic zinc and lead operations, presenting first-mover positioning for specialized vendors. The country's national mining regulator imposes safety disclosure requirements that favor certified equipment imports. Rajasthan's zinc districts and Odisha's iron ore belts concentrate early procurement trials as operators test retrofit compatibility with legacy mechanized fleets.
Peru
Copper and gold extraction operations accelerate autonomous fleet trials as the Ministry of Energy and Mines advances ISO 17757-aligned safety protocols. The regulatory drafting process compresses decision timelines for fleet modernization among mid-tier operators. Southern copper provinces concentrate procurement momentum where depth-related hazards justify premium automation spend.
Automation in Mining Market Competitive Landscape
Top-tier vendors anchor integrated platform supply, while specialized component suppliers and regional system integrators occupy lower tiers. The vendor base stratifies across three archetypes: full-stack autonomy providers, narrow-vein specialists for hard-rock environments, and control system licensors capturing recurring software revenue. Dominant competitive moves include strategic partnerships between equipment OEMs and telecommunications infrastructure providers, plus backward integration into sensor manufacturing to secure supply chain positioning.
Within the integrated haulage ecosystem tier, Caterpillar and Komatsu Ltd. exemplify scale-driven platform vendors. Sandvik AB occupies a specialized position among narrow-vein automation providers for GPS-denied underground environments. These three entities represent contrasting strategic postures: surface-dominant fleet scale, drill-to-port workflow integration, and hard-rock precision engineering respectively.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu Ltd. |
| Sandvik AB |
| Hexagon AB |
| Rockwell Automation |
| Atlas Copco |
| Epiroc AB |
| Autonomous Solutions Inc. |
| RPMGlobal |
| Others |
Pricing and Supply Chain Analysis
Tier-1 mining corporations in Western Australia's Pilbara district command procurement authority through unbundled after-sales contracts, compressing vendor lock-in durations and fragmenting traditional maintenance pricing models across the autonomous fleet ecosystem.
Pricing Analysis
Cost-down pressure on integrated control platforms accelerates because tier-1 operators negotiate direct sensor supplier relationships, bypassing platform vendors. Pricing stratifies across premium certified tiers aligned with ISO 17757 compliance, standard retrofit-compatible architectures, and economy-grade component-level procurement. Mid-tier operators exhibit acute price sensitivity as legacy fleet compatibility requirements impose capital penalties above greenfield deployments. Tier-1 Pilbara miners demonstrate lowest price sensitivity, prioritizing uptime guarantees and safety certification over unit cost.
Supply Chain Analysis
LiDAR perception stack supply rests on German and Finnish component manufacturers, Japanese precision optics producers, and Australian system integrators deploying 5G mesh networks. Critical inputs span high-grade optical sensors, sub-10-centimeter GPS correction modules, and algorithm-driven decision-layer processors. Single-source vulnerability concentrates in proprietary software licensing pools, limiting component-level supplier diversification. Distribution runs through OEM direct sales for tier-1 operators and regional system integrators serving mid-tier retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Autonomous haulage fleet deployment capacity constrains market expansion, with certified system integrator scarcity propping pricing power for qualified vendors across Australian and Chilean mining jurisdictions.
For Market Incumbents: Deploy backward integration into sensor manufacturing to secure supply chain positioning against direct procurement relationships between tier-1 miners and component suppliers. Anchor market share through strategic partnerships with telecommunications infrastructure providers deploying 5G mesh networks in GPS-denied underground environments. ISO 17757 compliance investment represents the critical defensive lever as regulatory mandates compress decision timelines for fleet modernization. For New Entrants and Emerging Players: India's underground hard-rock zinc and lead operators present an underserved buyer archetype with narrow-vein automation penetration below 15%, offering first-mover positioning for specialized vendors. Peru's mid-tier copper and gold extraction operations face compressed decision timelines as the Ministry of Energy and Mines advances ISO 17757-aligned safety protocols. A certification-first go-to-market angle bypasses incumbent relationships in these pre-compliance windows. For Investors and Strategic Acquirers: The window for entry favors control system licensors capturing recurring software revenue through algorithm-driven decision layers and predictive maintenance algorithms. Long-term viability centers on vendors fusing AI-grade ore estimation with hardware installation, creating sticky revenue streams beyond initial deployment. Watch for TGA-type functional safety assessment harmonization across Australian states as an inflection indicator for certification bottleneck resolution.| Strategic Initiative | Industry Significance |
|---|---|
| 5G Mesh Network Deployment | Enables continuous autonomous operation in Chilean copper shafts below 1,200 meters depth. |
| ISO 17757 Certification Investment | Preempts compliance windows as Australia's Work Health and Safety Act escalates liability. |
| Backward Integration into Sensors | Secures supply chain positioning against direct tier-1 miner procurement of LiDAR components. |
| AI-Grade Ore Estimation Convergence | Fuses predictive maintenance with ore-grade sensing to capture recurring margin pools. |
| Narrow-Vein Automation Specialization | Addresses labor shortages in Ontario and Quebec underground metal extraction operations. |
Research Methodology
Multi-period observation of autonomous fleet procurement timelines, certification bottleneck resolution, and regulatory drafting progress anchored the trend analysis, supplemented by interviews with mine operations directors, autonomous system integrators, safety compliance officers, and telecommunications infrastructure planners. Secondary validation drew from ISO 17757 documentation, Australian Work Health and Safety Act amendments, Chilean Ministry of Energy and Mines regulatory drafts, and equipment procurement disclosures. Bottom-up segment sizing triangulated against top-down market aggregation across product type, technology, application, and end-user dimensions.
Segment-weighting approaches distributed value and volume across autonomous vehicles, control systems, drilling equipment, and haulage systems, with technology layers segmented by artificial intelligence, autonomous navigation, robotics, and IoT. Deployment model differentiation separated surface mining from underground applications, while end-user archetypes distinguished tier-1 mining corporations from regulatory bodies and service providers. CAGRs derived from equipment replacement cycles, regulatory compliance windows, and technology adoption S-curves across the projection horizon, with ore-grade estimation algorithm penetration and 5G mesh deployment velocity serving as key forecast inputs.
Revisions become necessary when ISO 17757 harmonization delays, 5G spectrum allocation bottlenecks, or lithium-ion battery supply constraints for autonomous vehicle power systems materialize. Forecasts reflect assumptions about certification timeline compression and skilled operator shortage persistence. A small set of regulatory drafting progress, telecommunications infrastructure deployment, and critical mineral supply chain triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Mining Tester Market
Mining Equipment
Borehole Equipment Market
Mining Equipment
Mining Locomotive Market
Mining Equipment
Continuous Miners Market
Mining Equipment
Underground Mining Diamond Drilling Market
Mining Equipment
Rotary Drilling Rig Market
Mining Equipment
Crawler Drill Rig Market
Mining Equipment
Surface Mining Equipment Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Mining Equipment Market
Mining Equipment
Autonomous Mining Truck Market
Mining Equipment
Borehole Enlargement System Market
Mining Equipment
Mining Drills and Breakers Market
Mining Equipment
Africa Mining Market
Mining Equipment
Stone Mining and Quarrying Market
Mining Equipment
Mechanical Mine Clearance System Market