
 Surface Mining Machinery Market | 2026-2036
Surface Mining Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Surface Mining Machinery Market Analysis
Aftermarket service revenue is reconfiguring margin pools away from new equipment sales across the surface mining machinery sector. Komatsu Ltd leverages its global parts distribution network to capture recurring service contracts in Australian iron ore basins. Caterpillar Inc anchors its competitive position through vertical integration into remanufactured powertrain components. Epiroc AB specializes in automation retrofit kits that extend the productive life of legacy truck fleets.
Surface mining machinery encompasses heavy equipment engineered for overburden removal and mineral extraction at open-pit operations, with dump trucks rated from 190 to 400 metric tons payload and hydraulic shovels delivering bucket capacities exceeding 50 cubic meters for high-volume earthmoving. Dragline excavators dominate capital deployment in Appalachian coal basins where single-bucket machines move over 100 million bank cubic meters annually. Electric and hybrid technology segments are attracting the fastest-growing share of OEM engineering hours as Tier 1 suppliers develop battery-electric powertrains for 240-ton-class haulers. Conventional diesel-mechanical systems still occupy the majority of installed base hours but face accelerating displacement from automation-integrated platforms.
EPA Tier 4 Final standards and the EU Green Deal's carbon border adjustment mechanism are tightening particulate and CO2 thresholds for imported mined commodities, compelling fleet operators to specify lower-emission equipment or face tariff penalties. MEE enforcement of dual carbon goals in China is restricting diesel machinery approvals in Inner Mongolian coal districts. Stakeholders must monitor how rapidly battery energy density improvements and autonomous haulage system validation timelines converge to reshape capital deployment cycles.
Market Dynamics
The electrification of 240-ton-class haulage fleets is compressing capital deployment cycles as battery energy density improvements converge with autonomous haulage system validation timelines, forcing incumbent OEMs to reconfigure engineering resource allocation.
Growth Catalysts
- Copper and lithium extraction operations:Chilean and Australian miners are accelerating orders for electric and autonomous haulage fleets to supply battery supply chain expansion.
- EPA Tier 4 Final standards:These emission thresholds are compelling North American coal and aggregates contractors to specify lower-emission equipment or face operational restrictions.
- EU Green Deal carbon border adjustments:The CBAM mechanism is creating tariff exposure for imported mined commodities, pushing European smelters to demand verified low-carbon extraction equipment from suppliers.
Market Restraints
- Battery cell supply concentration:Cathode material processing and cell manufacturing capacity concentrates in China, creating geopolitical exposure for Western OEMs scaling electric powertrains.
- MEE dual carbon enforcement:China's Ministry of Ecology and Environment is restricting diesel machinery approvals in Inner Mongolian coal districts, freezing fleet renewal for state-owned mining conglomerates.
- Autonomous system validation costs:The extended field-testing requirements for driverless haulage in pit operations are inflating R&D recovery timelines beyond traditional equipment development cycles.
Strategic Opportunities
- Automation retrofit kits:Epiroc AB's specialization in extending legacy truck fleet productive life through sensor and control system upgrades represents expandable white space across Australian iron ore basins.
- Remanufactured powertrain components:Caterpillar Inc's captive remanufacturing capabilities create a template for circular revenue models as diesel-to-electric conversions accelerate.
- Aftermarket service contracts:Komatsu Ltd's global parts distribution network demonstrates how recurring service revenue pools can be captured independently of new equipment sales cycles.
Industry Challenges
- Electrification skill gaps:Maintenance technicians trained on diesel-mechanical systems lack certification pathways for high-voltage battery and power electronics servicing, constraining fleet uptime guarantees.
- Legacy system integration:Pit dispatch and fleet management software architectures from the 1990s require expensive middleware development to interface with autonomous haulage platforms.
- Charging infrastructure capex:Mine-site electrical distribution upgrades to support megawatt-class fast-charging for 400-ton haulers are competing with core extraction capital allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surface Mining Machinery Market |
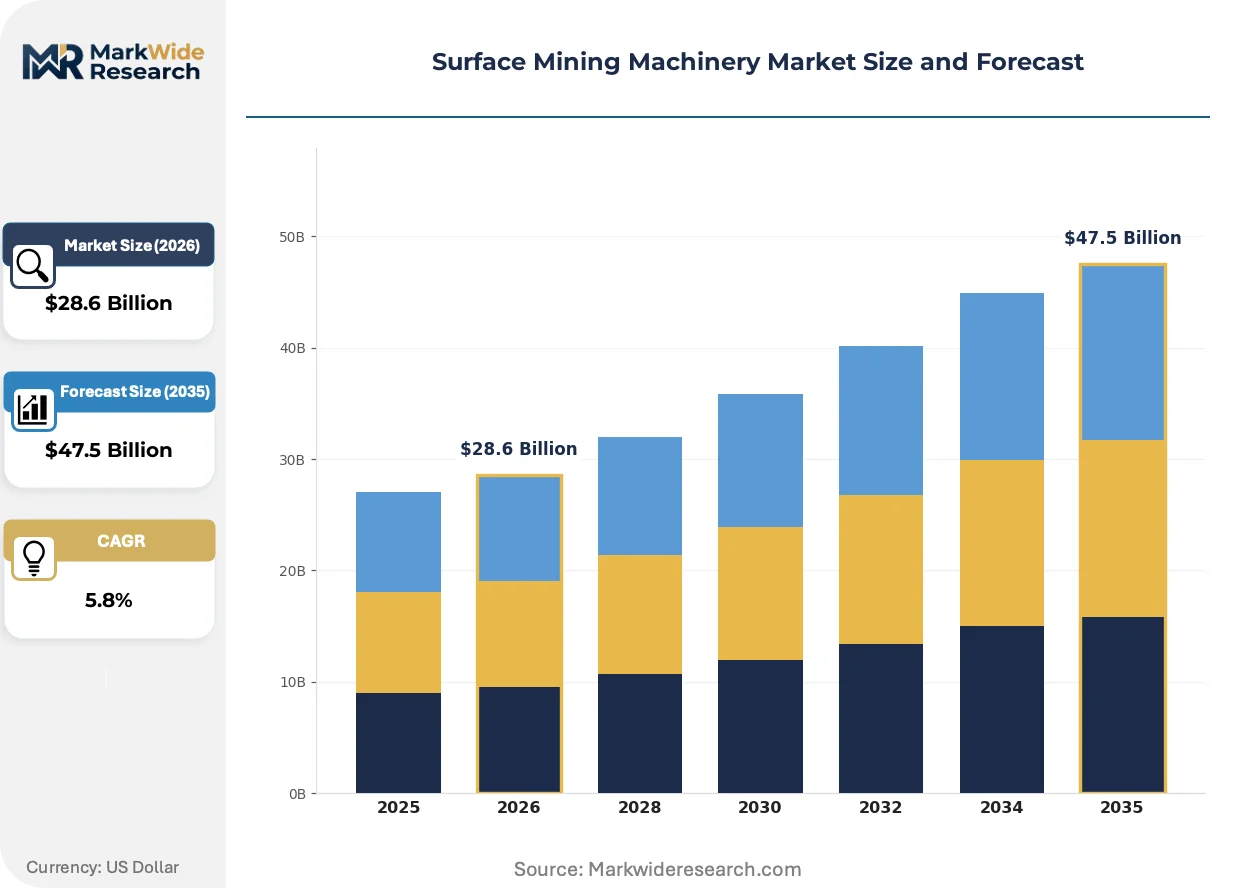
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dragline Excavators, Hydraulic Shovels, Surface Miners, Dump Trucks End User: Coal Mining, Precious Metals, Industrial Minerals, Non-Metallic Minerals Technology: Automation, Conventional, Hybrid, Electric Application: Mineral Extraction, Site Development, Recycling, Land Restoration |
| Companies Covered | Caterpillar Inc, Komatsu Ltd, Hitachi Construction Machinery Co. Ltd, Liebherr Group, Sandvik AB, Volvo Construction Equipment, J.C. Bamford Excavators Limited, Atlas Copco AB, Epiroc AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surface Mining Machinery Market Emerging Trajectories
Digital twin technology is virtualizing equipment performance optimization across surface mining operations, compressing the feedback loop between field telemetry and engineering design iterations.
Digital twin platforms aggregate real-time sensor data from hydraulic shovels and haul trucks to simulate component stress and predict failure modes before physical symptoms manifest. Major copper producers in Chile are deploying these systems across entire pit fleets to optimize maintenance scheduling. This capability is virtualizing traditional reliability engineering functions, allowing OEMs to deliver uptime guarantees as subscription services rather than hardware warranties.
EPA Tier 4 Final particulate and NOx thresholds are forcing diesel engine manufacturers to integrate exhaust after-treatment systems that add weight and complexity to 400-ton-class haulers. The compliance burden falls heaviest on Appalachian coal operators running aging dragline fleets where engine replacement economics are marginal. Contractors are responding by accelerating pilot programs for trolley-assist and full battery-electric retrofits in advance of potential carbon border tariff exposure.
Procurement departments at diversified miners are unbundling aftermarket service contracts from original equipment purchases, creating competitive tension between OEM captive service networks and independent rebuild specialists. Komatsu Ltd and Caterpillar Inc are defending attachment rates by embedding predictive maintenance software licenses into finance lease structures. This behavioral shift is most visible in Western Australian iron ore operations where equipment utilization rates exceed 90% and downtime costs dominate total cost of ownership calculations.
Surface Mining Machinery Market Segmentation
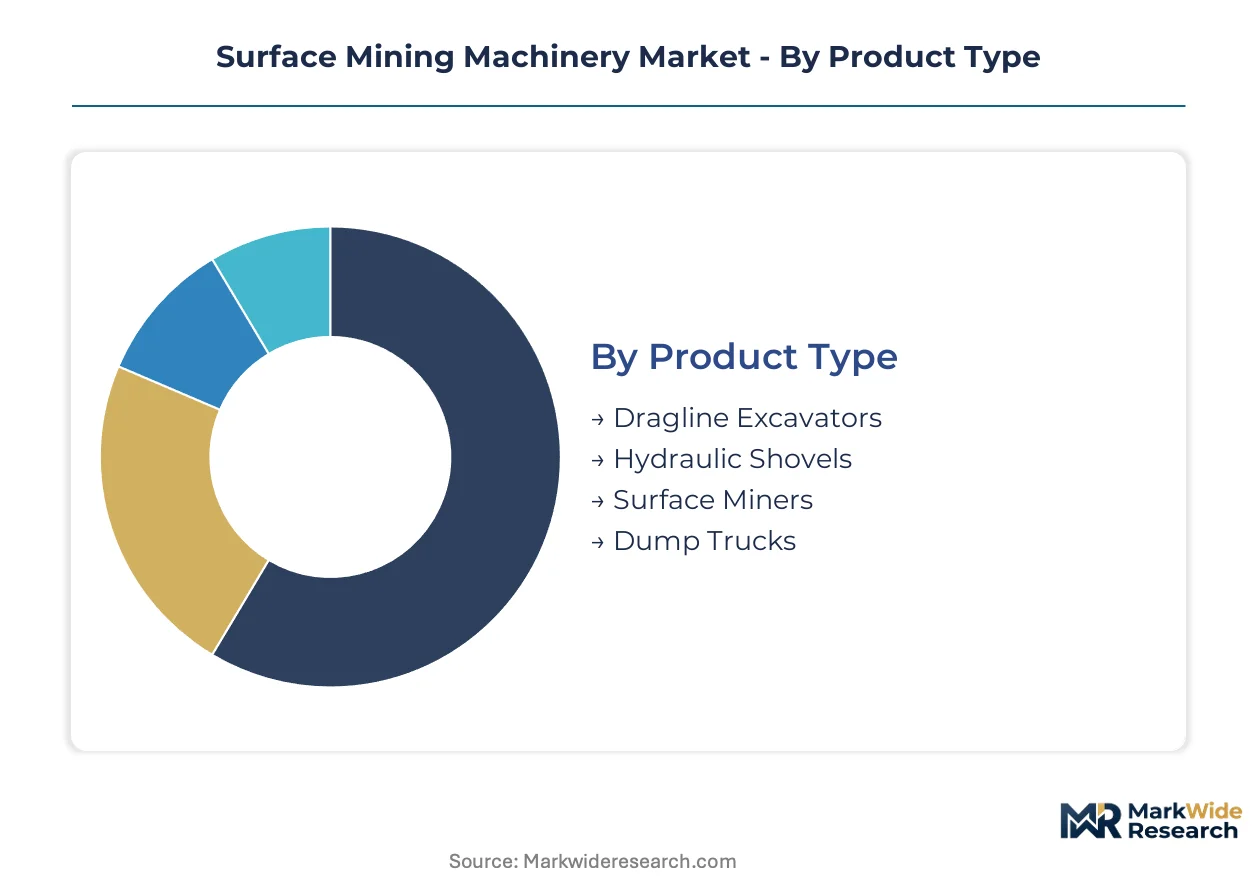
Equipment replacement cycles vary dramatically across surface mining machinery categories, from draglines operating for decades to automation modules refreshing every 3-5 years. Understanding these velocity differences helps suppliers align inventory, service capacity, and R&D pipelines with actual revenue timing.
Product Type:
Cycle times stretch from 40-year dragline rebuilds to 8-year haul truck turnovers, creating divergent aftermarket revenue profiles across the equipment base.
- Dump Trucks:Payload ratings from 190 to 400 metric tons dominate capital deployment in Chilean copper and Australian iron ore basins. Fleet operators in Western Australia now specify electric powertrains for new orders as diesel-to-electric retrofits accelerate under carbon border pressure.
- Hydraulic Shovels:Bucket capacities exceeding 50 cubic meters enable high-volume earthmoving in open-pit operations. Chinese state-owned miners are freezing diesel-powered approvals in Inner Mongolia, redirecting procurement toward electrified variants.
- Dragline Excavators:Single-bucket machines move over 100 million bank cubic meters annually in Appalachian coal districts, with EPA Tier 4 Final compliance forcing costly after-treatment retrofits on aging fleets.
- Surface Miners:Continuous cutting technology for selective ore extraction sees concentrated demand in German limestone and Australian bauxite operations where precision mining reduces processing costs.
Dump trucks anchor the volume base while surface miners gain share at the steepest rate as selective extraction techniques spread beyond traditional applications.
End User:
Customer capital intensity and regulatory exposure create distinct pricing power tiers, from state-backed coal conglomerates to speculative precious metal developers.
- Coal Mining:Appalachian and Inner Mongolian operators face the heaviest emission compliance burdens, with MEE restrictions freezing fleet renewal timelines for state-owned enterprises while EPA standards accelerate scrap-and-replace decisions in US basins.
- Precious Metals:Gold and silver extraction in Nevada and Western Australia drives automation adoption as labor costs and remote site logistics favor autonomous haulage deployment.
- Industrial Minerals:Phosphate and potash operations in Morocco and Saskatchewan prioritize equipment durability over technology refresh given stable, long-life reserve bases.
- Non-Metallic Minerals:Aggregate and limestone producers in Germany and the US exhibit fragmented fleet ownership, creating aftermarket service competition between OEM networks and independent rebuilders.
Coal mining retains the largest installed base though precious metals procurement is climbing the fastest as exploration success in tier-one jurisdictions restarts capital cycles.
Technology:
Engineering resource allocation tilts toward electrification and autonomy as conventional platforms enter harvest mode with diminishing R&D investment.
- Electric:Battery-electric powertrains for 240-ton-class haulers concentrate OEM development hours, with cathode material supply constraints in China creating geopolitical exposure for Western manufacturers scaling production.
- Automation:Autonomous haulage systems require extended field-testing in pit operations, inflating R&D recovery timelines beyond traditional equipment development cycles while delivering 15-20% productivity gains in Australian iron ore deployments.
- Hybrid:Trolley-assist configurations bridge diesel and full electrification, finding niche adoption in Chilean copper valleys where grid infrastructure supports dynamic charging during loaded haul segments.
- Conventional:Diesel-mechanical systems still occupy majority installed base hours but face accelerating displacement as carbon border adjustments tighten economic viability.
Conventional technology anchors the volume base while electric platforms gain share at the steepest rate as battery energy density improvements converge with validation timelines.
Application:
Revenue stability differs markedly between extraction-linked equipment and project-based site development machinery subject to construction cycle volatility.
- Mineral Extraction:Continuous production environments in Chilean copper and Pilbara iron ore generate 90%+ utilization rates, making downtime cost the dominant total cost of ownership factor in procurement decisions.
- Site Development:Greenfield project timing in African copper belts and Indonesian nickel provinces creates lumpy demand patterns tied to permitting and financing milestones.
- Recycling:Construction and demolition waste processing in Germany and Japan employs adapted surface mining equipment as circular economy regulations tighten landfill restrictions.
- Land Restoration:Post-closure rehabilitation in Appalachian coal districts and Australian legacy gold fields deploys refurbished draglines and dozers under regulatory bonding requirements.
Mineral extraction anchors the volume base while recycling applications gain share at the steepest rate as waste recovery regulations expand equipment addressable markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Surface mining machinery deployment patterns diverge sharply by geography: Australian iron ore operators prioritize automation-integrated electrification, while Appalachian coal basins struggle with aging dragline compliance economics against tightening EPA thresholds.
United States
Appalachian coal operators face acute pressure from EPA Tier 4 Final particulate and NOx mandates, forcing costly after-treatment retrofits on dragline fleets where engine replacement economics are marginal. Wyoming Powder River Basin mines are piloting trolley-assist configurations to bridge diesel and full electrification. Pittsburgh-based rebuild specialists compete with OEM captive service networks for aftermarket contracts.
Australia
Pilbara iron ore basins generate 90% equipment utilization rates, making downtime cost the dominant procurement factor for 400-ton-class haul truck fleets. Western Australian operators now specify electric powertrains for new orders as carbon border pressure accelerates diesel-to-electric retrofits. Perth serves as the regional automation validation hub for autonomous haulage system deployment.
Chile
Copper extraction in the Atacama Desert drives orders for battery-electric 240-ton-class haulers as miners supply battery supply chain expansion. Grid infrastructure in Chilean copper valleys supports dynamic charging during loaded haul segments. Antofagasta mining clusters concentrate OEM engineering resource allocation for high-altitude powertrain performance validation.
China
Inner Mongolian coal districts face frozen fleet renewal timelines as MEE enforcement of dual carbon goals restricts diesel machinery approvals for state-owned mining conglomerates. Shanxi Province operators redirect procurement toward electrified hydraulic shovel variants. Xuzhou manufacturing clusters supply domestic OEMs scaling battery-electric powertrain production for 240-ton-class haulers.
Germany
Limestone surface miners see concentrated demand in North Rhine-Westphalia quarries where precision extraction reduces downstream processing costs. EU Green Deal carbon border adjustments create tariff exposure for imported mined commodities, pushing European smelters to demand verified low-carbon extraction equipment. Cologne-based automation specialists develop sensor retrofit kits for legacy fleet productivity extension.
Surface Mining Machinery Market Vendor Landscape
Capability concentration sits with automation-electrification integrators; scale advantage sits with full-line manufacturers with captive remanufacturing networks. The vendor base organizes into three tiers: diversified heavy equipment conglomerates with mining-specific divisions, pure-play mining machinery specialists, and automation technology providers. Consolidation pressure favors players with backward integration into powertrain components and forward integration into predictive maintenance software subscriptions. Geographic expansion into Chilean copper and Australian iron ore basins represents the dominant competitive move, alongside strategic partnerships for battery cell supply security.
Within the diversified conglomerate tier, Caterpillar Inc and Komatsu Ltd exemplify scale-driven positions anchored by global parts distribution networks and captive remanufacturing capabilities. Epiroc AB occupies a specialist position representing the automation retrofit archetype, extending productive life of legacy truck fleets through sensor and control system upgrades. These three entities illustrate how competitive positioning increasingly separates hardware manufacturers from uptime-guarantee service providers.
| Leading Market Players |
|---|
| Caterpillar Inc |
| Komatsu Ltd |
| Hitachi Construction Machinery Co. Ltd |
| Liebherr Group |
| Sandvik AB |
| Volvo Construction Equipment |
| J.C. Bamford Excavators Limited |
| Atlas Copco AB |
| Epiroc AB |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese battery cell manufacturing is compressing supplier margins while simultaneously lowering input costs for Western OEMs developing electric powertrains, creating divergent pricing postures across tier-1 and tier-2 equipment markets. This utilization asymmetry forces incumbent manufacturers to absorb margin erosion on conventional diesel platforms while capturing premium pricing on electrified variants.
Pricing Analysis
Long-term offtake contracts dominate procurement for 240-ton-class haulage fleets in Australian iron ore basins, locking in volume commitments that insulate OEMs from spot-market volatility. Price differentiation stems from automation integration levels and EPA Tier 4 Final certification status, with carbon-compliant equipment commanding substantial premiums over legacy diesel alternatives. Cost compression in battery-electric segments is intensifying because cathode material processing concentrates in China, squeezing Western manufacturers without captive cell supply. Aggregates contractors in Germany exhibit the highest price sensitivity due to fragmented fleet ownership, while Chilean copper majors prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk planning for battery-electric powertrain components, forcing OEMs to diversify cathode material sourcing. Manufacturing capacity concentrates in China, South Korea, and Japan, with Xuzhou clusters supplying domestic OEMs and Korean cell makers feeding Western electrification programs. Raw material dependencies center on lithium carbonate from Chilean salares, cobalt hydroxide from the Democratic Republic of Congo, and high-grade nickel from Indonesian laterite operations. Single-source vulnerability in rare earth permanent magnets for traction motors threatens production continuity. Distribution runs through OEM captive service networks and independent rebuild specialists competing for aftermarket contracts in Pilbara and Appalachian basins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification and autonomy convergence is accelerating capital deployment cycle compression, with EPA Tier 4 Final and EU Green Deal carbon border adjustments forcing irreversible fleet renewal decisions across major mining jurisdictions.
For Market Incumbents: Harden automation-electrification integration capabilities through backward integration into battery management systems and power electronics manufacturing. Defend installed base relationships by embedding predictive maintenance subscriptions into finance lease structures, neutralizing independent rebuild specialists competing for Australian iron ore aftermarket contracts. Prioritize engineering resource allocation to high-altitude powertrain validation in Chilean copper valleys where grid infrastructure supports dynamic charging deployment. For New Entrants and Emerging Players: Establish a beachhead in automation retrofit kits for legacy 190-ton-class haul truck fleets across Australian iron ore basins, where Epiroc AB's specialization demonstrates expandable white space. Target the diesel-to-electric conversion segment in Appalachian coal districts facing acute EPA Tier 4 Final compliance pressure, where dragline fleet economics favor retrofit over replacement. Pursue sensor and control system upgrades as a service-based entry vector rather than capital equipment sales. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across battery-electric powertrain development, favoring asset-light automation software specialists over heavy manufacturing platforms. Acquisition targets should concentrate on predictive maintenance algorithm developers and high-voltage servicing certification providers addressing electrification skill gaps constraining fleet uptime. Monitor battery energy density improvement trajectories and autonomous haulage system validation timelines as the critical convergence signal for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Management Systems | Captive control over power electronics reduces exposure to Chinese cathode supply concentration. |
| Automation Retrofit Kit Development | Sensor upgrades extend productive life of legacy truck fleets in Australian iron ore basins. |
| Predictive Maintenance Subscription Embedding | Software licenses bundled into finance leases defend OEM attachment rates against independent rebuilders. |
| High-Altitude Powertrain Validation Partnerships | Antofagasta mining clusters provide proving grounds for Chilean copper valley electrification deployment. |
| Electrification Technician Certification Programs | Addressing high-voltage servicing skill gaps enables uptime guarantees for battery-electric fleet contracts. |
Methodological Framework
A spread of perspectives from mine maintenance directors, OEM procurement teams, aftermarket service heads, and EPC contractors converged on the working assumptions governing electrification adoption timelines. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, customs and trade data for machinery imports, and EPA enforcement action databases. Bottom-up equipment shipment tallies and top-down mining capital expenditure surveys were triangulated to anchor volume estimates.
Demand-supply-balance dynamics across the projection horizon shaped the analytical framework, with segmentation modeling across equipment type, technology platform, end-use commodity, and regional regulatory cluster. CAGRs were derived from equipment replacement cycle analysis and carbon compliance deadline impacts. Industry-specific forecast inputs incorporated battery energy density improvement curves and autonomous haulage system field-testing duration benchmarks from Perth validation hubs.
Sensitivities concentrate around MEE enforcement intensity in Inner Mongolia, EU Green Deal carbon border adjustment implementation timing, and cathode material supply chain disruption scenarios. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Mining Equipment
Smart Mining Market
Mining Equipment
Global Dozers Market
Mining Equipment
Underground Mining Automation Market
Mining Equipment
Drill Pipe Market
Mining Equipment
Global Connected Mining Market
Mining Equipment
Logging Cable Market
Mining Equipment
Global Autonomous Mining Equipment Market
Mining Equipment
Construction and Mining Equipment Spare Parts Market
Mining Equipment
Mining Drilling Services Market
Mining Equipment
Air Core Drilling Market
Mining Equipment
Smart Mining Technologies Market
Mining Equipment
Auger Drilling Machine Market
Mining Equipment
Underground Mining Equipment Market
Mining Equipment
Mining Drill Market
Mining Equipment
Latin America Mining Equipment Market
Mining Equipment
Drilling Stabilizers Market