
 Loader Bucket Attachments Market | 2026-2036
Loader Bucket Attachments Market Size, Share, and Industry Trends Forecast 2026-2036
Loader Bucket Attachments Market Analysis
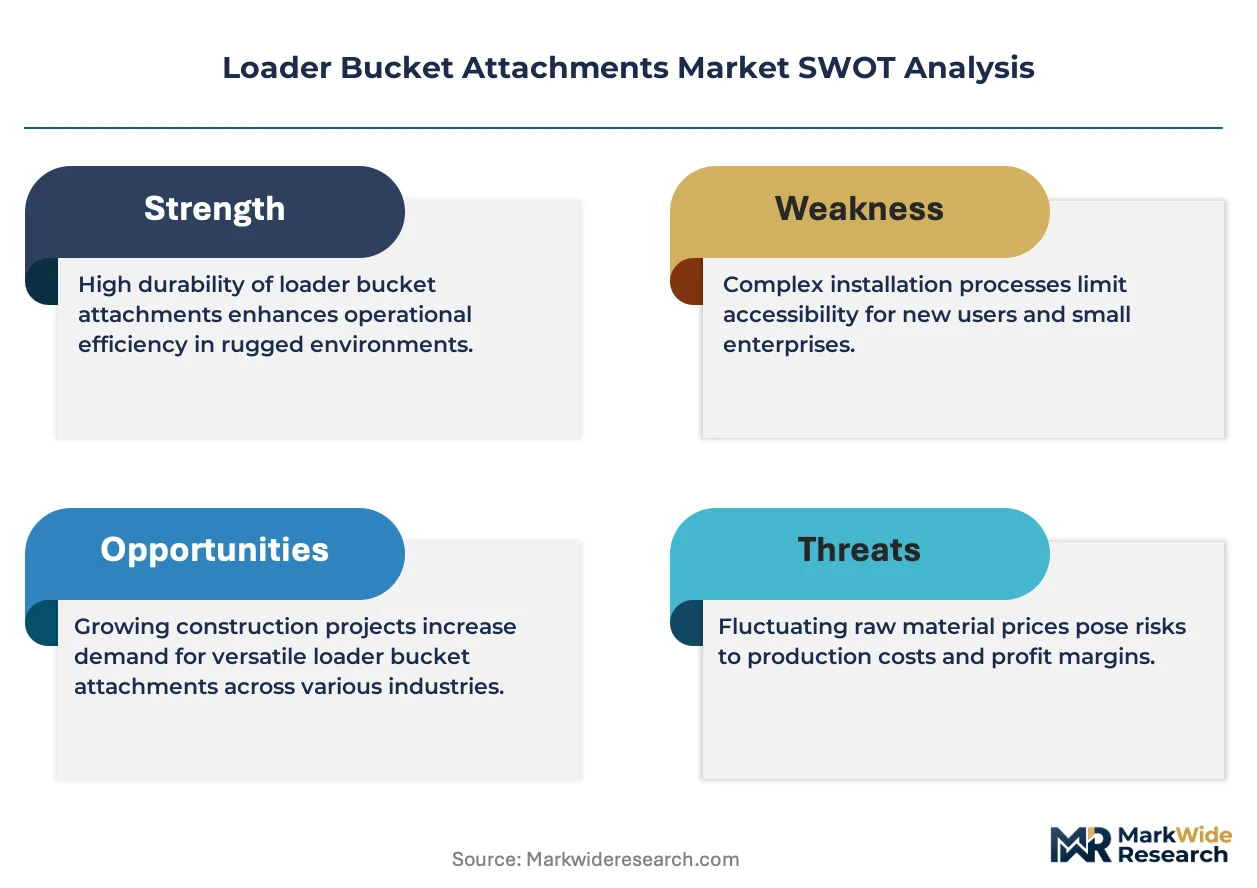
High-strength alloy specification tiers is redrawing competitive boundaries in loader bucket attachments. Caterpillar leverages its captive steel forging network to control alloy grade consistency across heavy-duty bucket lines. Komatsu anchors its position through integrated heat-treatment facilities that extend wear-plate durability in rock excavation cycles. Volvo Construction Equipment differentiates via proprietary payload-weighing systems embedded in grapple bucket architectures.
Loader bucket attachments are interchangeable front-end implements mounted to wheel loaders, skid steers, and compact track loaders, typically fabricated from quenched-and-tempered boron steel plate with hardness ratings exceeding 400 BHN to resist abrasion in aggregate handling. Their primary purpose is to adapt base machines across material handling, excavation, and site preparation tasks without dedicated equipment procurement. General purpose buckets still command the largest volume position due to universal compatibility across construction and agricultural fleets, though grapple buckets are capturing margin pools in waste management applications where sorted material recovery commands premium pricing. Steel dominates material selection for structural components, while polymer and composite inserts are gaining traction in snow buckets where weight reduction preserves machine lifting capacity.
EPA Tier 4 Final and OSHA silica exposure standards are reshaping attachment design priorities, with dust-suppression integration and enclosed cab compatibility becoming baseline requirements for construction site access. The EU Machinery Directive and CE marking protocols govern export eligibility for North American and Asian manufacturers serving European rental fleets. Stakeholders must monitor how upcoming EPA greenhouse gas regulations for off-road equipment cascade into weight-reduction mandates that favor alloy and composite material segments over traditional steel fabrications.
Market Dynamics
Emissions compliance deadlines are compressing product development cycles for loader bucket attachments, forcing fabricators to reconcile weight-reduction mandates with abrasion-resistance requirements in quenched boron steel architectures.
Growth Catalysts
- EPA Tier 4 Final:Off-road equipment emissions standards are accelerating fleet turnover in United States aggregate processing, creating replacement demand for compatible attachments with enclosed cab interfaces.
- Waste-to-energy infrastructure:Municipal solid waste diversion programs in Germany and France are expanding grapple bucket procurement for sorted material recovery at mechanical-biological treatment facilities.
- High-strength boron alloys:Hardness ratings exceeding 450 BHN are extending wear-plate service intervals in Canadian oil sands extraction, reducing downtime costs for winter-season operations.
Market Restraints
- Scrap steel price volatility:Quenched-and-tempered plate input costs fluctuate with Turkish and Vietnamese export flows, squeezing margin predictability for mid-tier fabricators.
- Heat-treatment capacity concentration:Integrated facilities in Germany's Ruhr industrial cluster control premium wear-plate processing, creating supply bottlenecks for North American OEMs lacking captive thermal infrastructure.
- Silica exposure compliance:OSHA's respirable crystalline silica standard is mandating dust-suppression integration that adds component cost without proportional pricing power in rental fleet channels.
Strategic Opportunities
- India's National Infrastructure Pipeline:Aggregate handling demand at highway and rail corridor projects is outpacing domestic attachment supply, creating import substitution potential for hardened steel bucket suppliers.
- EU Green Deal machinery retrofit mandates:Stage V engine upgrades in older wheel loaders are driving attachment refresh cycles as fleets seek weight-matched implements to preserve hydraulic performance.
- Telematics-payload convergence:Integration of load-weighing sensors with fleet management platforms is opening premium pricing tiers for grapple buckets in precision agriculture and port logistics.
Industry Challenges
- Welding automation skill scarcity:Robotic seam welding of complex bucket geometries requires certified operators that fabrication shops in the United States Great Lakes corridor struggle to recruit at competitive wages.
- CE marking timeline compression:EU Machinery Directive conformity assessment delays for new alloy grades are extending time-to-revenue for North American exporters serving European rental fleets.
- Legacy hydraulic interface fragmentation:Proprietary quick-coupler designs across Caterpillar, Komatsu, and Volvo machine lines force attachment makers to maintain redundant tooling inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loader Bucket Attachments Market |
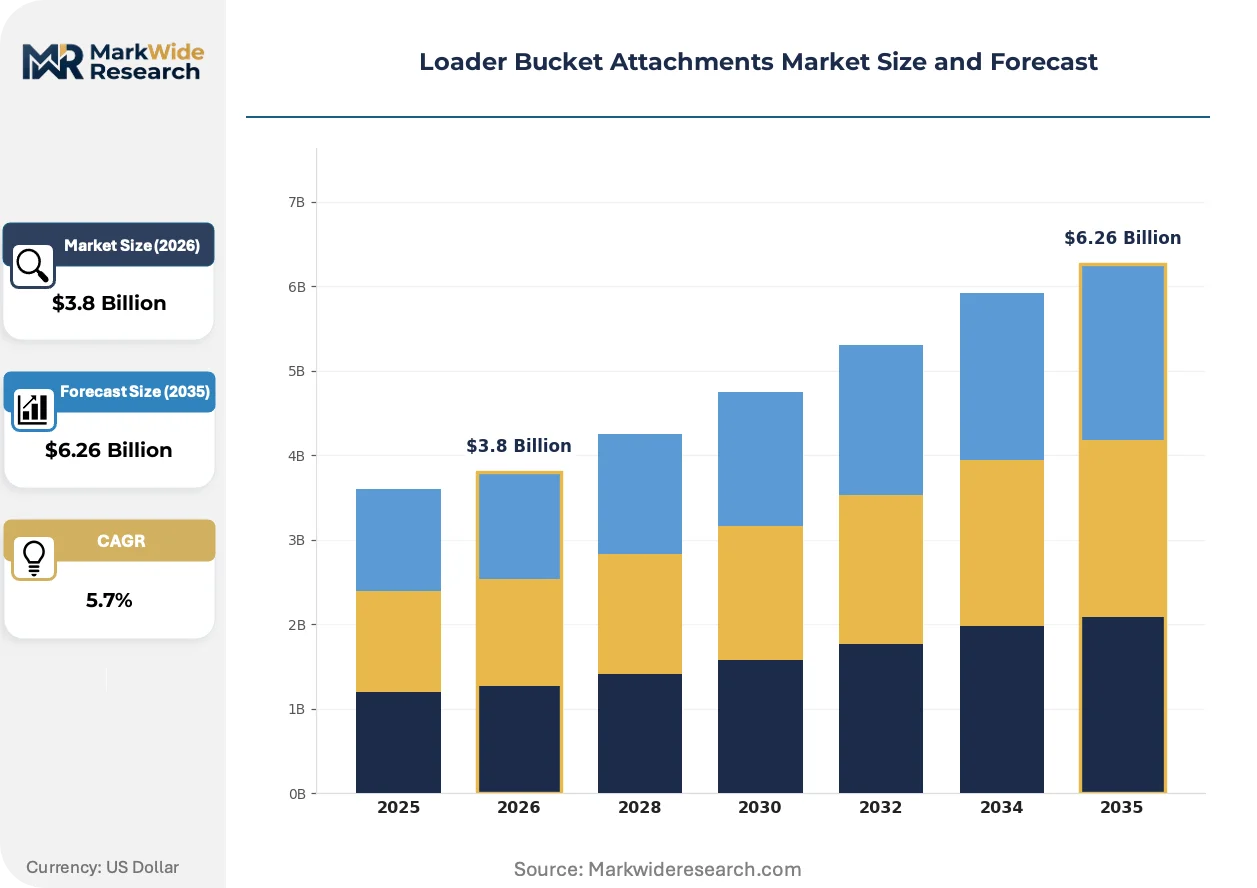
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose Buckets, Rock Buckets, Snow Buckets, Grapple Buckets Material: Steel, Polymer, Alloy, Composite End User: Construction, Agriculture, Waste Management, Landscaping Size: Standard, Heavy-duty, Compact, Extended |
| Companies Covered | Caterpillar, Komatsu, Volvo Construction Equipment, John Deere, Doosan, Liebherr, JCB, Hitachi Construction Machinery, Paladin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loader Bucket Attachments Market Emerging Trajectories
Attachment architectures are converging around sensor-embedded intelligence and material substitution, compressing the traditional trade-off between structural durability and machine payload efficiency.
Polymer-composite cutting edges are miniaturizing in snow bucket applications, replacing hardened steel bolt-on segments to reduce implement weight by fifteen to twenty percent. Municipal winter maintenance fleets in Minnesota and Wisconsin are adopting these hybrid designs to preserve lifting capacity on mid-size wheel loaders. The technology is miniaturizing the addressable market for traditional steel fabricators while opening margin pools for composite specialists with automotive supply chain heritage.
REACH substance restrictions on hexavalent chromium plating are eliminating traditional hard-chrome cylinder rod finishes for grapple bucket hydraulics across European Union member states. Fabricators are pivoting to nickel-tungsten carbide composite coatings or laser-clad alternatives that meet corrosion-resistance specifications without SVHC classification. Rental fleet operators in France and Benelux markets are now specifying REACH-compliant attachments as a procurement gate, forcing Asian exporters to reformulate surface treatment processes.
Fleet telematics integration is reshaping attachment procurement from capital expenditure to performance-contracted availability models. Large aggregate producers in Texas and Alberta are unbundling attachment ownership from machine uptime guarantees, pressuring OEMs to offer wear-based replacement schedules rather than unit sales. This service transition concentrates purchasing authority with corporate procurement functions and away from site equipment managers, compressing supplier margins through volume aggregation.
Loader Bucket Attachments Market Segmentation
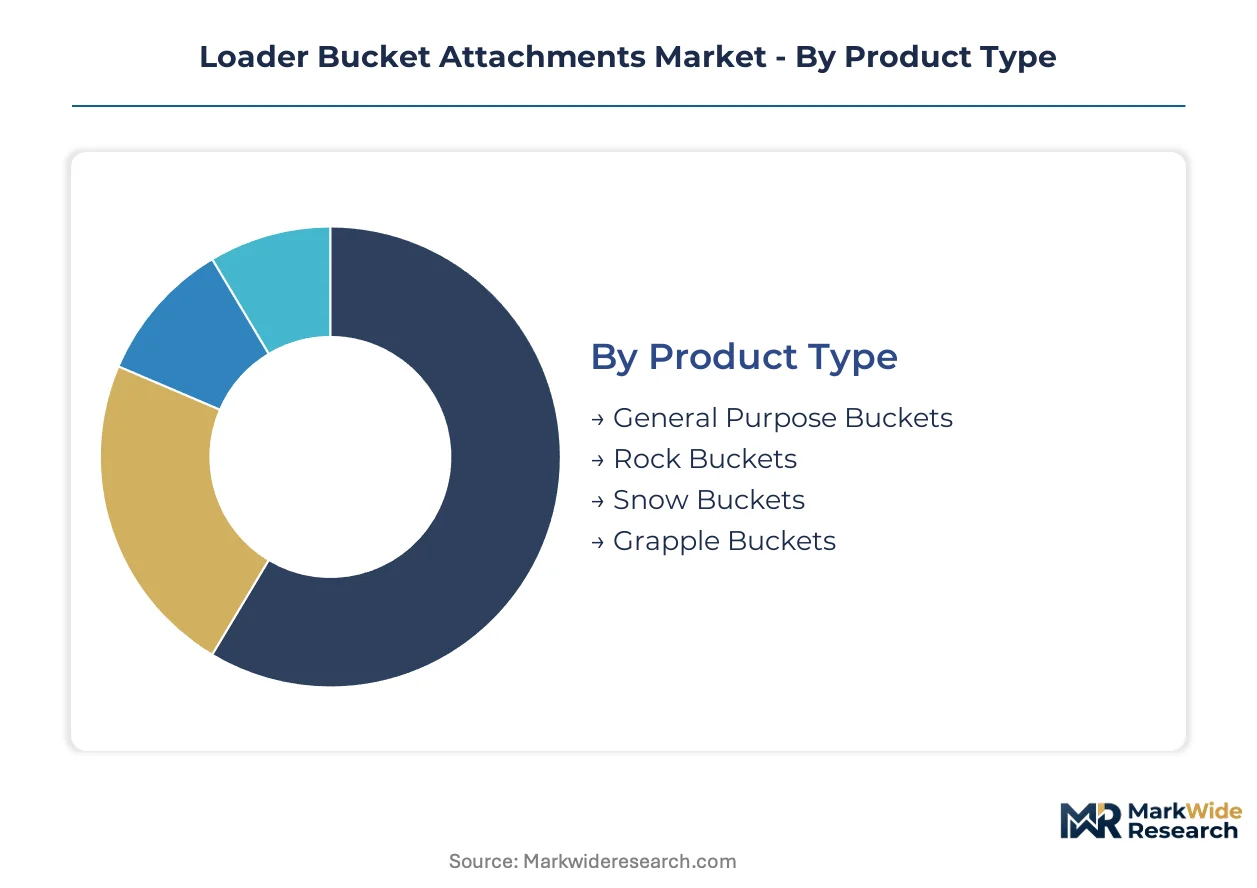
Loader bucket attachment specifications cascade directly into machine fuel efficiency, hydraulic performance, and regulatory compliance. Fabricators align product architectures with emissions mandates, material handling intensity, and seasonal procurement cycles across municipal and industrial fleets.
Product Type:
Margin pools concentrate in specialized designs that command premium pricing through durability certification and application-specific engineering.
- General Purpose Buckets:Fabricated from quenched boron steel plate with hardness ratings exceeding 400 BHN, these attachments prioritize universal quick-coupler compatibility across wheel loader and skid steer fleets. Demand clusters in United States aggregate processing corridors where seasonal fleet turnover accelerates replacement cycles under Tier 4 Final compliance deadlines.
- Grapple Buckets:Multi-tine hydraulic architectures integrate proprietary payload-weighing sensors for sorted material recovery operations. Waste-to-energy infrastructure expansion across Germany and France is driving procurement for mechanical-biological treatment facilities where precision load documentation supports diversion credit verification.
- Rock Buckets:Reinforced corner gussets and abrasion-resistant wear plates extend service intervals in Canadian oil sands extraction.
- Snow Buckets:Polymer-composite cutting edges reduce implement weight by fifteen to twenty percent for municipal winter maintenance fleets in Minnesota and Wisconsin.
The dominant share belongs to General Purpose Buckets, while Grapple Buckets are closing the gap fastest.
Material:
Cost tiers separate commodity fabricators from specialists controlling captive heat-treatment infrastructure.
- Steel:Quenched-and-tempered boron plate remains the structural baseline for heavy-duty excavation cycles, with hardness specifications dictating wear-plate replacement economics. Turkish and Vietnamese scrap export flows create input cost volatility that squeezes margin predictability for mid-tier fabricators lacking long-term mill contracts.
- Alloy:High-strength specifications exceeding 450 BHN enable weight reduction without payload sacrifice, aligning with Stage V emissions standards. Germany's Ruhr industrial cluster controls premium wear-plate processing capacity, creating supply bottlenecks for North American OEMs without captive thermal infrastructure.
- Polymer:Snow bucket cutting edge applications in Great Lakes municipal fleets leverage automotive supply chain heritage for hybrid designs.
- Composite:Multi-material architectures merge structural steel with fiber-reinforced polymer inserts for weight-critical agricultural handling.
Steel retains volume leadership, though Alloy specifications are expanding most quickly in emissions-regulated jurisdictions.
End User:
Application intensity determines abrasion-resistance specifications and attachment refresh frequency.
- Construction:EPA Tier 4 Final and OSHA silica exposure standards mandate dust-suppression integration and enclosed cab compatibility as baseline site access requirements. Fleet procurement concentrates with corporate equipment managers rather than site supervisors as telematics-enabled uptime contracts displace unit sales.
- Waste Management:Sorted material recovery operations command premium pricing for grapple buckets with REACH-compliant hydraulic finishes. France and Benelux rental fleet operators now specify nickel-tungsten carbide coatings as procurement gates, eliminating Asian exporters with legacy hexavalent chromium processes.
- Agriculture:Precision load-weighing convergence with fleet management platforms opens premium tiers for grain handling operations.
- Landscaping:Compact loader compatibility drives standardized quick-coupler procurement across municipal parks departments.
Construction anchors current volume, yet Waste Management is gaining share fastest through diversion infrastructure mandates.
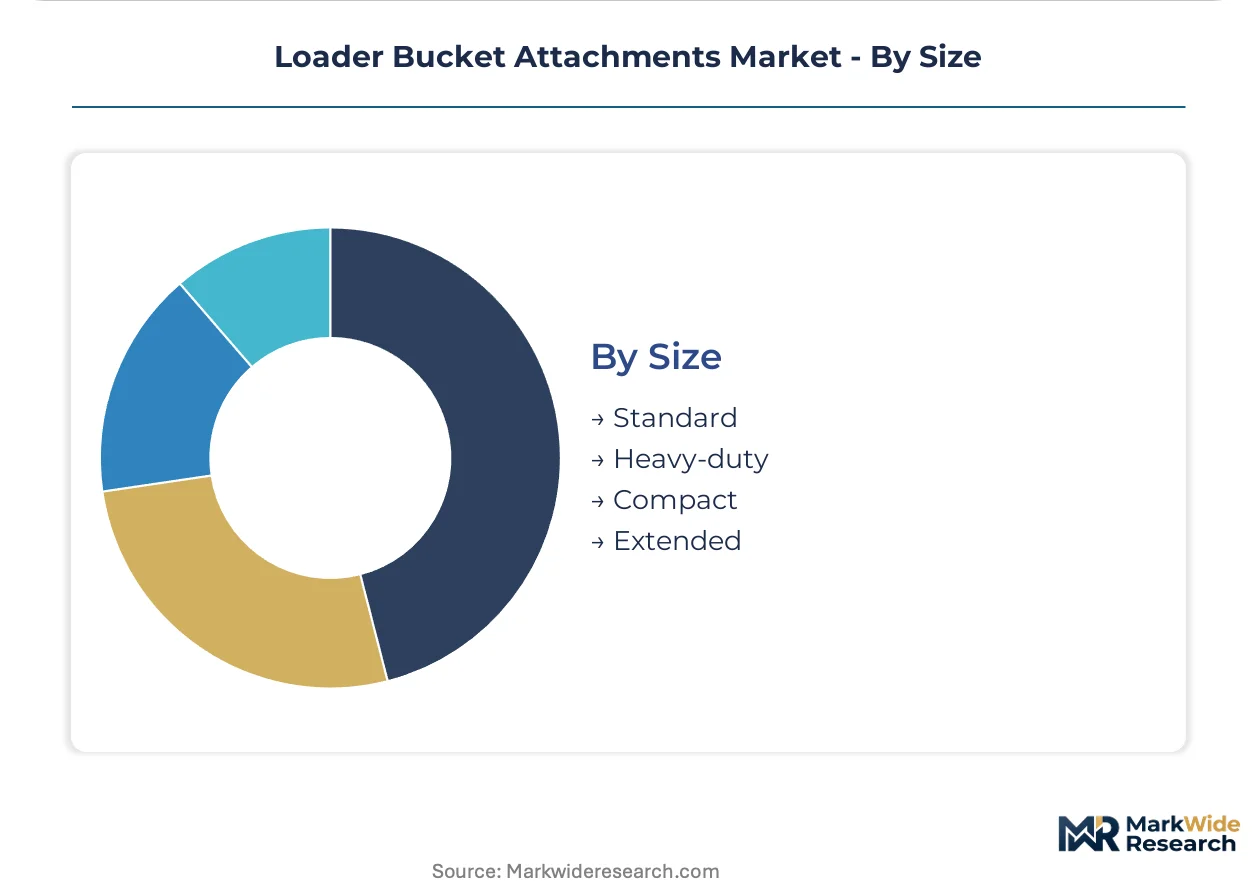
Size:
Customer type stratification separates rental fleet standardization from owner-operator customization.
- Heavy-duty:Reinforced sidewall construction and extended wear packages target Canadian oil sands and Texas aggregate producers with continuous-duty cycle requirements. OEMs unbundle attachment ownership from machine uptime guarantees, concentrating purchasing authority with corporate procurement functions.
- Compact:Skid steer and compact track loader interfaces dominate landscaping and light construction applications where maneuverability constraints override capacity optimization. Proprietary quick-coupler designs across Caterpillar, Komatsu, and Volvo machine lines force attachment makers to maintain redundant tooling inventories.
- Standard:Universal compatibility positioning serves rental fleet operators seeking cross-machine deployment flexibility.
- Extended:High-capacity architectures for port logistics and bulk material handling require matched hydraulic system calibration.
Heavy-duty specifications hold the dominant position, while Compact configurations are climbing the fastest through skid steer fleet expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in loader bucket attachments reflect concentrated manufacturing capacity in Germany and the United States against import dependency in infrastructure-expanding markets. Trade balances favor alloy-grade fabricators with captive heat-treatment infrastructure.
United States
Aggregate processing corridors across Texas and the Great Lakes drive seasonal procurement cycles for Tier 4 Final compatible attachments. EPA emissions deadlines compress fleet replacement timelines, accelerating demand for enclosed-cab interface designs. Manufacturing concentrates in Illinois and Ohio fabrication clusters serving municipal winter maintenance contracts.
Germany
Waste-to-energy infrastructure expansion across mechanical-biological treatment facilities commands premium grapple bucket specifications. REACH substance restrictions on hexavalent chromium plating mandate nickel-tungsten carbide hydraulic finishes for EU market access. The Ruhr industrial cluster controls premium wear-plate heat-treatment capacity, creating supply bottlenecks for non-integrated competitors.
Canada
Oil sands extraction operations in Alberta require rock bucket architectures with hardness ratings exceeding 450 BHN for winter-season durability. Federal emissions harmonization with EPA standards drives attachment refresh cycles alongside wheel loader fleet turnover. Fabrication demand clusters in Edmonton and Calgary serving energy sector procurement.
India
National Infrastructure Pipeline highway and rail corridor projects outpace domestic attachment supply, creating import substitution openings for hardened steel bucket suppliers. BIS certification requirements govern structural steel specifications for construction equipment attachments. Manufacturing activity concentrates in Maharashtra and Gujarat industrial zones targeting aggregate handling demand.
France
Sorted material recovery mandates expand grapple bucket procurement for municipal solid waste diversion programs. EU Green Deal machinery retrofit requirements drive attachment refresh cycles alongside Stage V engine upgrades. Rental fleet operators in Paris and Lyon markets specify REACH-compliant surface treatments as procurement gates.
Loader Bucket Attachments Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and heat-treatment capability dimensions. The vendor base stratifies between integrated OEMs with captive steel forging networks and regional fabricators dependent on outsourced thermal processing. Three archetypes dominate: alloy-grade specialists controlling premium wear-plate infrastructure, telematics-embedded system integrators, and cost-optimized commodity fabricators serving rental channels. Consolidation pressures concentrate through M&A activity targeting heat-treatment capacity, while strategic partnerships proliferate around sensor-embedded payload systems.
Among diversified construction equipment manufacturers, Caterpillar, Komatsu, and Volvo Construction Equipment occupy positions spanning premium alloy specification and integrated telematics architectures. These entities exemplify the integrated OEM archetype through captive supply chain control over steel grade consistency and thermal processing. Their positioning reflects the competitive premium attached to emissions-compliant, weight-optimized designs serving regulated jurisdictions.
| Leading Market Players |
|---|
| Caterpillar |
| Komatsu |
| Volvo Construction Equipment |
| John Deere |
| Doosan |
| Liebherr |
| JCB |
| Hitachi Construction Machinery |
| Paladin |
| Others |
Supply Flow & Price Mechanics
Long-term mill contracts for quenched-and-tempered boron plate lock in both alloy grade consistency and cost visibility for attachment fabricators serving Tier 4 Final fleet replacement cycles. These agreements insulate integrated OEMs from Turkish and Vietnamese scrap export volatility while exposing mid-tier fabricators to margin compression.
Pricing Analysis
Industrial OEM buyers anchor three-tier pricing stratification across premium, standard, and economy levels. Premium tiers attach to hardness certifications exceeding 450 BHN and REACH-compliant hydraulic finishes, while economy tiers serve rental fleets with basic wear-plate specifications. Cost compression in mid-grade segments is intensifying because scrap steel price volatility transfers directly to fabricators lacking captive forging networks. Municipal procurement teams exhibit highest price sensitivity, whereas oil sands operators prioritize service-interval guarantees over unit cost.
Supply Chain Analysis
Germany's Ruhr industrial cluster heat-treatment capacity controls premium wear-plate processing for North American and Asian OEMs. Raw material flows draw from Turkish scrap export terminals, Vietnamese quenched-plate mills, and domestic boron steel producers in the United States Great Lakes corridor. Single-source vulnerability concentrates in thermal processing infrastructure, where integrated German facilities create bottlenecks for non-captive competitors. Distribution runs through OEM captive networks and independent fabrication shops serving regional rental fleets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Loader bucket attachments sit in early-cycle expansion as emissions compliance deadlines compress fleet replacement timelines and telematics integration opens performance-contracting revenue models.
For Market Incumbents: Shield alloy-grade positioning by deepening backward integration into captive heat-treatment infrastructure before Ruhr cluster bottlenecks harden. Secure long-term offtake agreements with boron steel mills to defend margin position against scrap price volatility. Prioritize sensor-embedded payload system R&D to capture telematics convergence premiums in precision agriculture and port logistics. For New Entrants and Emerging Players: CE marking fast-track programs for REACH-compliant hydraulic finishes unlock European rental fleet procurement gates currently closed to Asian exporters with legacy hexavalent chromium processes. Target India's National Infrastructure Pipeline aggregate handling demand, where domestic attachment supply shortages create import substitution openings. Pursue joint-venture structures with automotive composite specialists to miniaturize polymer cutting edge technology for Great Lakes municipal snow fleets. For Investors and Strategic Acquirers: Mid-cap fabrication specialists with certified robotic welding capabilities represent priority acquisition targets as skill scarcity intensifies across the United States Great Lakes corridor. Long-term viability hinges on heat-treatment capacity control and telematics integration depth. Watch for inflection when fleet telematics penetration crosses threshold for performance-contracted availability models to displace unit sales in Texas and Alberta aggregate operations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment | Ruhr cluster bottlenecks reward captive thermal infrastructure with premium wear-plate pricing power. |
| REACH-Compliant Surface Treatment Reformulation | Nickel-tungsten carbide coatings unlock EU rental fleet procurement gates in France and Benelux markets. |
| Telematics-Payload Sensor Integration | Load-weighing convergence with fleet management platforms opens premium pricing tiers in precision agriculture. |
| Robotic Welding Automation Deployment | Certified operator scarcity across Great Lakes fabrication clusters creates sustainable cost advantages. |
| Composite Cutting Edge Partnership | Automotive supply chain heritage enables fifteen to twenty percent weight reduction for municipal snow fleets. |
Methodological Framework
The analysis maps general purpose, grapple, rock, and snow bucket sub-sectors, each validated through OEM procurement directors, rental fleet equipment managers, and municipal maintenance supervisors. Primary interviews with heat-treatment facility operators and aftermarket service heads cross-check capacity utilization and replacement cycle timing. Secondary sources include EPA Tier 4 Final compliance filings, EU Machinery Directive CE marking databases, Turkish and Vietnamese customs export records, and aggregate producer fleet disclosure documents. Bottom-up attachment unit demand triangulates against top-down wheel loader production data.
Consistency checks validate volume and value outputs against external benchmarks across the projection horizon. The analytical framework models product type, material specification tier, end-use intensity, and machine size class dimensions. CAGRs derive from replacement cycle compression under emissions deadlines and telematics adoption curves. Industry-specific inputs include hardness rating upgrade trajectories, scrap steel price correlation models, and REACH substance restriction implementation timelines.
Underlying assumptions cover emissions compliance deadline adherence, alloy grade availability from mill networks, and telematics platform interoperability standards, with deviation risk concentrated in heat-treatment capacity expansion delays and trade flow disruptions from Turkish scrap export policy shifts. Practitioners should keep alternative scenarios live as Stage V harmonization schedules and EPA greenhouse gas rulemakings evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
High-Density Racks Market
Material Handling Equipment
Forklift Tire Market
Material Handling Equipment
Heavy Duty Telehandler Market
Material Handling Equipment
High-Precision Gear Reducer Market
Material Handling Equipment
Industrial Static Equipment Market
Material Handling Equipment
Slag Handling Equipment Market
Material Handling Equipment
Hose Pipe Market
Material Handling Equipment
Pneumatic Conveying Systems Market
Material Handling Equipment
Dock Levelers Market
Material Handling Equipment
Trencher Attachments Market
Material Handling Equipment
Hydraulics Components Market
Material Handling Equipment
Middle East and Africa Automated Material Handling Market
Material Handling Equipment
Coal Handling Equipment Market
Material Handling Equipment
Low Clearance Loaders Market
Material Handling Equipment
Arrestor Cables Market
Material Handling Equipment
Rolling Mill Machine Market