
 Crane Motors Market | 2026-2036
Crane Motors Market Size, Share, and Industry Trends Forecast 2026-2036
Crane Motors Market Outlook
Project finance and equipment leasing structures are reshaping competitive dynamics in crane motor supply. Konecranes leverages its service-network density to bundle motor replacement into long-term maintenance contracts. SANY anchors its position through backward integration into foundry and winding operations, controlling input cost volatility. XCMG competes aggressively on delivery speed for standard-duty electric motors in emerging markets.
Crane motors are electromechanical power units engineered to deliver high starting torque, intermittent duty cycles, and precise load control under severe mechanical stress, typically operating at IP55 protection or higher. These motors convert electrical energy into rotational mechanical force to drive hoist, trolley, and bridge mechanisms in overhead and gantry crane systems. Electric motors dominate installed base volumes across construction and manufacturing applications, while servomotors command premium positioning where millimeter-grade load positioning justifies higher capital outlay. AC motor technology sustains the broadest addressable market due to grid compatibility and maintenance simplicity, whereas brushless DC variants capture share in automated warehousing and aerospace end-user settings demanding extended operational life.
FCC electromagnetic compatibility standards govern motor controller emissions in US installations, while EU CE marking and Machinery Directive compliance shape product design for European access. China's GB standards and MIIT energy-efficiency classifications dictate minimum performance thresholds for domestic and export-bound motor production. Stakeholders must monitor how evolving carbon-border adjustment mechanisms and regional efficiency mandates recalibrate manufacturing location decisions and certification investment priorities.
Market Dynamics
Port operators in China's coastal manufacturing belts are driving procurement intensity as container throughput expansion demands higher-capacity hoist systems, while EU F-Gas Regulation compliance costs are restructuring motor enclosure cooling specifications for European installations.
Growth Catalysts
- Container throughput expansion:Port operators in Shanghai and Ningbo-Zhoushan are scaling crane motor procurement to match rising cargo volumes through Asia-Pacific shipping lanes.
- EU F-Gas Regulation:Tightened refrigerant-based cooling requirements for motor enclosures are accelerating replacement cycles in European port and heavy manufacturing installations.
- Permanent magnet motor technology:Adoption of rare-earth magnet designs is improving torque density and reducing energy losses in high-duty-cycle crane applications.
Market Restraints
- Copper and rare-earth price volatility:Winding wire and magnet material cost swings compress margin predictability for motor manufacturers serving price-sensitive infrastructure projects.
- Foundry capacity concentration:Specialized cast iron and aluminum housing production clusters in specific Chinese provinces create geographic supply vulnerability during regional disruptions.
- Technical limitation in extreme duty cycles:Thermal management constraints in continuous heavy-lift applications limit standard motor lifespans below total crane system depreciation schedules.
Strategic Opportunities
- Underpenetrated Southeast Asian port infrastructure:Vietnam and Indonesia are expanding container terminal capacity without mature domestic motor supply chains, creating import substitution openings.
- Regulatory tailwind from China's dual carbon goals:MIIT energy-efficiency classifications are mandating premium-efficiency motor adoption in domestic heavy industry, elevating technical specifications.
- IoT-enabled predictive maintenance convergence:Integration of vibration sensing and thermal monitoring with motor controllers is creating recurring revenue streams through condition-based service contracts.
Industry Challenges
- Electromechanical technician shortage:Specialized skills in high-voltage winding repair and magnetic bearing alignment are scarce in emerging market installation bases.
- CE marking and Machinery Directive certification timelines:Extended third-party testing periods for European market entry delay revenue recognition on custom-engineered motor configurations.
- Legacy DC system integration complexity:Retrofitting aging crane fleets with modern AC variable-frequency drives requires mechanical brake and control system coordination that extends project durations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crane Motors Market |
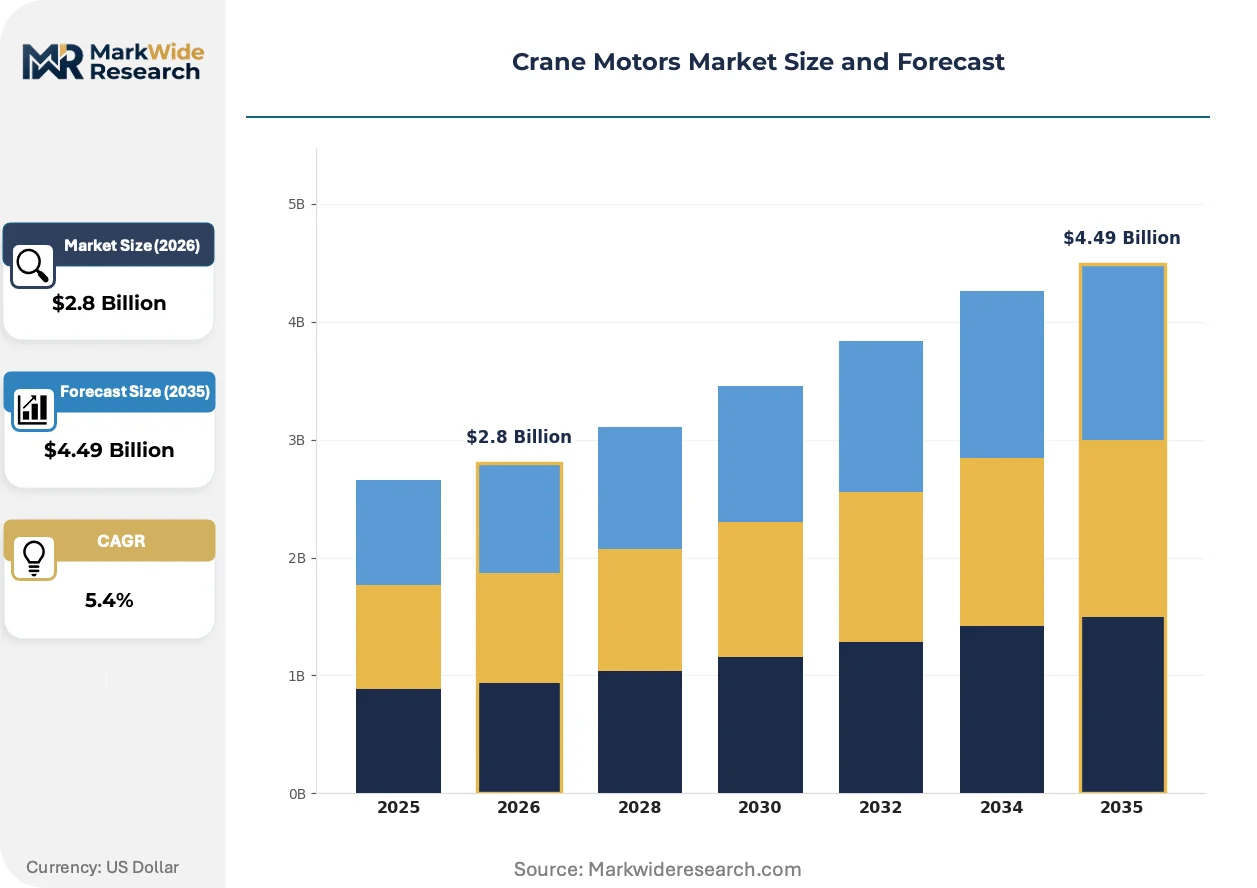
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.49 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Motors, Hydraulic Motors, Pneumatic Motors, Servomotors Application: Construction, Manufacturing, Shipping, Mining Technology: AC Motors, DC Motors, Stepper Motors, Brushless Motors End User: Industrial, Commercial, Infrastructure, Aerospace |
| Companies Covered | Uesco Industries, Inc., Gorbel, Inc., Konecranes, SANY, XCMG, Demag Cranes, EMH, Inc, Clescrane, LOADMATE INDUSTRIES PRIVATE LIMITED, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crane Motors Market Strategic Shifts
Sensor-embedded motor architectures and predictive analytics platforms are transforming crane motor value propositions from commodity hardware to integrated uptime-guarantee systems.
Variable-frequency drive technology with integrated edge computing is digitizing load profiling and energy consumption patterns in real-time. Port operators in Rotterdam and Hamburg are deploying these systems at scale to optimize hoist acceleration curves against vessel loading windows. The resulting operational data streams are digitizing maintenance scheduling from calendar-based to condition-triggered interventions, compressing unplanned downtime incidence.
EU F-Gas Regulation phase-down schedules are forcing refrigerant transitions in motor enclosure cooling systems. Manufacturers serving European port and steel mill installations must redesign thermal management around lower-global-warming-potential alternatives. This regulatory pressure is most acute in German heavy-lift applications, where operators are absorbing redesign costs to maintain CE-marked equipment eligibility.
Leasing and power-by-the-hour contracting are displacing outright motor purchase in capital-constrained infrastructure markets. African and Latin American port authorities are adopting this model to bypass upfront capex requirements while accessing premium-efficiency equipment. Brazilian container terminal operators have emerged as early adopters, structuring contracts around guaranteed availability metrics rather than asset ownership.
Crane Motors Market Segmentation
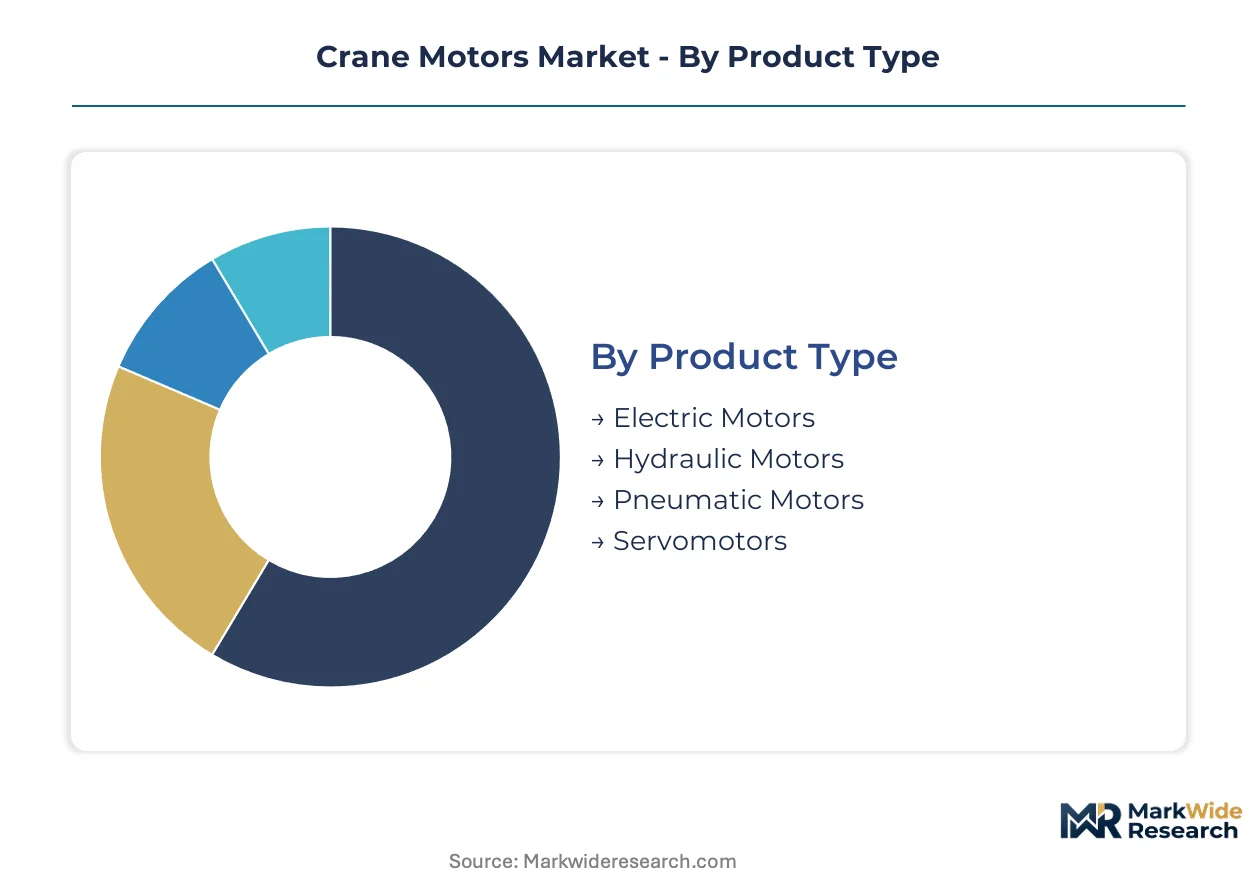
Crane motor segmentation determines service contract structures, spare parts inventory depth, and technician specialization requirements. Product type and application boundaries shape aftermarket revenue potential more acutely than initial equipment margins.
Product Type:
After-sales-service intensity varies sharply across motor technologies, with winding repair cycles and bearing replacement schedules dictating long-term vendor relationships.
- Electric Motors:AC and DC electromechanical units dominate installed volumes across overhead crane systems, with copper-wound stators requiring periodic insulation testing. Demand concentrates in China's coastal manufacturing belts where heavy-lift infrastructure deployment drives replacement procurement.
- Servomotors:Closed-loop positioning systems with encoder feedback deliver millimeter-grade load control for automated warehousing and aerospace assembly. German automotive suppliers and Japanese electronics manufacturers absorb premium pricing for precision duty cycles.
- Hydraulic Motors:Fluid power units serve explosive-environment applications where electrical spark risk is prohibitive.
- Pneumatic Motors:Compressed-air systems occupy niche food-grade and chemical processing installations requiring intrinsic safety.
Electric motors hold the largest share; momentum sits with servomotors as warehouse automation accelerates.
Application:
Capital deployment cycles and equipment utilization rates create divergent margin profiles across end-use environments.
- Shipping:Port crane motors endure salt corrosion and intermittent heavy-lift stress at container terminals. Rotterdam and Hamburg operators are retrofitting variable-frequency drives to match vessel loading windows, compressing unplanned downtime.
- Construction:Mobile and tower crane motors face weather exposure and site-to-site transport vibration. Indian infrastructure contractors and Indonesian port authorities are expanding fleet capacity without mature domestic supply chains.
- Manufacturing:Overhead bridge crane systems in steel mills and automotive plants demand thermal management for continuous duty cycles.
- Mining:Underground hoist motors require explosion-proof enclosures and sealed bearing assemblies for abrasive dust environments.
Shipping commands the deepest aftermarket penetration; construction is climbing the fastest as emerging market infrastructure investment accelerates.
Technology:
Controller compatibility and grid infrastructure shape regional technology adoption patterns more than performance specifications alone.
- AC Motors:Induction and synchronous alternating-current designs sustain the broadest addressable market through grid compatibility and maintenance simplicity. Chinese MIIT energy-efficiency classifications are mandating premium-efficiency adoption in domestic heavy industry.
- Brushless Motors:Rare-earth magnet designs eliminate commutator wear for extended operational life in automated systems. EU F-Gas Regulation compliance costs are accelerating enclosure cooling redesigns for European aerospace and warehousing installations.
- DC Motors:Wound-field and permanent magnet direct-current systems persist in legacy crane fleets requiring control system coordination.
- Stepper Motors:Open-loop positioning systems occupy low-torque precision applications in laboratory and light assembly contexts.
AC motors anchor current installed base; brushless designs are gaining share fastest on predictive maintenance convergence.
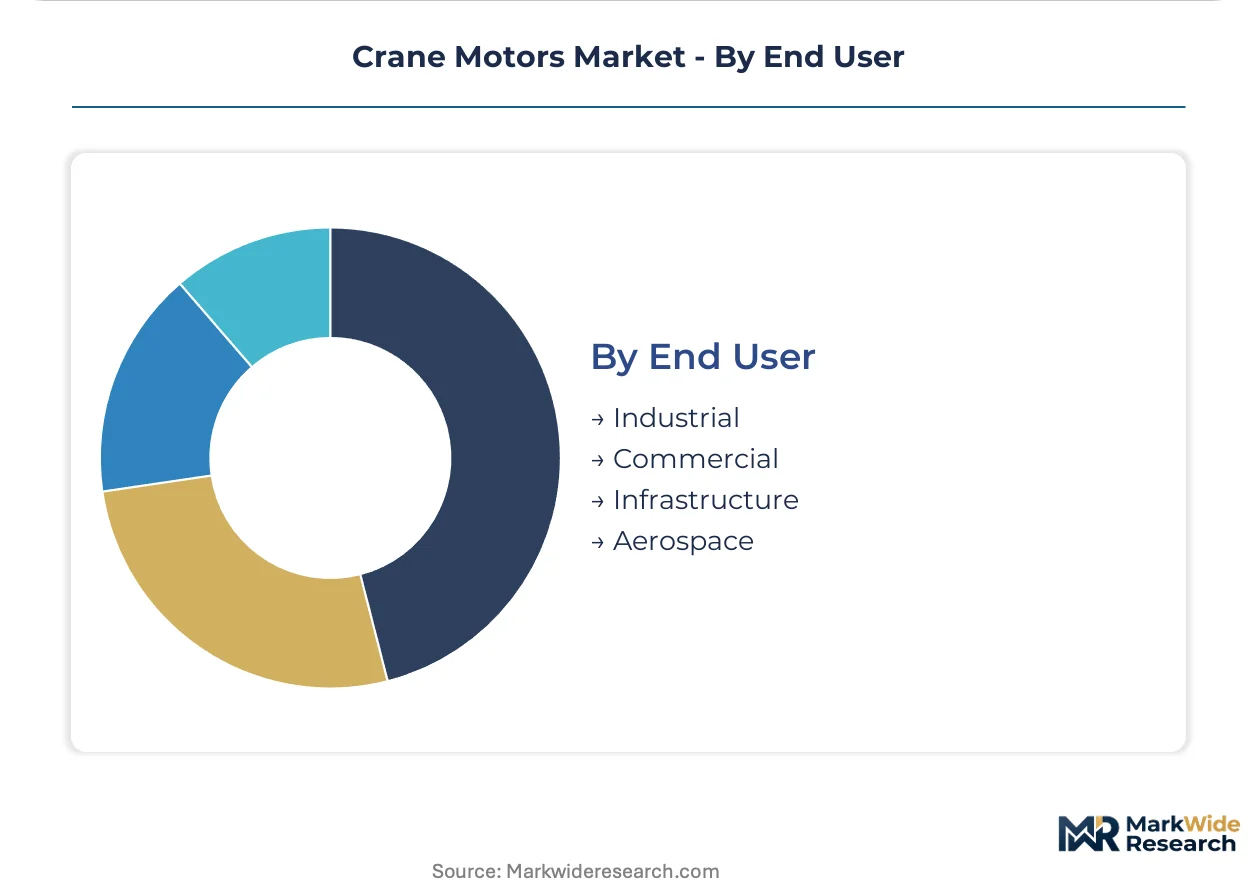
End User:
Procurement authority structures and total-cost-of-ownership horizons differentiate customer segments more than technical requirements.
- Industrial:Steel mills, cement plants, and automotive factories operate motors on depreciation schedules aligned with production line investments. Brazilian container terminal operators are adopting power-by-the-hour contracting to bypass upfront capex requirements.
- Infrastructure:Port authorities and transportation agencies balance public funding cycles with availability-guarantee demands. Vietnam and Indonesia are expanding terminal capacity without captive motor supply chains, creating import substitution openings.
- Commercial:Logistics warehouses and distribution centers prioritize energy efficiency rebates and rapid payback periods.
- Aerospace:Aircraft assembly hangars and MRO facilities specify servomotors for fuselage positioning with zero-defect tolerances.
Industrial users generate the highest service contract attachment rates; infrastructure is expanding most quickly on port modernization programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Premium-efficiency motor procurement in Germany commands price premiums exceeding Southeast Asian benchmarks by double-digit percentages, reflecting regulatory stringency and technical specification divergence across Atlantic and Pacific supply zones.
China
Shanghai and Ningbo-Zhoushan port operators are scaling crane motor procurement to match container throughput expansion through Asia-Pacific shipping lanes. MIIT energy-efficiency classifications mandate premium-efficiency adoption in domestic heavy industry, elevating technical specifications. The Yangtze River Delta manufacturing belt concentrates foundry and winding operations, with SANY and XCMG anchoring captive supply chains.
Germany
Rotterdam and Hamburg port authorities are retrofitting variable-frequency drives to optimize hoist acceleration curves against vessel loading windows. EU F-Gas Regulation phase-down schedules force refrigerant transitions in motor enclosure cooling systems, accelerating replacement cycles. The Ruhr industrial corridor and Bavarian heavy-lift clusters absorb redesign costs to maintain CE-marked equipment eligibility.
United States
Gulf Coast and Pacific Northwest container terminals are expanding crane motor procurement as intermodal freight volumes rise. FCC electromagnetic compatibility standards govern motor controller emissions in port and steel mill installations. Houston and Los Angeles-Long Beach port complexes drive aftermarket service contract intensity through uptime-guarantee procurement structures.
India
Maharashtra and Gujarat infrastructure contractors are expanding mobile and tower crane fleet capacity without mature domestic motor supply chains. BIS certification requirements and CEA electrical safety mandates shape import substitution dynamics. The Mumbai-Pune industrial corridor and Hazira port cluster create demand concentration for standard-duty electric motors.
Brazil
São Paulo and Santos container terminal operators are adopting power-by-the-hour contracting to bypass upfront capex requirements while accessing premium-efficiency equipment. ANVISA industrial equipment regulations and port authority availability-guarantee demands structure procurement decisions. The Southeast industrial belt drives leasing model penetration in capital-constrained infrastructure markets.
Crane Motors Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in winding wire and magnetic bearing supply. The vendor base organizes around three strategic archetypes: full-system crane manufacturers with captive motor production, independent motor fabricators serving aftermarket replacement cycles, and rare-earth magnet suppliers controlling torque-density differentiation. Consolidation pressure concentrates among European port equipment installers and Chinese coastal manufacturing belt producers. Dominant competitive moves include backward integration into foundry operations and geographic expansion through Southeast Asian port infrastructure contracts.
Among Finnish and Chinese platform integrators, Konecranes and SANY occupy positions exemplifying service-network density and captive supply chain control respectively. Konecranes leverages maintenance contract bundling to anchor long-term motor replacement revenue. SANY represents backward integration archetypes through in-house foundry and winding operations. XCMG sits within the delivery-speed competitive vector for standard-duty electric motors in emerging markets. These three companies illustrate how geographic origin and corporate structure shape strategic positioning without converging on identical capability investments.
| Leading Market Players |
|---|
| Uesco Industries, Inc. |
| Gorbel, Inc. |
| Konecranes |
| SANY |
| XCMG |
| Demag Cranes |
| EMH, Inc |
| Clescrane |
| LOADMATE INDUSTRIES PRIVATE LIMITED |
| Others |
Value Chain & Pricing Dynamics
The Shanghai-Ningbo container corridor's freight cost volatility feeds directly into motor landed pricing, amplifying spreads between standard-duty units from coastal Chinese foundries and configured-to-order systems bearing European certification overhead.
Pricing Analysis
Configured-to-order pricing commands spreads of 40-60% above standard SKUs, with CE marking and Machinery Directive compliance tiering premium brackets. Copper winding wire and rare-earth magnet grades differentiate price bands alongside thermal management specifications. Cost compression in standard-duty segments intensifies as XCMG and SANY flood emerging markets with volume production. Infrastructure contractors in India and Indonesia exhibit acute price sensitivity, while German port operators absorb premiums for availability-guaranteed service bundles.
Supply Chain Analysis
Foundry capacity concentrates in Jiangsu and Zhejiang provinces, with Clescrane and LOADMATE INDUSTRIES PRIVATE LIMITED tapping contract winding operations for export-bound production. Copper rod and laminated electrical steel draw from Chilean mining clusters and Chinese state steel mills. Single-source vulnerability in rare-earth magnet processing—centered on Chinese separation facilities—exposes torque-dense motor lines to supply interruption. Distribution runs through port equipment OEMs and independent aftermarket distributors serving replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crane motor demand sits in early-cycle expansion as permanent magnet technology penetrates beyond aerospace into mainstream port automation, compressing replacement intervals for induction motor fleets.
For Market Incumbents: Pre-empt servomotor commoditization by locking exclusive magnet supply agreements with rare-earth processors before price transparency erodes torque-density premiums. Anchor port operator relationships through predictive maintenance platform integration, converting hardware sales into recurring uptime contracts. Defend against Chinese foundry cost advantages by deepening technical service density in European and North American installation bases. For New Entrants and Emerging Players: Build out Southeast Asian port infrastructure presence ahead of domestic supply chain maturation in Vietnam and Indonesia, where terminal expansions lack captive motor fabrication. Target construction crane fleet operators in India's Maharashtra-Gujarat corridor with rapid-delivery standard-duty AC motors, bypassing CE marking timelines that stall European market entry. Lead with leasing structures that convert capital-constrained buyers from purchase to power-by-the-hour contracting. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underoptimized crane motor divisions lacking predictive maintenance software integration. Long-term viability hinges on rare-earth magnet access and IoT-enabled service contract attach rates. Monitor MIIT energy-efficiency classification enforcement as the inflection signal for premium-motor substitution acceleration in Chinese domestic demand.| Strategic Initiative | Industry Significance |
|---|---|
| Rare-Earth Magnet Supply Agreement | Secures torque-density differentiation as permanent magnet adoption accelerates in high-duty-cycle applications. |
| Predictive Maintenance Platform Launch | Converts Rotterdam and Hamburg port operators from transactional buyers to recurring-revenue service relationships. |
| Southeast Asian Port Infrastructure Contract | Captures Vietnam and Indonesia terminal expansions before domestic motor supply chains mature. |
| EU F-Gas Regulation Compliance Redesign | Maintains CE-marked equipment eligibility for German steel mill and port installations facing refrigerant transition mandates. |
| Power-by-the-Hour Contracting Rollout | Bypasses upfront capex constraints for Brazilian and African port authorities accessing premium-efficiency equipment. |
Study Parameters
Desk research of customs trade databases, MIIT energy-efficiency filings, and EU F-Gas Regulation implementation precedents preceded structured interviews with port maintenance directors, crane OEM procurement teams, foundry operations managers, and aftermarket service heads. Primary fieldwork across Shanghai, Hamburg, and Mumbai industrial corridors validated secondary estimates of replacement cycle timing and certification cost structures. Bottom-up unit economics triangulated against top-down port infrastructure investment flows.
Assumptions held copper and rare-earth price bands within historical volatility ranges while varying container throughput growth, regulatory phase-in schedules, and automation penetration rates across the projection horizon. Segmentation modeling tracked product type, application intensity, technology architecture, and end-user procurement authority. CAGRs derived from installed base depreciation schedules and technology substitution curves, with thermal management constraints and technician availability shaping regional adoption ceilings.
Stress conditions across magnet supply disruption, EU F-Gas enforcement acceleration, and emerging market currency depreciation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on infrastructure investment continuity and regulatory implementation timing. Quarterly review of port operator capex announcements and MIIT efficiency classification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Aluminum Die Casting Machinery Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Grader Machinery Market
Construction Equipment and Machinery
Computer Numerical Control Machines Market
Construction Equipment and Machinery
Steel Fabrication Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Automatic Nesting CNC Router Market
Construction Equipment and Machinery
Global Rebar Processing Equipment Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Cold Forging Machines Market