
 Computer Numerical Control Machines Market | 2026-2036
Computer Numerical Control Machines Market Size, Share, and Industry Trends Forecast 2026-2036
Computer Numerical Control Machines Market Analytics
The EU Green Deal is expanding requirements for industrial energy efficiency and emissions transparency across European metalworking supply chains. DMG MORI leverages its integrated machine-tool-plus-software architecture to capture retrofit demand from regulated facilities. Yamazaki Mazak Corporation anchors its competitive position through deep manufacturing scale across Japanese and European production hubs. FANUC Corporation dominates the CNC controller segment with proprietary servo systems that reduce energy consumption in compliance with tightening factory standards.
Computer numerical control machines are programmable automated machine tools that execute pre-coded commands to shape metal, composite, or polymer workpieces with tolerances often measured in micrometers, serving precision manufacturing across discrete industries. Milling machines occupy the largest installed base due to versatility in subtractive operations spanning simple drilling to complex contouring. 5-Axis technology leads growth trajectories as aerospace and medical device producers demand single-setup machining of complex geometries that 3-Axis systems cannot achieve. Mass Production applications sustain the deepest margin pools through multi-year tooling contracts and aftermarket service attach rates.
The EPA enforces stationary source emissions rules that constrain coolant mist and particulate discharge from U.S. machining centers, while OSHA mandates machine guarding and lockout protocols that influence control system design. REACH restricts hazardous substances in metalworking fluids and lubricants, forcing European CNC operators toward dry machining and minimum quantity lubrication architectures. Stakeholders must monitor evolving carbon border adjustment mechanisms and decide whether to front-load capital expenditure on electrified spindle systems or risk competitive displacement in export-oriented supply chains.
Market Dynamics
Electrification of spindle systems and servo architectures is compressing energy consumption benchmarks across metalworking facilities, forcing capital allocation decisions between retrofit cycles and full replacement timelines.
Growth Catalysts
- EU Green Deal industrial emissions standards:Metalworking facilities across Germany, Italy, and Spain face mandatory retrofit deadlines, accelerating procurement of energy-efficient CNC architectures.
- Electric vehicle powertrain machining:Automotive OEMs require multi-axis systems for aluminum housing and rotor shaft production, pulling demand from traditional internal combustion component lines.
- 5-Axis contouring capabilities:Aerospace and medical device producers demand single-setup machining of titanium and cobalt-chrome geometries, eliminating tolerance stack-up from multiple fixture repositioning.
Market Restraints
- Controller and servo motor supply concentration:Japanese and German component suppliers dominate high-precision motion control systems, creating vulnerability to regional logistics disruptions.
- Skilled CNC programmer scarcity:Machine shops in the US Midwest and Northern Italy report extended lead times for qualified G-code and CAM specialists, constraining utilization rates.
- REACH substance restrictions:Metalworking fluid reformulation costs and dry machining infrastructure requirements add 15-25% to facility upgrade budgets for European operators.
Strategic Opportunities
- India precision engineering clusters:Aerospace tier-1 suppliers near Bangalore and Hyderabad are expanding 5-Axis capacity for export-oriented defense and commercial airframe contracts.
- Digital twin integration:Convergence of physics-based simulation with real-time spindle load monitoring enables predictive tool wear algorithms, reducing unplanned downtime.
- US Inflation Reduction Act clean manufacturing credits:Domestic machine tool producers qualify for production tax incentives when deploying energy-efficient architectures in battery and electric motor supply chains.
Industry Challenges
- Multi-axis CAM programming complexity:Aerospace and medical device shops report 18-24 month training curves for simultaneous 5-Axis toolpath optimization, constraining workforce scalability.
- Legacy FANUC and Siemens controller integration:Brownfield facilities face protocol incompatibility when retrofitting 1990s-era machines with modern IoT-enabled monitoring systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Computer Numerical Control Machines Market |
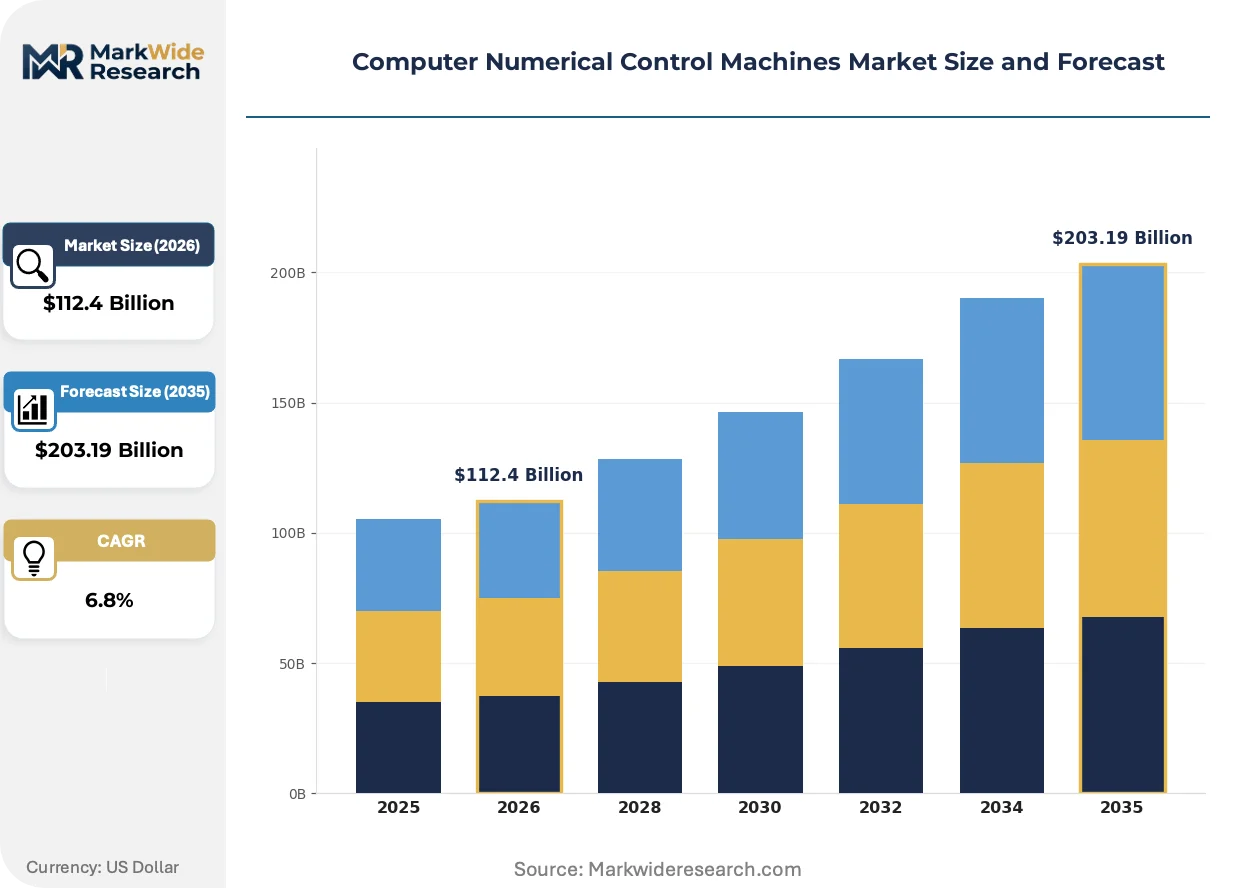
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $203.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Milling Machines, Lathes, Plasma Cutters, Laser Cutters Technology: 5-Axis, 3-Axis, CNC Routers, Hybrid Systems End User: Aerospace, Automotive Manufacturing, Robotics, Electronics Application: Prototyping, Mass Production, Tooling, Custom Fabrication |
| Companies Covered | DMG MORI, Yamazaki Mazak Corporation, Okuma Corporation, Haas Automation, FANUC Corporation, TRUMPF, JTEKT Corporation, Hurco Companies, Doosan Machine Tools, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Computer Numerical Control Machines Market Evolving Landscape
Edge-computing architectures and open-control platforms are dismantling the proprietary controller monopoly that has structured CNC markets for three decades.
Containerized edge software is decentralizing machine intelligence from centralized factory servers to individual spindle controllers. Tier-1 automotive suppliers in Stuttgart and Detroit are deploying Linux-based real-time operating systems on multi-axis mills, enabling sub-millisecond adaptive feedrate adjustments. This shift is decentralizing maintenance decision-making from plant-level engineering to operator-level dashboards, compressing response latency from hours to seconds.
REACH substance restrictions and the EU F-Gas Regulation are mandating elimination of perfluorinated compounds from metalworking fluids and cooling systems. German and Italian machine tool builders now specify minimum quantity lubrication as standard on new mill installations, with dry machining options for aluminum and magnesium alloys. Medical device manufacturers in Switzerland and Ireland are fastest to adopt, driven by cleanroom contamination protocols and extended surface finish requirements.
Aftermarket service unbundling is fragmenting traditional multi-year maintenance contracts into modular subscription tiers. Machine shops in the US Southeast and Poland are purchasing spindle monitoring and predictive analytics separately from mechanical service, often sourcing software from third-party industrial IoT platforms rather than OEM channels. This pattern is most pronounced among mid-cap job shops running mixed fleets of DMG MORI, Mazak, and Haas equipment, where vendor-agnostic dashboards reduce training overhead.
Computer Numerical Control Machines Market Segmentation
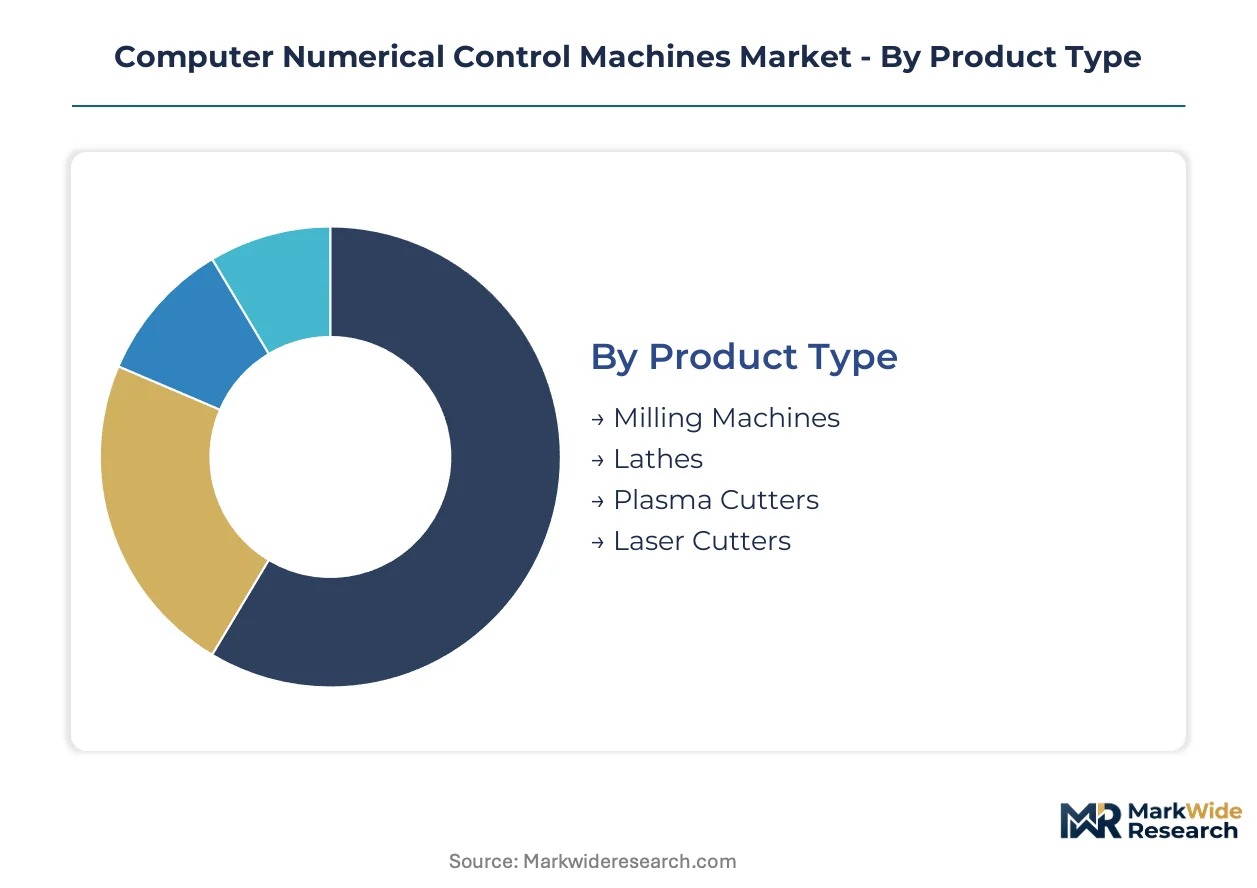
CNC machine procurement patterns diverge sharply across product architectures and end-use requirements, with regulatory compliance burdens and precision specifications dictating supplier selection criteria. Understanding how certification requirements, energy efficiency mandates, and application complexity segment demand enables targeted positioning across discrete manufacturing verticals.
Product Type:
Milling machines carry CE marking and machinery directive compliance obligations for European installations, while plasma and laser cutters face additional EPA emissions scrutiny in US facilities.
- Milling Machines:Subtractive machining centers execute drilling, contouring, and pocketing operations across ferrous and non-ferrous alloys. German automotive suppliers around Stuttgart anchor replacement demand as EU Green Deal retrofit deadlines compress procurement timelines for energy-efficient spindle architectures.
- Lathes:Rotational workpiece machining systems deliver cylindrical precision for shaft, pin, and housing production. Italian precision engineering clusters near Milan and Turin concentrate demand for multi-spindle configurations serving aerospace tier-1 contracts.
- Plasma Cutters:Thermal cutting systems slice conductive metals via ionized gas streams, requiring fume extraction infrastructure under OSHA ventilation standards.
- Laser Cutters:Solid-state and CO2 beam systems achieve micron-level kerf precision in sheet metal processing, with Swiss medical device manufacturers driving fiber laser adoption for cobalt-chrome implant fabrication.
Milling machines sit at the top of the volume ranking, with laser cutters climbing the fastest.
Technology:
Capital deployment intensity varies threefold across technology tiers, with 5-Axis systems commanding premium pricing against standardized 3-Axis platforms.
- 5-Axis:Simultaneous multi-directional machining eliminates fixture repositioning for complex turbine blades and orthopedic implants. Bangalore aerospace suppliers expand capacity for export-oriented defense contracts, pulling demand from traditional European machine tool channels.
- 3-Axis:Cartesian coordinate systems handle prismatic geometries with simpler CAM programming requirements and shorter operator training curves.
- CNC Routers:Gantry-based systems machine wood, composites, and soft metals at lower spindle speeds, with Polish furniture manufacturers driving volume procurement.
- Hybrid Systems:Additive-subtractive combinations deposit and finish metal layers in single setups, qualifying for US Inflation Reduction Act clean manufacturing credits when deployed in battery supply chains.
3-Axis maintains the broadest installed base, though 5-Axis gains share fastest in precision-driven end uses.
End User:
Customer technical sophistication and contract visibility determine aftermarket service attach rates and multi-year tooling agreement penetration.
- Aerospace:Titanium and nickel-alloy machining for airframes and engines demands AS9100 certification and single-source qualification protocols. Hyderabad tier-1 suppliers invest in 5-Axis capacity for commercial and defense export programs.
- Automotive Manufacturing:Powertrain housing and rotor shaft production for electric vehicles pulls aluminum machining demand from traditional cast iron internal combustion component lines.
- Robotics:Precision gearboxes and actuator housings require tight tolerance control for harmonic drive compatibility.
- Electronics:Miniaturized component machining for connectors and heat sinks favors high-speed spindle configurations with sub-micron positioning repeatability.
Automotive manufacturing leads absolute spend, with aerospace expanding most quickly on defense and commercial airframe contracts.
Application:
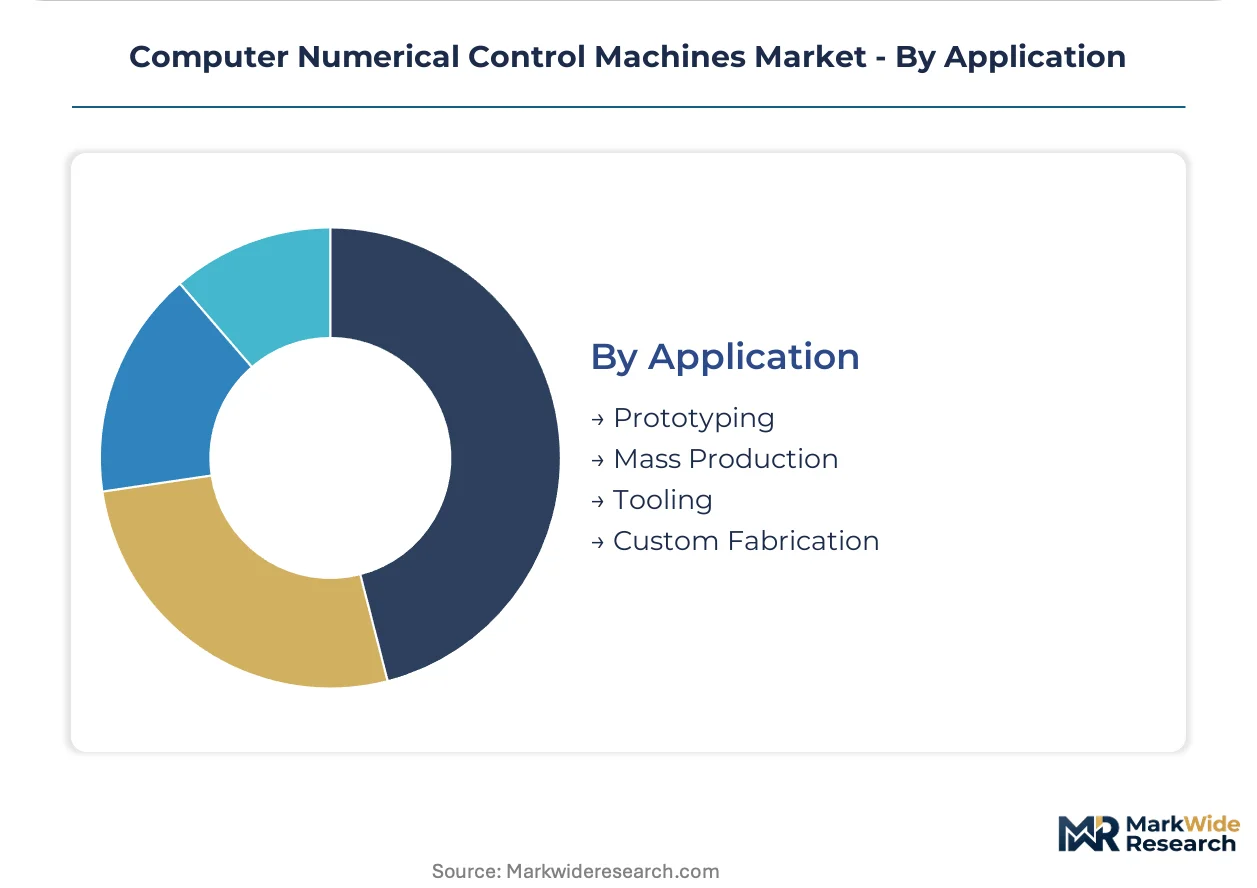
Volume scale and margin structure invert across application modes, with mass production sustaining deepest service revenue pools against prototyping's project-based economics.
- Mass Production:Multi-year automotive and aerospace contracts generate predictable aftermarket parts and service streams. US Southeast machine shops running mixed OEM fleets unbundle predictive analytics from mechanical maintenance to reduce vendor lock-in.
- Prototyping:Low-volume, high-mix machining for product development cycles prioritizes rapid programming turnaround over unit cost minimization.
- Tooling:Die and mold production for injection molding and stamping operations requires hardened steel machining with extended tool life optimization.
- Custom Fabrication:Job shop environments serving fragmented industrial demand favor machine versatility over specialization.
Mass production commands the largest revenue share, while prototyping shows steepest expansion trajectory on compressed product development cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters anchor European CNC programmer density, while Japanese controller specialists concentrate motion-control talent in Nagoya and Tokyo manufacturing corridors.
United States
Electric vehicle battery housing contracts pull aluminum machining demand toward Michigan and Tennessee automotive corridors. OSHA machine guarding mandates and EPA coolant mist regulations constrain brownfield retrofit timelines in Midwest job shops. Detroit tier-1 suppliers deploy Linux-based real-time control systems on multi-axis mills, compressing adaptive feedrate response latency to sub-millisecond thresholds.
Germany
EU Green Deal industrial emissions deadlines compress procurement timelines for energy-efficient spindle architectures across Baden-Württemberg and Bavaria. REACH substance restrictions and F-Gas Regulation mandates accelerate dry machining and minimum quantity lubrication adoption. Stuttgart precision engineering clusters anchor replacement demand as metalworking facilities retrofit legacy equipment for compliance.
Japan
Proprietary servo system production concentrates in Nagoya and Tokyo manufacturing hubs, supplying global OEM controller demand. METI industrial efficiency standards drive domestic machine tool builder R&D allocation toward electrified spindle architectures. Osaka-area fabricators maintain captive production of high-precision motion control components for aerospace and medical device export contracts.
India
Bangalore and Hyderabad aerospace tier-1 suppliers expand 5-Axis capacity for defense and commercial airframe export programs. BIS certification requirements and PLI scheme incentives pull capital toward precision engineering clusters in Karnataka and Telangana. Domestic machine tool procurement accelerates as global OEMs qualify Indian suppliers for titanium and nickel-alloy machining contracts.
Italy
Multi-spindle lathe demand concentrates in Milan and Turin precision engineering clusters serving aerospace tier-1 contracts. EU machinery directive compliance obligations and CE marking requirements shape supplier selection criteria for European installations. Northern Italian job shops report extended lead times for qualified G-code and CAM specialists, constraining utilization rates on new equipment.
Computer Numerical Control Machines Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the CNC machine tool value chain, creating a tiered structure where integrated machine-tool-plus-software architectures command premium positioning against component-specialist suppliers. Japanese and German incumbents dominate high-precision motion control systems, while Taiwanese and South Korean fabricators compete on standardized 3-Axis platforms. Strategic archetypes separate full-system integrators, controller-specialist component suppliers, and mid-scale job shop equipment providers. Competitive moves concentrate on M&A for software capabilities and geographic expansion into Indian and Southeast Asian precision engineering clusters.
Among Japanese-origin integrated manufacturers, DMG MORI and Yamazaki Mazak Corporation exemplify the full-system archetype, anchoring positions through machine-tool-plus-software architectures. FANUC Corporation occupies a distinct tier as a controller-specialist, representing the motion-control component archetype that supplies servo systems across OEM channels. These three entities illustrate the competitive separation between integrated platform providers and specialized component suppliers that structures procurement decisions in regulated European and North American facilities.
| Leading Market Players |
|---|
| DMG MORI |
| Yamazaki Mazak Corporation |
| Okuma Corporation |
| Haas Automation |
| FANUC Corporation |
| TRUMPF |
| JTEKT Corporation |
| Hurco Companies |
| Doosan Machine Tools |
| Others |
Value Network & Pricing Analysis
EU Green Deal industrial emissions standards gate qualified supply and premium-tier pricing access by mandating energy-efficient spindle architectures and dry machining infrastructure that only certified European and Japanese builders can deliver. Metalworking facilities in Germany and Italy face retrofit deadlines that compress procurement timelines, while REACH substance restrictions add compliance costs that stratify pricing tiers between certified and non-certified equipment suppliers.
Pricing Analysis
Bundled-versus-unbundled service splits define competitive positioning across the CNC machine tool value chain. Three-tier pricing structure across premium, standard, and economy levels separates integrated machine-tool-plus-software architectures from component-specialist suppliers and mid-scale job shop equipment. Price differentiation hinges on AS9100 certification tier and aftermarket service attach rates. Cost compression in standard-tier 3-Axis platforms is intensifying because Taiwanese and South Korean fabricators compete on commoditized specifications. Mid-cap job shops running mixed OEM fleets exhibit highest price sensitivity, while aerospace tier-1 suppliers demonstrate lowest sensitivity due to single-source qualification protocols.
Supply Chain Analysis
Dual-sourcing requirements from automotive and aerospace OEMs mandate multi-supplier qualification for servo motors and motion control systems. Geographic supply concentrates in Japan, Germany, and Taiwan, with proprietary controller production anchored in Nagoya and Tokyo manufacturing corridors. Raw material dependencies span rare-earth magnets for servo motors, high-grade cast iron for machine beds, and precision ball screws. Single-source vulnerability in high-precision motion control components creates exposure to regional logistics disruptions. Distribution runs through authorized dealer networks and direct OEM sales teams serving precision engineering clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Computer Numerical Control Machines Market functions as a stable compounder, with electric vehicle powertrain machining and EU emissions retrofit cycles generating predictable replacement demand across multi-year automotive and aerospace contracts.
For Market Incumbents: Deploy software unbundling to capture aftermarket revenue from mixed-fleet job shops in the US Southeast and Poland. Acquire edge-computing specialists to fortify open-control platforms against proprietary controller erosion. Channel control through certified service networks defends margin position against third-party industrial IoT platforms. For New Entrants and Emerging Players: The US Inflation Reduction Act clean manufacturing credits in domestic battery supply chains open a window for hybrid additive-subtractive system penetration. Target precision engineering clusters in Bangalore and Hyderabad where BIS certification requirements and PLI scheme incentives pull capital toward localized 5-Axis capacity. Go-to-market through aerospace tier-1 supplier qualification programs accelerates reference customer acquisition. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale controller-agnostic software platforms because brownfield facilities face protocol incompatibility when retrofitting legacy FANUC and Siemens installations. Five-to-ten-year viability rests on predictive maintenance algorithm differentiation and cross-OEM dashboard standardization. Watch for inflection in carbon border adjustment mechanism enforcement that would front-load capital expenditure on electrified spindle systems.| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Platform Integration | Linux-based real-time operating systems on multi-axis mills compress adaptive feedrate response latency in Stuttgart and Detroit automotive corridors. |
| Minimum Quantity Lubrication Standardization | German and Italian machine tool builders specify MQL as default to satisfy REACH substance restrictions and EU F-Gas Regulation mandates. |
| 5-Axis Capacity Expansion | Bangalore and Hyderabad aerospace suppliers invest for defense and commercial airframe export programs under BIS certification pathways. |
| Predictive Analytics Unbundling | Mid-cap job shops source spindle monitoring separately from mechanical service to reduce vendor lock-in across mixed DMG MORI and Mazak fleets. |
| Retrofit Service Contracting | EU Green Deal deadlines in Baden-Württemberg and Bavaria compress procurement timelines for energy-efficient spindle architecture upgrades. |
Research Methodology
Direct dialogue with plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads grounded qualitative assessment of retrofit demand and unbundling patterns. Secondary validation drew from SEC filings of listed machine tool builders, ECHA REACH substance restriction updates, EU Green Deal implementation timelines, and customs data on servo motor trade flows. Bottom-up and top-down triangulation cross-checked segment-level procurement patterns against aggregate capital expenditure disclosures from automotive and aerospace OEMs.
Bottom-up volume modeling built from named country production cluster analysis and end-use vertical capacity expansion announcements, while top-down approaches tested aggregate figures against machinery directive compliance obligations and CE marking registration databases. Segmentation dimensions spanned product architecture, technology tier, end-use vertical, and application mode across the projection horizon. CAGRs derived from regression analysis of historical replacement cycles and regulatory deadline impacts, with electric vehicle powertrain machining intensity and EU emissions retrofit timelines as industry-specific forecast inputs.
Revisions become necessary when carbon border adjustment mechanism enforcement accelerates, REACH substance restrictions expand to additional metalworking fluid categories, or regional logistics disruptions constrain Japanese and German servo motor supply. Deviation in EU Green Deal industrial emissions deadline adherence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Crane Motors Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Canada Metal Fabrication Equipment Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Cold Forging Machines Market
Construction Equipment and Machinery
Global Hydraulic Ironworker Machine Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Global Metal Embossing Machine Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Benelux Metal Fabrication Equipment Market