
 Milling Machine Market | 2026-2036
Milling Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Milling Machine Market Intelligence
The direct-to-end-user sales channel for specialized, high-value machines is fragmenting as regional distributors and integrators gain influence. DMG MORI sustains its market position through a combination of German and Japanese engineering expertise and a global service network. Haas Automation competes on accessibility and user-friendly controls, targeting small to mid-sized metalworking shops. Meanwhile, Makino specializes in high-precision and high-speed machining centers for demanding mold and die applications.
A milling machine is a subtractive manufacturing tool that uses rotating multi-point cutters to remove material from a workpiece. These machines achieve high tolerances, often below 0.01mm, for shaping metal and other rigid materials in precision engineering. While manual machines persist in smaller shops, CNC milling machines dominate new capital expenditures, especially for aerospace component production. Within product types, vertical milling machines represent a foundational segment, but multi-axis universal machines offer the highest growth potential.
Machine safety and operator protection are governed by standards such as the EU's Machinery Directive, which mandates CE marking for market access. In the United States, OSHA regulations dictate workplace safety protocols, while ISO standards for machine tool accuracy ensure component quality. Future investment decisions will hinge on balancing the upfront cost of advanced automation against the long-term benefits of improved productivity and precision.
Market Dynamics
The market's core dynamic is the tension between the high initial capital expenditure for multi-axis CNC systems and the non-negotiable demand for their precision in sectors like aerospace, forcing a strategic calculus in every investment.
Growth Catalysts
- Aerospace Component Production:Stringent requirements for precision-machined turbine blades, landing gear, and structural airframe parts in the aerospace sector drive consistent demand for advanced, multi-axis milling machines capable of working with exotic alloys.
- Automotive Electrification:The transition to electric vehicles requires new manufacturing capabilities for milling complex aluminum battery enclosures, lightweight chassis components, and electric motor housings, especially within industrial clusters in China.
- Medical Device Manufacturing:The production of miniaturized surgical instruments and custom orthopedic implants from materials like titanium and PEEK relies on high-precision 5-axis milling to achieve complex geometries and superior surface finishes.
Market Restraints
- High Capital Outlay:The substantial upfront cost of advanced CNC milling centers, particularly 5-axis and universal machines, remains a significant barrier to adoption for many small and medium-sized metalworking shops.
- Skilled Labor Shortage:A persistent global scarcity of trained CNC programmers and operators who can effectively manage complex machining setups and troubleshoot advanced equipment limits the productive capacity of installed machines.
- Input Cost Volatility:Fluctuations in the prices of critical raw materials such as high-grade steel, tungsten carbide for cutting tools, and aluminum directly impact both machine manufacturing costs and end-user operational expenses.
Strategic Opportunities
- Hybrid Manufacturing Systems:Integrating additive manufacturing capabilities with subtractive milling in a single machine platform creates opportunities to produce parts with complex internal features and optimized topologies that are impossible with either method alone.
- Industrial Policy Incentives:Government initiatives like India's Production Linked Incentive (PLI) scheme for electronics and automotive manufacturing stimulate domestic capital investment, creating new demand for machine tools.
- Automation and Software Services:Developing subscription-based models for advanced CAM software, remote machine monitoring, and predictive maintenance analytics offers a recurring revenue stream beyond the initial hardware sale.
Industry Challenges
- Cybersecurity for Connected Machines:Securing networked CNC machines against cyber threats is a critical operational challenge, as breaches can result in the theft of valuable design IP, production downtime, or physical damage to equipment.
- Integration with Legacy Systems:Manufacturers face significant technical hurdles and costs when integrating new, digitally-native milling machines with existing factory floor equipment and older enterprise resource planning (ERP) systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Milling Machine Market |
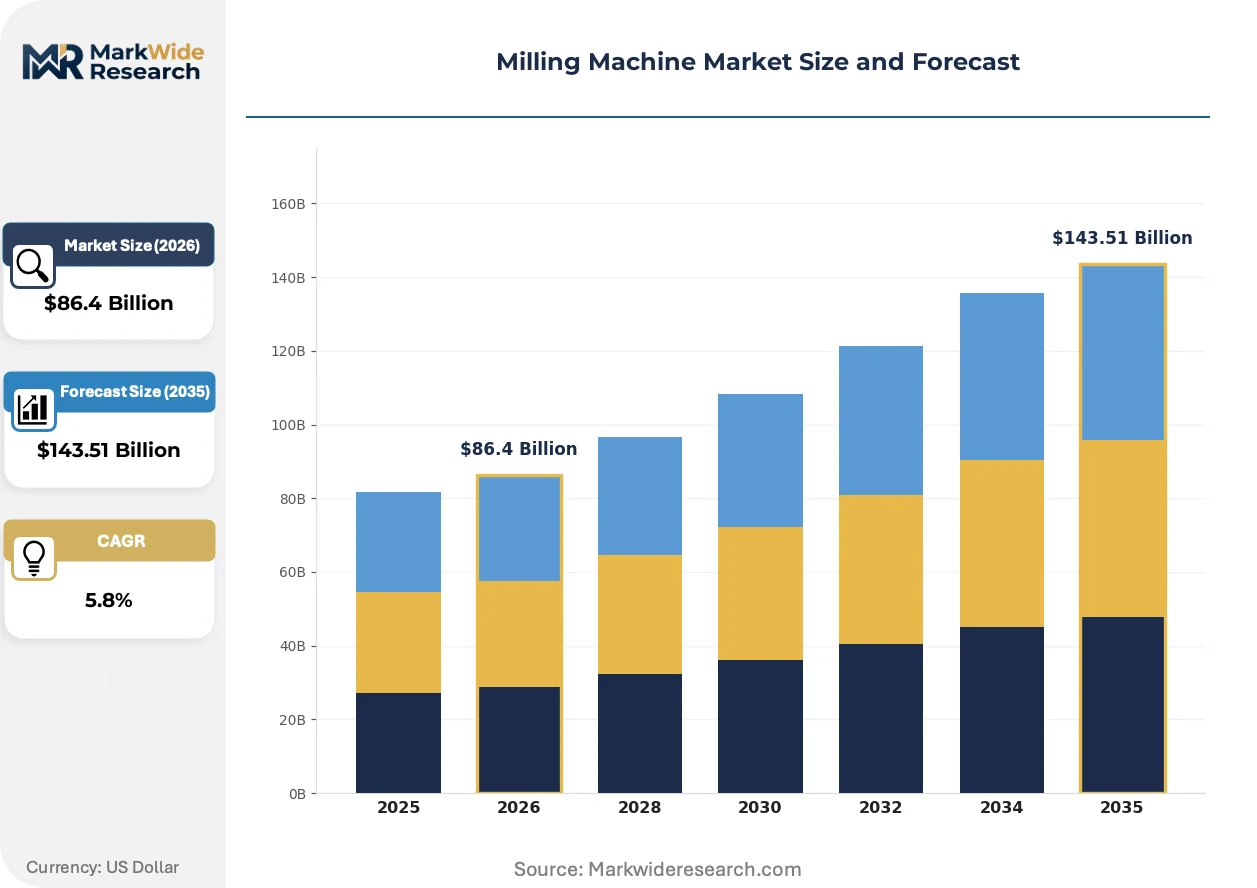
| Market Size in 2026 | $86.4 Billion |
| Market Size in 2035 | $143.51 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vertical Milling Machines, Horizontal Milling Machines, Universal Milling Machines, CNC Milling Machines, Bed Type Milling Machines Technology: Computer Numerical Control, Manual Operation, Hybrid Control, High-Speed Milling, Digital Interface Application: Metal Fabrication, Aerospace Component Production, Mold Making, Die Casting, Precision Engineering End User: Metalworking Shops, Aerospace Manufacturers, Automotive Suppliers, Tool & Die Makers, Electronics Equipment Fabricators |
| Companies Covered | Okuma, Makino, DMG MORI, Hardinge, CHIRON, Yamazaki Mazak, Doosan Machine Tools, Hurco, Haas Automation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Milling Machine Market Strategic Shifts & Innovations
A fundamental shift towards software-defined manufacturing ecosystems is reshaping the competitive landscape. This transition prioritizes data integration, automation intelligence, and operational connectivity over standalone machine performance.
Digital Twin technology creates a high-fidelity virtual replica of the milling process, allowing for simulation and optimization. Aerospace and automotive component makers are early adopters for complex 5-axis machining operations. The operational focus is migrating from post-process quality control and physical prototypes to predictive, simulation-driven process verification before cutting metal.
The European Union's Machinery Directive, with its stringent CE marking protocols, dictates comprehensive machine safety and cybersecurity standards. This forces manufacturers to embed enhanced safety controllers and secure data pathways into their equipment designs. Exporters to the EU face the most direct impact, requiring significant engineering updates to meet compliance for market access.
End-user behavior is evolving toward on-demand machining through digital manufacturing platforms. This disrupts the traditional model of direct capital equipment acquisition, especially for job shops and prototyping firms. The shift is most prominent in North American and European design and engineering sectors that value speed and flexibility over asset ownership.
Milling Machine Market Segmentation
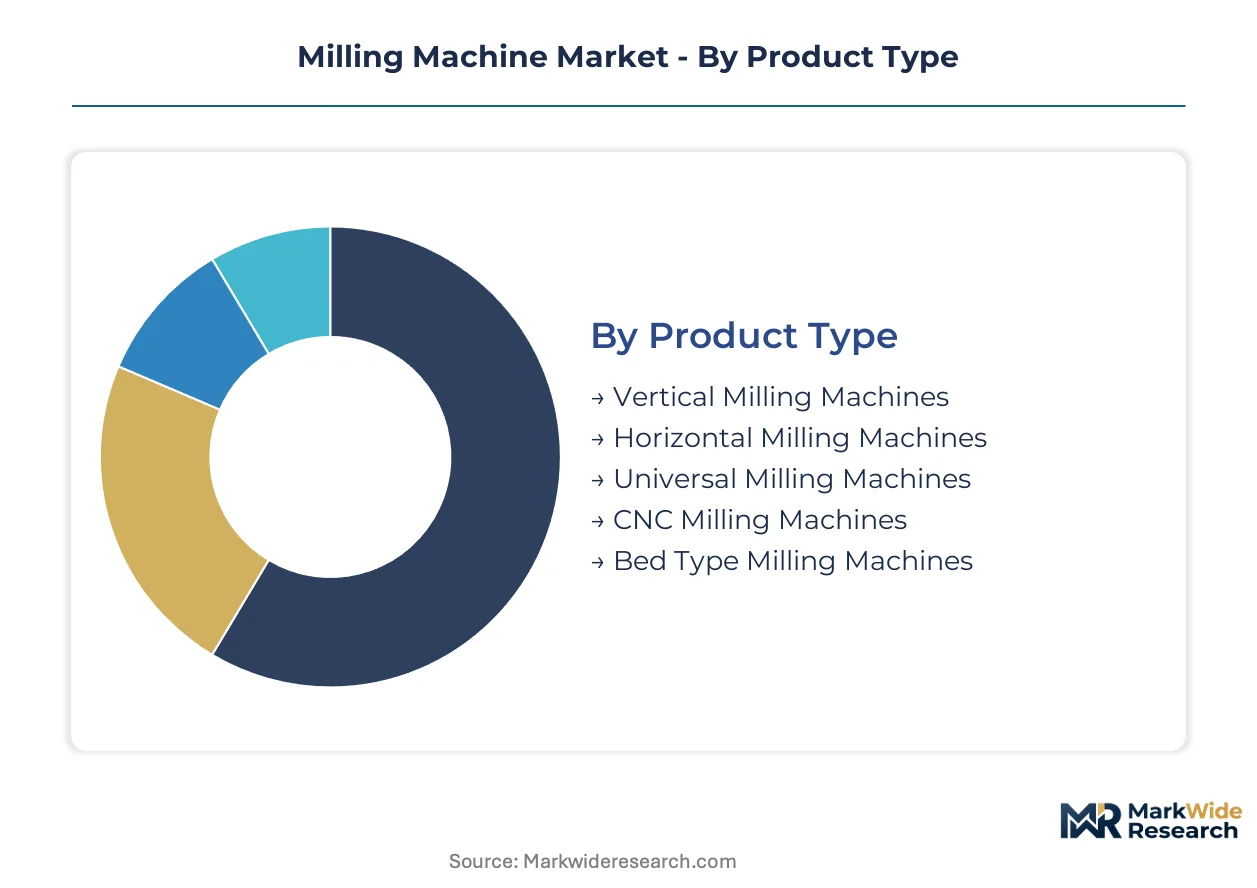
Market segmentation for milling machines provides a granular understanding of demand drivers and technological preferences across diverse industrial applications. Analyzing these segments helps stakeholders identify specific growth pockets and tailor product development to meet specialized manufacturing requirements.
Product Type:
The product type segmentation reveals a market with both mature foundational technologies and emerging advanced systems driving innovation.
- CNC Milling Machines:These machines operate via programmed computer instructions, enabling high precision, repeatability, and the machining of complex geometries with minimal human intervention. Demand concentrates in aerospace component production in the United States, driven by stringent quality standards for critical parts.
- Universal Milling Machines:Combining the capabilities of both vertical and horizontal spindles, universal milling machines offer exceptional versatility for a wide range of machining operations. Automotive suppliers in Germany increasingly adopt these systems for flexible production lines handling diverse component types.
- Vertical Milling Machines:Characterized by a vertically oriented spindle, these machines are widely used for general-purpose machining, facing, and drilling operations.
- Horizontal Milling Machines:Featuring a horizontally oriented spindle, these machines are suitable for heavy material removal and gang milling applications.
- Bed Type Milling Machines:These robust machines provide high rigidity and stability, making them ideal for heavy-duty machining of large workpieces with consistent accuracy.
Vertical Milling Machines handle the majority of throughput; CNC Milling Machines are the fastest mover on share.
Technology:
Technology segmentation highlights the diverse operational needs across various manufacturing applications, from traditional methods to highly automated processes.
- Computer Numerical Control:This technology automates machine operations through programmed instructions, ensuring repeatable accuracy and reducing human error across production runs. Aerospace manufacturers in Japan rely on CNC for processing exotic alloys and complex structural components.
- High-Speed Milling:Involving rapid tool rotation and feed rates, high-speed milling enables faster material removal, improved surface finishes, and reduced cycle times. Mold and die makers in China leverage this technology to produce intricate tooling with greater efficiency.
- Manual Operation:These traditional machines require direct operator control for all movements, often found in smaller workshops or for specialized, low-volume tasks.
- Hybrid Control:Hybrid control systems integrate elements of both manual and automated operation, offering flexibility for varied production environments.
- Digital Interface:Digital interfaces provide intuitive control and monitoring capabilities for machine parameters, enhancing operator efficiency and data collection.
Computer Numerical Control technology underpins most advanced manufacturing, while High-Speed Milling gains share in specialized applications.
Application:
Application areas delineate the specific customer requirements shaping machine tool design and capabilities, from heavy industry to micro-components.
- Aerospace Component Production:This sector demands milling machines capable of extreme precision, multi-axis capabilities, and the efficient processing of exotic alloys like titanium. Manufacturers in India utilize advanced systems for turbine blade and structural airframe part fabrication.
- Precision Engineering:Encompassing the creation of components with extremely tight tolerances and fine surface finishes, this application is critical for sensitive instruments. Medical device firms in Switzerland depend on 5-axis milling for miniaturized surgical instruments and orthopedic implants.
- Metal Fabrication:This broad application involves shaping and assembling metal structures and components for general industrial use.
- Mold Making:Milling machines are essential for creating intricate molds and dies used in plastic injection molding and metal casting processes.
- Die Casting:This application utilizes milling for finishing and refining cast metal parts, ensuring dimensional accuracy and surface quality.
Aerospace Component Production drives innovation in multi-axis machines, while Metal Fabrication represents the largest volume segment.
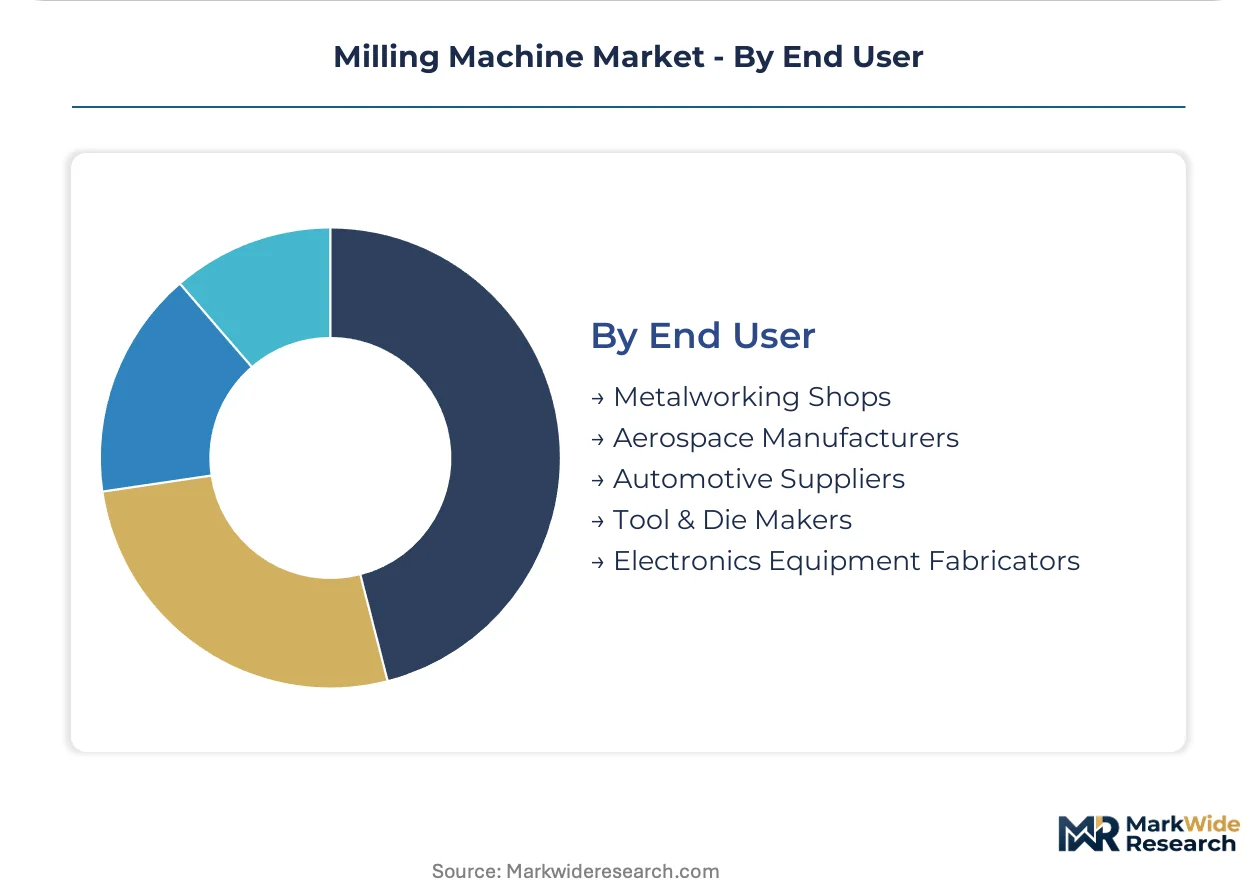
End User:
End-user segmentation reveals varying volume demands and technological sophistication across different industrial sectors, influencing machine purchasing decisions.
- Aerospace Manufacturers:These end users require state-of-the-art multi-axis milling machines for producing high-value, safety-critical components from advanced materials. Companies in the United Kingdom invest heavily in automation for complex airframe and engine parts.
- Automotive Suppliers:This segment demands high-volume production capabilities for components like engine blocks, chassis parts, and battery enclosures, often requiring robust, automated milling solutions. Suppliers in China are rapidly adopting new machines for electric vehicle component manufacturing.
- Metalworking Shops:These diverse shops range from small job shops to larger contract manufacturers, utilizing a variety of milling machines for custom and batch production.
- Tool & Die Makers:Specializing in the creation of tooling for other manufacturing processes, these users need high-precision machines for intricate and durable molds and dies.
- Electronics Equipment Fabricators:This sector uses milling machines for producing precision components and enclosures for electronic devices, often requiring fine feature machining.
Aerospace Manufacturers require the most advanced systems, while Metalworking Shops represent a broad base for entry-level and mid-range machines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power asymmetry defines the milling machine market, with European manufacturers often commanding premium valuations for advanced systems, while Asian producers focus on volume and cost-efficiency. This dynamic influences investment patterns and technology adoption across different regions. End-user demand and regulatory frameworks further shape regional market characteristics.
United States
Demand for milling machines in the United States stems from stringent precision requirements in aerospace component production and advanced medical device manufacturing. OSHA regulations dictate workplace safety protocols, influencing machine design and operational procedures. Industrial clusters in the Midwest and Pacific Northwest concentrate aerospace and automotive suppliers, driving demand for multi-axis CNC systems.
Germany
Germany's milling machine market is propelled by the automotive sector's transition to electrification and its robust precision engineering industry. The EU's Machinery Directive mandates CE marking, ensuring high safety and performance standards for machines sold within the region. Manufacturing hubs in Bavaria and Baden-Württemberg are key centers for advanced machine tool development and adoption.
China
China's market expansion is fueled by massive investments in automotive and electronics manufacturing, alongside a growing aerospace industry. Government initiatives, such as the MIIT's focus on industrial upgrading, encourage the adoption of advanced CNC technologies. The Yangtze River Delta and Pearl River Delta regions represent significant industrial clusters for high-volume production.
India
India's milling machine market benefits from an expanding manufacturing base across aerospace and automotive sectors, supported by government incentives. The Production Linked Incentive (PLI) scheme for electronics and automotive manufacturing stimulates domestic capital investment. Industrial zones in Maharashtra and Karnataka are witnessing increased demand for precision machining capabilities.
Japan
Japan, with its focus on high-precision and high-speed machining, sees consistent demand from aerospace, medical device, and mold and die applications. METI guidelines promote advanced manufacturing technologies and energy efficiency in machine tools. The Kanto and Chubu regions are central to Japan's advanced manufacturing and machine tool production.
Milling Machine Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream, supplying critical elements to machine builders. The market exhibits a tiered structure, with a few global players offering comprehensive solutions alongside numerous niche specialists. Strategic archetypes include high-precision specialists, general-purpose providers, and cost-efficient volume manufacturers. Dominant competitive moves involve strategic partnerships for software integration and significant investments in advanced automation R&D.
Within the high-precision specialist archetype, Makino exemplifies dedication to demanding mold and die applications, delivering high-speed machining centers that cater to intricate tooling requirements. DMG MORI represents a blend of German and Japanese engineering expertise, maintaining its strong market position through a comprehensive global service network that supports complex installations. Haas Automation occupies the accessible, user-friendly segment, targeting small to mid-sized metalworking shops with its competitively priced and straightforward control systems, thereby broadening market access.
| Leading Market Players |
|---|
| Okuma |
| Makino |
| DMG MORI |
| Hardinge |
| CHIRON |
| Yamazaki Mazak |
| Doosan Machine Tools |
| Hurco |
| Haas Automation |
| Others |
Cost & Logistics Intelligence
Upstream component specialists in Germany and Japan, supplying precision bearings and advanced control systems, directly influence the premium margin pools for high-value machine tool builders. This concentration shapes pricing power and innovation within the global milling machine market.
Pricing Analysis
Configured-to-order multi-axis CNC systems command a significant premium over standard vertical milling machines. Value-based pricing is dominant, reflecting the precision capabilities and productivity gains offered by advanced equipment. Price differentiation stems from the machine's tolerance capabilities and brand reputation. Cost compression in volume segments is intensifying due to competition from Asian manufacturers. Aerospace and medical device manufacturers exhibit low price sensitivity, prioritizing performance, while smaller metalworking shops remain highly price-sensitive.
Supply Chain Analysis
Extended payment terms for capital equipment and supply-chain finance facilities support the acquisition of high-value milling machines. Geographic supply concentration for critical components rests in Germany for engineering and Japan for precision manufacturing. Key raw material dependencies include high-grade steel for machine frames and tungsten carbide for cutting tools. Geopolitical risks affecting trade routes pose a structural risk to component availability. Distribution runs through a hybrid model, combining direct sales for major accounts and regional distributors for broader market reach.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The milling machine market presents a fragmentation opportunity, as the shift towards on-demand machining through digital manufacturing platforms creates numerous niche demands.
For Market Incumbents: Insulate core market share by investing heavily in advanced automation R&D and expanding global service networks. Strategic partnerships for software integration can counteract the threat from emerging digital manufacturing platforms. Reinforce brand premium through stringent CE marking compliance and ISO standards, particularly for aerospace component production.
For New Entrants and Emerging Players: Establish a beachhead in underserved market segments, such as small to mid-sized metalworking shops seeking user-friendly controls and accessible pricing. Target specific application niches like medical device manufacturing with specialized 5-axis machines. A subscription-based model for advanced CAM software and remote monitoring services offers a viable go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with regional integrators and specialized component suppliers, offering attractive acquisition targets. Long-term viability in this market depends on the non-negotiable demand for precision in critical sectors like aerospace and medical. The accelerating adoption rate of digital twin technology serves as a key signal to watch for future growth potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Integration Partnerships | Enhances multi-axis CNC system capabilities for complex geometries. |
| Hybrid Manufacturing R&D | Enables production of optimized topologies for aerospace components. |
| Global Service Network Expansion | Supports advanced machine tool installations for DMG MORI. |
| Subscription-based CAM Software | Provides recurring revenue streams for automation providers. |
| CE Marking Compliance Investment | Secures market access for European Union machine tool sales. |
Research Approach
Initial hypotheses were tested against primary input from aerospace component engineers, automotive manufacturing leads, machine tool R&D directors, and metalworking shop owners, then refined. This qualitative data was validated through secondary research, drawing from industry association reports, government manufacturing statistics, and patent databases. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Demand-supply-balance models underpin the forecast framework, projecting market evolution across the analysis window. Segmentation dimensions included product type, technology, application, end user, and regional demand patterns. Compound Annual Growth Rates were derived through regression analysis of historical data and projected forward using econometric models. Key forecast inputs included capital expenditure trends in aerospace and automotive electrification investment.
Stress conditions across global economic growth, raw material price stability, and skilled labor availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions documented in the full report. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Engineering Machinery Counterweight Iron Market
Construction Equipment and Machinery
Dredge Automation Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Roll Forming Machine Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Lattice Cranes Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Metalworking Machinery Market