
 Colombia Metal Fabrication Equipment Market | 2026-2036
Colombia Metal Fabrication Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Colombia Metal Fabrication Equipment Market Outlook
Computer numerical control integration with robotic automation is rewriting production economics for Colombian metal fabricators. Colfax leverages its international technology portfolio to supply advanced welding systems to Andean industrial clients. Gerdau anchors its position through captive steel production feeding downstream fabrication demand. Ternium competes by controlling flat-rolled steel supply chains that shape equipment utilization rates across the sector.
Colombia metal fabrication equipment encompasses machinery designed to cut, form, join, and finish metallic workpieces, typically operating at power ratings from 2 kW to 20 kW for laser systems and force capacities exceeding 100 tons for press brakes. Its primary purpose is transforming raw steel, aluminum, and alloys into precision components for industrial assembly and infrastructure build-out. Laser cutting machines dominate capital expenditure among large fabricators seeking kerf-width precision below 0.3 mm for aerospace-grade materials. Welding equipment sustains the broadest installed base, though robotic automation segments attract disproportionate investment from automotive parts suppliers retooling for export compliance.
Colombia's Ministry of Industry and Commerce enforces technical regulations under Law 1955 of 2019 for industrial machinery importation, while ICONTEC administers Colombian Technical Standards (NTC) aligned with ISO welding quality protocols. These frameworks elevate compliance costs for foreign OEMs but create protected terrain for local assemblers meeting NTC-certified specifications. Stakeholders must monitor whether forthcoming energy-efficiency mandates from the Mining and Energy Planning Unit reshape equipment procurement criteria for electrically intensive processes.
Market Dynamics
Automated fabrication systems are compressing production economics across Colombian metalworking clusters, forcing mid-tier fabricators to retool or exit as Bogotá and Medellín buyers consolidate procurement around CNC-integrated suppliers.
Growth Catalysts
- Construction sector automation mandates:Large infrastructure developers now specify robotic welding systems for structural steel contracts, pulling demand from manual equipment categories.
- ICONTEC NTC certification alignment:Colombian Technical Standards harmonization with ISO welding protocols creates protected demand for certified domestic assemblers.
- Medellín manufacturing cluster density:Geographic concentration of automotive parts suppliers generates equipment-sharing economies and accelerated technology diffusion.
Market Restraints
- Imported machinery cost structure:Law 1955 of 2019 compliance testing adds landed cost burden for European and Asian OEMs, limiting price competition.
- Steel input volatility:Flat-rolled steel supply concentration under Ternium and Gerdau exposes fabricators to captive pricing power in raw materials.
- Laser system technical limitation:High-power fiber laser maintenance requires specialized technicians scarce outside Bogotá's industrial corridor.
Strategic Opportunities
- Cali-Pacific corridor underpenetration:Port-proximate manufacturing zones lack dense equipment supplier networks, creating first-mover terrain for service-forward distributors.
- Energy-efficiency regulatory tailwind:Anticipated Mining and Energy Planning Unit mandates for electrically intensive processes will favor next-generation servo-electric press brakes.
- Cloud-based predictive maintenance convergence:IoT sensor integration with CNC controllers enables remote diagnostics services, shifting revenue from hardware to recurring software.
Industry Challenges
- CNC programming skill scarcity:Technical institutes produce insufficient G-code and robotic welding technicians to match retooling velocity in Antioquia and Cundinamarca.
- Legacy mechanical press integration friction:Hybrid automation retrofits on 1990s-era equipment demand custom engineering that stretches project timelines and erodes margin.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colombia Metal Fabrication Equipment Market |
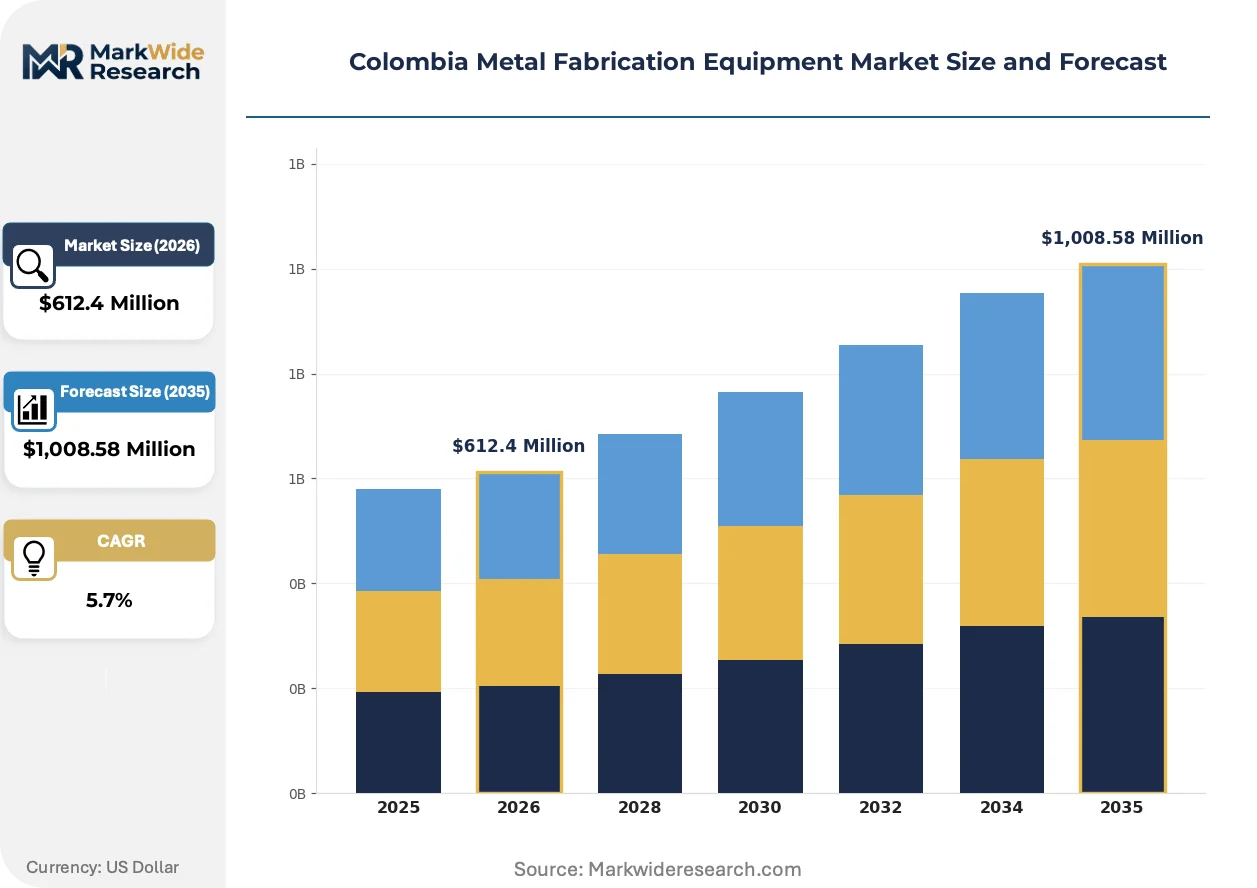
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $1,008.58 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Laser Cutting Machines, Welding Equipment, Press Brakes, Bending Machines Technology: Computer Numerical Control, Manual, Robotic Automation, Electric End User: Aerospace, Construction, Automotive Parts, Metalworking Application: Manufacturing, Repair Services, Custom Fabrication, Component Assembly |
| Companies Covered | Colfax, INPLASMEC, Ternium, Recicladora MetalPlast Solutions MG, Listonplast SAS, Gerdau, Arbez Ingenieria, Grupo Hera Colombia, PRAMEC SAS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colombia Metal Fabrication Equipment Market Strategic Shifts
Digital thread technologies are collapsing the gap between design and production floor, enabling Colombian fabricators to bid on precision contracts previously reserved for Mexican or Brazilian competitors with deeper automation histories.
Cloud-native manufacturing execution software is digitizing job scheduling and real-time quality tracking across small and mid-size Bogotá shops. Tier-two automotive suppliers adopt these platforms fastest, compressing quoting cycles from days to hours and forcing equipment vendors to bundle software subscriptions with hardware sales.
Colombia's Ministry of Industry and Commerce is tightening technical regulations under Law 1955 of 2019, extending conformity assessment requirements to robotic welding cells previously exempt. Foreign OEMs face extended approval timelines, while local assemblers with existing NTC certification infrastructure capture displaced demand in the interim compliance gap.
Equipment-as-a-service contracting is displacing outright purchase in Medellín's automotive parts cluster. Tier-one suppliers now lease laser cutting capacity with bundled maintenance, transferring obsolescence risk to vendors and compressing capital deployment cycles for buyers scaling export-compliant production.
Colombia Metal Fabrication Equipment Market Segmentation
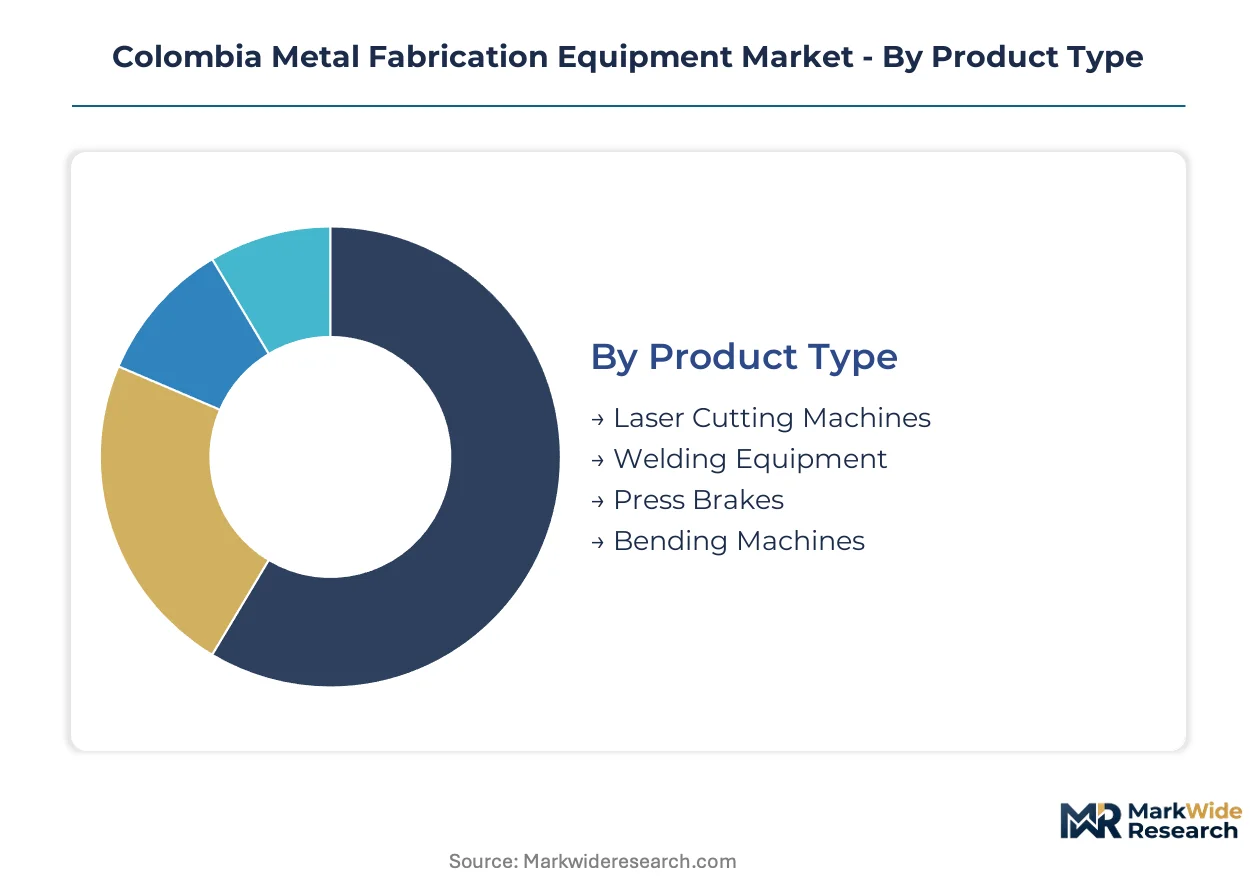
Segmentation reveals how equipment procurement cycles diverge across Colombian metalworking clusters. Bogotá fabricators replace laser systems every seven years while Medellín automotive suppliers rotate welding robots on four-year compliance-driven cycles. Understanding these velocity differences shapes inventory and service strategies for equipment distributors.
Product Type:
Laser cutting machines turn over slowest due to capital intensity and installation complexity, while welding equipment refreshes fastest as ICONTEC certification updates force compliance-driven replacement.
- Laser Cutting Machines:Fiber and CO2 systems operating at 2 kW to 20 kW power ratings deliver kerf-width precision below 0.3 mm for aerospace-grade materials. Demand concentrates among large Bogotá fabricators bidding on infrastructure contracts where precision tolerances are non-negotiable. Maintenance scarcity outside the capital corridor constrains penetration.
- Welding Equipment:Arc, MIG, and TIG systems constitute the broadest installed base across Colombian metalworking. Construction sector buyers in Antioquia now specify robotic welding cells for structural steel contracts, pulling demand from manual equipment categories.
- Press Brakes:Hydraulic and servo-electric systems with force capacities exceeding 100 tons transform flat-rolled steel into precision-formed components. Ternium and Gerdau's captive steel pricing directly shapes utilization economics for these capital assets.
- Bending Machines:Roll and rotary-draw systems handle aluminum and alloy tubing for automotive exhaust and furniture applications. Cali-Pacific corridor fabricators underinvest here due to sparse technical service networks.
Welding equipment dominates installed base. Laser cutting machines are where expansion concentrates.
Technology:
Cost tiers separate premium CNC-integrated systems from entry-level manual equipment, with robotic automation commanding mid-to-premium positioning as automotive suppliers retool for export compliance.
- Computer Numerical Control:Integrated controllers coordinate multi-axis motion for cutting, forming, and joining operations with programmability down to 0.01 mm repeatability. CNC programming skill scarcity in Antioquia and Cundinamarca technical institutes creates a supply-side bottleneck that stretches project timelines.
- Robotic Automation:Six-axis articulated arms with welding end-effectors execute continuous seam operations at speeds manual operators cannot match. Medellín's automotive parts cluster generates equipment-sharing economies that accelerate technology diffusion among tier-two suppliers.
- Manual:Operator-dependent equipment persists in small Bogotá job shops serving custom fabrication niches where batch sizes resist automation economics.
- Electric:Servo-driven press brakes and bending systems eliminate hydraulic fluid maintenance while cutting energy consumption. Anticipated Mining and Energy Planning Unit mandates for electrically intensive processes favor this technology trajectory.
Manual systems retain deepest installed base. Robotic automation is climbing the fastest.
End User:
Application maturity varies sharply: construction demands rugged durability while aerospace imposes certification traceability that only Bogotá's most advanced fabricators currently satisfy.
- Construction:Structural steel fabricators serving infrastructure developers specify automated welding systems for highway and commercial building contracts. Law 1955 of 2019 compliance testing adds landed cost burden for imported robotic cells, protecting local NTC-certified assemblers.
- Automotive Parts:Tier-one and tier-two suppliers in Medellín's manufacturing cluster lease laser cutting capacity with bundled maintenance, transferring obsolescence risk to vendors. Export compliance requirements drive the fastest retooling cycles in this segment.
- Aerospace:Precision component suppliers serving Embraer and Airbus subcontracting chains demand kerf-width precision below 0.3 mm. Only three Bogotá fabricators currently hold the NADCAP welding certifications required for direct aerospace supply.
- Metalworking:General fabrication job shops across Cundinamarca and Antioquia serve construction, furniture, and agricultural equipment OEMs with mixed manual and semi-automated capacity.
Metalworking commands deepest installed base. Automotive parts is gaining share fastest.
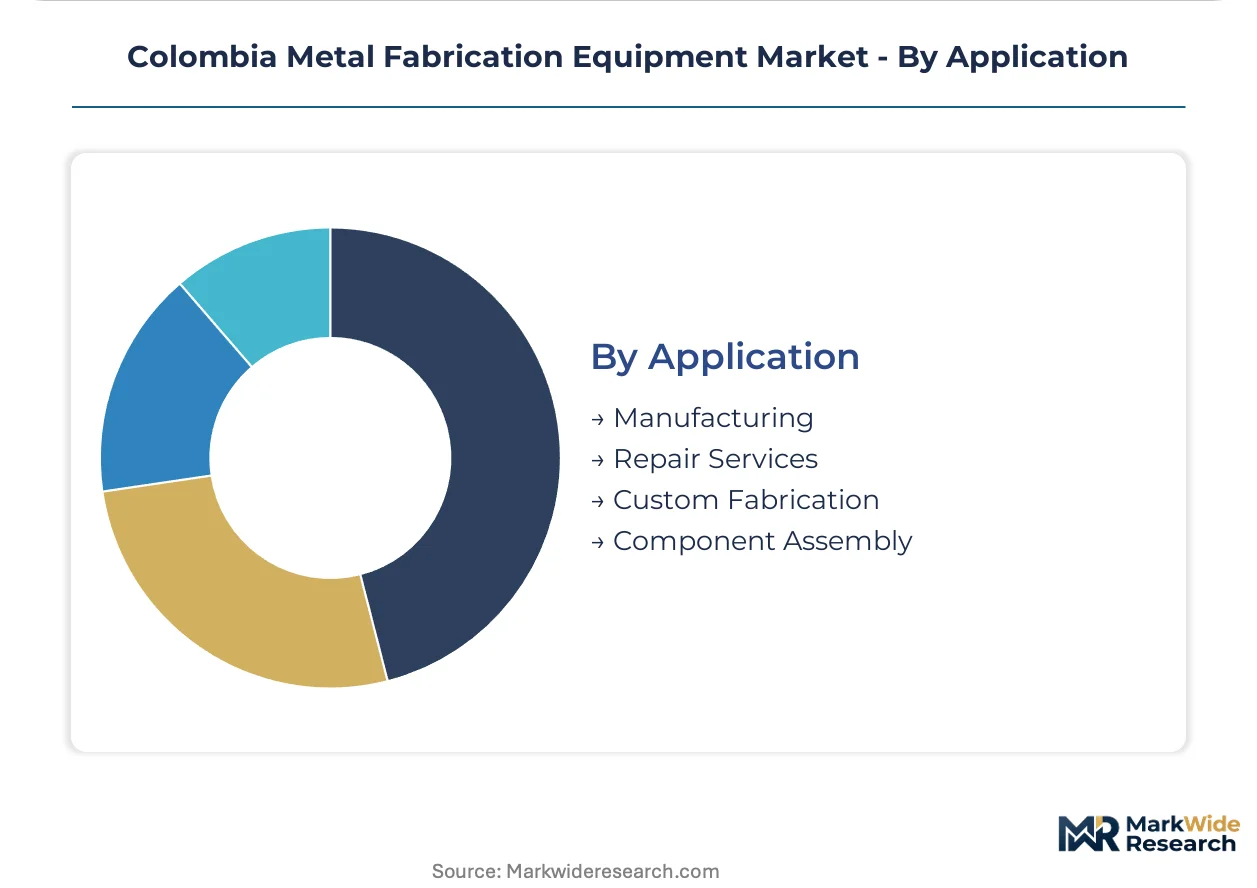
Application:
Volume concentration separates high-throughput manufacturing from episodic repair and custom work, with component assembly representing the margin-rich middle ground where automation investments recover fastest.
- Manufacturing:Continuous production environments in Gerdau and Ternium downstream operations run equipment at utilization rates above 80 percent. Cloud-native manufacturing execution software is digitizing job scheduling across these operations, compressing quoting cycles from days to hours.
- Component Assembly:Tier-one automotive suppliers integrate laser-cut and press-braked parts into subassemblies for export. Equipment-as-a-service contracting is displacing outright purchase here, compressing capital deployment cycles.
- Custom Fabrication:Small-batch architectural metalwork and specialized machinery frames demand flexible equipment configurations. Bogotá job shops dominate this fragmented segment.
- Repair Services:On-site welding and emergency fabrication for mining and oil infrastructure operates on opportunistic demand patterns with irregular equipment utilization.
Manufacturing dominates installed base. Component assembly is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian steel exports flow into Colombian fabrication clusters, while Mexican automotive parts suppliers source precision equipment from Andean distributors serving Bogotá and Medellín industrial corridors.
Andean Region
Ecuadorian mining contractors drive demand for heavy-duty welding systems in copper extraction projects. The country's national technical standards body enforces conformity assessment for imported industrial machinery. Quito-based fabricators underinvest in laser cutting capacity due to sparse service technician networks.
Central America
Costa Rican medical device OEMs require precision metal components for surgical instrument assembly. The national quality regulator mandates ISO 13485 alignment for equipment used in regulated manufacturing. San José hosts a nascent cluster of contract fabricators serving North American healthcare supply chains.
Southern Cone
Chilean copper smelter maintenance operations sustain demand for portable welding and cutting equipment. The national mining regulator imposes safety certification requirements for machinery operating in subterranean environments. Antofagasta's mining services corridor concentrates equipment rental and repair operations.
Caribbean Basin
Dominican Republic tourism infrastructure developers specify automated structural steel fabrication for resort construction. The national standards institute enforces technical regulations for imported construction machinery. Santo Domingo's free trade zones attract light fabrication operations serving North American retail fixtures.
Brazil
São Paulo state automotive OEMs drive demand for robotic welding cells in passenger vehicle assembly. The national industrial property institute administers conformity assessment procedures for imported capital goods. ABC Paulista's manufacturing belt hosts the densest concentration of metal fabrication equipment distributors in Latin America.
Colombia Metal Fabrication Equipment Market Competitive Environment
On the supply side, the industry is tiered between integrated steel producers controlling downstream demand, international technology licensors supplying advanced systems, and regional assemblers capturing protected domestic share. Three strategic archetypes dominate: captive steel-integrated fabricators, foreign OEMs with local certification infrastructure, and service-forward distributors leasing equipment rather than selling outright. Competitive moves center on portfolio diversification into predictive maintenance services and geographic expansion into underpenetrated Pacific corridor markets.
Among steel-integrated players, Gerdau and Ternium occupy positions that exemplify backward integration into fabrication demand generation. Colfax represents the international technology licensor archetype, supplying advanced welding systems through established distribution channels. Regional specialists including INPLASMEC and PRAMEC SAS sit within the certified domestic assembler tier, capturing demand displacement during foreign OEM compliance gaps.
| Leading Market Players |
|---|
| Colfax |
| INPLASMEC |
| Ternium |
| Recicladora MetalPlast Solutions MG |
| Listonplast SAS |
| Gerdau |
| Arbez Ingenieria |
| Grupo Hera Colombia |
| PRAMEC SAS |
| Others |
Value Chain & Pricing Dynamics
Ternium and Gerdau's captive steel production in Colombia anchors raw material pricing power that flows downstream into fabrication equipment utilization economics. Their control over flat-rolled steel supply chains concentrates margin capture upstream while forcing equipment buyers to absorb input volatility through compressed maintenance budgets or deferred replacement cycles.
Pricing Analysis
Next-generation servo-electric press brakes command 40-60% premiums over hydraulic equivalents, while prior-generation CO2 laser systems trade at distressed valuations against fiber laser replacements. Three-tier pricing structure across premium CNC-integrated, standard semi-automated, and economy manual equipment levels reflects certification grade and after-sales bundling intensity. Cost compression in mid-tier welding equipment is intensifying because ICONTEC NTC certification updates accelerate compliance-driven replacement demand. Small Bogotá job shops exhibit highest price sensitivity, while Medellín automotive tier-ones prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Extended payment terms from 90 to 180 days characterize supplier-financing arrangements for European and Asian OEMs navigating Law 1955 of 2019 compliance testing. Equipment sourcing concentrates in Germany, Japan, and South Korea for precision CNC controllers and robotic welding cells. Component dependencies include high-power fiber laser sources, servo motor drives, and specialized welding consumables. Single-source vulnerability sits with fiber laser maintenance technicians concentrated in Bogotá's industrial corridor. Distribution runs through authorized dealer networks with service-forward capabilities in Antioquia and Cundinamarca.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Colombia's metal fabrication equipment market represents early-cycle expansion as construction sector automation mandates pull demand from manual equipment categories into robotic welding systems. Cloud-based predictive maintenance convergence creates recurring revenue infrastructure that extends equipment vendor economics beyond hardware sales.
For Market Incumbents: Harden certification infrastructure against ICONTEC NTC alignment requirements to capture demand displacement during foreign OEM approval gaps. Deepen captive steel relationships with Ternium and Gerdau to secure raw material allocation priority during supply tightness. Expand predictive maintenance service portfolios to offset hardware margin compression from equipment-as-a-service contracting trends.
For New Entrants and Emerging Players: Cali-Pacific corridor manufacturing zones lacking dense equipment supplier networks represent the most penetrable entry point for service-forward distributors. Automotive parts suppliers in Medellín's cluster seeking export compliance retooling offer white-space demand for leased laser cutting capacity with bundled maintenance. Go-to-market execution should anchor on IoT-enabled remote diagnostics capabilities that differentiate against legacy hardware vendors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional assemblers holding NTC-certified manufacturing infrastructure. Long-term viability over a 5-10 year window rests on software-enabled service revenue transitioning from transactional equipment sales. The signal to watch is Mining and Energy Planning Unit mandate timing for electrically intensive process efficiency standards.
| Strategic Initiative | Industry Significance |
|---|---|
| NTC Certification Infrastructure Expansion | Captures demand displacement during foreign OEM compliance gaps under Law 1955 of 2019. |
| Predictive Maintenance Service Launch | Shifts revenue from hardware sales to recurring software subscriptions with CNC-integrated IoT sensors. |
| Cali-Pacific Corridor Distribution Buildout | Establishes first-mover position in port-proximate manufacturing zones lacking dense supplier networks. |
| Servo-Electric Press Brake Portfolio Addition | Aligns product mix with anticipated Mining and Energy Planning Unit efficiency mandates. |
| Equipment-as-a-Service Contracting Model | Transfers obsolescence risk from buyers to vendors in Medellín's automotive parts cluster. |
Study Parameters
The analysis maps laser cutting machines, welding equipment, press brakes, and bending machines, each validated through plant engineers, OEM procurement teams, aftermarket service heads, and maintenance directors. Primary interviews with equipment distributors and fabrication shop owners combined with secondary validation from customs records, SEC filings of multinational suppliers, ICONTEC certification databases, and Mining and Energy Planning Unit regulatory disclosures. Bottom-up equipment installation tracking and top-down steel consumption modeling provide triangulation across data sources.
Assumptions around ICONTEC NTC certification timelines, Mining and Energy Planning Unit mandate implementation, and construction sector automation adoption velocity were held fixed while steel input pricing and exchange rate trajectories were varied across sensitivity scenarios. Segmentation dimensions modeled include product type, technology tier, end-user industry, and geographic cluster. CAGRs were derived from equipment replacement cycle analysis and capital expenditure survey data. Industry-specific forecast inputs encompass Gerdau and Ternium downstream demand generation and automotive export compliance retooling intensity.
Macroeconomic conditions sit as an overlay; deviation in peso-dollar exchange rates, construction sector credit availability, or regional steel trade flows would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation timing and technology adoption curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Roll Forming Machine Market
Construction Equipment and Machinery
Hydraulic Shop Crane Market
Construction Equipment and Machinery
Steel Fabrication Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Hot Chamber Die Casting Machine Market
Construction Equipment and Machinery
Shaper & Shaping Machine Market
Construction Equipment and Machinery
Global Rebar Processing Equipment Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Crushing, Screening, and Mineral Processing Equipment Market
Construction Equipment and Machinery
Latin America Paper Making Machine Market
Construction Equipment and Machinery
Concrete Finishing Equipment Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Global Woodworking Machinery Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Global Electric Presses Market