
 ASEAN Construction Machinery Market | 2026-2036
ASEAN Construction Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
ASEAN Construction Machinery Market Outlook
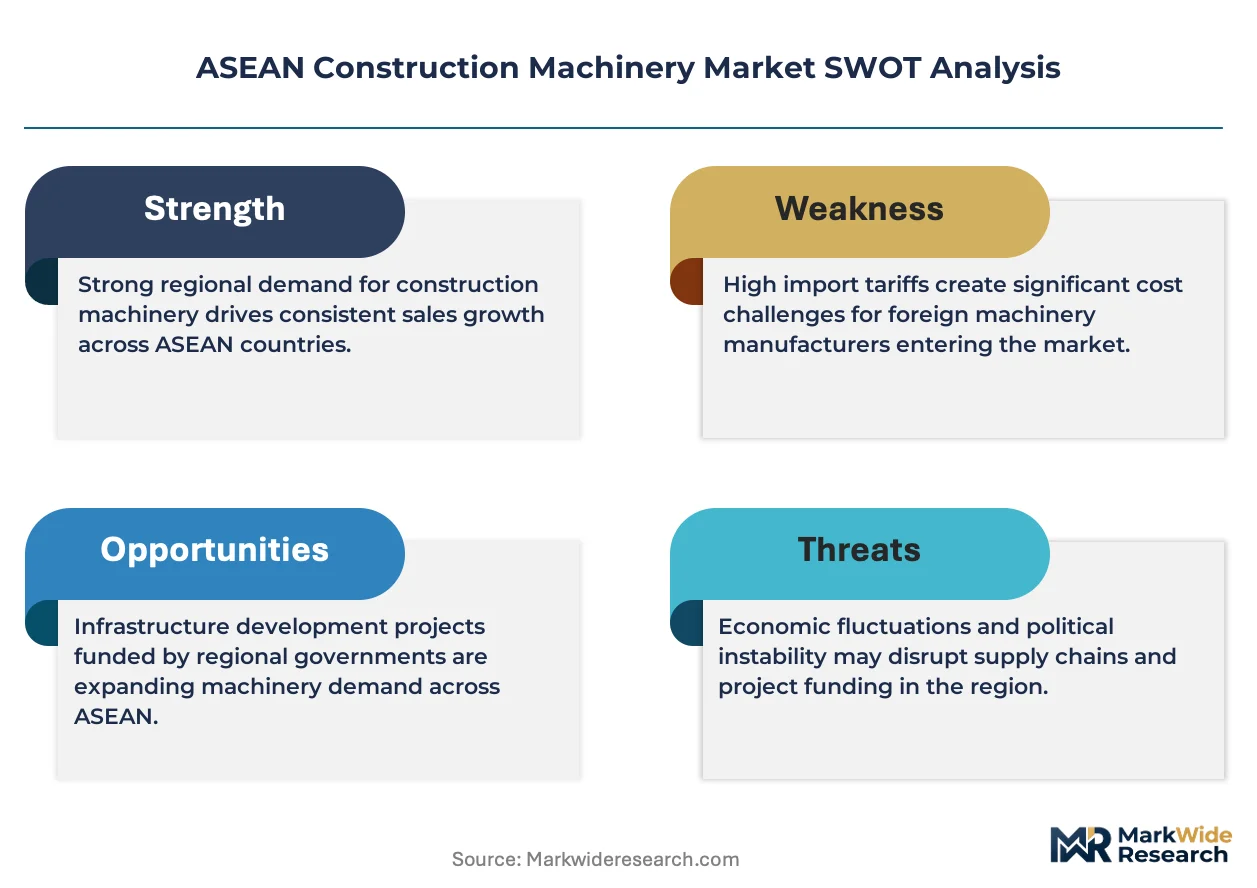
ISO 9001 quality management certification is reorganizing supplier eligibility for public works tenders across Southeast Asia. Komatsu Ltd. sustains manufacturing scale through its established Indonesian assembly operations serving domestic and export demand. XCMG leverages cost-engineered hydraulic excavators to compete aggressively in Vietnam's infrastructure expansion. Caterpillar Inc. anchors premium positioning through its regional parts distribution network headquartered in Singapore.
ASEAN construction machinery encompasses earth-moving, lifting, and material-handling equipment engineered to power outputs exceeding 75 kW for commercial and civil engineering applications. Hydraulic systems dominate current fleet composition, though electric drive trains are penetrating urban demolition and site preparation contracts with stricter emissions boundaries. Excavators command the largest product type share, reflecting trenching and foundation work intensity across the region's land development pipeline. Road construction applications absorb the steepest demand growth, driven by trans-ASEAN highway connectivity programs and port-linked industrial zone buildouts.
Thailand's Industrial Standards Institute, Indonesia's Ministry of Industry local content thresholds, and Vietnam's Ministry of Construction equipment registration rules collectively determine import access and domestic assembly incentives. These frameworks push OEMs toward joint ventures or component sourcing within ASEAN member states to qualify for government project awards. Stakeholders must track evolving national content ratios and emissions tier alignments as procurement rules harden across member states.
Market Dynamics
Indonesia's Ministry of Industry local content thresholds and Thailand's Industrial Standards Institute certification mandates are forcing foreign OEMs into joint ventures and domestic assembly partnerships, restructuring competitive entry paths across Southeast Asia's public procurement landscape.
Growth Catalysts
- Trans-ASEAN Highway Connectivity:Government infrastructure agencies in Vietnam, Thailand, and Indonesia are expanding fleet procurement for road and rail corridors, driving sustained equipment demand through multi-year capital programs.
- ISO 9001 Tender Eligibility:Quality management certification is reorganizing supplier eligibility for public works contracts, filtering out uncertified competitors from national procurement pools.
- Java Urban Construction Belt:Indonesia's densest population corridor generates concentrated demand for foundation and trenching equipment, anchoring excavator deployment intensity.
Market Restraints
- Steel and Hydraulics Input Volatility:Fluctuating commodity prices for high-grade steel and precision hydraulic components compress margin predictability for equipment assemblers.
- Import Dependency Concentration:Critical powertrain and electronic control systems remain concentrated in Japanese and Korean supplier bases, exposing ASEAN assemblers to supply disruption risk.
- Emissions Tier Misalignment:Divergent national emissions standards across member states create certification fragmentation, raising compliance costs for pan-ASEAN product strategies.
Strategic Opportunities
- Vietnam Northern Manufacturing Corridor:Underpenetrated demand for material-handling equipment in Hai Phong and Bac Ninh industrial zones offers first-mover positioning for regional distributors.
- Electric Drive Convergence:Battery-electric powertrains combined with telematics platforms are opening urban demolition contracts with strict emissions boundaries previously closed to diesel fleets.
- Domestic Content Incentives:Indonesia's local content regulations reward joint ventures with preferential access to state-owned enterprise procurement, creating structural advantages for partnered market entry.
Industry Challenges
- Certification Timeline Compression:Equipment registration rules under Vietnam's Ministry of Construction and Thailand's Industrial Standards Institute create multi-month approval bottlenecks that delay project mobilization.
- Telematics Integration Complexity:Legacy fleet management systems in established contractor bases resist seamless integration with connected equipment platforms, slowing digital service adoption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ASEAN Construction Machinery Market |
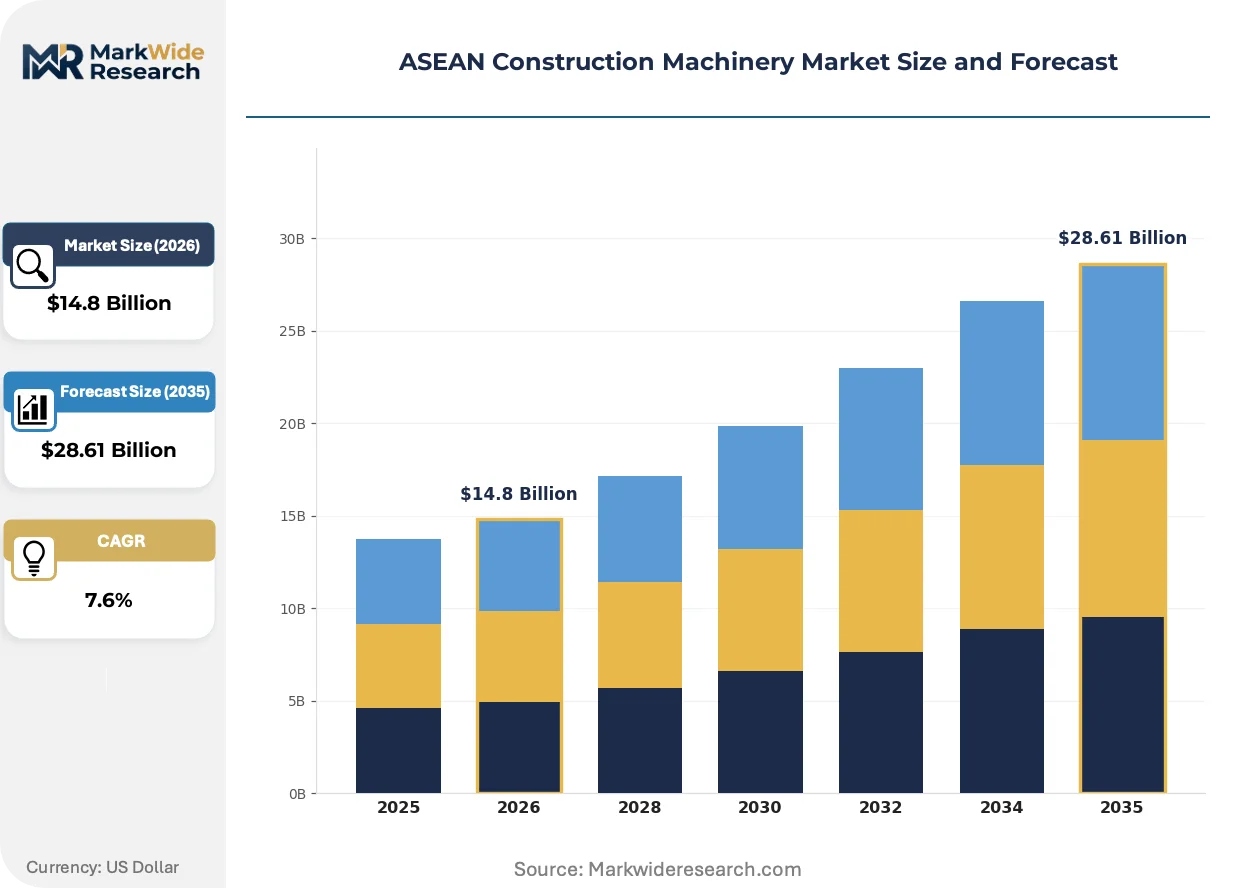
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $28.61 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Excavators, Bulldozers, Graders, Cranes End User: Contractors, Builders, Excavation Services, Government Agencies Technology: Hydraulic, Electric, Engine-Powered, Automation Application: Road Construction, Land Development, Site Preparation, Demolition |
| Companies Covered | Liebherr Group, XCMG (Xuzhou Construction Machinery Group Co. Ltd.), Caterpillar Inc., JCB (JC Bamford Excavators Ltd.), SANY, Komatsu Ltd., Mitsubishi Corporation, Volvo Construction Equipment, Hitachi Construction Machinery Co., Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ASEAN Construction Machinery Market Strategic Shifts
Electrification, regulatory harmonization pressures, and procurement digitization are converging to reshape equipment specification and fleet management practices across Southeast Asian construction markets.
Telematics-enabled predictive maintenance systems are miniaturizing sensor arrays and edge computing modules for integration into compact excavators and wheel loaders. Mid-sized contractors in Thailand's residential construction sector are adopting these systems fastest, drawn by fuel consumption transparency and downtime reduction. The technology is miniaturizing total cost of ownership calculations, compressing payback period assumptions that previously favored basic mechanical specifications.
Indonesia's BIS-equivalent national standards body is tightening equipment safety and emissions testing protocols for imported machinery. This regulatory tightening is forcing foreign OEMs to establish domestic testing facilities or partner with local certification laboratories before market entry. Heavy excavator categories face the steepest compliance burden, with several manufacturers accelerating Indonesian assembly investments to bypass full import certification requirements.
Equipment-as-a-service contracting is displacing traditional ownership models among Vietnam's infrastructure developers and Singapore-based regional contractors. Fleet managers now prioritize utilization-rate guarantees and bundled maintenance over asset acquisition, shifting capital allocation from balance sheets to operating expenditure lines. This behavioral shift is most visible in Vietnam's northern manufacturing corridor, where project-based contractors lack storage capacity for owned equipment between construction phases.
ASEAN Construction Machinery Market Segmentation
Equipment specification varies sharply across ASEAN procurement channels. Government tender rules, emissions boundaries, and project scale together determine which machinery categories capture capital allocation in Thailand, Vietnam, and Indonesia.
Product Type:
Margin pools concentrate in high-utilization categories with aftermarket parts dependency and financing attachment rates.
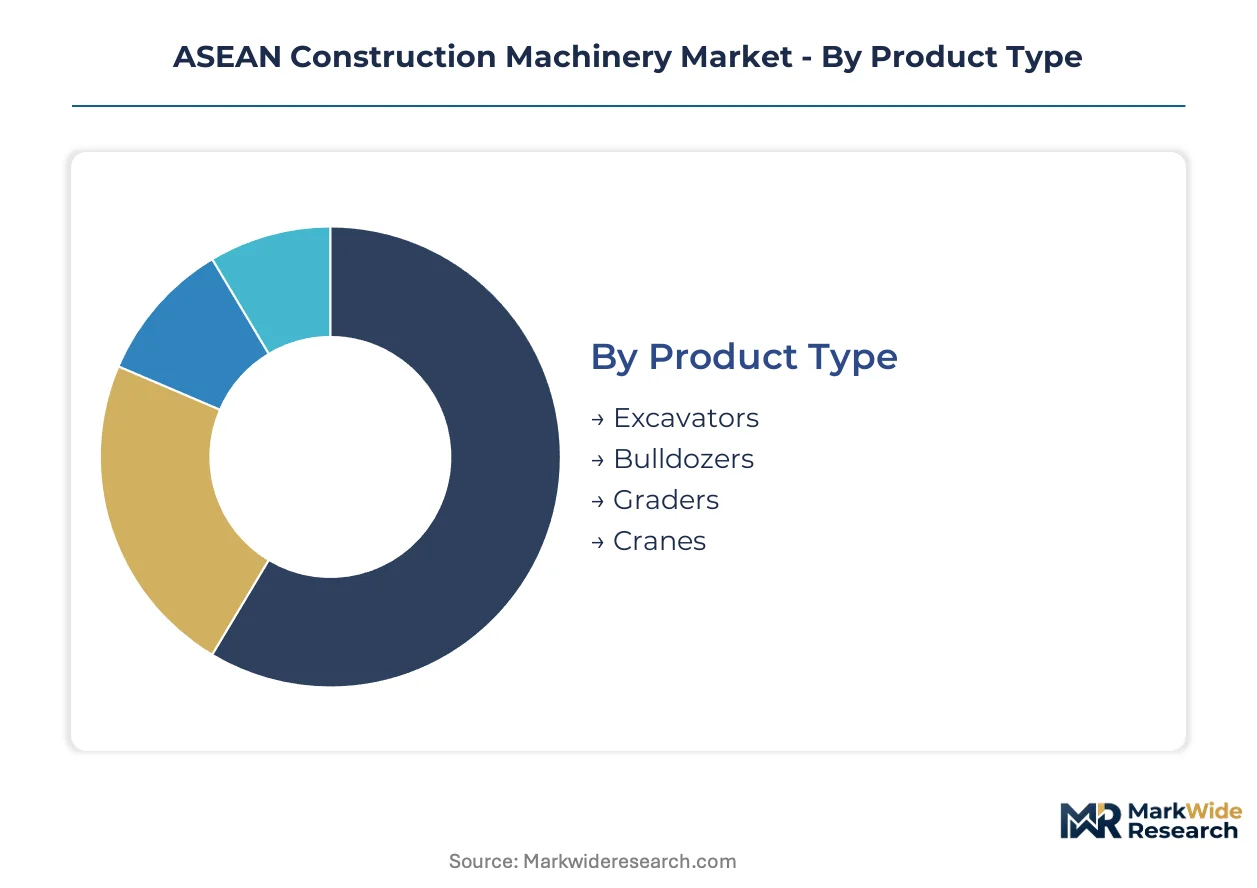
- Excavators:Hydraulic-powered machines with operating weights from 6 to 45 tonnes dominate fleet composition across the region. Vietnam's northern manufacturing corridor and Indonesia's Java urban belt absorb the steepest deployment volumes for foundation and trenching work, with rental fleets expanding fastest among mid-sized contractors lacking storage capacity between project phases.
- Bulldozers:Track-type tractors with blade capacities exceeding 5 cubic meters serve land clearing and rough grading operations. Road construction applications in Thailand's trans-ASEAN highway corridors drive sustained procurement, though diesel emissions tier misalignment across member states fragments certification requirements for pan-regional product strategies.
- Graders:Motor graders with articulated frames and precision blade control finish road surfaces to specification. Indonesia's Ministry of Industry local content thresholds push foreign OEMs toward domestic assembly partnerships for this category.
- Cranes:Mobile and crawler configurations handle lifting operations across industrial zone buildouts. Singapore-based regional contractors prioritize utilization-rate guarantees over ownership in this capital-intensive segment.
Excavators hold installed capacity. Cranes are rotating up the share rankings.
End User:
Procurement authority and financing access separate customer tiers more than fleet scale alone.
- Contractors:Private construction firms executing commercial and residential projects constitute the volume base. Equipment-as-a-service contracting is displacing traditional ownership models among Vietnam's infrastructure developers, shifting capital allocation from balance sheets to operating expenditure lines.
- Builders:Vertical developers with in-house construction capabilities source machinery for captive project pipelines. Thailand's residential construction sector adopts telematics-enabled predictive maintenance systems fastest, drawn by fuel consumption transparency.
- Excavation Services:Specialized earth-moving subcontractors rent or lease equipment against project-specific contracts. This segment lacks storage capacity for owned equipment between construction phases.
- Government Agencies:State-owned enterprises and infrastructure ministries deploy the largest individual fleet orders. Indonesia's local content regulations reward joint ventures with preferential access to this procurement channel.
Government agencies anchor volume concentration. Contractors are climbing the fastest as equipment-as-a-service penetration deepens.
Technology:
Powertrain architecture determines emissions compliance pathways and operating cost profiles across national regulatory boundaries.
- Hydraulic:Fluid-power transmission systems dominate current ASEAN fleet composition through proven reliability and repair network density. Legacy fleet management systems in established contractor bases resist seamless integration with connected equipment platforms, slowing digital service adoption in this installed base.
- Electric:Battery-electric powertrains combined with telematics platforms open urban demolition contracts with strict emissions boundaries previously closed to diesel fleets. Singapore and Bangkok municipal authorities are tightening emissions boundaries fastest.
- Engine-Powered:Diesel internal combustion engines with tiered emissions controls serve remote projects lacking charging infrastructure. Divergent national emissions standards across member states create certification fragmentation.
- Automation:Semi-autonomous machine control and GPS-guided grading reduce operator skill requirements. Miniaturizing sensor arrays and edge computing modules enable integration into compact excavators and wheel loaders.
Hydraulic systems hold installed capacity. Electric configurations are expanding most quickly on emissions boundary tightening.
Application:
Project type determines equipment mix, utilization intensity, and replacement cycle frequency.
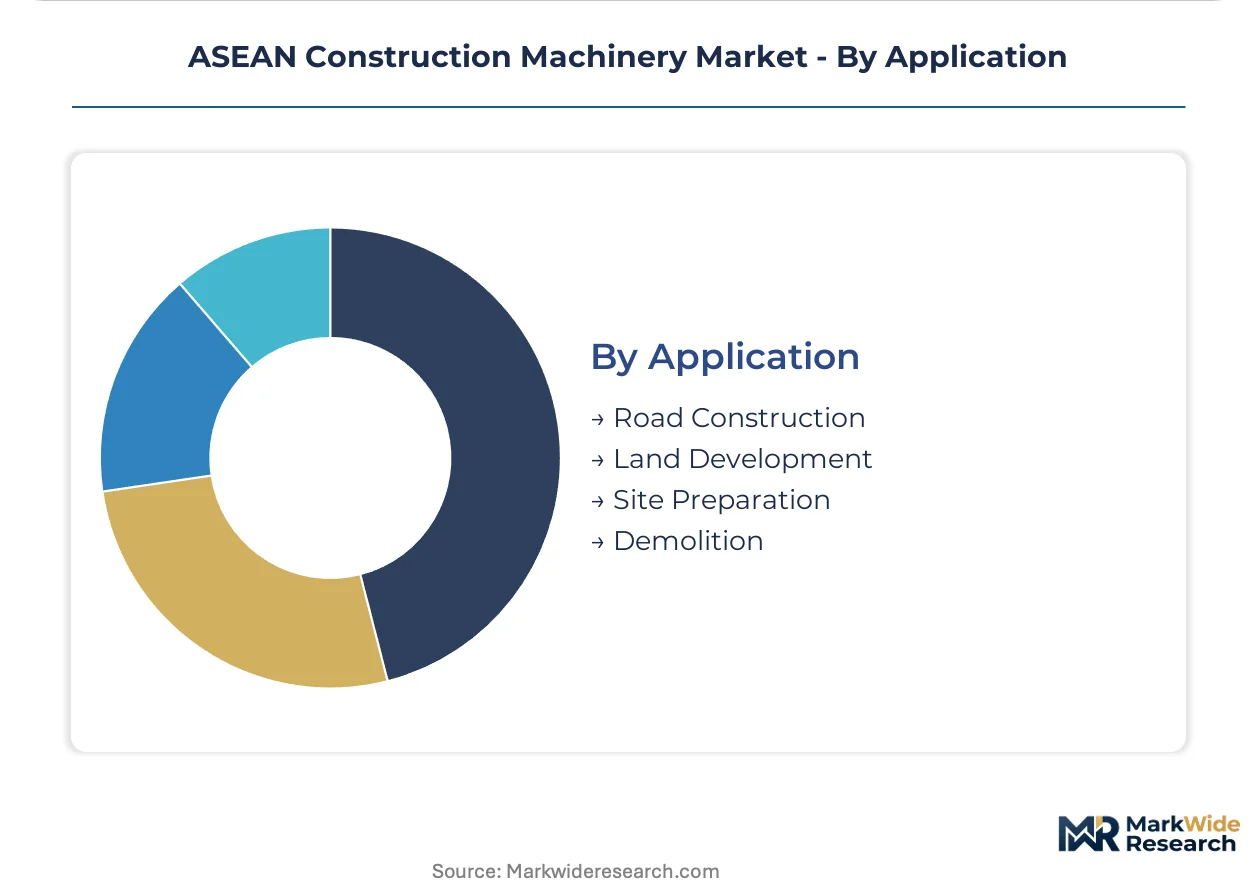
- Road Construction:Highway, arterial road, and bridge building operations absorb the steepest demand growth across the region. Trans-ASEAN highway connectivity programs and port-linked industrial zone buildouts in Thailand, Vietnam, and Indonesia drive multi-year capital equipment procurement.
- Land Development:Greenfield site conversion for industrial, residential, and commercial use requires coordinated earth-moving fleets. Indonesia's densest population corridor generates concentrated demand for foundation equipment.
- Site Preparation:Grading, drainage, and utility rough-in work precedes vertical construction. This application faces multi-month approval bottlenecks under Vietnam's Ministry of Construction equipment registration rules.
- Demolition:Deconstruction of existing structures demands specialized attachments and emissions-controlled operations. Urban demolition contracts with strict emissions boundaries increasingly specify electric drive trains.
Road construction anchors volume concentration. Demolition is gaining share fastest on urban renewal project acceleration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indonesia's Ministry of Industry local content thresholds and Vietnam's Ministry of Construction equipment registration rules are redirecting foreign OEM investment toward domestic assembly partnerships across Southeast Asia's public procurement landscape.
Indonesia
Java's urban construction belt generates concentrated excavator demand for foundation and trenching work in Jakarta and Surabaya. The Ministry of Industry enforces local content thresholds that reward joint ventures with preferential access to state-owned enterprise procurement. Komatsu Ltd. sustains manufacturing scale through established Indonesian assembly operations serving domestic and export demand.
Vietnam
The northern manufacturing corridor spanning Hai Phong and Bac Ninh industrial zones absorbs steep material-handling equipment deployment. XCMG leverages cost-engineered hydraulic excavators to compete aggressively in infrastructure expansion tenders. Equipment-as-a-service contracting displaces traditional ownership models among project-based contractors lacking storage capacity between construction phases.
Thailand
Trans-ASEAN highway connectivity programs drive multi-year capital equipment procurement for road and rail corridors. The Industrial Standards Institute mandates ISO 9001 certification for public works tender eligibility, filtering uncertified competitors from national procurement pools. Mid-sized contractors in the residential construction sector adopt telematics-enabled predictive maintenance systems fastest.
Singapore
Municipal authorities tighten emissions boundaries fastest, opening urban demolition contracts to battery-electric powertrains previously closed to diesel fleets. Regional contractors headquartered in Singapore prioritize utilization-rate guarantees and bundled maintenance over crane ownership. Caterpillar Inc. anchors premium positioning through its regional parts distribution network headquartered in the city-state.
Philippines
Port-linked industrial zone buildouts in Batangas and Subic Bay generate sustained demand for earth-moving and lifting equipment. The national infrastructure agency accelerates fleet procurement for road construction applications. Local contractors face multi-month approval bottlenecks under equipment registration rules that delay project mobilization.
ASEAN Construction Machinery Market Competitive Environment
Player mix skews toward integrated multinational assemblers with regional distribution networks and cost-engineered Chinese fabricators competing on specification-adjusted pricing. The market structure concentrates volume among established OEMs with domestic assembly presence in Indonesia and Thailand, while mid-tier specialists capture niche segments through rental fleet partnerships. Three strategic archetypes dominate: premium-tier multinationals with aftermarket parts dependency, value-engineered Chinese exporters with aggressive tender pricing, and regional distributors with utilization-rate service models. Competitive moves center on domestic content compliance partnerships and telematics platform integration.
Within the premium-tier multinational segment, Caterpillar Inc. and Komatsu Ltd. occupy positions anchored by regional parts distribution and established assembly operations. XCMG exemplifies the cost-engineered archetype competing through specification-adjusted hydraulic excavators. Volvo Construction Equipment sits within the telematics-integrated tier, representing the service-model pivot toward predictive maintenance and utilization guarantees.
| Leading Market Players |
|---|
| Liebherr Group |
| XCMG (Xuzhou Construction Machinery Group Co. Ltd.) |
| Caterpillar Inc. |
| JCB (JC Bamford Excavators Ltd.) |
| SANY |
| Komatsu Ltd. |
| Mitsubishi Corporation |
| Volvo Construction Equipment |
| Hitachi Construction Machinery Co. |
| Others |
Value Chain & Pricing Dynamics
Battery-electric powertrain substitution for hydraulic systems is redrawing component sourcing maps toward East Asian battery cell suppliers while compressing aftermarket parts pricing power for traditional drivetrain assemblers. This displacement simultaneously elevates upfront equipment costs and shifts lifetime value capture toward telematics-enabled service bundling.
Pricing Analysis
Certification tier alignment with Indonesia's Ministry of Industry local content thresholds and Thailand's Industrial Standards Institute mandates creates the primary spread between premium and standard equipment positioning. Three-tier pricing structure separates ISO 9001-certified units with full aftermarket support from basic mechanical specifications and economy-grade imports without local assembly. Cost compression in the hydraulic excavator segment is intensifying because XCMG and SANY are competing aggressively on specification-adjusted tender pricing. Government agencies demonstrate lowest price sensitivity due to total-cost-of-ownership procurement rules, while excavation services contractors exhibit highest sensitivity driven by project-based cash flow constraints.
Supply Chain Analysis
Port congestion at Tanjung Priok and Hai Phong is elevating inbound logistics costs for fully-knocked-down kits awaiting domestic assembly. Component concentration rests on China for precision hydraulic systems, Japan for electronic control modules, and South Korea for high-grade steel alloys. Critical powertrain dependencies expose ASEAN assemblers to single-source vulnerability when Japanese suppliers face production allocation constraints. Distribution runs through regional parts distribution networks headquartered in Singapore, with secondary stocking points in Jakarta and Bangkok serving contractor fleet maintenance demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ASEAN construction machinery is recovering from a cyclical trough driven by trans-ASEAN highway connectivity program restarts and port-linked industrial zone buildouts resuming capital allocation.
For Market Incumbents: Consolidate domestic assembly partnerships in Indonesia and Thailand to satisfy local content thresholds before certification rules harden further. Deepen backward integration into hydraulic component production to defend margin position against cost-engineered Chinese entrants. Prioritize telematics platform integration to capture recurring service revenue as equipment-as-a-service contracting displaces traditional ownership models among Vietnam's infrastructure developers.
For New Entrants and Emerging Players: ISO 9001 certification fast-track through Singapore-based accreditation bodies opens procurement eligibility for Thailand's public works tenders within compressed timelines. Target Vietnam's northern manufacturing corridor for material-handling equipment deployment where rental fleet penetration remains underdeveloped. Pursue joint venture structures with Indonesian domestic assemblers to bypass full import certification requirements and access state-owned enterprise procurement channels.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors holding utilization-rate service contracts in Singapore and Bangkok. Long-term viability hinges on electrification transition execution and telematics platform maturity across the five-to-ten year window. Monitor Indonesia's BIS-equivalent national standards body emissions tier alignment announcements as the inflection signal for compliance cost step-ups favoring capitalized incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Assembly Partnership | Indonesia's Ministry of Industry local content thresholds reward joint ventures with preferential state-owned enterprise procurement access. |
| Telematics Platform Integration | Predictive maintenance systems compress total cost of ownership calculations for Thailand's residential construction contractors. |
| Electric Drive Train Certification | Singapore municipal emissions boundaries open urban demolition contracts previously closed to diesel-powered fleets. |
| Aftermarket Parts Network Expansion | Caterpillar's regional distribution hub in Singapore anchors premium positioning through reduced equipment downtime. |
| Rental Fleet Utilization Guarantees | Equipment-as-a-service contracting shifts capital allocation from balance sheets to operating expenditure lines for Vietnamese contractors. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with fleet managers at Indonesian state-owned enterprises, procurement directors at Thai infrastructure contractors, aftermarket service heads at regional distributors, and plant engineers at Vietnamese industrial zone developers; alongside secondary validation through customs import records, Ministry of Construction equipment registration databases, and ISO certification registries. Bottom-up equipment deployment estimates triangulated against top-down infrastructure capital expenditure disclosures.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, powertrain technology, end-user procurement authority, and application intensity. CAGRs were derived from equipment replacement cycle analysis and infrastructure pipeline visibility. Forecast inputs incorporated local content threshold evolution patterns and emissions tier convergence assumptions across member states.
Decision-makers should treat outputs as directional under sustained infrastructure capital commitment assumptions; material deviation in government fiscal capacity or trade lane disruption would warrant model refresh. Specific risk factors include steel and hydraulics input volatility, certification timeline compression under Vietnam's Ministry of Construction rules, and telematics integration complexity with legacy fleet management systems. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Global Rebar Processing Equipment Market
Construction Equipment and Machinery
Global Industrial Assembly Equipment Market
Construction Equipment and Machinery
Construction Machinery Attachment Market
Construction Equipment and Machinery
Global Electric Presses Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Industrial Dryers Market
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Parallel-Shaft Gear Reducer Market
Construction Equipment and Machinery
Global Laundry Folding Machine Market
Construction Equipment and Machinery
Brick Making Machines Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Africa Heavy Construction Equipment Rental Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Concrete Block Making Machines Market