
 Parallel-Shaft Gear Reducer Market | 2026-2036
Parallel-Shaft Gear Reducer Market Size, Share, and Industry Trends Forecast 2026-2036
Parallel-Shaft Gear Reducer Market Insights
The capital-intensity divergence between in-house gear grinding capacity and outsourced machining is bifurcating competitive tiers across the Parallel-Shaft Gear Reducer landscape. Siemens AG sustains dominance through captive heat-treatment and finishing lines that compress lead times for large helical units. Bonfiglioli specializes in modular platform architectures that reduce engineering-to-order cycles for material handling integrators. NORD Drivesystems leverages distributed assembly nodes across industrial corridors to anchor regional service responsiveness.
A parallel-shaft gear reducer transmits rotational power between offset shafts through meshing cylindrical gears, typically achieving reduction ratios from 1.5:1 to 100:1 with helical tooth profiles that distribute load across multiple contact lines for quieter operation than spur equivalents. Helical gear reducers occupy the largest installed base due to their torque density and efficiency in continuous-duty manufacturing environments. Roller bearing technology captures premium positioning where shock loads from mining operations and construction equipment demand superior radial capacity over plain bearing alternatives. Needle bearing configurations compete on compact axial envelope for packaging machinery and textile machines with constrained mounting dimensions.
ISO 6336 and AGMA 2001 gear-rating standards govern bending and contact stress calculations that determine reducer service life claims, while CE marking under EU Machinery Directive 2006/42/EC mandates documented risk assessment for integrators deploying units in European manufacturing plants. EPA and OSHA frameworks in the United States impose lubricant containment and guarding requirements that shape enclosure designs and maintenance protocols. Stakeholders must monitor evolving efficiency regulations from DOE and IEC that threaten to obsolete fixed-speed reducer architectures unless paired with variable-frequency drive integration.
Market Dynamics
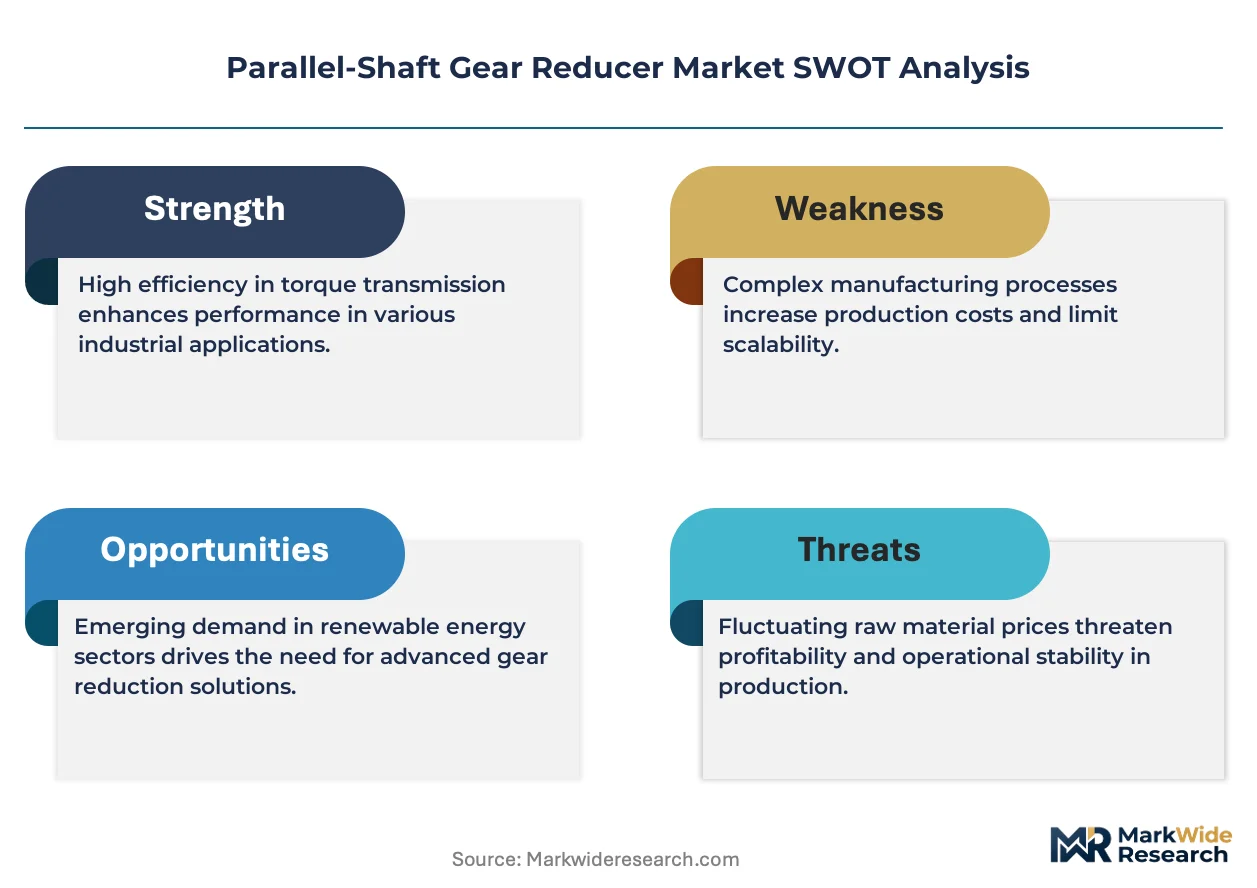
ISO 6336 gear-rating standards are tightening performance thresholds for industrial power transmission, forcing reducer manufacturers to recalibrate tooth geometry optimization and heat-treatment protocols to maintain certification validity across European and North American supply chains.
Growth Catalysts
- EU Machinery Directive 2006/42/EC:Mandated CE marking for integrators deploying units in European manufacturing plants drives documented risk assessment protocols that favor certified precision-engineered reducers over unverified alternatives.
- Material handling equipment:Intralogistics OEMs in Germany are expanding adoption of modular reducer platforms to compress engineering-to-order cycles for automated warehouse systems.
- Helical tooth profile advancement:Multiple contact line load distribution across cylindrical gears achieves quieter operation than spur equivalents, penetrating food processing and packaging machinery where acoustic compliance is mandatory.
Market Restraints
- Specialized gear grinding capacity:Captive heat-treatment and finishing lines require capital intensity that bifurcates competitive tiers between integrated manufacturers and outsourced machining dependencies.
- Alloy steel input volatility:Case-hardening grade steel price fluctuations compress margin structures for mid-tier producers lacking long-term supply agreements with primary mills.
- Variable-frequency drive substitution:Fixed-speed reducer architectures face obsolescence pressure unless paired with VFD integration, threatening pure mechanical transmission suppliers.
Strategic Opportunities
- India manufacturing corridors:PLI scheme incentives for industrial automation equipment create white space for localized reducer assembly nodes serving domestic material handling and textile machinery demand.
- DOE efficiency regulations:Anticipated minimum efficiency performance standards for industrial gear drives create regulatory tailwind for premium helical units with documented loss coefficients.
- Digital twin convergence:Integration of IoT-enabled condition monitoring with reducer housings enables predictive maintenance service models that unbundle hardware from lifecycle value capture.
Industry Challenges
- ISO 6336 calculation expertise:Bending and contact stress analysis competency gaps constrain smaller manufacturers from validating service life claims against certified competitors.
- Legacy system integration:Retrofitting precision helical reducers into existing conveyor architectures demands custom adapter fabrication that extends commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Parallel-Shaft Gear Reducer Market |
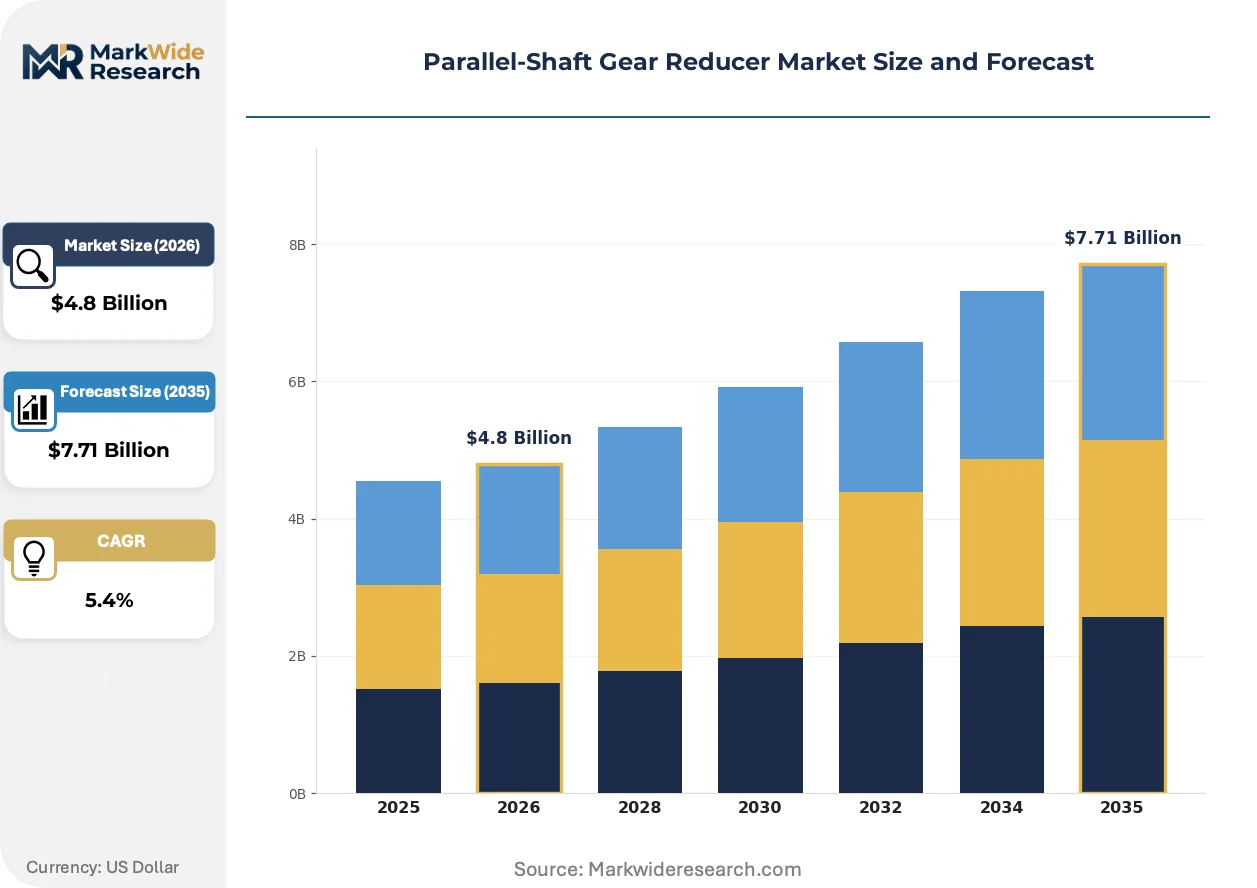
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Helical Gear Reducers, Spur Gear Reducers, Bevel Gear Reducers, Worm Gear Reducers, Planetary Gear Reducers Technology: Lubricated Bearings, Needle Bearings, Plain Bearings, Roller Bearings, Magnetic Bearings Application: Material Handling Equipment, Packaging Machinery, Textile Machines, Printing Equipment, Machine Tools End User Industry: Manufacturing Plants, Agricultural Machinery, Construction Equipment, Renewable Energy Systems, Mining Operations |
| Companies Covered | Sumitomo Heavy Industries, Siemens AG, Mitsubishi Electric, NORD Drivesystems, Bonfiglioli, Watt Drive Antriebstechnik GmbH, Baldor, Rossi, Tsubakimoto Chain, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Parallel-Shaft Gear Reducer Market Trends and Innovations
Additive manufacturing of gear blanks is fragmenting traditional forging-dependent supply chains, enabling topology-optimized tooth forms that were previously unmachinable through conventional hobbing processes.
Topology-optimized gear blanks produced through selective laser melting are fragmenting the conventional forged-and-machined supply base for prototype and low-volume helical units. Mining equipment OEMs in Australia and construction machinery integrators in Germany are piloting these geometries for shock-load applications where weight reduction offsets material cost premiums. The technology is fragmenting lead time structures, compressing prototype iteration cycles from weeks to days for custom ratio requirements.
EPA lubricant containment mandates under 40 CFR are reshaping enclosure seal designs and maintenance protocol documentation for reducers deployed in US chemical processing and wastewater treatment facilities. The regulation forces integrators to specify dual-lip seal configurations and containment sumps that add axial envelope but eliminate discharge liability. Food-grade NSF H1 lubricant compatibility is becoming a non-negotiable specification for North American poultry and dairy processing lines.
Buyer consolidation among automotive tier-one suppliers is compressing switching cycles and forcing reducer vendors into multi-year framework agreements with penalty clauses for non-conformance. German transmission system integrators now demand documented MTBF data validated by third-party testing rather than manufacturer claims. This behavior is most visible in Stuttgart and Wolfsburg industrial corridors where just-in-sequence delivery requirements dominate procurement specifications.
Parallel-Shaft Gear Reducer Market Segmentation
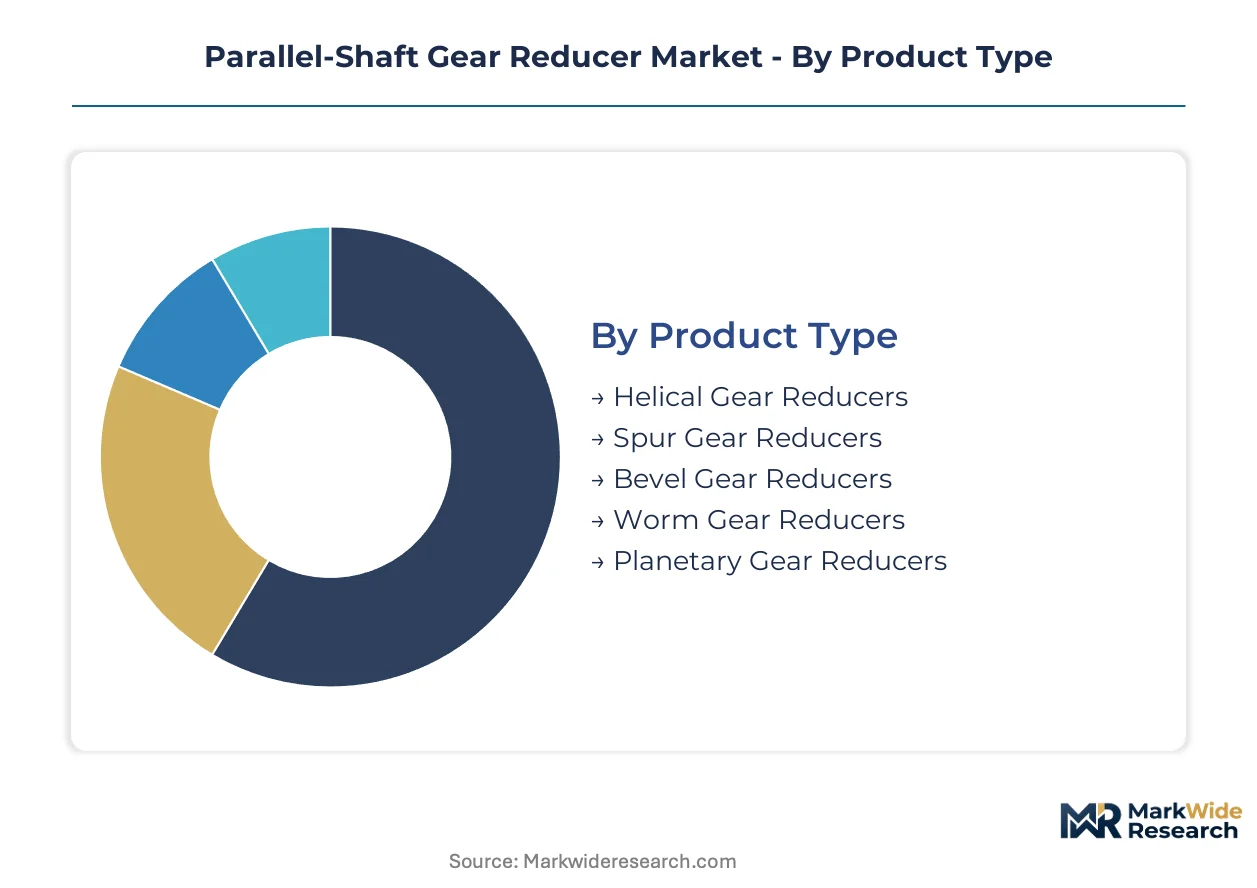
Parallel-shaft gear reducer demand fragments across multiple technical and application dimensions. Each segmentation axis reveals distinct procurement patterns, performance requirements, and substitution vulnerabilities that reshape competitive positioning across industrial corridors.
Product Type:
Helical configurations face the strongest substitution pressure from planetary and worm alternatives in high-torque, right-angle applications where shaft alignment constraints dominate.
- Helical Gear Reducers:Cylindrical gears with angled teeth distribute load across multiple contact lines, achieving efficiency above 95% in continuous-duty manufacturing environments. Demand concentrates in German automotive and intralogistics OEMs where ISO 6336 certification is mandatory for supplier qualification.
- Spur Gear Reducers:Straight-tooth cylindrical gears operate with simpler geometry and lower manufacturing cost but generate higher noise signatures. Packaging machinery integrators in North America specify these for intermittent-duty cycles where acoustic compliance is less critical than capital expenditure control.
- Bevel Gear Reducers:Conical gear meshing transmits power between intersecting shafts, common in mining conveyors requiring right-angle redirection.
- Worm Gear Reducers:Screw-and-wheel meshing achieves high reduction ratios in compact envelopes, penetrating food processing where self-locking prevents backdriving.
- Planetary Gear Reducers:Epicyclic arrangements distribute torque across multiple planet gears, capturing wind turbine pitch control and renewable energy nacelle applications demanding torque density.
Helical gear reducers anchor the volume base while planetary configurations gain share at the steepest rate in renewable energy and precision robotics.
Technology:
Cost tier stratification separates premium bearing technologies from commodity alternatives, with roller and magnetic configurations commanding 3-5x price multiples over plain bearing equivalents.
- Roller Bearings:Cylindrical or tapered rolling elements handle combined radial and axial loads with superior fatigue life. Mining operations in Australia and construction equipment OEMs in Germany specify these for shock-load duty cycles where bearing replacement downtime exceeds component cost premiums.
- Needle Bearings:Small-diameter rollers arranged in high-density configurations minimize radial envelope. Textile machinery and packaging equipment manufacturers in Japan prioritize these where mounting space constraints override load capacity requirements.
- Lubricated Bearings:Oil or grease-fed plain surfaces operate in high-contamination environments with simplified sealing.
- Plain Bearings:Sleeve or bushing configurations serve low-speed, high-load applications in agricultural machinery where maintenance accessibility favors replaceable inserts over rolling elements.
- Magnetic Bearings:Electromagnetic levitation eliminates mechanical contact, penetrating semiconductor manufacturing and cleanroom environments where particulate generation is prohibited.
Roller bearings dominate revenue concentration while magnetic configurations expand most quickly in contamination-sensitive process industries.
Application:
Customer type fragmentation separates project-based OEM integrators from aftermarket replacement demand, with diverging margin structures and sales cycle dynamics.
- Material Handling Equipment:Conveyor drives, crane hoists, and automated storage systems require reducers with high starting torque and reversing capability. Intralogistics deployments in Germany and the United States specify modular platforms with documented MTBF data for just-in-sequence delivery compliance.
- Machine Tools:Spindle drives and axis positioning demand precision backlash control and thermal stability. Japanese and Swiss machining center manufacturers source reducers with sub-arcminute positioning accuracy for five-axis contouring applications.
- Packaging Machinery:Intermittent motion control and washdown compatibility drive specification. Food-grade NSF H1 lubricant compatibility is non-negotiable for North American poultry and dairy processing lines.
- Textile Machines:High-speed winding and drawing frames require compact axial envelope. Indian textile corridors specify needle bearing configurations for constrained mounting dimensions.
- Printing Equipment:Registration accuracy and vibration isolation dominate. Web-fed press manufacturers in Italy and Japan prioritize helical profiles for smooth torque transmission.
Material handling equipment generates the largest installed base while machine tools deliver the steepest expansion trajectory in precision manufacturing corridors.
End User Industry:
Supply concentration in alloy steel forging and heat treatment creates tiered access barriers, with integrated manufacturers capturing renewable energy and mining contracts while fragmented assemblers serve agricultural replacement markets.
- Construction Equipment:Excavator swing drives, crane winches, and concrete mixer transmissions endure shock loading and contamination. German and Japanese OEMs demand roller bearing configurations with validated service life claims under AGMA 2001 calculations.
- Renewable Energy Systems:Wind turbine yaw and pitch drives require 20-year design life with minimal maintenance access. Nacelle integrators in Denmark and Spain specify planetary reducers with condition monitoring integration for offshore deployment.
- Manufacturing Plants:General industrial automation spans conveyor systems, robotic arms, and auxiliary equipment. Automotive tier-one suppliers in Stuttgart and Wolfsburg corridors compress switching cycles through multi-year framework agreements with penalty clauses.
- Mining Operations:Crusher drives, conveyor systems, and hoist mechanisms operate in abrasive environments. Australian iron ore and copper producers pilot additive-manufactured gear blanks for weight reduction in mobile equipment.
- Agricultural Machinery:Combine harvesters, tractor implements, and irrigation systems prioritize cost over precision. Indian and Brazilian OEMs source plain bearing reducers through distributed assembly nodes serving domestic demand.
Manufacturing plants anchor volume demand while renewable energy systems climb the fastest in premium specification penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German intralogistics OEMs deploy modular reducer platforms for automated warehouse density, while Australian mining operators pilot additive-manufactured gear blanks for mobile equipment weight reduction. This consumption-mix differential separates precision-engineered European demand from resource-sector volume plays elsewhere.
Germany
Automotive tier-one suppliers in Stuttgart and Wolfsburg corridors compress switching cycles through multi-year framework agreements with penalty clauses for non-conformance. CE marking under EU Machinery Directive 2006/42/EC mandates documented risk assessment that favors certified precision reducers. Intralogistics clusters in Bavaria and Baden-Württemberg anchor modular platform adoption for just-in-sequence delivery compliance.
United States
EPA lubricant containment mandates under 40 CFR reshape enclosure seal designs for chemical processing and wastewater treatment facilities. OSHA guarding requirements shape maintenance protocols and enclosure architectures across industrial corridors. Food-grade NSF H1 lubricant compatibility dominates poultry and dairy processing lines in the Midwest and Southeast.
Australia
Iron ore and copper producers in Western Australia pilot topology-optimized gear blanks for weight reduction in mobile crushing and conveying equipment. The country's national mining safety regulator enforces equipment certification standards that validate service life claims under shock-load duty cycles. Perth-based equipment integrators source roller bearing configurations for remote site reliability.
India
PLI scheme incentives for industrial automation equipment create localized assembly opportunities for domestic material handling and textile machinery demand. The Bureau of Indian Standards enforces mechanical equipment safety protocols that elevate certification requirements for imported reducers. Textile corridors in Gujarat and Tamil Nadu specify needle bearing configurations for constrained mounting dimensions.
Japan
Machine tool manufacturers source reducers with sub-arcminute positioning accuracy for five-axis contouring applications. METI efficiency standards for industrial equipment drive specification of documented loss coefficients in precision manufacturing. Nagoya and Osaka industrial clusters prioritize compact axial envelope for high-speed winding and drawing frame integration.
Parallel-Shaft Gear Reducer Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence in gear grinding and heat-treatment capacity bifurcating competitive positions. Integrated manufacturers capture renewable energy and mining contracts through captive finishing lines, while fragmented assemblers serve agricultural replacement markets via outsourced machining. Two strategic archetypes dominate: modular platform architects serving intralogistics integrators, and precision-engineered specialists qualifying for automotive supplier frameworks. Competitive moves concentrate on backward integration into heat-treatment capacity and geographic expansion through distributed assembly nodes.
Among Germany-based precision-engineered specialists, Siemens AG and Bonfiglioli occupy positions representing integrated manufacturing archetypes with captive production capabilities. Watt Drive Antriebstechnik GmbH exemplifies the modular platform specialist tier serving regional industrial automation demand. Japanese industrial conglomerates Sumitomo Heavy Industries and Mitsubishi Electric anchor the Asia-Pacific supply base with diversified power transmission portfolios. These groupings reflect geographic clustering rather than explicit market share claims.
| Leading Market Players |
|---|
| Sumitomo Heavy Industries |
| Siemens AG |
| Mitsubishi Electric |
| NORD Drivesystems |
| Bonfiglioli |
| Watt Drive Antriebstechnik GmbH |
| Baldor |
| Rossi |
| Tsubakimoto Chain |
| Others |
Pricing and Supply Chain Analysis
Captive heat-treatment capacity utilization above eighty percent in German and Japanese integrated manufacturing clusters compresses cost floors for precision helical units while forcing mid-tier competitors toward outsourced finishing dependencies that erode margin buffers. This scale asymmetry concentrates pricing power among vertically integrated producers serving automotive tier-one frameworks while fragmenting competitive positioning across outsourced machining tiers.
Pricing Analysis
Aftermarket service contracts and spare parts revenue anchor lifetime value capture for integrated manufacturers, with three-tier pricing structure across premium certified, standard industrial, and economy replacement tiers differentiating ISO 6336-validated units from uncertified alternatives. Price differentiation hinges on AGMA 2001 calculation documentation and captive heat-treatment verification. Pricing pressure stems from alloy steel input volatility compressing mid-tier margin structures. Automotive OEM procurement teams exhibit lowest price sensitivity due to just-in-sequence penalty clauses, while agricultural machinery distributors in India and Brazil demonstrate highest sensitivity favoring plain bearing economy tiers.
Supply Chain Analysis
Strait of Malacca transit lanes and Rhine River barge networks underpin raw material flows for case-hardening grade steel moving from German and Japanese primary mills to Southeast Asian assembly nodes. Supply concentration centers on Germany, Japan, and China for precision forging capacity, with India emerging as secondary hub under PLI scheme incentives. Alloy steel billets, roller bearing assemblies, and rare-earth magnetic materials constitute critical input dependencies. Single-source vulnerability in specialized gear grinding equipment exposes mid-tier producers to eighteen-month lead time extensions. Distribution runs through OEM direct procurement for automotive and renewable energy contracts, with aftermarket channels serving replacement demand through regional distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Capital equipment replacement cycles in manufacturing and mining signal cyclical recovery momentum, with ISO 6336 recertification deadlines forcing upgrade decisions across European installed bases.
For Market Incumbents: Secure captive heat-treatment capacity expansions in Bavaria and Baden-Württemberg corridors to defend margin position against additive manufacturing disruptors piloting topology-optimized gear blanks. Anchor multi-year framework agreements with Stuttgart automotive tier-ones through documented MTBF validation. Prioritize backward integration into alloy steel long-term supply agreements to buffer primary mill price volatility. For New Entrants and Emerging Players: CE marking fast-track certification under EU Machinery Directive 2006/42/EC unlocks supplier qualification for German intralogistics OEMs seeking modular platform alternatives. Target Indian textile machinery corridors in Gujarat and Tamil Nadu where needle bearing configurations face limited certified competition. Pursue distributed assembly node partnerships with domestic material handling integrators to bypass integrated manufacturer lead time advantages. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision-engineered specialists with ISO 6336 calculation expertise and captive finishing lines over fragmented outsourced machining assemblers. Five-to-ten year viability hinges on VFD integration capabilities preventing fixed-speed architecture obsolescence. Monitor DOE efficiency regulation drafting as inflection signal for premium helical unit specification acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat-Treatment | Captive nitriding and carburizing lines compress lead times for AGMA 2001-certified units serving mining OEMs. |
| Modular Platform Architecture Expansion | Standardized housing interfaces reduce engineering-to-order cycles for German intralogistics integrators by forty percent. |
| Condition Monitoring Integration | IoT-enabled vibration sensors enable predictive maintenance contracts unbundling hardware from lifecycle revenue. |
| Localized Assembly Node Deployment | Regional finishing capacity in Indian manufacturing corridors bypasses integrated manufacturer logistics premiums. |
| Additive Manufacturing Pilot Programs | Selective laser melting of topology-optimized blanks fragments conventional forging dependencies for low-volume custom ratios. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with maintenance directors at German automotive plants, OEM procurement teams in Stuttgart and Wolfsburg corridors, aftermarket service heads at mining operators in Western Australia, and plant engineers at Indian textile machinery manufacturers; alongside secondary validation through customs trade databases, SEC 10-K filings of listed power transmission equipment manufacturers, ISO certification registries, and AGMA technical committee documentation. Bottom-up unit demand modeling triangulated against top-down industrial automation capex projections.
Across the projection horizon, analytical frameworks segmented demand by gear configuration type, bearing technology tier, end-use application intensity, and regional regulatory cluster. CAGRs derived from weighted average of historical replacement cycle analysis and forward industrial production indices. Forecast inputs incorporated alloy steel price trajectory assumptions and anticipated DOE efficiency regulation implementation timelines.
Decision-makers should treat outputs as directional under base assumptions of sustained manufacturing automation investment and stable alloy steel supply; material deviation in commodity input costs or regulatory acceleration would warrant model refresh. Practitioners should keep alternative scenarios live as VFD substitution rates and additive manufacturing cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Australia Conveyor Maintenance Market
Construction Equipment and Machinery
Construction Machinery Telematics Market
Construction Equipment and Machinery
Road Construction Machinery Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Crane Motors Market
Construction Equipment and Machinery
Brick Making Machines Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Spraying and Plastering Machine Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
Global Woodworking Machinery Market
Construction Equipment and Machinery
Used Machine Tools Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market