
 Automatic Nesting CNC Router Market | 2026-2036
Automatic Nesting CNC Router Market Size, Share, and Industry Trends Forecast 2026-2036
Automatic Nesting CNC Router Market Analytics
The EU Machinery Directive is expanding compliance burdens for non-European OEMs seeking CE marking, which raises engineering and certification costs for entry into European woodworking automation. BIESSE Group leverages its Italian manufacturing base and established certification pathways to sustain dominant positioning across European furniture factories. Style CNC competes aggressively on cost-engineered portable router configurations for mid-scale Asian workshops. Blue Elephant CNC Machine anchors its growth on laser-cutting technology integration within fixed-router platforms for composite material processing.
An automatic nesting CNC router is a computer-numerical-control machine that optimizes cutting layouts through algorithmic part nesting to maximize material yield from sheet goods, typically operating with spindle speeds exceeding 18,000 RPM and positional accuracies within 0.05 mm for panel processing applications. Fixed router systems dominate margin pools in high-volume furniture manufacturing where throughput and repeatability justify capital intensity, while portable router demand accelerates in custom marine and aerospace prototyping environments where shop-floor flexibility commands premium pricing. CNC machining as a technology category leads installed base volumes, though laser cutting integration within nesting workflows is displacing mechanical routing for aluminum and composite applications in automotive supplier networks.
The EPA governs airborne particulate emissions from wood-processing facilities in the United States, which compels router OEMs to engineer integrated dust-collection interfaces and filtration specifications into machine designs. China's MIIT enforces GB standards for industrial equipment interoperability that shape control architecture and data-export capabilities for machines sold into domestic smart-factory programs. Stakeholders must monitor how evolving machinery safety standards across multiple jurisdictions will reshape R&D allocation and aftermarket service requirements for nesting automation portfolios.
Market Dynamics
Algorithmic nesting optimization is compressing material yield thresholds across panel processing operations, forcing OEMs to engineer control architectures that integrate real-time sheet optimization with legacy shop-floor management systems.
Growth Catalysts
- EU Machinery Directive compliance pathways:CE marking requirements under the EU Machinery Directive are tightening safety and interoperability standards, compelling European furniture manufacturers to upgrade toward certified automated nesting platforms.
- Marine prototyping flexibility demand:Custom marine and aerospace prototyping environments are commanding portable router configurations that deliver shop-floor mobility without sacrificing positional accuracy.
- China smart-factory interoperability mandates:MIIT enforcement of GB standards for industrial equipment interoperability is accelerating control-system upgrades in domestic panel processing clusters.
Market Restraints
- Control architecture input cost volatility:Proprietary motion control hardware and industrial PC components concentrate supply risk with German and Japanese component suppliers, exposing OEM margins to semiconductor allocation constraints.
- Mechanical routing substitution pressure:Laser cutting integration within nesting workflows is displacing spindle-based routing for aluminum and composite applications in automotive supplier networks.
- CE marking engineering friction:Non-European OEMs face elevated certification costs and extended validation timelines to satisfy EU Machinery Directive safety documentation requirements.
Strategic Opportunities
- Composite material processing convergence:Laser-cutting technology integration within fixed-router platforms is opening margin pools in carbon-fiber and advanced polymer panel applications previously served by dedicated cutting systems.
- EPA emission control aftermarket:EPA particulate emission standards for wood-processing facilities are creating retrofit demand for integrated dust-collection interfaces and filtration specifications.
- Mid-scale Asian workshop portability gap:Cost-engineered portable router configurations address underpenetrated mid-scale workshops in Vietnam and Indonesia seeking automation without fixed-capital commitment.
Industry Challenges
- CNC programming and nesting algorithm talent scarcity:Furniture manufacturers struggle to recruit operators capable of optimizing cutting layouts through algorithmic part nesting while managing spindle parameter calibration.
- Legacy shop-floor integration complexity:Fixed-router system deployments require extensive MES and ERP interface engineering to synchronize real-time sheet optimization with existing production scheduling infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automatic Nesting CNC Router Market |
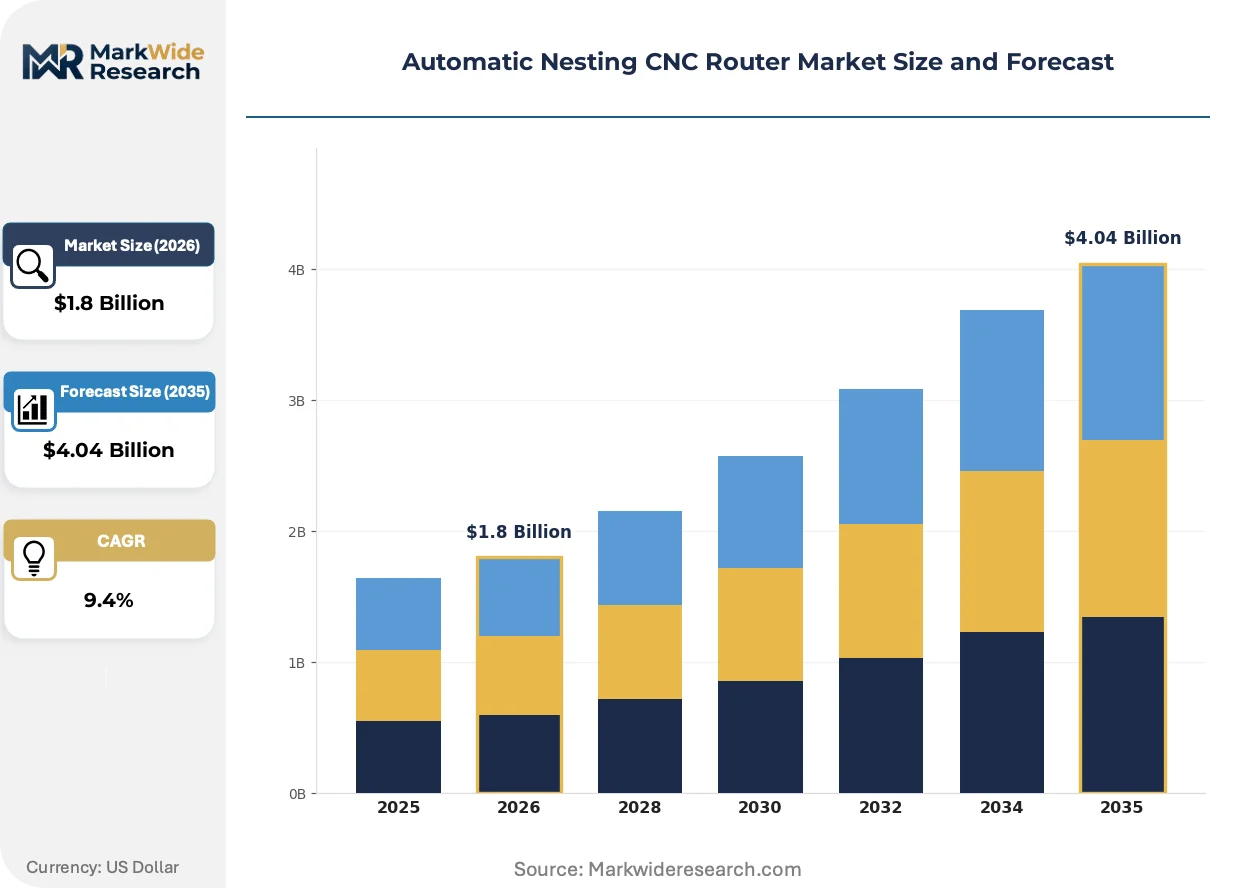
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Router, Fixed Router, Handheld Router, Table Router Technology: Laser Cutting, Plasma Cutting, Waterjet Cutting, CNC Machining End User: Furniture Manufacturers, Aerospace, Automotive, Marine Material: Wood, Composite, Aluminum, Plastic |
| Companies Covered | Style CNC, Blue Elephant CNC Machine, BIESSE Group, Jinan Forsun CNC Machinery Co. Ltd, Wood Tech, Qingdao Aosguo CNC Router Co. Ltd, Qingdao Yingsi Machinery Co. Ltd, Jinan iGolden CNC Equipment Co. Ltd, Jinan Eagle CNC Machinery Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automatic Nesting CNC Router Market Evolving Landscape
Control system convergence with industrial IoT architectures is actively rewiring how nesting automation interfaces with upstream design software and downstream material handling equipment.
Hybrid laser-mechanical routing platforms are rewriting competitive specifications in composite panel processing. Aerospace tier-one suppliers in Germany and the United States are adopting these configurations at accelerated procurement cycles. The technology is compressing capital equipment footprints by eliminating separate cutting and routing stations.
EPA enforcement of airborne particulate standards is tightening dust-collection integration mandates for wood-processing facilities. Router OEMs now engineer filtration specifications as standard machine interfaces rather than aftermarket attachments. Furniture manufacturers in the United States face retrofit deadlines that compress upgrade decision timelines.
Service unbundling from equipment sales is disrupting traditional distribution economics. Aftermarket maintenance contracts and remote diagnostic subscriptions are displacing bundled warranty structures in European and North American markets. German furniture factories are pioneering outcome-based service agreements that tie vendor compensation to machine uptime guarantees.
Automatic Nesting CNC Router Market Segmentation
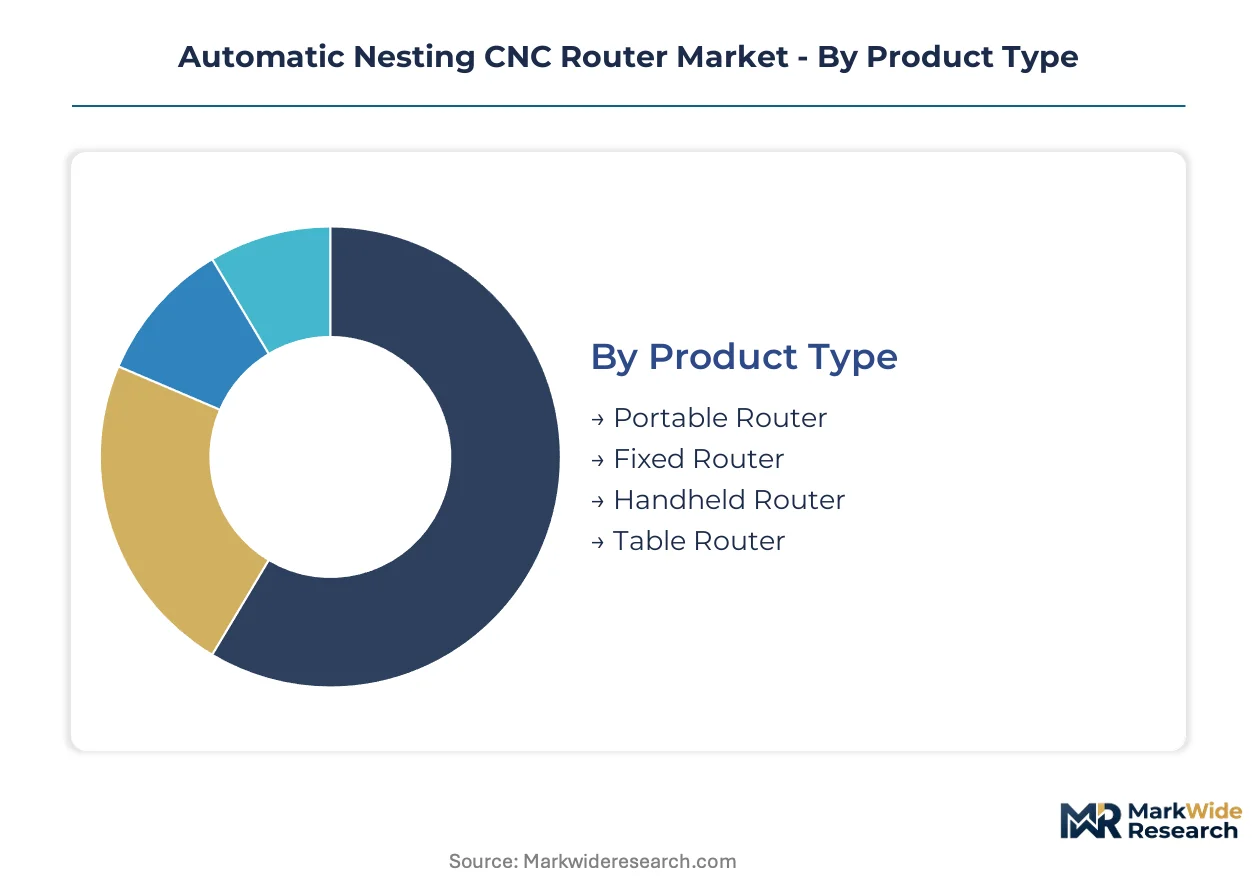
Segmentation in automatic nesting CNC routers reveals how capital intensity, material compatibility, and regulatory exposure split demand across divergent buyer profiles. Product configuration and technology choice determine whether vendors capture premium-margin fixed installations or high-volume portable deployments.
Product Type:
Fixed router systems dominate revenue pools through high-throughput furniture manufacturing, while portable configurations command premium pricing in flexibility-dependent environments.
- Fixed Router:Stationary gantry systems with enclosed cutting beds deliver positional accuracies within 0.05 mm for continuous panel processing. German and Chinese furniture factories favor these configurations for material yield optimization at scale, though CE marking compliance raises engineering costs for non-European OEMs.
- Portable Router:Mobile gantry designs enable repositioning across shop floors without sacrificing spindle performance above 18,000 RPM. Custom marine prototyping workshops in the United States and aerospace prototyping clusters pay premiums for this flexibility where fixed-capital commitment is prohibitive.
- Handheld Router:Operator-guided units serve edge-finishing and small-batch customization in mid-scale Asian workshops.
- Table Router:Bench-mounted systems target educational institutions and entry-level woodworking operations with constrained floor space.
Today's leader: Fixed Router. Tomorrow's challenger: Portable Router.
Technology:
Mechanical routing retains installed base dominance, yet thermal cutting methods are capturing composite material applications through speed advantages.
- CNC Machining:Spindle-based mechanical routing with algorithmic nesting optimization remains the reference standard for wood panel processing. Furniture manufacturers across North America and Europe specify these systems for proven interoperability with legacy shop-floor management infrastructure.
- Laser Cutting:CO2 and fiber laser integration within nesting workflows eliminates tooling changeover for aluminum and carbon-fiber panels. Automotive supplier networks in Germany and the United States are accelerating procurement of hybrid laser-mechanical platforms.
- Plasma Cutting:High-velocity ionized gas systems address thick-gauge metal applications outside traditional router sweet spots.
- Waterjet Cutting:Abrasive jet processing serves heat-sensitive advanced polymer panels in aerospace tier-one supply chains.
CNC Machining anchors current procurement volumes. Laser Cutting is climbing the fastest among emerging technology configurations.
End User:
End-use segmentation tracks how material waste reduction mandates and labor cost pressures concentrate automation investment.
- Furniture Manufacturers:Large-format panel processors drive fixed-router demand through algorithmic nesting for material yield maximization. North American and European factories face compressed upgrade timelines from EPA emission enforcement and EU Machinery Directive compliance pathways.
- Aerospace:Tier-one suppliers adopt hybrid laser-mechanical platforms for carbon-fiber and advanced polymer processing. German and United States prototyping clusters prioritize portable configurations for shop-floor reconfiguration flexibility.
- Automotive:Supplier networks displace mechanical routing with laser cutting integration for aluminum panel applications.
- Marine:Custom boat builders command portable router premiums where one-off hull geometries defy fixed-system programming.
Furniture Manufacturers represent the deepest installed base. Aerospace presents the steepest expansion trajectory for premium system configurations.
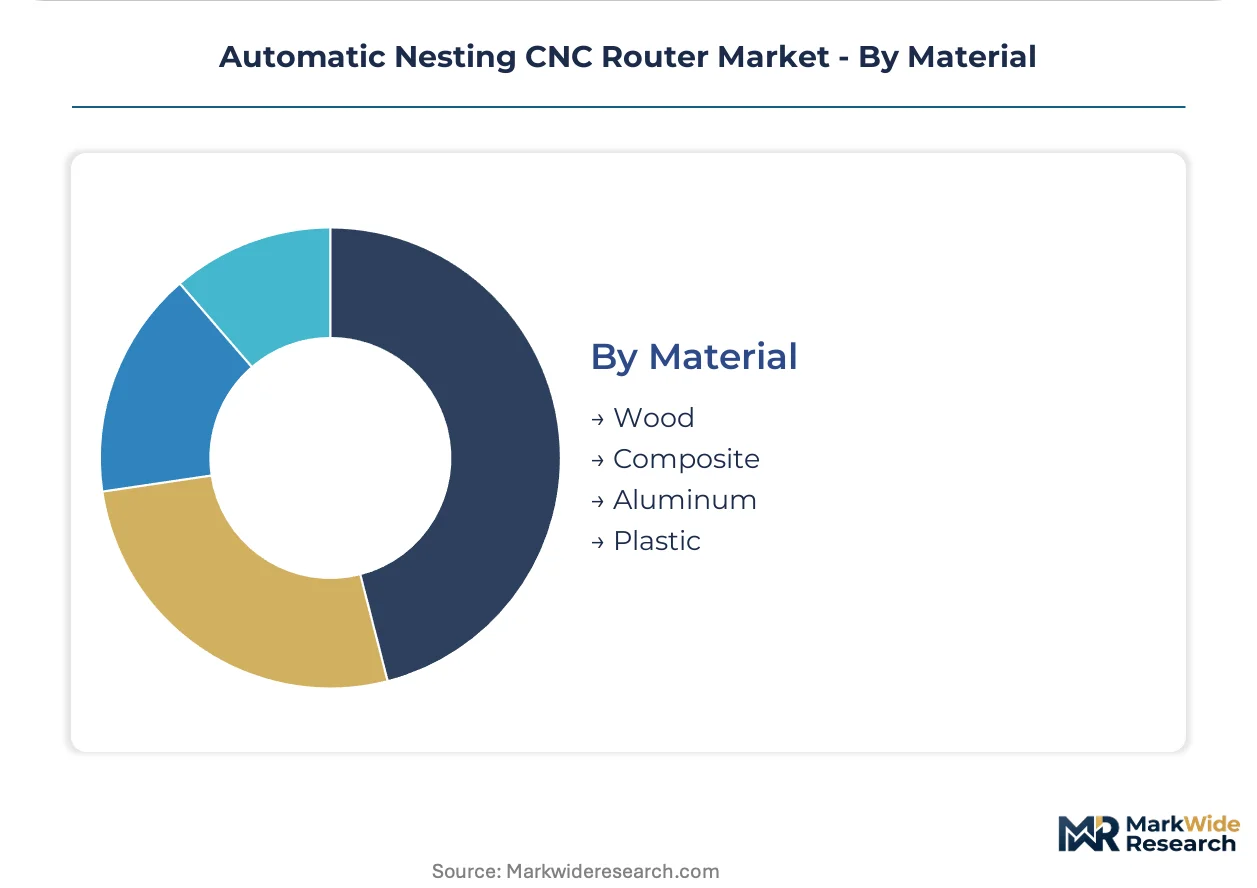
Material:
Material compatibility determines spindle parameter calibration, dust-collection integration mandates, and cutting technology substitution risk.
- Wood:Softwood and hardwood panel processing generates the largest installed base volume. EPA particulate emission standards compel integrated dust-collection interfaces as standard machine specifications rather than aftermarket attachments.
- Composite:Carbon-fiber and glass-reinforced polymer panels are opening margin pools for laser-cutting technology integration within fixed-router platforms. Aerospace and automotive supplier networks drive specification convergence here.
- Aluminum:Non-ferrous sheet applications face displacement pressure from laser cutting in automotive prototyping.
- Plastic:Thermoplastic and thermoset panels serve marine and industrial packaging applications with moderate automation penetration.
Wood commands current procurement volume. Composite is gaining share fastest as multi-material processing requirements reshape buyer specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled CNC programming talent concentrates in German industrial clusters, Chinese smart-factory hubs, and American aerospace prototyping centers, anchoring regional demand patterns for automatic nesting CNC router systems.
Germany
Furniture automation investments and aerospace tier-one supplier procurement drive fixed-router demand. CE marking requirements under the EU Machinery Directive compel engineering upgrades for safety documentation and interoperability certification. The Stuttgart and Munich industrial corridors host dense concentrations of panel processing facilities adopting hybrid laser-mechanical platforms.
United States
Custom marine prototyping workshops and aerospace prototyping clusters command portable router premiums for shop-floor flexibility. EPA enforcement of airborne particulate emission standards tightens dust-collection integration mandates for wood-processing facilities. The Pacific Northwest and Great Lakes regions concentrate furniture manufacturers facing compressed retrofit decision timelines.
China
Large-format panel processing clusters in domestic smart-factory programs scale automated nesting investments to reduce material waste. MIIT enforcement of GB standards for industrial equipment interoperability shapes control architecture and data-export capabilities. The Yangtze River Delta and Pearl River Delta manufacturing belts dominate procurement volumes for cost-engineered configurations.
Italy
Established woodworking machinery OEMs leverage domestic manufacturing bases and certification pathways to sustain positioning across European furniture factories. EU Machinery Directive compliance pathways raise engineering costs for non-European competitors seeking CE marking. The Emilia-Romagna and Veneto regions maintain dense supplier networks for high-throughput fixed-router deployments.
Japan
Precision component suppliers and automotive prototyping networks accelerate procurement of laser-cutting integration within nesting workflows for aluminum and composite applications. METI industrial standards shape motion control hardware specifications and semiconductor allocation protocols. The Nagoya and Osaka industrial zones concentrate tier-one automotive supplier demand for multi-material processing capabilities.
Automatic Nesting CNC Router Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered market positions. The vendor base organizes around three strategic archetypes: European heritage manufacturers with established certification pathways, Chinese cost-engineered fabricators serving mid-scale Asian workshops, and hybrid technology integrators combining laser and mechanical routing capabilities. Competitive moves concentrate on geographic expansion into underpenetrated Southeast Asian markets and portfolio diversification toward composite material processing configurations.
Among Italian heritage manufacturers, BIESSE Group anchors the established certification pathway archetype for European furniture automation. Chinese fabricators including Style CNC and Jinan Forsun CNC Machinery Co. Ltd occupy positions within the cost-engineered portable router tier addressing mid-scale workshop demand across Vietnam and Indonesia. Blue Elephant CNC Machine exemplifies the hybrid technology integrator archetype, representing vendors converging laser-cutting capabilities with fixed-router platforms for carbon-fiber and advanced polymer applications.
| Leading Market Players |
|---|
| Style CNC |
| Blue Elephant CNC Machine |
| BIESSE Group |
| Jinan Forsun CNC Machinery Co. Ltd |
| Wood Tech |
| Qingdao Aosguo CNC Router Co. Ltd |
| Qingdao Yingsi Machinery Co. Ltd |
| Jinan iGolden CNC Equipment Co. Ltd |
| Jinan Eagle CNC Machinery Co. Ltd |
| Others |
Value Network & Pricing Analysis
Hybrid laser-mechanical routing platform adoption is compressing capital equipment footprints while simultaneously redistributing cost economics toward integrated control architectures and concentrating supply leverage among German and Japanese motion control specialists. This technology transition forces buyers to absorb premium component sourcing for multi-material processing capabilities while OEMs face margin compression from semiconductor allocation constraints.
Pricing Analysis
The bundled-vs-unbundled service split is rewriting revenue recognition across European and North American markets. Three-tier pricing structure across premium, standard, and economy levels separates CE-certified fixed-router installations from portable configurations and handheld units. Price differentiation rests on certification grade and after-sales service bundling. Cost compression in mid-scale Asian workshop tiers is intensifying because Chinese fabricators compete aggressively on cost-engineered portable configurations. Mid-scale Vietnamese and Indonesian workshops exhibit highest price sensitivity; German aerospace tier-one suppliers show least.
Supply Chain Analysis
Dual-sourcing requirements for motion control hardware and industrial PC components are mandating multi-supplier qualification across German and Japanese semiconductor specialists. Proprietary control architecture sourcing draws from Germany, Japan, and Taiwan for precision motion components. Linear guide systems, servo motors, and CNC controllers anchor bill-of-materials exposure. Single-source vulnerability concentrates in German motion control suppliers facing semiconductor allocation constraints. Distribution runs through authorized dealer networks and direct OEM sales channels serving furniture manufacturing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Machinery Directive CE marking pathways and EPA particulate emission enforcement are compressing upgrade decision timelines and forcing capital redeployment toward certified automated nesting platforms.
For Market Incumbents: Anchor defensive positioning through backward integration into control architecture production and captive supply of motion control components to offset German and Japanese supplier concentration risk. Deepen certification investment in CE marking pathways to raise engineering friction for non-European OEM challengers. Laser cutting substitution pressure in automotive supplier networks demands hybrid technology portfolio expansion. For New Entrants and Emerging Players: Mid-scale Asian workshop operators in Vietnam and Indonesia represent the most penetrable buyer archetype currently underserved by established European heritage manufacturers. Portable router configurations with cost-engineered control architectures offer white-space entry without competing against BIESSE Group's fixed-router dominance. Direct distribution partnerships with regional machinery dealers provide the cleanest go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among Chinese cost-engineered fabricators lacking CE marking certification but possessing established portable router production capabilities. Long-term viability across the analysis window favors hybrid technology integrators converging laser and mechanical routing for composite material processing. Watch aerospace tier-one supplier procurement acceleration as the inflection signal indicating premium configuration demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Certification Investment | Unlocks European furniture factory access and raises rival engineering costs. |
| Hybrid Laser-Mechanical Platform Launch | Captures aerospace carbon-fiber processing demand from dedicated cutting systems. |
| Backward Integration into Motion Control | Reduces exposure to German and Japanese semiconductor allocation constraints. |
| Portable Router Cost Engineering | Addresses Vietnamese and Indonesian workshop automation gaps without fixed-capital commitment. |
| Aftermarket Service Unbundling | Transforms warranty economics into recurring revenue through remote diagnostic subscriptions. |
Research Methodology
Multiple input streams — structured interviews with plant engineers and OEM procurement teams, regulatory filing analysis, and trade flow reconciliation — were reconciled to construct market estimates. Primary fieldwork captured perspectives from maintenance directors at furniture manufacturing facilities, aftermarket service heads at European distributors, and control systems engineers at hybrid technology integrators. Secondary validation drew from EU Machinery Directive documentation, EPA enforcement records, MIIT GB standard publications, and customs data for industrial equipment imports. Bottom-up installation base enumeration and top-down expenditure flow analysis were triangulated against manufacturer shipment disclosures.
Data-stream reconciliation across product configuration, technology type, end-use industry, and material compatibility dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic drivers and regulatory enforcement timelines. Forecast inputs incorporated smart-factory interoperability mandate acceleration in China, EPA retrofit deadline compression in the United States, and aerospace prototyping cluster expansion in Germany.
Underlying measurement precision varies by segment; fixed-router furniture manufacturing deployments carry tighter precision than emerging portable aerospace prototyping applications. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and semiconductor supply normalization. Deviation in EU Machinery Directive implementation timelines or Chinese smart-factory program acceleration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Metalworking Machinery Market
Construction Equipment and Machinery
Latin America Injection Molding Machines Market
Construction Equipment and Machinery
Woodworking Machines Market
Construction Equipment and Machinery
Robotic Mill Liner Market
Construction Equipment and Machinery
Friction Stir Welding Equipment Market
Construction Equipment and Machinery
Australia Construction Machinery Market
Construction Equipment and Machinery
Global Hydraulic Demolition Machine and Breaker Market
Construction Equipment and Machinery
Grouting Machine Market
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Double Decker Roll Forming Machine Market
Construction Equipment and Machinery
Plastic Injection Molding Machines Market
Construction Equipment and Machinery
Europe Metal Fabrication Equipment Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
Industrial Machinery Market
Construction Equipment and Machinery
Concrete Floor Grinding Machine Market
Construction Equipment and Machinery
Global Electric Presses Market