
 Industrial Machinery Market | 2026-2036
Industrial Machinery Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Machinery Market Outlook
Premium-tier specifications with integrated telematics and predictive diagnostics is rotating demand away from baseline equipment across construction and mining fleets. Caterpillar Inc. leverages its captive dealer network to control aftermarket parts flows. Siemens anchors European demand through its digital twin integration in CNC machining platforms. Komatsu Ltd. differentiates via autonomous haulage systems deployed across Australian iron ore operations.
Industrial machinery comprises powered mechanical equipment designed to perform specific manufacturing, construction, material processing, or energy extraction tasks, typically operating at pressures from 150 to 10,000 psi and tolerances measured in micrometers for precision applications. These systems convert electrical, hydraulic, or thermal energy into mechanical work to shape, move, or process raw materials into finished components or extracted resources. Construction equipment and material handling categories command the largest installed base volumes, while additive manufacturing represents the fastest-expanding technology segment as aerospace fabricators adopt metal deposition for complex turbine geometries. Machine tools retain the deepest margin pools due to long replacement cycles and proprietary control software lock-in among OEMs and precision fabricators.
EPA Tier 4 Final emissions standards and OSHA machine guarding regulations in the United States compel engine redesigns and safety system retrofits, while REACH chemical restrictions in Europe constrain hydraulic fluid formulations and surface coating chemistries. The EU Machinery Directive's conformity assessment requirements shape market access timelines for non-European exporters. Stakeholders must monitor convergence between carbon border adjustment mechanisms and embedded emissions tracking in heavy equipment supply chains to anticipate compliance cost shifts.
Market Dynamics
Telematics integration and predictive maintenance protocols are compressing replacement cycles across construction and mining fleets, forcing capital deployment toward connected equipment platforms rather than standalone mechanical assets.
Growth Catalysts
- EPA Tier 4 Final:Off-road diesel engine mandates in the United States accelerate fleet turnover as contractors face compliance deadlines for non-road mobile machinery.
- Precision manufacturing corridors:Stuttgart and Munich anchor European demand for CNC machining platforms with embedded digital twin capabilities.
- Autonomous haulage:Australian iron ore operations deploy self-driving truck fleets that require synchronized loading equipment and centralized fleet management infrastructure.
Market Restraints
- Specialized steel alloys:High-grade bearing steel and chromium-molybdenum formulations face price volatility tied to nickel and molybdenum concentrate markets.
- Hydraulic fluid chemistry:REACH restrictions in Europe constrain formulation options for biodegradable hydraulic fluids, limiting supplier pools.
- Control software lock-in:Proprietary CNC operating systems from incumbent OEMs create switching costs that delay technology refresh cycles.
Strategic Opportunities
- Metal deposition aerospace:Additive manufacturing for complex turbine geometries opens service contracts with engine fabricators seeking weight reduction.
- Carbon border adjustments:Embedded emissions tracking in heavy equipment supply chains creates compliance service revenue for machinery vendors with lifecycle monitoring tools.
- Dealer network digitization:Captive aftermarket parts flows migrate to predictive inventory systems that anticipate failure modes before downtime occurs.
Industry Challenges
- Mechatronics talent scarcity:Integration of hydraulic, electrical, and software systems requires cross-trained technicians that vocational pipelines struggle to produce at scale.
- EU Machinery Directive timelines:Conformity assessment procedures for non-European exporters extend market access lead times by six to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Machinery Market |
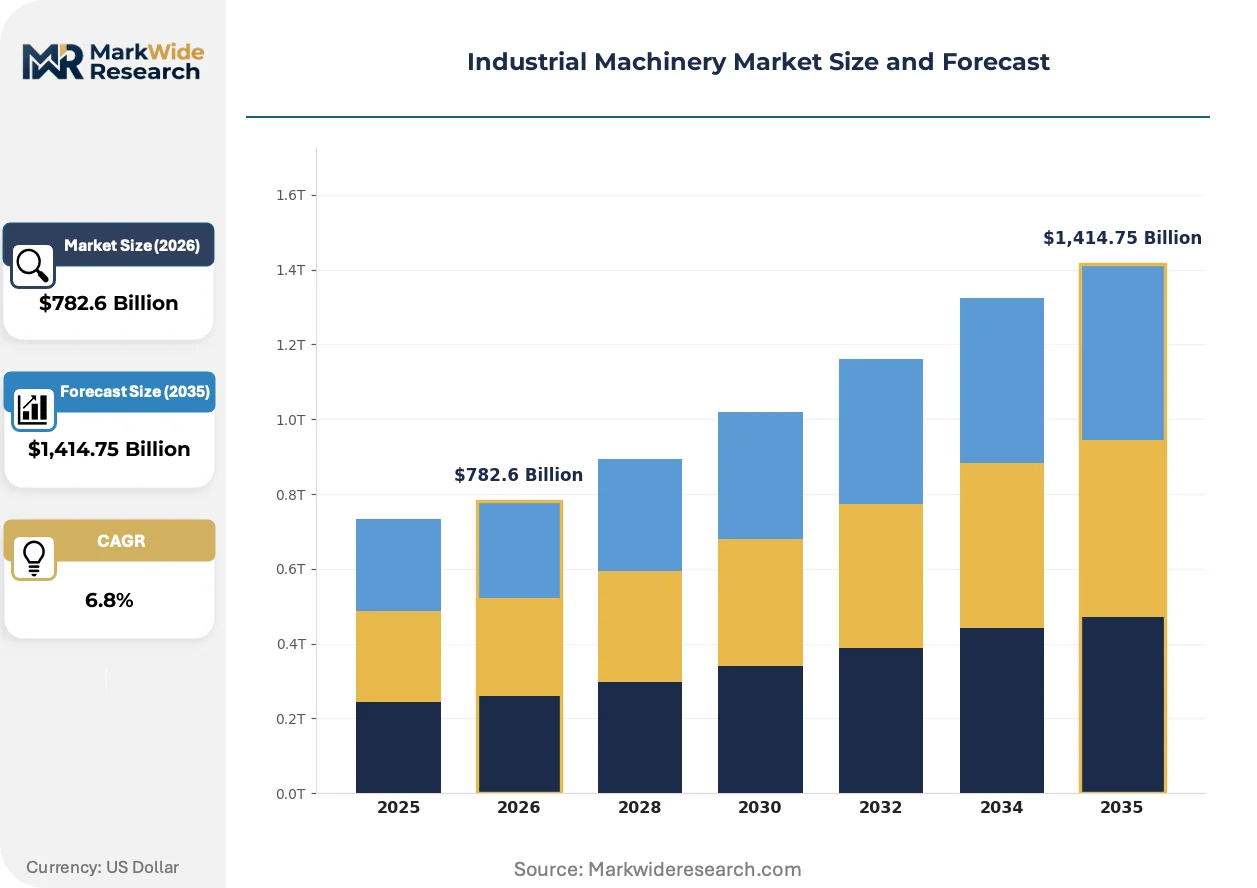
| Market Size in 2026 | $782.6 Billion |
| Market Size in 2035 | $1,414.75 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Construction Equipment, Material Handling, Machine Tools, Agriculture Equipment Technology: Automation, Robotics, CNC Machining, Additive Manufacturing Application: Manufacturing, Construction, Mining, Energy End User: OEMs, Contractors, Fabricators, Aftermarket Providers |
| Companies Covered | Caterpillar Inc., Deere & Company, General Electric Company, Siemens, Komatsu Ltd., Rockwell Automation, Honeywell International, Hitachi, Cummins, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Machinery Market Strategic Shifts
Equipment intelligence layers are separating hardware margins from software and data service revenue, restructuring how OEMs capture lifetime value from installed bases.
Digital twin integration is fragmenting traditional CNC machining procurement. Aerospace and automotive fabricators in Germany and Japan adopt virtual commissioning platforms that simulate tool paths before physical production. This compression of setup cycles is displacing conventional trial-and-error programming methods and reducing scrap rates in precision applications.
REACH chemical restrictions in Europe are forcing hydraulic fluid reformulation across construction equipment categories. The regulation bans specific anti-wear additives and requires biodegradable base stocks. Mining contractors in Scandinavia and German municipal fleets face accelerated maintenance intervals as new chemistries stabilize, creating aftermarket service demand.
After-sales service unbundling is reshaping buyer-supplier relationships in North American construction markets. Large fleet operators negotiate direct telemetry access rather than dealer-mediated maintenance contracts. Equipment lessors and rental houses in Texas and Alberta now demand API-level data portability to integrate machinery health signals into their own asset management platforms.
Industrial Machinery Market Segmentation
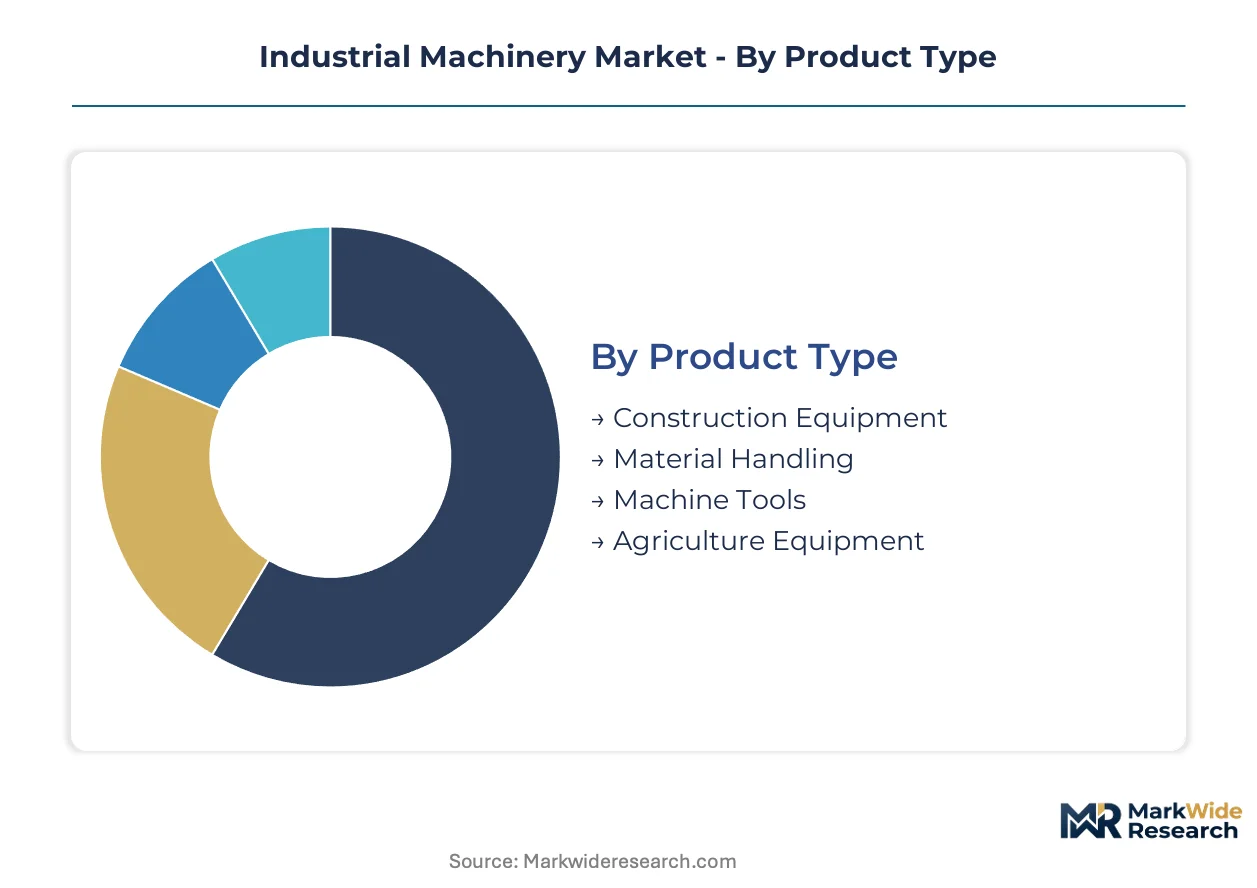
Segmentation in industrial machinery reveals where capital allocation concentrates and which technology layers command pricing power. Equipment buyers prioritize integrated platforms over standalone mechanical assets, reshaping how vendors structure product portfolios.
Product Type:
Substitution pressure varies sharply across equipment categories, with digital-integrated platforms displacing purely mechanical alternatives in fleet procurement decisions.
- Construction Equipment:Heavy earthmoving and lifting systems operating at 150-10,000 psi hydraulic pressures. Australian iron ore contractors and Chilean mining operators accelerate replacement cycles for EPA Tier 4 Final compliance. Telematics-integrated excavators and dozers command premium positioning over baseline mechanical configurations.
- Machine Tools:Precision CNC platforms with micrometer-level tolerances and proprietary control software architectures. Stuttgart and Munich fabricators anchor European demand through digital twin integration that compresses setup cycles and reduces scrap rates.
- Material Handling:Conveyors, cranes, and automated storage systems for logistics and manufacturing floors.
- Agriculture Equipment:Tractors, harvesters, and planting systems with increasing precision agriculture sensor integration.
Construction Equipment retains volume leadership; Machine Tools holds the steepest expansion curve.
Technology:
Cost tier stratification separates premium-integrated systems from economy mechanical alternatives, with mid-tier vendors struggling to defend positioning.
- CNC Machining:Computer-numerical control platforms with multi-axis capability and embedded simulation software. German automotive and aerospace fabricators adopt virtual commissioning to displace trial-and-error programming methods.
- Additive Manufacturing:Metal deposition systems for complex turbine geometries and topology-optimized components. Aerospace engine fabricators seek weight reduction through direct energy deposition and powder bed fusion.
- Automation:Programmable logic controllers and sensor networks coordinating production line workflows.
- Robotics:Articulated arms and collaborative systems for welding, assembly, and material manipulation tasks.
CNC Machining captures the deepest margin pools; Additive Manufacturing gains share fastest among emerging technology layers.
Application:
Application concentration tracks capital expenditure cycles, with mining and energy exhibiting longer replacement horizons than manufacturing.
- Manufacturing:Discrete production environments spanning automotive, aerospace, and industrial component fabrication. German precision corridors drive CNC platform refresh cycles through digital twin adoption.
- Mining:Surface and underground extraction operations requiring synchronized loading and haulage infrastructure. Australian autonomous haulage deployments demand centralized fleet management systems.
- Construction:Commercial, residential, and infrastructure project execution with seasonal demand fluctuations.
- Energy:Oil and gas extraction, power generation, and renewable infrastructure installation.
Manufacturing sustains replacement frequency leadership; Mining carries the longest equipment lifecycles.
End User:
Customer type determines procurement modality, with fleet scale dictating whether buyers negotiate direct telemetry access or accept dealer-mediated service structures.
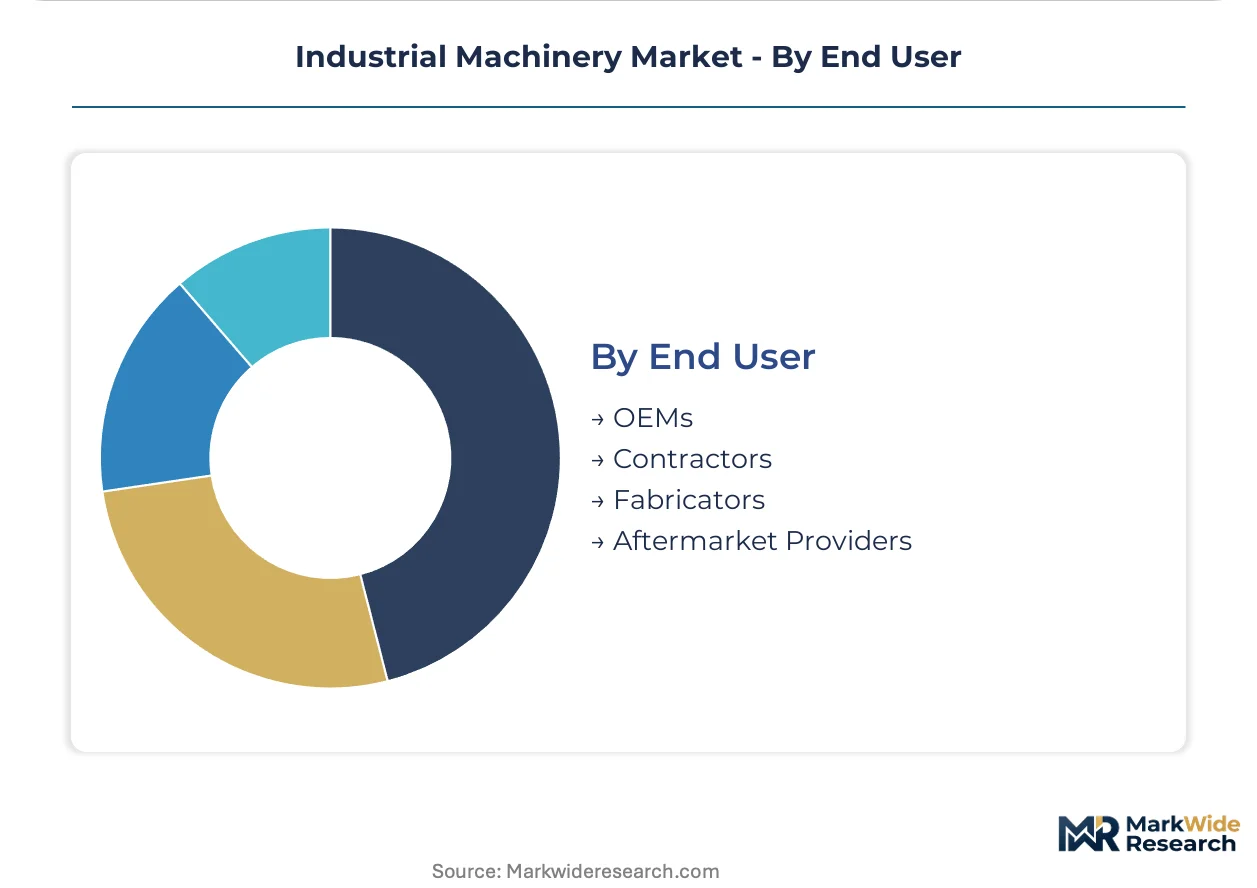
- Contractors:Construction and mining operators managing equipment fleets across multiple project sites. Large North American operators in Texas and Alberta demand API-level data portability to integrate machinery health signals into proprietary asset management platforms.
- OEMs:Original equipment manufacturers integrating machinery into larger system architectures or downstream product lines.
- Fabricators:Precision metalworking shops and component producers with specialized machining requirements.
- Aftermarket Providers:Parts distributors and service organizations maintaining installed equipment bases.
Contractors dominate procurement volume; Aftermarket Providers capture expanding service revenue as equipment intelligence layers proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in industrial machinery tilt toward net exporters with precision manufacturing depth. Import dependency concentrates in resource economies replacing aging fleets. Export competitiveness tracks digital twin adoption and emissions-compliant engine production.
United States
Construction contractors and mining operators drive replacement demand for EPA Tier 4 Final compliant fleets. OSHA machine guarding regulations force safety system retrofits across metal fabrication shops. Texas and Alberta fleet operators demand API-level data portability for proprietary asset management integration.
Germany
Automotive and aerospace fabricators anchor European CNC platform demand through digital twin adoption. REACH chemical restrictions constrain hydraulic fluid formulations and surface coating chemistries. Stuttgart and Munich precision manufacturing corridors compress setup cycles through virtual commissioning platforms.
China
Domestic infrastructure stimulus and Belt and Road equipment exports sustain construction machinery volumes. MIIT industrial upgrading policies accelerate smart manufacturing adoption in state-owned enterprises. Yangtze River Delta clusters concentrate additive manufacturing system production for aerospace subcontractors.
Japan
Machine tool OEMs and robotics integrators serve automotive and electronics precision manufacturing. METI carbon neutrality roadmaps drive energy-efficient equipment R&D tax incentives. Nagoya automotive supplier networks adopt predictive maintenance protocols for synchronized production lines.
Australia
Iron ore mining contractors deploy autonomous haulage systems requiring centralized fleet management infrastructure. TGA-equivalent mining safety regulations mandate equipment telemetry integration for remote operations monitoring. Western Australia Pilbara operations accelerate replacement cycles for synchronized loading equipment.
Industrial Machinery Market Competitive Environment
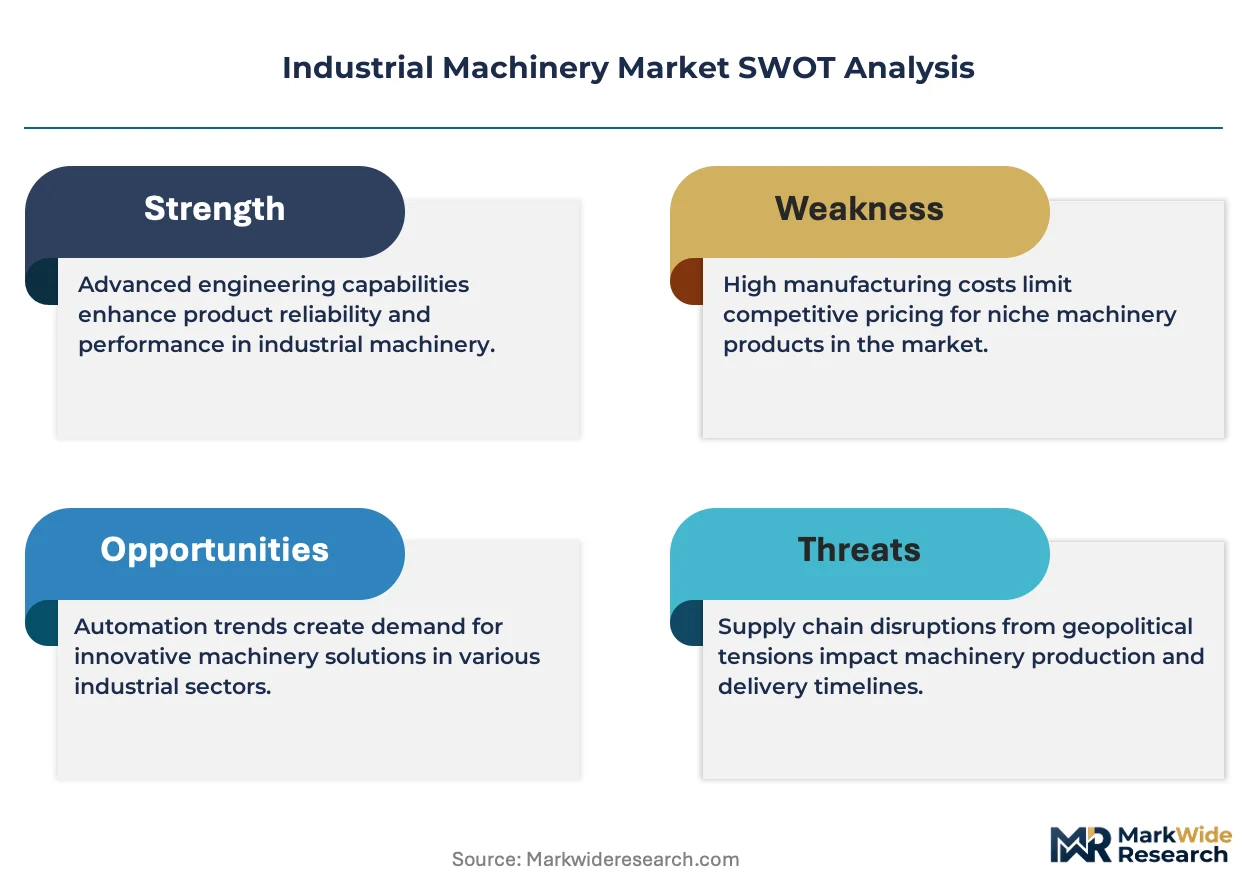
Listed leaders compete with private specialists across capital intensity and technology integration dimensions. Market structure tilts toward consolidated premium tiers with captive aftermarket revenue streams, while mid-scale fabricators face margin compression from software-defined differentiation. Three archetypes dominate: diversified industrials with financing arms, precision engineering specialists with proprietary control systems, and autonomous systems integrators. Competitive moves concentrate on dealer network digitization and predictive service contract bundling.
Among diversified industrial conglomerates, Caterpillar Inc. and General Electric Company exemplify scale-driven archetypes with captive financing and aftermarket parts control. Siemens anchors European positioning through digital twin integration architectures. Komatsu Ltd. occupies the autonomous systems tier with haulage automation deployed across Australian mining operations.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Deere & Company |
| General Electric Company |
| Siemens |
| Komatsu Ltd. |
| Rockwell Automation |
| Honeywell International |
| Hitachi |
| Cummins |
| Others |
Value Chain & Pricing Dynamics
Ninety-day bearing steel lead times from specialty mills in Germany and Japan compress margin buffers for mid-tier machine tool OEMs while amplifying pricing leverage for vertically integrated incumbents with captive metallurgical supply. This inventory pressure concentrates procurement power among construction and mining fleet operators in Australia and Chile who can absorb premium pricing for EPA-compliant integrated platforms.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by telematics integration depth and EPA Tier 4 Final certification status. Cost compression in mid-tier mechanical configurations intensifies because proprietary CNC control software locks fabricators into incumbent vendor ecosystems. Large fleet operators in Texas and Alberta exhibit lowest price sensitivity due to direct telemetry access negotiations, while municipal procurement offices in Scandinavia face highest sensitivity from REACH-compliant hydraulic fluid cost premiums.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes elevates inbound logistics costs for German precision manufacturing corridors sourcing high-grade chromium-molybdenum alloys. Supply concentrates in China for rare-earth magnet components, Germany for precision bearing assemblies, and Japan for servo motor systems. Raw material dependencies span nickel concentrate, molybdenum ore, and rare-earth elements. Single-source vulnerability from Taiwanese semiconductor foundries feeding CNC controller production threatens equipment intelligence layer availability. Distribution runs through captive dealer networks for aftermarket parts, with direct OEM relationships for large fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in proprietary control software lock-in that generates switching costs exceeding three replacement cycles for precision fabricators.
For Market Incumbents: Shield installed base revenue by deepening backward integration into bearing steel supply through offtake agreements with German specialty mills. Accelerate certification investment for EU Machinery Directive conformity assessment to extend market access lead times for non-European challengers. The threat of autonomous haulage system displacement from Komatsu Ltd. and emerging Chinese smart manufacturing platforms demands preemptive telemetry bundling.
For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Stuttgart opens white-space access for mid-scale CNC platforms with open-architecture control systems. Target Australian iron ore contractors with synchronized loading equipment retrofit kits compatible with existing autonomous haulage infrastructure. The most penetrable segment lies in aftermarket predictive maintenance services for North American construction lessors seeking API-level data portability.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because equipment intelligence layers separate hardware margins from software and data service income streams. Acquisition targets should prioritize machine tool OEMs with proprietary digital twin architectures and captive aftermarket parts flows. The signal to watch is carbon border adjustment mechanism implementation timing, which would accelerate embedded emissions tracking compliance spending across heavy equipment supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Network Digitization | Caterpillar Inc. and Komatsu Ltd. deploy predictive inventory systems anticipating failure modes before downtime occurs. |
| Digital Twin Integration | Siemens anchors European CNC demand through virtual commissioning platforms that compress setup cycles. |
| Autonomous Haulage Deployment | Australian iron ore operations require synchronized loading equipment and centralized fleet management infrastructure. |
| Backward Integration into Bearing Steel | Specialty alloy supply agreements with German and Japanese mills secure input cost stability for precision platforms. |
| REACH-Compliant Hydraulic Fluid Reformulation | European construction and mining fleets face accelerated maintenance intervals creating aftermarket service demand. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across maintenance directors at Australian iron ore operations, plant engineers in Stuttgart precision manufacturing corridors, OEM procurement teams at German automotive suppliers, and aftermarket service heads at North American construction fleet operators. Secondary validation drew from EPA regulatory filings, EU Machinery Directive conformity assessment databases, SEC 10-K equipment manufacturer disclosures, and customs trade data for specialty steel alloy flows. Bottom-up equipment shipment tallies triangulated against top-down capital expenditure surveys from mining and construction trade associations.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product type, technology layer, application vertical, and end-user procurement modality, with geographic regulatory clusters treated as distinct demand environments. CAGRs derived from replacement cycle compression analysis tied to EPA Tier 4 Final compliance deadlines and telematics adoption curves. Industry-specific forecast inputs incorporated autonomous haulage deployment timelines and digital twin adoption rates among German aerospace fabricators.
Underlying assumptions cover sustained infrastructure stimulus in China, stable nickel and molybdenum concentrate pricing, and incremental REACH chemical restriction expansion, with deviation risk concentrated in carbon border adjustment mechanism acceleration and mechatronics technician pipeline constraints. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment and Machinery
Injection Molding Machine Market
Construction Equipment and Machinery
Benelux Metal Fabrication Equipment Market
Construction Equipment and Machinery
Briquetting Machine Market
Construction Equipment and Machinery
Pipe Relining Machine Market
Construction Equipment and Machinery
Automatic Nesting CNC Router Market
Construction Equipment and Machinery
ASEAN Construction Machinery Market
Construction Equipment and Machinery
Plastic Extrusion Machines Market
Construction Equipment and Machinery
Milling Machine Market
Construction Equipment and Machinery
Thermoforming Machines Market
Construction Equipment and Machinery
Sheet Metal Fabrication Equipment Market
Construction Equipment and Machinery
GCC Construction Machinery Rental Market
Construction Equipment and Machinery
Roll Forming Machine Market
Construction Equipment and Machinery
Colombia Metal Fabrication Equipment Market
Construction Equipment and Machinery
Engineering Machinery Counterweight Iron Market
Construction Equipment and Machinery
Cold Milling Machine Market
Construction Equipment and Machinery
Dredge Automation Market