
 Coworking Spaces Market | 2026-2036
Coworking Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
Coworking Spaces Market Analytics
The coworking industry is pivoting on a widening gap between amenity-rich premium locations and stripped-down commodity offerings in secondary cities. IWG sustains the broadest geographic footprint through its multi-brand portfolio spanning Regus and Spaces. WeWork differentiates through design-forward environments targeting creative and technology tenants. Industrious anchors the premium corporate segment with hospitality-infused service models that command sustained price premiums.
Coworking spaces constitute commercially operated work environments providing shared infrastructure, flexible lease terms, and managed services to individuals and organizations on a non-exclusive basis. Facilities typically integrate high-speed internet, climate control, ergonomic furnishings, and meeting room access within a single membership or usage-based contract. The flexible office category dominates current supply volume, while corporate packages represent the fastest-expanding service model as enterprises outsource satellite location management. Dedicated desk arrangements retain the deepest margin pools due to predictable occupancy and lower operational turnover.
OSHA workplace safety standards, the EU Green Deal building performance requirements, and India's BIS structural codes collectively shape facility design, energy retrofit obligations, and market access conditions across major operating geographies. Compliance costs are filtering smaller operators toward franchise or management-contract structures rather than direct ownership. Stakeholders must monitor how municipal zoning reforms in dense metropolitan cores either expand or constrain permissible coworking locations.
Market Dynamics
The coworking sector is compressing around enterprise technology teams demanding satellite locations with hospitality-grade service levels, while hybrid work policies harden into permanent organizational structures across multinational employers.
Growth Catalysts
- EU Green Deal retrofit mandates:Building efficiency requirements are accelerating capital flows into upgraded commercial stock, expanding addressable inventory for flexible office operators.
- Enterprise technology segment expansion:Technology employers now represent the fastest-growing client category as they outsource satellite location management to specialized providers.
- Bengaluru-Mumbai cluster concentration:Indian metropolitan absorption of new supply is creating scalable operating templates for emerging market penetration.
Market Restraints
- Commercial real estate input volatility:Prime urban location rents and utility costs fluctuate with central bank rate cycles, compressing operator margin buffers.
- Supply concentration in tier-1 corridors:Premium inventory clusters in finite metropolitan cores, limiting geographic diversification for portfolio operators.
- Structural substitution by remote-first employers:Fully distributed technology companies eliminate physical workspace demand entirely from their cost structures.
Strategic Opportunities
- Secondary city underpenetration:Tier-2 Indian markets and comparable emerging economy cities present whitespace for stripped-down commodity offerings.
- OSHA compliance services bundling:Workplace safety standard adherence creates ancillary revenue streams through outsourced facility management.
- AI-powered space optimization convergence:Sensor networks and predictive occupancy algorithms are reducing per-desk operational overhead.
Industry Challenges
- Hospitality-talent scarcity:Premium service models require front-desk and community management skills that commercial real estate traditionally does not cultivate.
- Legacy lease liability integration:Long-term commercial contracts with landlords create balance sheet rigidity when enterprise clients demand monthly flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coworking Spaces Market |
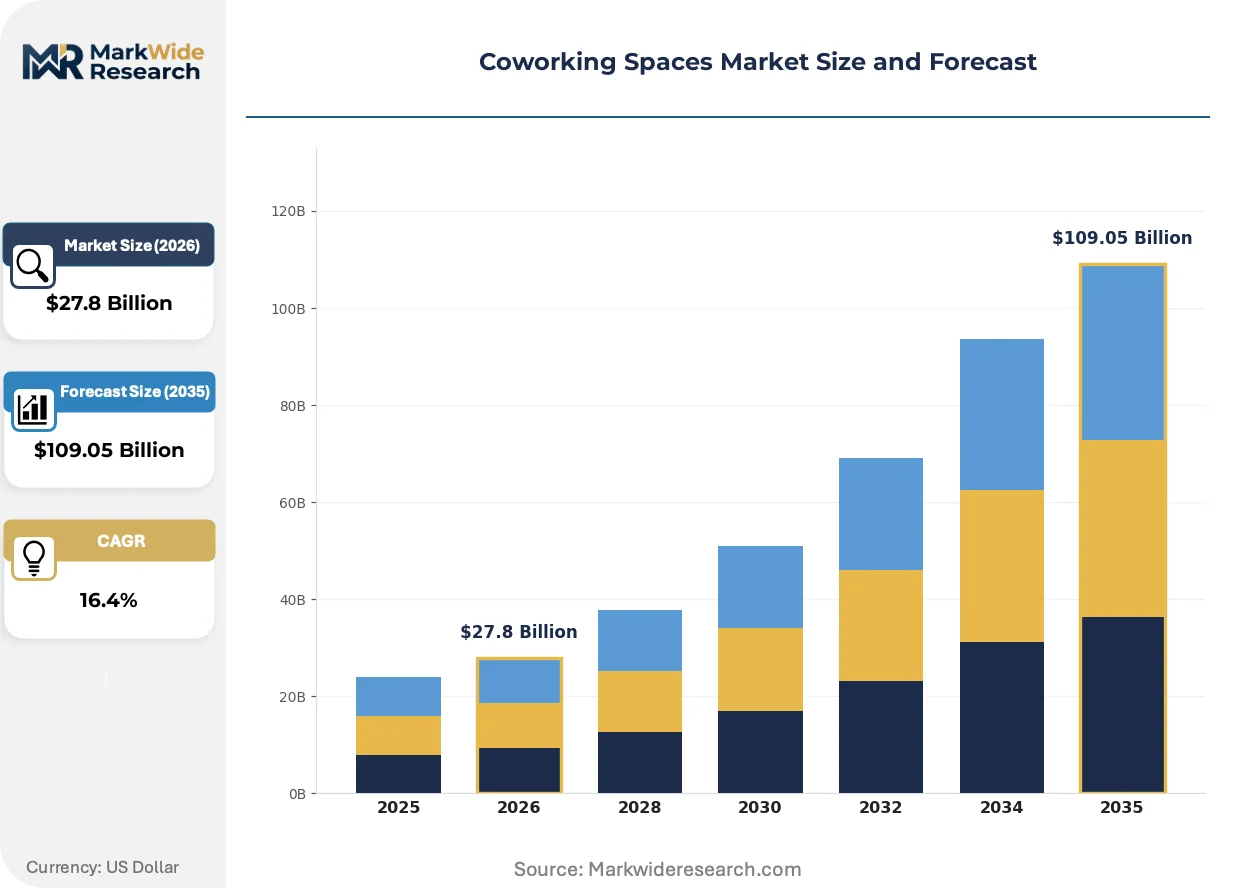
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $109.05 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Flexible Office, Dedicated Desk, Hot Desk, Meeting Rooms Service Model: Membership, Pay-as-you-go, Corporate Packages, Event Space Client Type: Startups, Freelancers, Small Enterprises, Corporations Facility Features: High-speed Internet, Conference Rooms, Pantry Services, Lounge Areas |
| Companies Covered | Servcorp, Venture X, IWG (International Workplace Group), Premier Workspaces, Mindspace, WeWork, Ucommune, 91springboard, Industrious, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coworking Spaces Market Evolving Landscape
Facility operations are digitizing rapidly as sensor infrastructure and predictive algorithms replace manual space management, while regulatory pressure on building performance intensifies capital allocation toward efficiency retrofits.
Occupancy sensing networks is automating climate control, desk allocation, and meeting room scheduling across premium locations. Enterprise clients with hundred-plus seat deployments are mandating these systems as baseline procurement requirements. The technology is automating the traditional community manager role, compressing staffing ratios from one per fifty desks toward one per two hundred.
The EU Green Deal building performance standards are mandating energy efficiency upgrades across existing commercial stock. Operators must retrofit HVAC systems and lighting infrastructure to maintain market access. Dedicated desk arrangements face the steepest compliance cost penalties due to their 24-hour operational profiles.
Enterprise procurement teams are consolidating vendor relationships around single-provider global contracts. Satellite location management is migrating from decentralized real estate departments to centralized workplace strategy functions. This concentration is most visible in technology sector employers with distributed engineering teams across multiple countries.
Coworking Spaces Market Segmentation
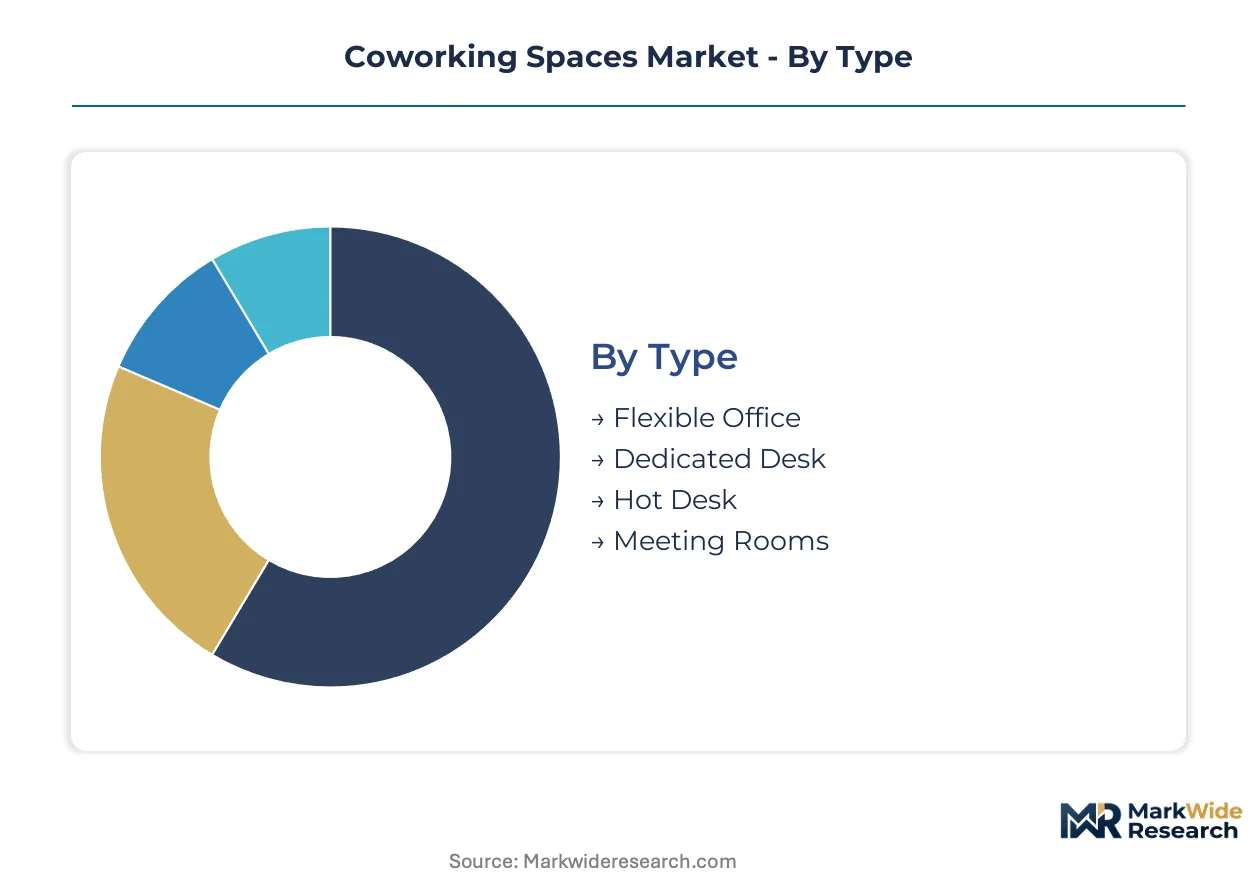
Coworking operators configure inventory around four distinct axes: physical space type, commercial contract structure, tenant organizational profile, and amenity infrastructure. Each axis carries different margin profiles and capital intensity requirements that shape portfolio strategy.
Type:
Physical configuration determines lease flexibility, operational complexity, and revenue predictability across facility portfolios.
- Flexible Office:Self-contained suites with private access and dedicated infrastructure support teams requiring confidentiality without long-term commercial leases. Demand concentrates among enterprise technology teams in Bengaluru and Mumbai seeking satellite locations with hospitality-grade service levels under hybrid work policies.
- Dedicated Desk:Permanently assigned workstations within shared environments generate the deepest margin pools through predictable occupancy and reduced operational turnover. Small enterprises in Indian metropolitan clusters absorb the bulk of this inventory as they scale headcount without committing to traditional commercial contracts.
- Hot Desk:Unassigned seating accessed on-demand suits freelancers and transient workers with irregular schedules.
- Meeting Rooms:Bookable enclosed spaces for client presentations and team gatherings generate ancillary revenue streams.
Flexible Office leads on scale; Dedicated Desk leads on margin stability.
Service Model:
Commercial contract structures range from recurring subscriptions to transactional usage, with distinct working capital implications.
- Corporate Packages:Consolidated multi-location contracts with centralized billing and standardized service levels. Enterprise technology employers now expand most quickly in this category as they outsource satellite location management to specialized providers across distributed engineering teams.
- Membership:Monthly recurring subscriptions with tiered access privileges form the baseline revenue foundation for most operators.
- Pay-as-you-go:Per-hour or per-day pricing accommodates sporadic users without commitment.
- Event Space:Temporary venue rental for workshops, product launches, and corporate gatherings diversifies revenue beyond daily workspace.
Membership anchors revenue stability; Corporate Packages climb the fastest.
Client Type:
Tenant organizational maturity drives space configuration requirements and contract negotiation leverage.
- Corporations:Multinational employers with hundred-plus seat deployments mandate sensor-based space optimization and global vendor consolidation. Procurement teams in technology sector employers are migrating satellite location management from decentralized real estate departments to centralized workplace strategy functions.
- Startups:Venture-backed companies with volatile headcount needs prioritize month-to-month flexibility over cost optimization.
- Freelancers:Independent professionals seek community access and professional infrastructure without residential distraction.
- Small Enterprises:Established businesses with 10-50 employees use coworking as a bridge between home offices and dedicated commercial leases.
Corporations command pricing power; Startups exhibit the steepest expansion trajectory.
Facility Features:
Infrastructure specifications differentiate premium locations from commodity offerings and determine compliance cost exposure.
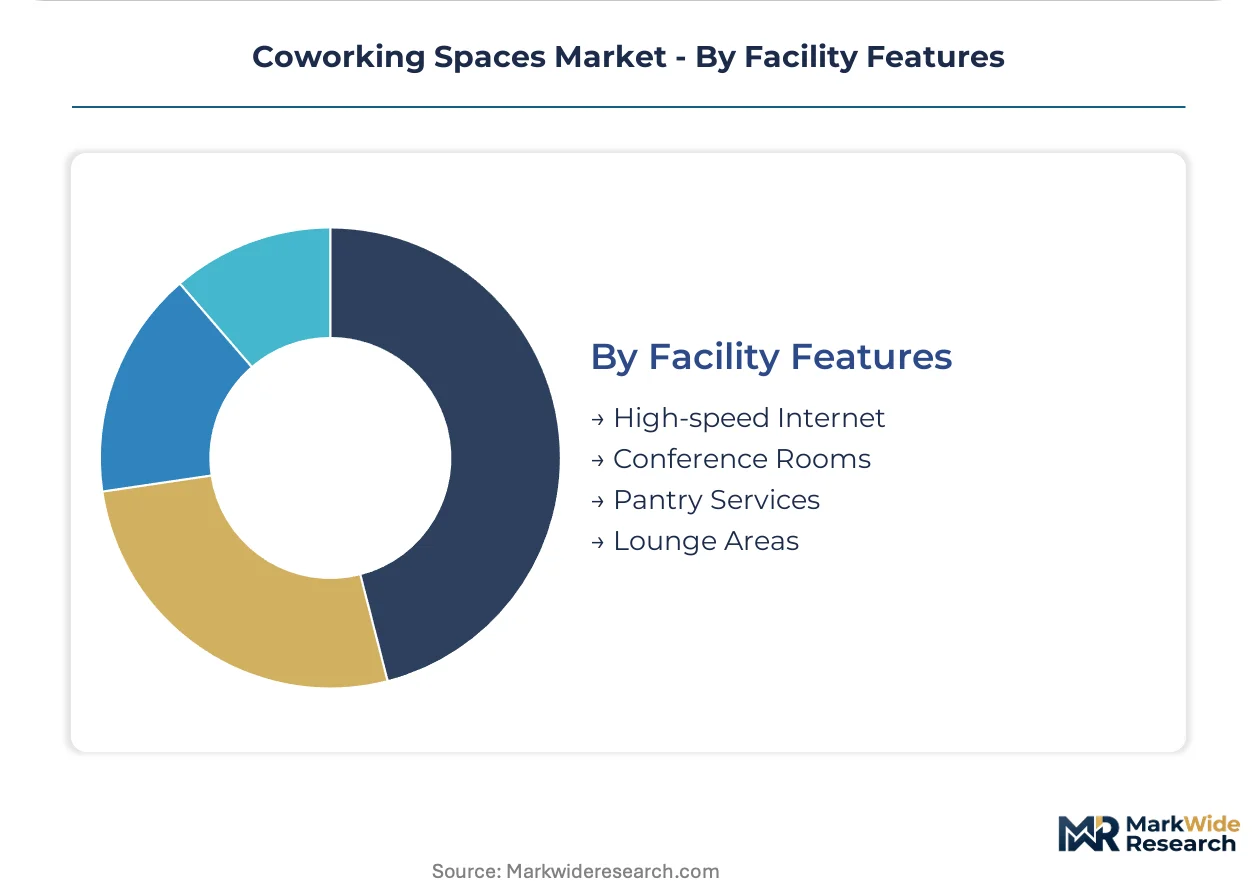
- High-speed Internet:Redundant fiber connectivity with enterprise-grade security protocols represents non-negotiable baseline infrastructure. EU Green Deal building performance standards are mandating energy efficiency upgrades that affect telecommunications equipment cooling and power redundancy systems.
- Conference Rooms:Video-enabled meeting spaces with acoustic treatment support hybrid collaboration between distributed teams.
- Pantry Services:F&B infrastructure ranging from self-service coffee to catered meals affects daily operational staffing requirements.
- Lounge Areas:Informal gathering spaces with soft seating and natural light support unstructured collaboration and tenant retention.
High-speed Internet leads on necessity; Conference Rooms lead on enterprise procurement priority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India absorbs flexible office supply faster than Germany expands inventory, while the United States concentrates enterprise technology demand across coastal metropolitan corridors. Regulatory divergence on building efficiency and workplace safety is fragmenting operator compliance strategies across jurisdictions.
United States
Enterprise technology employers in Seattle and Austin drive satellite location procurement under permanent hybrid policies. OSHA workplace safety standards mandate ergonomic assessments and emergency egress protocols for multi-tenant facilities. New York City and San Francisco operators absorb the steepest commercial rent volatility as central bank rate cycles compress margin buffers.
India
Bengaluru and Mumbai clusters absorb the bulk of new supply as technology sector headcount scales without traditional lease commitments. BIS structural codes govern facility safety certifications and electrical installation standards for commercial retrofits. Hyderabad and Pune sub-markets replicate the operating templates developed in larger metropolitan corridors.
Germany
Corporate procurement teams in Berlin and Munich consolidate vendor relationships around hospitality-grade service levels. EU Green Deal building performance requirements accelerate HVAC retrofit investments across existing commercial stock. Frankfurt operators face the steepest energy efficiency compliance costs due to 24-hour operational profiles in financial district locations.
United Kingdom
Technology sector employers in London and Manchester outsource satellite management to specialized providers with global contract capabilities. GDPR and workplace safety regulations shape data infrastructure and facility access protocols across multi-tenant environments. Birmingham and Leeds secondary markets present whitespace for stripped-down commodity offerings.
China
Dual carbon goals and building efficiency mandates in Shanghai and Beijing accelerate green retrofit investments across aging commercial stock. GB standards and local fire safety codes govern structural modifications and occupancy limits for flexible office conversions. Shenzhen and Hangzhou technology corridors concentrate demand for premium locations with integrated digital infrastructure.
Coworking Spaces Market Competitive Landscape
Top-tier vendors anchor premium hospitality-infused service models, while mid-tier operators compete on geographic density and stripped-down commodity pricing. The market structures around three strategic archetypes: global multi-brand portfolio companies, design-forward creative-focused operators, and regional specialists with localized service customization. Dominant competitive moves include franchise network expansion and technology platform licensing to reduce capital intensity.
Within the global portfolio tier, IWG and WeWork exemplify divergent positioning strategies. IWG occupies a position spanning multiple price points through its Regus and Spaces brand architecture. WeWork sits within the design-forward archetype targeting creative and technology tenant profiles. Industrious anchors the premium corporate segment with hospitality-infused service models that command sustained price premiums.
| Leading Market Players |
|---|
| Servcorp |
| Venture X |
| IWG (International Workplace Group) |
| Premier Workspaces |
| Mindspace |
| WeWork |
| Ucommune |
| 91springboard |
| Industrious |
| Others |
Value Network & Pricing Analysis
Prime urban commercial rents in Bengaluru and Mumbai flow through tiered membership structures, compressing margin buffers for operators while EU Green Deal retrofit obligations add fixed cost layers that price-sensitive Indian small enterprises resist absorbing.
Pricing Analysis
Capacity additions in Hyderabad and Pune are reshaping price floors for flexible office inventory, forcing established operators to defend positioning through service differentiation rather than location scarcity alone. Three-tier pricing structure across premium, standard, and economy levels separates Industrious hospitality-infused models from stripped-down commodity offerings in secondary corridors. Cost compression in the hot desk tier is intensifying because sensor automation reduces per-desk staffing overhead. Freelancers and transient workers exhibit the steepest price sensitivity, while enterprise technology procurement teams prioritize global contract standardization over unit cost minimization.
Supply Chain Analysis
Ergonomic furniture supply rests on Chinese and Vietnamese manufacturing clusters with German and Italian design house licensing. HVAC and building automation systems draw from Japanese and South Korean component producers. Single-source vulnerability concentrates in sensor network hardware where Taiwanese semiconductor fabrication feeds predictive occupancy algorithms. Distribution runs through regional facility management contractors who bundle installation with ongoing maintenance obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coworking sector functions as a geographic-arbitrage play where EU Green Deal compliance costs in Frankfurt and Berlin create margin headroom for operators achieving equivalent service levels in lower-regulatory-burden Indian metropolitan clusters.
For Market Incumbents: Extend franchise network coverage into tier-2 Indian markets before capital-light competitors establish density. Acquire sensor-technology capabilities in-house to reduce dependency on external HVAC automation vendors facing EU component scarcity. Legacy lease liability exposure threatens balance sheet flexibility as enterprise clients demand monthly contract terms.
For New Entrants and Emerging Players: The premium-to-economy price gap in Birmingham and Leeds secondary UK corridors offers white-space entry with stripped-down inventory configurations. Target small enterprise segments in Hyderabad sub-markets where operating templates from Bengaluru transfer with minimal adaptation. Lead with OSHA compliance bundling as differentiated service anchor.
For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with localized hospitality customization because enterprise procurement consolidation favors single-provider global contracts. Five-to-ten year viability hinges on technology-enabled operating leverage rather than pure location arbitrage. Watch enterprise technology employer headcount announcements as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Franchise Network Expansion | Capital-light geographic penetration into tier-2 Indian markets accelerates footprint without direct real estate ownership. |
| Sensor Infrastructure Deployment | Predictive occupancy algorithms from Japanese automation vendors compress staffing ratios from one per fifty desks toward one per two hundred. |
| EU Green Deal Retrofit Program | HVAC and lighting upgrades maintain market access as building performance standards harden across German and UK commercial stock. |
| Corporate Package Consolidation | Centralized workplace strategy functions at technology employers mandate global vendor relationships with standardized service levels. |
| Hospitality Talent Development | Front-desk and community management capabilities differentiate premium locations from commodity offerings in supply-constrained labor markets. |
Research Methodology
Direct dialogue with coworking operators, facility managers at enterprise technology employers, commercial real estate brokers, and workplace strategy consultants grounded qualitative assessment in operational reality. Secondary validation drew from OSHA workplace safety filings, EU Green Deal implementation guidance, BIS structural code documentation, and SEC disclosures from publicly traded flexible office providers. Bottom-up demand modeling across membership tiers triangulated against top-down commercial real estate absorption data.
Market sizing outputs segmented across physical space type, service model contract structure, client organizational profile, and amenity infrastructure specifications. CAGRs derived from regression analysis of historic occupancy rates, rent growth trajectories, and enterprise headcount expansion patterns across the analysis window. Forecast inputs incorporated hybrid work policy permanence assumptions and regulatory retrofit obligation schedules without specific year anchoring.
Caveats apply where central bank rate cycles, enterprise remote-first policy reversals, or municipal zoning reforms could materially shift the outlook. Forecasts reflect documented assumptions about technology sector headcount growth and building efficiency compliance timelines. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Property Tax Services Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
US Home Service Market
Real Estate Services
Public Warehousing Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Home Warranty Service Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
Lease Management Market
Real Estate Services
Canada Real Estate Services Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
Green Lease Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
Co-Working Space Services Market
Real Estate Services
Asia-Pacific Self Storage Market