
 Public Warehousing Market | 2026-2036
Public Warehousing Market Size, Share, and Industry Trends Forecast 2026-2036
Public Warehousing Market Analysis
Value-added service revenue is tilting away from pure storage toward integrated fulfillment and inventory management bundles. DHL Supply Chain leverages its automated sortation networks to capture premium pricing in e-commerce fulfillment. XPO Logistics anchors its North American footprint through dedicated last-mile distribution centers. Kuehne + Nagel differentiates with temperature-controlled pharmaceutical storage certifications across European hubs.
Public warehousing denotes third-party commercial facilities offering shared storage, handling, and distribution services to multiple clients under short- or long-term contracts, typically operating racking systems with 30- to 45-foot clear heights and floor load capacities exceeding 500 pounds per square foot to accommodate palletized and bulk inventory. These facilities serve as intermediary nodes in supply chains, consolidating inbound freight and executing outbound order fulfillment to reduce capital expenditure for shippers. Cold storage within the warehouse type dimension commands outsized margins due to specialized refrigeration infrastructure and stringent temperature validation protocols. The technology segment shows robotics and warehouse management systems absorbing disproportionate capital allocation as labor scarcity and throughput requirements intensify. Fulfillment centers among end users are experiencing the fastest structural expansion as direct-to-consumer order profiles reshape facility design specifications.
The US Occupational Safety and Health Administration enforces warehouse ergonomics and powered industrial truck standards that shape facility design and labor deployment. The European Union's Corporate Sustainability Reporting Directive and F-Gas Regulation impose emissions disclosure and refrigerant management obligations on cold chain operators. China's Ministry of Ecology and Environment monitors warehouse energy consumption under dual carbon goals. Stakeholders must weigh automation deployment timelines against evolving carbon accounting liabilities and regional energy pricing trajectories.
Market Dynamics
E-commerce fulfillment velocity requirements are compressing warehouse design cycles from 18-month buildouts to 90-day retrofits of existing industrial shells.
Growth Catalysts
- CSRD Mandates:The European Union's Corporate Sustainability Reporting Directive compels multinationals to outsource warehousing to third-party operators with verified carbon accounting infrastructure.
- Robotics Integration:Automated mobile robots and goods-to-person systems enable fulfillment centers to triple throughput per square foot without proportional labor expansion.
- Yangtze River Delta:Manufacturing concentration in China's eastern corridor generates sustained demand for bonded and cross-border storage facilities serving export-oriented supply chains.
Market Restraints
- Steel and Concrete Input Volatility:Warehouse construction costs swing with regional steel pricing, freezing speculative development in secondary markets.
- Refrigerant Supply Concentration:Cold storage operators depend on limited global suppliers of F-gas compliant cooling systems, creating equipment procurement bottlenecks.
- Last-Mile Real Estate Scarcity:Urban infill sites suitable for same-day fulfillment centers face zoning restrictions and community opposition in dense metropolitan cores.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for electronics and pharmaceuticals manufacturing are generating first-mover demand for contract warehousing near special economic zones.
- Pharmaceutical Cold Chain:Temperature-validated storage for biologics and vaccines represents an underserved premium segment with specialized certification barriers.
- 5G-Enabled Yard Management:Convergence of private cellular networks and real-time location systems allows trailer detention cost reduction through automated gate and dock scheduling.
Industry Challenges
- WMS Integration Complexity:Legacy enterprise resource planning systems resist API connectivity with modern warehouse management platforms, delaying automation deployments.
- Industrial Maintenance Technician Scarcity:Automated facilities require electro-mechanical specialists that outnumber available certified personnel in most labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Warehousing Market |
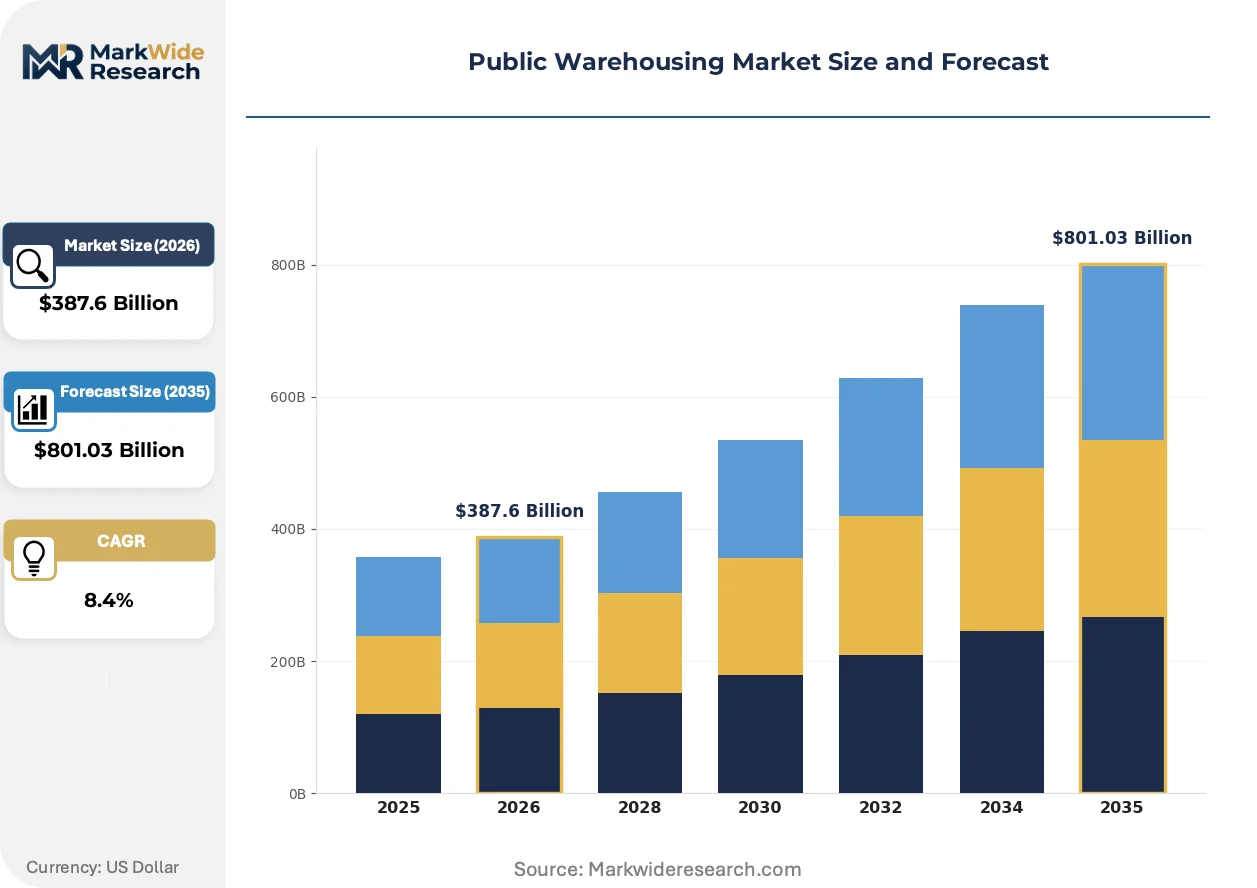
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $801.03 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Storage, Distribution, Inventory Management, Value-Added Services Warehouse Type: General Storage, Cold Storage, Bonded Warehouse, Fulfillment Center End User: Retailers, E-Commerce Firms, Manufacturers, Wholesalers Technology: Warehouse Management System, Robotics, IoT Solutions, Automation |
| Companies Covered | UPS Supply Chain Solutions, Ryder Supply Chain Solutions, DHL Supply Chain, GEODIS, DB Schenker, XPO Logistics, CEVA Logistics, Lineage Logistics, Kuehne + Nagel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Warehousing Market Emerging Trajectories
Facility intelligence layers are displacing hardware-centric investment as the primary competitive differentiator in third-party warehousing contracts.
Autonomous mobile robots are migrating from pilot installations to standard capital planning for e-commerce fulfillment centers. Mid-market 3PLs now specify AMR compatibility in new lease agreements. This technology shift is compressing labor cost structures while extending facility useful lives through modular retrofit capability.
The European Union's F-Gas Regulation phases down hydrofluorocarbon refrigerants in cold storage applications. Operators must retrofit or replace cooling infrastructure before mandated deadlines. Pharmaceutical and foodservice cold chain facilities in Germany, France, and the Netherlands face the most concentrated compliance timelines and capital exposure.
Direct-to-consumer order profiles are fragmenting pallet-based receiving into parcel-level sortation requirements. Fashion and consumer electronics brands now reject warehouses without scan tunnel and label application automation. This pattern is most pronounced in Southern California and the Netherlands, where same-day delivery coverage zones overlap with major port gateways.
Public Warehousing Market Segmentation
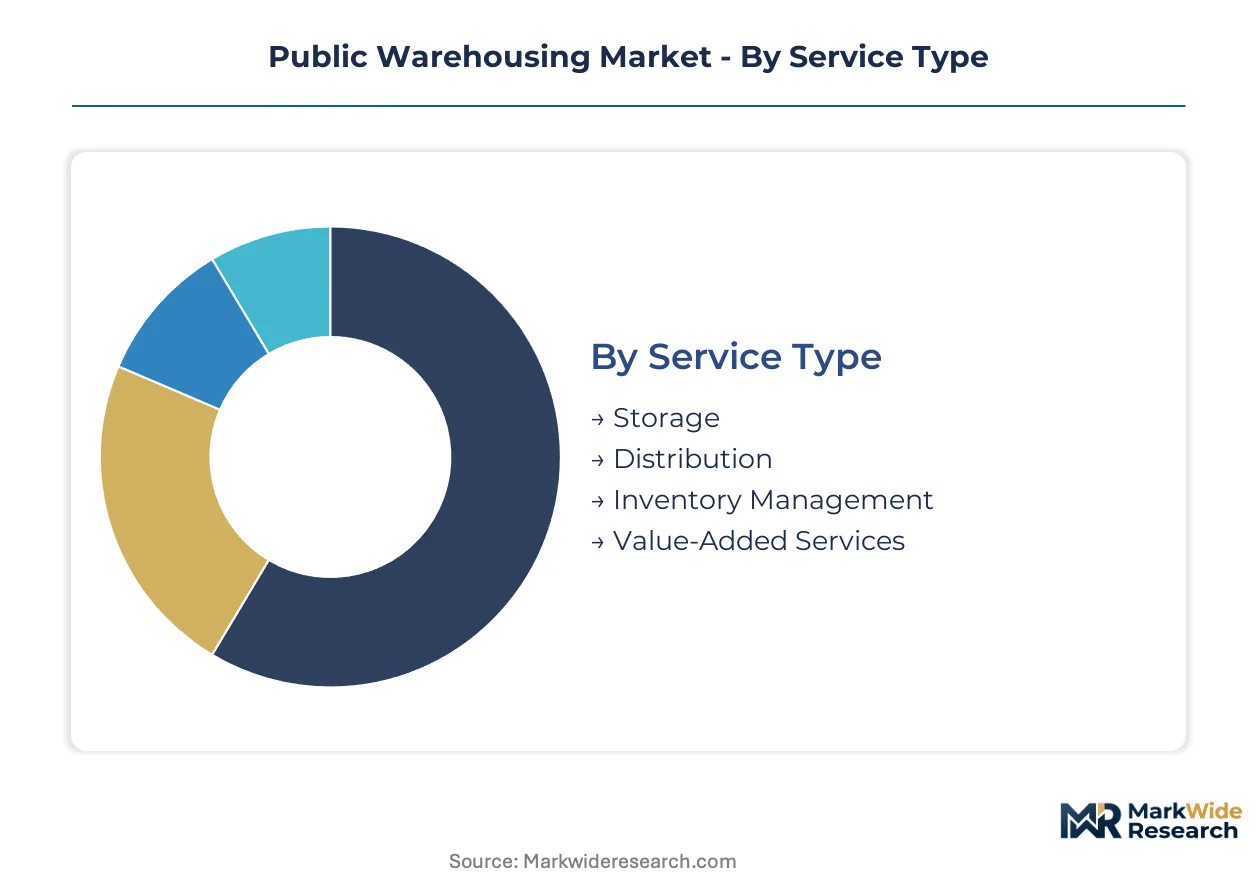
Public warehousing operators configure service portfolios around client capital constraints and inventory velocity requirements. Segment boundaries blur as pure storage contracts absorb fulfillment and technology layers to defend pricing power.
Service Type:
Mature revenue streams coexist with emerging high-margin bundles across the service spectrum.
- Storage:Core pallet-position contracting with 30- to 45-foot clear heights and floor loads exceeding 500 pounds per square foot. Demand concentrates among bulk commodity shippers in China's Yangtze River Delta manufacturing corridor facing working capital pressure from inventory carrying costs.
- Distribution:Cross-dock and consolidation services with bonded transit capabilities. E-commerce fulfillment operations in the Netherlands and Southern California drive specifications for scan tunnel and label application automation to handle parcel-level fragmentation.
- Inventory Management:Cycle counting, demand forecasting integration, and safety stock optimization. Retailers with seasonal SKU proliferation use these services to reduce ERP licensing overhead.
- Value-Added Services:Kitting, labeling, and light assembly bundled into per-unit pricing. The segment climbs fastest as 3PLs defend margin erosion in commoditized storage.
Storage handles the majority of throughput; value-added services are gaining share fastest.
Warehouse Type:
Facility specialization tracks temperature requirements, customs status, and order profile velocity.
- General Storage:Ambient racked facilities serving non-perishable goods with standard material handling equipment. Manufacturers in India's special economic zones under the PLI scheme generate first-mover demand for contract capacity near electronics and pharmaceutical production.
- Cold Storage:Refrigerated infrastructure with F-Gas Regulation compliance for hydrofluorocarbon phase-down. Germany, France, and the Netherlands face concentrated retrofit deadlines for pharmaceutical and foodservice applications.
- Bonded Warehouse:Customs-supervised storage deferring duty payment until goods exit for domestic consumption. China's eastern corridor uses these facilities for export-oriented supply chain consolidation.
- Fulfillment Center:Direct-to-consumer order processing with goods-to-person automation and same-day delivery radius coverage. Design cycles compress from 18-month buildouts to 90-day retrofits as e-commerce velocity requirements intensify.
General storage dominates square footage; fulfillment centers are expanding most quickly.
End User:
Customer type determines automation intensity and contract structure preferences.
- Retailers:Seasonal inventory buffering with promotional surge capacity. Fashion brands reject facilities without automated sortation as order profiles fragment from pallet to parcel.
- E-Commerce Firms:Direct-to-consumer fulfillment with returns processing integration. These operators specify AMR compatibility in new lease agreements and drive 5G-enabled yard management adoption.
- Manufacturers:Inbound component storage and finished goods distribution. Electronics and pharmaceutical producers near India's SEZs contract for bonded and cross-border capacity.
- Wholesalers:Pallet-in-pallet-out throughput with less frequent handling than retail-facing operations. These customers prioritize cost per pallet position over automation density.
E-commerce firms set the specification pace; manufacturers represent the steepest expansion trajectory.
Technology:
Capital allocation shifts from hardware-centric investment toward facility intelligence layers.
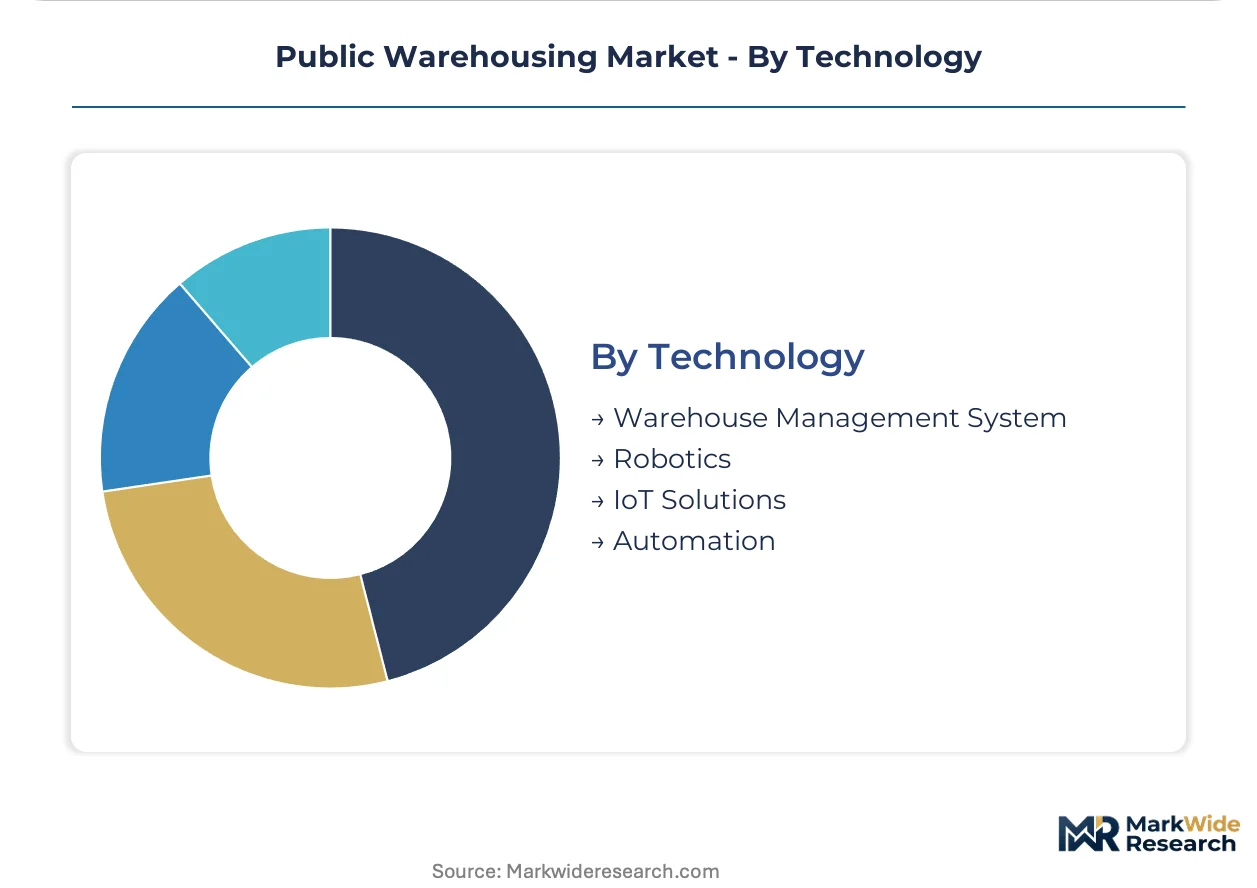
- Warehouse Management System:Software platforms coordinating inventory, labor, and equipment. Legacy ERP systems resist API connectivity with modern WMS platforms, delaying automation deployments in mid-market 3PLs.
- Robotics:Autonomous mobile robots and goods-to-person systems tripling throughput per square foot. AMRs migrate from pilot installations to standard capital planning as labor scarcity intensifies.
- IoT Solutions:Sensor networks for temperature validation, asset tracking, and energy monitoring. Cold chain operators use these for CSRD-mandated emissions disclosure.
- Automation:Conveyance, sortation, and packaging equipment integration. Electro-mechanical specialist scarcity constrains deployment timelines despite capital availability.
Warehouse management systems anchor technology spending; robotics is climbing fastest on share.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. Indian and Chinese buyers prioritize cost per pallet position, while Western European and North American shippers absorb premiums for carbon-verified facilities and automation density.
United States
E-commerce fulfillment velocity and pharmaceutical cold chain expansion drive warehouse demand. OSHA enforces powered industrial truck and ergonomics standards that shape facility design specifications. Southern California's Inland Empire hosts the densest concentration of same-day fulfillment centers serving port-adjacent supply chains.
Germany
Automotive component storage and pharmaceutical distribution anchor capacity utilization. The F-Gas Regulation mandates hydrofluorocarbon phase-downs for cold storage infrastructure. The Rhine-Ruhr corridor concentrates bonded warehousing serving export-oriented manufacturing.
China
Cross-border e-commerce and electronics manufacturing generate sustained demand for third-party storage. The Ministry of Ecology and Environment monitors warehouse energy consumption under dual carbon goals. The Yangtze River Delta manufacturing corridor dominates bonded and export-oriented facility development.
India
Electronics and pharmaceutical manufacturing under the PLI scheme create first-mover demand for contract warehousing. BIS standards govern material handling equipment safety and facility construction quality. Special economic zones in Gujarat and Maharashtra attract dedicated distribution center investment.
Netherlands
Port-centric logistics and pharmaceutical cold chain operations sustain premium pricing. The CSRD compels emissions disclosure from warehousing operators serving multinational clients. The Rotterdam-Antwerp corridor anchors European distribution with automated sortation specifications.
Public Warehousing Market Vendor Landscape
Capability concentration sits with specialized cold chain and pharmaceutical-certified operators; scale advantage sits with diversified global networks spanning multiple geographies and service types. The market structures around three tiers: integrated logistics conglomerates with end-to-end supply chain control, regional specialists commanding premium niches through certification barriers, and asset-light operators leveraging third-party facility networks. Dominant competitive moves include selective automation deployment to compress labor costs and strategic facility positioning near port gateways and manufacturing clusters.
Within the integrated logistics tier, DHL Supply Chain, XPO Logistics, and Kuehne + Nagel occupy positions defined by geographic coverage breadth and service portfolio depth. DHL Supply Chain exemplifies automation-heavy fulfillment specialization. XPO Logistics represents North American last-mile distribution density. Kuehne + Nagel anchors pharmaceutical cold chain certification across European hubs. These operators sit within a competitive set where facility intelligence layers and carbon accounting infrastructure increasingly separate premium pricing from commodity storage rates.
| Leading Market Players |
|---|
| UPS Supply Chain Solutions |
| Ryder Supply Chain Solutions |
| DHL Supply Chain |
| GEODIS |
| DB Schenker |
| XPO Logistics |
| CEVA Logistics |
| Lineage Logistics |
| Kuehne + Nagel |
| Others |
Supply Flow & Price Mechanics
F-Gas Regulation compliance deadlines in Germany, France, and the Netherlands compress both pricing tier spreads and supply chain configuration as cold storage operators face simultaneous equipment retrofit costs and refrigerant procurement bottlenecks. Steel input volatility and AMR compatibility requirements further stratify contract rates between premium-certified facilities and commoditized ambient storage.
Pricing Analysis
Value-added service bundling now drives lifetime contract value as pure storage rates commoditize across the Yangtze River Delta and India's special economic zones. Three-tier pricing structure across premium-certified, standard-automated, and economy-ambient levels separates operators with CSRD-verified carbon accounting from undifferentiated competitors. Pricing pressure stems from e-commerce fulfillment centers demanding per-unit economics without proportional labor expansion. Retailers and wholesalers in China's manufacturing corridor exhibit highest price sensitivity, while pharmaceutical and biologics shippers in Western Europe absorb premiums for temperature-validated infrastructure.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms now anchor equipment procurement for automated sortation and refrigeration systems across facility buildouts. Steel production concentrates in China, South Korea, and India; cooling system components draw from Germany, Japan, and limited F-gas compliant suppliers. Single-source vulnerability in refrigerant equipment creates procurement chokepoints for cold chain retrofits. Distribution runs through port-adjacent clusters in Southern California, the Netherlands, and China's eastern corridor, with last-mile real estate scarcity in dense metropolitan cores forcing inventory positioning trade-offs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
CSRD-mandated carbon disclosure and robotics integration are compressing facility design cycles from 18-month buildouts to 90-day retrofits, creating winner-take-most dynamics for operators with pre-positioned automation infrastructure.
For Market Incumbents: Build certification moats around pharmaceutical cold chain and CSRD-verified carbon accounting to defend against asset-light competitors. DHL Supply Chain and Kuehne + Nagel exemplify automation-heavy positioning that locks in premium pricing. Incumbents should accelerate vertical integration into robotics maintenance capabilities to offset electro-mechanical technician scarcity threatening deployment timelines. For New Entrants and Emerging Players: Mid-market 3PLs in India's PLI scheme corridors represent the most penetrable entry point, with electronics and pharmaceutical manufacturing generating first-mover demand for contract warehousing. Bonded warehouse capacity near Gujarat and Maharashtra special economic zones offers regulatory-advantaged positioning. New entrants should pursue AMR-compatible facility specifications as a go-to-market wedge against legacy ambient-only competitors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors diversified global networks with end-to-end supply chain control. Long-term viability over the next decade hinges on automation deployment timelines and carbon accounting infrastructure rather than pure square footage scale. Acquisition targets should demonstrate facility intelligence layers separating premium pricing from commodity storage. The signal to watch is 5G-enabled yard management adoption as a proxy for operational sophistication and margin expansion potential.| Strategic Initiative | Industry Significance |
|---|---|
| AMR Compatibility Certification | Goods-to-person robotics integration triples throughput per square foot for e-commerce fulfillment. |
| F-Gas Retrofit Completion | Pharmaceutical cold chain operators in Germany and the Netherlands avoid regulatory penalties. |
| CSRD Carbon Accounting Infrastructure | Verified emissions disclosure captures multinational outsourcing mandates under EU directives. |
| Last-Mile Distribution Center Positioning | Urban infill sites in Southern California and the Netherlands enable same-day delivery coverage. |
| 5G-Enabled Yard Management Deployment | Private cellular networks reduce trailer detention costs through automated gate scheduling. |
Methodological Framework
Desk research of customs and trade databases, SEC filings from logistics operators, and EU regulatory filings preceded structured interviews with warehouse operations directors, 3PL procurement leads, cold chain facility managers, and industrial real estate developers. Primary fieldwork combined with secondary validation across OSHA enforcement records, F-Gas Regulation compliance timelines, and PLI scheme documentation enabled bottom-up and top-down triangulation of capacity utilization and pricing dynamics.
Assumptions around steel input pricing stability, AMR deployment cost curves, and CSRD enforcement timelines were held fixed across baseline scenarios while e-commerce penetration rates and pharmaceutical cold chain expansion were stress-tested. Segmentation modeling covered service type, warehouse type, end user category, and technology adoption intensity. CAGRs were derived from facility square footage expansion, contract rate evolution, and value-added service mix shifts across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in regional energy pricing, steel commodity volatility, or trade policy affecting bonded warehouse utilization would shift the trajectory. Forecasts reflect documented assumptions regarding labor scarcity intensity and automation capital availability. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
GCC Interior Design Services Market
Real Estate Services
Warehousing Services Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
Property Tax Services Market
Real Estate Services
Singapore Self-Storage Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Canada Real Estate Services Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
United States Self Storage Market
Real Estate Services
Warehousing and Storage Services Market