
 Lease Management Market | 2026-2036
Lease Management Market Size, Share, and Industry Trends Forecast 2026-2036
Lease Management Market Intelligence
Platform licensing revenue is tilting from perpetual on-premise contracts toward recurring cloud subscriptions. Oracle leverages its enterprise database footprint to bundle lease accounting with broader ERP workflows. SAP sustains competitive pressure through native integration with S/4HANA financial modules. Yardi Systems dominates the North American multi-family and commercial property vertical with specialized asset management tools.
Lease management encompasses software systems that track, analyze, and report on contractual obligations between lessors and lessees, typically processing data fields including rent schedules, escalation clauses, renewal options, and impairment calculations across ASC 842 and IFRS 16 standards. Cloud-based deployment leads segment momentum as organizations migrate from legacy spreadsheet governance to API-connected platforms with real-time portfolio dashboards. Software solutions capture the deepest margin pools through modular pricing for lease accounting, abstracting, and compliance modules, while consultancy services anchor implementation revenue for complex enterprise rollouts.
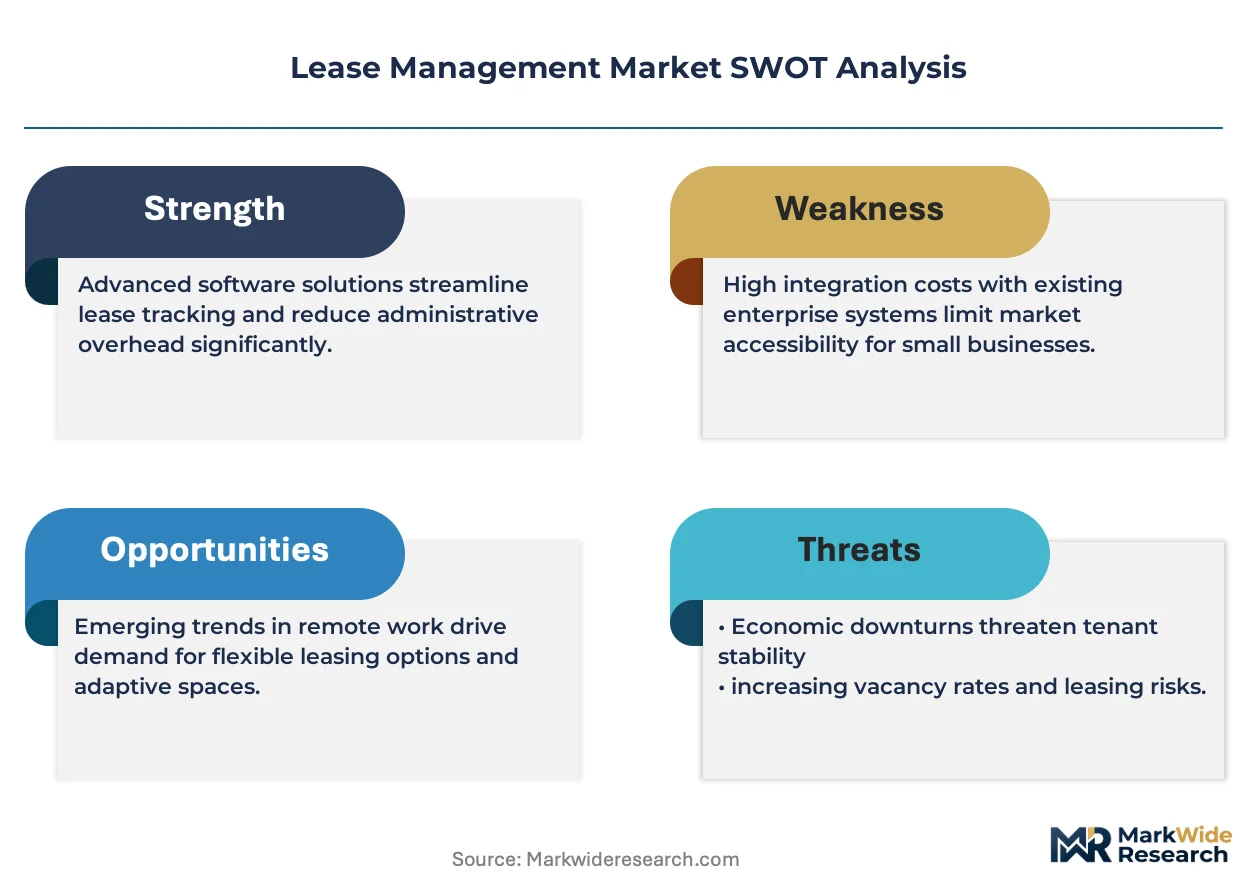
The US SEC mandates climate-related financial disclosures that cascade into lease-level carbon accounting requirements, while the EU CSRD extends sustainability reporting to leased assets across member states. ISO 55000 asset management standards further shape platform specifications for governance and risk frameworks. Stakeholders must evaluate whether their current systems can absorb emerging ESG data layers without fragmenting into parallel point solutions.
Market Dynamics
Cloud-native lease abstraction platforms are compressing implementation timelines from 18-month enterprise rollouts to 90-day modular deployments, forcing incumbent vendors to rearchitect pricing and service models around API-first delivery.
Growth Catalysts
- SEC Climate Disclosure Mandates:Asset-level carbon accounting requirements under US regulations are driving landlords toward integrated compliance platforms that bundle lease data with ESG reporting workflows.
- Multi-Tenant Portfolio Complexity:Commercial real estate firms managing thousands of lease contracts are automating abstraction to reduce manual data entry errors in rent schedules and escalation clauses.
- API-Connected Dashboards:Real-time portfolio visibility tools are migrating spreadsheet-dependent finance teams to centralized lease administration systems with automated impairment calculations.
Market Restraints
- Data Migration Friction:Legacy lease repositories in unstructured PDF and scanned document formats impose heavy cleansing costs before platform ingestion.
- Specialized Talent Scarcity:Shortage of professionals combining lease accounting expertise with ASC 842 and IFRS 16 technical configuration skills inflates implementation consulting rates.
- Interoperability Gaps:Point solutions for abstracting, accounting, and compliance often require custom middleware to connect with corporate ERP systems.
Strategic Opportunities
- EU CSRD Extension:Sustainability reporting mandates for leased assets across member states create demand for carbon accounting modules that overlay existing lease management platforms.
- Predictive Analytics Convergence:Machine learning models trained on lease expiration patterns and market rent forecasts enable proactive renewal negotiations and impairment risk scoring.
- Mid-Market Channel Expansion:Partner networks of regional accounting firms and property management consultants offer lower-touch distribution for standardized cloud subscriptions.
Industry Challenges
- Cross-Functional Coordination:Lease management implementations require synchronized input from real estate, finance, legal, and IT departments with competing priorities and timelines.
- Standardization Delays:Inconsistent data field definitions across lessor documentation and jurisdictional lease formats complicate automated abstraction engine training.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lease Management Market |
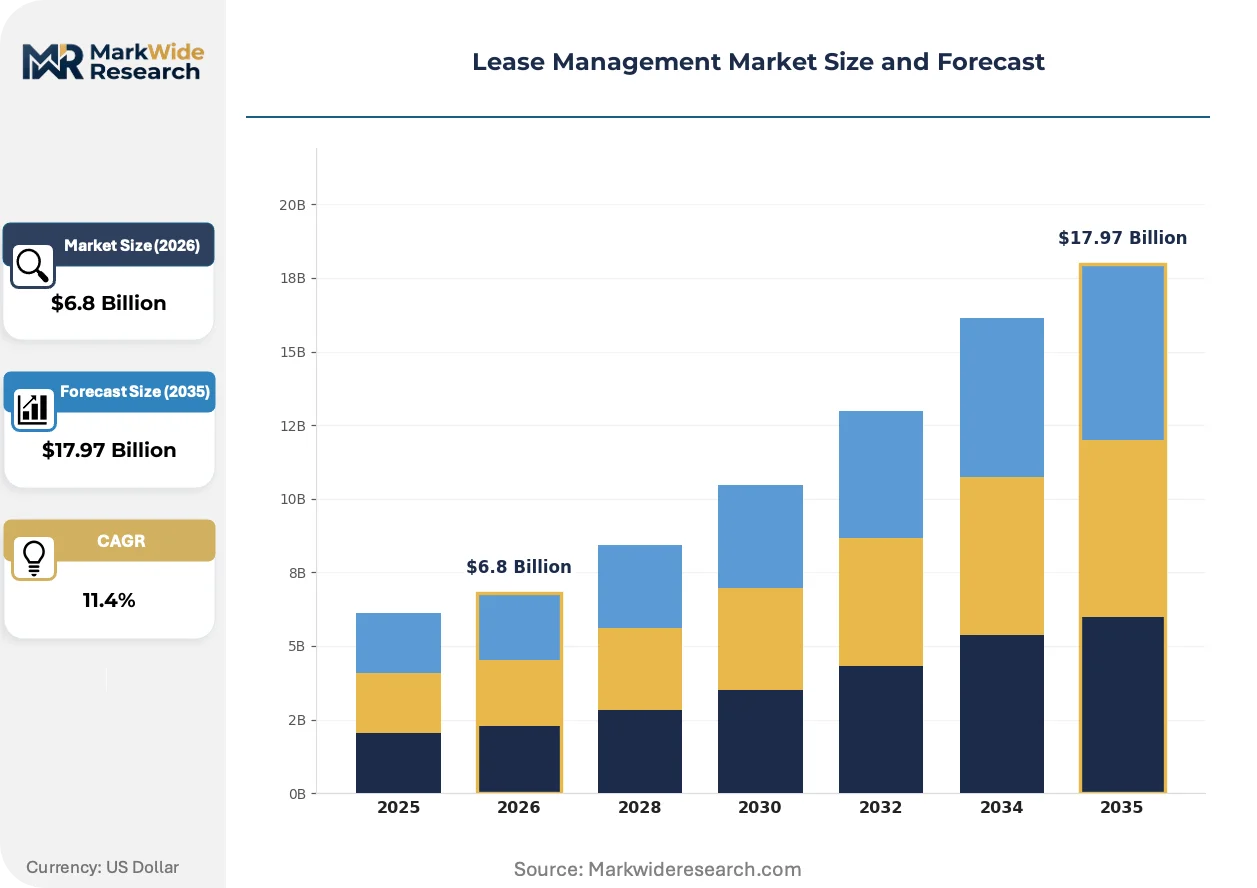
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Software, Consultancy Services, Cloud Solutions, Mobile Applications Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services End User: Retail, Corporate, Real Estate, Government Service Type: Support Services, Maintenance Services, Integration Services, Training Services |
| Companies Covered | Accruent, CoStar Group, IBM, Oracle, SAP, RealPage, LeaseAccelerator, Nakisa, Yardi Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lease Management Market Strategic Shifts & Innovations
Artificial intelligence is rewriting how lease obligations are extracted, validated, and analyzed, compressing document processing from hours to minutes while raising new questions about audit trail integrity and human oversight protocols.
Natural language processing engines are migrating from rules-based template matching to transformer-based comprehension of unstructured lease language. Mid-market property managers are piloting these tools for portfolio due diligence in acquisition scenarios. The technology is migrating from experimental deployments to production-grade abstraction pipelines that feed directly into accounting system journal entries.
The EU CSRD mandates granular sustainability disclosures for leased assets, extending carbon accounting obligations to previously exempt operational leases. Real estate investment trusts are retrofitting existing platforms with emissions tracking modules rather than procuring standalone ESG tools. European commercial landlords face the steepest compliance curves as member state regulators issue supplementary technical standards.
Buyers are unbundling implementation services from perpetual software licenses, preferring fixed-fee platform subscriptions with à la carte consulting for complex lease restructurings. Channel partners and independent accounting firms are capturing advisory revenue that previously accrued to primary vendors. This pattern is most pronounced in the United States, where institutional investors pressure operating partners to reduce technology procurement overhead.
Lease Management Market Segmentation
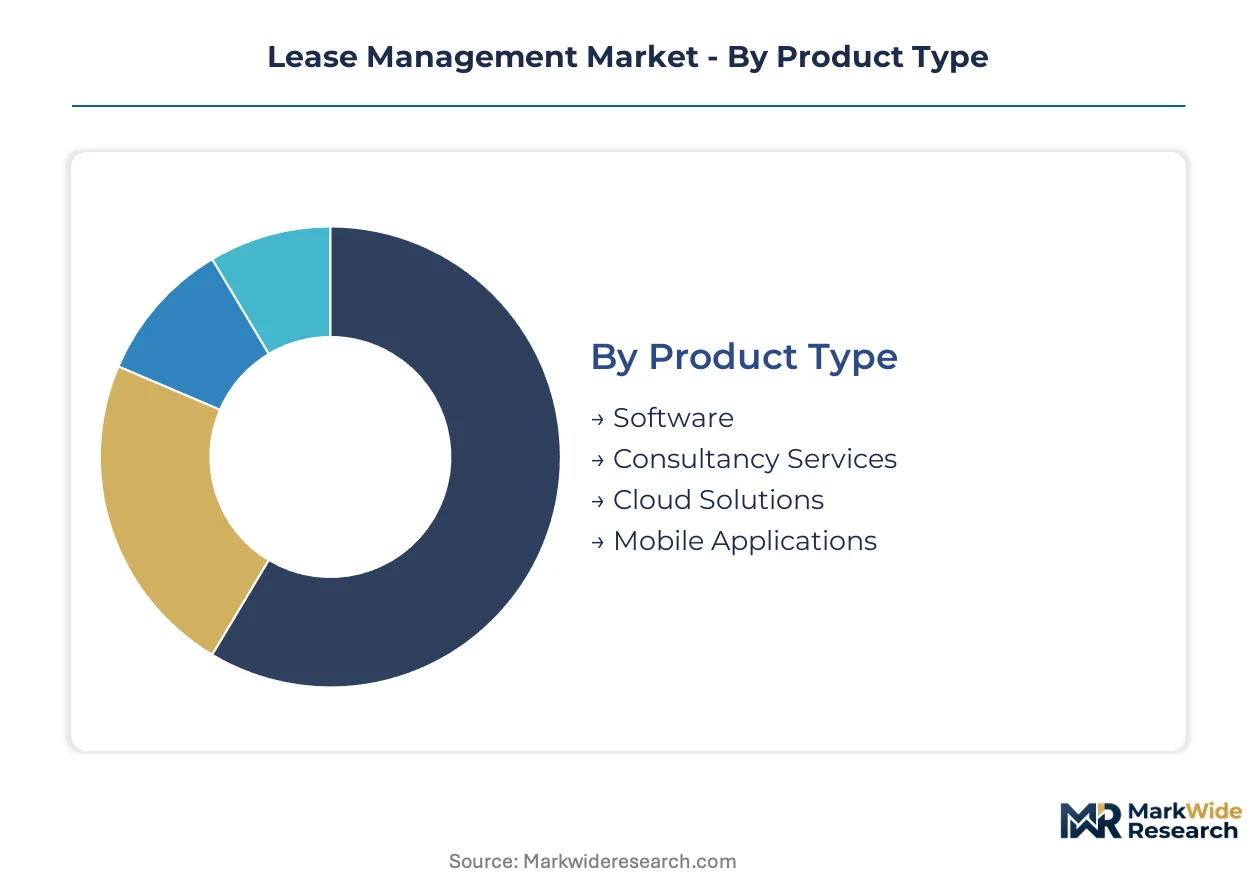
Lease management platforms fragment across deployment architectures, service delivery modes, and buyer sophistication levels. Each segmentation axis reveals distinct margin profiles and implementation complexity trade-offs that shape vendor positioning strategies.
Product Type:
Software solutions anchor the revenue base while service layers capture implementation complexity premiums across buyer segments.
- Software:Core platforms process lease data fields including rent schedules, escalation clauses, and impairment calculations under ASC 842 and IFRS 16 standards. Corporate real estate departments in the United States favor modular licensing that unbundles abstracting, accounting, and compliance functions to match portfolio scale.
- Cloud Solutions:API-connected architectures compress deployment timelines from multi-year enterprise rollouts to quarterly implementations. Real estate investment trusts migrating from spreadsheet governance drive concentration here, drawn by real-time portfolio dashboards and automated journal entry generation.
- Consultancy Services:Advisory revenue concentrates in complex lease restructurings and ASC 842 transition projects.
- Mobile Applications:Field-accessible tools for property managers handling multi-site inspections and tenant communications.
The dominant share belongs to Software, while Cloud Solutions is closing the gap fastest as institutional investors pressure operating partners to reduce technology procurement overhead.
Deployment:
Deployment choice correlates directly with buyer IT maturity and regulatory jurisdiction data residency requirements.
- Cloud-Based:Subscription pricing with automatic standard updates appeals to mid-market property managers lacking dedicated infrastructure teams. European commercial landlords face steeper compliance curves under CSRD technical standards, accelerating migration from on-premise legacy systems.
- On-Premise:Perpetual licenses persist among sovereign wealth funds and government agencies with stringent data localization mandates. These installations require heavy cleansing of unstructured PDF lease repositories before platform ingestion, inflating implementation timelines.
- Hybrid:Split architectures separate sensitive lease data on private infrastructure while leveraging cloud analytics layers.
- Managed Services:Outsourced administration models for smaller portfolios without internal lease accounting expertise.
Cloud-Based deployments command the installed base majority, though Hybrid configurations are expanding most quickly among regulated financial institutions.
End User:
Vertical specialization demands shape feature prioritization and sales cycle length across buyer categories.
- Real Estate:Investment trusts and property managers operating thousands of lease contracts require automated abstraction to reduce manual data entry errors. SEC climate disclosure mandates now require granular asset-level carbon accounting, pushing this segment toward integrated ESG reporting workflows.
- Corporate:Multi-location retailers and manufacturers balance lease administration against ERP integration requirements. These buyers unbundle implementation services from licenses, preferring fixed-fee subscriptions with à la carte consulting for complex restructurings.
- Retail:Franchise operators and chain stores with high location turnover velocity.
- Government:Public sector lessors with specialized procurement and transparency obligations.
Real Estate holds the revenue concentration, while Corporate verticals are gaining share fastest as distributed workforces expand lease footprints beyond traditional headquarters.
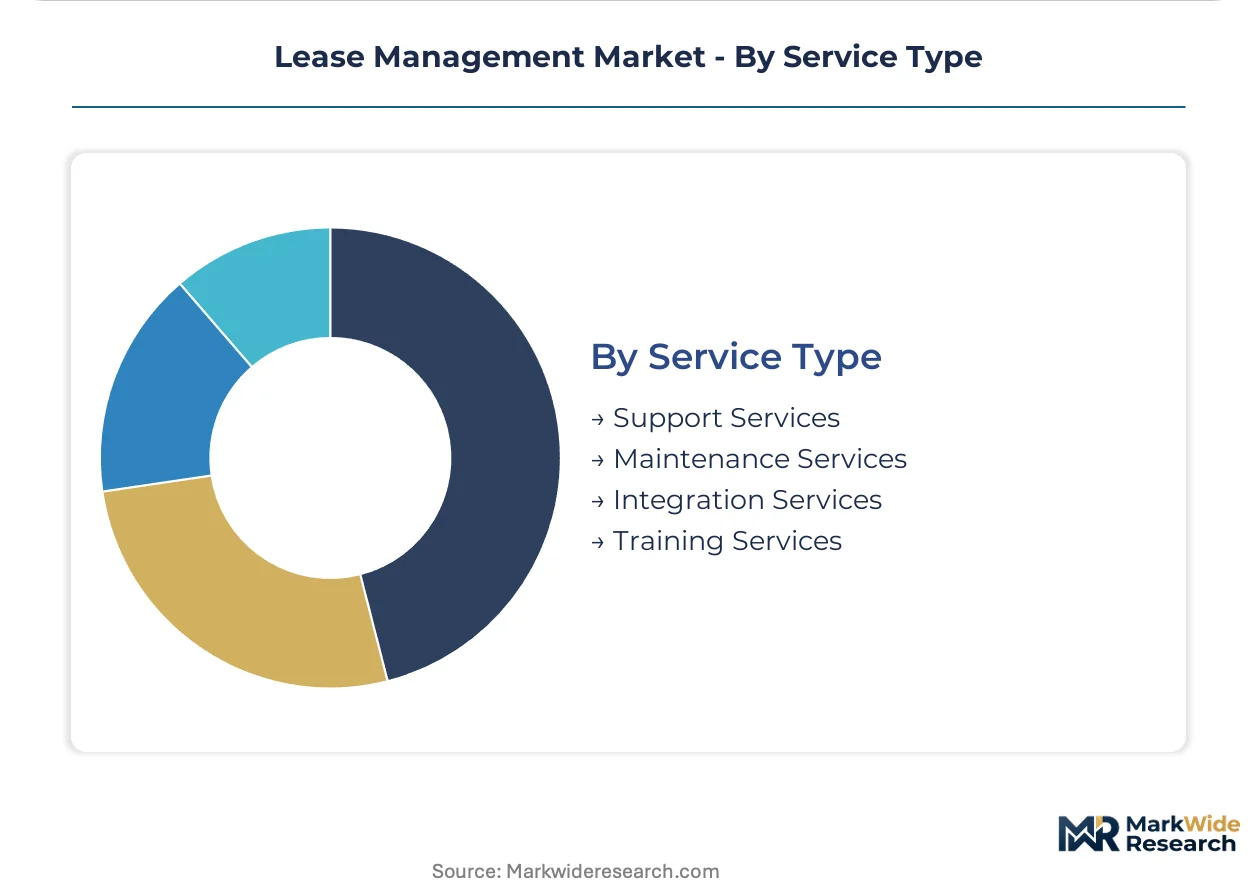
Service Type:
Post-sale service mix determines customer lifetime value and renewal elasticity across buyer tiers.
- Integration Services:Middleware development connecting point solutions for abstracting, accounting, and compliance to corporate ERP systems. These projects absorb scarce talent combining lease accounting expertise with technical configuration skills, inflating consulting rates.
- Support Services:Ongoing troubleshooting and platform optimization for live deployments. Channel partners and independent accounting firms increasingly capture this revenue that previously accrued to primary vendors.
- Training Services:User enablement programs for finance teams migrating from spreadsheet-dependent processes.
- Maintenance Services:Update management and security patching for on-premise installations.
Integration Services generates the highest margin pool, while Support Services is climbing the fastest as recurring revenue models displace perpetual license structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development for lease management concentrates heavily in the United States, with secondary engineering clusters in Germany and the United Kingdom supporting compliance module specialization. Cloud infrastructure deployment spans multiple jurisdictions as data residency requirements fragment hosting strategies.
United States
Institutional property owners operate the largest lease portfolios globally, driving demand for automated abstraction and real-time portfolio dashboards. SEC climate disclosure rules now mandate granular asset-level carbon accounting, pushing landlords toward integrated compliance platforms. New York and San Francisco anchor the vendor ecosystem, with enterprise software firms clustering around financial services corridors.
Germany
Corporate real estate departments prioritize ERP-native lease accounting solutions that integrate with existing financial workflows. EU CSRD technical standards extend sustainability reporting obligations to leased assets, accelerating migration from spreadsheet governance. Frankfurt and Munich host the densest concentration of implementation consultants combining lease accounting expertise with technical configuration skills.
United Kingdom
Real estate investment trusts favor API-connected architectures that compress deployment timelines from multi-year rollouts to quarterly implementations. GDPR data residency requirements shape hosting decisions for pan-European portfolios. London dominates advisory revenue for complex lease restructurings, while regional accounting firms capture mid-market channel expansion opportunities.
Japan
Manufacturers with distributed facility footprints balance lease administration against stringent data localization mandates. METI guidelines on asset management governance shape platform specifications for risk frameworks. Tokyo anchors demand for hybrid deployment models that separate sensitive lease data on private infrastructure while leveraging cloud analytics layers.
Australia
Superannuation funds with substantial property allocations drive adoption of predictive analytics for lease expiration pattern forecasting. TGA-equivalent financial reporting standards require impairment calculation rigor comparable to ASC 842 and IFRS 16. Sydney and Melbourne concentrate vendor support services as channel partners capture recurring revenue previously accruing to primary software vendors.
Lease Management Market Key Industry Players
Enterprise software conglomerates and specialized property technology vendors split the market along integration depth versus vertical specialization lines. Consolidation pressure intensifies as cloud-native entrants compress implementation timelines from 18-month enterprise rollouts to 90-day modular deployments. Two strategic archetypes dominate: database-centric platforms bundling lease accounting with broader ERP workflows, and asset management specialists delivering purpose-built tools for multi-tenant portfolios. Competitive moves center on API-first delivery rearchitecture and mid-market channel expansion through regional accounting firm partnerships.
Within the enterprise software tier, Oracle and SAP exemplify database-centric positioning, leveraging enterprise infrastructure footprints to embed lease functionality within broader financial workflows. Yardi Systems occupies a specialized position anchored in North American multi-family and commercial property verticals. These three represent divergent strategic bets on integration breadth versus domain depth.
| Leading Market Players |
|---|
| Accruent |
| CoStar Group |
| IBM |
| Oracle |
| SAP |
| RealPage |
| LeaseAccelerator |
| Nakisa |
| Yardi Systems |
| Others |
Cost & Logistics Intelligence
Trans-Pacific fiber routes linking San Francisco data centers to Singapore cloud regions transmit the cost volatility of GPU compute and storage tiers directly into lease management SaaS pricing, concentrating margin pressure on vendors without captive infrastructure while amplifying price differentiation between API-native platforms and legacy on-premise installations.
Pricing Analysis
ASC 842 and IFRS 16 compliance mandates dictate the pricing tier structure across the lease management landscape. Three-tier pricing structure across premium, standard, and economy levels separates enterprise-grade ERP-integrated suites from modular cloud subscriptions and basic abstraction tools. Price differentiation rests on certification depth—SOC 2 Type II and ISO 27001 tiers command 40-60% premiums—and vertical specialization for commercial real estate versus general corporate use. Cost compression in the mid-market tier is intensifying because channel partners and regional accounting firms are unbundling implementation services from software licenses. Corporate real estate departments at institutional property owners show least price sensitivity, while mid-market property managers with sub-thousand lease portfolios negotiate aggressively on per-seat subscription rates.
Supply Chain Analysis
Upstream compute infrastructure feeds from hyperscaler data center concentrations in the United States, Ireland, and Singapore, with secondary clustering in Frankfurt and Tokyo for data residency compliance. Cloud-native lease management platforms draw from NVIDIA GPU allocations for AI abstraction engines, specialized document processing hardware, and API gateway bandwidth. Single-source vulnerability concentrates in foundation model providers powering natural language processing for lease extraction, where two vendors dominate enterprise-grade deployments. Distribution runs through direct enterprise sales teams for large real estate investment trusts, regional system integrators for mid-market rollouts, and accounting firm channel partners for standardized compliance modules.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lease management market functions as a switching-cost fortress, where ASC 842 and IFRS 16 compliance entrenchment creates durable revenue visibility for vendors that capture initial enterprise deployments.
For Market Incumbents: Build data network effects by aggregating anonymized lease benchmarks across client portfolios to train proprietary market rent forecasting models. Incumbents should deepen ERP integration moats through exclusive API partnerships with Oracle and SAP while accelerating carbon accounting module development ahead of EU CSRD enforcement timelines. Cloud-native entrants with 90-day deployment capabilities threaten traditional 18-month implementation cycles, demanding rapid rearchitecture of service delivery models around modular, API-first delivery. For New Entrants and Emerging Players: Southeast Asian commercial property markets offer the most penetrable geography, where institutional capital inflows from Singaporean and Australian pension funds outpace local platform sophistication. New entrants should target mid-market Japanese manufacturers with distributed facility footprints, where METI governance guidelines create compliance urgency without entrenched vendor relationships. A channel-first go-to-market through regional property management consultants enables lower customer acquisition costs than direct enterprise sales. For Investors and Strategic Acquirers: Specialized asset management vendors with native ESG reporting capabilities represent the most attractive acquisition archetype, as sustainability disclosure mandates compound software valuation premiums. Long-term viability hinges on platforms' capacity to absorb emerging data layers—carbon accounting, predictive impairment scoring—without fragmenting into point solutions. Watch for inflection signals in channel partner revenue mix shifts, where independent accounting firms capturing implementation consulting indicates platform commoditization pressure.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Platform Rearchitecture | Compresses deployment timelines from multi-year rollouts to quarterly implementations for real estate investment trusts. |
| Carbon Accounting Module Development | Addresses SEC climate disclosure mandates requiring granular asset-level emissions tracking for leased portfolios. |
| Channel Partner Network Expansion | Captures mid-market advisory revenue previously accruing to primary vendors through regional accounting firm partnerships. |
| ERP-Native Integration Investment | Embeds lease functionality within broader financial workflows to increase switching costs and renewal elasticity. |
| Predictive Analytics Acquisition | Machine learning models trained on lease expiration patterns enable proactive renewal negotiations and impairment risk scoring. |
Research Approach
A standing panel of commercial real estate CIOs, lease accounting directors at Fortune 500 manufacturers, property management firm operations leads, and ERP implementation consultants provided ongoing calibration throughout the study period. Primary interview insights triangulated against secondary sources including SEC climate disclosure filings, EU CSRD technical standards documentation, ISO 55000 asset management guidelines, and hyperscaler infrastructure capex disclosures. Bottom-up lease portfolio sizing across end-user segments combined with top-down software spending estimates from corporate IT budget surveys.
Scenario-bracketing around regulatory enforcement timelines and cloud migration velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, buyer sophistication tier, vertical specialization, and geographic regulatory cluster. CAGRs derived from cohort-level adoption curves weighted by implementation timeline compression observed in recent cloud-native deployments. Forecast inputs incorporated AI abstraction engine accuracy improvements and ESG reporting module attach rates.
Practitioners should monitor SEC enforcement discretion on climate disclosure deadlines and EU member state CSRD technical standard finalizations for early signals of compliance-driven procurement acceleration. Forecasts embed assumptions regarding cloud infrastructure cost trajectories and foundation model provider concentration. Cross-checking against vendor-reported implementation timeline disclosures and channel partner revenue mix shifts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
United States Self Storage Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
Canada Real Estate Services Market
Real Estate Services
US Home Service Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Home Warranty Service Market
Real Estate Services
Property Tax Services Market