
 GCC Interior Design Services Market | 2026-2036
GCC Interior Design Services Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Interior Design Services Market Foresight
Design-build contracting is rewriting how interior design services reach property developers across the Gulf. Dewan Architects + Engineers leverages its integrated architecture-to-fit-out model to control project timelines from concept to handover. Hirsch Bedner Associates anchors its regional presence through hospitality specialization, sustaining long-term relationships with luxury hotel operators. Woods Bagot competes on workplace strategy expertise, extending its advisory services beyond aesthetics into organizational performance design.
GCC interior design services encompass spatial planning, material specification, lighting design, and custom furniture curation for built environments, typically governed by local fire safety codes, accessibility standards, and cultural requirements for privacy and gender separation. The discipline serves commercial, residential, and institutional clients seeking environments that balance functionality with brand expression. Hospitality design leads service revenue pools given the region's sustained luxury hotel construction, while multi-unit developments under project scale are capturing accelerated interest from institutional investors seeking standardized, repeatable design packages across portfolio assets. Corporate offices within client type represent a mature but high-volume segment where design firms differentiate through technology integration and wellness certification rather than pure aesthetics.
Saudi Building Code and UAE Fire and Life Safety Code establish baseline compliance thresholds for materials, egress, and accessibility across all interior fit-outs, with Dubai Municipality and Saudi Standards, Metrology and Quality Organization enforcing conformance through permitting workflows. MOHAP and relevant emirate-level health authorities impose additional clinical environment standards for healthcare interiors, narrowing vendor eligibility and extending project timelines. Stakeholders must monitor how evolving green building mandates across Gulf jurisdictions reshape material procurement and designer competency requirements.
Market Dynamics
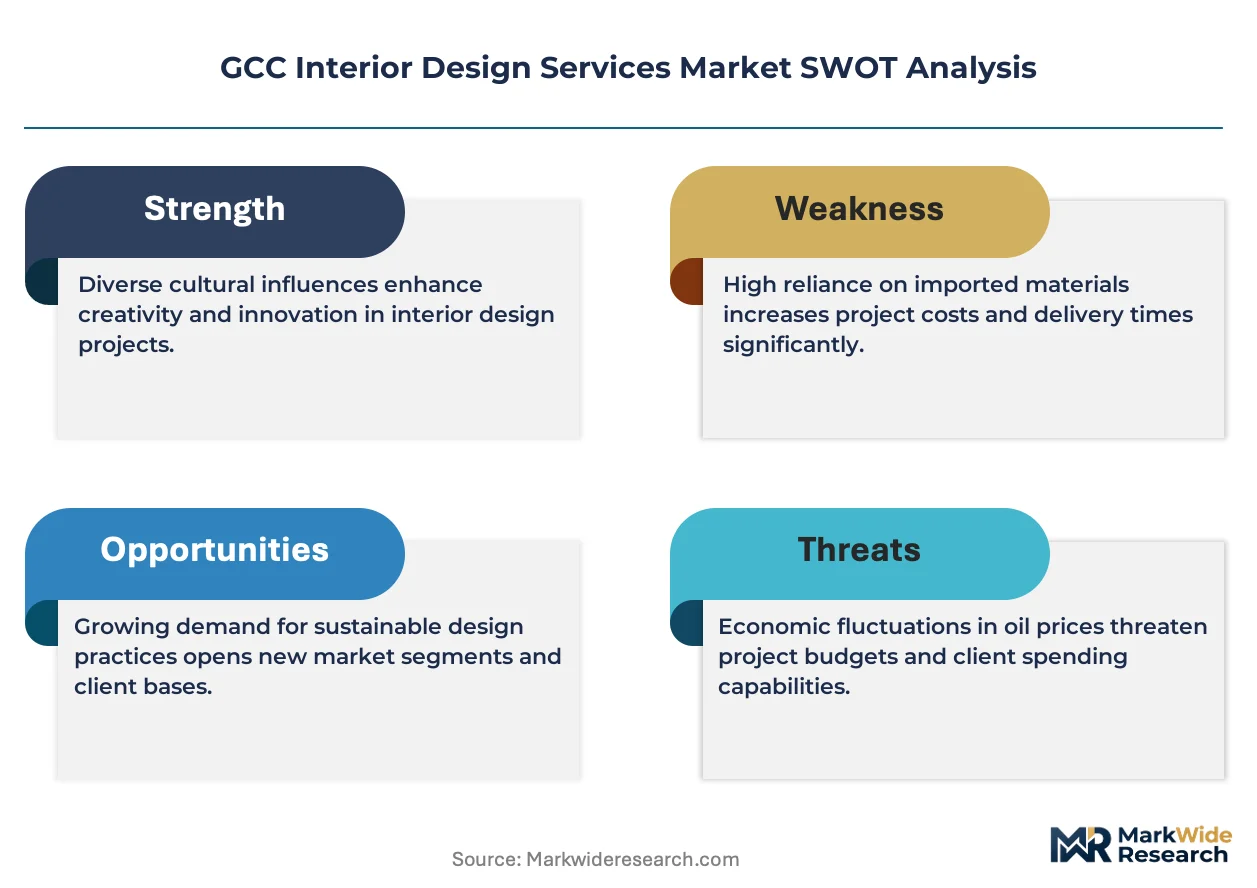
Saudi Vision 2030 mandates for sustainable building standards are compressing procurement timelines and forcing material specification changes across hospitality and commercial fit-out projects. Design-build contracting is consolidating vendor relationships as developers seek single-point accountability from concept through handover.
Growth Catalysts
- Hospitality Fit-Out Acceleration:Luxury hotel developments across Dubai and Riyadh are driving compressed design cycles and premium material demand from international suppliers.
- Saudi Building Code Evolution:Enhanced fire safety and accessibility requirements are expanding mandatory design review scopes and professional certification needs for fit-out specialists.
- Modular Construction Integration:Prefabricated interior systems are reducing on-site labor dependency and enabling faster project delivery for multi-unit residential portfolios.
Market Restraints
- Specialized Material Import Dependency:High-performance finishes and certified fire-resistant substrates concentrate sourcing from European and East Asian suppliers, exposing projects to freight cost volatility and extended lead times.
- Skilled Labor Pool Constraints:Technical competency in Building Information Modeling and sustainable material specification remains concentrated among a limited cohort of accredited professionals across the Gulf.
- Permitting Workflow Friction:Multi-layer approvals through Dubai Municipality and Saudi Standards, Metrology and Quality Organization extend project initiation timelines and compress design phase budgets.
Strategic Opportunities
- Kuwait Institutional Pipeline:Government healthcare and education infrastructure programs are generating demand for standardized, repeatable interior packages from design firms with regional delivery capability.
- Wellness Certification Premium:WELL Building Standard and Fitwel accreditation requirements from corporate occupiers are creating advisory service revenue streams beyond traditional spatial design.
- Digital Twin Convergence:Integration of IoT sensor networks with 3D spatial modeling is enabling predictive maintenance contracts and long-term facility management relationships for design practices.
Industry Challenges
- BIM Coordination Complexity:Multi-disciplinary model integration between architecture, MEP, and interior specialists generates rework costs and schedule slippage on large-scale mixed-use developments.
- MOHAP Healthcare Compliance:Clinical environment standards for infection control and medical gas systems narrow vendor eligibility and extend documentation requirements for hospital fit-out projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Interior Design Services Market |
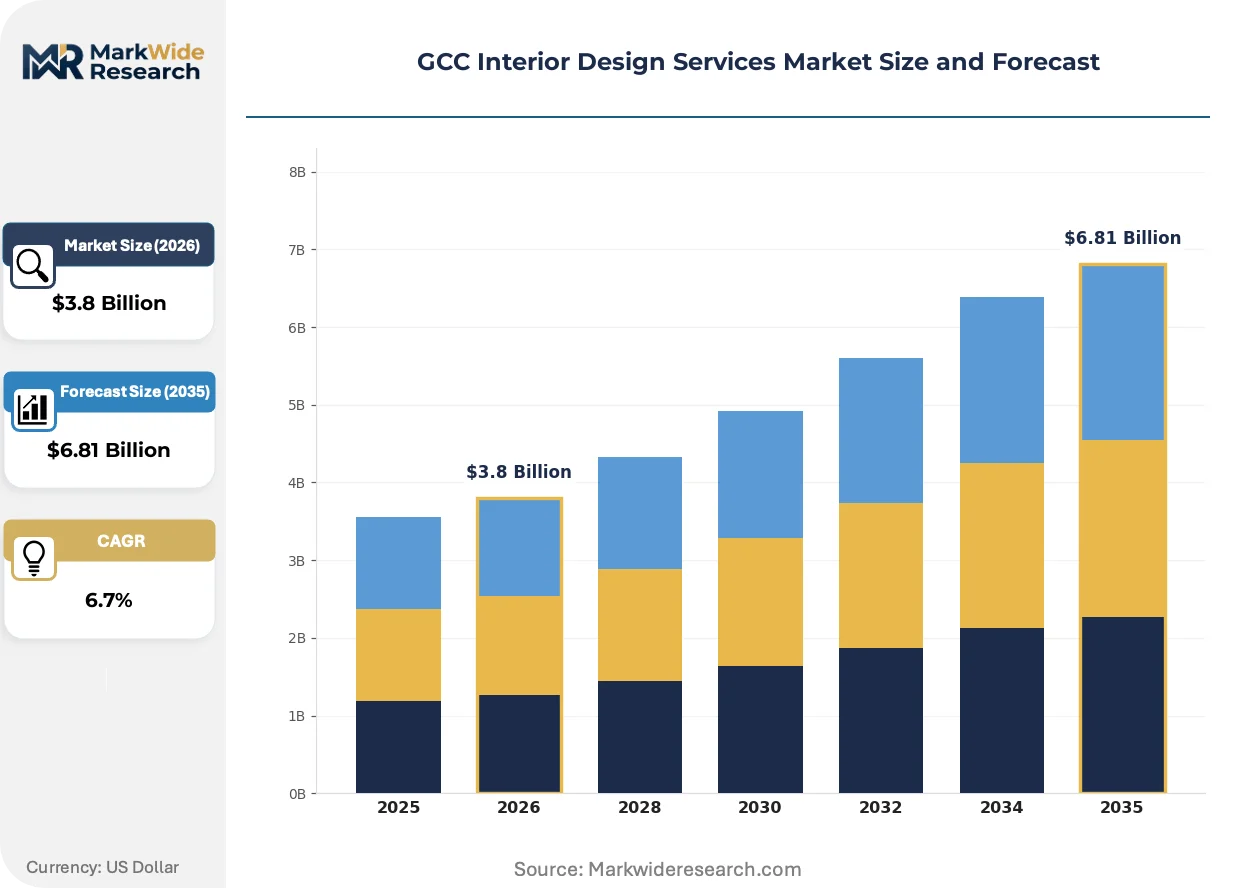
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Residential Design, Commercial Design, Hospitality Design, Institutional Design, Landscape Design Project Scale: Small Scale, Medium Scale, Large Scale, Multi-Unit Developments Client Type: Individual Homeowners, Corporate Offices, Property Developers, Public Sector Entities, Educational Institutions Design Style: Modern, Contemporary, Traditional, Minimalist, Eclectic |
| Companies Covered | Dewan Architects + Engineers, Hirsch Bedner Associates, Gensler, Woods Bagot, Aedas, Atkins, Depa, CallisonRTKL, KEO International Consultants, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Interior Design Services Market Shifts & Advancements
Computational design tools and material science advances are compressing the traditional boundary between aesthetic conception and technical execution. Firms that embed performance data into early-stage spatial planning are capturing advisory relationships that extend beyond project handover.
Parametric design software is digitizing how interior spaces respond to environmental performance targets. Hospitality operators in Dubai are adopting generative algorithms to optimize daylight penetration and thermal comfort across guest room clusters. This capability is digitizing the traditional silo between architect and interior designer, enabling real-time material specification adjustments based on energy modeling outputs.
Saudi Arabia's adoption of green building mandates through the Saudi Building Code is mandating lifecycle assessment documentation for interior materials. Project teams must now submit embodied carbon calculations and end-of-life disposal plans as part of permitting workflows. Healthcare and education segments face the steepest compliance curves, with MOHAP and the Ministry of Education respectively tightening procurement specifications around low-VOC finishes and recycled content thresholds.
Corporate occupiers are unbundling design services from traditional lump-sum contracts, favoring phased engagements that separate strategy, documentation, and implementation oversight. This purchasing pattern disrupts legacy fee structures and rewards firms with dedicated workplace research capabilities. The shift is most pronounced in Dubai's financial district, where multinational tenants rotate design partners based on post-occupancy performance data rather than portfolio precedent alone.
GCC Interior Design Services Market Segmentation
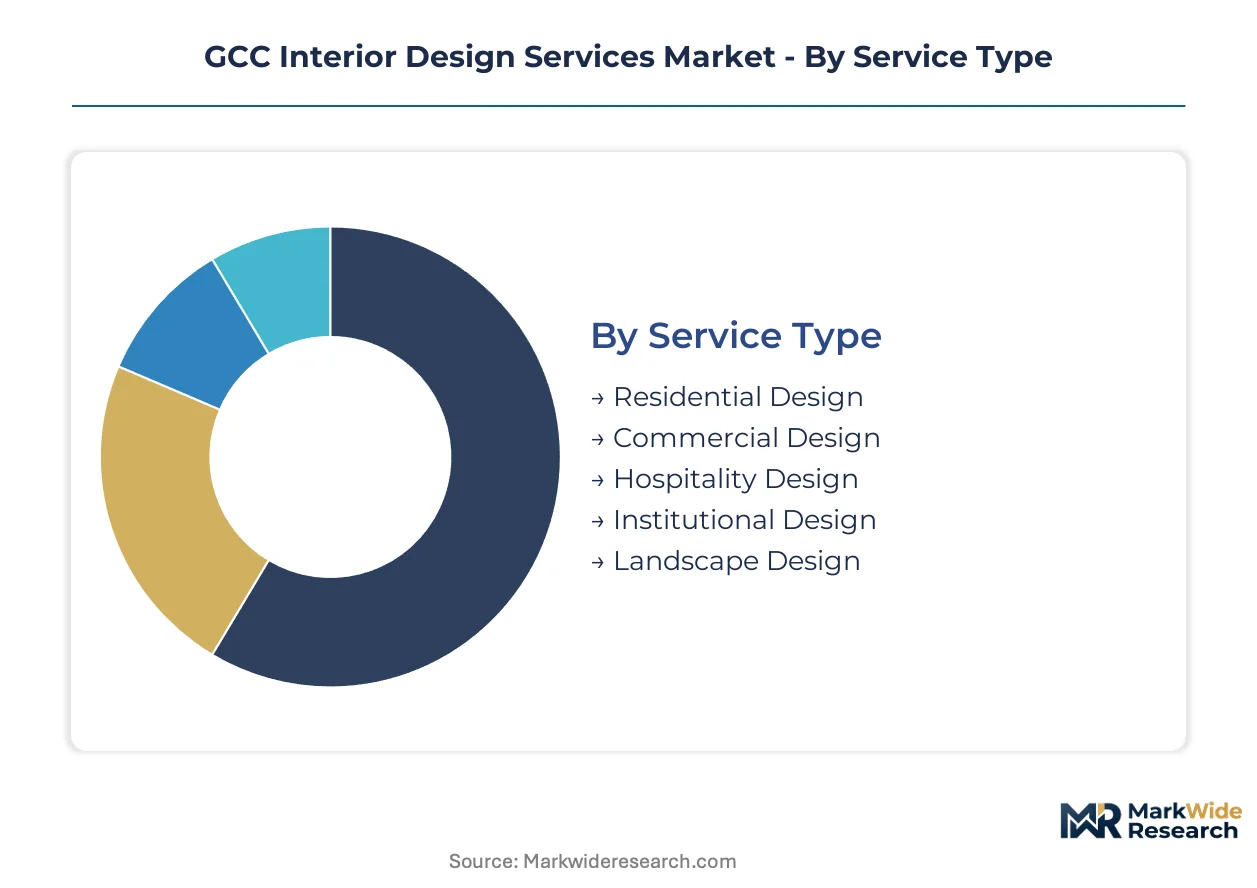
Interior design services in the Gulf Cooperation Council fragment across service specializations, project magnitudes, and client procurement patterns. Each dimension shapes fee structures, talent requirements, and regulatory exposure differently.
Service Type:
Cost tier differentiation separates commoditized spatial planning from advisory-intensive verticals requiring specialized certification and technical coordination.
- Hospitality Design:Luxury hotel fit-outs demand fire-rated material specifications and guest experience choreography across lobbies, suites, and F&B outlets. Dubai's sustained pipeline of five-star developments compresses design cycles and sustains premium fee multiples for firms with operator relationships.
- Commercial Design:Workplace strategy services now extend beyond aesthetics into organizational performance, wellness certification, and technology integration. Corporate occupiers in Dubai International Financial Centre unbundle traditional lump-sum contracts into phased engagements separating strategy from implementation.
- Residential Design:High-net-worth individual commissions in Emirates Hills and Riyadh's Diplomatic Quarter emphasize bespoke furniture curation and smart home integration.
- Institutional Design:Healthcare and education interiors face MOHAP and Ministry of Education procurement specifications around infection control and low-VOC finishes.
- Landscape Design:Outdoor spatial planning for mixed-use developments integrates irrigation engineering and native plant specification under Dubai Municipality landscaping codes.
Hospitality design commands the established base. The steepest expansion runs through institutional verticals as Saudi healthcare and education infrastructure programs accelerate.
Project Scale:
Volume concentration and margin structure diverge sharply between bespoke commissions and repeatable multi-unit packages favored by institutional investors.
- Multi-Unit Developments:Standardized interior packages across residential portfolios enable design firms to amortize documentation costs and capture recurring maintenance contracts. Saudi giga-projects and Dubai's build-to-rent pipeline favor this procurement model.
- Large Scale:Mixed-use developments exceeding 50,000 square meters require BIM coordination across architecture, MEP, and interior disciplines. Rework costs from model integration failures compress design phase margins.
- Medium Scale:Boutique hospitality and corporate headquarters fit-outs balance customization depth with manageable coordination complexity.
- Small Scale:Individual residential renovations and retail fit-outs concentrate in Dubai's established neighborhoods and Jeddah's historic district adaptive reuse projects.
Multi-unit developments concentrate procurement volume. Large-scale projects absorb the most specialized technical capacity.
Client Type:
Customer sophistication and decision-making velocity shape engagement structures from single-point homeowner relationships to multi-stakeholder public procurement.
- Property Developers:Master developers across Dubai South and Riyadh's King Abdullah Financial District drive design-build consolidation, seeking single-point accountability from concept through handover.
- Corporate Offices:Multinational tenants rotate design partners based on post-occupancy performance data rather than portfolio precedent alone.
- Public Sector Entities:Ministry of Health and Ministry of Education procurement mandates standardized documentation, extended vendor qualification, and lifecycle cost analysis.
- Individual Homeowners:Ultra-high-net-worth commissions in Abu Dhabi's Saadiyat Island and Doha's Pearl-Qatar emphasize privacy, cultural requirements for gender separation, and art integration.
- Educational Institutions:University expansions in Kuwait and Saudi Arabia generate demand for flexible learning environments and biophilic design under tightened sustainability procurement rules.
Property developers anchor current revenue. Corporate offices are gaining share fastest through workplace advisory expansion.
Design Style:
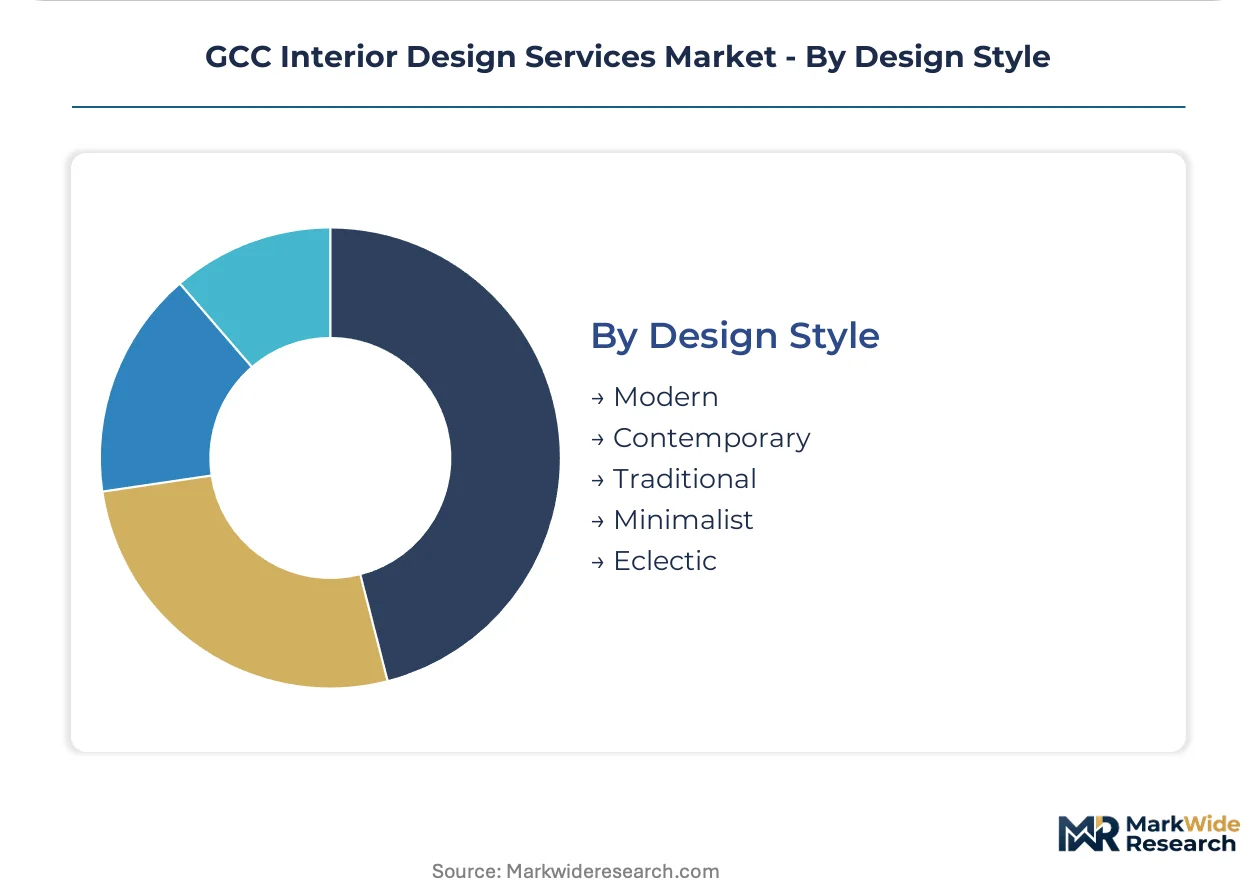
Application context and material specification intensity vary across aesthetic traditions, with regulatory and climatic factors constraining certain approaches in the Gulf environment.
- Modern:Clean lines and open plans dominate commercial and hospitality applications, though Saudi Building Code fire safety requirements mandate compartmentalization that modifies pure open concepts.
- Contemporary:Adaptive aesthetics blending regional motifs with international standards prevail in luxury residential and diplomatic interiors across Abu Dhabi and Doha.
- Traditional:Mashrabiya screens, courtyard configurations, and ornamental plasterwork concentrate in heritage hospitality projects and royal palace commissions.
- Minimalist:Reduced material palettes and concealed storage systems appeal to younger corporate executives in Dubai's Business Bay residential towers.
- Eclectic:Curated mixing of periods and provenances requires sophisticated procurement from international auction houses and artisan networks, limiting scalability.
Contemporary styling holds the broadest addressable base. Modern applications are climbing the fastest as wellness certification and daylight optimization priorities reshape specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jebel Ali Port and the Khalifa Port corridor underpin the UAE's logistics supremacy, channeling European and East Asian material flows into Gulf fit-out projects. Saudi Arabia's Riyadh-Qiddiya high-speed rail link and NEOM linear city infrastructure are redistributing design demand northward. Kuwait's Mubarak Al-Kabeer Port expansion connects the northern Gulf to international supplier networks.
United Arab Emirates
Dubai's commercial mega-project pipeline and Abu Dhabi's Saadiyat Island cultural district sustain hospitality and luxury residential fit-out volumes. Dubai Municipality enforces Fire and Life Safety Code compliance through multi-layer permitting workflows. The Dubai Design District cluster concentrates international design studios serving regional developer accounts.
Saudi Arabia
NEOM, Qiddiya, and Red Sea Project giga-developments are compressing procurement timelines for standardized interior packages. Saudi Building Code mandates for sustainable materials and lifecycle assessment documentation reshape vendor eligibility. Riyadh's King Abdullah Financial District anchors corporate workplace design demand from multinational tenants.
Kuwait
Government healthcare infrastructure programs under the Ministry of Health generate institutional interior demand with extended documentation requirements. The Public Authority for Industry enforces standardized procurement specifications for educational facilities. Kuwait City's healthcare cluster concentrates hospital fit-out projects requiring MOHAP-equivalent infection control standards.
Qatar
Post-World Cup hospitality asset repositioning sustains interior renovation cycles across Doha's hotel inventory. Qatar General Organization for Standardization maintains material certification requirements aligned with Gulf standardization initiatives. The Pearl-Qatar and Lusail developments concentrate ultra-high-net-worth residential commissions emphasizing smart home integration.
Bahrain
Financial services sector expansion in Manama's Diplomatic Area drives corporate workplace fit-out demand. The Ministry of Works mandates accessibility standards for public sector interiors. Bahrain Bay and Diyar Al Muharraq mixed-use developments attract regional design firms seeking mid-scale project diversification.
GCC Interior Design Services Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material specification and custom fabrication. The vendor base organizes around three strategic archetypes: full-service design-build operators, hospitality-specialized studios, and workplace strategy consultancies. Consolidation pressure intensifies as developers seek single-point accountability from concept through handover. Dominant competitive moves include design-build contracting consolidation and advisory service portfolio expansion into wellness certification and post-occupancy performance.
Within the integrated architecture-to-fit-out tier, Dewan Architects + Engineers exemplifies the design-build consolidation archetype controlling project timelines across concept phases. Hirsch Bedner Associates occupies a position representing hospitality specialization sustained through operator relationship depth. Woods Bagot anchors the workplace strategy vector extending advisory services beyond spatial aesthetics into organizational performance design. These three entities collectively illustrate how service model differentiation supersedes geographic origin in regional competitive positioning.
| Leading Market Players |
|---|
| Dewan Architects + Engineers |
| Hirsch Bedner Associates |
| Gensler |
| Woods Bagot |
| Aedas |
| Atkins |
| Depa |
| CallisonRTKL |
| KEO International Consultants |
| Others |
Supply & Pricing Matrix
Italian marble quarries and German fire-rated substrate manufacturers anchor the premium tier's cost base, concentrating margin capture upstream while Gulf-based fit-out contractors compete on installation velocity and design-build bundling rather than material sourcing control.
Pricing Analysis
Volume-discount tiering separates property developer portfolios from individual residential commissions. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and customization depth. Cost compression in the standard tier is intensifying because Saudi Building Code mandates force lifecycle assessment documentation overhead. Property developers exhibit lowest price sensitivity given design-build consolidation priorities, while individual homeowners in secondary Gulf markets drive hardest bargain scrutiny.
Supply Chain Analysis
Tariff exposure between European Union member states and Gulf Cooperation Council jurisdictions dominates landed cost volatility for certified fire-resistant finishes. Material flows draw from Italy, Germany, and China for surface finishes, textiles, and modular systems respectively. Single-source vulnerability concentrates in specialized healthcare-grade substrates meeting MOHAP infection control standards. Distribution runs through Jebel Ali Port and Khalifa Port corridor consolidation points before last-mile fit-out contractor deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Design-build contracting consolidation threatens traditional fee-for-service studios as developers demand single-point accountability, forcing incumbents to defend against disintermediation by platform integrators.
For Market Incumbents: Harden advisory service moats through WELL Building Standard and Fitwel certification investment, embedding post-occupancy performance data capabilities that resist commoditization. Deepen backward integration into custom furniture fabrication to capture margin pools currently leaking to European artisan networks. Design-build operators like Dewan Architects + Engineers exemplify the consolidation threat eroding pure-play design fees.
For New Entrants and Emerging Players: Pursue Kuwait's Ministry of Health healthcare infrastructure pipeline where standardized, repeatable interior packages face limited regional competition. Target Bahrain's mid-scale financial services workplace fit-outs in Manama's Diplomatic Area, a geography receiving insufficient attention from Dubai- and Riyadh-focused studios. Lead with digital twin and IoT-integrated spatial modeling as differentiated entry proposition.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed hospitality-specialized studios carrying legacy operator relationships but lacking technology integration capabilities. Long-term viability hinges on advisory service revenue expansion beyond lump-sum project fees. Watch for Saudi giga-project procurement pauses as inflection signal for portfolio rebalancing toward institutional healthcare and education verticals.
| Strategic Initiative | Industry Significance |
|---|---|
| Design-Build Consolidation | Dewan Architects + Engineers demonstrates timeline control from concept through handover. |
| Wellness Certification Investment | WELL and Fitwel accreditation opens advisory revenue streams beyond spatial design. |
| Digital Twin Integration | IoT sensor convergence with 3D modeling enables predictive maintenance contracts. |
| Modular Construction Partnership | Prefabricated interior systems reduce on-site labor dependency for multi-unit portfolios. |
| Regional Delivery Capability Buildout | Kuwait and Bahrain expansion captures institutional pipeline diversification. |
Research Methodology
A spread of perspectives from hospitality design directors, healthcare facility planners, property developer procurement leads, and fit-out contractor project managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against Dubai Municipality permitting records, Saudi Standards Metrology and Quality Organization regulatory filings, and customs data tracking Italian marble and German substrate import volumes. Bottom-up project pipeline enumeration triangulated against top-down construction sector expenditure estimates.
Demand-supply-balance framing anchored the analytical approach across the analysis window, modeling service type segmentation alongside project scale tiers and client procurement patterns. CAGRs derived from fitted growth curves incorporating hospitality fit-out acceleration, Saudi green building mandate compliance cost trajectories, and modular construction adoption rates. BIM coordination complexity and skilled labor pool constraints entered as supply-side ceiling variables.
Sensitivities concentrate around Saudi giga-project timeline adjustments, freight cost volatility for European material imports, and permitting workflow friction extensions. Forecasts reflect documented assumptions on regulatory enforcement intensity and developer consolidation preferences. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
United States Self Storage Market
Real Estate Services
Egypt Real Estate Brokerage Market
Real Estate Services
Asia-Pacific Real Estate Brokerage Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
Switzerland Self-Storage Market
Real Estate Services
Global Self Storage Market
Real Estate Services
Public Warehousing Market
Real Estate Services
Warehousing and Storage Services Market
Real Estate Services
Co-Working Space Services Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
Relocation Management Service Market
Real Estate Services
Property Tax Services Market
Real Estate Services
Singapore Self-Storage Market
Real Estate Services
Second-Hand Housing Trading Platform Market
Real Estate Services
Germany Self-Storage Market