
 Latin America Coworking Spaces Market | 2026-2036
Latin America Coworking Spaces Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Coworking Spaces Market Foresight
CE marking harmonization for commercial building safety is consolidating operational standards across Latin American coworking operators. WeWork leverages its capital reserves to sustain premium locations in São Paulo and Mexico City. Selina anchors its hybrid hospitality-coworking model in tourist-centric urban zones. IWG/Regus dominates suburban and secondary-city penetration through its franchise-heavy footprint.
Latin America coworking spaces are commercial real estate assets that combine flexible lease structures, shared infrastructure, and technology-enabled access control to deliver on-demand workspace solutions for mobile professionals and small enterprises. These facilities typically integrate high-speed connectivity, ergonomic furnishings, and climate systems designed for density levels of 4-6 square meters per occupant. Private offices command the deepest margin pools across the space type dimension, while hot desks represent the fastest-growing category as price-sensitive freelancers and startups prioritize cost efficiency over permanence. Corporate partnerships within the business model segment are expanding fastest, as enterprise clients outsource satellite office needs to third-party operators rather than committing to direct leases.
ANVISA in Brazil, COFEPRIS in Mexico, and local municipal zoning boards across Argentina and Colombia shape health, safety, and commercial use approvals that determine where coworking facilities can operate and at what compliance cost. ISO 45001 occupational health standards and country-specific fire codes increasingly appear in operator certification portfolios as enterprise clients mandate documented workplace safety. Stakeholders must monitor how municipal tax treatment of flexible workspace providers evolves, as reclassification from service to real estate taxation would compress operator margins and redirect investment toward jurisdictions with lighter fiscal burdens.
Market Dynamics
Enterprise satellite office outsourcing is compressing traditional lease cycles across Latin America, as multinational technology and professional services firms abandon direct commercial real estate commitments in favor of flexible third-party workspace arrangements. This structural shift redistributes occupancy risk from corporate balance sheets to specialized operators while accelerating demand for ISO-certified facilities with documented health and safety protocols.
Growth Catalysts
- ANVISA Regulatory Modernization:Brazil's streamlined health-tech and fintech compliance frameworks are lowering operational barriers for specialized coworking operators serving regulated industries in São Paulo.
- Technology Startup Density:Venture-backed software companies across Mexico City and Buenos Aires are absorbing flexible office inventory at rates that outpace legacy professional services tenants.
- ISO 45001 Certification Mandates:Enterprise procurement departments are requiring documented occupational health standards, filtering contract awards toward certified operators with compliant safety management systems.
Market Restraints
- Municipal Tax Reclassification Risk:Local governments in Argentina and Colombia are evaluating flexible workspace providers for potential reclassification from service to real estate taxation, which would compress operator margins.
- Secondary City Infrastructure Gaps:Broadband reliability and power grid stability in Brazilian interior markets outside São Paulo limit expansion feasibility for technology-dependent operators.
- Commercial Lease Rate Volatility:Dollar-denominated rental obligations in Buenos Aires create currency mismatch exposure for operators generating peso-denominated membership revenue.
Strategic Opportunities
- COFEPRIS-Aligned Health-Tech Clusters:Mexico's pharmaceutical regulator is enabling specialized laboratory-grade coworking facilities in Mexico City for medical device and biotech startups requiring controlled environments.
- Hybrid Hospitality Convergence:Operators integrating extended-stay accommodation with workspace access are capturing digital nomad and project-based consulting demand in tourist-centric urban zones.
- Corporate Partnership Channels:Direct outsourcing agreements with enterprise real estate departments represent underdeveloped revenue streams compared to individual membership models.
Industry Challenges
- Fire Code Compliance Timelines:Municipal approval processes for density modifications and egress system upgrades in older commercial buildings delay facility openings by six to eighteen months in major metropolitan markets.
- Access Control Integration Complexity:Legacy building management systems in converted Class B and C properties resist seamless integration with cloud-based member authentication platforms, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Coworking Spaces Market |
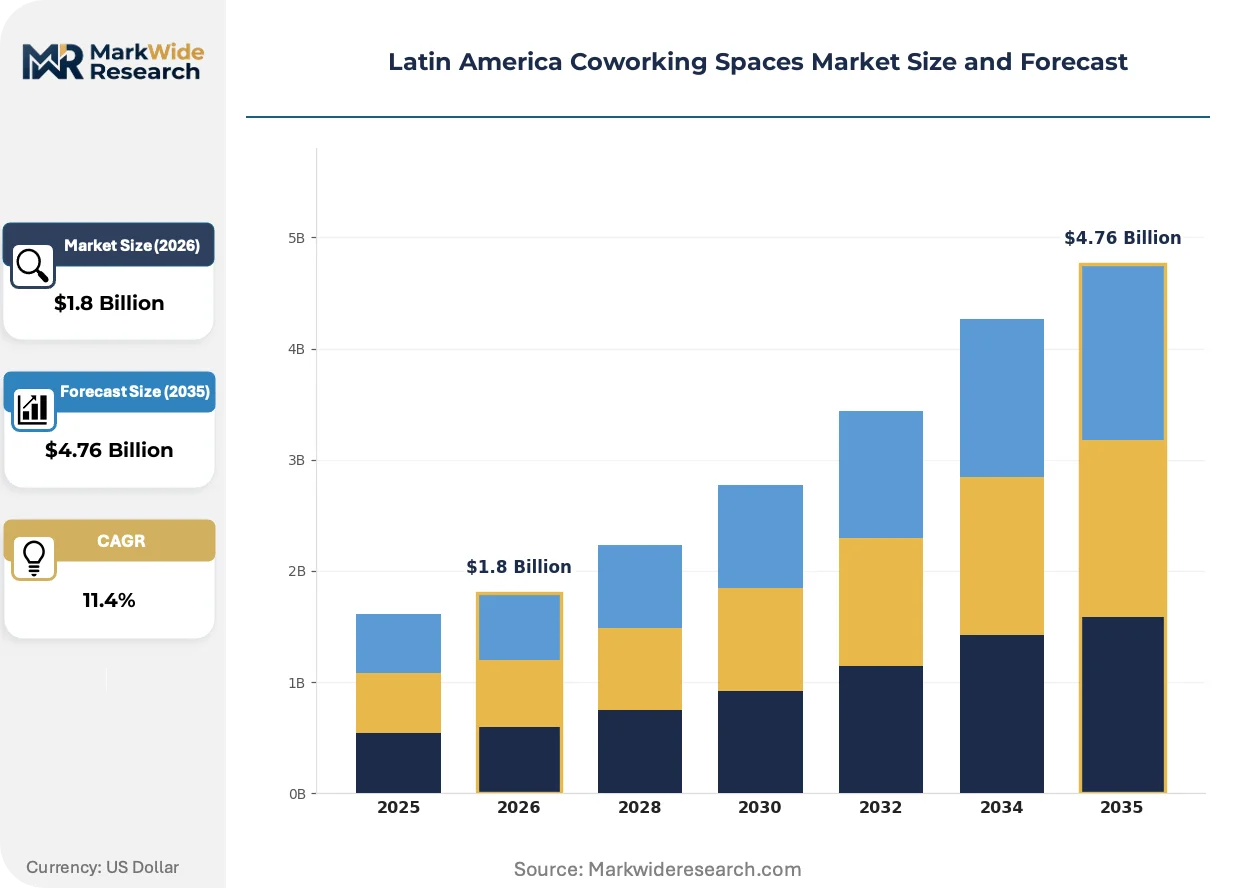
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Space Type: Private Offices, Dedicated Desks, Hot Desks, Meeting Rooms Industry Vertical: Technology, Finance, Marketing, Consulting Business Model: Membership-Based, Pay-Per-Use, Corporate Partnerships, Franchise Service Type: Event Spaces, Virtual Office, Training Rooms, Collaboration Areas |
| Companies Covered | Selina, Knotel, WeWork, Industrious Office, Alley, IWG/Regus, Woba, Techspace, Impact Hub, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Coworking Spaces Market Shifts & Advancements
Workspace technology stacks are converging around unified platforms that collapse multiple operational functions into single-vendor solutions, reducing integration overhead for multi-location operators. This consolidation is accelerating competitive differentiation between technology-native entrants and legacy real estate players.
Biometric access control is unifying physical security, membership billing, and space utilization analytics into single-touchpoint systems for Latin American operators. Mid-market coworking chains in São Paulo and Mexico City are adopting these platforms faster than independent single-location competitors. The technology is compressing administrative staffing requirements while enabling real-time occupancy optimization that legacy keycard systems cannot replicate.
CE marking harmonization for commercial building safety equipment is standardizing fire suppression and emergency egress component specifications across Brazil, Mexico, and Argentina. This regulatory convergence reduces procurement complexity for operators running multi-country portfolios. Facilities management teams are responding by consolidating supplier relationships around European-certified equipment vendors with regional distribution capabilities.
Enterprise real estate departments are unbundling satellite office requirements from bundled service contracts, awarding workspace procurement to specialized operators while retaining direct control over IT infrastructure and security policy. This disintermediation of integrated facility management providers is most visible among North American technology companies expanding Latin American development centers. Procurement teams in these organizations are prioritizing operators with SOC 2 Type II documentation over traditional commercial real estate brokers lacking technology risk management credentials.
Latin America Coworking Spaces Market Segmentation
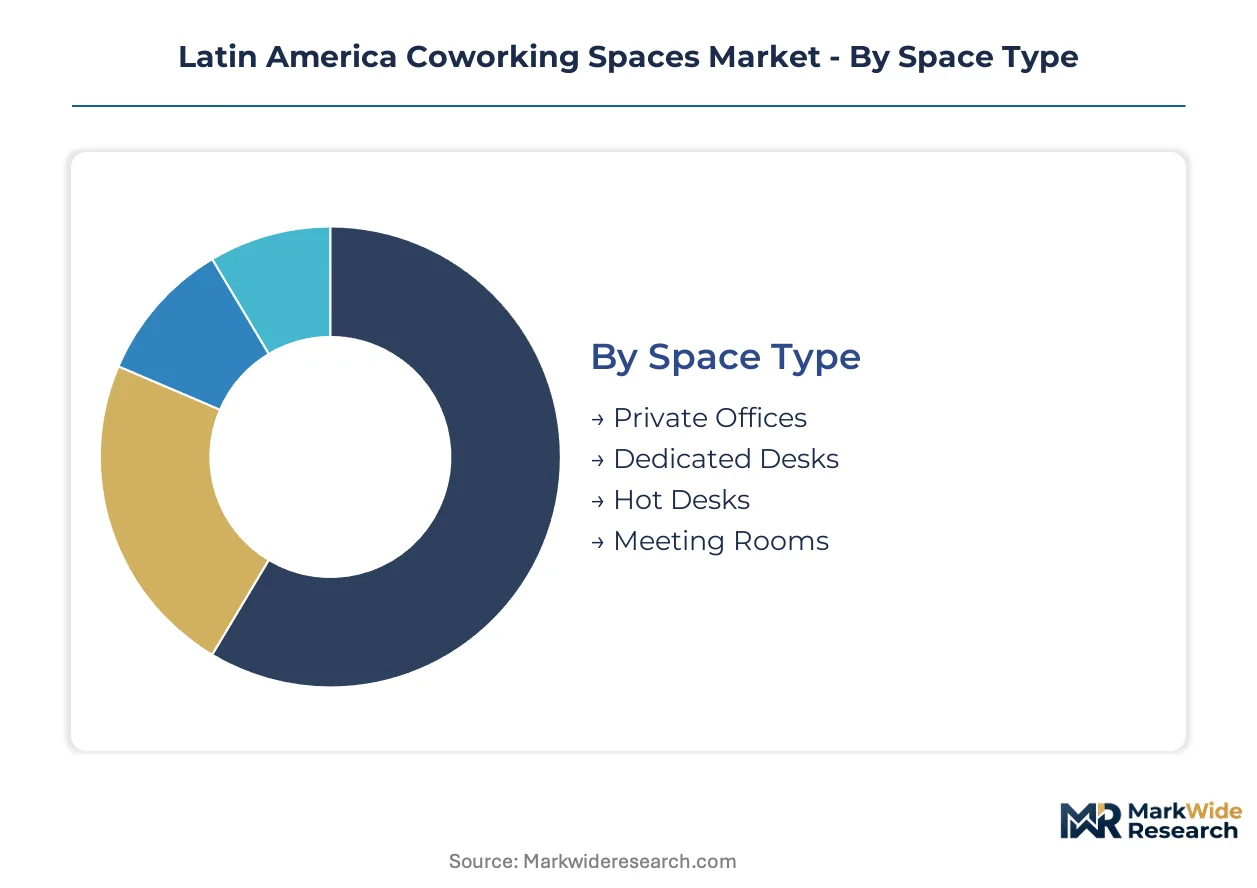
Workspace configuration and commercial engagement models determine revenue stability and capital efficiency for Latin American operators. Segmentation reveals where margin pools concentrate and which contract structures redistribute occupancy risk most effectively.
Space Type:
Supply concentration tilts toward configurations that maximize revenue per square meter while accommodating enterprise procurement requirements.
- Private Offices:Enclosed workspaces with dedicated access control and climate zones command premium pricing from legal, financial, and health-tech tenants requiring confidentiality. São Paulo's ANVISA-regulated operators absorb the majority of this inventory as compliance-driven firms prioritize documented security protocols.
- Hot Desks:Unassigned seating with first-come access enables density ratios of 4-6 square meters per occupant, the most aggressive space economics in the portfolio. Freelance professionals and seed-stage startups in Mexico City and Buenos Aires are expanding this category fastest as price sensitivity overrides permanence preferences.
- Dedicated Desks:Reserved workstations with personal storage balance flexibility with territorial security for small teams.
- Meeting Rooms:Bookable enclosed spaces with presentation infrastructure serve project-based collaboration and client-facing activities.
Private offices absorb the bulk of installed capacity; hot desks are expanding most quickly.
Industry Vertical:
Cost tier differentiation separates compliance-heavy regulated tenants from lighter administrative users.
- Technology:Software developers and venture-backed startups require redundant connectivity, 24/7 access, and SOC 2-aligned security documentation. Mexico City and Buenos Aires technology corridors are concentrating demand as enterprise satellite outsourcing accelerates.
- Finance:Fintech operators and investment advisory practices demand acoustic privacy, biometric access, and ANVISA or CVM-aligned operational frameworks. São Paulo's regulatory modernization is lowering barriers for specialized financial services coworking facilities.
- Marketing:Creative agencies and digital marketing boutiques prioritize aesthetic environments and event-capable common areas over technical infrastructure.
- Consulting:Project-based professional services firms favor hybrid arrangements combining membership access with pay-per-use meeting room credits.
Technology verticals dominate current absorption rates; finance is climbing the fastest as regulatory clarity improves.
Business Model:
Customer type segmentation determines contract duration, payment predictability, and sales cycle economics.
- Corporate Partnerships:Direct outsourcing agreements with enterprise real estate departments provide multi-year revenue visibility and ISO 45001 certification requirements. North American technology firms expanding Latin American development centers are filtering awards toward operators with documented safety management systems.
- Membership-Based:Monthly recurring subscriptions with tiered access levels generate predictable cash flows from individual professionals and small enterprises.
- Pay-Per-Use:Transactional day passes and hourly meeting room bookings capture occasional users with minimal commitment.
- Franchise:License arrangements enabling rapid secondary-city expansion without direct capital deployment by the brand owner.
Membership-based contracts anchor current revenue; corporate partnerships are gaining share fastest as enterprise procurement matures.
Service Type:
Maturity gradients separate established workspace commodities from emerging amenity categories.
- Virtual Office:Mail handling, reception services, and registered business addresses without physical workspace access. Remote professionals and foreign market entrants across Brazil, Mexico, and Argentina are expanding demand for compliant local presence without real estate commitment.
- Event Spaces:Configurable areas for product launches, training sessions, and networking functions with catering and AV infrastructure.
- Training Rooms:Instructional environments with tiered seating, recording capability, and breakout configurations.
- Collaboration Areas:Open lounge and project-room formats designed for ad-hoc teamwork and informal client meetings.
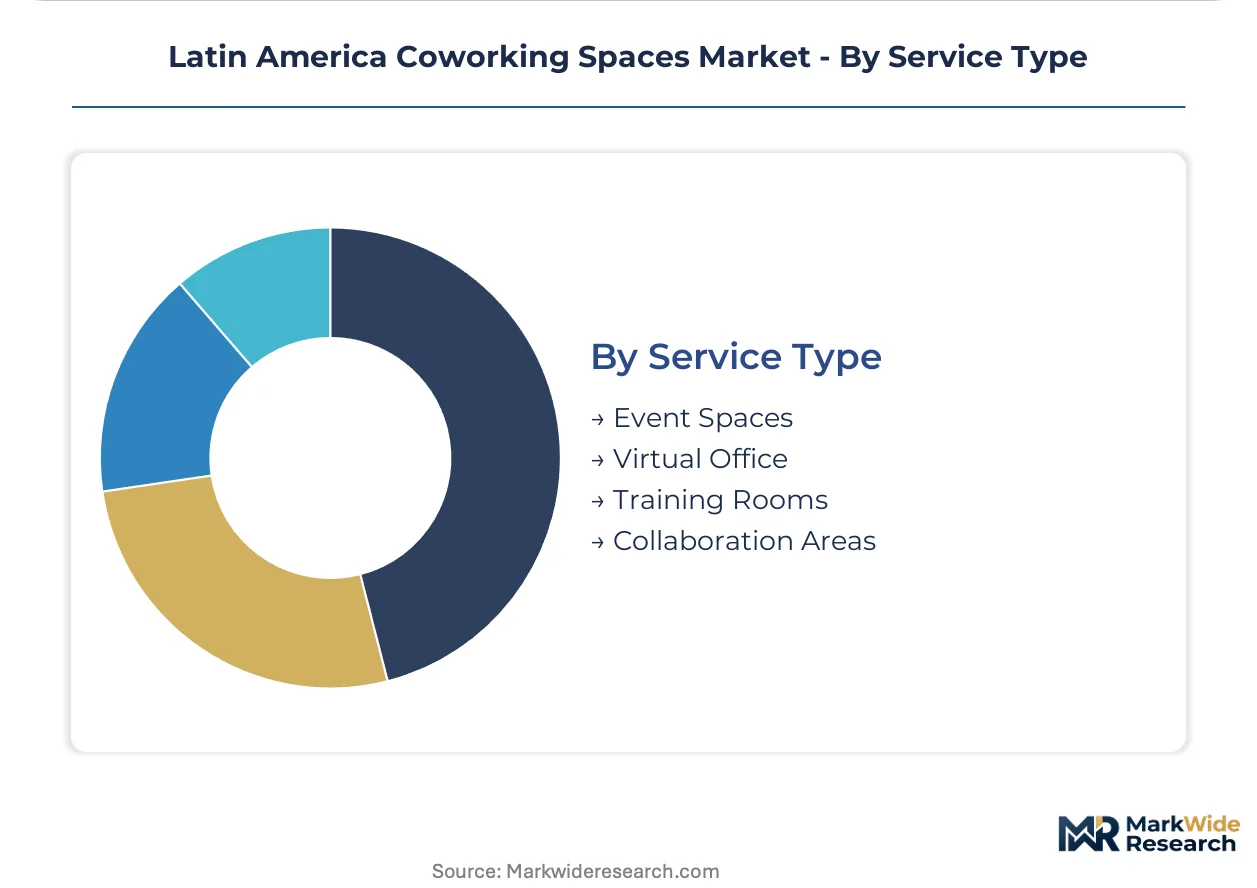
Virtual office services command the widest geographic distribution; event spaces are expanding most quickly as hybrid programming proliferates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone tax incentives concentrate electronics assembly and logistics operations, generating satellite workspace demand from compliance-conscious importers and regional distributors.
Brazil
São Paulo's Vila Olímpia and Faria Lima districts absorb premium flexible office inventory as fintech operators seek ANVISA-aligned facilities for health-tech adjacencies. The regulatory agency's streamlined digital compliance frameworks lower operational barriers for specialized operators. Rio de Janeiro's Porto Maravilha redevelopment zone is attracting hybrid hospitality-coworking concepts targeting creative industry freelancers.
Mexico
CDMX's Santa Fe and Polanco corridors concentrate enterprise satellite offices for North American technology firms outsourcing Latin American development centers. COFEPRIS pharmaceutical regulator alignment enables laboratory-grade coworking clusters for medical device startups. Monterrey's Nuevo León manufacturing belt is expanding flexible workspace supply to serve cross-border supply chain managers and industrial engineering consultants.
Argentina
Buenos Aires' Palermo and Puerto Madero neighborhoods host the majority of installed flexible office capacity despite peso-dollar currency mismatch risks for operators. The national securities regulator CNV mandates documented operational frameworks for fintech-tenant facilities. Córdoba's emerging technology corridor is absorbing second-tier coworking inventory from operators diversifying beyond capital-city exposure.
Chile
Santiago's Las Condes and Providencia districts concentrate demand from mining sector professional services firms requiring satellite meeting infrastructure. The Superintendencia de Bancos e Instituciones Financieras (SBIF) successor frameworks shape compliance requirements for financial services coworking tenants. Valparaíso's port logistics zone is generating niche demand for project-based workspace among shipping and commodities trading intermediaries.
Colombia
Bogotá's Zona Rosa and Parque de la 93 clusters absorb flexible office demand from marketing agencies and digital services boutiques. The Superintendencia Financiera de Colombia (SFC) regulates fintech tenant operations in specialized facilities. Medellín's Ruta N innovation district is expanding coworking supply calibrated to early-stage technology venture density.
Latin America Coworking Spaces Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Latin America's coworking market. IWG/Regus anchors the franchise-heavy expansion model through suburban and secondary-city penetration, while WeWork sustains premium urban positions via capital reserve deployment. Three archetypes dominate: global network operators with standardized service tiers, hybrid hospitality-coworking integrators targeting digital nomad flows, and regional boutique chains emphasizing localized design aesthetics. Competitive dynamics center on portfolio diversification into virtual office services and direct corporate partnership channels that bypass individual membership acquisition costs.
Within the global network tier, WeWork and IWG/Regus occupy positions exemplifying scale-driven standardization versus franchise-enabled geographic reach. Selina represents the hospitality-coworking convergence archetype, anchoring hybrid concepts in tourist-centric urban zones across multiple Latin American markets. Knotel and Industrious Office sit within the enterprise-focused segment, targeting direct outsourcing agreements with corporate real estate departments rather than individual professional memberships. These three groupings illustrate how capital structure and customer acquisition strategy differentiate competitive positioning more than physical space configuration alone.
| Leading Market Players |
|---|
| Selina |
| Knotel |
| WeWork |
| Industrious Office |
| Alley |
| IWG/Regus |
| Woba |
| Techspace |
| Impact Hub |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ISO 45001-compliant facilities and uncertified competitors manifests in both membership pricing premiums and supplier selection rigor across São Paulo and Mexico City. ANVISA-aligned operators command elevated rates while sourcing fire suppression and egress systems exclusively from CE-marked European vendors, whereas price-driven independents absorb spot inventory from regional distributors with shorter lead times but inconsistent documentation.
Pricing Analysis
Lead-time compression drives pricing stratification across Latin American coworking markets, with enterprise clients paying premiums for immediate occupancy in certified facilities while spot-market seekers accept discounted rates for flexible move-in windows. Three-tier pricing structure across premium, standard, and economy levels reflects certification status, geographic cluster density, and after-sales amenity bundling. Cost compression in the economy tier is intensifying as municipal tax reclassification threats in Argentina and Colombia squeeze operator margins. Freelance professionals and seed-stage startups exhibit the highest price sensitivity, while North American technology firms expanding development centers demonstrate minimal elasticity for documented SOC 2 and ISO 45001 compliance.
Supply Chain Analysis
Reverse-logistics flows for ergonomic furnishings and access control hardware remain underdeveloped across Latin American coworking markets, with most operators defaulting to disposal rather than refurbishment programs. Supply concentrates in Brazil, Mexico, and China for climate systems, biometric readers, and modular partition components. Raw material dependencies span steel framing from Brazilian mills, semiconductor chips from Taiwanese foundries, and fire-rated glass from Mexican manufacturers. Single-source vulnerability in cloud-based member authentication platforms creates operational continuity risk. Distribution runs through regional facility management integrators who consolidate procurement for multi-location operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
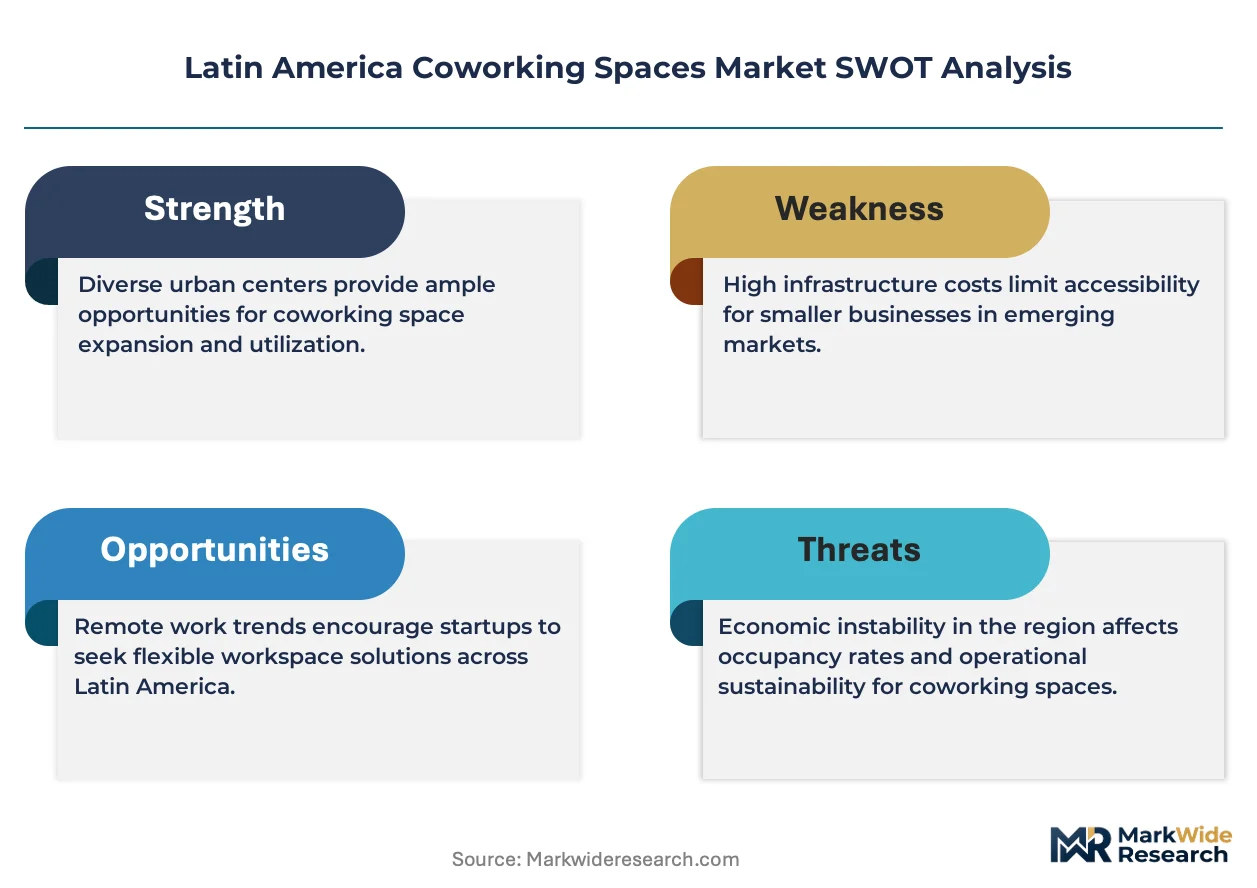
Latin American coworking markets operate as a cost-of-compliance story where ANVISA's digital-first regulatory modernization in Brazil erects barrier-to-entry moats favoring operators with documented safety management systems and capital reserves for certification investments.
For Market Incumbents: Lock in enterprise satellite office contracts through multi-year corporate partnership agreements before competitors achieve ISO 45001 certification parity. Defend against IWG/Regus franchise expansion by securing exclusive building management relationships in São Paulo's Vila Olímpia and Faria Lima districts. Vertical integration into virtual office services captures remote professional demand with minimal incremental real estate exposure. For New Entrants and Emerging Players: COFEPRIS pharmaceutical regulator alignment in Mexico opens a window for laboratory-grade coworking facilities serving medical device and biotech startups requiring controlled environments. Target Monterrey's Nuevo León manufacturing belt for cross-border supply chain manager demand underserved by CDMX-centric operators. Pursue hybrid hospitality-coworking convergence in tourist-centric urban zones as the most penetrable white-space configuration. For Investors and Strategic Acquirers: Re-rating potential sits with technology-native operators possessing SOC 2 Type II documentation given enterprise procurement departments' prioritization of technology risk management credentials over traditional commercial real estate broker relationships. Long-term viability favors multi-location portfolios spanning at least three metropolitan clusters to distribute municipal tax reclassification exposure. Monitor municipal zoning board deliberations in Buenos Aires and Bogotá for early signals of flexible workspace provider reclassification from service to real estate taxation.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 45001 Certification Investment | Enterprise procurement departments mandate documented occupational health standards, filtering contract awards toward compliant operators. |
| Biometric Access Control Platform Integration | Unified physical security, membership billing, and space utilization analytics compress administrative staffing requirements. |
| Corporate Partnership Channel Development | Direct outsourcing agreements with enterprise real estate departments provide multi-year revenue visibility beyond individual memberships. |
| Hybrid Hospitality-Coworking Convergence | Extended-stay accommodation integration captures digital nomad and project-based consulting demand in tourist-centric urban zones. |
| Virtual Office Service Expansion | Mail handling and registered business address offerings capture remote professional demand without physical workspace commitment. |
Research Methodology
Independent corroboration across facility operator interviews, municipal zoning board filings, and enterprise real estate procurement disclosures underwrites the qualitative findings in this study. Primary fieldwork engaged coworking space general managers, commercial real estate brokers specializing in flexible office arrangements, enterprise facility procurement officers, and regulatory compliance consultants across São Paulo, Mexico City, and Buenos Aires. Secondary validation drew from ANVISA digital compliance framework documentation, COFEPRIS pharmaceutical facility guidelines, ISO 45001 certification registries, and commercial building safety equipment import records. Bottom-up location-level capacity assessments and top-down metropolitan market sizing were triangulated against membership revenue models.
Rate-of-change decomposition across the analysis window separates organic demand growth from supply-driven absorption metrics. Segmentation dimensions modeled include space type configuration, industry vertical concentration, business model contract structure, and service type amenity tier. CAGRs were derived from rolling capacity addition schedules against membership pricing trajectories. Coworking-specific forecast inputs incorporate enterprise satellite office outsourcing penetration rates and municipal tax treatment evolution scenarios.
The model assumes a particular technology adoption path; alternative pathways for cloud-based access control platform migration would alter the outlook if legacy building management system integration complexity proves more prohibitive than projected. Forecasts reflect assumptions regarding regulatory modernization continuity, broadband infrastructure deployment timelines, and currency stability in dollar-denominated lease markets. Practitioners should monitor municipal tax reclassification deliberations, ANVISA compliance framework expansion announcements, and enterprise procurement department certification mandate updates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Singapore Self-Storage Market
Real Estate Services
US Home Service Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
Global Home Services Market
Real Estate Services
Relocation Management Service Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Switzerland Self-Storage Market
Real Estate Services
Property Tax Services Market
Real Estate Services
Germany Real Estate Services Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
Vietnam Self-Storage Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
Warehousing Services Market
Real Estate Services
Europe Coworking Spaces Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
Co-Working Space Services Market