
 Vietnam Self-Storage Market | 2026-2036
Vietnam Self-Storage Market Size, Share, and Industry Trends Forecast 2026-2036
Vietnam Self-Storage Market Analytics
Vietnam's National Technical Standards on building fire safety and construction quality is hardening compliance requirements for self-storage facility developers. TITAN Containers leverages its containerized portable storage expertise to serve industrial zones near Ho Chi Minh City. Lock+Store anchors its network in Hanoi and Da Nang with climate-controlled indoor facilities targeting residential downsizers. SafeHouse Storage specializes in 24/7 access security protocols for business customers in the southern economic corridor.
Self-storage denotes the commercial provision of rented space—typically modular units of 5 to 50 square meters—where individuals or businesses store goods under contractual terms, with facilities employing reinforced concrete or steel partitioning, climate control systems maintaining 18-24°C, and electronic access logging. Indoor storage dominates revenue generation in Vietnam's urban cores where land scarcity elevates multi-story construction, while portable storage records the fastest expansion as e-commerce sellers seek flexible inventory staging without fixed warehouse leases. Climate-controlled storage captures premium pricing from pharmaceutical distributors and electronics retailers requiring humidity regulation below 60% relative humidity.
Vietnam's Ministry of Construction enforces QCVN building standards that mandate sprinkler systems and emergency egress specifications for storage facilities above three stories, while the country's national fire safety inspectorate conducts annual compliance audits that shape facility design investments. The General Department of Vietnam Customs influences bonded storage configurations for import-export enterprises operating in industrial zones. Stakeholders must monitor how proposed amendments to urban land-use planning laws will rezone peripheral districts for commercial storage development.
Market Dynamics
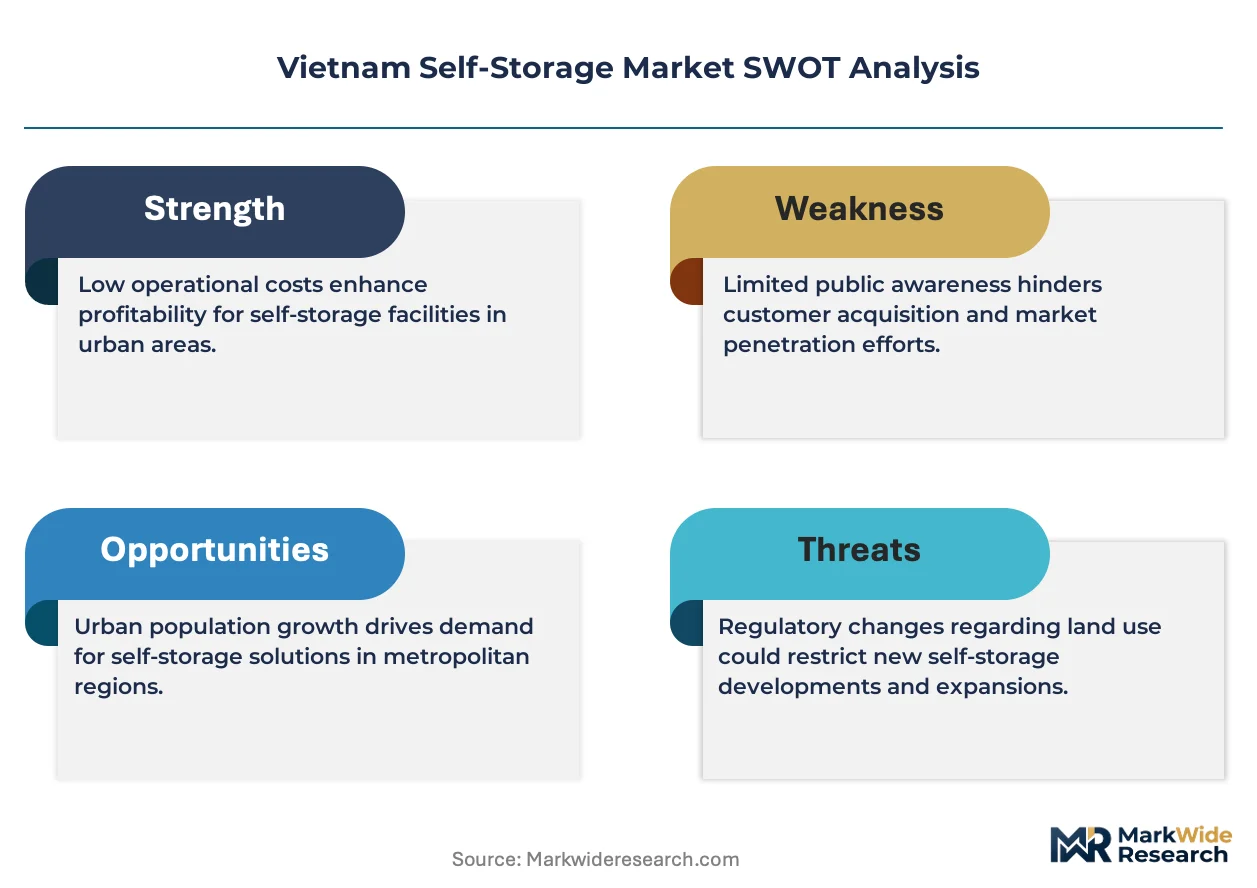
Vietnam's revised QCVN building standards are forcing facility developers to redesign multi-story storage structures around sprinkler mandates and emergency egress specifications, compressing development timelines and elevating capital requirements for new entrants in Ho Chi Minh City and Hanoi.
Growth Catalysts
- E-commerce logistics clustering:Third-party fulfillment operators in Binh Duong and Dong Nai provinces are leasing portable storage units for inventory staging, bypassing long-term warehouse commitments.
- QCVN 06:2022 fire safety standards:Mandatory sprinkler installations and compartmentalization rules above three stories are professionalizing facility construction quality and deterring informal competitors.
- Residential downsizing in urban cores:High-rise apartment dwellers in District 2 and Tay Ho district are renting climate-controlled units for furniture retention during relocation cycles.
Market Restraints
- Land cost escalation:Industrial zone plot prices in southern provinces have tripled since 2020, consuming 40-50% of facility development budgets.
- Steel input volatility:Reinforced partitioning and racking systems depend on imported H-beam and galvanized sheet, exposing operators to exchange rate fluctuation.
- Substitution by informal warehousing:Unlicensed ground-floor commercial space in peripheral districts undercuts regulated storage pricing by 30-40%.
Strategic Opportunities
- Bonded storage in deep-water ports:Hai Phong and Cai Mep terminals lack compliant customs-bonded self-storage, creating first-mover potential for import-export SMEs.
- Pharmaceutical cold-chain convergence:Temperature-controlled storage between 2-8°C for vaccine distributors remains underserved outside state hospital networks.
- Smart access integration:Biometric entry systems and IoT humidity monitoring can differentiate premium offerings in Hanoi's competitive Thanh Xuan district.
Industry Challenges
- Fire safety engineering talent scarcity:Qualified designers familiar with QCVN sprinkler hydraulic calculations command premiums that stretch pre-operational staffing budgets.
- Legacy electrical infrastructure:Retrofitted buildings in Hanoi's Old Quarter lack three-phase power capacity for climate-control compressor loads.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vietnam Self-Storage Market |
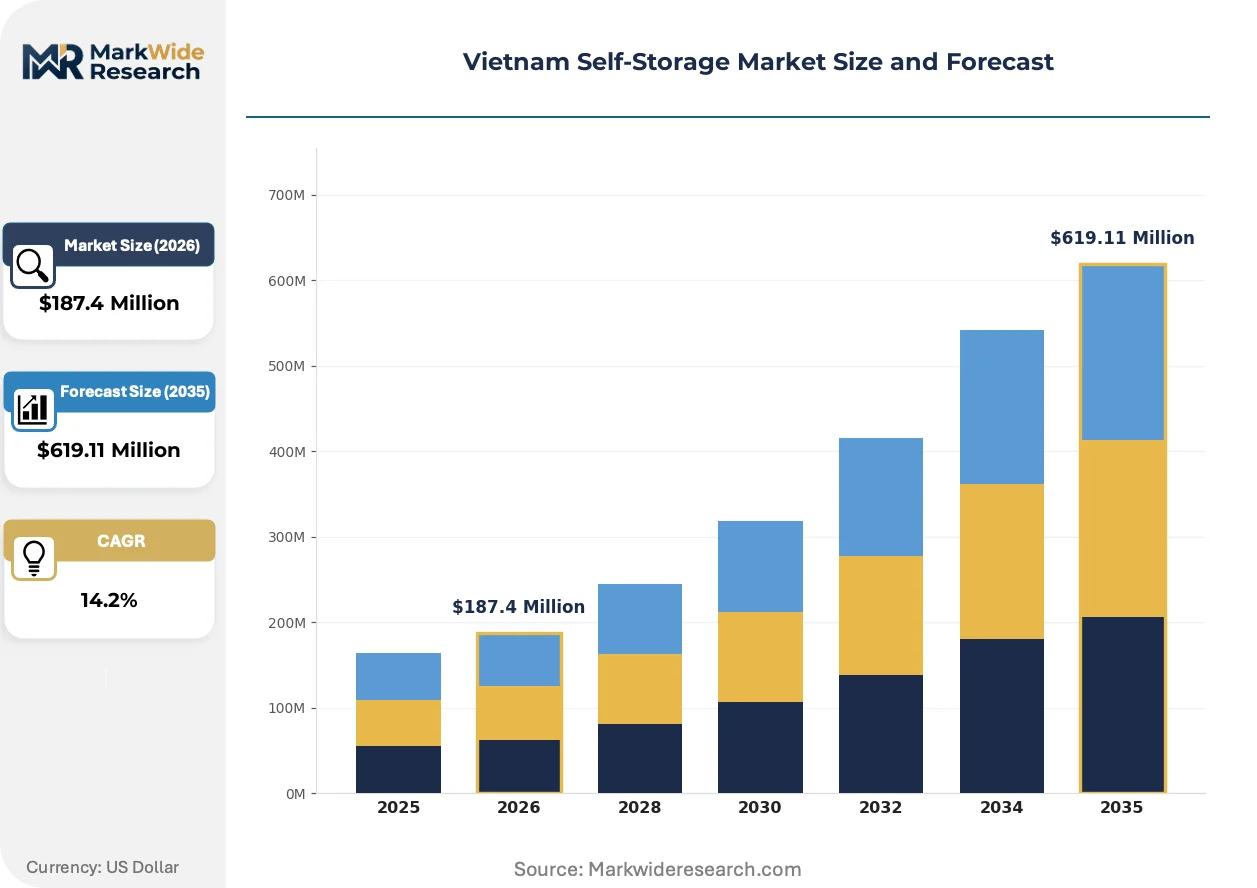
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Facility Type: Indoor Storage, Outdoor Storage, Climate-Controlled Storage, Portable Storage Unit Size: Small Units, Medium Units, Large Units, Extra Large Units Customer Type: Residential Customers, Business Customers, Students, Military Personnel Access Type: 24/7 Access, Limited Hours Access, Drive-Up Access, Virtual Access |
| Companies Covered | TITAN Containers, Lock+Store, MyStorage, Stored.vn, SafeHouse Storage, Saigon Storage, Extra Space Asia Corporation, Cube Self Storage Vietnam, KingKho Mini Storage, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vietnam Self-Storage Market Evolving Landscape
Facility operators are deploying sensor networks and modular construction methods to compress deployment timelines and capture premium pricing from compliance-sensitive business segments.
Containerized portable storage is overtaking fixed warehouse leasing among e-commerce sellers and construction contractors. These steel units deploy within 48 hours to industrial zones. Cross-docking operators in Long An province are adopting container fleets to stage inbound shipments without permanent facility commitments, compressing working capital cycles.
Vietnam's Ministry of Construction is tightening QCVN enforcement through annual fire safety inspectorate audits. Facilities must now document egress simulation testing and sprinkler flow-rate certification. Multi-story developers in Ho Chi Minh City's Thu Duc district are engaging third-party compliance consultants to accelerate permitting timelines.
Subscription-based access models are displacing traditional monthly rental contracts among residential users. Young professionals in Hanoi's Cau Giay district prefer app-managed entry with prorated billing. This behavioral shift is visible most acutely among tech-sector employees relocating between shared apartments quarterly.
Vietnam Self-Storage Market Segmentation
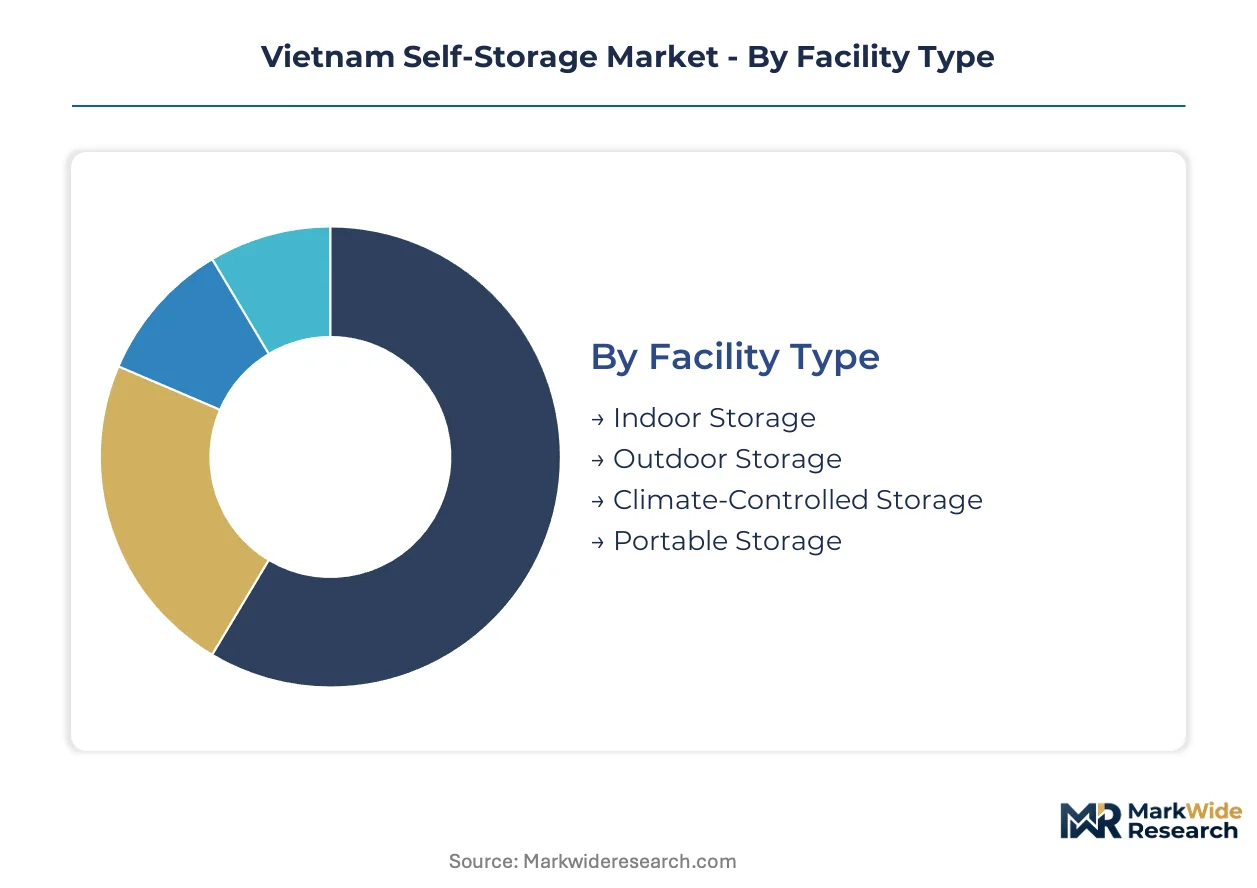
Segmentation in Vietnam's self-storage market reveals how facility economics, customer behavior, and regulatory compliance intersect. Each dimension carries distinct investment implications for developers navigating Ho Chi Minh City's land constraints and Hanoi's retrofitting challenges.
Facility Type:
Construction specifications and climate engineering differentiate facility economics across Vietnam's urban corridors.
- Indoor Storage:Multi-story reinforced concrete structures with elevator access dominate revenue generation in District 2 and Tay Ho. Ho Chi Minh City's land scarcity forces vertical development, compressing yields per square meter but capturing premium pricing from residential downsizers.
- Climate-Controlled Storage:Compressor systems maintaining 18-24°C with humidity regulation below 60% relative humidity command the highest margins. Pharmaceutical distributors in Thu Duc and electronics retailers in Cau Giay drive sustained occupancy for these specifications.
- Portable Storage:Steel container units deployable within 48 hours serve e-commerce fulfillment clusters in Binh Duong and Dong Nai. Third-party logistics operators lease these for inventory staging without fixed warehouse commitments.
- Outdoor Storage:Open-air paved lots with perimeter fencing target construction equipment and vehicle storage. Industrial zone adjacency in Long An and Hai Phong determines site viability.
Mature deployment sits with Indoor Storage. Newer deployment is concentrated in Portable Storage.
Unit Size:
Spatial allocation strategies reflect customer lifecycle patterns and inventory velocity requirements across Vietnam's urban centers.
- Small Units:Modular spaces of 5-10 square meters accommodate document archives and seasonal clothing. Young professionals in Hanoi's Cau Giay district rent these during quarterly apartment relocations.
- Medium Units:10-25 square meter configurations store furniture for residential downsizers. High-rise apartment dwellers in District 2 retain household goods during renovation cycles.
- Large Units:25-50 square meter spaces serve SME inventory overflow. Cross-docking operators in Long An province stage inbound shipments here.
- Extra Large Units:Spaces exceeding 50 square meters target construction contractors and manufacturing equipment. Industrial zone proximity in Dong Nai shapes demand concentration.
Volume concentration rests with Medium Units. Steepest expansion trajectory belongs to Small Units.
Customer Type:
Contract structures and access frequency vary sharply between residential mobility patterns and business inventory cycles.
- Business Customers:SMEs in Ho Chi Minh City's southern economic corridor lease climate-controlled units for compliance-sensitive inventory. QCVN fire safety standards mandate sprinkler installations that professional operators can document.
- Residential Customers:Urban apartment dwellers in Hanoi and Ho Chi Minh City rent for relocation buffering and space constraints. Subscription-based access models with app-managed entry are displacing traditional monthly contracts.
- Students:Semester-based storage demand concentrates near university clusters in Thu Duc and Cau Giay. Price sensitivity drives preference for shared unit arrangements.
- Military Personnel:Rotational deployment cycles create predictable seasonal demand near bases in Ba Ria-Vung Tau and Hai Phong. Facilities offering 24/7 access capture this segment.
Revenue maturity aligns with Business Customers. Fastest customer acquisition is occurring among Residential Customers.
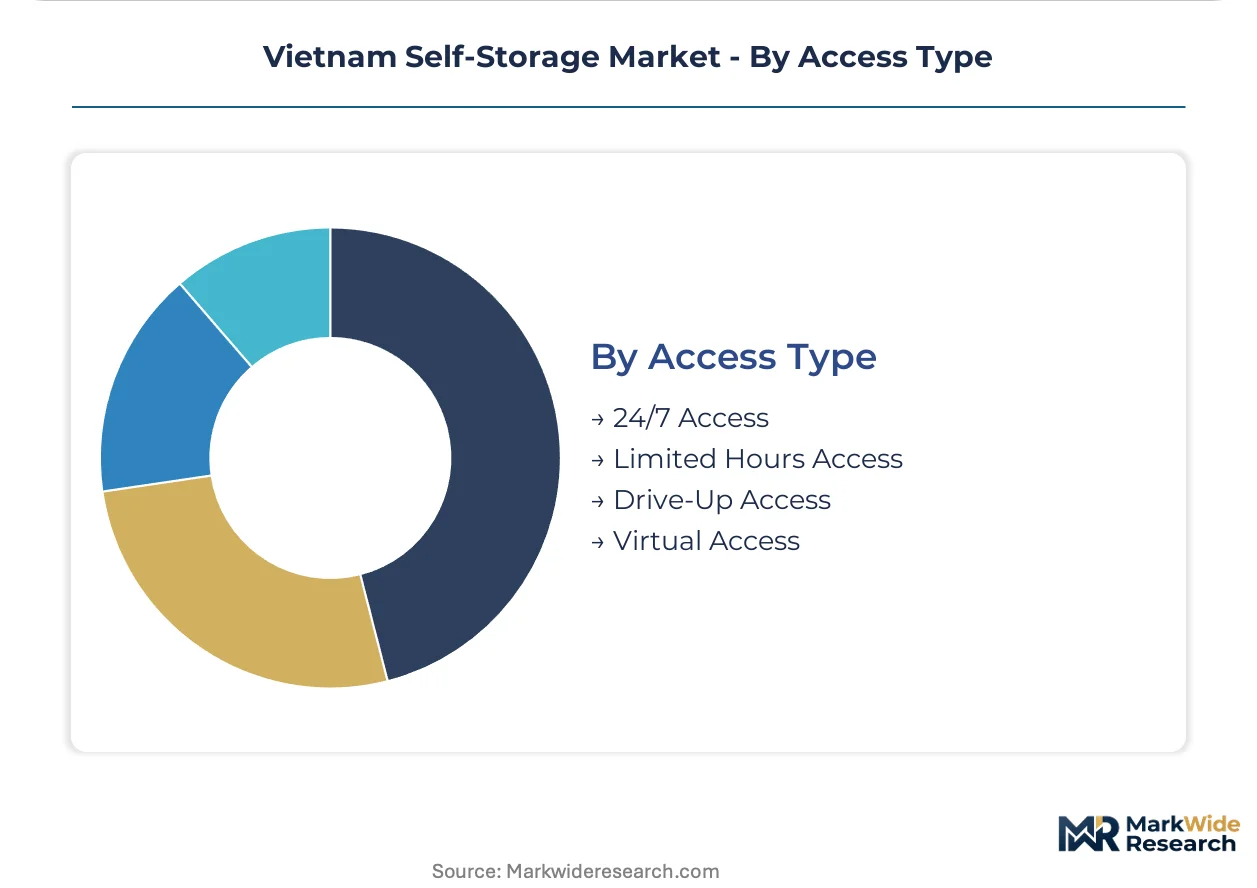
Access Type:
Security protocols and labor cost structures determine operational economics across facility tiers.
- 24/7 Access:Biometric entry systems and electronic logging serve business customers requiring inventory retrieval flexibility. SafeHouse Storage specializes in these protocols for southern economic corridor clients.
- Virtual Access:App-managed entry with prorated billing attracts tech-sector employees in Hanoi's Cau Giay district. This model compresses administrative overhead while capturing premium pricing.
- Drive-Up Access:Ground-level roll-up doors facilitate heavy item loading for construction contractors and furniture movers. Land-intensive configurations limit deployment to peripheral districts.
- Limited Hours Access:Staffed reception during business hours reduces security infrastructure investment. Legacy facilities in Hanoi's Old Quarter operate under this constraint due to electrical infrastructure limitations.
Established penetration rests with Limited Hours Access. Technology deployment is accelerating fastest in Virtual Access.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Self-storage consumption concentrates in Vietnam's southern economic corridor while facility development spreads northward. Production of climate-controlled and portable storage units clusters near industrial zones in Ho Chi Minh City and Binh Duong province. The country's revised QCVN building standards are reshaping where developers can economically construct multi-story facilities.
Ho Chi Minh City
E-commerce logistics operators and residential downsizers drive demand in District 2 and Thu Duc. Vietnam's Ministry of Construction enforces QCVN 06:2022 fire safety standards that mandate sprinkler systems above three stories. Thu Duc district developers engage third-party compliance consultants to accelerate permitting timelines for vertical storage structures.
Hanoi
Climate-controlled indoor facilities target residential customers in Tay Ho and Cau Giay districts. The national fire safety inspectorate conducts annual compliance audits that shape facility design investments. Cau Giay district sees subscription-based access models displacing traditional monthly contracts among tech-sector employees.
Da Nang
Lock+Store anchors its central region network here with climate-controlled facilities. The city's urban land-use planning amendments are rezoning peripheral districts for commercial storage development. Industrial zone adjacency in Lien Chieu district supports cross-docking operators seeking flexible inventory staging.
Binh Duong Province
Third-party fulfillment operators lease portable storage units for inventory staging. The General Department of Vietnam Customs influences bonded storage configurations for import-export enterprises. E-commerce logistics clustering in Di An and Thuan An cities drives fastest expansion in containerized portable storage deployment.
Hai Phong
Deep-water port terminals lack compliant customs-bonded self-storage for import-export SMEs. Vietnam's Ministry of Construction building standards apply equally to northern port facilities. Dinh Vu industrial zone presents first-mover potential for bonded storage serving manufacturing supply chains.
Vietnam Self-Storage Market Competitive Landscape
The competitive structure tilts toward specialized operators rather than integrated national chains. Facility developers cluster around three strategic archetypes: containerized portable storage specialists, climate-controlled indoor facility operators, and security-focused business service providers. Competitive moves center on compliance certification acceleration and technology-enabled access differentiation rather than price-based rivalry.
Among containerized portable storage specialists, TITAN Containers exemplifies the industrial zone deployment model. Lock+Store and SafeHouse Storage occupy distinct positioning vectors within the indoor facility segment, with the former emphasizing climate control and the latter prioritizing 24/7 access protocols. These three operators represent how market participants are segmenting around compliance capabilities and customer access preferences rather than competing on unit economics alone.
| Leading Market Players |
|---|
| TITAN Containers |
| Lock+Store |
| MyStorage |
| Stored.vn |
| SafeHouse Storage |
| Saigon Storage |
| Extra Space Asia Corporation |
| Cube Self Storage Vietnam |
| KingKho Mini Storage |
| Others |
Value Network & Pricing Analysis
Steel input costs for reinforced partitioning and container fabrication cascade through three distinct pricing tiers, with imported H-beam and galvanized sheet from China and South Korea feeding premium climate-controlled facilities, mid-tier indoor storage, and economy portable units serving e-commerce logistics clusters in Binh Duong.
Pricing Analysis
Climate-controlled storage anchored to humidity regulation outcomes commands the highest margins, with pharmaceutical distributors in Thu Duc and electronics retailers in Cau Giay paying premiums for 18-24°C stability below 60% relative humidity. Price differentiation separates certified QCVN-compliant facilities with documented sprinkler flow-rate certification from informal ground-floor competitors undercutting by 30-40%. Pricing pressure intensifies in the portable storage segment as e-commerce sellers prioritize working capital compression over facility quality. Students and young professionals in university districts exhibit greatest price sensitivity, while bonded storage seekers near Hai Phong deep-water ports demonstrate lowest sensitivity due to compliance requirements.
Supply Chain Analysis
Imported steel inputs from China, South Korea, and Japan anchor facility construction costs, with H-beam for multi-story structures and galvanized sheet for containerized units constituting 40-50% of development budgets. Compressor systems for climate control draw from Thai and Malaysian HVAC suppliers, while biometric access hardware sources from Taiwanese electronics manufacturers. Single-source vulnerability concentrates in fire safety engineering talent for QCVN sprinkler hydraulic calculations. Distribution runs through industrial zone developers in Ho Chi Minh City and Hanoi who control land allocation for peripheral district rezoning.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vietnam's self-storage market is consolidating around compliance capabilities, with QCVN fire safety standards forcing informal operators toward exit or acquisition by certified facility developers.
For Market Incumbents: Extend climate-controlled capacity in Thu Duc and Cau Giay districts before land rezoning finalizes, securing three-phase power infrastructure commitments from EVN Hanoi to preempt electrical capacity constraints. Acquire portable storage fleets to serve cross-docking operators in Long An province, defending against TITAN Containers' industrial zone penetration. Certification investment in bonded storage configurations creates defensible positioning near Hai Phong deep-water terminals. For New Entrants and Emerging Players: Pharmaceutical cold-chain distributors represent the most penetrable buyer archetype, with 2-8°C vaccine storage demand concentrated outside state hospital networks. Target bonded self-storage deployment in Dinh Vu industrial zone, Hai Phong, where customs-compliant facilities remain absent. A go-to-market angle anchored to QCVN compliance documentation acceleration addresses the 6-12 month permitting bottleneck throttling competitor timelines. For Investors and Strategic Acquirers: Annual fire safety inspectorate audit failure rates exceeding 15% among legacy facilities is the leading indicator that consolidation momentum will accelerate. Five-to-ten year viability favors operators with vertical integration into container fabrication or captive HVAC maintenance capabilities. Watch for amendments to urban land-use planning laws rezoning peripheral districts as the signal for land-bank valuation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| QCVN Compliance Certification Investment | Accelerates permitting timelines in Thu Duc and Cau Giay districts. |
| Bonded Storage Configuration Development | Captures first-mover position near Hai Phong deep-water terminals. |
| Container Fleet Expansion | Serves cross-docking operators in Long An and Binh Duong provinces. |
| Smart Access Technology Integration | Differentiates premium offerings in Hanoi's competitive Thanh Xuan district. |
| Pharmaceutical Cold-Chain Capability Buildout | Addresses underserved 2-8°C vaccine distributor demand outside state networks. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across facility developers, fire safety engineering consultants, and e-commerce logistics operators. QCVN building standards documentation, Ministry of Construction audit reports, and General Department of Vietnam Customs bonded storage regulations provided regulatory validation. Bottom-up triangulation across unit-level economics in Ho Chi Minh City and Hanoi converged with top-down market sizing from industrial zone development permits.
Facility type, unit size, customer segment, and access technology were modeled at district-level granularity across the projection horizon. Climate-controlled versus non-climate occupancy rates, portable storage deployment velocity, and QCVN compliance certification timelines fed analytical frameworks. CAGRs derived from land cost escalation curves and steel input price volatility assumptions.
Revisions become necessary when QCVN enforcement intensity shifts, urban land-use planning amendments accelerate peripheral district rezoning, or informal warehousing substitution intensifies beyond current 30-40% price undercut levels. A small set of named triggers—fire safety inspectorate audit failure rates, EVN three-phase power capacity expansion schedules, and bonded storage customs framework updates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Egypt Real Estate Brokerage Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
Singapore Customs Brokerage Market
Real Estate Services
Co-Working Space Services Market
Real Estate Services
IBC Rental Business Market
Real Estate Services
Global Home Services Market
Real Estate Services
Warehousing Services Market
Real Estate Services
Germany Self-Storage Market
Real Estate Services
Global Self Storage Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
Lease Management Market
Real Estate Services
Property Tax Services Market
Real Estate Services
Europe Real Estate Brokerage Market
Real Estate Services
Latin America Coworking Spaces Market