
 Co-Working Space Services Market | 2026-2036
Co-Working Space Services Market Size, Share, and Industry Trends Forecast 2026-2036
Co-Working Space Services Market Analysis
Enterprise technology deployment is pivoting from centralized headquarters to distributed satellite arrangements, reshaping procurement patterns for flexible workspace. IWG plc leverages its multi-brand portfolio to sustain density across tier-one and tier-two cities. WeWork Inc. competes on design-forward environments that anchor creative-industry tenants. Industrious Operating Company LLC specializes in hospitality-infused service tiers that differentiate its suburban and urban locations.
Co-working space services denote commercial real estate arrangements where individuals or organizations access shared office infrastructure—including workstations, meeting rooms, and telecommunications—through short-term contractual obligations rather than conventional long-term leases. Providers typically engineer spaces with fiber-optic connectivity, ergonomic furnishings, and climate-controlled environments to support knowledge-worker productivity across variable occupancy loads. Private offices within facility-type segmentation command premium pricing due to enterprise demand for branded, secure environments, while hot desking retains volume leadership among freelancers and early-stage ventures. Monthly pricing models dominate revenue stability, though hourly and daily structures capture event-based and transient professional use cases.
Building regulators in New York enforce Local Law 97 carbon-emission caps that elevate retrofit costs for co-working operators maintaining older stock. Singapore's Building and Construction Authority mandates Green Mark certification thresholds that shape development timelines for new flexible workspace supply. India's National Building Code, administered by the Bureau of Indian Standards, specifies fire-safety and accessibility parameters that filter market-entry feasibility. Stakeholders must monitor how municipal zoning reforms and energy-performance standards redistribute operating-cost burdens across facility-type segments.
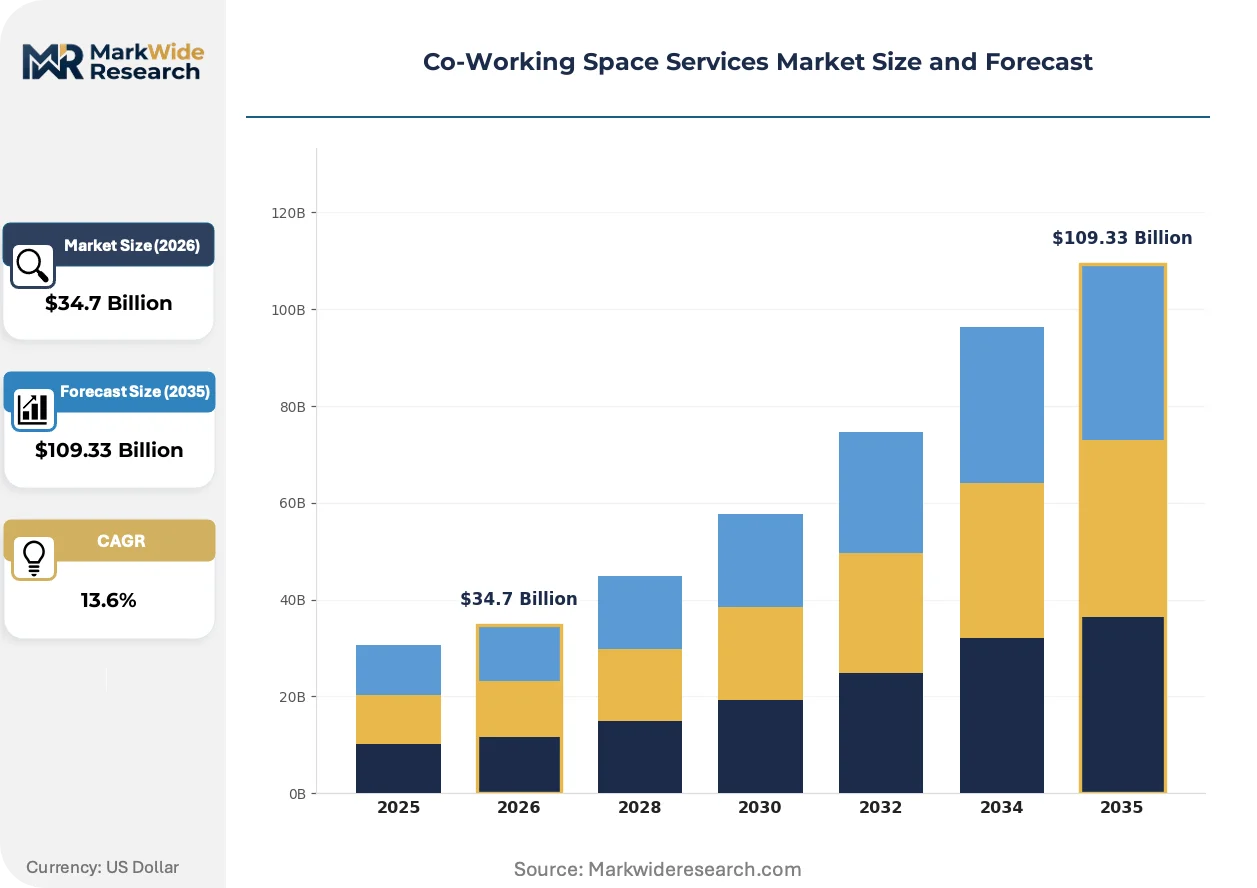
Market Dynamics
Enterprise hybrid work mandates are fragmenting real estate demand into distributed satellite networks, compressing lease tenures and elevating flexible workspace procurement above traditional commercial office contracting.
Growth Catalysts
- EU Green Deal retrofit mandates:Energy-efficiency standards under this framework accelerate building modernization across Germany, France, and Italy, generating turnkey retrofit demand that co-working operators capture through managed workspace services.
- India startup density:Bengaluru and Mumbai clusters absorb surging IT services and venture-funded tenancy, concentrating flexible office absorption in technology corridors with inadequate conventional supply.
- Fiber-optic infrastructure densification:Municipal broadband initiatives in Singapore, South Korea, and the UAE reduce connectivity provisioning costs for providers, enabling rapid location deployment without carrier negotiation delays.
Market Restraints
- Local Law 97 carbon caps:New York City's emission thresholds impose retrofit cost burdens on operators maintaining pre-war building stock, compressing margins for Manhattan-based providers.
- Landlord concentration in tier-one cities:Five institutional property owners control majority Class-A office supply in London, Paris, and Tokyo, constraining lease negotiation leverage for expanding operators.
- Remote collaboration software substitution:Video conferencing and virtual office platforms reduce physical workspace dependency among distributed teams, capping penetration in cost-sensitive segments.
Strategic Opportunities
- Suburban corridor penetration:Secondary cities around Austin, Manchester, and Hyderabad exhibit undersupplied professional services demand with limited incumbent flexible workspace presence.
- Green Mark certification arbitrage:Singapore's BCA thresholds create premium positioning for pre-certified developments, attracting sustainability-mandated multinational tenants at rate premiums.
- AI-enabled space optimization:Convergence of occupancy sensors and predictive analytics enables dynamic pricing and energy management, reducing per-desk operational overhead.
Industry Challenges
- Fire-safety compliance timelines:India's National Building Code administered by BIS imposes extended approval cycles for multi-tenant configurations, delaying market entry in high-demand corridors.
- Enterprise integration complexity:Large technology tenants demand API connectivity with internal access control and visitor management systems, requiring bespoke development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Co-Working Space Services Market |
| Market Size in 2026 | $34.7 Billion |
| Market Size in 2035 | $109.33 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Hot Desking, Dedicated Desks, Private Offices, Virtual Offices End User: Freelancers, Startups, Small Enterprises, Corporations Pricing Model: Hourly, Daily, Monthly, Annual Facility Type: Urban Centers, Suburban Areas, Business Parks, Mixed-Use Developments |
| Companies Covered | IWG plc, WeWork Inc., Industrious Operating Company LLC, Servcorp Limited, JustCo Pte Ltd, Ucommune International Ltd, The Executive Centre, Mindspace, Novel Coworking, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Co-Working Space Services Market Emerging Trajectories
Digitization of building systems and shifting enterprise procurement protocols are compressing traditional real estate service models while elevating data-centric workspace management.
Smart building management platforms integrating IoT sensors, HVAC automation, and access control are electrifying operational efficiency across multi-location portfolios. Enterprise technology teams deploying these systems reduce per-location facility management headcount by half. Real estate investment trusts and institutional landlords now mandate platform interoperability as a tenancy condition.
CSRD disclosure requirements across the European Union impose granular energy-performance reporting on commercial building operators. Scope 3 emission tracking obligations cascade to co-working tenants, forcing providers to install sub-metering infrastructure. German and Dutch operators lead compliance adoption, creating template architectures for Mediterranean markets.
Enterprise procurement departments are consolidating vendor relationships through master service agreements covering distributed location networks. Single-provider contracts replacing fragmented satellite office arrangements compress supplier counts by two-thirds. Financial services and professional services verticals in the United Kingdom and United States drive this consolidation most aggressively.
Co-Working Space Services Market Segmentation
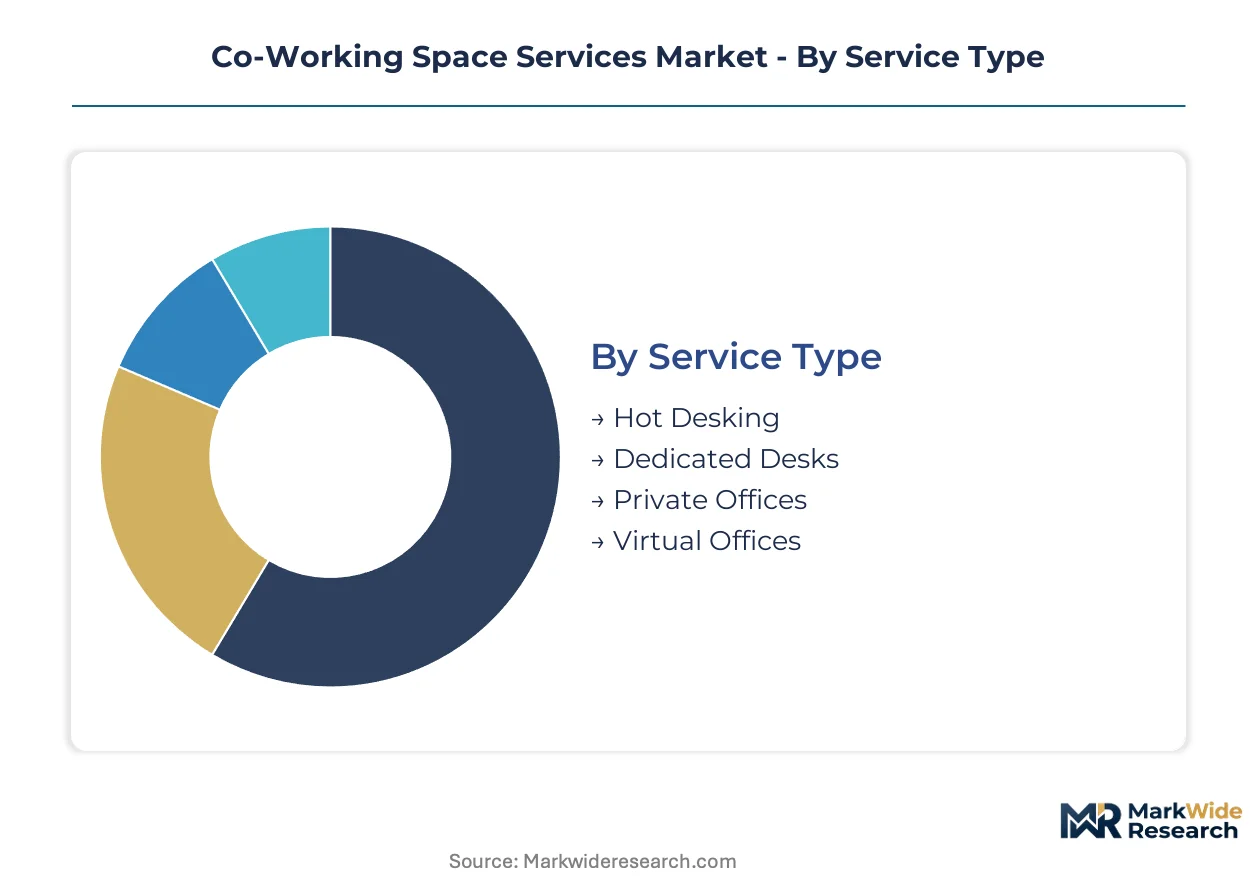
Segmentation in co-working space services reveals how procurement patterns diverge across customer maturity, location strategy, and commitment horizons. Providers calibrate infrastructure investment and contract structures to match these distinct demand profiles.
Service Type:
Cost tier separates occasional users from committed tenants, with pricing elasticity and amenity access scaling accordingly.
- Hot Desking:Unassigned seating in open-floor configurations with shared power and Wi-Fi infrastructure. Freelancers in Bengaluru and Mumbai absorb the bulk of this inventory, driven by venture-funded startup density and limited conventional office supply.
- Dedicated Desks:Permanently reserved workstations within communal areas, offering storage lockability and consistent location. Small enterprises across Singapore's technology corridor favor this tier for team cohesion without private office overhead.
- Private Offices:Enclosed suites with branded entry and dedicated climate control. Corporations under EU Green Deal retrofit mandates seek these for secure, compliant environments in Frankfurt and Paris.
- Virtual Offices:Mailing address and reception services without physical occupancy. Remote-first teams in Austin and Manchester leverage this for market presence in premium postal codes.
Hot desking leads volumes today; private offices are gaining share fastest.
End User:
Customer maturity determines contract length, integration complexity, and service tier requirements.
- Freelancers:Individual knowledge workers purchasing episodic access. India's National Building Code fire-safety parameters filter viable locations for this price-sensitive cohort in high-demand corridors.
- Startups:Venture-backed teams scaling headcount unpredictably. New York City's Local Law 97 carbon caps compress margin for operators serving this segment in pre-war Manhattan stock.
- Small Enterprises:Established companies with 10-50 employees seeking satellite presence. Suburban corridors around Hyderabad exhibit undersupplied demand from this cohort.
- Corporations:Large technology and financial services firms with hybrid work mandates. API connectivity requirements with internal access control systems force bespoke development resources.
Freelancers dominate transaction counts; corporations command revenue concentration.
Pricing Model:
Commitment horizon structures revenue predictability and operational planning horizons for providers.
- Hourly:Transient access for meetings or focused work sessions. Event-based professional use in UAE municipal broadband zones enables rapid deployment without carrier negotiation delays.
- Daily:Single-shift occupancy with inclusive amenity access. Consultants traversing London's financial district favor this for client proximity without lease liability.
- Monthly:Recurring billing with guaranteed seat or office availability. Revenue stability from this structure funds fiber-optic infrastructure densification in South Korean markets.
- Annual:Prepaid contracts with rate locks and expansion rights. Master service agreements in United Kingdom financial services verticals consolidate vendor relationships through this commitment tier.
Monthly contracts anchor revenue stability; annual agreements are expanding most quickly.
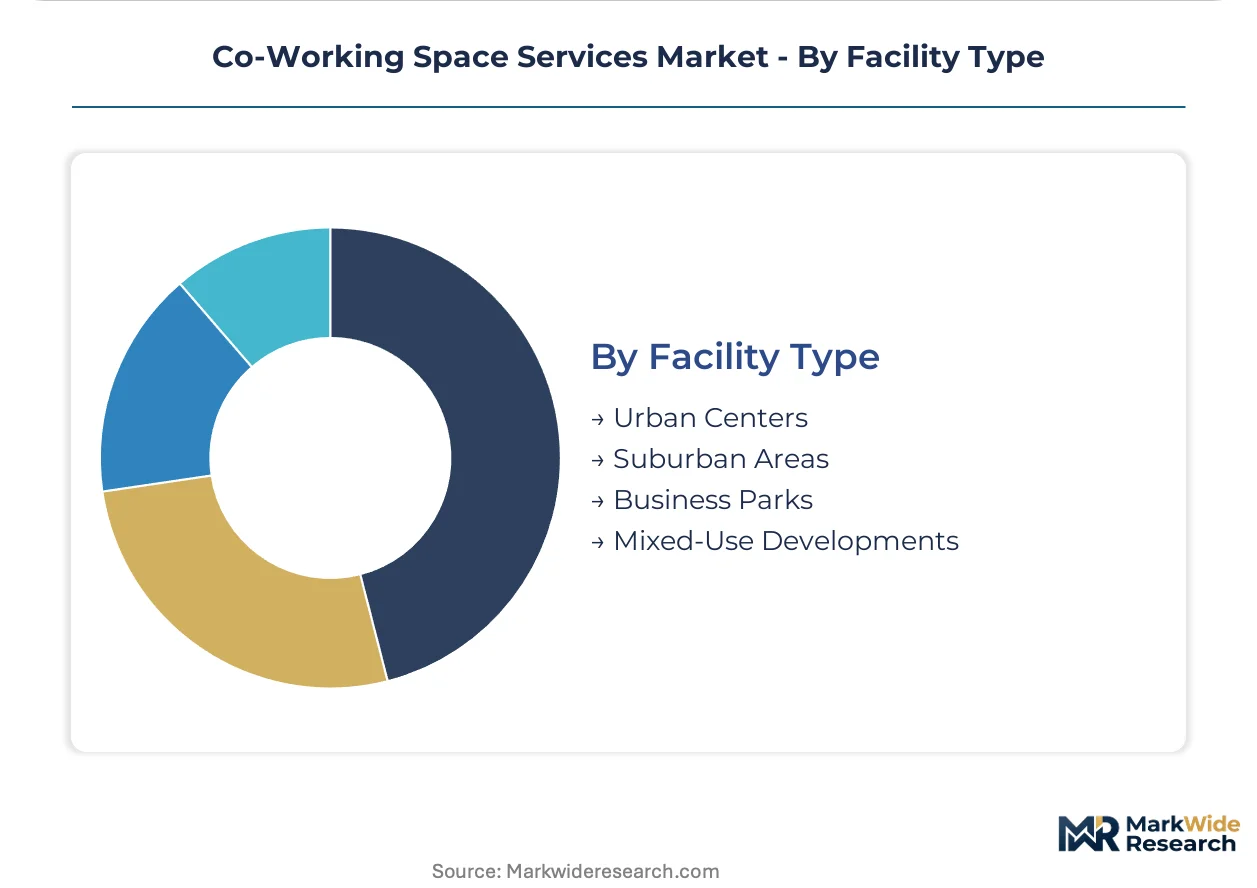
Facility Type:
Geography within metropolitan areas shapes accessibility, parking ratios, and regulatory exposure.
- Urban Centers:Central business district locations with transit connectivity and ground-floor retail. Singapore's Building and Construction Authority Green Mark certification thresholds shape development timelines for new supply in this category.
- Suburban Areas:Residential-adjacent facilities capturing commute-avoidance preferences. Manchester and Austin secondary cities show limited incumbent flexible workspace presence here.
- Business Parks:Campus-style environments with surface parking and campus security. Germany's EU Green Deal retrofit mandates accelerate building modernization demand that operators capture through managed workspace services.
- Mixed-Use Developments:Integrated residential, retail, and office configurations with shared amenity pools. Tokyo's institutional landlord concentration constrains lease negotiation leverage for expanding operators in this format.
Urban centers retain volume leadership; suburban areas show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redistributing co-working investment toward jurisdictions with favorable compliance costs. Operators migrate capital from high-retrofit-burden markets to emerging corridors where building codes remain permissive and energy mandates lag.
United States
Enterprise hybrid mandates fragment real estate demand into satellite networks across Austin and secondary metros. New York City's Local Law 97 imposes carbon-emission caps that elevate retrofit costs for Manhattan providers maintaining pre-war stock. Dallas-Fort Worth absorbs expanding technology tenancy with limited incumbent flexible workspace presence.
Germany
EU Green Deal retrofit mandates accelerate building modernization across Frankfurt and Berlin technology corridors. CSRD disclosure requirements impose granular energy-performance reporting on commercial operators, forcing sub-metering infrastructure installation. Munich clusters concentrate corporate demand for compliant, secure private office environments.
India
Bengaluru and Mumbai technology corridors absorb surging IT services and venture-funded startup tenancy. The Bureau of Indian Standards administers National Building Code fire-safety parameters that filter market-entry feasibility in high-demand corridors. Hyderabad exhibits undersupplied professional services demand with constrained conventional office supply.
Singapore
The Building and Construction Authority mandates Green Mark certification thresholds that shape development timelines for new flexible workspace supply. Financial services and professional services verticals drive vendor consolidation through master service agreements. Marina Bay and Raffles Place clusters command premium positioning for sustainability-mandated multinational tenants.
United Kingdom
Enterprise procurement departments consolidate satellite office arrangements through single-provider contracts covering distributed location networks. London's institutional landlord concentration constrains lease negotiation leverage for expanding operators. Manchester secondary cities show limited incumbent flexible workspace presence amid rising suburban professional services demand.
Co-Working Space Services Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with multi-brand portfolios commanding tier-one density while design-forward independents anchor creative-industry niches. The vendor base organizes around three strategic archetypes: hospitality-infused service tier specialists, satellite-network scale operators, and certification-premium positioning players. Dominant competitive moves include suburban corridor penetration to capture commute-avoidance preferences and API-enabled enterprise integration to secure multinational master service agreements.
Within the multi-brand scale tier, IWG plc occupies a position exemplifying density-focused geographic coverage across tier-one and tier-two cities. WeWork Inc. and Industrious Operating Company LLC represent contrasting hospitality and design-forward archetypes that differentiate through service tier depth and aesthetic positioning respectively. These three anchors illustrate how competitive positioning stratifies between scale-driven network effects and experience-driven tenant retention mechanics.
| Leading Market Players |
|---|
| IWG plc |
| WeWork Inc. |
| Industrious Operating Company LLC |
| Servcorp Limited |
| JustCo Pte Ltd |
| Ucommune International Ltd |
| The Executive Centre |
| Mindspace |
| Novel Coworking |
| Others |
Supply Flow & Price Mechanics
Smart building management platform deployment simultaneously compresses per-location facility management headcount and concentrates procurement leverage among operators with multi-location portfolios. Fiber-optic infrastructure densification across Singapore, South Korea, and the UAE reduces connectivity provisioning costs, redistributing margin pressure toward energy-efficiency compliance investments under the EU Green Deal and New York Local Law 97.
Pricing Analysis
Direct-to-enterprise contract structures bypass traditional broker markups, compressing channel margins while expanding rate transparency. Three-tier pricing structure across premium, standard, and economy levels segments by certification grade and amenity depth, with Green Mark certified locations in Singapore commanding rate premiums. Cost compression in Manhattan pre-war stock intensifies because Local Law 97 retrofit obligations compound operating overhead. Freelancers and early-stage ventures exhibit highest price sensitivity, while corporations under hybrid mandates demonstrate lowest elasticity due to integration requirements.
Supply Chain Analysis
Regional distribution centers in Germany, India, and Singapore anchor hub-and-spoke patterns for ergonomic furnishings and telecommunications infrastructure. Providers draw from Chinese manufacturing for workstation assemblies, Vietnamese textile suppliers for soft furnishings, and domestic contractors for climate-control installation. Single-source vulnerability concentrates in fiber-optic carrier relationships where municipal broadband initiatives remain incomplete. Distribution runs through landlord-integrated service agreements in tier-one cities, constraining operator negotiation leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
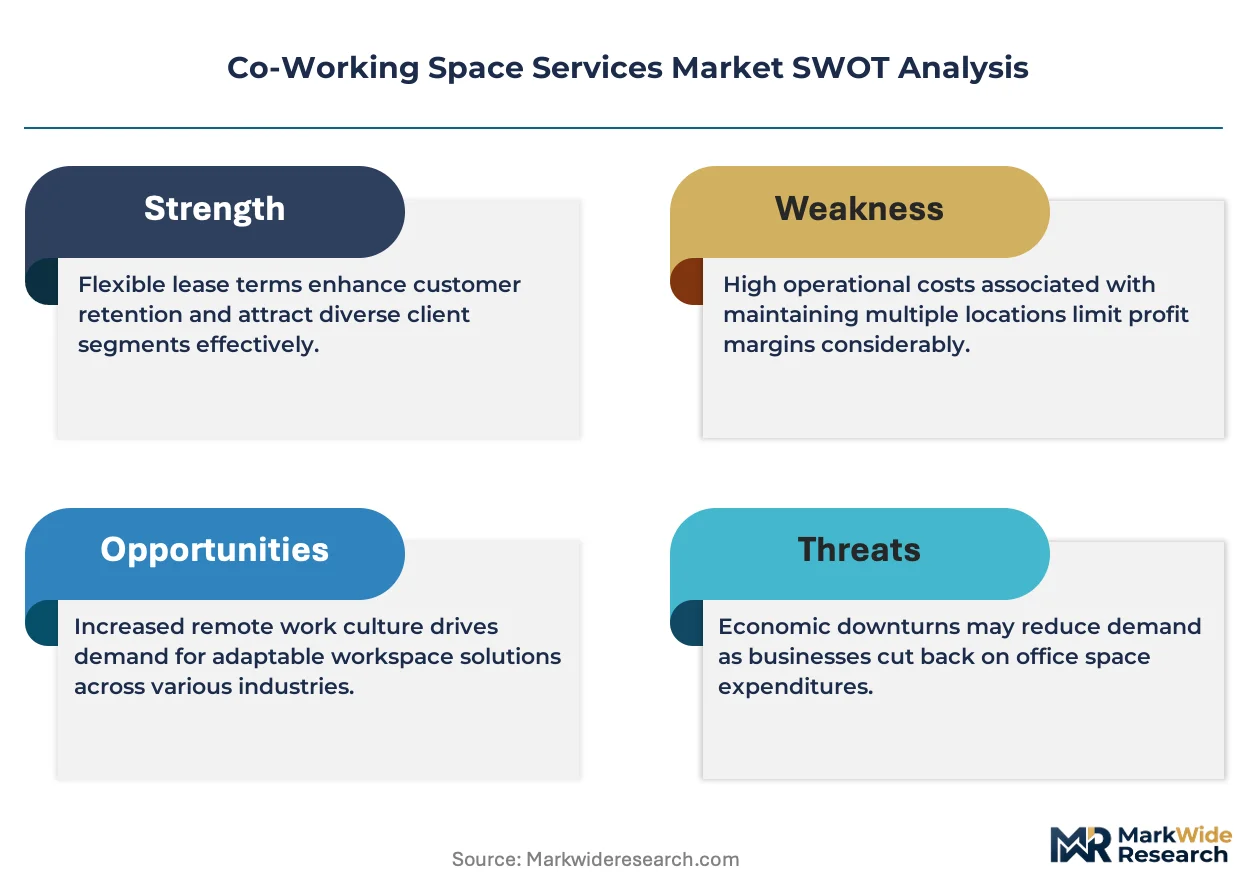
The co-working space services market functions as a regulatory compounder where EU Green Deal retrofit mandates and New York Local Law 97 carbon caps simultaneously elevate compliance costs and consolidate viable supply among capitalized operators.
For Market Incumbents: Deploy AI-enabled space optimization to reduce per-desk operational overhead and defend margin position against remote collaboration software substitution. Expand suburban corridor presence around Austin, Manchester, and Hyderabad to capture commute-avoidance preferences before emerging entrants establish density. Prioritize API connectivity investments to secure multinational master service agreements that lock in annual contract structures. For New Entrants and Emerging Players: Begin with virtual office and hot desking tiers in secondary Indian cities where National Building Code fire-safety timelines delay incumbent expansion. Target sustainability-mandated multinational tenants in Singapore by securing pre-certified Green Mark developments that command rate premiums. Pursue hospitality-infused service differentiation to anchor tenant retention against scale-driven competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among suburban-focused operators with limited tier-one exposure but established local density. Long-term viability centers on regulatory arbitrage capacity and platform interoperability for enterprise integration. Monitor municipal zoning reform velocity as the inflection indicator for operating-cost redistribution across facility-type segments.| Strategic Initiative | Industry Significance |
|---|---|
| Green Certification Program | EU Green Deal compliance positions operators for mandatory retrofit contracts across Frankfurt and Berlin corridors. |
| Suburban Corridor Expansion | Undersupplied demand around Austin and Manchester captures commute-avoidance preferences with limited incumbent presence. |
| API Platform Integration | Enterprise access control connectivity secures multinational master service agreements in UK financial services verticals. |
| AI-Enabled Space Optimization | Predictive analytics reduce per-desk operational overhead while supporting dynamic pricing across variable occupancy loads. |
| Long-term Supply Agreement | Fiber-optic infrastructure partnerships with municipal broadband initiatives eliminate carrier negotiation delays in UAE zones. |
Methodological Framework
Multiple input streams — facility operator interviews, landlord procurement lead discussions, tenant experience surveys, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary engagement with co-working portfolio directors, commercial real estate brokers, enterprise workplace strategists, and municipal planning officials informed operational cost structures and contract velocity patterns. Secondary validation drew from Building and Construction Authority certification databases, Bureau of Indian Standards compliance records, SEC real estate investment trust filings, and EU energy-performance disclosure registries. Bottom-up location-level capacity assessments and top-down metropolitan absorption projections were triangulated to anchor forecast ranges.
Data-stream reconciliation across the projection horizon applied service type, end user maturity, pricing model commitment tier, and facility type geography as core segmentation dimensions. CAGRs were derived from rolling absorption rates against supply pipeline visibility, with hybrid work policy permanence and energy-retrofit cost trajectories as primary swing variables. Enterprise procurement consolidation patterns and municipal broadband deployment schedules served as industry-specific forecast modifiers.
Caveats apply where remote collaboration software substitution acceleration or abrupt regulatory enforcement relaxation could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate Services
Global Self Storage Market
Real Estate Services
Public Warehousing Market
Real Estate Services
Latin America Coworking Spaces Market
Real Estate Services
Coworking Spaces Market
Real Estate Services
Global Home Services Market
Real Estate Services
Asia-Pacific Self Storage Market
Real Estate Services
US Real Estate and Hospitality Market
Real Estate Services
United Arab Emirates Real Estate Services Market
Real Estate Services
Warehousing and Storage Services Market
Real Estate Services
Thailand Real Estate Market
Real Estate Services
Property Tax Services Market
Real Estate Services
Green Lease Market
Real Estate Services
US Landscaping Services Market
Real Estate Services
Switzerland Self-Storage Market
Real Estate Services
United States Real Estate Services Market
Real Estate Services
Home Warranty Service Market