
 FIBC Market | 2026-2036
FIBC Market Size, Share, and Industry Trends Forecast 2026-2036
FIBC Market Analysis
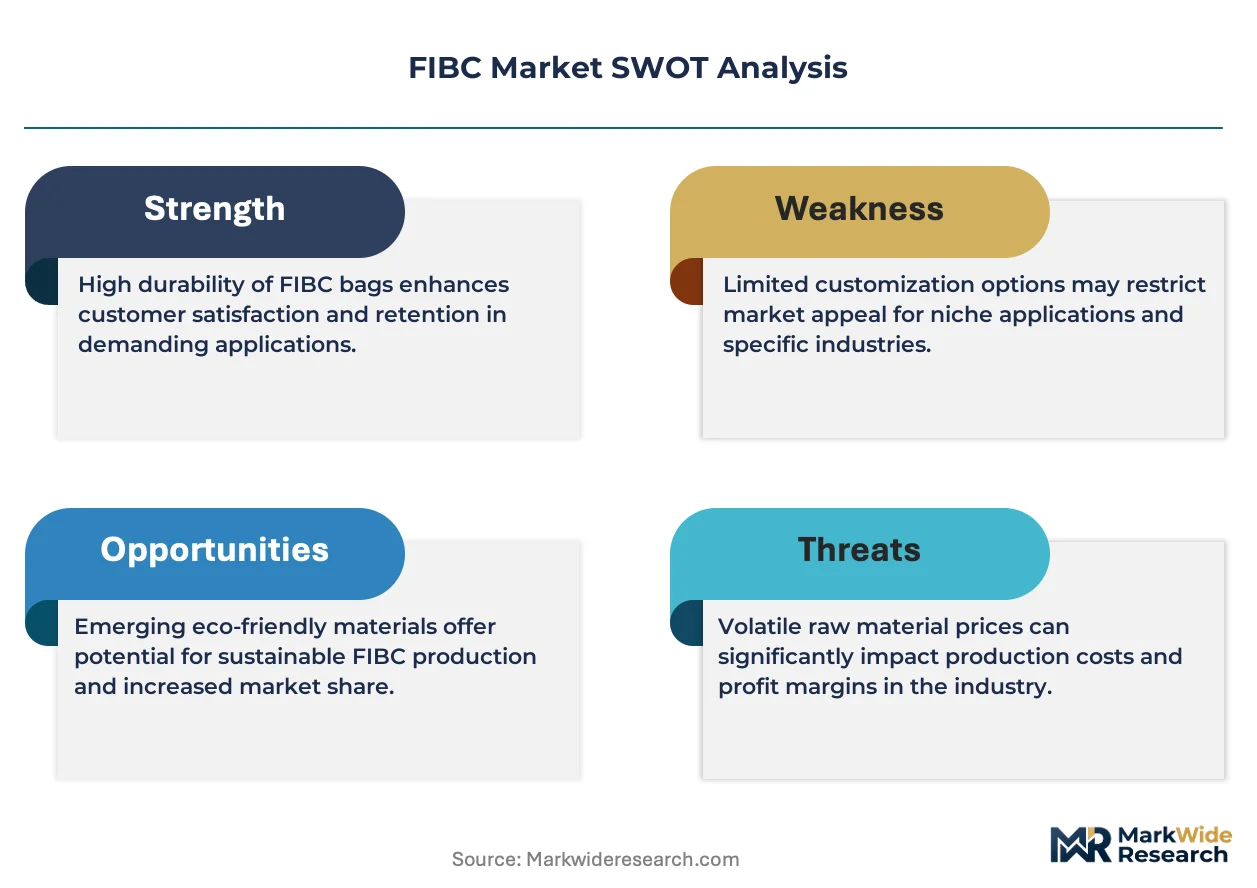
REACH compliance is broadening the cost-of-entry calculus for European-bound FIBC shipments, compelling manufacturers to certify virgin and recycled polypropylene streams. Greif Inc. anchors its position through captive resin sourcing and integrated woven fabric production across North American plants. Rishi FIBC Solutions Pvt Ltd dominates South Asian export channels with specialized conductive and food-grade bag certifications. Bulkcorp International extends its footprint via dedicated facilities serving Middle Eastern petrochemical clients.
Flexible intermediate bulk containers are large woven polypropylene bags, typically rated for 500–2,000 kg loads, designed for storing and transporting dry flowable materials in granular, powder, or flake form. Standard FIBC commands the volume base across cement and mineral applications, though conductive FIBC captures premium pricing in flammable chemical handling where static dissipation is mandatory. Biodegradable material experimentation remains nascent but draws procurement interest from European food distributors facing extended producer responsibility obligations under the EU Green Deal.
The US EPA oversees industrial packaging waste streams, while India's BIS enforces load-testing protocols for export-bound bulk bags, and ISO 21898 defines cyclic top-lift and drop-test benchmarks that govern cross-border acceptance. Regulatory divergence between jurisdictions forces manufacturers to maintain parallel certification tracks, elevating working capital requirements for multi-market suppliers. Stakeholders must weigh regional compliance trajectories against capacity localization decisions as carbon-border adjustments reshape landed cost structures.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material transitions across woven polypropylene supply chains, compelling manufacturers to requalify virgin and recycled resin streams for European-bound shipments.
Growth Catalysts
- REACH compliance expansion:Chemical certification requirements for European import channels are pulling investment into traceable polypropylene sourcing and testing infrastructure.
- Agricultural commodity handlers:Brazilian soybean and Southeast Asian palm oil exporters are scaling bulk packaging procurement to match harvest volume growth and port modernization timelines.
- Conductive FIBC adoption:Static-dissipative bag specifications are penetrating flammable chemical handling operations where solvent-based formulations dominate material flows.
Market Restraints
- Polypropylene resin volatility:Crude-linked feedstock pricing swings compress margin predictability for converters lacking captive resin supply.
- Weaving capacity concentration:Fabric production clusters in Gujarat and Zhejiang create geographic single-point vulnerabilities for non-integrated bag manufacturers.
- Recyclate quality inconsistency:Post-consumer polypropylene degradation limits load-bearing performance in heavy-duty applications, constraining circular content targets.
Strategic Opportunities
- Indian chemical export corridors:Gujarat and Maharashtra port infrastructure expansion is creating dedicated demand for food-grade and conductive certifications serving Middle Eastern and European clients.
- Extended producer responsibility mandates:EU Green Deal packaging obligations are opening procurement channels for biodegradable material experiments among food distributors.
- Digital printing integration:Variable-data bag marking is converging with track-and-trace requirements, enabling lot-level accountability for pharmaceutical and food-grade shipments.
Industry Challenges
- Parallel certification maintenance:Manufacturers serving multiple jurisdictions must sustain separate BIS, ISO 21898, and REACH qualification tracks, elevating working capital intensity.
- Drop-test protocol divergence:Cyclic top-lift and drop-test benchmarks vary between Indian export requirements and European acceptance standards, complicating single-SKU strategies.
- Carbon-border adjustment preparation:Embedded emissions documentation requirements are forcing resin sourcing audits and supplier requalification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FIBC Market |
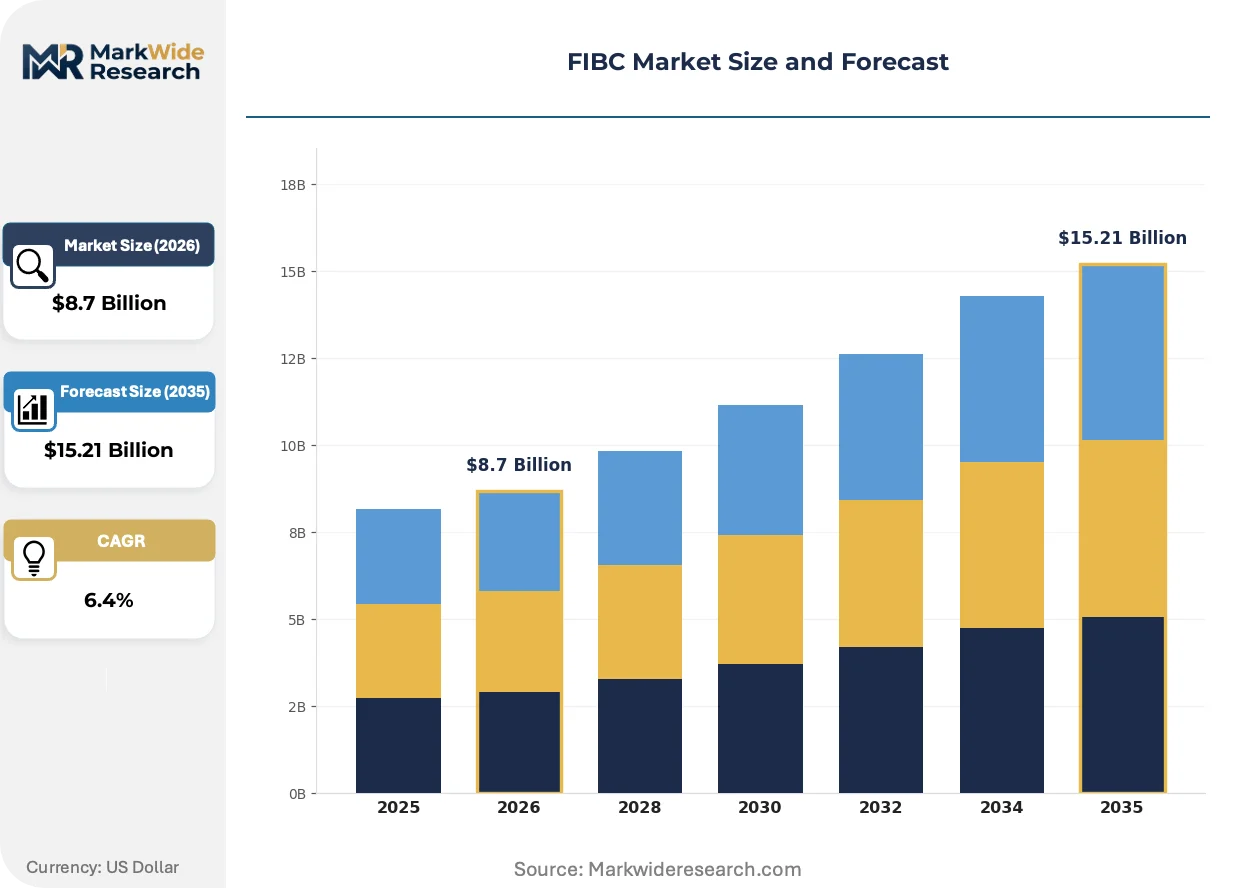
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard FIBC, Conductive FIBC, Ventilated FIBC, Printed FIBC Material: PP Woven, PE Coated, Biodegradable, Recycled Material Application: Food, Chemicals, Pharmaceuticals, Construction Size: Small, Medium, Large, Custom |
| Companies Covered | United Bags Inc., Nghe An Packaging Joint Stock Company, Greif Inc., Global-Pak, Bulk Bag Depot, Mauser Packaging Solutions, Rishi FIBC Solutions Pvt Ltd, Bulkcorp International, Amcor, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FIBC Market Emerging Trajectories
Material science advances and regulatory documentation requirements are reshaping competitive positioning in woven bulk packaging, with differentiation increasingly tied to certification breadth and circular content verification.
Anti-static masterbatch technology is converging with conductive yarn weaving processes to produce Type C and Type D FIBC variants. Petrochemical handlers in Rotterdam and Antwerp terminals are specifying these bags for solvent and powder transfers. The technology is converging with insurance risk assessments, compressing approval timelines for hazardous material shipments.
REACH SVHC candidate list expansion is tightening substance disclosure obligations for polypropylene additives and colorants. European converters must now document phthalate and heavy metal content down to 0.1% weight thresholds. Food-grade and pharmaceutical FIBC segments are responding with dedicated clean-room production lines and additive-free resin specifications.
Buyers are consolidating vendor panels around integrated suppliers capable of resin-to-bag traceability. Cement and mineral handlers in Turkey and Egypt are shifting from spot procurement to framework agreements with annual volume commitments. This concentration is most visible in Middle Eastern petrochemical supply chains, where integrated converters are displacing trading-house intermediaries.
FIBC Market Segmentation
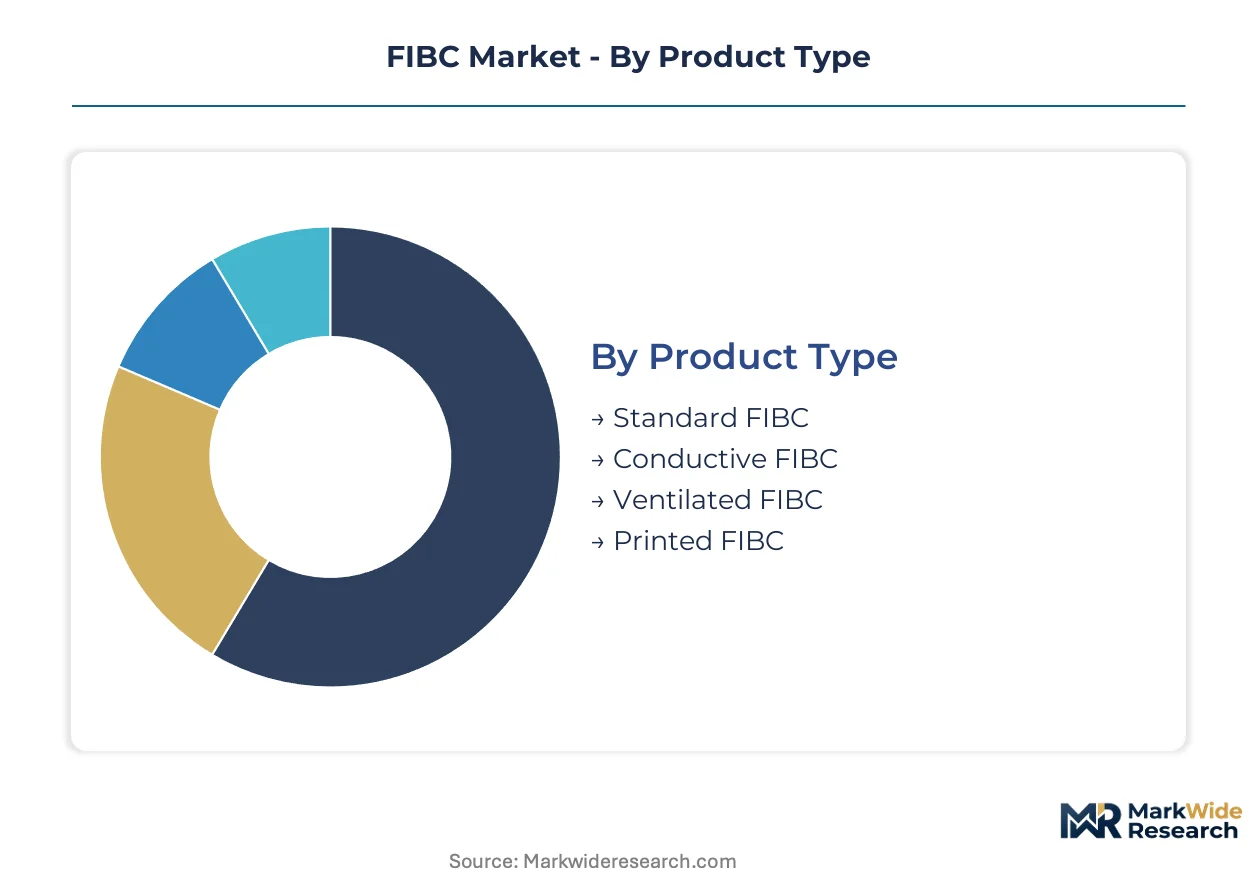
FIBC segmentation maps directly to regulatory compliance tiers and handling risk profiles. Product specifications determine certification requirements, while material composition governs recyclability obligations under EU Packaging and Packaging Waste Regulation mandates.
Product Type:
Technical specifications differentiate FIBC variants across electrostatic risk, breathability, and branding requirements.
- Standard FIBC:Unlined woven polypropylene construction rated for 500–2,000 kg dry bulk loads. Cement handlers in Turkey and Egypt dominate procurement, with procurement shifting from spot buying to annual framework agreements requiring volume commitments.
- Conductive FIBC:Type C and Type D variants incorporate conductive yarns or anti-static masterbatch for static dissipation. Rotterdam and Antwerp petrochemical terminals specify these bags for solvent and powder transfers, with insurance risk assessments compressing approval timelines for hazardous material shipments.
- Ventilated FIBC:Mesh-panel construction enables airflow for moisture-sensitive agricultural commodities. Brazilian soybean exporters scale procurement to match harvest volumes and port modernization timelines.
- Printed FIBC:Digital variable-data marking supports lot-level track-and-trace for pharmaceutical and food-grade shipments. European food distributors facing extended producer responsibility obligations under the EU Green Deal drive adoption.
Standard FIBC leads on scale; Conductive FIBC leads on momentum.
Material:
Resin sourcing and circular content verification increasingly determine supplier qualification in European-bound channels.
- PP Woven:Virgin polypropylene dominates heavy-duty applications. REACH SVHC candidate list expansion tightens additive disclosure obligations, forcing converters to document phthalate and heavy metal content down to 0.1% weight thresholds.
- PE Coated:Polyethylene liner integration provides moisture barrier protection for hygroscopic chemicals. Middle Eastern petrochemical clients specify coated constructions for humidity-exposed supply chains.
- Biodegradable:Experimental starch-based and PLA blends draw procurement interest from European food distributors. Material performance in load-bearing applications remains unproven at commercial scale.
- Recycled Material:Post-consumer polypropylene feedstock faces quality inconsistency constraints. Degradation limits load-bearing performance, constraining circular content targets in heavy-duty cement and mineral applications.
PP Woven commands volume share; Recycled Material faces the steepest compliance climb.
Application:
End-use specifications cascade into certification depth and production environment requirements.
- Food:FSSAI and EU food-contact compliance mandate dedicated clean-room production lines and additive-free resin specifications. India's chemical and food export corridors around Gujarat and Maharashtra create concentrated demand for food-grade certifications.
- Chemicals:Flammable solvent handling drives Type C and Type D FIBC adoption. Static-dissipative specifications penetrate operations where solvent-based formulations dominate material flows.
- Pharmaceuticals:Lot-level accountability requirements converge with digital printing integration. Track-and-trace mandates elevate bag marking specifications.
- Construction:Cement and mineral handlers in Turkey and Egypt consolidate vendor panels around integrated suppliers capable of resin-to-bag traceability.
Construction anchors volume; Chemicals commands premium pricing tiers.
Size:
Dimensional specifications align with handling equipment and storage constraints across port and warehouse infrastructure.
- Small:Compact footprints suit manual handling in constrained warehouse environments. Pharmaceutical and specialty chemical applications favor smaller formats for batch control.
- Medium:Balanced payload-to-handling ratio serves general industrial applications. Most common specification across diversified chemical handlers.
- Large:Maximum payload ratings optimize vessel and container utilization. Bulk commodity exporters in Brazil and Southeast Asia specify large formats for port efficiency.
- Custom:Dimensional tailoring matches specialized filling and discharge equipment. Integrated converters capture value through engineering collaboration.
Large sizes dominate export corridors; Custom configurations expand fastest in pharmaceutical channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Weaving technician pools in Gujarat and Zhejiang anchor production capacity for woven polypropylene fabric. These concentrations shape regional supply reliability and certification specialization across export corridors.
United States
Cement handlers and chemical distributors drive FIBC procurement volumes. The EPA oversees industrial packaging waste streams through Resource Conservation and Recovery Act frameworks. Integrated converters in the Gulf Coast petrochemical belt maintain captive resin sourcing for domestic bag production.
Germany
REACH compliance mandates are tightening substance disclosure thresholds for polypropylene additives. ECHA enforcement of SVHC candidate list expansions compels documentation down to 0.1% weight thresholds. Industrial packaging demand concentrates around Rhine-Ruhr chemical handling terminals and Hamburg port logistics clusters.
India
Food-grade and chemical export corridors through Gujarat and Maharashtra are scaling certification infrastructure. BIS enforces load-testing protocols for export-bound bulk bags under ISO 21898 alignment. The Mundra and JNPT port zones attract integrated weaving-to-bag manufacturing investments.
Brazil
Soybean and agricultural commodity exporters are matching harvest volumes with bulk packaging procurement scales. ANVISA oversees food-contact compliance for export-bound shipments. Port modernization at Santos and Paranaguá is driving large-format FIBC specifications for vessel utilization efficiency.
China
Weaving capacity clusters in Zhejiang province supply fabric to converters across Asia-Pacific chemical export channels. GB standards and MIIT regulations govern industrial packaging quality benchmarks. The Yangtze River Delta petrochemical corridor sustains captive resin-to-fabric production integration.
FIBC Market Vendor Landscape
The competitive structure tilts toward integrated resin-to-bag manufacturers with captive weaving capacity. Tiering separates multi-plant integrated operators from regional converters dependent on merchant fabric supply. Two strategic archetypes dominate: vertically integrated specialists controlling upstream resin and weaving, and certification-focused exporters serving regulated European and Middle Eastern channels. Capacity expansion and geographic licensing partnerships represent the primary competitive moves as carbon-border documentation requirements reshape supplier qualification.
Among North American integrated packaging groups, Greif Inc. and Mauser Packaging Solutions occupy positions exemplifying captive resin sourcing and multi-plant woven fabric production. Vietnamese fabricators such as Nghe An Packaging Joint Stock Company represent the export-specialist archetype, anchoring regional supply to Southeast Asian agricultural commodity channels. Indian specialists including Rishi FIBC Solutions Pvt Ltd and Bulkcorp International sit within the certification-intensive tier, serving Middle Eastern petrochemical and European food-grade procurement requirements.
| Leading Market Players |
|---|
| United Bags Inc. |
| Nghe An Packaging Joint Stock Company |
| Greif Inc. |
| Global-Pak |
| Bulk Bag Depot |
| Mauser Packaging Solutions |
| Rishi FIBC Solutions Pvt Ltd |
| Bulkcorp International |
| Amcor |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap converters in Gujarat and Zhejiang anchor woven fabric supply, translating concentrated ownership into pricing discipline that resists spot-market volatility. Their captive loom networks buffer resin cost swings while framework agreements with cement handlers in Turkey and Egypt lock annual volume commitments.
Pricing Analysis
Bundled certification-plus-logistics contracts separate premium-tier conductive FIBC from unbundled standard bag transactions. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth—Type C and Type D static-dissipative bags command spreads over unlined constructions due to REACH documentation and insurance risk assessments. Cost compression in standard grades intensifies because merchant fabric buyers face polypropylene resin volatility without captive supply. Cement and mineral handlers exhibit highest price sensitivity, while Rotterdam petrochemical terminals prioritize specification compliance over unit economics.
Supply Chain Analysis
Regional distribution centers in Mundra, JNPT, and Santos manage hub-and-spoke patterns for agricultural commodity exporters. Fabric production clusters in India, China, and Vietnam feed converters across Middle Eastern and European channels. Raw material flows draw from virgin polypropylene resin, conductive masterbatch additives, and PE liner films. Single-source vulnerability concentrates in Zhejiang weaving capacity, where loom downtime ripples through non-integrated bag manufacturers. Distribution runs through port-centric logistics clusters serving chemical and food export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Chemical handlers in Rotterdam and Antwerp are consolidating procurement around conductive FIBC specifications that demand traceable resin-to-bag documentation.
For Market Incumbents: Cement captive resin sourcing through backward integration into polypropylene supply, particularly around Gulf Coast and Yangtze River Delta petrochemical belts. Expand clean-room production lines for food-grade and pharmaceutical certifications before EU Green Deal extended producer responsibility mandates harden. Defensive moats deepen through ISO 21898 and REACH qualification tracks that merchant fabric buyers cannot replicate. For New Entrants and Emerging Players: Launch via digital printing integration for lot-level track-and-trace in pharmaceutical and food-grade channels. White-space concentrates in biodegradable material experiments for European food distributors facing circular content obligations. Target ventilated FIBC specifications for Brazilian soybean exporters scaling procurement to match harvest volumes. Go-to-market leverage rests on engineering collaboration for custom dimensional configurations. For Investors and Strategic Acquirers: Valuations sit cheapest among regional converters dependent on merchant fabric supply, as integrated resin-to-bag operators capture widening margin spreads. Long-term viability favors specialists with captive weaving and certification breadth serving regulated European and Middle Eastern channels. Watch carbon-border adjustment implementation timelines as the inflection signal for supplier requalification urgency.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Greif Inc. and Mauser Packaging Solutions anchor margin stability through captive polypropylene sourcing. |
| Clean-Room Production Investment | EU REACH SVHC disclosure mandates force additive-free resin specifications for food-grade FIBC segments. |
| Digital Printing Integration | Lot-level track-and-trace convergence enables pharmaceutical and food-grade procurement channel access. |
| Conductive FIBC Certification Expansion | Type C and Type D specifications penetrate Rotterdam and Antwerp petrochemical terminals for solvent handling. |
| Geographic Licensing Partnerships | Vietnamese fabricators extend regional supply reach to Southeast Asian agricultural commodity channels. |
Methodological Framework
Bottom-up chemical and food export modeling reconciled against top-down weaving capacity tracking forms the analytical core. Primary interviews with plant managers at integrated converters, procurement leads at cement and petrochemical handlers, distribution channel partners in Middle Eastern logistics clusters, and technical R&D directors at masterbatch suppliers inform demand-side calibration. Secondary validation draws from BIS load-testing protocols, ECHA SVHC candidate list expansions, ISO 21898 benchmark documentation, customs records for woven polypropylene fabric trade flows, and SEC filings from North American packaging groups.
Historical trendline analysis of certification infrastructure investment and resin-to-fabric production integration patterns anchors projection logic. Segmentation dimensions span product type across electrostatic risk tiers, material composition including virgin and recycled polypropylene streams, end-use application from construction to pharmaceuticals, and regional production hub specialization. CAGRs derive from volume-weighted capacity expansion schedules and regulatory compliance cost trajectories. Forecast inputs incorporate REACH documentation burden escalation and carbon-border adjustment preparation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under polypropylene resin volatility spikes or abrupt EU Packaging and Packaging Waste Regulation enforcement shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Plastic Bags and Sacks Market
Bags and Containers
Refuse Bags Market
Bags and Containers
Freezer Bags Market
Bags and Containers
Drum Liners Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Zipper Bags Market
Bags and Containers
Flat Bottom Bags Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Cooler Bags Market
Bags and Containers
Global Bag Filling Machines Market
Bags and Containers
Pre-Made Bags Market
Bags and Containers
North America Retail Bags Market
Bags and Containers
Single Lip Bags Market
Bags and Containers
2 Loop FIBC Bags Market
Bags and Containers
Americas Plastic Bags and Sacks Market