
 BOPP Bags Market | 2026-2036
BOPP Bags Market Size, Share, and Industry Trends Forecast 2026-2036
BOPP Bags Market Outlook
Southeast Asian polypropylene film extruders is broadening woven bag capacity to serve rice and fertilizer exporters. Berry Global Inc. leverages vertical integration from resin to finished bag across North American agricultural channels. United Bags Inc. anchors its position through specialty lamination for moisture-sensitive industrial chemicals. LC Packaging competes on certified food-grade gusseted formats for European retail private labels.
Biaxially oriented polypropylene (BOPP) bags consist of woven polypropylene fabric coated with oriented PP film, typically achieving tensile strengths of 30–50 N/mm² and moisture vapor transmission rates below 5 g/m²/day, serving primary roles in bulk grain handling, fertilizer distribution, and retail food packaging. Gusseted bags occupy the dominant volume position due to superior stackability in containerized shipping, while zipper bags represent the fastest margin pool as snack food brands convert from multilayer laminates. The 30 micron thickness tier sustains the broadest cross-industry adoption, balancing unit economics against puncture resistance requirements.
India's BIS certification mandates migration limits for food-contact polypropylene, while REACH compliance in Europe restricts certain phthalate plasticizers in bag coatings, and FDA food contact notifications govern U.S. import eligibility for woven PP food packaging. These frameworks elevate testing costs for smaller extruders but create barrier-to-entry advantages for accredited producers. Stakeholders must monitor evolving extended producer responsibility schemes in target export markets, as these programs will increasingly determine supplier qualification status without explicit regulatory deadlines.
Market Dynamics
EU REACH compliance on phthalate plasticizers and India's BIS migration limits for food-contact polypropylene are compressing supplier margins while accelerating accreditation-driven consolidation among extruders serving agricultural and food export channels.
Growth Catalysts
- EU REACH additive restrictions:Phased limitations on certain plasticizers in bag coatings are forcing reformulation investments that accredited producers convert into pricing power over smaller competitors.
- Rice export volumes from Southeast Asian manufacturing clusters:Vietnam, Thailand, and Indonesia are expanding containerized grain shipments that favor gusseted BOPP formats for stackability and moisture protection.
- Co-extrusion lamination:Advanced multi-layer coating lines enable 30-micron films to achieve sub-5 g/m²/day vapor transmission rates, opening industrial chemical applications previously served by multilayer laminates.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracker output fluctuations in Middle Eastern and North American petrochemical complexes transmit directly to woven fabric input costs.
- Extruder concentration in East Asian coastal zones:Overreliance on Zhejiang and Guangdong provinces for biaxial orientation equipment creates single-point vulnerability to port congestion and power rationing.
- Polyethylene woven sack substitution:Lower-cost PE alternatives are capturing price-sensitive fertilizer markets in Sub-Saharan Africa and Central Asian landlocked economies.
Strategic Opportunities
- Brazilian agricultural mechanization:Soybean and corn handlers in Mato Grosso and Goiás are converting from bulk handling to pre-packed BOPP formats for containerized export to Chinese crushers.
- EU extended producer responsibility schemes:Packaging waste directives in Germany, France, and Italy will mandate recycled content thresholds, creating first-mover advantage for extruders with post-industrial scrap integration.
- Digital print integration with form-fill-seal lines:Variable-data printing on oriented film enables batch-traceable QR codes for European retail private labels seeking supply chain transparency.
Industry Challenges
- BIS food-grade certification timelines:Indian extruders face 14-18 month approval cycles for migration testing, delaying market entry against accredited competitors.
- Slitter-rewinder operator scarcity:Tension control expertise for micron-thin film handling is concentrated among aging workforces in established manufacturing regions.
- Legacy ERP integration with traceability systems:Batch recording for REACH and FDA compliance requires retrofitting decades-old extrusion plant control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | BOPP Bags Market |
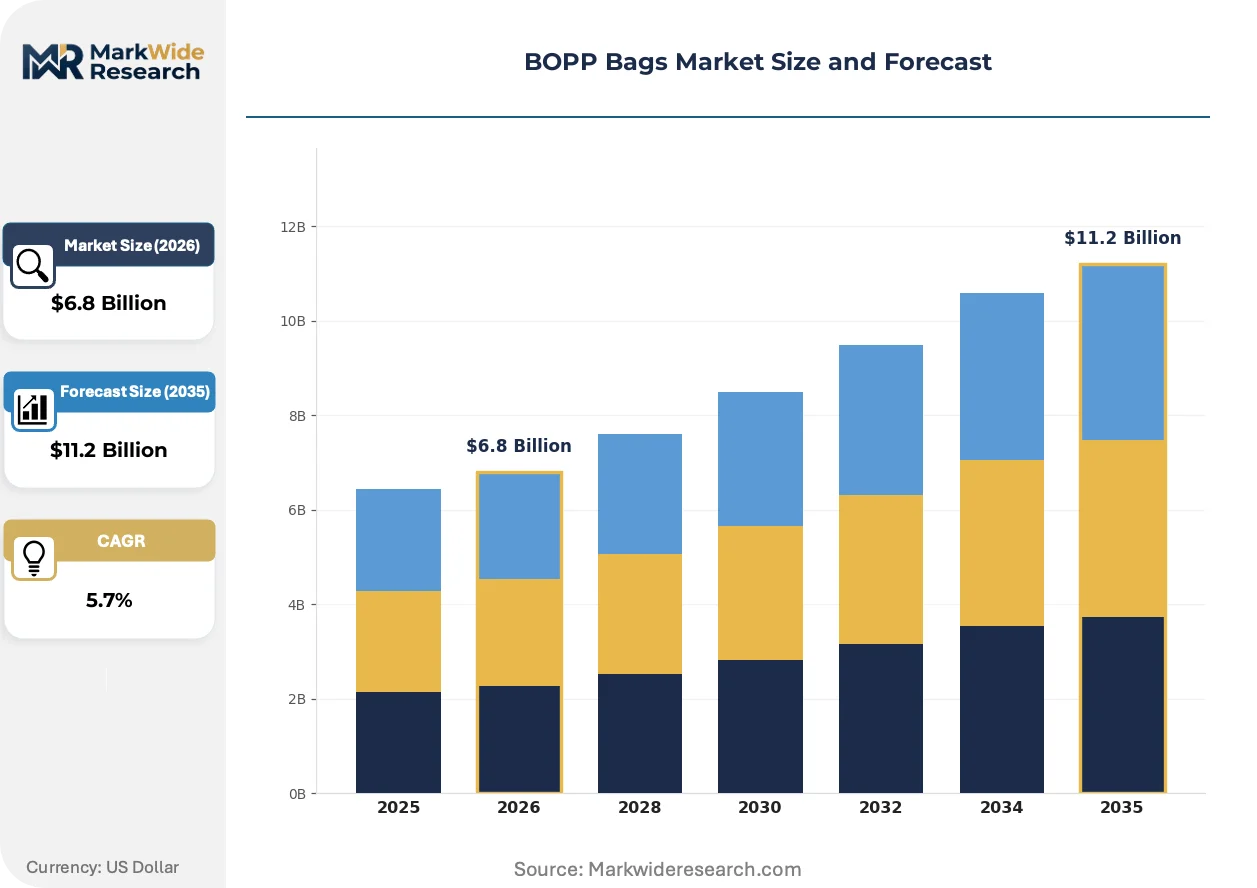
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flat Bags, Gusseted Bags, Zipper Bags, Die-Cut Bags End User: Food Packaging, Retail, Agricultural, Industrial Thickness: 20 Micron, 30 Micron, 40 Micron, 50 Micron Printing Type: Flexographic, Gravure, Digital, Others |
| Companies Covered | Berry Global Inc., United Bags Inc., Manyan Inc., LC Packaging, Umasree Texplast, Cosmos Films Ltd., Indra Industries Ltd., Abdos Polymers Ltd., Hanoi Plastic Bag JSC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
BOPP Bags Market Strategic Shifts
Active barrier technologies and digital manufacturing controls are compressing specification tolerances while regulatory traceability mandates are rewiring supplier qualification protocols across food and chemical end-uses.
High-barrier metallized BOPP films with aluminum oxide or silicon oxide coatings are absorbing moisture-sensitive applications previously served by aluminum foil laminates. Specialty coffee roasters in Nordic markets and probiotic snack brands in North American natural channels are specifying these formats for 12-month shelf stability. The technology is absorbing margin from multilayer flexible packaging converters who lack metallization capacity.
REACH Annex XVII restrictions on phthalates and emerging restrictions on PFAS in food-contact materials are forcing coating chemistry reformulations across European supply chains. Extruders serving German and French retail private labels are accelerating non-fluorinated barrier development to preempt 2025-2027 restriction timelines. The policy shift most affects mid-tier producers dependent on legacy solvent-based adhesive systems.
Direct mill-to-farm procurement contracts are consolidating buyer power among Brazilian and Indian agricultural cooperatives. These arrangements bypass traditional distributor networks and specify certified food-grade gusseted formats with embedded traceability coding. The pattern is most visible in Maharashtra's sugarcane belt and Paraná's poultry feed operations, where handler consolidation has reduced qualified supplier pools to three-to-four accredited extruders per region.
BOPP Bags Market Segmentation
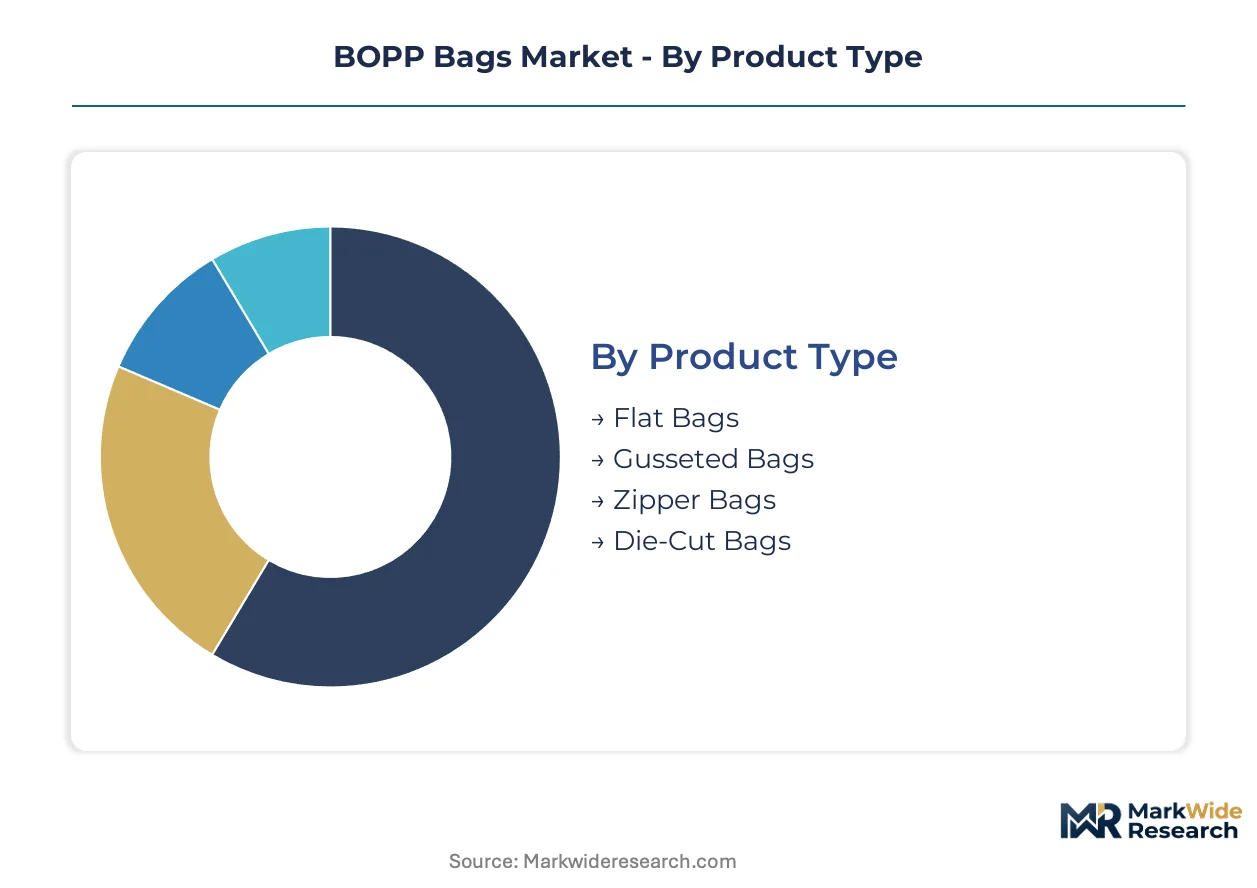
BOPP bag specifications vary sharply across handling requirements, regulatory exposure, and shelf-life demands. Buyers select formats based on stacking geometry, moisture sensitivity, and traceability mandates rather than commodity pricing alone.
Product Type:
Container utilization rates and pallet stability drive format selection more than material cost differentials.
- Gusseted Bags:Four-sided expansion panels enable rectangular stacking profiles that maximize container cube efficiency for rice and fertilizer shipments. Vietnamese and Thai exporters specify these formats for 20-foot container loads where floor space optimization directly reduces freight cost per ton.
- Zipper Bags:Reclosable track systems bonded to oriented film substrates serve snack brands converting from multilayer laminates for portion control and shelf visibility. North American natural food channels specify these for probiotic and specialty nut applications where reseal functionality supports extended consumption windows.
- Flat Bags:Two-dimensional sealing surfaces suit high-speed form-fill-seal lines for sugar and salt where product flow characteristics permit minimal headspace. Indian processors favor these for domestic distribution where pallet stacking height is constrained by warehouse clearance.
- Die-Cut Bags:Pre-formed handle apertures serve retail produce and bakery segments requiring consumer carry functionality without secondary bagging.
Volume sits with Gusseted Bags; growth tilts toward Zipper Bags.
End User:
Regulatory stringency and contamination liability create divergent specification tiers across customer categories.
- Food Packaging:Migration-tested substrates meeting BIS and FDA food-contact notifications command premium positioning for rice, flour, and pulse exports. Indian extruders with accredited testing protocols capture recurring orders from Maharashtra and Andhra Pradesh processing cooperatives.
- Agricultural:Fertilizer and grain handlers in Brazil's Mato Grosso and Goiás states specify laminated gusseted formats for containerized soybean export to Chinese crushers. Moisture vapor transmission below 5 g/m²/day prevents caking during tropical transit.
- Industrial:Chemical distributors specify metallized barrier layers for hygroscopic compounds where aluminum foil laminates face cost pressure. Nordic specialty chemical importers are specifying these for 12-month shelf stability requirements.
- Retail:European private labels demand embedded QR traceability and variable-data printing for supply chain transparency compliance with extended producer responsibility schemes in Germany, France, and Italy.
Revenue concentrates in Food Packaging; margin expansion is steepest in Retail.
Thickness:
Puncture resistance requirements and resin economics balance at discrete specification plateaus.
- 30 Micron:The cross-industry default achieves tensile strength of 30–50 N/mm² while minimizing unit material cost. Co-extrusion lamination enables sub-5 g/m²/day vapor transmission rates at this gauge, displacing thicker alternatives in industrial chemical applications.
- 20 Micron:Ultra-light gauges serve high-volume salt and sugar where product abrasiveness is low and freight cost minimization dominates. Southeast Asian processors specify these for intra-regional shipments with shorter dwell times.
- 40 Micron:Reinforced puncture resistance serves fertilizer blends with sharp crystalline fractions and agricultural seeds with irregular geometries. Brazilian cooperatives specify these for mechanized handling systems with higher drop frequencies.
- 50 Micron:Maximum durability tiers serve abrasive mineral concentrates and construction chemicals where bag integrity failure carries severe cleanup liability. Limited volume but insulated from polyethylene woven sack substitution pressure.
Unit economics favor 30 Micron; specification creep is pushing 40 Micron faster.
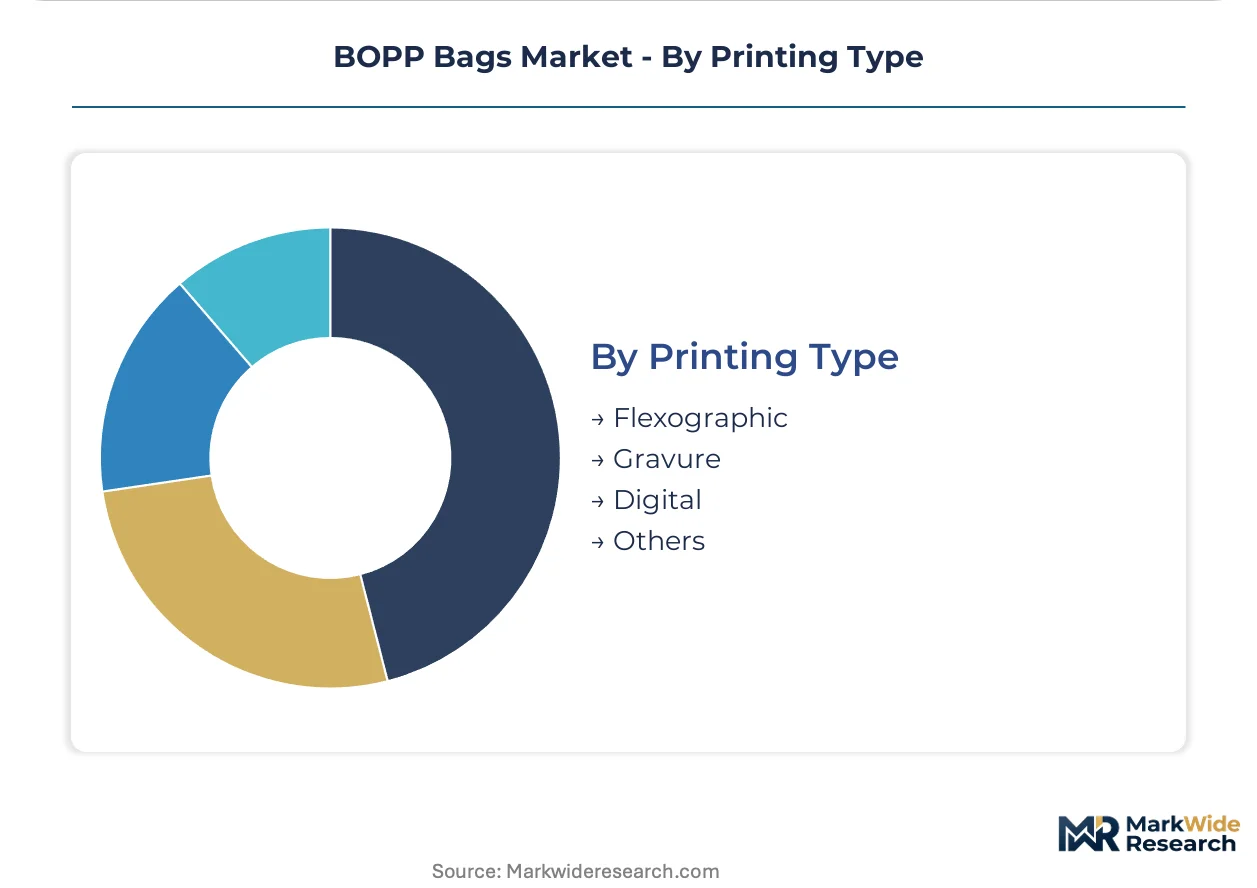
Printing Type:
Run length and design change frequency determine technology selection across converter bases.
- Flexographic:Central impression cylinder configurations dominate long-run agricultural and fertilizer applications where plate costs amortize across millions of impressions. Zhejiang and Guangdong extruders maintain captive flexo capacity for rice export contracts.
- Digital:Inkjet and toner systems enable batch-traceable QR codes and variable graphics for European retail private labels with regional customization requirements. Direct integration with form-fill-seal lines supports lot-specific traceability without plate changeover delays.
- Gravure:Engraved cylinder systems sustain premium cosmetic and food applications where tonal range and metallic effects justify high setup costs and extended lead times.
- Others:Screen and offset hybrid systems serve short-run specialty applications and prototype development for format validation prior to scale-up.
Flexographic handles current volume; digital is climbing the fastest on traceability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Propylene feedstock availability from Middle Eastern crackers anchors BOPP bag production economics, while agricultural export corridors in Brazil and Southeast Asia concentrate downstream demand for laminated woven formats.
United States
FDA food contact notifications govern woven PP eligibility for bulk grain exports to Asian markets. Berry Global Inc. leverages captive resin supply across North American agricultural channels. Gulf Coast petrochemical complexes near Houston supply homopolymer feedstock to extrusion plants serving containerized soybean shipments.
Germany
REACH Annex XVII restrictions on phthalate plasticizers force coating chemistry reformulations for industrial chemical packaging. Extended producer responsibility schemes in France and Italy create recycled content thresholds that German extruders preemptively integrate. The Ruhr industrial corridor hosts metallization capacity for high-barrier coffee and probiotic applications.
India
BIS certification mandates migration limits for food-contact polypropylene, compressing margins for non-accredited producers. Maharashtra's sugarcane belt and Andhra Pradesh rice processing cooperatives specify certified gusseted formats with embedded traceability. Gujarat's chemical belt consumes laminated variants for hygroscopic fertilizer compounds.
Brazil
Soybean and corn handlers in Mato Grosso and Goiás convert from bulk handling to pre-packed BOPP formats for Chinese crusher destinations. ANVISA compliance requirements parallel FDA standards for food-contact woven PP. The Paraná poultry feed corridor consolidates procurement through three-to-four accredited extruders per region.
Vietnam
Rice export volumes through Ho Chi Minh City container terminals favor gusseted formats for 20-foot load optimization. Zhejiang and Guangdong equipment suppliers dominate biaxial orientation line installations across Mekong Delta processing clusters. Co-extrusion lamination enables sub-5 g/m²/day vapor transmission rates for tropical transit conditions.
BOPP Bags Market Competitive Environment
Global majors compete with regional champions across resin-to-finished-bag integration depth. The vendor base organizes into three tiers: integrated resin producers with captive extrusion, specialized lamination houses serving moisture-sensitive chemicals, and commodity converters competing on BIS and REACH accreditation speed. Consolidation accelerates through form-fill-seal line integration and post-industrial scrap recycling partnerships.
Among North American integrated producers, Berry Global Inc. exemplifies backward control from petrochemical feedstock through finished agricultural packaging. United Bags Inc. and LC Packaging occupy distinct archetypes within specialty barrier and certified food-grade segments respectively. Hanoi Plastic Bag JSC represents Southeast Asian regional champions scaling metallized capacity for Nordic coffee roaster specifications.
| Leading Market Players |
|---|
| Berry Global Inc. |
| United Bags Inc. |
| Manyan Inc. |
| LC Packaging |
| Umasree Texplast |
| Cosmos Films Ltd. |
| Indra Industries Ltd. |
| Abdos Polymers Ltd. |
| Hanoi Plastic Bag JSC |
| Others |
Value Chain & Pricing Dynamics
Agricultural cooperatives in Maharashtra and Mato Grosso concentrate procurement power through direct mill-to-farm contracts, anchoring BOPP bag pricing in long-term offtake agreements rather than spot resin indices. This buyer consolidation compresses margin pools for non-accredited extruders while rewarding REACH and BIS-certified producers with pricing power tied to compliance speed.
Pricing Analysis
Service bundling separates premium-tier suppliers from commodity converters, with migration-tested substrates and embedded traceability coding commanding substantial premiums over unlaminated alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and after-sales technical support inclusion. Price differentiation hinges on BIS and REACH accreditation status alongside volume scale commitments. Cost compression in the economy tier intensifies as polyethylene woven sack substitution accelerates in Sub-Saharan African fertilizer markets.
Supply Chain Analysis
Propylene feedstock supply rests on naphtha-cracker output from Middle Eastern and North American petrochemical complexes, with homopolymer resin flowing to extrusion plants near Houston and Rotterdam. Biaxial orientation equipment concentrates in Zhejiang and Guangdong provinces, creating single-source vulnerability for Southeast Asian processors. Slitter-rewinder operator scarcity in established manufacturing regions constrains capacity expansion. Distribution runs through containerized export corridors serving Vietnamese rice terminals and Brazilian soybean crushers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slitter-rewinder operator scarcity constrains qualified extrusion capacity expansion, propping pricing for accredited producers across food export channels.
For Market Incumbents: Cement market position through captive metallization capacity for high-barrier coffee and probiotic applications, insulating margin pools from multilayer laminate converters. Accelerate post-industrial scrap integration partnerships to preempt EU extended producer responsibility recycled content thresholds. Backward integration into resin supply hedges propylene feedstock volatility exposure. For New Entrants and Emerging Players: Specialty chemical distributors in Nordic markets represent an underserved buyer archetype seeking aluminum oxide-coated formats for 12-month shelf stability. Digital print integration with form-fill-seal lines opens European retail private label traceability mandates as a penetrable entry vector. Lead with batch-traceable QR coding capabilities to differentiate from legacy flexo-dependent incumbents. For Investors and Strategic Acquirers: The window for entry favors mid-tier lamination houses with REACH-compliant coating chemistry and existing food-grade certification protocols. Long-term viability centers on suppliers positioned for EU packaging waste directive compliance through scrap integration infrastructure. Watch for BIS approval timeline compression in India as an inflection signal for accreditation-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive propylene feedstock from Gulf Coast crackers insulates margin volatility for North American agricultural channels. |
| Metallization Capacity Expansion | Aluminum oxide coating lines absorb moisture-sensitive applications from aluminum foil laminate converters in Nordic coffee markets. |
| Post-Industrial Scrap Integration | Recycled content thresholds in German and French extended producer responsibility schemes qualify suppliers for retail private label procurement. |
| Digital Print Line Integration | Variable-data QR coding enables batch traceability compliance for European retail chains without plate changeover delays. |
| BIS Certification Acceleration | Migration-tested substrates capture recurring orders from Maharashtra sugarcane cooperatives against 14-18 month approval timelines. |
Study Parameters
Trade databases, customs records, and SEC filings from packaging converters formed the secondary backbone, cross-referenced with primary interviews involving extrusion plant managers, agricultural cooperative procurement leads, chemical distributor technical directors, and retail private label category buyers. Bottom-up volume triangulation across product type, thickness tier, and end-use segmentation converged with top-down macroeconomic drivers. Primary fieldwork validated coating chemistry reformulation timelines and accreditation bottleneck severity.
Historical trendline analysis of rice export volumes, fertilizer shipment patterns, and containerized grain trade flows anchored the projection framework across the analysis window. Segmentation modeling incorporated product format, thickness specification, printing technology, and regional regulatory cluster dimensions. CAGRs derived from elasticity-adjusted demand curves for gusseted and zipper formats, with propylene feedstock cost pass-through assumptions and substitution elasticity parameters for polyethylene woven sack alternatives.
Revisions become necessary when EU REACH Annex XVII restrictions accelerate PFAS prohibition timelines or when Indian BIS certification cycles compress dramatically. Forecasts reflect assumptions regarding slitter-rewinder labor availability and extended producer responsibility implementation pacing. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Americas Plastic Bags and Sacks Market
Bags and Containers
Non-Laminated Heat-Sealed Bags Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Dome Shrink Basket Bags Market
Bags and Containers
Waterproof Bags Market
Bags and Containers
Conical Bags Packaging Market
Bags and Containers
Pre-Made Bags Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Tote and Ingredient Bags Packaging Market
Bags and Containers
Liner Bags Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Volatile Corrosion Inhibitor Bags Market
Bags and Containers
Bulk Bag Conditioners Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Ziplock Food Bags Market