
 Non-Plastic Punnets Market | 2026-2036
Non-Plastic Punnets Market Size, Share, and Industry Trends Forecast 2026-2036
Non-Plastic Punnets Market Analytics
ISO 18606 compostability certification is bifurcating the supplier landscape into qualified and non-qualified tiers. Smurfit Kappa Group Plc leverages its integrated pulp-to-package model across European fresh produce networks. Groupe Guillin SA anchors its position through deep specialization in thermoformed fiber formats for soft fruit. Faerch Plast A/S differentiates via controlled composting partnerships with Scandinavian retail consortia.
Non-plastic punnets are rigid or semi-rigid containers manufactured from cellulose-based fibers, bamboo pulp, or thin-gauge aluminum, engineered to ventilate moisture and withstand hydro-cooling in produce supply chains. Cardboard punnets dominate current volume due to existing corrugation infrastructure and printability for retail branding, while bamboo variants capture premium positioning in organic and zero-waste channels where fiber origin storytelling commands shelf price flexibility. The end-user split reveals retailers as the structural demand anchor, with farmers' markets and specialty stores representing faster-growth outlets where minimum-order constraints from large converters do not apply.
The EU Single-Use Plastics Directive and national implementations through France's AGEC law and Germany's Packaging Act shape material eligibility and extended producer responsibility obligations. EFSA food-contact approvals for novel bamboo and agricultural residue fibers determine which substrates gain commercial scale. Stakeholders must monitor composting infrastructure gaps between certification requirements and actual industrial composting availability.
Market Dynamics
EU Single-Use Plastics Directive enforcement is compressing material substitution timelines, forcing converters to secure EFSA food-contact approvals for novel fibers before existing thermoforming lines become stranded assets.
Growth Catalysts
- France AGEC Law:France's anti-waste circular economy law mandates plastic reduction targets for fresh produce packaging, creating immediate pull-through for molded fiber alternatives in supermarket berry categories.
- Organic Retail Expansion:Specialized organic chains in Germany and the Netherlands are specifying bamboo-origin punnets for premium price positioning and zero-waste store formats.
- Hydro-Cooling Compatibility:Advanced pulp formulations now withstand cold-chain moisture exposure, eliminating the performance gap that previously protected plastic incumbents in soft fruit logistics.
Market Restraints
- Pulp Input Volatility:Recycled corrugated fiber prices fluctuate with packaging demand cycles, compressing margin stability for converters without backward integration into pulp supply.
- Composting Infrastructure Gaps:Industrial composting facility availability lags behind ISO 18606 certification requirements in Eastern European markets, creating compliance-performance disconnects.
- Thin-Gauge Aluminum Substitution:Metal punnets retain shelf-life advantages for high-value berries, limiting fiber penetration in export-oriented supply chains where moisture control is critical.
Strategic Opportunities
- Poland and Czech Republic:Central European retail modernization is outpacing local converter capacity, creating entry windows for qualified suppliers with existing EFSA approvals.
- Agricultural Residue Fibers:Wheat straw and rice husk pulps are gaining regulatory traction as EFSA expands novel food-contact evaluations, promising cost structures below wood-based alternatives.
- Direct-to-Consumer Channels:Subscription produce boxes and farm delivery services are bypassing traditional retail procurement minimums, enabling smaller-batch fiber punnet adoption.
Industry Challenges
- Compostability Certification Timelines:ISO 18606 and EN 13432 testing protocols require 12-18 month validation cycles, delaying product launches against tightening regulatory deadlines.
- Thermoforming Line Retrofit Costs:Converting existing plastic-forming equipment for fiber slurry processing demands capital outlays that strain mid-tier packaging specialists.
- Moisture Barrier Formulation Expertise:Food-safe coatings that maintain compostability credentials require polymer chemistry capabilities scarce among traditional corrugated converters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Non-Plastic Punnets Market |
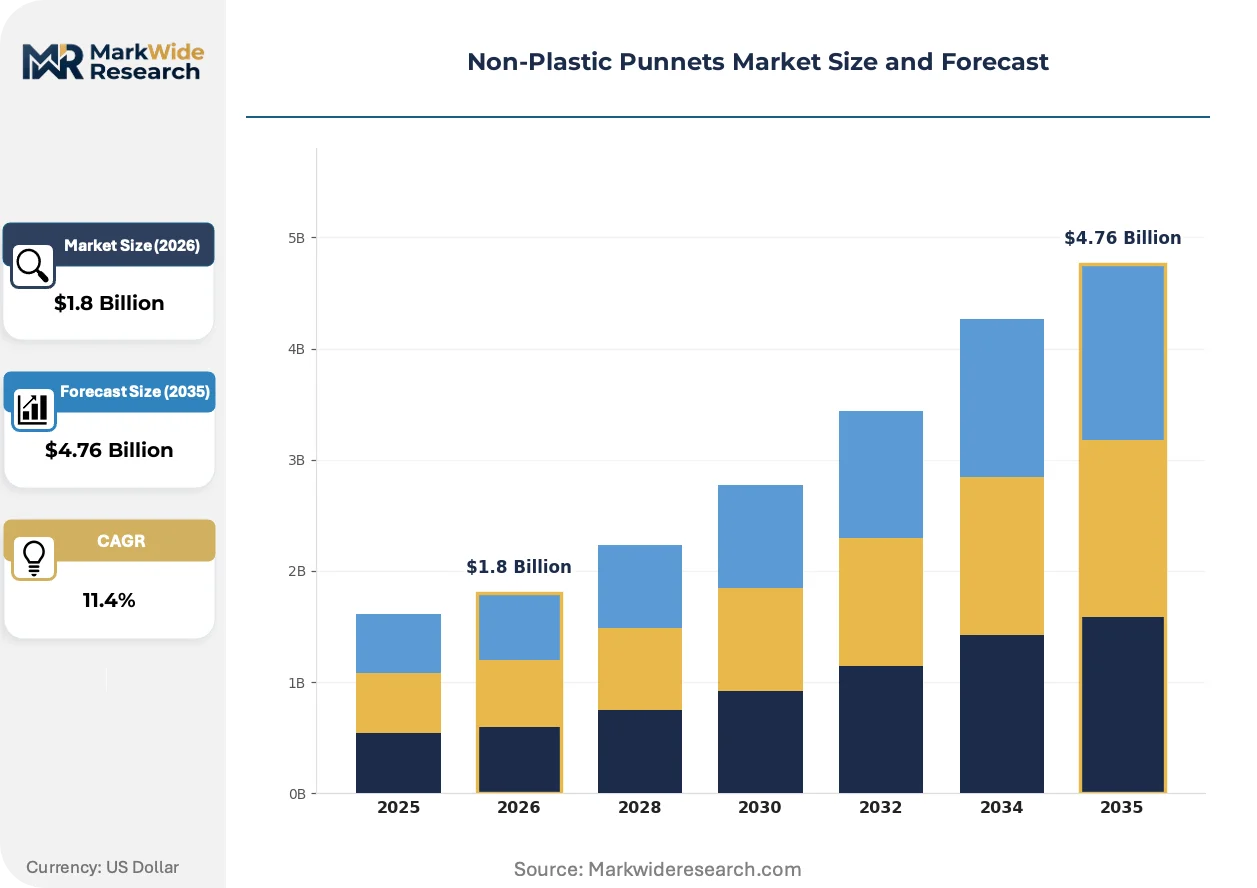
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Cardboard, Bamboo, Wood, Metal Product Type: Fruits, Vegetables, Bakery, Confectionery End User: Retailers, Farmers, Food Processors, Wholesalers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Farmers' Markets |
| Companies Covered | Smurfit Kappa Group Plc, Coveris Holdings SA, LC Packaging International BV, Groupe Guillin SA, LINPAC Packaging Limited, Faerch Plast A/S, Quinn Packaging Ltd, Royal Interpack Group, Van Der Windt Packaging Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Non-Plastic Punnets Market Evolving Landscape
Novel fiber sourcing and processing methods are collapsing the traditional trade-offs between compostability, moisture resistance, and unit economics that have structured this category for two decades.
Molded fiber thermoforming is fragmenting the incumbent technology hierarchy. Advanced pulp molding systems now achieve wall thickness precision comparable to plastic injection molding, enabling berry punnet geometries previously impossible in fiber. Scandinavian retail consortia are specifying these formats for private-label soft fruit lines. The technology is fragmenting converter specialization patterns, as corrugated giants and plastic specialists now compete directly in thermoformed fiber capacity.
Germany's Packaging Act amendment tightens extended producer responsibility thresholds for single-use food packaging, forcing retailers to document recycling pathway compliance. This legislative pressure accelerates fiber punnet qualification programs across German discounter supply chains. The regulation most directly impacts berry and cherry categories, where seasonal volume spikes concentrate procurement decision windows.
Retail buyer consolidation around sustainability scorecards is compressing supplier qualification cycles. Major European supermarket chains now mandate third-party compostability certification as a baseline bidding requirement, displacing self-declared environmental claims. This behavioral shift is most visible in Germany and France, where procurement teams have integrated lifecycle assessment data into annual vendor reviews.
Non-Plastic Punnets Market Segmentation
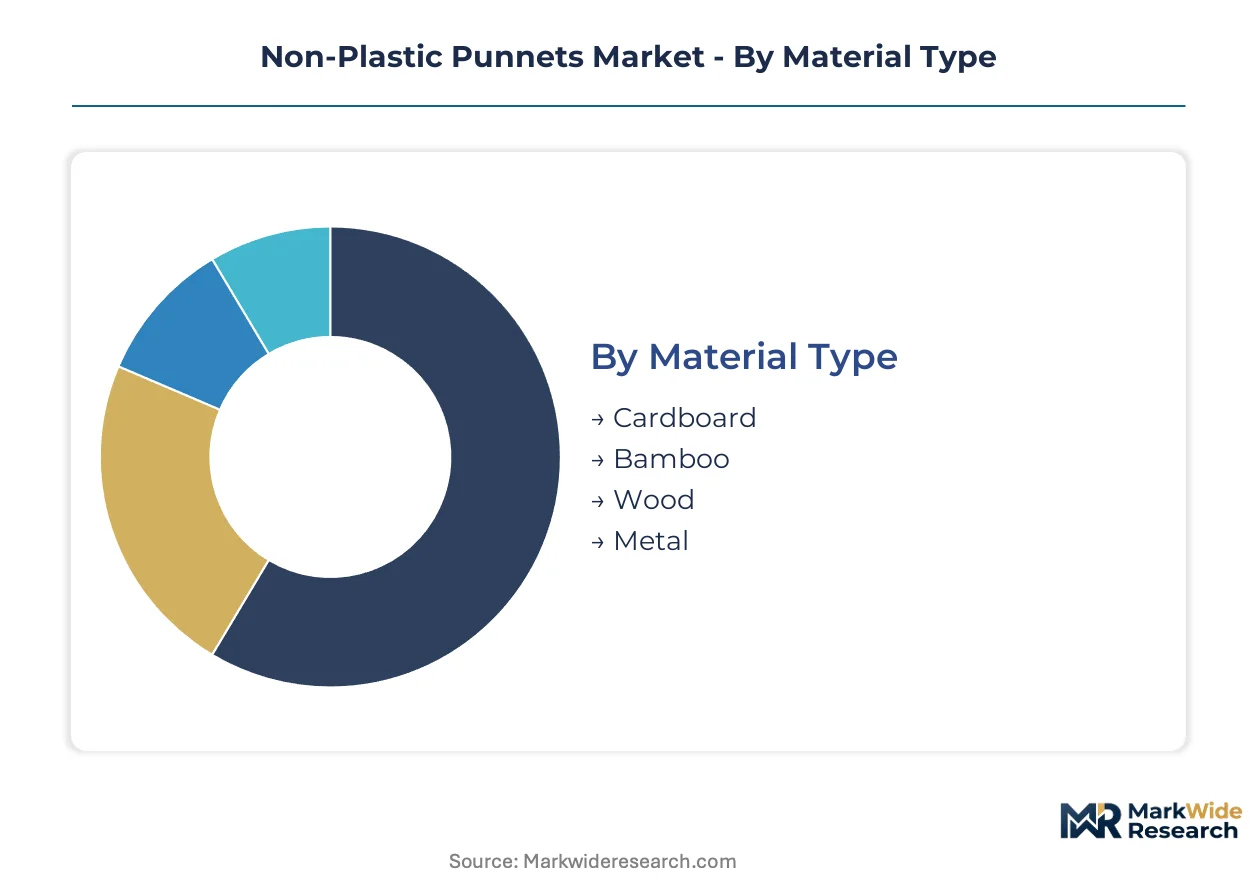
Material certification tiers and end-use performance requirements fragment procurement patterns across European fresh produce supply chains. Retail buyer consolidation around compostability scorecards forces converters to align product portfolios with specific regulatory thresholds rather than generic sustainability claims.
Material Type:
EFSA food-contact approvals and ISO 18606 certification status differentiate material eligibility for commercial scale deployment across EU member states.
- Cardboard:Recycled corrugated fiber formulations leverage existing pulping infrastructure and printability for retail branding. German discounter chains and French supermarket networks concentrate procurement volume here due to established supply security and cost predictability under extended producer responsibility frameworks.
- Bamboo:Rapid-renewable grass pulps command premium positioning in organic retail channels where fiber origin storytelling supports shelf price flexibility. Dutch and German zero-waste store formats specify bamboo-origin punnets for berry and soft fruit categories, though EFSA novel food-contact evaluations remain incomplete for some substrate variants.
- Wood:Virgin and recycled wood fiber blends serve intermediate price positioning between cardboard economy tiers and bamboo premiums.
- Metal:Thin-gauge aluminum retains moisture barrier superiority for export-oriented berry supply chains where cold-chain integrity overrides compostability mandates.
Cardboard handles the majority of throughput; bamboo is the fastest mover on share.
Product Type:
Hydro-cooling compatibility requirements and shelf-life sensitivity determine which material substrates gain adoption in specific fresh produce categories.
- Fruits:Berry punnets dominate molded fiber innovation as Scandinavian retail consortia specify thermoformed geometries for private-label soft fruit lines. Advanced pulp formulations now withstand cold-chain moisture exposure, eliminating the performance gap that previously protected plastic incumbents in strawberry and raspberry logistics.
- Vegetables:Cherry tomato and asparagus punnets follow berry adoption curves with 12-18 month lag as converters validate moisture barrier coatings for higher-respiration produce.
- Bakery:Lower moisture exposure permits broader material experimentation, though food-contact grease resistance requirements limit substrate options.
- Confectionery:Premium positioning and lower volume throughput attract bamboo and agricultural residue fiber trials.
Fruits absorb the greatest converter capacity investment; vegetables are climbing the fastest as moisture barrier formulations mature.
End User:
Procurement scale and sustainability mandate stringency separate demand tiers across the value chain.
- Retailers:German and French supermarket chains anchor structural demand through annual vendor reviews integrating lifecycle assessment data and third-party compostability certification as baseline bidding requirements. Seasonal volume spikes in berry and cherry categories concentrate decision windows.
- Farmers:Direct-to-consumer subscription services and farm delivery platforms bypass traditional retail minimum-order constraints, enabling smaller-batch fiber punnet adoption with faster qualification cycles.
- Food Processors:Intermediate handling requirements and private-label contract specifications drive material standardization toward cardboard and certified fiber blends.
- Wholesalers:Price-sensitive bulk procurement lags retail sustainability mandates, preserving plastic alternatives in export and discount channels.
Retailers command the dominant procurement volume; farmers are expanding most quickly as direct channels fragment traditional supply relationships.
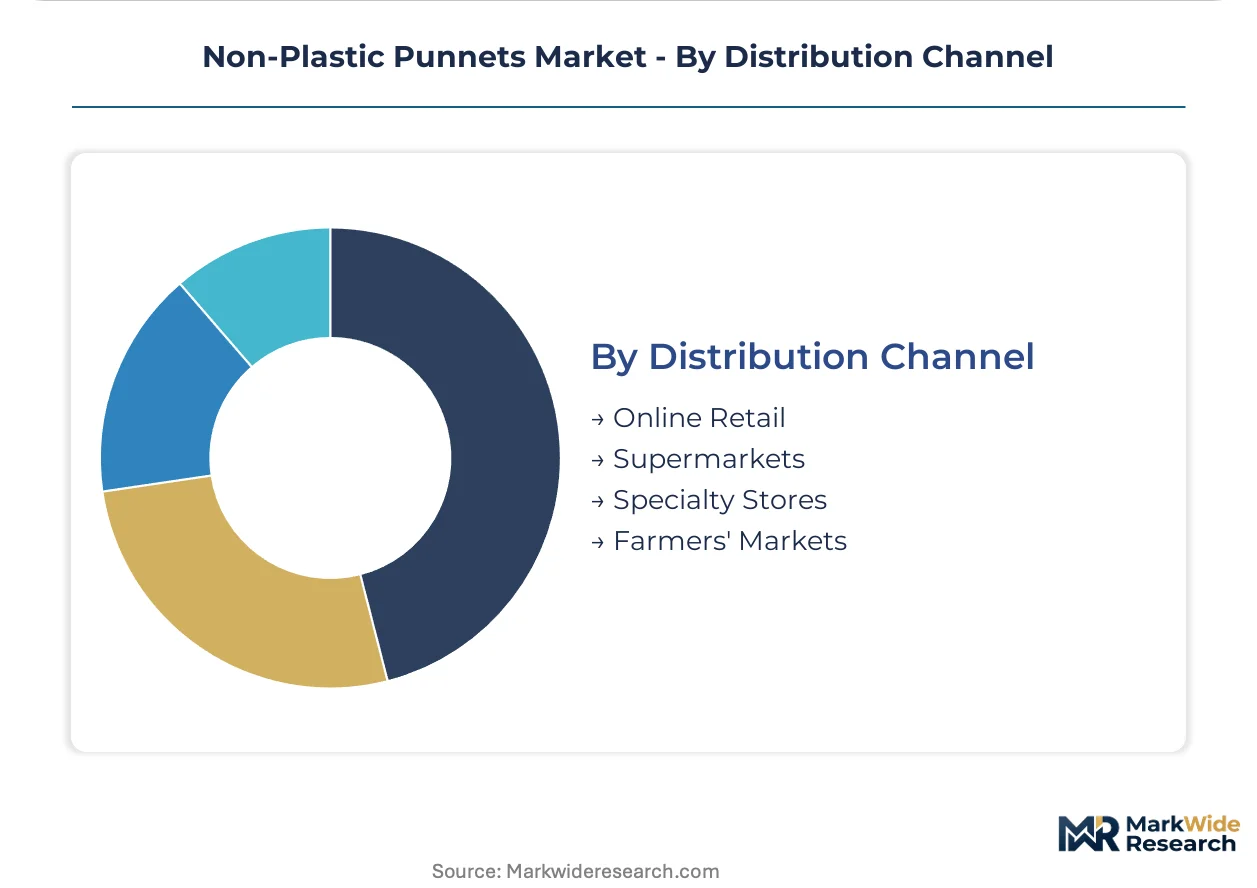
Distribution Channel:
Channel-specific logistics infrastructure and customer touchpoint characteristics shape material specification patterns.
- Supermarkets:AGEC law compliance in France and Packaging Act obligations in Germany force documentation of recycling pathway compliance for single-use food packaging. Major chains specify molded fiber punnets for berry categories as seasonal procurement concentrates.
- Specialty Stores:Organic and zero-waste formats in the Netherlands and Germany specify bamboo-origin punnets for premium price positioning and brand differentiation.
- Online Retail:Subscription produce boxes require damage-resistant fiber formulations for last-mile handling without retail display aesthetics.
- Farmers' Markets:Minimum-order constraints from large converters do not apply, enabling rapid experimentation with novel agricultural residue fibers.
Supermarkets process the highest absolute volume; specialty stores are gaining share fastest as sustainability positioning hardens into competitive differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German discounter chains and French supermarket networks anchor procurement volume for non-plastic punnets, while specialty retailers in the Netherlands and organic channels across Scandinavia drive premium-tier demand for bamboo and agricultural residue alternatives.
Germany
Discounter chains and organic retailers jointly drive volume for cardboard and bamboo alternatives, with seasonal berry procurement concentrating decision windows each spring. The Packaging Act amendment tightens extended producer responsibility thresholds for single-use food packaging. Bavaria-based converters are scaling thermoformed fiber capacity to meet retailer qualification programs.
France
Supermarket chains specify molded fiber punnets for berry categories as AGEC law compliance mandates plastic reduction targets for fresh produce packaging. The anti-waste circular economy law creates immediate pull-through for molded fiber alternatives. Île-de-France retail headquarters coordinate nationwide vendor reviews integrating lifecycle assessment data into procurement scorecards.
Netherlands
Zero-waste store formats and specialized organic chains specify bamboo-origin punnets for premium price positioning in soft fruit categories. National compostability mandates align with EU Single-Use Plastics Directive implementation timelines. Randstad logistics clusters enable rapid distribution of fiber punnets to Belgian and German retail networks.
Poland
Central European retail modernization is outpacing local converter capacity, creating entry windows for qualified suppliers with existing EFSA approvals. EU funding for circular economy infrastructure supports composting facility development in Warsaw and Kraków metropolitan areas. Silesian industrial zones attract foreign packaging specialists seeking proximity to German supply chains.
Sweden
Scandinavian retail consortia specify advanced pulp molding systems for private-label soft fruit lines, driving thermoformed fiber innovation. Controlled composting partnerships with municipal waste operators validate closed-loop packaging models. Stockholm-based sustainability procurement teams influence Nordic-wide supplier qualification standards.
Non-Plastic Punnets Market Competitive Landscape
Player mix skews toward integrated pulp-to-package conglomerates and specialized fiber thermoforming specialists, with mid-tier corrugated converters attempting line retrofits to capture regulatory-driven substitution demand. Two strategic archetypes dominate: backward-integrated giants controlling pulp supply security, and technology-focused specialists mastering moisture barrier formulations. Competitive moves concentrate on EFSA approval racing and compostability certification stacking ahead of tightening EU deadlines.
Within the integrated conglomerate tier, Smurfit Kappa Group Plc exemplifies scale-driven positioning through captive pulp supply chains spanning European fresh produce networks. Groupe Guillin SA and Faerch Plast A/S occupy specialist positions, with the former representing deep specialization in thermoformed fiber formats and the latter anchoring controlled composting partnership models with retail consortia.
| Leading Market Players |
|---|
| Smurfit Kappa Group Plc |
| Coveris Holdings SA |
| LC Packaging International BV |
| Groupe Guillin SA |
| LINPAC Packaging Limited |
| Faerch Plast A/S |
| Quinn Packaging Ltd |
| Royal Interpack Group |
| Van Der Windt Packaging Ltd |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements between German discounter chains and molded fiber converters lock in pulp supply access while anchoring price visibility across seasonal berry procurement cycles. These contracts insulate qualified suppliers from recycled corrugated fiber spot volatility while forcing non-integrated competitors into margin compression.
Pricing Analysis
Cost-plus contracts with OCC indexation dominate procurement between major retailers and backward-integrated converters. Pricing stratifies across ISO 18606-certified premium tiers, EFSA-pending standard tiers, and uncertified economy alternatives. Cost compression in the economy tier is intensifying because pulp input volatility compresses margins for converters without captive supply. German discounter chains exhibit highest price sensitivity, while Dutch zero-waste specialty stores accept premium positioning for bamboo-origin certification.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp corridors and container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for bamboo pulp imports. Supply concentrates in Germany, France, and Poland, with Bavaria-based thermoforming capacity expanding fastest. Raw material dependencies center on recycled corrugated fiber, virgin wood pulp, and rapid-renewable bamboo grass. Single-source vulnerability around EFSA-approved coating chemistries creates supply chain risk. Distribution runs through retailer-controlled consolidation centers serving seasonal berry procurement windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Single-Use Plastics Directive enforcement window compresses substitution timelines, creating a high-growth disruption as thermoformed fiber technology eliminates the moisture-barrier performance gap that protected plastic incumbents for two decades.
For Market Incumbents: Consolidate thermoforming capacity in Poland and the Czech Republic to capture Central European retail modernization outpacing local converter supply. Secure backward integration into agricultural residue pulp supply before EFSA approvals for wheat straw and rice husk variants commercialize, displacing wood-based cost structures.
For New Entrants and Emerging Players: Direct-to-consumer subscription produce boxes represent a service-layer gap where large converter minimum-order constraints exclude incumbent participation. Target farmers' market channels and farm delivery platforms with smaller-batch bamboo and agricultural residue fiber formats, leveraging faster qualification cycles outside retail procurement scorecards.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier corrugated converters with thermoforming line retrofit capabilities and pending ISO 18606 certification. The 5-10 year viability window favors suppliers with EFSA food-contact approval moats and controlled composting partnerships with municipal waste operators. Watch for composting infrastructure buildout in Eastern European markets as the inflection signal for geographic expansion timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive fiber sourcing insulates margin stability from OCC price volatility cycles. |
| ISO 18606 Certification Acceleration | Third-party compostability validation becomes baseline bidding requirement for German and French retail procurement. |
| Controlled Composting Partnerships | Municipal waste operator alliances close the loop between certification requirements and actual industrial composting availability. |
| Agricultural Residue Fiber Scale-Up | Wheat straw and rice husk pulps promise cost structures below wood-based alternatives pending EFSA novel food-contact evaluations. |
| Thermoforming Line Retrofit Investment | Advanced pulp molding systems achieve wall thickness precision comparable to plastic injection molding for berry geometries. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with packaging procurement managers at German and French supermarket chains, thermoforming operations directors at molded fiber converters, and sustainability compliance officers at retail headquarters; and secondary validation against EU Single-Use Plastics Directive implementation timelines, EFSA novel food-contact approval databases, and ISO 18606 certification registries. Bottom-up volume modeling across material type, product category, and end-user segments triangulated against top-down market sizing from pulp consumption and retail packaging procurement disclosures.
Across the analysis window, forecasts deployed a segmented growth framework modeling cardboard, bamboo, wood, and metal material tiers against fruit, vegetable, bakery, and confectionery end-use applications. CAGRs derived from regression analysis of historical substitution rates, regulatory deadline compression effects, and composting infrastructure deployment curves. Industry-specific inputs included seasonal berry procurement volume spikes, AGEC law compliance timelines, and thermoforming capacity expansion announcements.
Forecasts assume regulatory continuity in EU member state implementations of the Single-Use Plastics Directive, France's AGEC law, and Germany's Packaging Act amendments; material policy shifts accelerating or delaying extended producer responsibility thresholds would require re-modeling. Composting infrastructure gaps between certification requirements and actual industrial availability, EFSA approval timeline delays for novel fibers, and pulp input price volatility represent specific risk factors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
New Packages and Materials for Power Devices Market
Packaging Materials
Spices, Dry Mixes and Extracts Packaging Market
Packaging Materials
Vacuum Thermoformed Packaging Market
Packaging Materials
Collapsible Tube Packaging Market
Packaging Materials
Release Film for OCA Market
Packaging Materials
Anti-Scratch Film Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Window Packaging Market
Packaging Materials
Cupcake Wrappers Market
Packaging Materials
Europe Airless Packaging Market
Packaging Materials
Box and Carton Overwrap Films Market
Packaging Materials
Tube Packaging Market
Packaging Materials
Lubricant Packaging Market
Packaging Materials
Sterilization Roll Market
Packaging Materials
US Packaging Market
Packaging Materials
Single Dose Detergent Packaging Market