
 Volatile Corrosion Inhibitor Bags Market | 2026-2036
Volatile Corrosion Inhibitor Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Volatile Corrosion Inhibitor Bags Market Analytics
Aftermarket service revenue from corrosion audit and VCI program management is reshaping how suppliers capture lifetime value from industrial accounts. Cortec Corporation leverages its integrated VCI chemistry and film manufacturing to control specification-setting with major automotive exporters. Daubert Cromwell anchors North American distribution through captive technical service teams that specify bag formats at the plant level. Northern Technologies International Corporation specializes in recyclable and bio-based VCI substrates, differentiating its offering against conventional polyethylene formulations.
Volatile corrosion inhibitor bags are multilayer packaging structures impregnated with vapor-phase corrosion inhibitors that sublime to form a molecular protective film on ferrous and non-ferrous metal surfaces, typically operating at vapor pressures between 10^-4 and 10^-6 mmHg at ambient temperatures. Composite bags combining polyethylene barriers with kraft paper layers dominate high-value electronics and machinery exports where moisture vapor transmission rates below 0.5 g/m²/day are specified. Application demand in automotive components leads volume given just-in-time shipping protocols that extend in-transit storage intervals, while metal parts applications for aerospace fasteners and tooling represent the fastest-growing margin pool due to certification requirements and lot-traceability standards.
EPA registration under FIFRA governs VCI active ingredient claims in the United States, while REACH restricts certain nitrite-based chemistries across European supply chains; both frameworks push formulators toward amine-carboxylate and plant-derived inhibitor systems. China's GB standards for packaging materials and Japan's JIS Z 1535 anti-corrosion packaging specifications create additional compliance layers for exporters serving East Asian manufacturing clusters. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that fragment product lines and erode scale economics.
Market Dynamics
REACH compliance in the European Union and EPA registration requirements under FIFRA are compressing the acceptable chemistry portfolio for volatile corrosion inhibitors, forcing formulators toward amine-carboxylate and plant-derived systems while fragmenting product lines across jurisdictions.
Growth Catalysts
- Automotive just-in-time shipping protocols:Extended in-transit storage intervals for precision metal components are expanding specification requirements for moisture vapor transmission rates below 0.5 g/m²/day.
- REACH nitrite restrictions:The European Union's ban on certain nitrite-based chemistries is accelerating adoption of alternative inhibitor systems across European supply chains.
- Aerospace certification requirements:Lot-traceability standards for fasteners and tooling are creating premium demand for multilayer composite bags with documented vapor pressure specifications.
Market Restraints
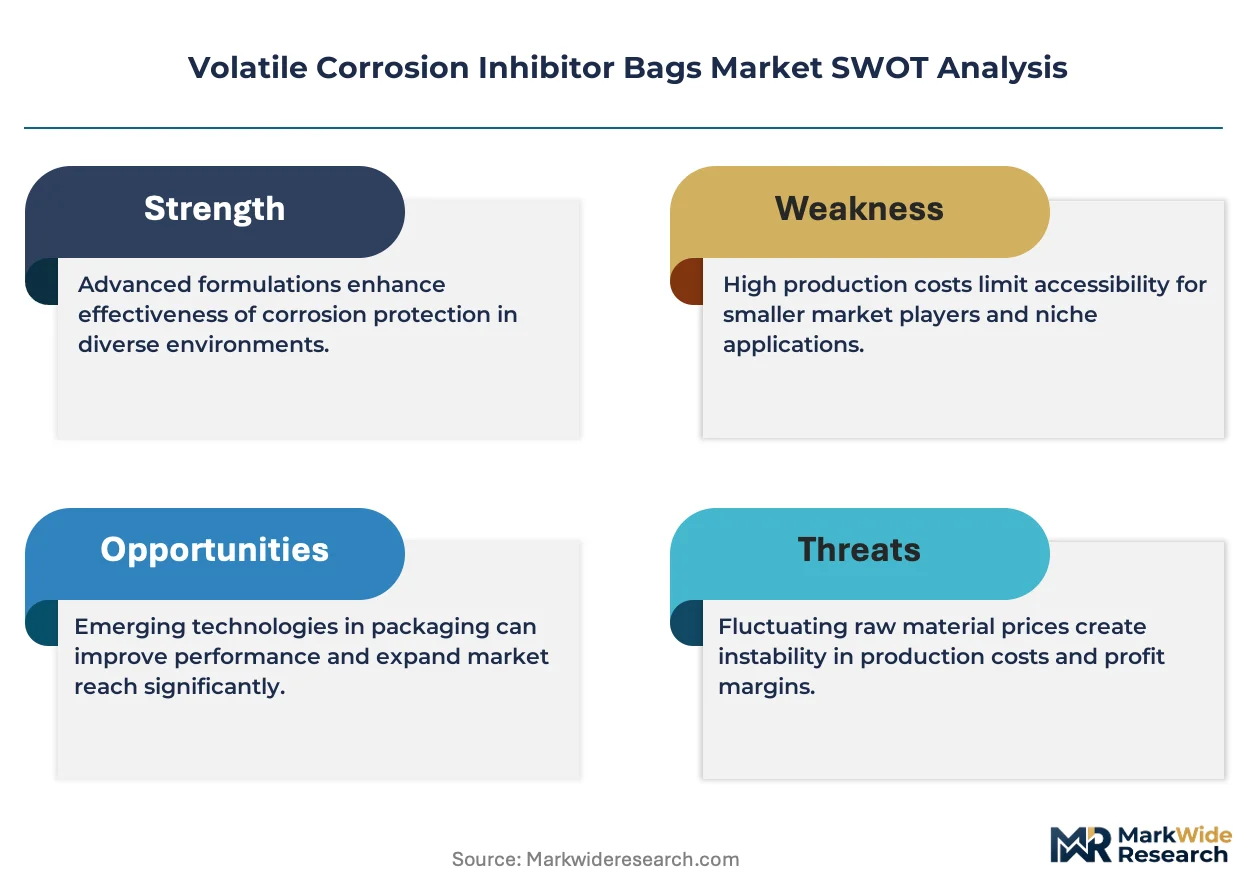
- Petroleum-derived polyethylene feedstock volatility:Crude oil price swings directly compress margin structures for conventional VCI bag manufacturers.
- Supply concentration in Germany and China:Dense clustering of precision metalworking capacity creates geographic dependency risk for logistics networks.
- Technical limitation in high-temperature applications:Vapor pressure degradation above 60°C restricts deployment in certain heat-treatment and foundry environments.
Strategic Opportunities
- Recyclable and bio-based substrate development:Plant-derived inhibitor systems paired with compostable films open circular-economy procurement channels.
- Aftermarket corrosion audit services:Industrial accounts are unbundling VCI program management from product supply, creating recurring revenue streams.
- China's GB standards compliance services:Exporters serving East Asian manufacturing clusters require technical support for packaging material certifications.
Industry Challenges
- Reformulation cost fragmentation:Divergent regulatory requirements between EPA FIFRA, REACH, and Japan's JIS Z 1535 force parallel product line maintenance.
- Certification timeline compression:Aerospace lot-traceability standards demand extended documentation cycles that strain working capital.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Volatile Corrosion Inhibitor Bags Market |
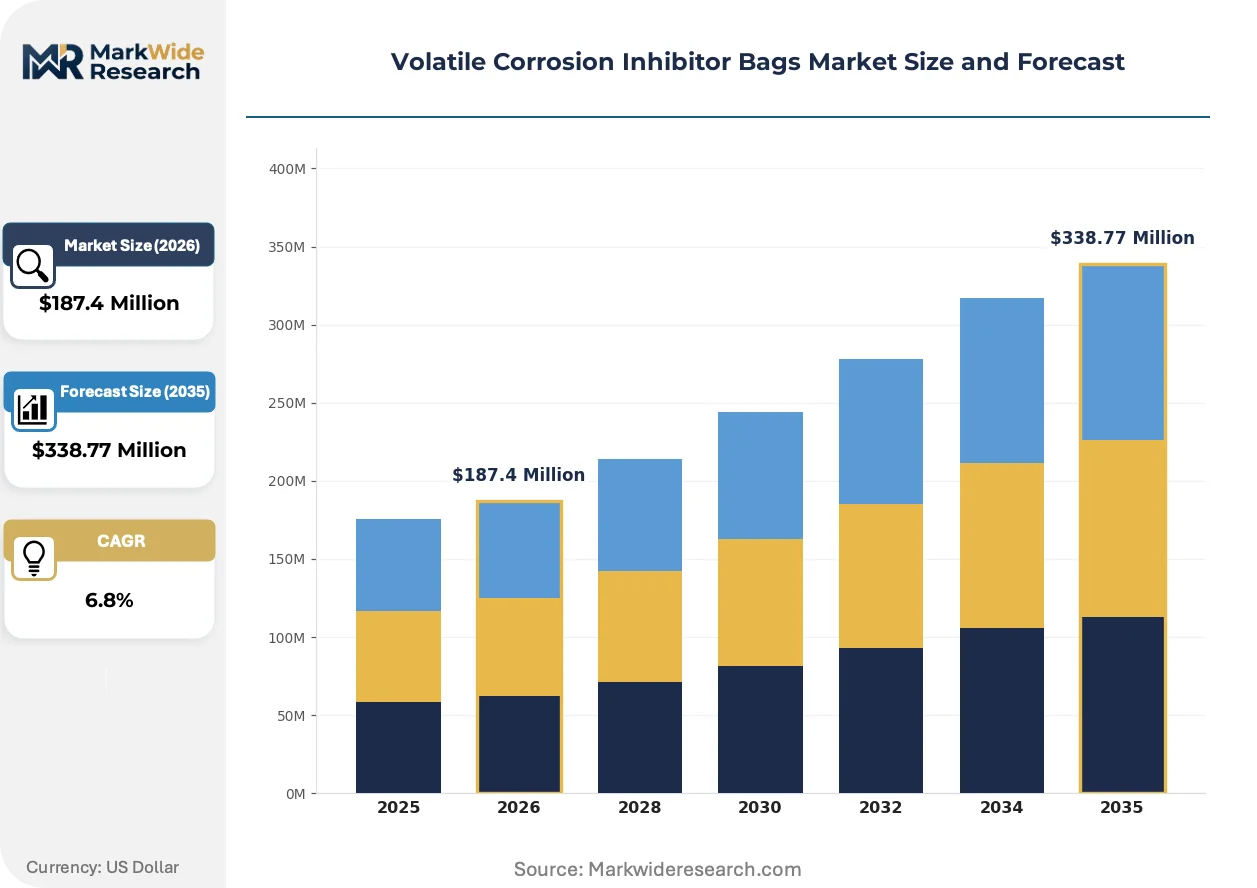
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Bags, Composite Bags, Kraft Paper Bags, Film Bags Application: Automotive Components, Electronics, Machinery, Metal Parts End User: Manufacturers, Distributors, Retailers, Exporters Size: Small, Medium, Large, Extra Large |
| Companies Covered | Cortec Corporation, Daubert Cromwell, Northern Technologies International Corporation, Armor Protective Packaging, Transcendia, Smurfit Kappa Group, Zerust, Aicello Corporation, Branopac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Volatile Corrosion Inhibitor Bags Market Evolving Landscape
Active chemistry substitution and digital integration of quality assurance systems are restructuring how VCI bag specifications are set, verified, and enforced across export-heavy manufacturing clusters.
Smart packaging with embedded humidity and vapor-pressure sensors is digitizing real-time corrosion risk monitoring for high-value electronics and machinery shipments. Automotive exporters in Germany and the United States are piloting these systems for transoceanic container tracking. The technology is digitizing specification-setting authority away from procurement departments toward integrated logistics platforms.
REACH authorization procedures for nitrite-based corrosion inhibitors are forcing accelerated R&D timelines for amine-carboxylate alternatives. Formulators face dual-registration burdens in the European Union and United States while maintaining legacy product lines. Specialty chemical divisions serving aerospace fasteners are absorbing the steepest compliance costs.
Buyers are consolidating vendor relationships around suppliers offering integrated chemistry and film manufacturing capabilities. Tier-1 automotive exporters in Germany now specify bag formats at the plant level through captive technical service teams rather than distributor networks. This concentration is most visible in precision metalworking corridors around Stuttgart and Shanghai.
Volatile Corrosion Inhibitor Bags Market Segmentation
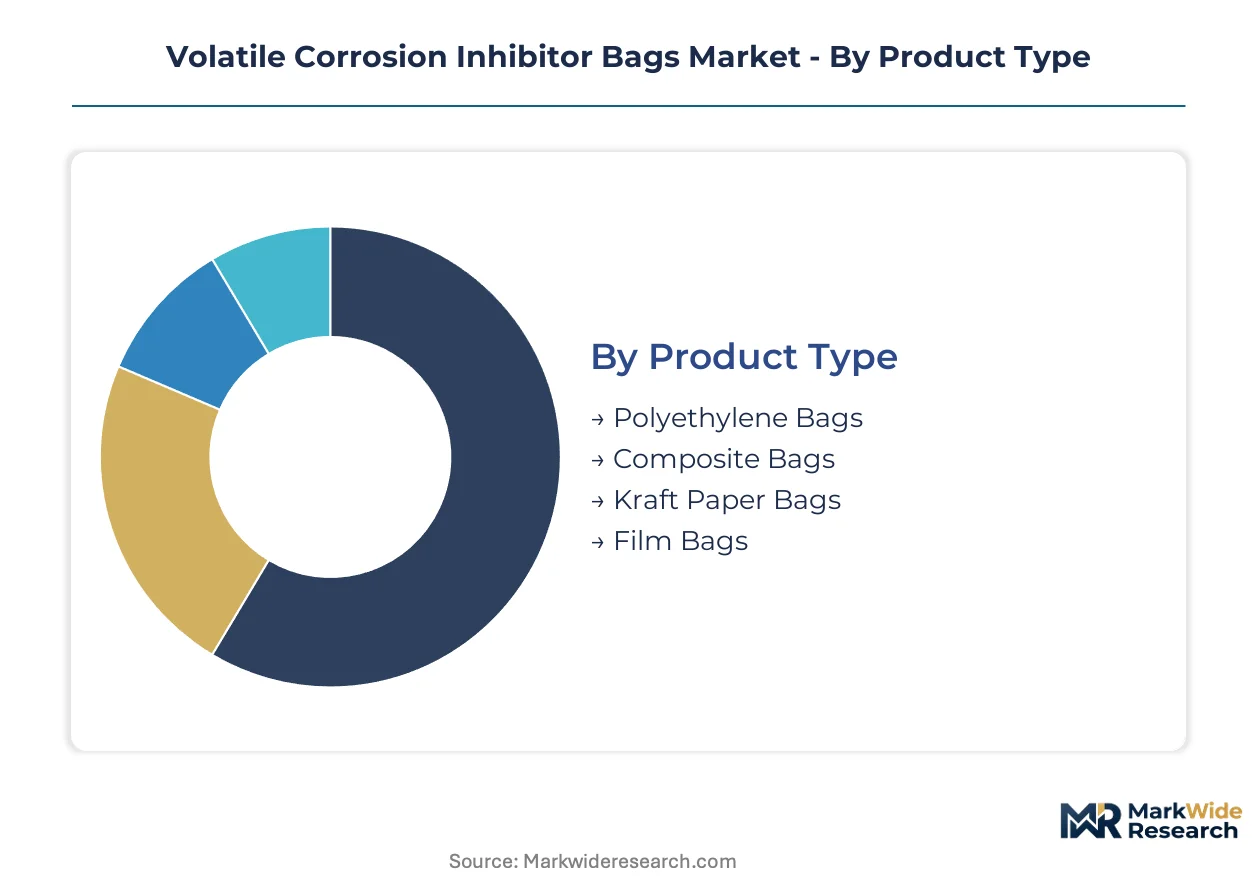
Volatile corrosion inhibitor bags serve heterogeneous protection requirements across precision metalworking clusters, electronics manufacturing corridors, and export logistics networks. Segmentation reveals how material specifications, application criticality, and procurement scale drive divergent margin structures and supplier capability requirements.
Product Type:
Material composition determines barrier performance, vapor pressure stability, and regulatory compliance pathways across export-heavy supply chains.
- Polyethylene Bags:Monolayer or coextruded polyethylene films impregnated with VCI active chemistry dominate high-volume automotive component shipments. German automotive exporters specify these formats for just-in-time delivery protocols where moisture vapor transmission rates below 0.5 g/m²/day are mandatory.
- Composite Bags:Multilayer structures combining polyethylene barriers with kraft paper or aluminum foil layers command premium positioning in aerospace fasteners and precision electronics. Lot-traceability requirements for US Department of Defense contractors concentrate demand around documented vapor pressure specifications between 10^-4 and 10^-6 mmHg.
- Kraft Paper Bags:VCI-impregnated paper substrates serve machinery and tooling applications where puncture resistance and recyclability outweigh moisture barrier demands.
- Film Bags:Thin-gauge polymeric films with surface-applied corrosion inhibitors target cost-sensitive consumer metal goods and short-cycle distribution.
Composite bags command the established base. The steepest expansion runs through polyethylene formats as automotive export volumes from Germany and China accelerate.
Application:
End-use criticality shapes specification stringency, certification burden, and supplier qualification timelines across manufacturing verticals.
- Automotive Components:Precision-machined powertrain parts, brake systems, and fuel injection components require extended in-transit protection through transoceanic container shipping. Stuttgart-based OEMs now specify bag formats at the plant level through captive technical service teams rather than distributor procurement channels.
- Metal Parts:Aerospace fasteners, tooling, and heat-treated alloys represent the most demanding certification environment. Japan's JIS Z 1535 anti-corrosion packaging specifications and US aerospace lot-traceability standards create dual-compliance burdens that filter supplier participation.
- Electronics:Printed circuit boards, connectors, and semiconductor packaging demand ultra-low outgassing formulations compatible with cleanroom assembly environments.
- Machinery:Industrial equipment and capital goods shipments prioritize puncture resistance and handling durability over vapor pressure precision.
Automotive components anchor volume concentration. Metal parts for aerospace applications are climbing the fastest as certification requirements deepen supplier moats.
End User:
Procurement scale and technical capability determine whether VCI program management stays in-house or migrates to integrated supplier relationships.
- Manufacturers:Tier-1 automotive and aerospace producers with captive metallurgy laboratories specify active chemistry formulations directly. These accounts unbundle corrosion audit services from product supply, creating recurring revenue streams for technical service teams.
- Exporters:Mid-cap precision metalworking firms serving German, Chinese, and US manufacturing clusters require compliance support for divergent regulatory frameworks including EPA FIFRA registration and REACH authorization.
- Distributors:Industrial packaging resellers aggregate fragmented demand from job shops and maintenance operations, favoring standardized polyethylene formats with minimal technical qualification.
- Retailers:Hardware and consumer goods channels represent price-sensitive, low-specification demand for basic corrosion protection of finished metal products.
Manufacturers control the premium tier through direct specification authority. Exporters are gaining share fastest as cross-border regulatory complexity deepens demand for technical support services.
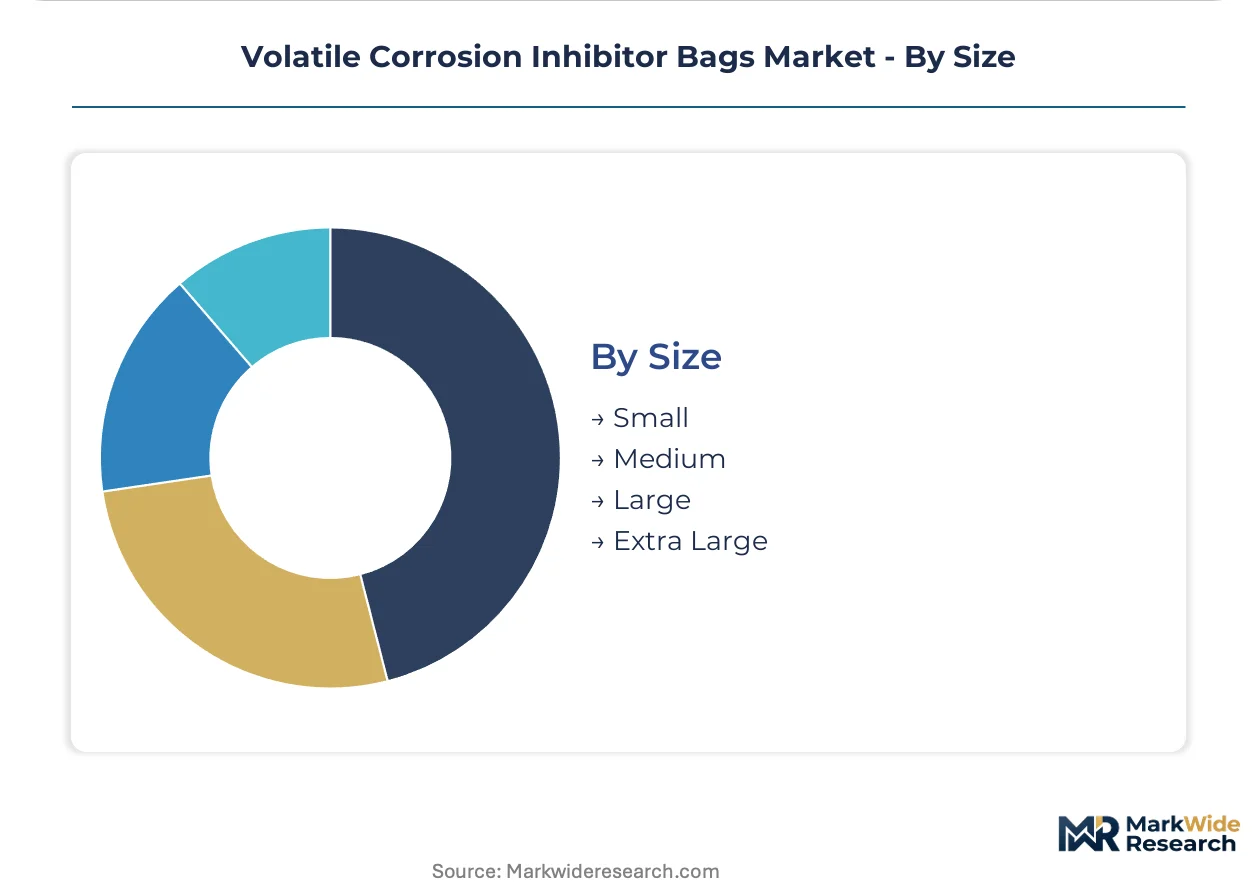
Size:
Dimensional segmentation correlates with part geometry, shipment consolidation patterns, and automated packaging line compatibility.
- Medium:Standard formats for individual automotive components and medium machinery parts balance material efficiency with handling convenience.
- Large:Bulk formats for palletized shipments and consolidated machinery exports dominate ocean freight container utilization optimization.
- Small:Compact dimensions target precision fasteners, electronic connectors, and aerospace hardware where individual part protection precedes kit assembly.
- Extra Large:Custom formats for oversized industrial equipment and specialty machinery require reinforced seams and lifting features.
Medium and large formats command the volume base. Small formats for precision electronics and aerospace hardware are expanding most quickly as miniaturization trends concentrate value in compact components.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
VCI bag supply chains concentrate where precision metalworking and automotive export infrastructure overlap most densely. Germany, China, and the United States host the dominant manufacturing clusters, with regulatory divergence forcing parallel compliance investments across jurisdictions.
United States
Aerospace logistics teams at Boeing and Lockheed Martin are expanding long-cycle parts storage procurement. EPA registration under FIFRA governs active ingredient claims, pushing formulators toward amine-carboxylate systems. The Detroit-Windsor automotive corridor specifies moisture vapor transmission rates below 0.5 g/m²/day for just-in-time powertrain shipments.
Germany
Stuttgart-based OEMs now set bag specifications at the plant level through captive technical service teams. REACH authorization procedures restrict nitrite-based chemistries, accelerating R&D timelines for plant-derived alternatives. The precision metalworking belt around Stuttgart and Munich drives premium demand for multilayer composite formats.
China
Automotive export volumes from Shanghai and Yangtze River Delta manufacturing clusters are accelerating polyethylene format adoption. GB standards for packaging materials create additional compliance layers for inbound suppliers. Shenzhen electronics manufacturers specify ultra-low outgassing formulations for semiconductor packaging applications.
Japan
Aerospace fastener producers in Nagoya and Tokyo face dual-compliance burdens from JIS Z 1535 anti-corrosion specifications and customer lot-traceability requirements. METI industrial standards guide packaging material selection for precision machinery exports. The Chubu region's tooling sector generates premium demand for documented vapor pressure specifications.
India
Automotive component suppliers in Pune and Chennai are adopting VCI protocols for transoceanic container shipments to European and North American OEMs. BIS packaging standards create domestic certification requirements alongside customer-mandated international specifications. The Tamil Nadu precision engineering corridor is emerging as a technical service deployment target for regional distributors.
Volatile Corrosion Inhibitor Bags Market Competitive Landscape
Integrated chemistry-film manufacturers and technical service specialists split the market into distinct capability tiers. Consolidation pressure favors suppliers with captive formulation expertise and plant-level specification authority. Three archetypes dominate: backward-integrated chemical formulators, regional technical service providers, and substrate-focused material innovators. Competitive moves center on unbundling corrosion audit services from product supply and consolidating distributor relationships around integrated platforms.
Among North American integrated manufacturers, Cortec Corporation and Daubert Cromwell exemplify the chemistry-film control archetype. Northern Technologies International Corporation occupies a position within the sustainable substrate tier. Japanese specialists including Aicello Corporation and European players such as Branopac sit within the precision-format segment. Zerust and Armor Protective Packaging represent the technical service-heavy distribution model. These groupings illustrate how specification-setting authority flows toward suppliers with captive metallurgy laboratories and direct automotive OEM relationships.
| Leading Market Players |
|---|
| Cortec Corporation |
| Daubert Cromwell |
| Northern Technologies International Corporation |
| Armor Protective Packaging |
| Transcendia |
| Smurfit Kappa Group |
| Zerust |
| Aicello Corporation |
| Branopac |
| Others |
Value Network & Pricing Analysis
Petroleum-derived polyethylene feedstock volatility compresses margin structures for conventional VCI bag manufacturers while simultaneously widening pricing spreads between commodity-grade polyethylene formats and multilayer composite alternatives. This input-cost instability forces buyers toward long-term contract structures that lock in volume commitments against spot-market exposure, reshaping procurement relationships across automotive and aerospace supply chains.
Pricing Analysis
EPA registration under FIFRA dictates the pricing tier structure across the United States market, segmenting offerings into premium amine-carboxylate formulations, standard nitrite-legacy products facing phase-out pressure, and economy-grade film bags with surface-applied chemistry. Certification grade and volume scale drive price differentiation, with aerospace lot-traceability documentation commanding substantial premiums over automotive just-in-time specifications. Cost compression in the economy tier is intensifying because Chinese export manufacturers are absorbing margin erosion to maintain market access. Distributors serving job shops and maintenance operations exhibit the highest price sensitivity, while Tier-1 automotive OEMs with captive technical service teams prioritize performance guarantees over unit economics.
Supply Chain Analysis
Export-control restrictions on advanced polymer processing equipment limit capacity expansion in certain jurisdictions, concentrating multilayer composite manufacturing in Germany, the United States, and Japan. Raw material flows draw from Saudi Arabian and Qatari polyethylene feedstock, Chinese VCI active ingredient synthesis, and European specialty paper substrates. Single-source vulnerability runs through nitrite-based chemistry suppliers facing REACH authorization withdrawal. Distribution runs through captive technical service teams for major automotive exporters, while fragmented job-shop demand aggregates through industrial packaging resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory divergence between EPA FIFRA, REACH, and Japan's JIS Z 1535 standards fragments product lines and creates specialist niches for compliance-focused suppliers. This fragmentation rewards targeted capability investments over broad-based market coverage.
For Market Incumbents: Harden specification-setting authority by embedding captive metallurgy laboratories within Stuttgart and Shanghai automotive corridors. Deepen backward integration into amine-carboxylate chemistry production to offset feedstock volatility and secure EPA registration timelines. Consolidate distributor relationships around integrated platforms offering bundled corrosion audit services, neutralizing price-only competitors. For New Entrants and Emerging Players: Recyclable and bio-based VCI substrates for European automotive exporters represent the most penetrable entry point, as REACH nitrite restrictions accelerate demand for plant-derived alternatives. India's Tamil Nadu precision engineering corridor offers secondary penetration potential as BIS certification requirements mature. Lead with technical service deployment rather than product margin, capturing recurring corrosion program management revenue before scaling manufacturing footprint. For Investors and Strategic Acquirers: REACH authorization deadlines for legacy nitrite chemistries reshape the acquisition landscape toward formulators with proven amine-carboxylate pipelines and established EPA dual-registration. Five-to-ten-year viability favors backward-integrated specialists with captive film extrusion and direct automotive OEM relationships. Monitor EPA registration approval timelines for novel plant-derived inhibitors as the critical inflection signal for portfolio rebalancing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into VCI Chemistry | Cortec Corporation's captive formulation control insulates margin structures from raw material volatility. |
| Recyclable Substrate Development | Compostable film partnerships unlock circular-economy procurement channels with European automotive OEMs. |
| Captive Technical Service Deployment | Plant-level specification authority at Stuttgart-based Tier-1 suppliers displaces distributor intermediaries. |
| Dual-Registration Compliance Investment | Parallel EPA FIFRA and REACH authorization accelerates market access across transatlantic supply chains. |
| Aftermarket Corrosion Audit Services | Unbundled VCI program management creates recurring revenue streams from industrial accounts. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive component procurement directors, aerospace logistics managers, VCI formulator R&D leads, industrial packaging distributors, and regulatory compliance officers. Secondary validation drew from EPA FIFRA registration databases, ECHA REACH authorization proceedings, Japan's JIS Z 1535 standards documentation, and customs trade flow records for polyethylene and specialty paper substrates. Bottom-up volume estimates from plant-level procurement data were triangulated against top-down market sizing derived from automotive export volumes and aerospace fastener shipment values.
Calibration against historical price realizations and regulatory approval timelines anchored the projection framework across the analysis window. Segmentation dimensions modeled include material composition tier, end-use application criticality, procurement scale archetype, and regional regulatory cluster. CAGRs were derived from slope analysis of adoption curves for amine-carboxylate alternatives and automotive export growth trajectories. Industry-specific inputs incorporated moisture vapor transmission rate specification trends and lot-traceability documentation burden estimates.
Macroeconomic conditions sit as an overlay; deviation in crude oil price trajectories and transoceanic freight rates would shift the trajectory for polyethylene-based format adoption. Forecasts reflect documented assumptions regarding REACH authorization timelines and EPA registration approval velocities. Material shifts in nitrite-based chemistry regulatory status or breakthrough plant-derived inhibitor efficacy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Cassava Bags Market
Bags and Containers
Compression Bags Market
Bags and Containers
Pasted Valve Bags Market
Bags and Containers
PVDC Shrink Bags Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Isothermal Bags Market
Bags and Containers
Bags and Containers Market
Bags and Containers
Breathable Bags Market
Bags and Containers
Flat Bottom Bags Market
Bags and Containers
Freezer Bags Market
Bags and Containers
BOPP Bags Market
Bags and Containers
Block Sack Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Big Bag Discharge Station Market
Bags and Containers
Leno Bags Market