
 Loop Handle Bags Market | 2026-2036
Loop Handle Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Loop Handle Bags Market Foresight
ISO 18606 compostability certification is redrawing competitive boundaries in loop handle bag supply. Novolex leverages integrated film-to-bag manufacturing across multiple North American plants. Berry Global Inc. anchors its position through blown film extrusion capacity and resin partnerships. Smurfit Kappa Group differentiates via paper-based loop handle systems targeting grocery replacement cycles.
Loop handle bags are carrier formats incorporating reinforced die-cut or attached handles formed from the primary substrate, typically produced through blown film extrusion, flat-bed die cutting, or twisted paper handle attachment at 70–150 gsm basis weight; they serve retail and grocery sectors requiring durable, ergonomic load-bearing capacity. Plastic material types still dominate volume but face margin compression from regulatory caps, while paper variants capture premium positioning in European grocery channels. Application segmentation shows retail and grocery absorbing the majority of unit demand, with promotional use representing a smaller but higher-margin pool tied to brand customization.
FDA food-contact regulations, EPA guidelines on recycled content claims, and EU REACH restrictions on phthalate plasticizers collectively constrain material choices and elevate compliance costs for cross-border suppliers. California's SB 270 reusable bag statute and New York's plastic bag ban create a patchwork of state-level standards that fragment procurement requirements. Stakeholders must monitor evolving extended producer responsibility frameworks and resin certification thresholds to secure shelf access in regulated channels.
Market Dynamics
EU Single-Use Plastics Directive enforcement and parallel state bans in California and New York are forcing substrate transitions across retail supply chains, compressing virgin plastic volumes while elevating certified compostable and recycled-content specifications.
Growth Catalysts
- REACH phthalate restrictions:EU ECHA mandates on plasticizer content are accelerating bio-based polymer adoption in European grocery retail.
- German reusable bag mandates:Grocery chains enforce strict carry-bag reusability standards, creating anchored demand for durable loop handle formats.
- Blown film extrusion advances:Thinner-gauge high-density polyethylene production is reducing material intensity per unit without sacrificing load capacity.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock fluctuations compress margins for non-integrated converters.
- California SB 270 patchwork:State-level reusable bag statutes create fragmented procurement requirements that complicate national distribution.
- Paper substrate limitations:Moisture sensitivity and basis weight minimums constrain paper loop handle performance in wet grocery environments.
Strategic Opportunities
- ISO 18606 certification gap:Limited compostable film capacity creates first-mover advantage for certified suppliers in regulated channels.
- Promotional brand customization:Higher-margin branded loop handle programs remain underpenetrated relative to plain grocery stock.
- Extended producer responsibility frameworks:Emerging EPR schemes in France and Italy mandate producer-funded collection, favoring established compliance infrastructure.
Industry Challenges
- Composting infrastructure mismatch:Industrial composting facility scarcity limits end-of-life value proposition for certified films.
- Cross-border resin certification:Divergent FDA food-contact and EU REACH standards complicate material qualification for multinational suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Loop Handle Bags Market |
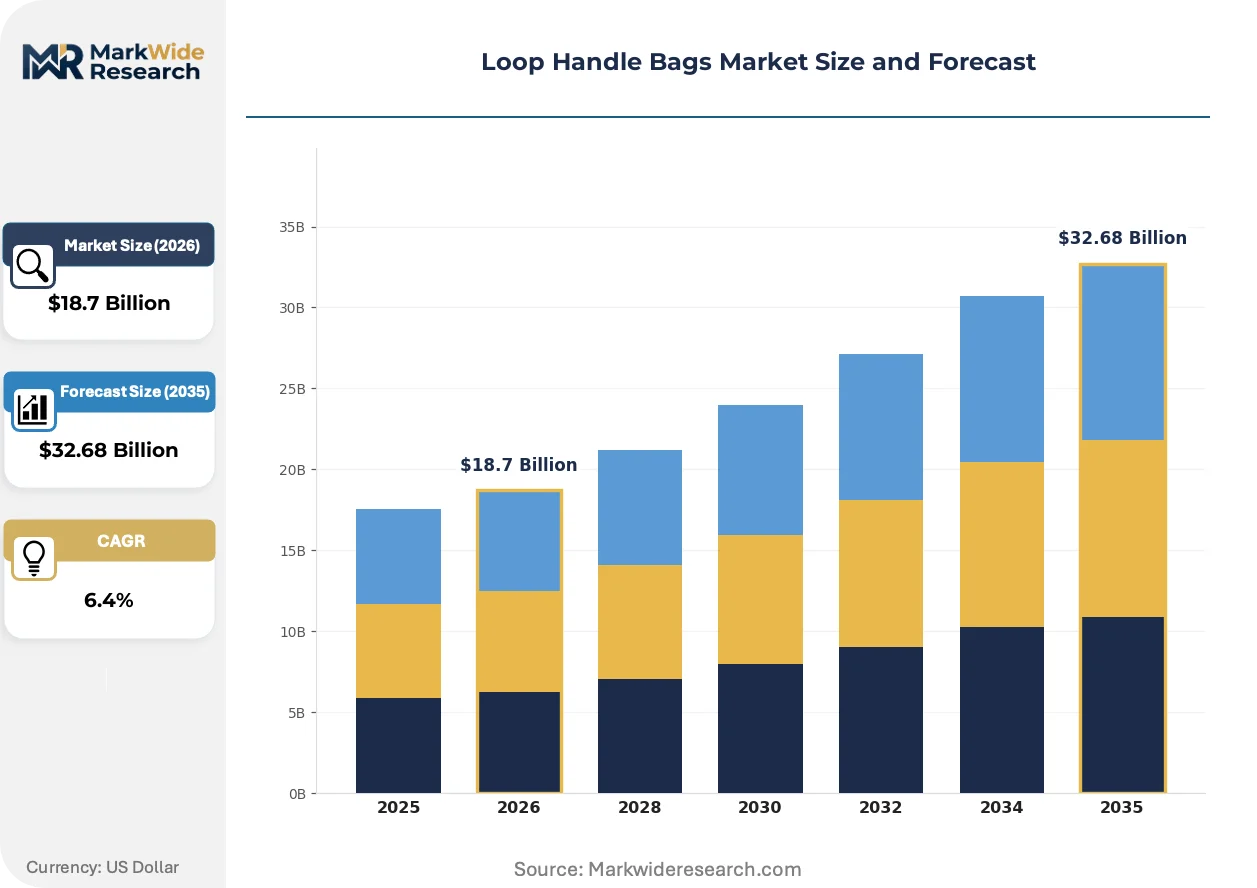
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Non-woven, Cotton Application: Retail, Grocery, Promotional, Packaging Size: Small, Medium, Large, Extra Large End User: Consumers, Businesses, Wholesalers, Events |
| Companies Covered | Novolex, Berry Global Inc., Smurfit Kappa Group, Amcor Limited, Bring Back Bag, Sunder Products, International Plastics, Avon-Flex, Alpha Poly Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Loop Handle Bags Market Shifts & Advancements
Material science advances and regulatory stringency are converging to reshape loop handle bag specifications, with certification thresholds and performance requirements tightening faster than substrate economics can absorb.
Biodegradable polymer blends incorporating polylactic acid and polyhydroxyalkanoates are miniaturizing the performance gap with conventional polyethylene in load-bearing applications. German discount grocery chains have adopted these formulations for private-label bag programs. The technology is miniaturizing the cost premium that previously confined compostable films to premium positioning.
California's SB 270 reusable bag statute mandates minimum 125-use durability testing and 20% post-consumer recycled content floors. Retail procurement teams must validate supplier claims through third-party certification. The regulation most affects mid-market grocery chains lacking in-house compliance resources.
Direct-store-delivery networks are consolidating bag procurement decisions from individual store managers to regional distribution centers. This concentration shifts volume toward contracted suppliers with national certification coverage. The pattern is most visible in US Northeast metropolitan markets where distributor consolidation has accelerated.
Loop Handle Bags Market Segmentation
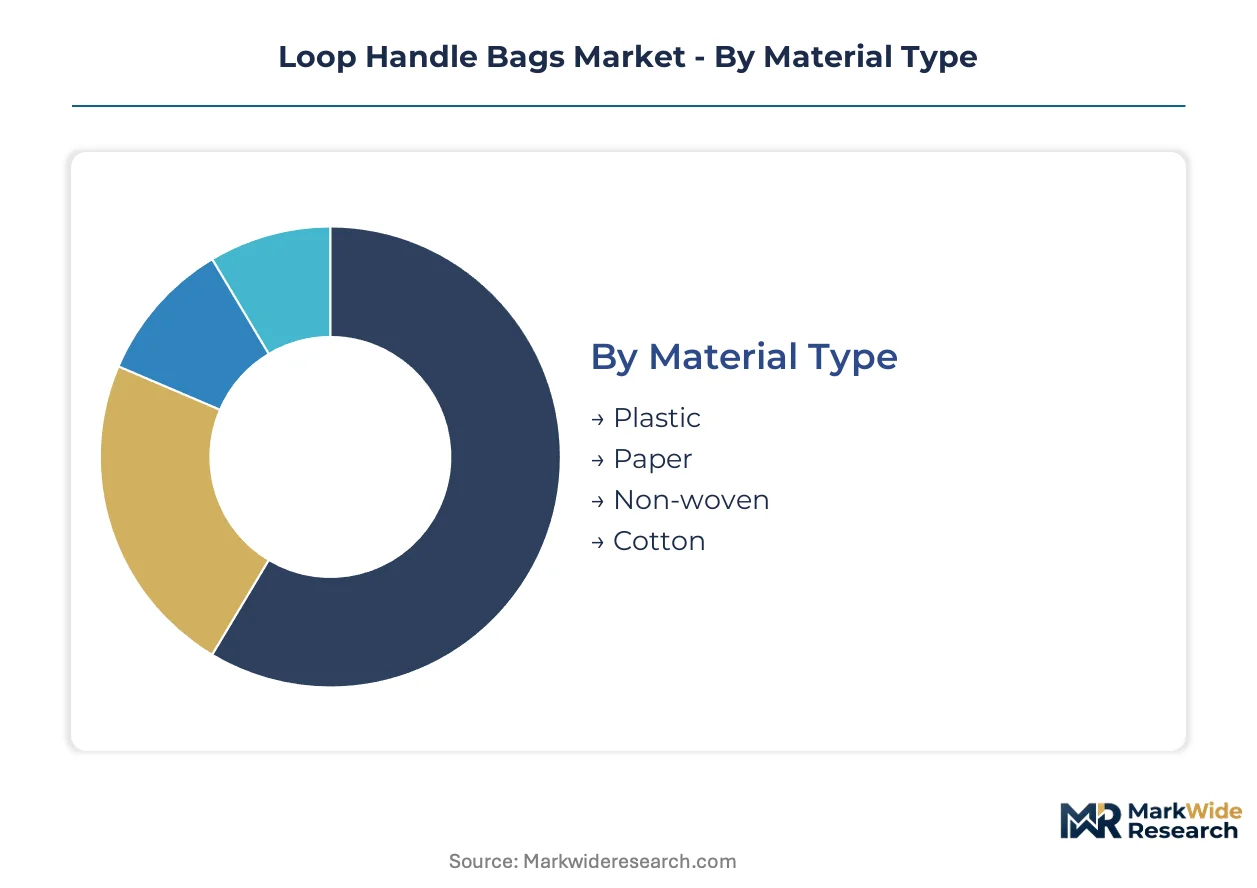
Loop handle bag procurement patterns diverge sharply between domestic retail consumption and export-led wholesale channels. Material specifications and size configurations track distinct regulatory thresholds across destination markets, forcing suppliers to maintain parallel product lines.
Material Type:
Domestic grocery retail in Germany and France absorbs high volumes of certified compostable films, while export-oriented manufacturing concentrates on conventional polyethylene for price-sensitive Asian and Latin American markets.
- Plastic:High-density polyethylene and low-density polyethylene formulations dominate load-bearing applications through blown film extrusion at 25–50 micron gauges. German discount grocery chains enforce strict reusability testing, compressing virgin resin demand in favor of post-consumer recycled blends that meet EU REACH phthalate limits.
- Paper:Kraft and white-top kraft substrates at 70–150 gsm basis weight serve European grocery replacement cycles where moisture sensitivity is manageable. Smurfit Kappa anchors supply through integrated paper mill and converting assets, capturing premium positioning in French and UK supermarket private-label programs.
- Non-woven:Polypropylene spunbond fabrics at 60–100 gsm offer intermediate durability for promotional and event use, with Chinese manufacturing clusters supplying North American brand marketers through direct import channels.
- Cotton:Natural fiber canvas at 8–12 oz weight serves boutique retail and corporate gifting segments, with Indian and Bangladeshi textile converters dominating export supply.
Plastic commands the established base. The steepest expansion runs through paper.
Application:
Volume concentration tilts toward high-frequency grocery replenishment, while margin capture concentrates in low-volume promotional programs requiring brand customization and shorter production runs.
- Retail:Department store and specialty retail adoption centers on polyethylene and non-woven formats with printed brand identifiers, with California SB 270 compliance mandating 125-use durability certification for reusable classifications.
- Grocery:Supermarket and hypermarket chains in Germany, France, and Italy enforce extended producer responsibility mandates, shifting procurement toward ISO 18606 certified compostable films or durable multi-use constructions.
- Promotional:Branded event and trade show distribution favors non-woven and cotton substrates with full-color printing, commanding 3–5x unit premiums over plain grocery stock.
- Packaging:E-commerce fulfillment and product protection applications favor plastic loop handle formats with reinforced bottom gussets, with demand clustering in US Northeast distribution centers.
Grocery absorbs volume leadership. Promotional segments are climbing the fastest on margin contribution.
Size:
European regulatory frameworks indirectly shape size distribution through reusability testing protocols that favor larger, more durable constructions over single-use mini formats.
- Small:Compact formats under 30 cm width serve pharmacy and convenience retail, with limited growth trajectory due to regulatory pressure on superfluous packaging.
- Medium:Standard 35–45 cm width configurations match average grocery basket volumes, dominating German and French supermarket procurement specifications.
- Large:Expanded 50–60 cm width constructions accommodate bulk retail and club store formats, with demand concentrating in US wholesale channels.
- Extra Large:Oversized formats above 65 cm width serve home improvement and furniture retail, with paper substrate limitations constraining adoption in wet or heavy-load environments.
Medium dimensions anchor current procurement. Large formats are gaining share fastest through club store expansion.
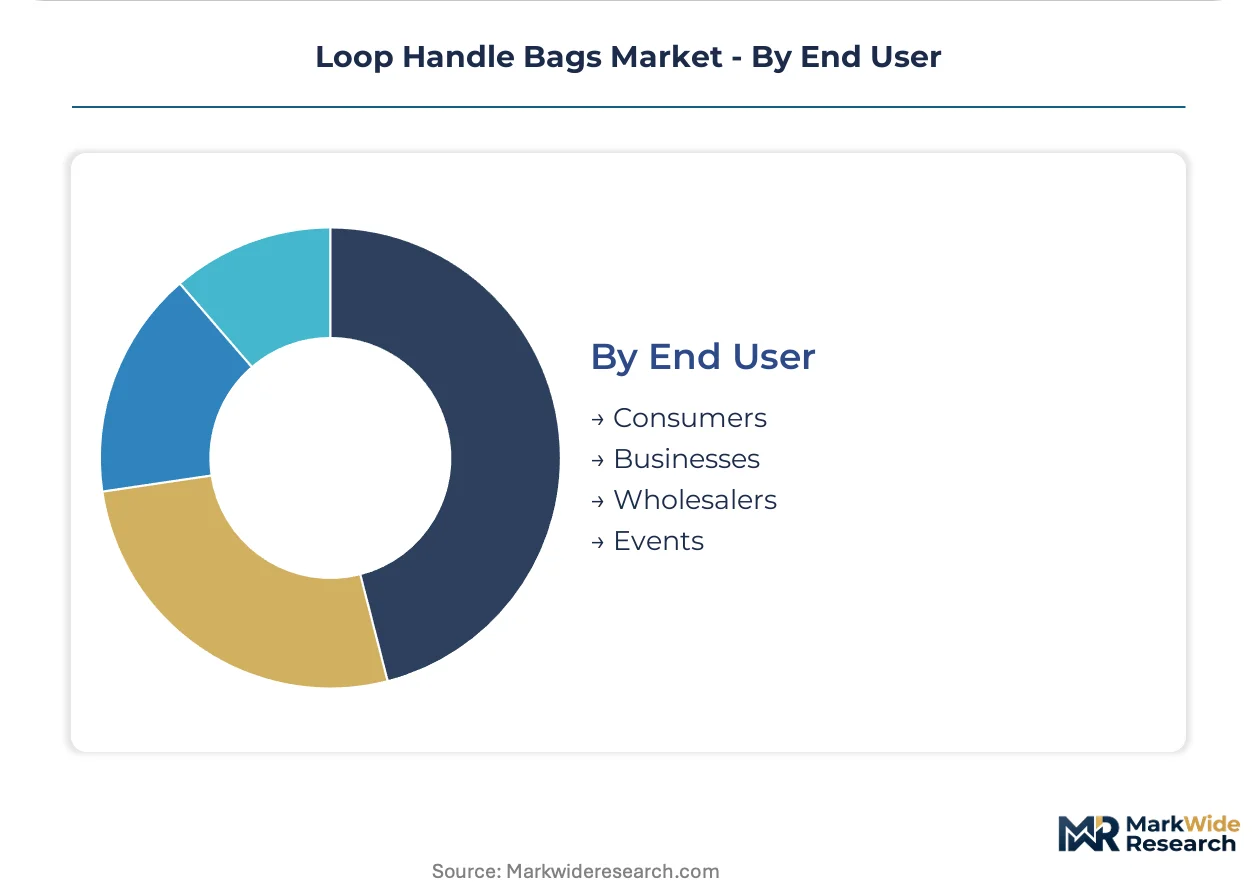
End User:
Procurement decision-making has consolidated from individual store managers to regional distribution centers, concentrating volume toward suppliers with national certification coverage and consolidated logistics capabilities.
- Consumers:Individual purchase patterns concentrate in retail checkout and event environments, with limited price elasticity for impulse-acquired reusable formats.
- Businesses:Corporate procurement programs for retail operations and office facilities enforce sustainability reporting requirements, favoring certified compostable or recycled-content specifications.
- Wholesalers:Distributor intermediaries in US Northeast and German wholesale markets aggregate demand across fragmented retail accounts, privileging suppliers with inventory depth and rapid replenishment.
- Events:Trade show and conference organizers represent seasonal demand spikes with concentrated lead times, favoring non-woven and cotton formats with expedited custom printing.
Business procurement commands volume concentration. Event segments show the steepest expansion trajectory on brand customization premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility mandates and single-use plastic bans are redirecting procurement flows across major economies. Germany, France, and California enforce the strictest reusability standards. Asian manufacturing clusters supply price-sensitive markets with conventional polyethylene formats.
United States
California's SB 270 statute mandates 125-use durability testing and 20% post-consumer recycled content floors for reusable bag classifications. The EPA oversees recycled content claim verification under its guidelines. Northeast metropolitan distribution centers concentrate procurement decisions, consolidating volume toward suppliers with national certification coverage.
Germany
Discount grocery chains anchor European demand through strict carry-bag reusability mandates that favor durable loop handle constructions. ECHA enforces REACH phthalate restrictions that accelerate bio-based polymer adoption. The country's central European logistics position channels certified compostable film supply into French and Italian retail networks.
France
Supermarket private-label programs drive premium positioning for paper-based loop handle systems in grocery replacement cycles. Emerging EPR frameworks mandate producer-funded collection infrastructure. Paris-region retail headquarters coordinate centralized procurement specifications that privilege ISO 18606 certified suppliers.
China
Manufacturing clusters in the Yangtze River Delta and Pearl River Delta supply global export demand for conventional polyethylene and non-woven formats. The country's national environmental regulator enforces dual carbon goals that pressure domestic converters toward recycled-content specifications. Zhejiang and Jiangsu provinces host integrated film-to-bag production capacity serving North American and European wholesale channels.
India
BIS standards on plastic thickness and recyclability constrain virgin material use in domestic retail applications. The central government's PLI scheme incentivizes domestic manufacturing of biodegradable alternatives. Maharashtra and Gujarat textile converters supply cotton canvas loop handle formats for boutique retail and corporate gifting segments.
Loop Handle Bags Market Competitive Landscape
Listed leaders compete with private specialists across substrate technology and certification depth. The vendor base fragments across integrated resin-to-bag manufacturers, paper-based converters, and regional non-woven fabricators. Three archetypes dominate: blown film extrusion specialists with captive resin partnerships, integrated paper mill operators leveraging kraft substrate control, and import-dependent distributors serving promotional segments. Capacity expansion and certification acquisition represent the dominant competitive moves as procurement teams consolidate supplier bases.
Within the integrated manufacturing tier, Novolex and Berry Global Inc. exemplify North American scale positions anchored in multi-plant film extrusion networks. Smurfit Kappa Group occupies a distinct European paper-based position through mill-integrated converting assets. These three names represent the structural concentration visible across substrate categories.
| Leading Market Players |
|---|
| Novolex |
| Berry Global Inc. |
| Smurfit Kappa Group |
| Amcor Limited |
| Bring Back Bag |
| Sunder Products |
| International Plastics |
| Avon-Flex |
| Alpha Poly Corporation |
| Others |
Supply & Pricing Matrix
Post-consumer recycled resin substitution for virgin polyethylene simultaneously shifts supply geography toward North American reprocessing clusters and compresses pricing power for non-integrated converters dependent on spot resin markets. This input transition rewards suppliers with captive recycling infrastructure while squeezing margins for buyers locked into conventional supply contracts.
Pricing Analysis
Certification level creates the primary spread between commodity polyethylene and ISO 18606-compliant compostable films, with three-tier pricing structure across premium certified, standard recycled-content, and economy virgin resin tiers. Price differentiation hinges on ECHA REACH compliance documentation and California SB 270 durability validation. Cost compression in the virgin resin tier is intensifying because of ethylene feedstock volatility. Grocery retail procurement teams show highest price sensitivity, while promotional brand marketers absorb premium positioning with minimal elasticity.
Supply Chain Analysis
Just-in-time inventory strategies dominate European grocery retail procurement, while North American distributors maintain strategic stockpiles against resin price volatility. Supply concentrates in China, Germany, and the United States, with Yangtze River Delta manufacturing clusters feeding export demand. The chain draws from ethylene feedstock, blown film extrusion capacity, and third-party certification services. Single-source vulnerability runs through concentrated compostable film resin supply. Distribution runs through regional distribution centers consolidating formerly fragmented store-level procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Extended producer responsibility frameworks are transforming loop handle bags into compliance-platform economics, where interoperability across certification systems determines shelf access. The shift favors suppliers building modular compliance infrastructure spanning FDA, REACH, and state-level mandates.
For Market Incumbents: Fortify positions through backward integration into post-consumer recycled resin reprocessing and ISO 18606 certification acquisition. Blown film extrusion capacity in multiple North American plants anchors supply security against resin volatility. Novolex and Berry Global demonstrate the defensive value of captive resin partnerships.
For New Entrants and Emerging Players: Differentiate on compostable film formulations with certified supply to German and French grocery retail. Promotional brand customization segments remain underpenetrated relative to plain grocery stock, offering white-space entry. Direct-store-delivery network consolidation creates channel openings for regional suppliers with rapid custom printing capabilities.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated manufacturers with mill-integrated converting assets and established EPR compliance infrastructure. Long-term viability centers on suppliers navigating tightening certification thresholds across multiple regulatory jurisdictions. The signal to watch is industrial composting facility buildout rates, which determine end-of-life value realization for certified films.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recycling | Captive post-consumer resin supply insulates margins against ethylene volatility. |
| ISO 18606 Certification Acquisition | EU grocery retail mandates create first-mover advantage in regulated channels. |
| Regional Distribution Center Consolidation | Northeast US metropolitan markets concentrate procurement toward certified national suppliers. |
| Compostable Film Formulation R&D | Polylactic acid and polyhydroxyalkanoate blends narrow performance gaps with polyethylene. |
| EPR Compliance Infrastructure Buildout | France and Italy mandates favor producers with producer-funded collection capabilities. |
Research Methodology
Desk research of trade customs data, SEC filings from packaging converters, and EU regulatory databases preceded structured interviews with blown film extrusion plant managers, grocery retail procurement directors, sustainability compliance officers, and resin supply specialists. Primary fieldwork across Germany, France, California, and China validated secondary estimates. Bottom-up unit volume modeling triangulated against top-down value chain analysis.
Variance decomposition across material type, application, and regional regulatory cluster shaped the analytical framework over the projection horizon. Segmentation dimensions included plastic versus paper substrate, retail versus promotional end-use, and certified compostable versus conventional specifications. CAGRs derived from elasticity-adjusted demand curves incorporating EPR mandate phase-in schedules and resin price scenario modeling. Forecast inputs included German reusable bag mandate enforcement intensity and California SB 270 compliance cost pass-through rates.
The analysis sits within stated boundaries; outcomes outside sustained regulatory enforcement or industrial composting infrastructure buildout would require recalibration. Forecasts reflect documented assumptions regarding EPR implementation timelines and resin technology cost curves. Revision becomes warranted when bio-based polymer cost parity thresholds cross decisively.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Net Bags Market
Bags and Containers
Conductive Bags Market
Bags and Containers
Bag-In-Box Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Mesh Bags Market
Bags and Containers
Bulk Bag Conditioners Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Zipper Bags Market
Bags and Containers
Inner Bulk Liners Market
Bags and Containers
Water Soluble Bags Market
Bags and Containers
Nonwoven Containers Market
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
Non-Laminated Heat-Sealed Bags Market
Bags and Containers
Clay Desiccant Bag Market
Bags and Containers
Laser Scored Bags Market
Bags and Containers
Global Household Food Storage Containers Market