
 Mattress and Furniture Bags Market | 2026-2036
Mattress and Furniture Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Mattress and Furniture Bags Market Foresight
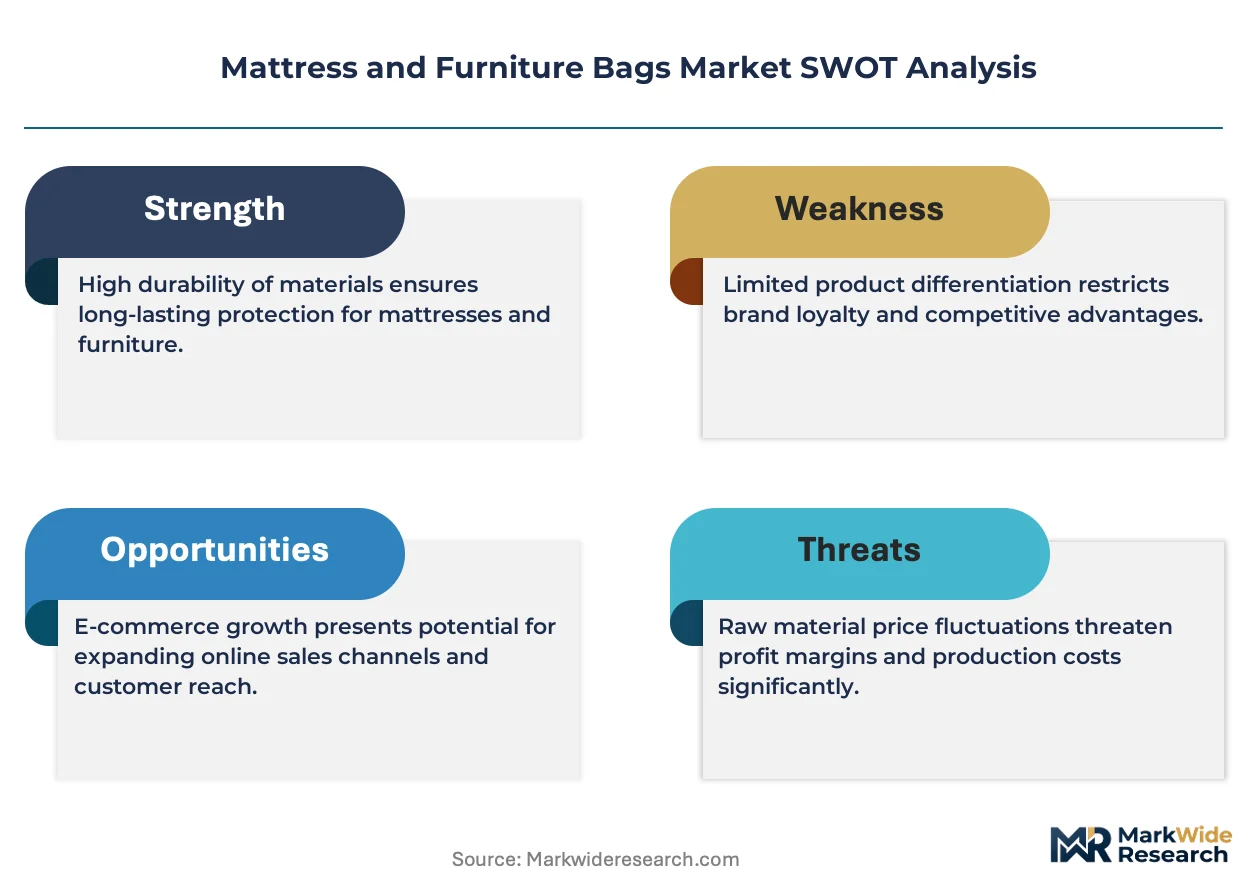
Heavy-duty polyethylene specifications are redrawing competitive boundaries in protective packaging. U-Haul International leverages its captive moving-services network to anchor bag sales directly at the point of rental. Grainger, Inc. sustains institutional contracts through industrial-grade vinyl furniture protectors stocked for commercial maintenance teams. Uline, Inc. dominates direct-to-business distribution with exhaustive catalog breadth and next-day fulfillment infrastructure.
Mattress and furniture bags are protective enclosures manufactured from polyethylene, vinyl, or woven fabric, typically ranging from 2 to 6 mil thickness, designed to shield upholstered goods from moisture, dust, and abrasion during storage or transport. Their primary commercial purpose centers on damage prevention across moving, renovation, and long-term warehousing applications. Polyethylene material commands the largest volume share due to its cost-efficiency and moisture-barrier performance, while vinyl alternatives capture premium margin pools in hospitality and commercial settings where reusability matters. Moving companies represent the fastest-growing end-user channel as professional relocation services expand fleet capacity and standardize protective protocols.
FDA guidelines on food-contact plastics indirectly constrain recycled-content sourcing for manufacturers serving dual-use packaging segments, while EPA waste-reduction frameworks push reformulation toward post-consumer resin incorporation. OSHA workplace safety standards influence bag thickness and labeling requirements for commercial handlers lifting wrapped furniture. Stakeholders must monitor evolving state-level extended producer responsibility legislation that could reshape material specifications and recycling infrastructure investments.
Market Dynamics
EPA waste-reduction frameworks are compressing virgin resin demand while moving companies standardize protective protocols, forcing manufacturers to reformulate around post-consumer polyethylene without sacrificing 2-6 mil puncture resistance.
Growth Catalysts
- Professional moving services expansion:Fleet operators are mandating mattress bags for damage-claim reduction, creating institutional pull through rental networks and direct procurement contracts.
- REACH-compliant recycled-content mandates:European Union packaging waste directives are accelerating post-consumer resin incorporation targets for polyethylene film producers serving cross-border logistics.
- Renovation activity concentration:United States metropolitan remodeling permits sustain steady volume for dust-protection applications in residential storage.
Market Restraints
- Polyethylene resin price volatility:Feedstock ethylene costs tied to natural gas liquids create margin compression for 2-4 mil standard-grade bag producers.
- Thin-film collection infrastructure gaps:Municipal recycling streams lack dedicated polyethylene film sorting capacity, limiting closed-loop material recovery for manufacturers.
- Biodegradable alternative performance deficits:PLA and starch-based films fail moisture-barrier testing at equivalent thickness, constraining premium positioning.
Strategic Opportunities
- Hospitality refurbishment cycles:Hotel mattress replacement programs in Florida and Nevada generate concentrated demand for reusable vinyl protectors with branded closures.
- Extended producer responsibility frameworks:California and New York state-level packaging fee structures reward higher recycled-content ratios with reduced compliance burdens.
- E-commerce furniture fulfillment:Direct-to-consumer mattress-in-a-box shippers are adopting custom-fit polyethylene sleeves for last-mile damage prevention.
Industry Challenges
- Post-consumer resin certification timelines:FDA food-contact clearance processes delay dual-use packaging segment sourcing flexibility.
- Film thickness standardization gaps:Absence of unified mil-rating protocols across moving, storage, and hospitality verticals complicates SKU rationalization.
- Legacy warehouse management integration:Automated bag-dispensing systems require retrofitting for pallet-scale furniture protection workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mattress and Furniture Bags Market |
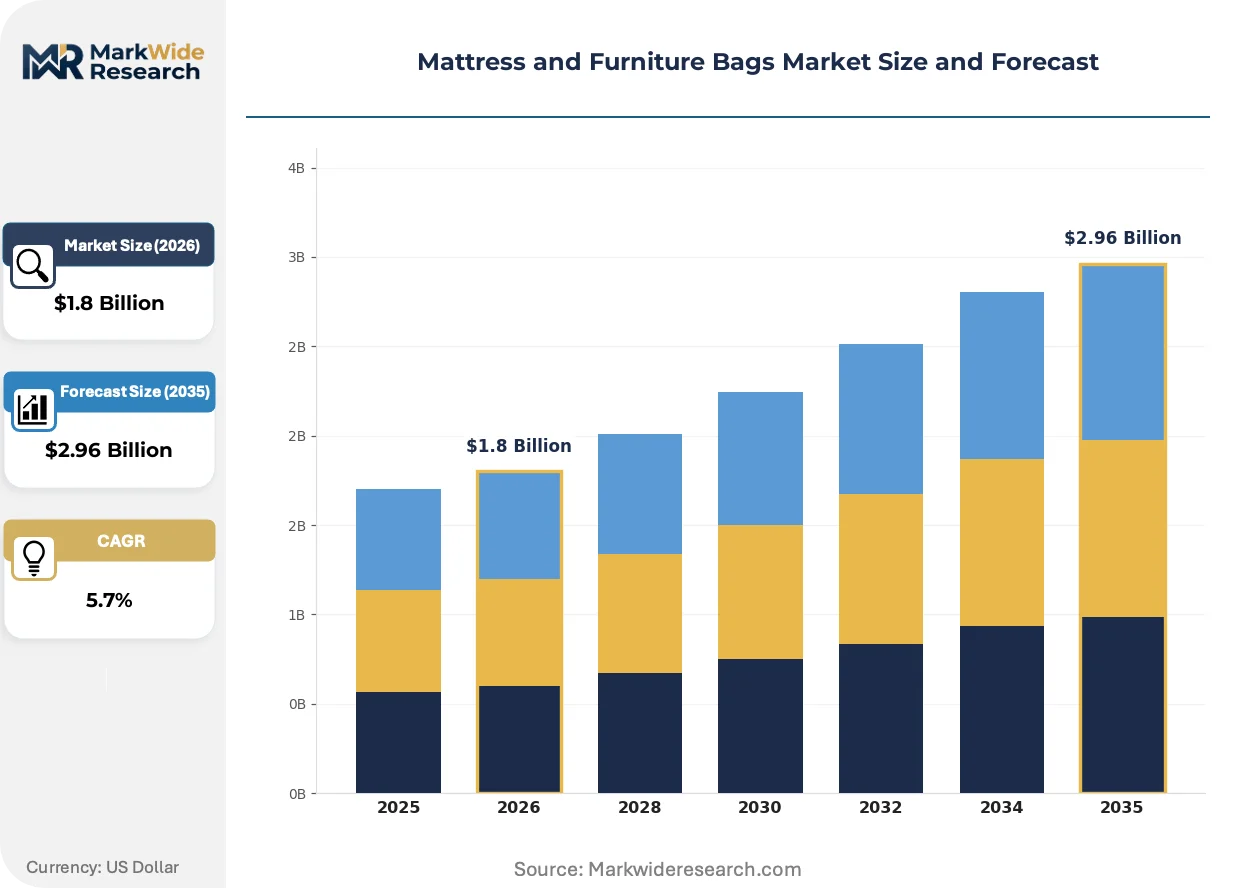
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mattress Bags, Sofa Covers, Armchair Covers, Furniture Protectors Material: Plastic, Fabric, Polyethylene, Vinyl End User: Residential, Commercial, Hospitality, Moving Companies Packaging Type: Rolls, Bags, Sheets, Bulk Packs |
| Companies Covered | U-Haul International, Inc., Grainger, Inc., Global Industrial, Home Depot, Uline, Inc., Coverstore, Mattress Safe, Inc., Polymershapes, Interstate Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mattress and Furniture Bags Market Shifts & Advancements
Material science advances and regulatory compliance pressures are fragmenting the protective packaging landscape into performance-tiered segments. Manufacturers now balance virgin resin cost efficiency against circular-economy positioning.
Co-extruded multilayer polyethylene is bifurcating the standard-grade segment from premium moisture-barrier applications. Moving companies with high-claim exposure are adopting 4-6 mil reinforced films at triple the rate of residential DIY buyers. This thickness stratification is compressing mid-tier supplier margins while rewarding dedicated industrial-grade producers with specification lock-in.
EPA's evolving guidelines on single-use plastics are forcing reformulation toward 30% post-consumer resin minimums for non-food packaging. Film extruders serving dual-use segments face sourcing constraints as FDA indirect food-contact rules limit recycled-content eligibility. Manufacturers are responding by segregating production lines between FDA-compliant virgin streams and EPA-aligned recycled-content dedicated capacity.
Direct procurement from moving fleet operators is displacing distributor-mediated purchasing for high-volume accounts. U-Haul and similar rental networks now specify bag dimensions and closure types in master service agreements, bypassing traditional industrial supply catalogs. This channel compression is most visible in Texas and California, where consolidated fleet purchasing concentrates volume with three specialized converters.
Mattress and Furniture Bags Market Segmentation
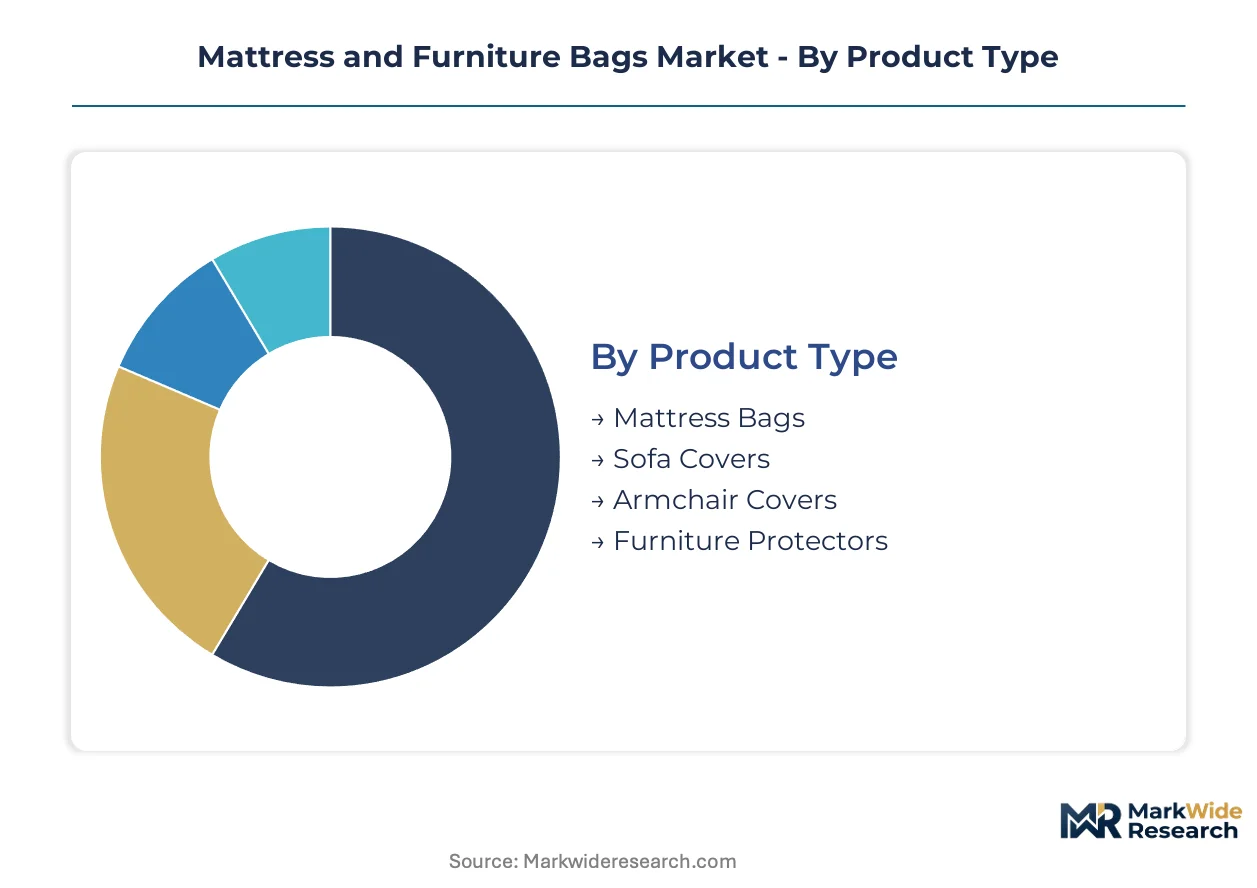
Segmentation in the mattress and furniture bags market determines which specifications capture volume versus margin. Channel dynamics vary sharply between commodity polyethylene rolls sold through industrial distributors and custom-fit vinyl protectors specified by hospitality procurement teams.
Product Type:
Mattress bags flow through moving company rental counters and e-commerce fulfillment channels, while furniture protectors concentrate in commercial maintenance contracts.
- Mattress Bags:Manufactured from 2-6 mil polyethylene with gusseted side panels for queen and king dimensions. Fleet operators in Texas and California specify reinforced 4-mil minimums for damage-claim reduction, driving institutional procurement consolidation.
- Sofa Covers:Elasticized polyethylene or non-woven fabric designs with drawstring closures. Renovation contractors in United States metropolitan markets sustain steady volume for dust-protection during residential remodeling.
- Armchair Covers:Compact-format protectors targeting single-piece upholstery. Retail hardware channels stock these for DIY moving applications.
- Furniture Protectors:Multi-purpose sheets for tables, dressers, and irregular shapes. Commercial storage facilities purchase these in bulk for warehouse inventory protection.
Mattress bags dominate installed base. Sofa covers are where expansion concentrates.
Material:
Cost tier stratification separates commodity resin grades from premium formulations serving reusability requirements.
- Plastic:Generic term encompassing LDPE and LLDPE formulations. Standard-grade 2-3 mil films serve price-sensitive residential moving applications through mass-market retailers.
- Fabric:Non-woven polypropylene or canvas alternatives. These capture premium positioning in hospitality refurbishment cycles where branded appearance and multiple-use durability justify higher unit economics.
- Polyethylene:Dominant volume material with co-extruded multilayer structures for moisture barrier performance. EPA waste-reduction frameworks are compressing virgin resin demand while manufacturers reformulate around post-consumer content.
- Vinyl:PVC-based films with 8-12 mil thickness for heavy-duty commercial applications. Hotel mattress replacement programs in Florida and Nevada generate concentrated demand for reusable vinyl protectors with zippered closures.
Polyethylene dominates installed base. Vinyl is where margin expansion concentrates.
End User:
Customer type determines specification rigor, with commercial accounts demanding certified thickness and closure integrity versus residential price sensitivity.
- Residential:DIY movers purchasing through hardware retailers or rental counter add-ons. Volume concentrates in standard 2-mil polyethylene bags for single-use applications.
- Commercial:Corporate relocation services and furniture retailers with standardized protective protocols. These accounts specify 4-mil minimums and master service agreements with direct converter relationships.
- Hospitality:Hotel and motel operators with mattress replacement programs. Procurement teams prioritize reusable vinyl formats with property branding and extended lifecycle performance.
- Moving Companies:Fleet operators mandating protective packaging for damage-claim reduction. This channel is expanding most quickly as professional relocation services standardize bag specifications across national networks.
Residential dominates installed base. Moving companies are where volume growth concentrates.
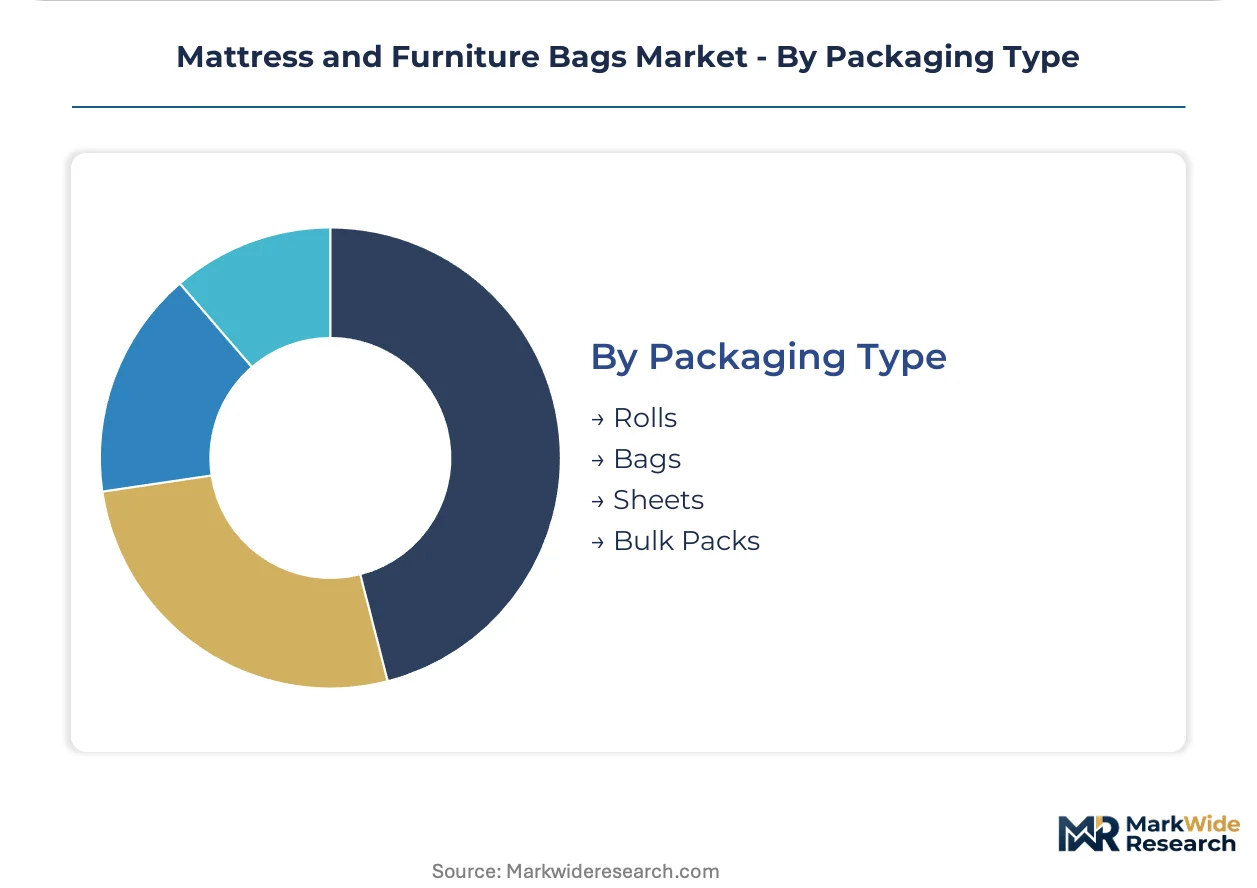
Packaging Type:
Supply concentration varies by format, with rolls and bulk packs flowing through industrial distributors versus individual bags at retail.
- Rolls:Continuous polyethylene film on cardboard cores for on-site cutting. Commercial movers and storage facilities purchase these for dimensional flexibility across mixed furniture inventories.
- Bags:Pre-sized individual protectors with sealed or gusseted construction. U-Haul rental networks and hardware retailers stock these for consumer convenience and impulse purchase.
- Sheets:Flat-cut film for draping over large or irregular pieces. Art handlers and antique specialists specify these for custom protection applications.
- Bulk Packs:Case-quantity packaging for institutional procurement. Property management companies and hotel chains purchase bulk packs for standardized inventory across multiple locations.
Rolls dominate installed base. Bags are where channel expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential DIY buyers in mass-market retail channels exhibit the highest price elasticity, while fleet operators in consolidated procurement markets absorb premium specifications without volume contraction.
United States
Professional moving services and renovation activity concentrate demand in Texas and California, where fleet operators mandate 4-mil polyethylene minimums for damage-claim reduction. EPA waste-reduction frameworks are compressing virgin resin demand while pushing reformulation toward post-consumer content. The Dallas-Fort Worth metroplex anchors procurement consolidation for national rental networks.
Germany
REACH-compliant recycled-content mandates from ECHA are accelerating post-consumer resin incorporation targets for polyethylene film producers. Industrial logistics hubs in the Rhine-Ruhr region sustain institutional demand for heavy-duty furniture protection. Berlin-based packaging distributors are bridging cross-border supply into neighboring EU markets.
China
E-commerce furniture fulfillment expansion is driving custom-fit polyethylene sleeve adoption among direct-to-consumer mattress shippers. MEE guidelines on plastic waste reduction are pressuring manufacturers toward circular-economy reformulation. The Yangtze River Delta manufacturing cluster dominates export-oriented film extrusion capacity.
United Kingdom
Commercial relocation services and hospitality refurbishment cycles sustain vinyl protector demand in London and Southeast England. EU packaging waste directives continue influencing domestic regulatory alignment post-Brexit. Manchester logistics corridors channel distribution into Northern England and Scotland.
India
Urban residential mobility and metro-area renovation activity are expanding polyethylene bag consumption in Maharashtra and Karnataka. BIS standards for plastic packaging are gradually tightening material specifications. The Delhi-NCR warehousing cluster is emerging as a distribution hub for North Indian moving company procurement.
Mattress and Furniture Bags Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with specification-driven fleet contracts rewarding dedicated industrial-grade producers while mass retail channels compress margins for commodity converters. The market structure fragments across three tiers: captive rental-network suppliers, industrial distributors with catalog breadth, and specialized converters serving hospitality procurement. Two strategic archetypes dominate—vertically integrated fleet-affiliated suppliers and independent film extruders with direct converter relationships. Competitive moves concentrate on master service agreement lock-in with national moving networks and segregated production lines for regulatory compliance.
Among North American distributors, U-Haul International anchors the captive-network archetype through rental-counter integration, while Uline exemplifies catalog-breadth dominance in direct-to-business fulfillment. Grainger occupies the institutional maintenance-contract tier with industrial-grade vinyl positioning. These three represent the prevailing competitive vectors without implying specific strategic actions or market share claims.
| Leading Market Players |
|---|
| U-Haul International, Inc. |
| Grainger, Inc. |
| Global Industrial |
| Home Depot |
| Uline, Inc. |
| Coverstore |
| Mattress Safe, Inc. |
| Polymershapes |
| Interstate Packaging |
| Others |
Supply & Pricing Matrix
EPA waste-reduction frameworks gate both supplier qualification and price differentiation simultaneously, compressing virgin resin demand while rewarding post-consumer resin incorporation with compliance premiums. Fleet operators in Texas and California absorb specification-driven pricing without volume contraction, whereas residential DIY channels exhibit acute price elasticity toward standard-grade polyethylene.
Pricing Analysis
After-sales revenue from damage-claim reduction services drives lifetime value for fleet-affiliated suppliers. Three-tier pricing structure across premium, standard, and economy levels segments by mil thickness and closure type, with 4-6 mil reinforced films commanding sustained premiums. Cost compression in standard-grade 2-3 mil residential bags is intensifying because of polyethylene resin price volatility tied to natural gas liquids. Moving company fleet operators demonstrate lowest price sensitivity due to damage-claim liability exposure, while mass-market hardware retailers face highest elasticity.
Supply Chain Analysis
China and the United States anchor polyethylene film extrusion capacity for mattress and furniture bag production. Feedstock ethylene draws from natural gas liquids in North America and naphtha cracking in Asia, while post-consumer resin sourcing rests on municipal thin-film collection infrastructure. Single-source vulnerability concentrates in virgin resin supply chains exposed to commodity price swings. Distribution runs through industrial distributors with catalog breadth and captive rental-network counter integration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Damage-claim reduction services represent a service-attach opportunity expanding faster than hardware sales, as fleet operators monetize protection protocols beyond unit bag margins.
For Market Incumbents: Fortify master service agreement lock-in with national moving networks to preempt emerging specialized converters. Backward integration into post-consumer resin sourcing secures EPA compliance premiums against virgin resin price volatility. Certification investment in FDA-segregated production lines protects dual-use packaging segment access. For New Entrants and Emerging Players: Lead with hospitality refurbishment cycles in Florida and Nevada where reusable vinyl protector demand concentrates with branded closure specifications. White-space exists in e-commerce furniture fulfillment among direct-to-consumer mattress-in-a-box shippers adopting custom-fit polyethylene sleeves. Go-to-market through direct converter relationships bypasses distributor margin compression. For Investors and Strategic Acquirers: California and New York extended producer responsibility frameworks reshape the acquisition landscape toward recycled-content capability. Long-term viability centers on segregated production infrastructure serving both FDA-compliant virgin streams and EPA-aligned recycled-content capacity. Target film extruders with established post-consumer resin certification timelines. The signal to monitor is state-level packaging fee structure implementation accelerating compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Post-Consumer Resin Integration | EPA waste-reduction frameworks reward 30% minimum incorporation with reduced compliance burdens in California and New York. |
| Master Service Agreement Expansion | U-Haul rental networks specify bag dimensions and closure types, bypassing traditional industrial supply catalogs. |
| Segregated Production Line Investment | FDA food-contact clearance processes require dedicated virgin resin capacity separate from EPA-aligned recycled-content streams. |
| Hospitality Procurement Direct Access | Hotel mattress replacement programs in Florida and Nevada generate concentrated demand for reusable vinyl formats. |
| E-Commerce Fulfillment Partnership | Direct-to-consumer mattress shippers adopt custom-fit polyethylene sleeves for last-mile damage prevention. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA regulatory filings, customs trade data, and industrial distributor catalog disclosures. Conversations with fleet procurement managers, film extrusion plant engineers, hospitality purchasing directors, and retail category buyers informed specification trends and channel dynamics. Bottom-up volume triangulation against top-down market sizing validates segment-level outputs.
Segmentation dimensions modeled include material type, mil thickness tier, end-user channel, and packaging format across the projection horizon. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and fleet operator procurement consolidation. Industry-specific inputs incorporate polyethylene resin price indices and state-level extended producer responsibility implementation timelines.
Forecasts assume regulatory continuity in EPA waste-reduction frameworks and state-level packaging legislation; material policy shifts would require re-modeling around accelerated biodegradable mandates or resin import restrictions. Recalibration cycles align with material shifts in fleet operator procurement standardization and post-consumer resin certification clearance timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Counter Bags Market
Bags and Containers
North America Retail Bags Market
Bags and Containers
Slider Bags Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Anti-Static Polyethylene Bag Market
Bags and Containers
Inclusion Bags Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Air Bubble Bags Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Double Zipper Bags Market
Bags and Containers
Dome Shrink Basket Bags Market
Bags and Containers
Ventilated Bulk Bags Market
Bags and Containers
Heat Sealing Bags Market
Bags and Containers
Self-Sealed Bubble Bags Market
Bags and Containers
Drum Liners Market
Bags and Containers
Pasted Valve Bags Market