
 Double Zipper Bags Market | 2026-2036
Double Zipper Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Double Zipper Bags Market Foresight
Modular packaging configurations is shifting how procurement teams evaluate total cost of ownership across the supply chain. Berry Global Inc. leverages vertical integration in film extrusion and zipper track manufacturing to control specification consistency. SC Johnson & Son, Inc. anchors its position through brand strength in consumer-facing resealable formats. Reynolds Consumer Products LLC competes on manufacturing scale, operating high-throughput converting lines that serve retail private-label programs.
Double zipper bags incorporate two interlocking closure tracks, typically co-extruded with polyethylene or polypropylene substrates, to create redundant seals against moisture and oxygen ingress. The dual-track geometry permits repeated opening and closing without seal degradation, serving food preservation, pharmaceutical protection, and industrial component storage. Standard bags occupy the volume base across retail and household channels, while biodegradable bags represent the fastest-expanding material segment as converters respond to E.U. single-use directives and corporate sustainability procurement mandates. Custom bags concentrate margin pools where brand owners specify printed graphics, die-cut handles, or tamper-evident features.
The U.S. Food and Drug Administration governs food-contact materials through 21 CFR compliance, while the European Chemicals Agency enforces REACH restrictions on substances in plastic articles. The EU Packaging and Packaging Waste Regulation sets extended producer responsibility targets that reshape material selection and recyclability design. Stakeholders must monitor how evolving extended producer responsibility frameworks alter cost allocation between resin suppliers, converters, and brand owners across their served geographies.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing converters to redesign around mono-material architectures, eliminating multi-layer barriers that previously secured zipper track adhesion. This regulatory compression is redistributing technical capability toward film extruders with in-house lamination control.
Growth Catalysts
- REACH substance restrictions:ECHA enforcement on phthalate plasticizers is accelerating migration to bio-based zipper resins in food-contact applications across German retail chains.
- Chilled logistics expansion:European cold-chain infrastructure investment is pulling high-barrier double zipper specifications for temperature-sensitive pharmaceutical distribution.
- Mono-material co-extrusion:Advances in single-substrate zipper bonding are enabling mechanical recycling compatibility without seal performance loss.
Market Restraints
- Polyethylene resin concentration:Feedstock supply clusters along the US Gulf Coast expose converters to hurricane-induced volatility and force majeure events.
- Multi-layer legacy capacity:Stranded assets in solvent-based adhesive lamination lines create write-down pressure during mono-material transition.
- Paper-based flexible packaging:Fiber substitutes with grease-resistant coatings are capturing premium snack segments where moisture barriers are secondary.
Strategic Opportunities
- Indian cold-chain modernization:FSSAI enforcement of temperature-controlled distribution for dairy and prepared foods is opening specification demand for resealable barrier formats.
- Extended producer responsibility credits:EU member state eco-modulation schemes reward recyclability design with fee reductions that improve margin capture.
- RFID-zipper integration:Convergence of track-embedded antennas with inventory management systems is creating authenticated closure solutions for high-value pharmaceutical serialization.
Industry Challenges
- Mono-material certification timelines:RecyClass and APR testing protocols require 12-18 month validation cycles that delay product launches.
- Zipper track precision engineering:Tolerance control for interlocking geometry demands capital-intensive metrology systems that mid-scale converters struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Double Zipper Bags Market |
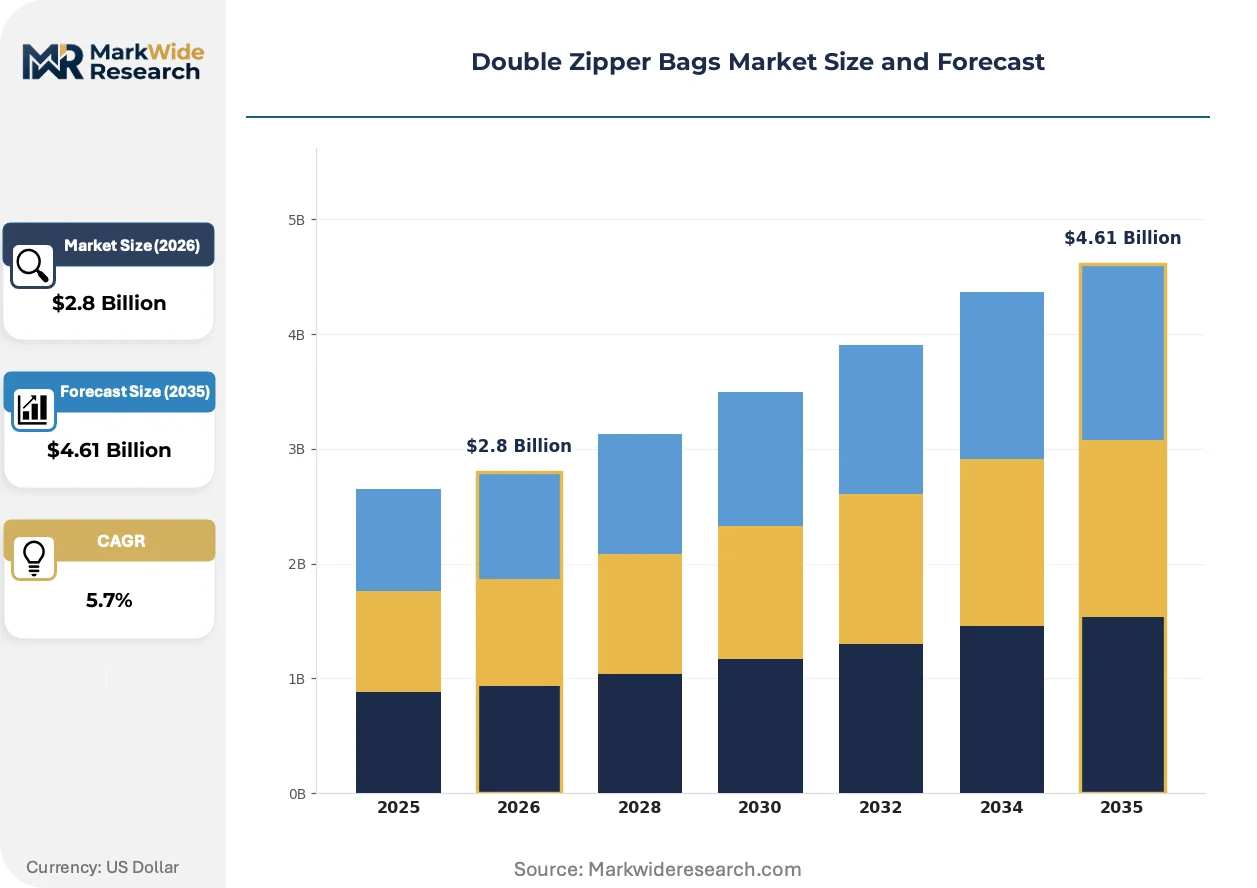
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Bags, Reusable Bags, Biodegradable Bags, Custom Bags Material: Polyethylene, Polypropylene, Low-Density Polyethylene, High-Density Polyethylene End User: Retail, Food Service, Packaging Industry, Households Size: Small, Medium, Large, Extra Large |
| Companies Covered | SC Johnson & Son, Inc., Berry Global Inc., Reynolds Consumer Products LLC, Amcor plc, Mondi, Sealed Air Corporation, Constantia Flexibles, Glenroy, Inc., ProAmpac LLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Double Zipper Bags Market Shifts & Advancements
Active material science and digital integration are compressing product development cycles while regulatory compliance is becoming a technical specification rather than a checkbox. These forces are converging to redefine competitive differentiation.
Biodegradable zipper resins derived from polylactic acid and polyhydroxyalkanoates are expanding into fresh produce retail where composting infrastructure exists. German supermarket chains specify these formats for private-label organic lines. The technology is expanding into premium positioning that commands shelf-space allocation and supplier preference.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated barrier coatings from food-contact films. Converters in the Netherlands and Belgium are retrofitting extrusion lines with plasma-enhanced chemical vapor deposition systems. The chilled ready-meal segment is absorbing reformulation costs through contract renegotiation.
Direct sourcing from converter to food-service operator is consolidating procurement decisions previously fragmented across distributors. Large European contract caterers now specify zipper performance metrics in tender documents. France and the UK exhibit the most advanced disintermediation, with buyers demanding lot-level traceability data.
Double Zipper Bags Market Segmentation
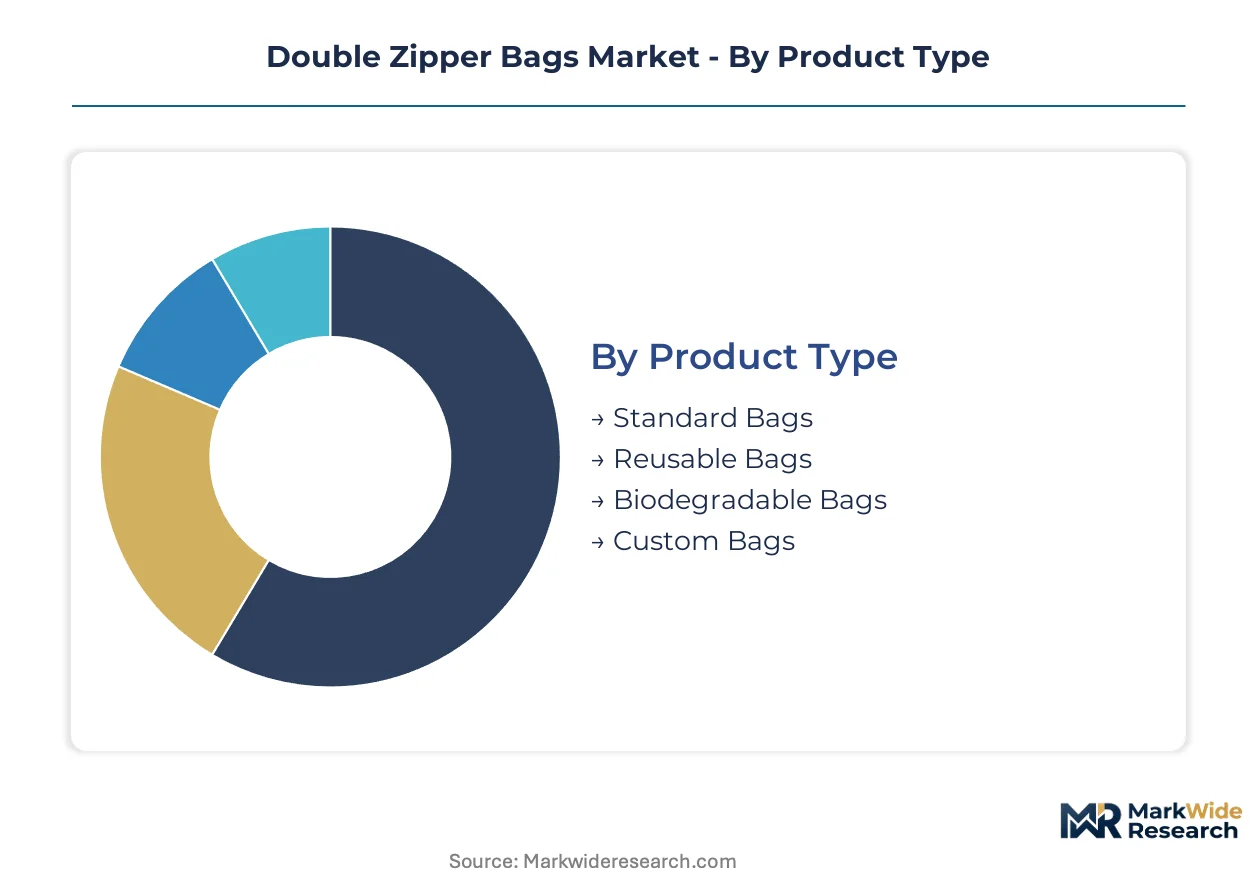
Converters and brand owners configure product portfolios across four intersecting dimensions. Material selection now dominates technical roadmaps as mono-material mandates reshape extrusion investments. End-user concentration in food service and retail channels dictates barrier specifications and closure durability requirements.
Product Type:
Procurement teams segment orders by usage frequency, disposal method, and customization depth rather than unit economics alone.
- Standard Bags:Single-use polyethylene or polypropylene formats with basic double-track closures serve high-volume retail and household channels. German supermarket chains specify these for private-label ambient and chilled lines where cost efficiency outweighs premium positioning.
- Biodegradable Bags:Polylactic acid and polyhydroxyalkanoate resins enable compostable disposal in municipal organic waste streams. Demand concentrates in French and Benelux retail where E.U. single-use directives and corporate sustainability procurement mandates accelerate specification shifts.
- Reusable Bags:Thicker gauge substrates with reinforced zipper tracks withstand 50-plus open-close cycles for industrial component storage and institutional food service.
- Custom Bags:Die-cut handles, tamper-evident features, and high-definition printed graphics serve brand-owner differentiation strategies in premium positioning.
Standard bags lead on scale; biodegradable bags lead on momentum.
Material:
Substrate selection determines recyclability certification pathways and zipper track bonding compatibility under evolving E.U. Packaging and Packaging Waste Regulation targets.
- Polyethylene:Linear low-density and metallocene grades dominate co-extrusion with zipper tracks for food-contact applications. Cold-chain infrastructure expansion across India pulls high-clarity formulations for temperature-sensitive pharmaceutical distribution.
- Polypropylene:Higher melting point and grease resistance suits hot-fill and microwaveable ready-meal formats. Dutch converters retrofit extrusion lines with plasma-enhanced chemical vapor deposition systems to eliminate fluorinated barrier coatings under REACH Annex XVII restrictions.
- Low-Density Polyethylene:Superior flexibility and impact resistance serve freezer-grade specifications for household and retail frozen food segments.
- High-Density Polyethylene:Stiffer hand and moisture barrier properties concentrate demand in industrial component storage and chemical protection applications.
Polyethylene commands installed capacity; polypropylene gains specification share fastest.
End User:
Channel concentration shapes order patterns, with direct sourcing from converter to operator consolidating procurement decisions previously fragmented across distributors.
- Food Service:Contract caterers and institutional kitchens specify portion-control formats with portion markings and resealability for freshness retention. Large European buyers now demand lot-level traceability data in tender documents.
- Retail:Private-label programs and branded consumer goods drive volume through high-throughput converting lines serving supermarket chains.
- Households:Mass-market consumption through club stores and e-commerce platforms emphasizes multi-pack configurations and value-tier pricing.
- Packaging Industry:Industrial converters and co-packers source unprinted stock for downstream customization and filling operations.
Food service leads on specification intensity; retail leads on absolute volume.
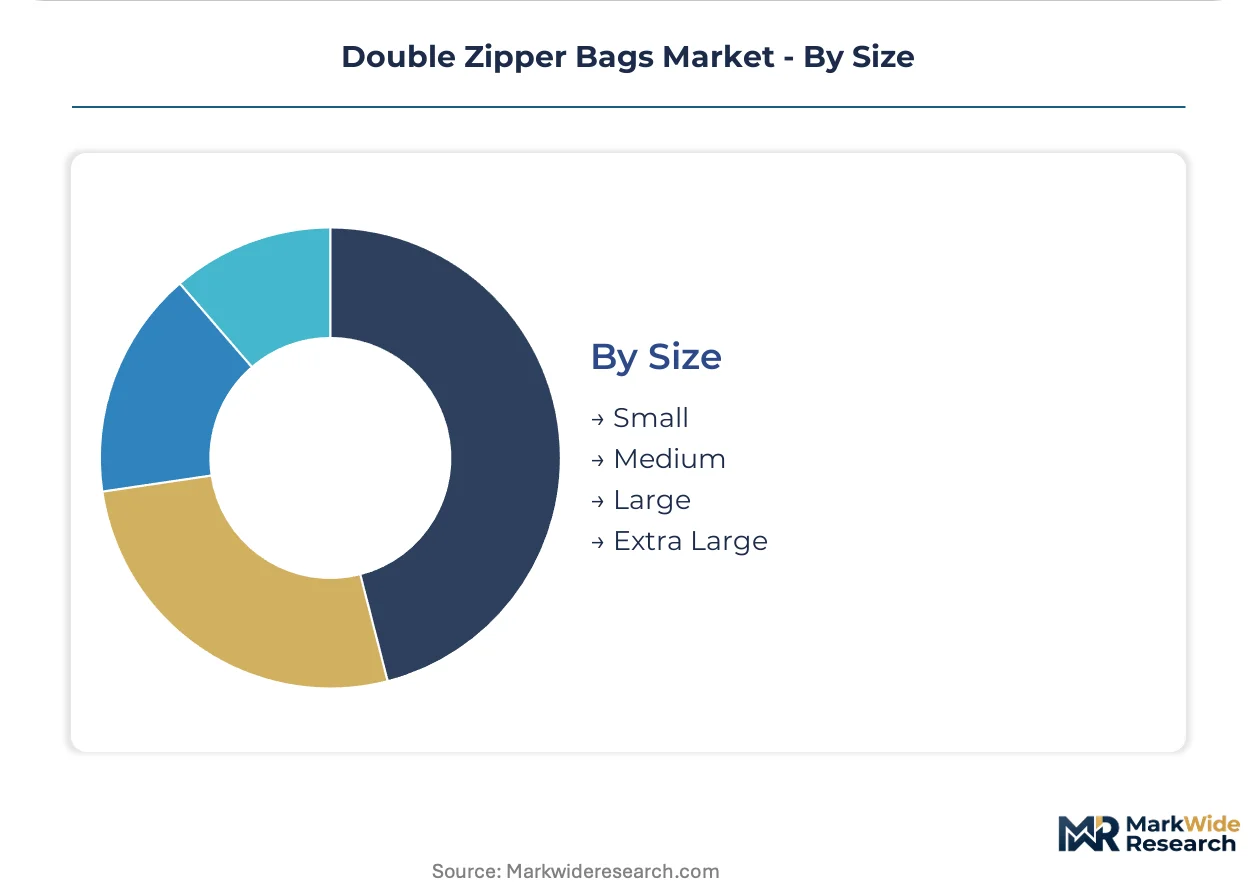
Size:
Dimensional segmentation aligns with filling equipment compatibility, shelf-space constraints, and end-use consumption patterns across channels.
- Small:Single-serve and sample formats serve pharmaceutical unit-dose and condiment portion packs.
- Medium:Standard household and retail SKUs balance storage efficiency with handling convenience for prepared foods and produce.
- Large:Bulk retail and food-service formats accommodate institutional procurement scales and back-of-house storage.
- Extra Large:Industrial and commercial specifications for component kits, garment protection, and oversized item handling.
Medium sizes anchor volume throughput; extra large commands margin premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Double zipper bag manufacturing traces its industrial lineage to post-war polyethylene extrusion advances in the United States and Germany, where food preservation chemistry and polymer processing first converged at commercial scale.
Germany
Retail chains and industrial buyers specify high-barrier zipper specifications for chilled and frozen applications. The EU Packaging and Packaging Waste Regulation tightens material recovery targets, pushing converters toward mono-material designs. The Rhine-Ruhr industrial corridor hosts film extruders retrofitting lines for mechanical recycling compatibility.
United States
Food service operators expand use of resealable formats for portion control and freshness retention. FDA 21 CFR compliance governs food-contact materials through substance restrictions and migration limits. The US Gulf Coast polyethylene resin clusters expose converters to hurricane-induced supply volatility.
France
Contract caterers demand lot-level traceability data in tender documents, consolidating procurement decisions previously fragmented across distributors. ECHA REACH enforcement on phthalate plasticizers accelerates migration to bio-based zipper resins. The Paris basin concentrates specification development for premium private-label organic lines.
India
FSSAI enforcement of temperature-controlled distribution for dairy and prepared foods opens specification demand for resealable barrier formats. Cold-chain infrastructure investment pulls high-clarity polyethylene formulations for pharmaceutical distribution. Maharashtra and Gujarat industrial zones attract converter capacity for domestic and export supply.
Netherlands
Converters retrofit extrusion lines with plasma-enhanced chemical vapor deposition systems to eliminate fluorinated barrier coatings under REACH Annex XVII restrictions. The chilled ready-meal segment absorbs reformulation costs through contract renegotiation. Rotterdam-Antwerp port logistics support resin import and film export flows.
Double Zipper Bags Market Competitive Landscape
Premium-margin players sit above commodity-margin players across specification intensity and certification depth. The vendor base stratifies into three tiers: integrated resin-to-zipper converters controlling co-extrusion consistency, brand-anchored consumer goods specialists, and scale-driven private-label manufacturers. Dominant competitive moves include backward integration into film extrusion and zipper track manufacturing, plus portfolio diversification into biodegradable resin formats.
Among US-based diversified packaging conglomerates, Berry Global Inc. and Reynolds Consumer Products LLC exemplify scale-driven archetypes, while SC Johnson & Son, Inc. represents brand-anchored positioning in consumer-facing resealable formats. These three companies occupy distinct margin tiers based on vertical integration depth and end-market concentration.
| Leading Market Players |
|---|
| SC Johnson & Son, Inc. |
| Berry Global Inc. |
| Reynolds Consumer Products LLC |
| Amcor plc |
| Mondi |
| Sealed Air Corporation |
| Constantia Flexibles |
| Glenroy, Inc. |
| ProAmpac LLC |
| Others |
Supply & Pricing Matrix
The EU Packaging and Packaging Waste Regulation gates qualified supply and premium-tier pricing access by mandating mono-material designs that eliminate multi-layer legacy capacity. Converters with certified mechanical recycling compatibility command margin premiums from German retail chains and French contract caterers, while uncertified competitors face price compression in commoditized standard bag segments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates RecyClass-certified mono-material formats from transitional multi-layer stock and basic polyethylene commodity bags. Price differentiation hinges on certification depth and volume scale, with private-label programs extracting steepest discounts through long-term offtake commitments. Cost compression in the economy tier is intensifying because stranded solvent-based lamination assets force fire-sale pricing. Household channel buyers exhibit highest price sensitivity; pharmaceutical and food-service operators prioritize seal performance over unit cost.
Supply Chain Analysis
Regional distribution centers in Germany, the Netherlands, and the United States anchor hub-and-spoke fulfillment patterns for chilled and frozen applications. Manufacturing concentrates in Germany, the United States, and India, with film extrusion and zipper track co-extrusion drawing from polyethylene resin clusters along the US Gulf Coast and Rotterdam-Antwerp port corridors. Feedstock supply rests on linear low-density polyethylene and metallocene grades vulnerable to hurricane-induced force majeure events. Distribution runs through direct converter-to-operator channels consolidating procurement decisions previously fragmented across distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
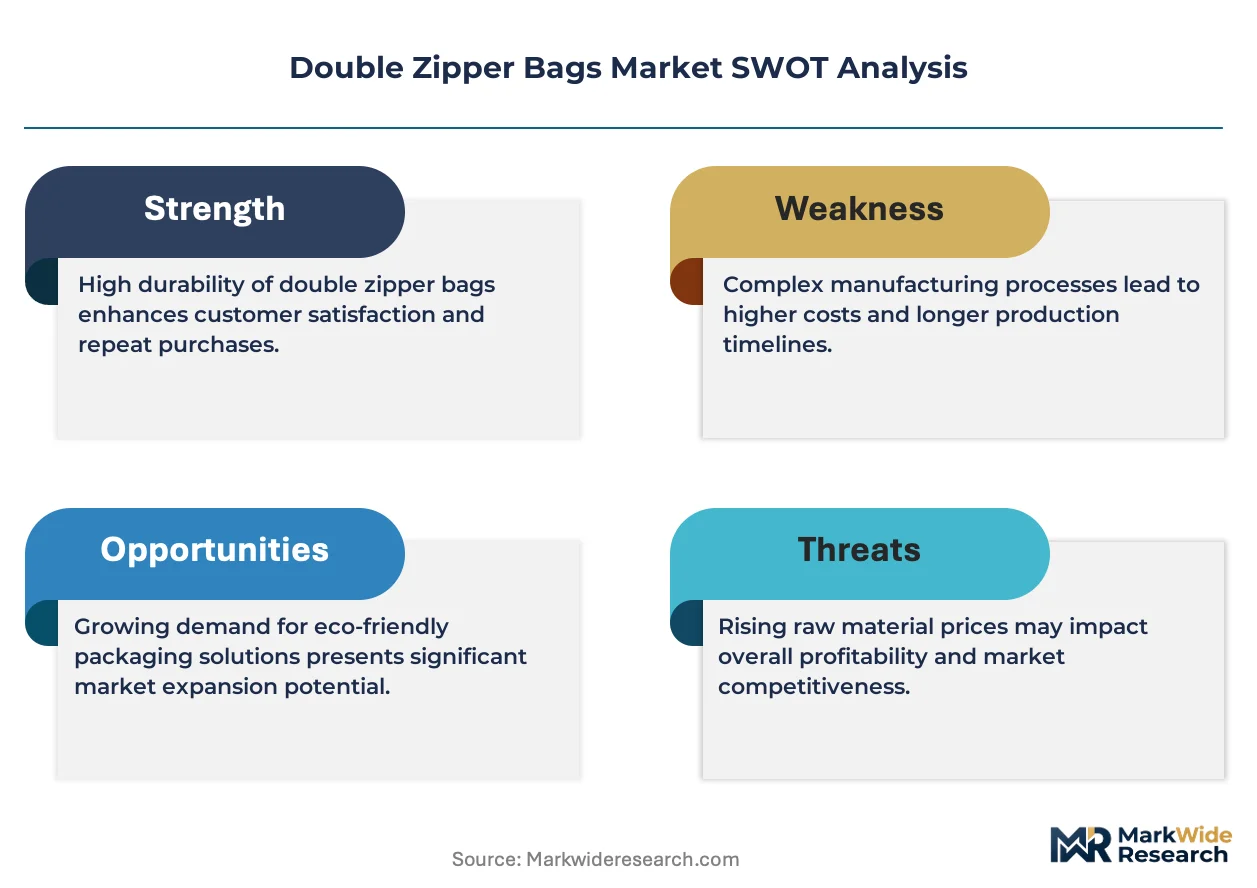
Margin expansion in double zipper bags rests on mono-material certification premiums offsetting stranded multi-layer asset write-downs, with converters capturing eco-modulation fee reductions through recyclability design.
For Market Incumbents: To counter paper-based flexible packaging substitutes in premium snack segments, Berry Global and Reynolds Consumer Products should accelerate backward integration into captive zipper track manufacturing and retrofit extrusion lines for plasma-enhanced chemical vapor deposition barrier coatings. Certification investment in RecyClass and APR protocols defends specification access to E.U. retail chains. For New Entrants and Emerging Players: FSSAI cold-chain enforcement in India opens a window for high-clarity polyethylene formulations serving temperature-sensitive pharmaceutical distribution, with Maharashtra and Gujarat industrial zones offering greenfield capacity advantages. Target food-service direct sourcing relationships in France and the United Kingdom where lot-level traceability requirements disintermediate traditional distributor channels. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale European converters with stranded multi-layer assets because mono-material retrofit costs exceed standalone valuation, creating distressed acquisition opportunities. Watch RecyClass certification timelines as inflection indicator—12-18 month validation cycles delay product launches and compress exit multiples for uncertified targets.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-material Extrusion Line Retrofit | Enables RecyClass certification access to German retail private-label programs. |
| Backward Integration into Zipper Track Manufacturing | Captures specification consistency for high-barrier chilled and frozen applications. |
| Biodegradable Resin Format Expansion | Positions converters for E.U. single-use directives and corporate sustainability mandates. |
| Direct Converter-to-Food-Service Sourcing | Consolidates procurement decisions and captures lot-level traceability premiums in France. |
| RFID-Zipper Integration Development | Creates authenticated closure solutions for pharmaceutical serialization requirements. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with film extrusion plant managers, retail category buyers, food-service procurement directors, and regulatory affairs specialists at packaging converters with secondary validation from ECHA REACH substance restriction databases, EU Packaging and Packaging Waste Regulation compliance filings, and FSSAI cold-chain enforcement circulars. Bottom-up shipment data from polyethylene resin distributors and top-down demand modeling from end-use consumption patterns were triangulated against trade flow records.
Historical reference periods anchored volume and value projections across the analysis window, with segmentation modeling across material substrate, product type, end-user channel, and geographic regulatory cluster. CAGRs were derived from fitted growth curves calibrated to disclosed capacity expansions and retrofit investment timelines. Industry-specific forecast inputs included mono-material certification adoption rates and cold-chain infrastructure investment pipelines in India and Europe.
Revisions become necessary when E.U. eco-modulation schemes alter fee structures, when REACH Annex XVII restrictions expand substance prohibitions, or when hurricane-induced resin supply disruptions exceed historical volatility bands. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Global Polypropylene Woven Bags and Sacks Market
Bags and Containers
Packaging Peanuts Market
Bags and Containers
Anti-Static Collapsible Tote Bins Market
Bags and Containers
Plastic Bags and Sacks Market
Bags and Containers
Gusseted Bags Market
Bags and Containers
Tamper Evident Bag Sealers Market
Bags and Containers
Baffle Bags Market
Bags and Containers
Side Gusset/Quad Seal Bag Market
Bags and Containers
4-Loop FIBC Market
Bags and Containers
Disposable Garbage Bags Market
Bags and Containers
Garbage Bag Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Bag Clips Market
Bags and Containers
Bin Liners Market
Bags and Containers
On the Go Packaging Market
Bags and Containers
Isothermal Bags Market