
 Bulk Bag Conditioners Market | 2026-2036
Bulk Bag Conditioners Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Bag Conditioners Market Insights
Direct-to-plant equipment procurement is tilting toward integrated system vendors with full-service capabilities. Flexicon Corporation leverages its pneumatic conveying heritage to bundle conditioning units with downstream equipment. National Bulk Equipment anchors its position through vertical integration into controls engineering and installation services. Spiroflow competes on customization depth for pharmaceutical clean-room configurations.
Bulk bag conditioners are industrial machines designed to restore flowability to compacted materials in flexible intermediate bulk containers through controlled application of mechanical force, vibration, or pneumatic pressure, typically operating at pressures between 2,000 and 10,000 pounds depending on material caking severity. Their primary purpose is to eliminate manual sledgehammer breaking or unsafe climbing practices while ensuring consistent downstream feeding to processing equipment. Hydraulic press configurations dominate margin pools in chemical manufacturing applications where extreme compaction demands heavy-duty force application. Pneumatic systems lead unit volume in food packaging lines where gentle product handling preserves particle integrity. Digital controller technology represents the fastest-advancing segment as facilities retrofit legacy conditioners with programmable logic interfaces for batch traceability.
OSHA ergonomic and machine guarding standards directly shape equipment design requirements for US installations, while FDA food contact surface regulations govern stainless steel specifications and cleanability protocols in food processing and pharmaceutical end uses. The EU Machinery Directive and CE marking requirements create compliance thresholds for European exports that condition market entry for non-certified suppliers. Stakeholders must monitor evolving automation integration standards and weigh capital deployment between standalone retrofits and fully integrated material handling lines.
Market Dynamics
Material flow assurance in powder processing now hinges on programmable logic integration, as facilities retrofit legacy hydraulic and pneumatic conditioners with batch-traceable digital controllers to meet FDA food contact documentation and OSHA ergonomic mandates.
Growth Catalysts
- OSHA Ergonomic Mandates:Workplace safety standards in the United States prohibit manual sledgehammer breaking of compacted bulk bags, forcing chemical manufacturers and food processors to deploy mechanical conditioning systems with guarded hydraulic presses.
- Pharmaceutical Clean-Room Expansion:Sterile powder handling requirements in FDA-regulated facilities drive demand for stainless steel conditioners with validated cleanability protocols and pneumatic gentle-handling configurations.
- Chemical Manufacturing Modernization:Powder processing facilities across the United States accelerate replacement cycles as legacy material handling infrastructure reaches end-of-life, creating pull-through demand for integrated conditioning and conveying systems.
Market Restraints
- Stainless Steel Input Volatility:Food-grade 316L stainless steel price fluctuations compress margin pools for manufacturers serving FDA-regulated end uses, particularly pharmaceutical and dairy processing applications.
- EU Machinery Directive Compliance Costs:CE marking requirements and conformity assessment procedures create fixed cost barriers for non-European suppliers seeking market entry, concentrating certified supply among established regional players.
- Manual Breaking Substitution:Low-cost labor markets and informal safety enforcement in select geographies perpetuate hazardous manual practices, delaying equipment adoption in price-sensitive procurement environments.
Strategic Opportunities
- Underpenetrated Food Packaging Automation:Mid-size bakeries and spice blending facilities in the United States remain reliant on manual conditioning, presenting conversion potential as pneumatic system costs decline through controller standardization.
- IRA Clean Manufacturing Incentives:Energy-efficient hydraulic system retrofits qualify for domestic production tax credits, creating procurement pull in chemical manufacturing facilities pursuing decarbonization roadmaps.
- Convergence of Vibration Sensing and Predictive Maintenance:Integration of IoT-enabled condition monitoring with legacy conditioning equipment enables service-contract revenue models and reduces unplanned downtime in continuous-process chemical plants.
Industry Challenges
- Controls Engineering Talent Scarcity:PLC programming and HMI configuration expertise required for digital controller retrofits outpaces vocational training pipeline output, extending installation timelines and inflating contractor rates.
- Legacy System Integration Complexity:Retrofitting programmable logic interfaces onto 1990s-era hydraulic conditioners demands custom mechanical adapters and proprietary communication bridges, fragmenting project scopes and escalating commissioning costs.
- FDA Validation Timeline Compression:Pharmaceutical customers require documented IQ/OQ/PQ protocols for clean-room installations, stretching sales-to-revenue cycles and consuming application engineering capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Bag Conditioners Market |
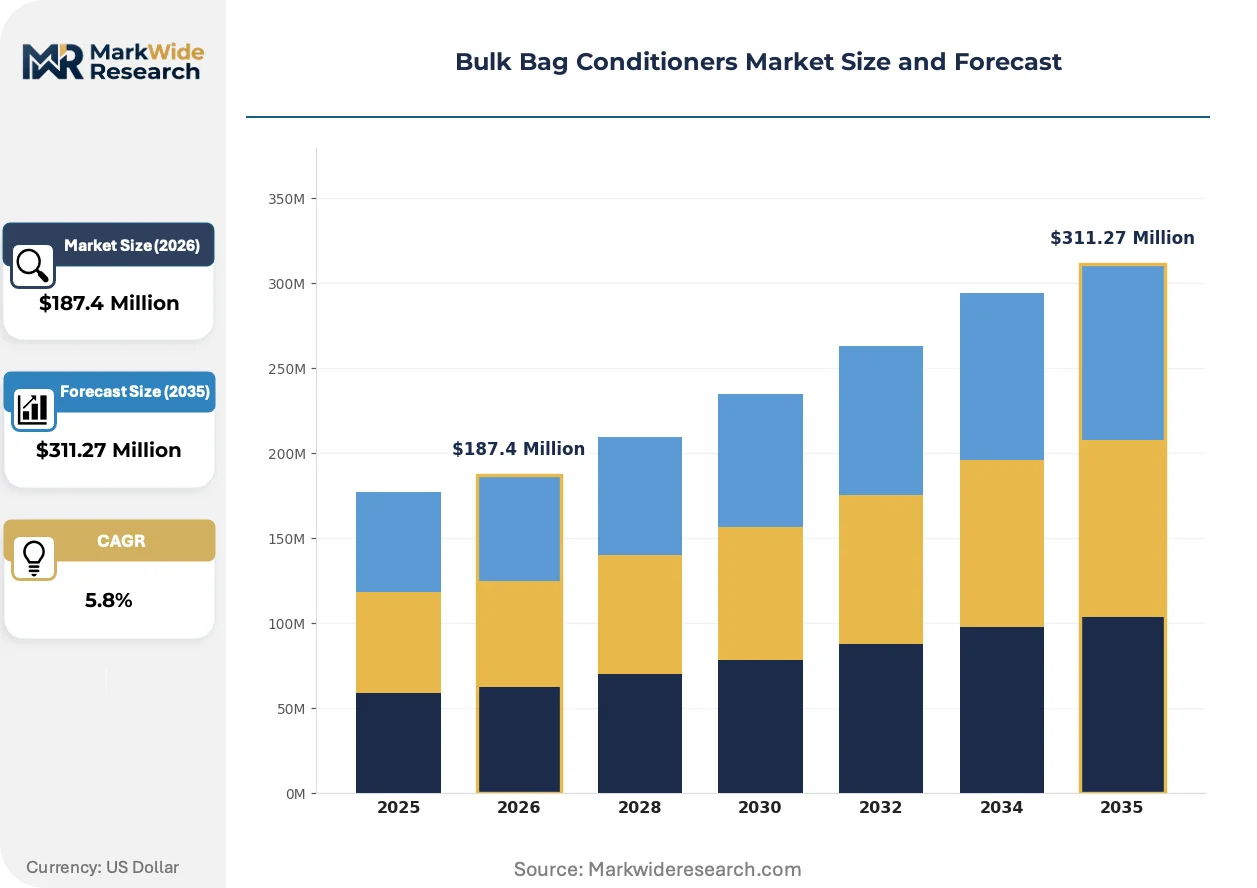
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Blowers, Vibration Plates, Hydraulic Presses, Electric Compressors Technology: Pneumatic Systems, Mechanical Arms, Automated Sensors, Digital Controllers Application: Powder Processing, Granule Handling, Chemical Manufacturing, Food Packaging End User Industry: Chemical Plants, Pharmaceutical Manufacturers, Agrochemical Producers, Food Processing Units |
| Companies Covered | Flexicon Corporation, National Bulk Equipment, Material Transfer & Storage, JMS (Jim Myers & Sons), Spiroflow, Hapman, GIMAT, Erie Technical Systems, General Kinematics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Bag Conditioners Market Trends and Innovations
Digital controller technology is compressing the competitive landscape by enabling batch traceability and remote diagnostics, while regulatory pressure on food contact surfaces and ergonomic safety accelerates specification upgrades across chemical and pharmaceutical end uses.
Programmable logic controller retrofits with integrated HMI interfaces are digitizing legacy hydraulic and pneumatic conditioners. Chemical manufacturers in the United States adopt these retrofits fastest, driven by batch documentation requirements for hazardous material handling. The technology is digitizing aftermarket service models by enabling predictive maintenance contracts and remote troubleshooting, displacing reactive break-fix arrangements.
REACH substance restrictions and EU Machinery Directive updates are tightening stainless steel surface finish specifications for European food contact applications. Industrial consequence includes mandatory 3-A Sanitary Standards compliance for exporters, elevating certification costs. Dairy and infant formula processors in Germany and France respond by consolidating procurement around vertically integrated suppliers with captive metallurgy and finishing capabilities.
Direct-to-plant equipment bundling is displacing standalone conditioner procurement as integrated system vendors capture specification authority. Chemical manufacturing facilities in Texas and Louisiana increasingly source conditioning units as downstream components of pneumatic conveying lines rather than separate capital items. Food packaging operations in California exhibit similar consolidation, preferring single-source accountability for material handling performance guarantees.
Bulk Bag Conditioners Market Segmentation
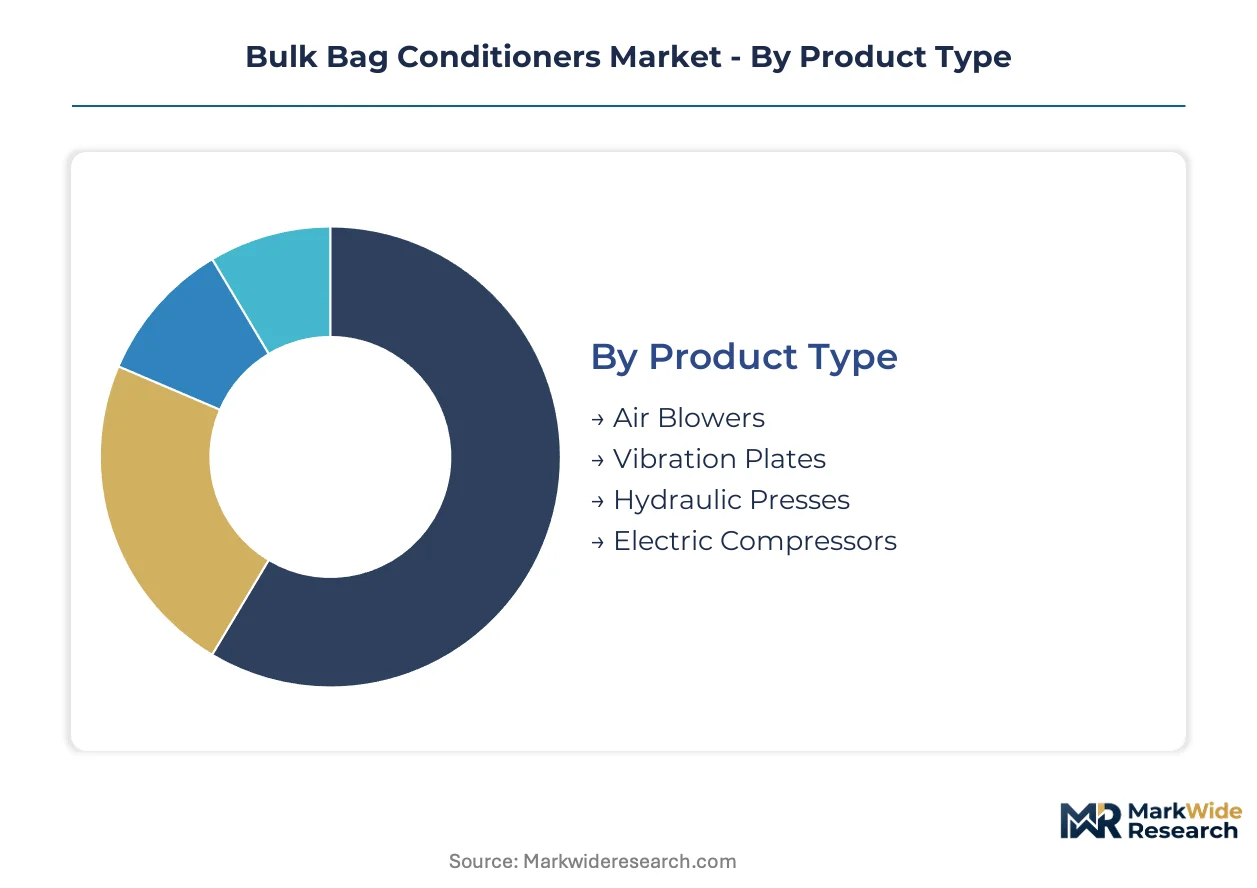
Segmentation in bulk bag conditioning equipment reveals how force application methods and control architectures align with material characteristics and regulatory environments. Procurement patterns diver sharply between heavy-duty chemical applications requiring extreme compaction force and food-grade operations prioritizing gentle handling and cleanability documentation.
Product Type:
Cost tier separates conditioning equipment into capital-intensive hydraulic configurations versus lower-unit-cost pneumatic alternatives, with stainless steel specifications adding further stratification for FDA-regulated end uses.
- Hydraulic Presses:Heavy-duty force application systems operating between 2,000 and 10,000 pounds pressure, purpose-built for severe material caking in chemical manufacturing. Demand concentrates in Texas and Louisiana petrochemical corridors where extreme compaction demands justify premium capital deployment.
- Vibration Plates:Oscillatory force systems that restore flowability without direct compression, preferred in food packaging lines where particle integrity preservation outweighs brute-force recovery. California dairy processors specify these for whey powder conditioning to maintain dissolution performance.
- Air Blowers:Pneumatic pressure systems delivering gentle material loosening through controlled air injection, common in spice blending facilities handling heat-sensitive products.
- Electric Compressors:Electromechanical force generation units offering precise pressure modulation for mid-range compaction applications in agrochemical formulation plants.
Hydraulic Presses hold installed capacity. Vibration Plates is rotating up the share rankings.
Technology:
Application context determines whether facilities prioritize mechanical reliability or digital integration, with batch traceability requirements increasingly tilting specifications toward programmable architectures.
- Digital Controllers:PLC-based control systems with integrated HMI interfaces enabling batch documentation, remote diagnostics, and predictive maintenance contracts. Chemical manufacturers in the United States adopt these fastest for hazardous material handling compliance.
- Pneumatic Systems:Compressed air-driven actuation technology delivering gentle, contamination-free force application, dominant in pharmaceutical clean-room configurations where oil-free operation is mandatory.
- Mechanical Arms:Articulated physical manipulation systems providing targeted compaction force without hydraulic fluid risk, specified in infant formula processing.
- Automated Sensors:IoT-enabled condition monitoring packages retrofitting legacy equipment with vibration analysis and predictive failure detection capabilities.
Pneumatic Systems hold installed capacity. Digital Controllers is climbing the fastest.
Application:
Volume throughput and material caking severity create distinct equipment specifications across processing contexts, with chemical operations demanding substantially higher force tolerances than food-grade alternatives.
- Chemical Manufacturing:High-severity compaction recovery in powder processing facilities handling hygroscopic or pressure-sensitive materials, where OSHA ergonomic mandates prohibit manual breaking. Gulf Coast facilities drive specification authority for integrated conditioning-conveying systems.
- Food Packaging:Gentle handling of granules and powders where particle size distribution affects downstream processing performance, governed by FDA food contact surface regulations and 3-A Sanitary Standards compliance requirements.
- Powder Processing:General-purpose material flow assurance across diverse industrial contexts, spanning pigments, minerals, and engineered polymers.
- Granule Handling:Specialized conditioning for coarse particulate materials where agglomeration rather than compaction drives flowability loss.
Chemical Manufacturing holds installed capacity. Food Packaging is gaining share fastest.
End User Industry:
Customer type determines procurement authority structures, with consolidated chemical majors favoring bundled system vendors while fragmented food processors retain standalone equipment purchasing patterns.
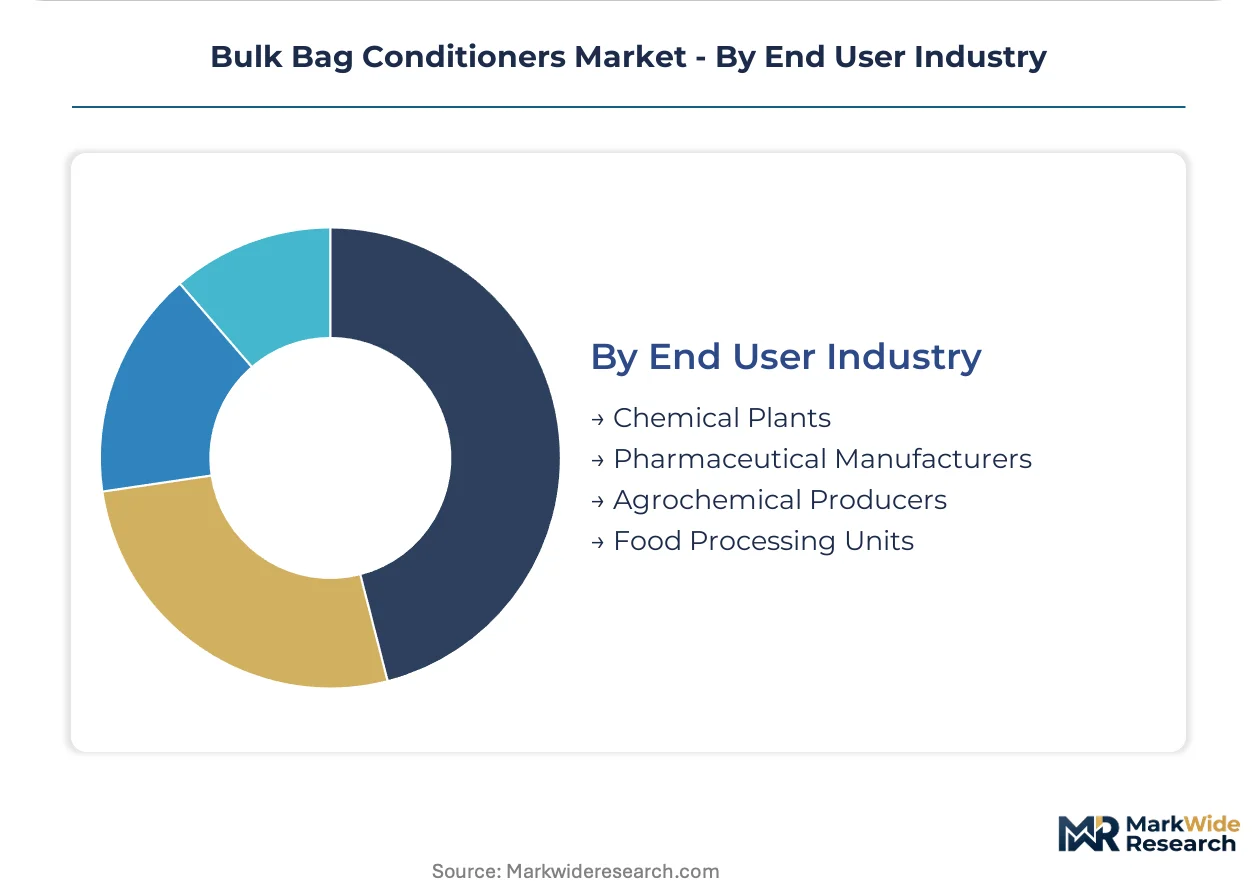
- Chemical Plants:Large-scale powder processing facilities with centralized procurement functions and established pneumatic conveying infrastructure, where conditioning equipment specifies as downstream components rather than discrete capital items.
- Pharmaceutical Manufacturers:FDA-regulated sterile powder handlers requiring validated IQ/OQ/PQ protocols, stainless steel 316L construction, and documented cleanability procedures for clean-room installations.
- Food Processing Units:Mid-size bakeries and spice blending operations with distributed procurement authority, presenting conversion potential from manual breaking as pneumatic system costs decline.
- Agrochemical Producers:Formulation plants handling fertilizer blends and crop protection powders, where seasonal demand patterns affect equipment utilization rates.
Chemical Plants hold installed capacity. Pharmaceutical Manufacturers is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
IRA clean manufacturing incentives in the United States are accelerating equipment replacement cycles across chemical processing corridors, while EU Machinery Directive compliance costs reshape competitive entry patterns in European food contact applications.
United States
OSHA ergonomic mandates prohibiting manual sledgehammer breaking drive mechanical conditioning system deployment across Texas and Louisiana petrochemical clusters. IRA domestic production tax credits for energy-efficient hydraulic retrofits create procurement pull in Gulf Coast powder processing facilities pursuing decarbonization roadmaps. Houston-area chemical plants increasingly specify conditioning units as downstream components of integrated pneumatic conveying lines rather than discrete capital purchases.
Germany
REACH substance restrictions and updated EU Machinery Directive requirements tighten stainless steel surface finish specifications for food contact equipment exports. Dairy and infant formula processors in Bavaria consolidate procurement around suppliers with captive metallurgy and finishing capabilities. Munich-region pharmaceutical clean-room installations demand validated IQ/OQ/PQ protocols and documented 316L cleanability procedures.
China
Dual carbon goals and MIIT industrial modernization directives accelerate material handling infrastructure upgrades in Yangtze River Delta chemical processing zones. GB standards compliance for food contact machinery creates certification thresholds for domestic equipment suppliers. Shanghai-area powder processing facilities retrofit legacy conditioners with programmable logic interfaces to meet batch traceability requirements for hazardous material handling.
India
PLI scheme incentives for food processing automation create conversion potential in mid-size spice blending and bakery operations historically reliant on manual breaking. FSSAI food contact surface regulations govern stainless steel specifications in dairy processing applications. Gujarat-based agrochemical formulation plants specify pneumatic gentle-handling configurations for heat-sensitive crop protection powder conditioning.
France
ANSM pharmaceutical manufacturing standards and CE marking requirements shape clean-room equipment specifications in Île-de-France sterile powder handling facilities. ECHA guidance on food contact materials elevates certification costs for conditioning system exporters. Lyon-region chemical processors adopt vibration plate configurations for hygroscopic material flow assurance without particle degradation.
Bulk Bag Conditioners Market Competitive Landscape
On the supply side, the industry is consolidating around integrated system vendors with full-service capabilities rather than standalone equipment fabricators. Three strategic archetypes dominate competitive positioning: pneumatic conveying heritage companies bundling downstream equipment, vertically integrated specialists with captive controls engineering, and customization-focused vendors serving pharmaceutical clean-room requirements. Dominant competitive moves include backward integration into installation services and technology licensing agreements for digital controller retrofits.
Within the integrated-system tier, Flexicon Corporation and National Bulk Equipment exemplify vendors leveraging pneumatic conveying heritage to capture specification authority through bundled offerings. Spiroflow occupies a position among customization-depth specialists targeting validated pharmaceutical configurations. These three anchors illustrate how competitive advantage increasingly derives from service integration breadth rather than equipment manufacturing scale alone.
| Leading Market Players |
|---|
| Flexicon Corporation |
| National Bulk Equipment |
| Material Transfer & Storage |
| JMS (Jim Myers & Sons) |
| Spiroflow |
| Hapman |
| GIMAT |
| Erie Technical Systems |
| General Kinematics |
| Others |
Pricing and Supply Chain Analysis
Chinese stainless steel 316L production concentration anchors margin distribution across hydraulic press and pneumatic system tiers, with food-grade metallurgy premiums flowing downstream to FDA-regulated pharmaceutical and dairy processors while chemical manufacturing buyers capture volume leverage through integrated system bundling.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated pharmaceutical configurations with IQ/OQ/PQ documentation from mid-range pneumatic systems and basic hydraulic units. Price differentiation hinges on FDA 21 CFR compliance certification and stainless steel surface finish grade, with chemical plant procurement teams exhibiting lowest sensitivity due to bundled conveying-line contracts while mid-size food processors face acute budget constraints. Cost compression in economy-tier pneumatic systems is intensifying because controller standardization is eroding hardware margins. Food processing units remain most price-sensitive, delaying replacement cycles when manual breaking appears viable.
Supply Chain Analysis
Contract manufacturing for digital controller assemblies concentrates in Taiwan and South Korea, with PLC module foundries feeding assembly operations in Germany and the United States. Raw material dependencies center on 316L stainless steel billets, hydraulic actuator castings, and pneumatic valve manifolds. Supply chain risk rests on single-source vulnerability for food-grade surface finishing capacity certified to 3-A Sanitary Standards. Distribution runs through OEM-direct channels for chemical plant accounts and regional equipment distributors serving fragmented food processing customers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment protects incumbent positions. FDA validation protocols and OSHA ergonomic mandates create switching costs that lock in specification authority for established system integrators.
For Market Incumbents: Insulate specification authority by backward integration into controls engineering talent pools, countering the threat of PLC programming scarcity that extends commissioning timelines. Deepen captive service capabilities in pharmaceutical clean-room validation to raise rival entry costs. Prioritize certification investment in EU Machinery Directive CE marking to forestall regional competitor expansion.
For New Entrants and Emerging Players: Pursue white-space conversion in mid-size US bakeries and spice blending facilities where pneumatic system cost declines are displacing manual breaking practices. Target the food packaging automation segment as the most penetrable vertical, leveraging controller standardization to undercut integrated system premiums. Deploy rental or lease-to-own financing as the primary go-to-market angle to overcome capital budget constraints.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed pneumatic conveying specialists holding installation service networks but lacking digital controller capabilities. Long-term viability favors vertically integrated platforms with captive metallurgy and validated pharmaceutical protocols. Watch FDA warning letter trends as the inflection signal indicating when documentation requirements will tighten further.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controls Engineering | Captive PLC programming capacity reduces commissioning delays and captures margin from scarce technical labor. |
| Pharmaceutical Validation Protocol Investment | IQ/OQ/PQ documentation capabilities lock in sterile powder handling customers under FDA 21 CFR oversight. |
| Pneumatic System Controller Standardization | Modular digital interfaces erode hardware premiums while expanding addressable market in price-sensitive food processing. |
| EU Machinery Directive CE Marking Expansion | Conformity assessment capabilities create fixed-cost barriers excluding non-certified Asian competitors from European food contact sales. |
| Predictive Maintenance Service Contracts | IoT-enabled vibration sensing converts equipment sales into recurring revenue streams with chemical plant accounts. |
Research Methodology
The analysis maps hydraulic press, pneumatic system, vibration plate, and digital controller sub-sectors, each validated through maintenance directors at chemical plants, procurement leads at pharmaceutical manufacturers, and aftermarket service heads at equipment distributors. Primary interviews with plant engineers and OEM procurement teams combined with secondary validation from OSHA enforcement databases, FDA 510(k) filings, and ACC chemical production surveys. Bottom-up equipment shipment tracking and top-down end-use industry capex analysis provided triangulation across the projection horizon.
Assumptions held fixed include OSHA ergonomic mandate enforcement intensity and FDA food contact surface regulation scope, while stainless steel input costs and automation adoption rates were varied across sensitivity scenarios. Segmentation dimensions modeled include force application method, control architecture, end-use industry, and regional regulatory cluster. CAGRs were derived from installed base replacement cycles and greenfield capacity additions, with chemical manufacturing modernization timelines and pharmaceutical clean-room expansion rates serving as key forecast inputs.
Sensitivities concentrate around stainless steel price volatility, EU Machinery Directive enforcement shifts, and manual breaking substitution persistence in low-cost labor markets. Forecasts reflect documented assumptions regarding regulatory trajectory and technology adoption curves. Cross-checking against ACC chemical industry capex surveys and FDA inspection citation databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Lunch Boxes and Lunch Bags Market
Bags and Containers
Trash Bags Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Slider Bags Market
Bags and Containers
Twin Seal Bags Market
Bags and Containers
Woven Sacks Market
Bags and Containers
Scented Trash Bags Market
Bags and Containers
Dome Shrink Basket Bags Market
Bags and Containers
Woven Bags Market
Bags and Containers
Global Household Food Storage Containers Market
Bags and Containers
Cassava Bags Market
Bags and Containers
Laminated Woven PP Bags Market
Bags and Containers
Vertical Form Fill Seal Baggers Market
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
Self-Sealing Ziplock Bags Market
Bags and Containers
Insulated Delivery Bag Market