
 Desiccant Bags Market | 2026-2036
Desiccant Bags Market Size, Share, and Industry Trends Forecast 2026-2036
Desiccant Bags Market Outlook
ISO 9001 and ISTA-certified production qualification is redrawing competitive boundaries in the desiccant bags sector. BASF SE leverages its integrated silica gel manufacturing network across European sites to sustain cost advantages in pharmaceutical-grade supply. Clariant AG anchors its position through specialized molecular sieve formulations for electronics humidity control. W. R. Grace & Co. competes on activated clay capacity, dominating bulk industrial applications with in-house mineral processing.
Desiccant bags are sealed permeable containers holding hygroscopic materials—typically silica gel, activated clay, or molecular sieves with pore diameters of 2-10 angstroms—that adsorb atmospheric moisture to maintain relative humidity below critical thresholds in enclosed packaging. Their primary purpose is protecting moisture-sensitive goods during storage and transit across pharmaceutical, electronics, and food supply chains. Silica gel occupies the largest volume share due to its cost-performance balance and FDA recognition for indirect food contact, while molecular sieves command premium positioning in electronics and lithium battery drying where ultra-low dew points are mandatory. The 1g and 5g single-use pouch formats lead pharmaceutical and consumer electronics applications, whereas 50g bulk bags and multi-use canisters serve automotive parts and industrial machinery with higher moisture loads.
FDA compliance for pharmaceutical contact materials, REACH substance restrictions in Europe, and EU MDR traceability requirements collectively elevate barrier-to-entry for new desiccant bag suppliers serving regulated industries. Japan's METI chemical substance reporting and China's GB standards for packaging materials add further compliance layers for multinational manufacturers. Stakeholders must monitor evolving pharmacopeial monographs and regional chemical registration rules to anticipate reformulation costs and qualification timelines.
Market Dynamics
EU F-Gas Regulation phase-down schedules and REACH substance restrictions are compressing fluorinated desiccant chemistries while elevating bio-based and mineral alternatives across pharmaceutical and electronics supply chains.
Growth Catalysts
- Pharmaceutical packaging expansion:Moisture-sensitive biologics and orphan drug formulations in Germany and the United States require ISO 9001-certified desiccant procurement at escalating volumes.
- REACH compliance mandates:ECHA substance restriction updates are disqualifying legacy cobalt chloride indicator desiccants, forcing reformulation toward iron-based and organic alternatives.
- Semiconductor cluster concentration:South Korean packaging facilities around Pyeongtaek and Yongin are standardizing molecular sieve specifications for lithium battery dry rooms.
Market Restraints
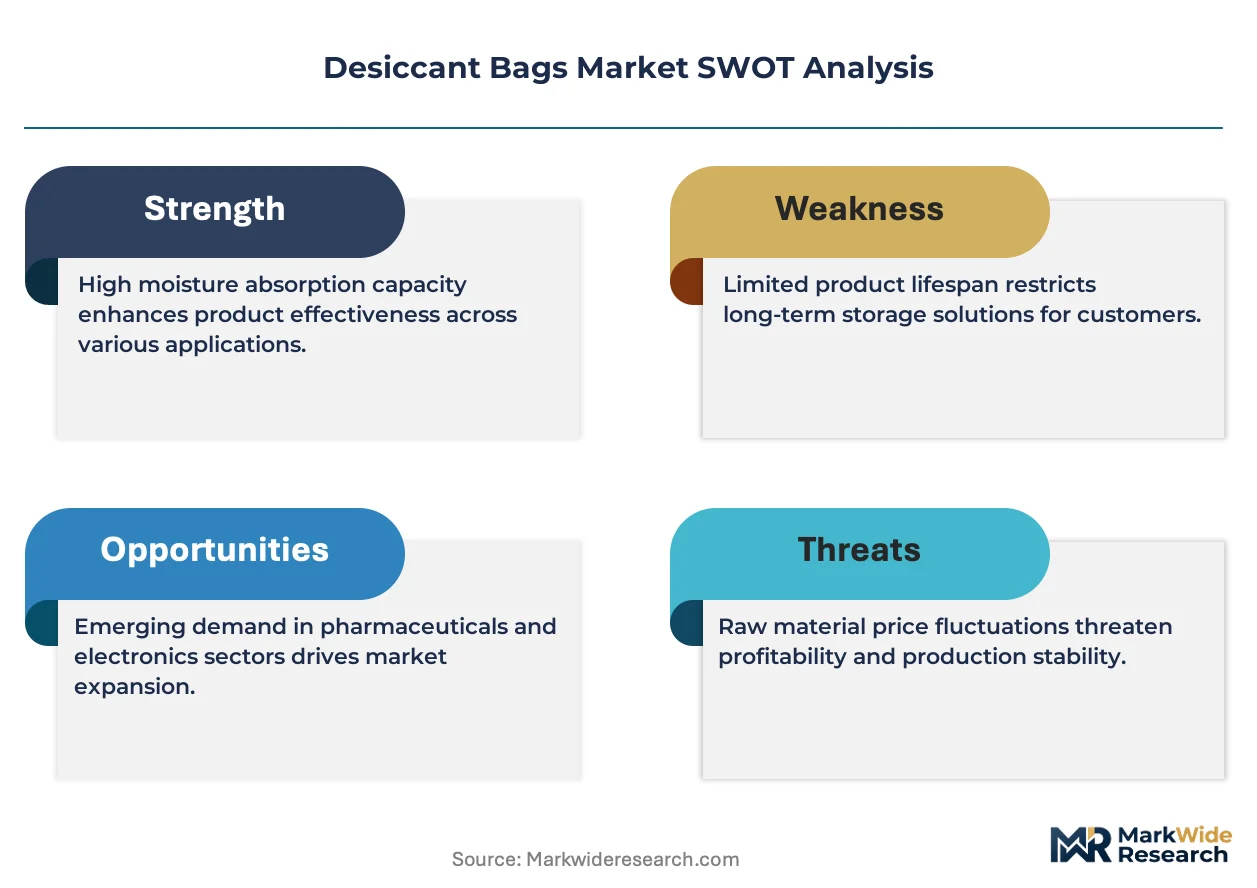
- Silica gel feedstock volatility:Sodium silicate and sulfuric acid input costs fluctuate with energy pricing in European and Chinese production basins.
- Activated bauxite supply concentration:High-purity clay deposits for pharmaceutical-grade desiccants concentrate in southeastern United States and select Caribbean extraction sites.
- Technical performance ceiling:Conventional silica gel achieves 35-40% equilibrium moisture capacity at 25°C/80% RH, constraining ultra-low dew point applications below -40°C.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO bulk drug park incentives and PLI scheme extensions are attracting desiccant qualification programs for export-oriented packaging.
- Cellular agriculture packaging:Cultured meat and precision fermentation products require novel humidity control protocols without traditional oxygen scavenger interference.
- EU MDR traceability mandates:Unique device identification requirements for medical device packaging create specification lock-in for qualified desiccant suppliers.
Industry Challenges
- ISTA certification timelines:Transit simulation qualification for pharmaceutical desiccant configurations extends 18-24 months, compressing product launch windows.
- Cross-contamination protocols:Electronics-grade molecular sieve production requires dedicated production lines segregated from industrial clay processing, elevating capital intensity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Desiccant Bags Market |
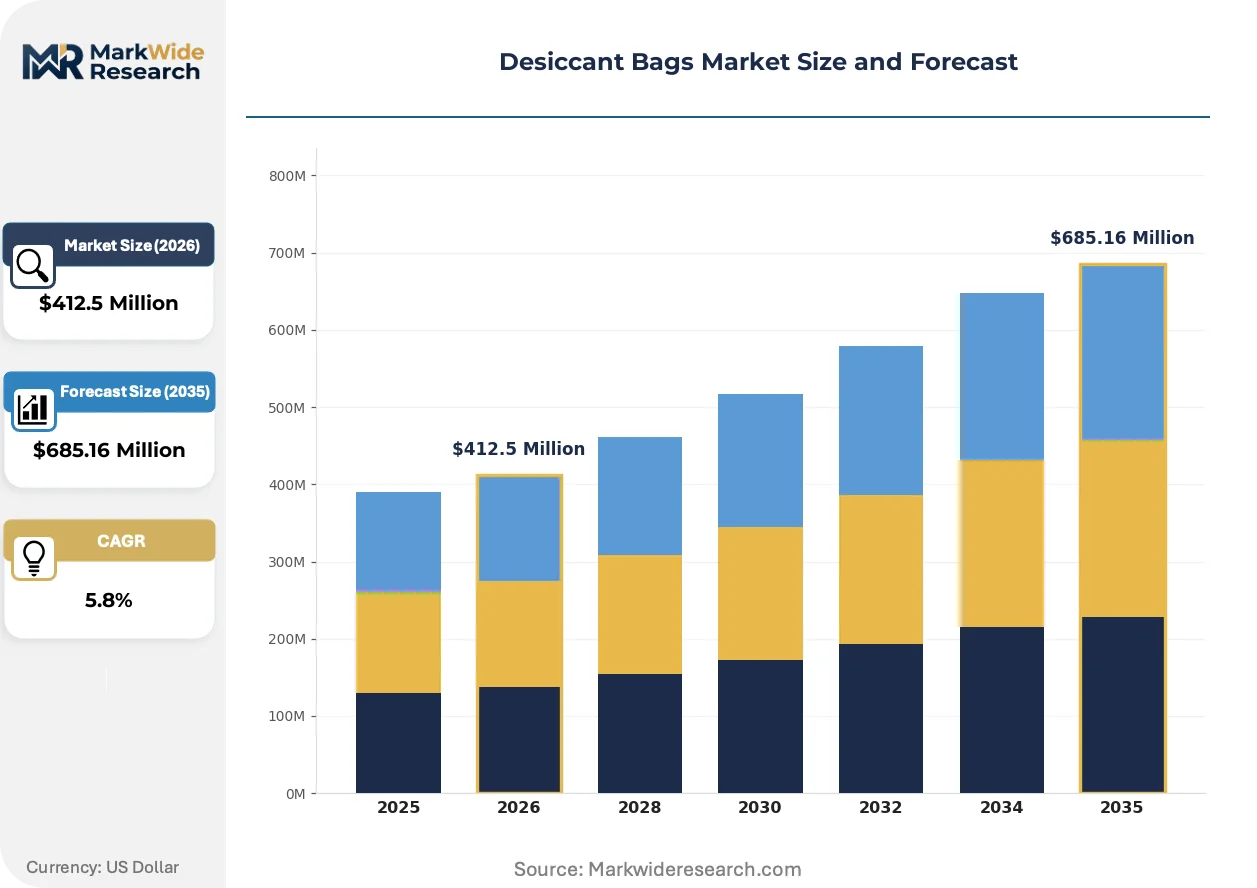
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica Gel, Activated Clay, Molecular Sieves, Calcium Sulfate End Use Industry: Pharmaceuticals, Electronics, Food & Beverage, Automotive Size: 1g, 5g, 10g, 50g Packaging Type: Single-use Pouches, Multi-use Canisters, Bulk Bags, Custom Packs |
| Companies Covered | BASF SE, Clariant AG, W. R. Grace & Co., Multisorb Technologies, Evonik Industries, CSP Technologies, Sanner GmbH, Honeywell International Inc., Tropack Packmittel GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Desiccant Bags Market Strategic Shifts
Active desiccant systems with humidity-indicating intelligence and regenerable formats are displacing passive single-use pouches in high-value pharmaceutical and aerospace logistics.
Biodegradable desiccant substrates derived from agricultural waste streams are decomposing petroleum-based polymer pouch constructions. European pharmaceutical contract packagers in the Netherlands and Denmark are piloting cellulose-fiber and seaweed-derived formats for orphan drug shipments. This materials transition is decomposing incumbent polypropylene nonwoven supply relationships and forcing film converter partnerships with bio-polymer specialists.
EU F-Gas Regulation Annex III restrictions on hydrofluorocarbon propellants are cascading into desiccant canister manufacturing. Aerosol-dispensed activated desiccants for industrial equipment preservation face reformulation toward compressed CO2 or mechanical pump systems. German automotive suppliers are accelerating qualification of fluorine-free desiccant deployment tools ahead of 2030 phase-down milestones.
Consolidated procurement through pharmaceutical contract manufacturing organizations is compressing direct supplier relationships. Large molecule drug packagers in Massachusetts and North Carolina are mandating vendor-managed inventory programs with electronic data interchange integration. This purchasing consolidation is most visible in United States biologics corridors, where three contract packagers control desiccant specification authority for approximately sixty percent of new molecular entity launches.
Desiccant Bags Market Segmentation
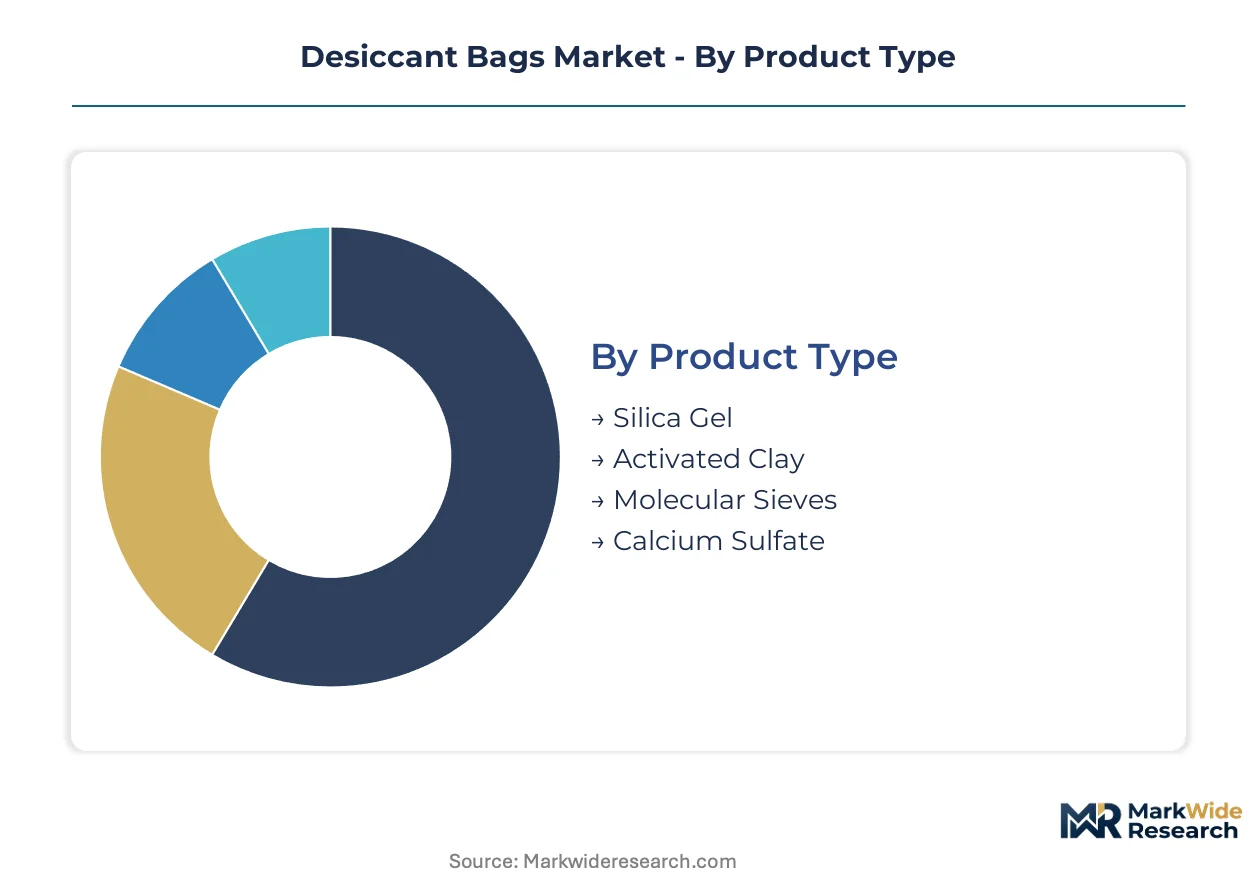
Desiccant bag segmentation reveals how material chemistry, application criticality, and packaging format interact to determine procurement specifications. Pharmaceutical and electronics end-users impose divergent performance thresholds that fragment supplier qualification pathways across product categories.
Product Type:
Silica gel faces substitution pressure from bio-based alternatives under REACH substance restrictions, while molecular sieves defend their position through irreplaceable ultra-low dew point performance.
- Silica Gel:Amorphous silicon dioxide with 2-4 nanometer pore structures delivers 35-40% moisture adsorption capacity at ambient conditions. Pharmaceutical packagers in Germany and the United States specify FDA-recognized grades for solid oral dosage protection, though ECHA cobalt chloride indicator bans are forcing indicator chemistry reformulation toward iron-based alternatives.
- Molecular Sieves:Synthetic zeolites with precisely calibrated 3A, 4A, and 13X pore diameters achieve dew points below -40°C required for lithium battery dry rooms. South Korean semiconductor packaging facilities around Pyeongtaek standardize 4A specifications for moisture-sensitive die attach processes, locking in premium positioning despite higher unit costs versus silica gel.
- Activated Clay:Montmorillonite-based mineral sorbent offers intermediate capacity at lower price points for industrial machinery preservation.
- Calcium Sulfate:Anhydrous gypsum chemistry serves niche applications requiring rapid initial adsorption kinetics.
Silica gel retains volume leadership; molecular sieves hold the steepest expansion curve.
End Use Industry:
Cost tier stratification separates validated pharmaceutical supply from price-sensitive automotive bulk procurement.
- Pharmaceuticals:Biologics and orphan drug formulations in Massachusetts and North Carolina corridors mandate ISO 9001 and ISTA-certified desiccant configurations with 18-24 month qualification timelines. EU MDR traceability requirements create specification lock-in for qualified suppliers serving medical device packaging.
- Electronics:Lithium battery manufacturing and semiconductor packaging drive molecular sieve adoption for ultra-low humidity environments. South Korean and German electronics clusters specify dedicated production lines segregated from industrial clay processing to prevent cross-contamination.
- Food & Beverage:FDA indirect food contact recognition for silica gel supports moisture control in nutritional supplements and dried goods.
- Automotive:German OEMs accelerate fluorine-free desiccant deployment tool qualification ahead of EU F-Gas Regulation phase-down milestones.
Pharmaceuticals command premium pricing tiers; electronics applications are expanding most quickly.
Size:
Volume scale separates consumer-facing unit doses from industrial moisture load management.
- 1g:Single-unit pharmaceutical blister packs and consumer electronics accessories.
- 5g:Standard format for pharmaceutical bottles and mid-size electronic device boxes.
- 10g:Intermediate capacity for multi-unit pharmaceutical shipments and precision instruments.
- 50g:Bulk format dominates automotive parts and industrial machinery with higher moisture loads; vendor-managed inventory programs concentrate procurement through contract packagers.
5g formats retain shipment frequency leadership; 50g applications gain share fastest through automotive consolidation.
Packaging Type:
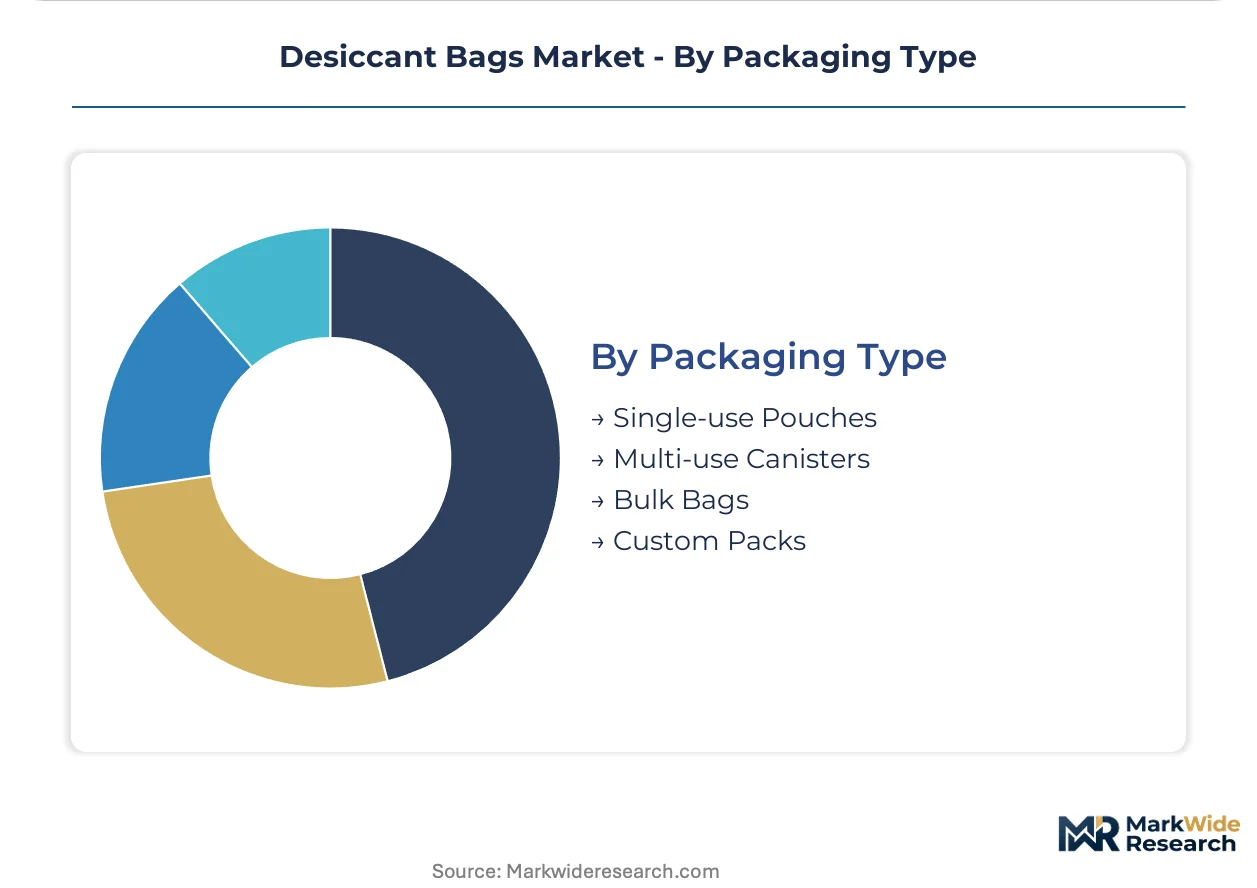
Customer type bifurcation separates one-time pharmaceutical use from regenerable industrial systems.
- Single-use Pouches:Tyvek and medical-grade nonwoven constructions dominate pharmaceutical and consumer electronics. European contract packagers in the Netherlands and Denmark pilot cellulose-fiber and seaweed-derived biodegradable substrates.
- Multi-use Canisters:Regenerable formats with humidity-indicating intelligence displace passive pouches in high-value aerospace and pharmaceutical logistics.
- Bulk Bags:50g and larger formats serve automotive and industrial machinery with standardized moisture protection protocols.
- Custom Packs:Tailored configurations integrate desiccant with oxygen scavengers for cellular agriculture and cultured meat applications.
Single-use pouches retain volume leadership; multi-use canisters hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical contract packagers and semiconductor manufacturers concentrate procurement authority in three distinct geographic corridors. German automotive suppliers and South Korean battery producers anchor molecular sieve demand, while United States biologics corridors standardize vendor-managed inventory programs.
United States
Massachusetts and North Carolina biologics corridors mandate ISO 9001-certified desiccant configurations with 18-24 month ISTA qualification timelines. FDA indirect food contact recognition for silica gel supports nutritional supplement packaging expansion. Three contract packagers in the Boston-Cambridge cluster control specification authority for approximately sixty percent of new molecular entity launches.
Germany
Automotive OEMs in Bavaria and Baden-Württemberg accelerate fluorine-free desiccant deployment tool qualification ahead of EU F-Gas Regulation phase-down milestones. ECHA substance restrictions disqualify legacy cobalt chloride indicator chemistries, forcing iron-based reformulation. BASF SE leverages integrated silica gel manufacturing across Ludwigshafen and Antwerp sites to sustain pharmaceutical-grade supply advantages.
South Korea
Semiconductor packaging facilities around Pyeongtaek and Yongin standardize 4A molecular sieve specifications for lithium battery dry rooms. MFDS pharmaceutical packaging material registrations add compliance layers for export-oriented drug manufacturers. Samsung SDI and LG Energy Solution procurement teams lock in dedicated production line requirements to prevent cross-contamination from industrial clay processing.
India
CDSCO bulk drug park incentives and PLI scheme extensions attract desiccant qualification programs for export-oriented pharmaceutical packaging. Maharashtra and Gujarat formulation hubs require REACH-compliant silica gel for European-bound shipments. Domestic molecular sieve production remains underdeveloped, creating import dependency for electronics-grade specifications.
China
GB standards for packaging materials and NMPA pharmaceutical container regulations elevate barrier-to-entry for multinational desiccant suppliers. Yangtze River Delta electronics manufacturers specify molecular sieves for lithium battery cell assembly. Sodium silicate feedstock volatility in Shandong and Jiangsu production basins compresses silica gel margin structures.
Desiccant Bags Market Competitive Environment
Player mix skews toward diversified chemical conglomerates with captive mineral processing capabilities. BASF SE and Evonik Industries anchor the integrated materials tier, while Clariant AG and CSP Technologies occupy specialized formulation positions. Strategic archetypes separate upstream mineral processors from downstream packaging converters and application-specific formulators. Competitive moves concentrate on backward integration into high-purity clay deposits and dedicated production line segregation for electronics-grade molecular sieves.
Within the integrated chemical tier, BASF SE and Evonik Industries exemplify upstream control over sodium silicate and synthetic zeolite feedstocks. Clariant AG occupies a specialist position through molecular sieve formulation expertise. W. R. Grace & Co. anchors the mineral processing archetype with activated clay capacity for bulk industrial applications. Sanner GmbH and Tropack Packmittel GmbH represent German mid-cap fabricators focused on pharmaceutical and industrial packaging formats respectively.
| Leading Market Players |
|---|
| BASF SE |
| Clariant AG |
| W. R. Grace & Co. |
| Multisorb Technologies |
| Evonik Industries |
| CSP Technologies |
| Sanner GmbH |
| Honeywell International Inc. |
| Tropack Packmittel GmbH |
| Others |
Value Chain & Pricing Dynamics
Iron-based indicator chemistry replacing cobalt chloride under ECHA restrictions simultaneously shifts procurement toward German and United States mineral processors while compressing margin structures for legacy reformulators. This substitution dynamic redraws supply geography toward REACH-compliant production basins and forces pricing recalibration across pharmaceutical-grade tiers.
Pricing Analysis
Cost-plus contracts with sodium silicate and sulfuric acid indexation dominate silica gel procurement. Three-tier pricing structure across pharmaceutical-grade, electronics-grade, and industrial-grade certifications separates ISO 9001-qualified supply from bulk automotive procurement. Pricing pressure stems from energy-linked feedstock volatility in European and Chinese production basins. Automotive buyers exhibit highest price sensitivity; biologics packagers accept premium tiers for ISTA-certified configurations.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for molecular sieve imports into South Korean semiconductor clusters. Supply concentrates in Germany for pharmaceutical-grade silica gel, China for sodium silicate feedstock, and the United States for activated bauxite extraction. Raw material dependencies span high-purity clay deposits, synthetic zeolite precursors, and medical-grade nonwoven substrates. Single-source vulnerability concentrates in southeastern United States clay extraction. Distribution runs through pharmaceutical contract manufacturing organizations with vendor-managed inventory programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Desiccant bag procurement is approaching a platform-economics inflection as vendor-managed inventory programs with electronic data interchange integration lock in specification authority among three United States contract packagers.
For Market Incumbents: Secure dedicated production line segregation for electronics-grade molecular sieves to prevent cross-contamination from industrial clay processing. Lock in backward integration into high-purity activated bauxite deposits in the southeastern United States before CDSCO bulk drug park incentives attract competing qualification programs. Certification investment in ISO 9001 and ISTA standards defends position against emerging bio-based substrate specialists. For New Entrants and Emerging Players: Anchor in India's Maharashtra and Gujarat formulation hubs where domestic molecular sieve production remains underdeveloped and import dependency creates white-space for electronics-grade specifications. Target cellular agriculture packaging applications requiring novel humidity control protocols without oxygen scavenger interference. Pursue partnership pathways with European contract packagers piloting cellulose-fiber and seaweed-derived biodegradable substrates. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed pharmaceutical packaging converters seeking exit liquidity after EU MDR traceability mandate implementation. Five-to-ten year viability hinges on qualification timeline compression and bio-based material transition execution. Monitor MFDS pharmaceutical packaging material registration acceleration as inflection signal for South Korean market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Clay Deposits | Captive supply of activated bauxite insulates margin structures from southeastern United States extraction concentration. |
| Dedicated Production Line Segregation | Electronics-grade molecular sieve qualification unlocks Samsung SDI and LG Energy Solution procurement specifications. |
| Bio-Based Substrate Partnership | Cellulose-fiber and seaweed-derived formats align with Netherlands and Denmark contract packager sustainability mandates. |
| Vendor-Managed Inventory Program Expansion | Electronic data interchange integration secures specification authority with Massachusetts and North Carolina biologics packagers. |
| Fluorine-Free Deployment Tool Qualification | German automotive OEM readiness for EU F-Gas Regulation phase-down milestones creates first-mover advantage. |
Study Parameters
A spread of perspectives from pharmaceutical packaging engineers, electronics manufacturing procurement leads, chemical plant operations managers, and desiccant substrate R&D directors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews across German automotive suppliers, South Korean semiconductor facilities, and United States biologics corridors with secondary validation from ECHA substance restriction updates, FDA pharmaceutical container guidance, and customs trade data for sodium silicate and synthetic zeolite flows. Bottom-up capacity modeling and top-down demand aggregation triangulated volume estimates.
Segmentation dimensions modeled include material chemistry tier, end-use industry criticality, packaging format scale, and regional regulatory cluster across the projection horizon. CAGRs derived from regression analysis of historical procurement volumes against pharmaceutical NME launch counts and lithium battery cell production expansion. Industry-specific forecast inputs encompass ISTA certification pipeline timelines and EU F-Gas Regulation phase-down implementation schedules.
Underlying assumptions cover sustained REACH compliance enforcement and South Korean semiconductor cluster concentration, with deviation risk concentrated in sodium silicate feedstock energy pricing volatility and CDSCO bulk drug park incentive acceleration. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Zipper Bags Market
Bags and Containers
Bulk Bag Conditioners Market
Bags and Containers
Piping Bags Market
Bags and Containers
Breather Bags Market
Bags and Containers
Bulk Bags Market
Bags and Containers
Bag-In-Box Packaging Market
Bags and Containers
Silicone Storage Bags Market
Bags and Containers
Twisted Handle Bags Market
Bags and Containers
Leno Bags Market
Bags and Containers
Vacuum Shrink Bags Market
Bags and Containers
Flip Lip Bags Market
Bags and Containers
Loose-Fill Peanuts Market
Bags and Containers
Drink Carrier Poly Bags Market
Bags and Containers
Bag in Drum Market
Bags and Containers
Non-Barrier Bag Market
Bags and Containers
Net Bags Market