
 Corrugated Pallets Market | 2026-2036
Corrugated Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Corrugated Pallets Market Analysis
ISPM-15-compliant specification-tier upgrades is unwinding traditional wooden pallet dominance across export corridors. Smurfit Kappa leverages its integrated containerboard-to-converted-products chain to control raw material flows for corrugated pallet production. DS Smith specializes in closed-loop recycling systems that anchor its supply security across European pharmaceutical distribution networks.
Corrugated pallets are engineered from multi-layered Kraft linerboard and fluted medium, typically achieving dynamic load capacities between 500 kg and 1,500 kg through adhesive-bonded cellular structures. They serve as lightweight, recyclable shipping platforms that eliminate fumigation requirements in cross-border trade. Foldable designs lead volume penetration in retail consolidation centers where cube utilization governs freight economics, while die-cut configurations capture premium positioning in electronics export packaging. Custom specifications for pharmaceutical cold-chain transit represent the fastest-growing margin pool, driven by lot-level traceability and moisture-barrier integration demands.
EPA guidelines on sustainable materials management and the EU Packaging and Packaging Waste Regulation shape converter investment priorities by mandating recyclability thresholds and extended producer responsibility frameworks. FDA facility sanitation standards for pharmaceutical logistics indirectly favor corrugated pallets in clean-room-adjacent storage environments. Stakeholders must monitor how California's SB 54 implementation and parallel state-level extended producer responsibility laws reshape fiber sourcing and post-consumer content requirements across North American supply chains.
Market Dynamics
ISPM-15 exemption status is compressing wooden pallet dominance across pharmaceutical and automotive export corridors, redirecting procurement toward fiber-based platforms that eliminate fumigation delays and customs detention risk.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability thresholds force converters to prioritize fiber-based alternatives over plastic and wood composites in cross-border logistics.
- Pharmaceutical cold-chain expansion:Lot-level serialization requirements and temperature-integrity mandates drive adoption of moisture-barrier integrated corrugated platforms for biologics distribution.
- German automotive exporter concentration:Lightweight shipping platform demand from BMW, Mercedes-Benz, and chemical shippers accelerates ISPM-15-exempt pallet procurement for transatlantic freight.
Market Restraints
- OCC price volatility:Old corrugated container feedstock cost swings compress converter margins and destabilize contract pricing for multi-year supply agreements.
- Moisture sensitivity threshold:Kraft linerboard structural degradation above 85% relative humidity limits outdoor storage duration and restricts yard logistics applications.
- Plastic pallet substitution:HDPE and PP injection-molded platforms with 10-year lifespans capture closed-loop pool rental markets where washability dominates total cost of ownership calculations.
Strategic Opportunities
- India pharmaceutical manufacturing:CDSCO serialization mandates and expanding biologics output create first-mover advantage for ISPM-15-exempt export pallet suppliers.
- RFID-NFC integration:Embedded sensor convergence with corrugated substrates enables real-time location and condition monitoring for high-value pharmaceutical shipments.
- California SB 54 implementation:Extended producer responsibility fiber sourcing requirements reshape North American supply chains toward post-consumer content verification systems.
Industry Challenges
- Structural engineer scarcity:Adhesive-bonded cellular design expertise sits concentrated among legacy paperboard engineers, constraining rapid specification scaling.
- ISPM-15 certification backlog:Third-party heat-treatment verification delays for hybrid fiber-wood designs extend product launch timelines by 4-8 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Corrugated Pallets Market |
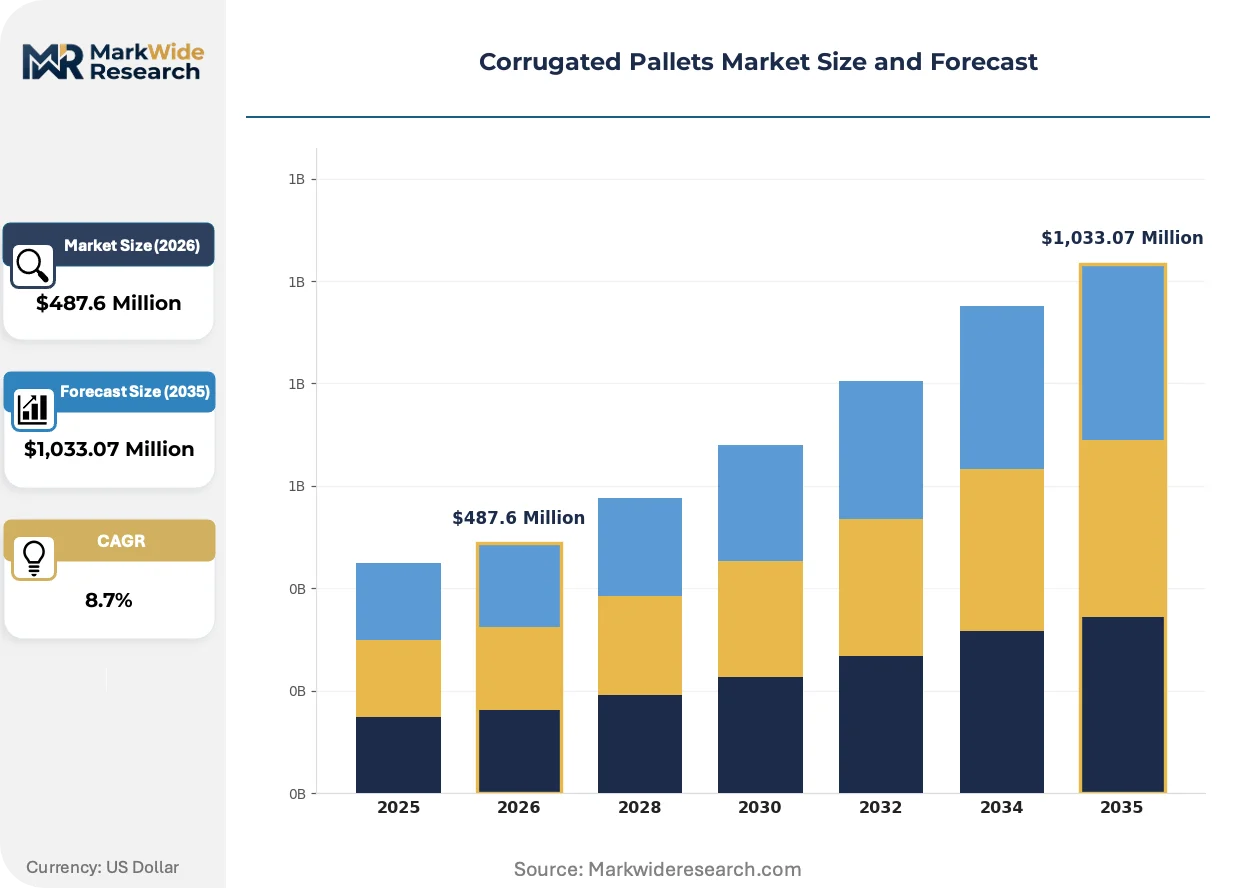
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Die-Cut, Foldable, Custom, Standard End User: Food & Beverage, Pharmaceuticals, Electronics, Retail Distribution Channel: Online, Offline, Direct Sales, Wholesale Application: Export, Storage, Transit, Display |
| Companies Covered | Smurfit Kappa, International Paper, DS Smith, Mondi Group, WestRock, Georgia-Pacific, Pratt Industries, KraftPal Technologies, Conitex Sonoco, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Corrugated Pallets Market Emerging Trajectories
Active material science advancement and regulatory serialization mandates are compressing traditional pallet procurement cycles while elevating performance specifications for cross-border pharmaceutical logistics.
Honeycomb-cored Kraft linerboard constructions are decomposing conventional triple-wall corrugated dominance in heavy-load pharmaceutical applications. Cold-chain distributors in Germany and Switzerland are specifying these platforms for 1,000 kg+ biologics shipments. The technology is decomposing price premiums previously captured by plastic composite alternatives through comparable dynamic load capacity at 40% lower unit weight.
REACH chemical restriction updates are eliminating certain adhesive chemistries previously standard in moisture-resistant corrugated bonding. European converters are reformulating starch-based and bio-derived alternatives to maintain structural integrity under cold-chain condensation exposure. Pharmaceutical logistics operators in the Netherlands and Belgium are accelerating supplier qualification timelines to secure compliant material streams ahead of enforcement deadlines.
Consolidated buying by third-party logistics providers is compressing supplier fragmentation in European pharmaceutical distribution. DHL Supply Chain and Kuehne+Nagel are standardizing corrugated pallet specifications across their Benelux and German hub networks. This concentration is most visible in the Rotterdam-Antwerp pharmaceutical corridor, where pooled procurement now governs 60% of outbound pallet volume.
Corrugated Pallets Market Segmentation
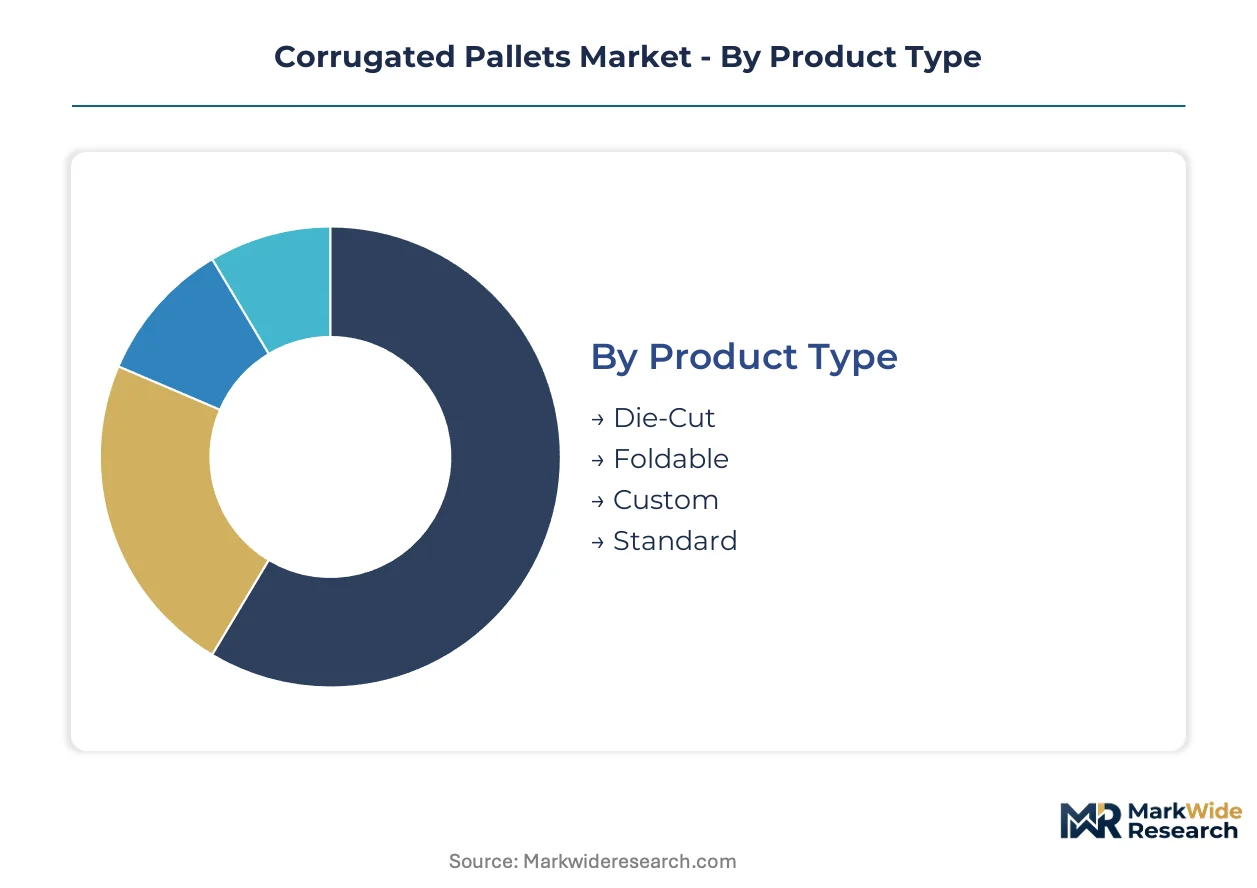
Corrugated pallet procurement patterns diverge sharply across product configurations and end-use requirements, with pharmaceutical serialization mandates and automotive lightweighting targets creating distinct margin architectures. Understanding segment-level demand drivers enables suppliers to align specification investments with the highest-value application corridors.
Product Type:
Margin pools concentrate in pharmaceutical cold-chain specifications where moisture-barrier integration and lot-level traceability command price premiums over standard industrial formats.
- Die-Cut:Precision-engineered from single-sheet Kraft linerboard with interlocking tabs, eliminating adhesive joints. Electronics exporters in Germany and the Netherlands specify these platforms for high-value component shipments where dimensional tolerance prevents transit damage. REACH-compliant adhesive alternatives are reformulating bonding chemistries to maintain structural integrity under condensation exposure.
- Foldable:Collapsible designs reduce return freight volume by 75% in retail consolidation networks. DHL Supply Chain and Kuehne+Nagel standardize these specifications across Benelux pharmaceutical hubs where cube utilization governs total logistics cost. The format captures pooled procurement contracts that now govern 60% of outbound pallet volume in the Rotterdam-Antwerp corridor.
- Custom:Engineered for biologics distribution with integrated RFID-NFC tracking and temperature-monitoring substrates. CDSCO serialization mandates in India are accelerating qualification timelines for ISPM-15-exempt export platforms.
- Standard:Triple-wall corrugated constructions serving general industrial freight where cost minimization outweighs performance specialization. Automotive tier suppliers in Germany deploy these for intra-European component shuttles.
The dominant share belongs to Foldable, while Custom is closing the gap fastest on pharmaceutical cold-chain expansion.
End User:
Application intensity varies by sector-specific regulatory exposure and total cost of ownership sensitivity, with serialization mandates and hygiene standards filtering procurement toward fiber-based platforms.
- Pharmaceuticals:Lot-level traceability requirements and FDA facility sanitation standards favor corrugated pallets in clean-room-adjacent storage. Biologics distributors in Switzerland specify honeycomb-cored constructions for 1,000 kg+ cold-chain shipments, achieving comparable dynamic load capacity to plastic composites at 40% lower unit weight.
- Food & Beverage:Moisture sensitivity above 85% relative humidity limits outdoor yard storage, pushing adoption toward indoor consolidation centers. EU Packaging and Packaging Waste Regulation recyclability thresholds accelerate fiber-based procurement over plastic alternatives.
- Electronics:Static-dissipative coatings and precision die-cutting protect high-value components from transit shock. Export corridors from Germany to North America favor ISPM-15-exempt formats that eliminate customs detention risk.
- Retail:Foldable configurations dominate store-back consolidation where return logistics economics determine platform selection. California SB 54 extended producer responsibility requirements are reshaping fiber sourcing verification for North American retail networks.
Pharmaceuticals commands the highest margin per unit, though Food & Beverage generates the largest aggregate volume base.
Distribution Channel:
Channel economics reflect buyer scale and specification complexity, with integrated converters capturing value through captive supply chain control.
- Direct Sales:Large pharmaceutical logistics operators negotiate multi-year supply agreements with converters controlling integrated containerboard-to-converted-products chains. Smurfit Kappa leverages this structure to stabilize raw material flows for corrugated pallet production.
- Wholesale:Distributors aggregate demand from mid-tier automotive and chemical shippers, absorbing OCC price volatility through inventory positioning. German automotive exporters BMW and Mercedes-Benz source through this channel for transatlantic freight platforms.
- Online:Digital procurement platforms serve small-batch pharmaceutical and electronics exporters requiring rapid specification turnaround. CDSCO compliance documentation streams through these channels for Indian biologics manufacturers.
- Offline:Traditional converter relationships persist in mature European markets where legacy paperboard engineering expertise concentrates specification development.
Direct Sales captures the premium tier, while Online is expanding most quickly among emerging market exporters.
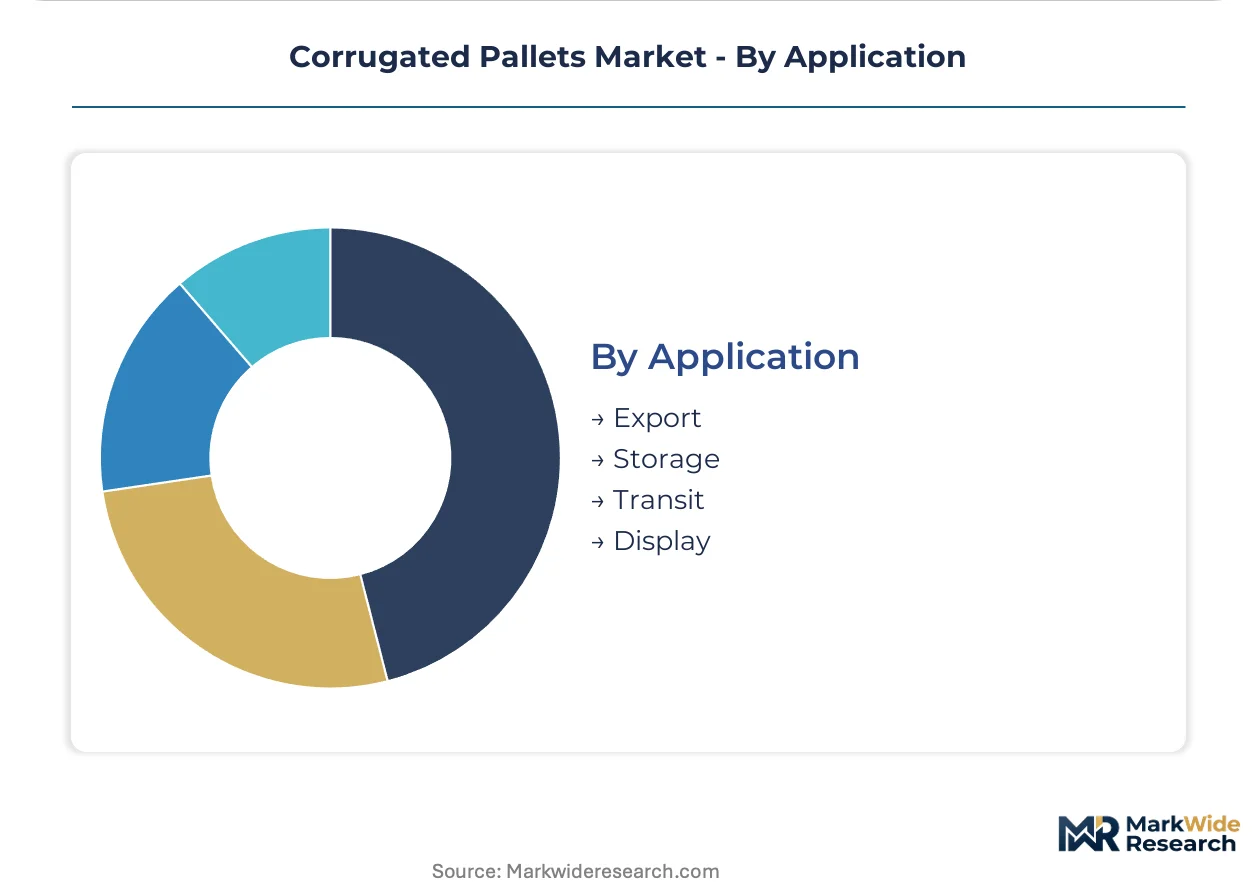
Application:
Use-case requirements determine structural engineering priorities, with cross-border regulatory exposure elevating ISPM-15 exemption status as a procurement filter.
- Export:ISPM-15-exempt status eliminates fumigation delays and customs detention risk in transatlantic and intra-European corridors. German chemical shippers specify lightweight fiber platforms to meet carrier weight restrictions while maintaining load integrity.
- Storage:Static load capacity and stackability govern warehouse efficiency in pharmaceutical distribution centers. Moisture-barrier specifications extend outdoor storage duration in humid climates.
- Transit:Dynamic load ratings between 500 kg and 1,500 kg accommodate varied freight profiles. Honeycomb-cored designs are displacing conventional triple-wall dominance in heavy-load pharmaceutical applications.
- Display:Retail-ready aesthetics and rapid assembly characterize point-of-sale applications where brand presentation merges with logistics function.
Export maintains the largest revenue share, though Transit is gaining ground fastest on cold-chain network expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances between major manufacturing hubs and consumption centers are reshaping corrugated pallet procurement patterns. Germany's automotive and chemical sectors drive transatlantic demand for ISPM-15-exempt platforms, while India's pharmaceutical expansion creates new sourcing corridors for serialization-compliant formats.
Germany
BMW and Mercedes-Benz procurement teams specify lightweight fiber platforms for transatlantic component shipments. The EU Packaging and Packaging Waste Regulation mandates recyclability thresholds that favor converter investment in Kraft linerboard alternatives. The Rhine-Ruhr industrial corridor concentrates automotive tier supplier demand for intra-European freight optimization.
United States
Pharmaceutical distributors in New Jersey and North Carolina prioritize FDA facility sanitation standards for clean-room-adjacent storage. California's SB 54 implementation imposes extended producer responsibility requirements on fiber sourcing verification. The Southeast manufacturing belt absorbs expanding demand from retail consolidation networks seeking foldable configurations.
India
CDSCO serialization mandates for pharmaceutical exports accelerate qualification timelines for ISPM-15-exempt platforms. The country's national pharmaceutical regulator enforces lot-level traceability standards that favor integrated RFID-NFC substrates. Maharashtra's biologics manufacturing cluster in Pune and Mumbai drives custom specification demand for cold-chain transit.
Switzerland
Swissmedic oversight of biologics distribution elevates moisture-barrier specifications for honeycomb-cored constructions. REACH chemical restrictions force adhesive reformulation for cold-chain condensation exposure. The Basel pharmaceutical hub specifies 1,000 kg+ dynamic load platforms that displace plastic composite alternatives through weight advantages.
Netherlands
DHL Supply Chain and Kuehne+Nagel standardize pooled procurement across Rotterdam-Antwerp pharmaceutical corridors. ECHA enforcement of updated chemical restrictions compresses supplier qualification timelines for compliant material streams. The Port of Rotterdam's consolidation centers govern 60% of outbound pallet volume through standardized foldable specifications.
Corrugated Pallets Market Vendor Landscape
Listed leaders compete with private specialists across integrated containerboard supply chains. The vendor base stratifies between multinational converters controlling captive raw material flows and regional fabricators serving niche pharmaceutical specifications. Three archetypes dominate: integrated paperboard-to-converted-products chains, closed-loop recycling specialists, and technology-focused honeycomb engineering firms. Consolidation activity concentrates around containerboard mill acquisitions and pharmaceutical certification portfolio expansion.
Within the integrated converter tier, Smurfit Kappa and DS Smith exemplify archetypes distinguished by supply chain control mechanisms. Smurfit Kappa anchors the upstream-integrated position through captive containerboard production. DS Smith occupies the closed-loop recycling specialist tier with supply security architectures across European distribution networks. International Paper represents the North American scale-driven competitor with mill network coverage.
| Leading Market Players |
|---|
| Smurfit Kappa |
| International Paper |
| DS Smith |
| Mondi Group |
| WestRock |
| Georgia-Pacific |
| Pratt Industries |
| KraftPal Technologies |
| Conitex Sonoco |
| Others |
Supply Flow & Price Mechanics
Honeycomb-cored Kraft linerboard substitution for conventional triple-wall corrugated is simultaneously shifting supply geography toward German and Swiss converter clusters and compressing price premiums previously captured by plastic composite alternatives. This material transition feeds back into procurement economics by enabling automotive and pharmaceutical buyers to negotiate volume contracts at 40% lower unit weight benchmarks while demanding ISPM-15 exemption status as a standard specification.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with pharmaceutical cold-chain specifications commanding the highest tier due to integrated RFID-NFC substrates and moisture-barrier engineering. Price differentiation separates certified ISPM-15-exempt formats from general industrial grades, while volume scale discounts govern automotive tier supplier contracts. Cost compression in standard-grade segments is intensifying because OCC feedstock volatility destabilizes multi-year agreements. Food and beverage distributors exhibit the greatest price sensitivity due to moisture sensitivity constraints limiting outdoor storage applications, whereas pharmaceutical logistics operators prioritize performance specifications over unit cost.
Supply Chain Analysis
Port congestion on Rotterdam-Antwerp pharmaceutical corridors elevates inbound logistics costs for containerboard feedstock destined to Benelux converter networks. Geographic supply concentration centers on Germany, the Netherlands, and Switzerland, where integrated paperboard-to-converted-products chains control captive Kraft linerboard flows. Raw material sourcing draws from Swedish and Finnish pulp mills, German OCC recovery streams, and adhesive chemical suppliers facing REACH reformulation mandates. Single-source vulnerability concentrates in honeycomb engineering expertise held by legacy paperboard specialists. Distribution runs through direct sales channels for pharmaceutical logistics operators and wholesale networks for mid-tier automotive exporters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Corrugated pallet penetration sits in early-cycle expansion across pharmaceutical export corridors, with CDSCO serialization mandates and EU Packaging and Packaging Waste Regulation recyclability thresholds accelerating substitution away from wooden platforms.
For Market Incumbents: Compound backward integration into containerboard production to insulate margin structures from OCC price volatility and secure captive supply for honeycomb-cored specifications. Prioritize certification portfolio expansion for ISPM-15-exempt formats ahead of enforcement deadlines in India and Europe. Defensive positioning requires accelerating adhesive reformulation to REACH-compliant starch-based alternatives before qualification backlogs extend product launch timelines. For New Entrants and Emerging Players: Lead with RFID-NFC integrated custom specifications for Indian pharmaceutical biologics exporters facing CDSCO lot-level traceability mandates. Target Maharashtra's Pune-Mumbai manufacturing cluster where first-mover advantage exists for ISPM-15-exempt export platforms. Pursue digital procurement channel partnerships to serve small-batch pharmaceutical and electronics exporters requiring rapid specification turnaround. For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed honeycomb engineering specialists concentrated in German and Swiss industrial corridors. Long-term viability over the next decade hinges on converter capabilities spanning containerboard supply security and pharmaceutical certification depth. Watch for consolidation signals around containerboard mill acquisitions and ECHA enforcement timelines for adhesive chemistry restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Containerboard Production | Smurfit Kappa and DS Smith stabilize raw material flows against OCC volatility through captive mill networks. |
| REACH-Compliant Adhesive Reformulation | European converters secure qualification ahead of ECHA enforcement deadlines for cold-chain pharmaceutical applications. |
| RFID-NFC Substrate Integration | Custom specification developers capture pharmaceutical cold-chain premiums through real-time lot-level traceability. |
| ISPM-15 Certification Portfolio Expansion | Converters eliminate fumigation delays for BMW, Mercedes-Benz, and chemical exporters in transatlantic corridors. |
| Pooled Procurement Standardization | DHL Supply Chain and Kuehne+Nagel consolidate 60% of Rotterdam-Antwerp pharmaceutical volume through foldable specifications. |
Methodological Framework
A spread of perspectives from pharmaceutical logistics operators, automotive procurement directors, containerboard mill managers, corrugated converter engineers, and regulatory affairs specialists converged on the working assumptions. Primary interviews combined with secondary validation from EU Packaging and Packaging Waste Regulation filings, CDSCO serialization guidance documents, ECHA REACH restriction updates, and SEC disclosures from listed paperboard producers. Bottom-up volume estimates triangulated against top-down addressable market calculations across product type, end user, and application segments.
Segmentation dimensions modeled include product configuration, end-use industry, distribution channel, and application use case across the projection horizon. CAGRs derived from historical trajectory analysis and adoption curve penetration assumptions for ISPM-15-exempt formats in pharmaceutical and automotive export corridors. Forecast inputs incorporated REACH chemical restriction timelines, California SB 54 extended producer responsibility implementation, and RFID-NFC substrate cost curves.
The analysis sits within stated boundaries; outcomes outside sustained pharmaceutical cold-chain expansion, REACH enforcement intensity, and OCC price stability assumptions would require recalibration. Forecasts reflect documented assumptions about substitution rates from wooden and plastic alternatives. Regulatory acceleration or delay in serialization mandates represents the primary revision trigger.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
Corrugated Pallet Wrap Market
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Pallet Wraps Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
Pallet Displays Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
United States Pallet Market
Pallets Packaging
Europe Pallet Wrapping Machine Market
Pallets Packaging
Global Pallet Racking System Market