
 United States Pallet Market | 2026-2036
United States Pallet Market Size, Share, and Industry Trends Forecast 2026-2036
United States Pallet Market Intelligence
Direct-to-warehouse procurement channels are rewriting how pallet suppliers engage large-volume buyers. Brambles Limited (CHEP) leverages its pooled rental network to sustain national coverage without owning every asset node. UFP Industries anchors its position through backward integration into lumber milling, securing fiber supply across the Pacific Northwest and Southern yellow pine belts. Kamps Pallets competes by specializing in recycled and remanufactured wooden units, occupying a cost-advantaged niche in closed-loop supply chains.
A pallet is a portable platform structure, typically constructed from hardwood, softwood, high-density polyethylene, steel, or engineered composites, designed to support goods during handling by forklifts, pallet jacks, or conveyors and to enable unitized load transport. Standard dimensions such as 48 by 40 inches dominate domestic freight compatibility, while load ratings typically range from 2,500 to 5,000 pounds depending on material and stringer configuration. Wooden pallets still lead by volume across food and beverage applications where single-use economics prevail, though plastic pallets are gaining fastest in pharmaceutical cold chains where washability and dimensional stability command premium positioning. Composite segments attract margin-focused buyers seeking durability without full metal weight, particularly in electronics export packaging where ISPM-15 heat treatment compliance adds cost complexity to traditional wood.
The EPA's sustainable materials management framework and OSHA workplace safety standards influence pallet design, with slip-resistant surfaces and maximum stack heights shaping warehouse liability exposure. USDA and FDA food contact regulations drive plastic pallet penetration in protein and dairy processing facilities where porous wood faces sanitation restrictions. Stakeholders must monitor how California's extended producer responsibility legislation and emerging state-level packaging waste rules alter material economics between reusable and single-use platforms.
Market Dynamics
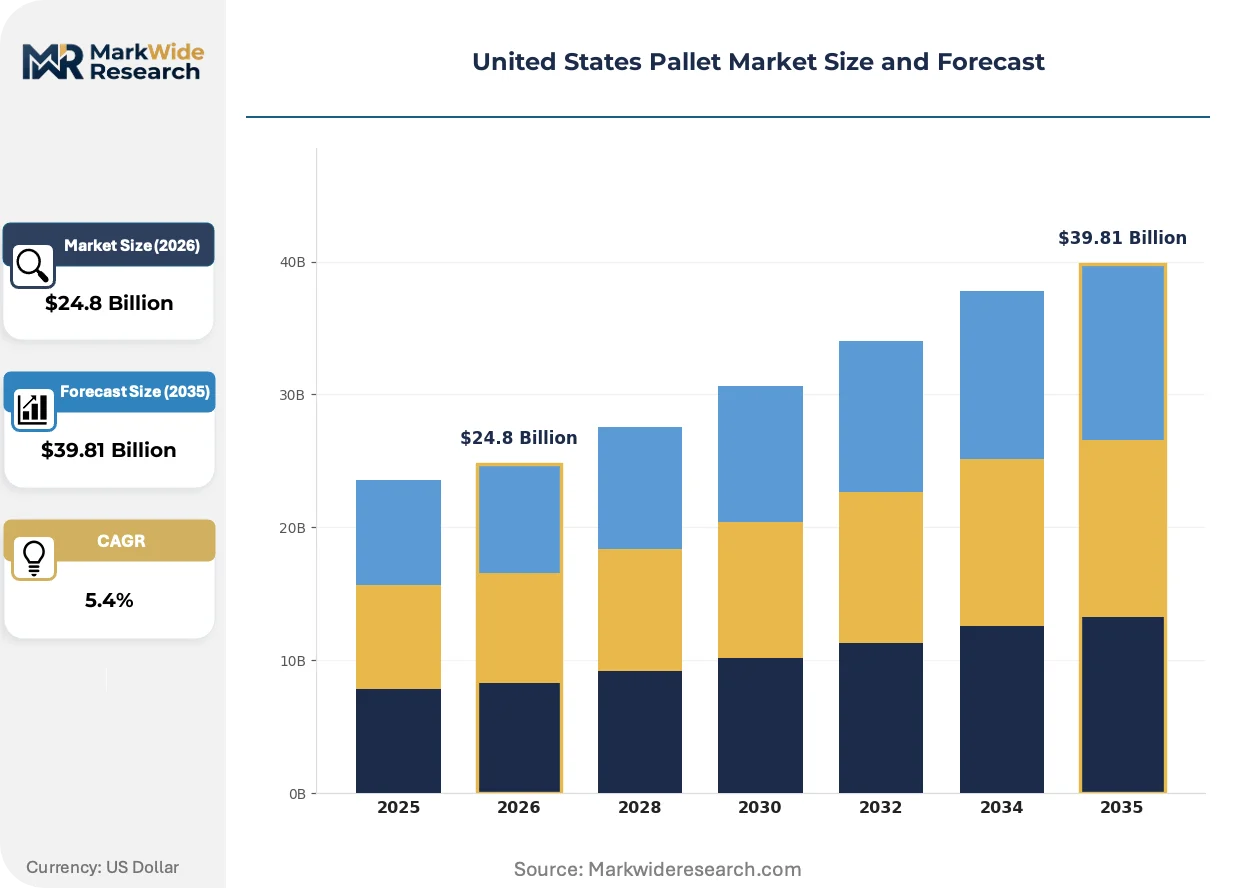
Direct-to-warehouse procurement channels are compressing traditional distributor margins while EPA sustainable materials management priorities force asset lifecycle accountability onto buyers. The tension between pooled rental economics and single-use wood pricing now determines fleet composition across major logistics corridors.
Growth Catalysts
- E-commerce fulfillment expansion:Amazon, Walmart, and Target distribution centers in Texas, Ohio, and California are consuming pallet volumes at rates exceeding traditional retail replenishment cycles.
- FDA food contact regulations:USDA and FDA sanitation mandates in protein and dairy processing are accelerating plastic pallet penetration where porous wood faces compliance barriers.
- RFID-tagged plastic pallets:Pharmaceutical cold chains are adopting sensor-embedded platforms for real-time temperature tracking and dimensional stability in automated storage systems.
Market Restraints
- Southern yellow pine supply concentration:Lumber milling capacity clusters in the Pacific Northwest and Southeast, exposing buyers to regional weather disruptions and freight cost volatility.
- ISPM-15 heat treatment compliance:Export-bound wooden pallets require certified thermal processing, adding cost complexity that disadvantages small-volume shippers.
- Steel pallet weight penalty:Full metal platforms exceed dimensional weight thresholds for air freight, limiting substitution in premium logistics segments.
Strategic Opportunities
- Closed-loop recycling infrastructure:Remanufactured wooden pallet networks in the Midwest offer cost-advantaged positioning against virgin material procurement.
- California extended producer responsibility:Emerging state-level packaging waste rules create first-mover advantage for reusable platform providers with take-back logistics.
- Composite material convergence:Engineered fiber-plastic blends are capturing electronics export applications where ISPM-15 exemption eliminates heat treatment burden.
Industry Challenges
- OSHA stack height compliance:Warehouse operators face liability exposure from slip-resistant surface mandates and maximum vertical storage limits that vary by facility type.
- Legacy WMS integration:RFID-tagged pallets require API connectivity with warehouse management systems that lack standardized data exchange protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Pallet Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $39.81 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Wooden, Plastic, Metal, Composite Size: Standard, Custom, Euro, Half Distribution Channel: Direct Sales, Wholesalers, Retailers, Online Application: Food & Beverage, Electronics, Pharmaceuticals, Clothing |
| Companies Covered | PalletOne, Elkhart Plastics, Brambles Limited (CHEP), New Pig, Kamps Pallets, Rehrig Pacific Company, Meridian, Action Pak, UFP Industries, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Pallet Market Strategic Shifts & Innovations
Asset digitization and material substitution are converging to redefine fleet economics, with sustainability metrics now embedded in procurement scorecards alongside unit cost. Buyers are demanding lifecycle data that rental providers historically treated as proprietary.
RFID-embedded pallet tracking is migrating from high-value pharmaceutical lanes into mainstream grocery and beverage distribution. Kroger and PepsiCo bottlers are piloting sensor networks for inventory velocity optimization. This visibility layer is compressing working capital requirements and enabling dynamic pool sizing that static depreciation models cannot match.
EPA sustainable materials management priorities are redirecting federal procurement toward reusable platforms with verified recycled content thresholds. The framework penalizes single-use wood in favor of pooled rental models with documented environmental product declarations. Food and beverage processors in the Midwest are responding by converting washdown-compatible plastic fleets ahead of anticipated state-level packaging waste rules.
Buyer consolidation among third-party logistics providers is concentrating purchasing power into regional mega-contracts that bypass traditional distributor networks. C.H. Robinson and XPO Logistics are negotiating direct mill relationships for captive pallet supply. This channel compression is most visible in the Ohio and Pennsylvania warehouse corridors where 3PL market share exceeds forty percent of total pallet throughput.
United States Pallet Market Segmentation
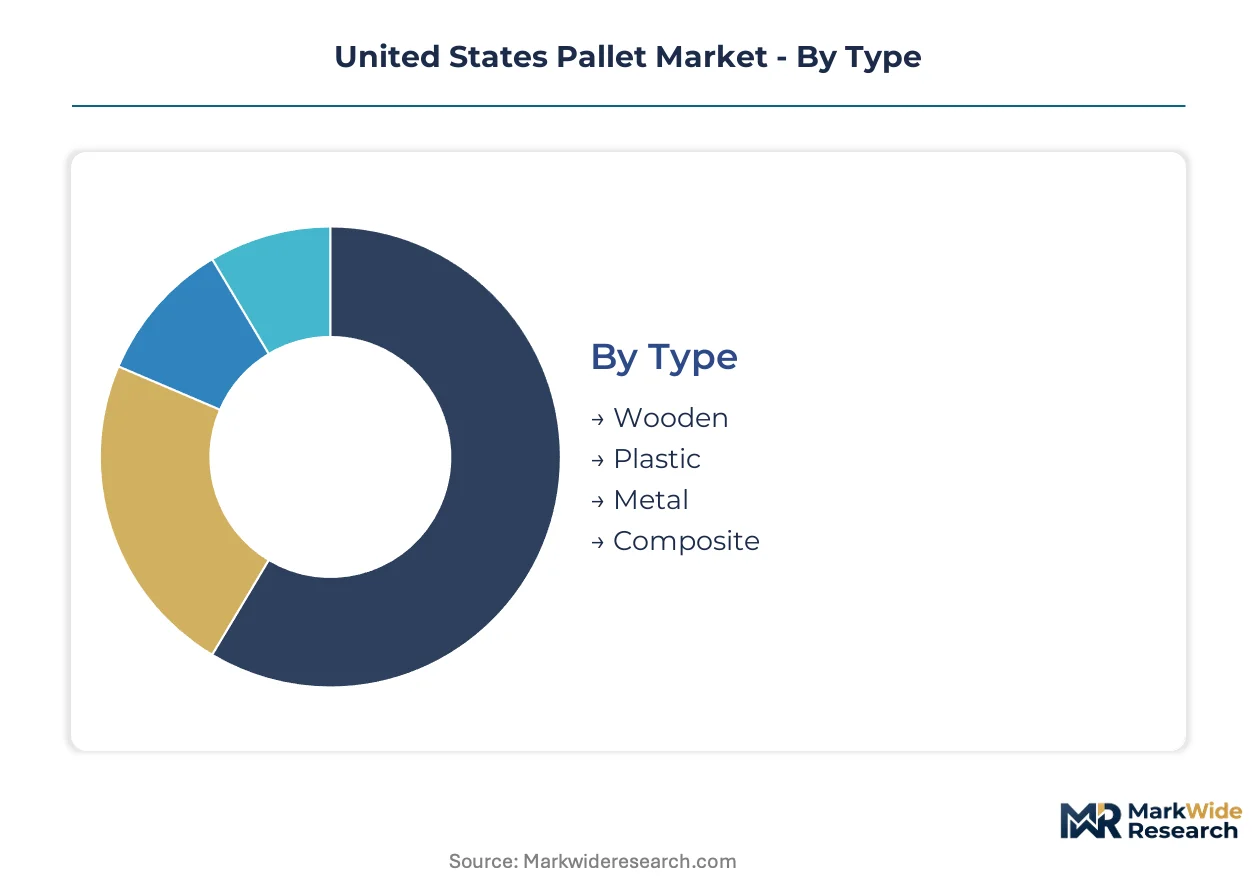
Pallet procurement in the United States fragments across material science, dimensional standards, channel economics, and sector-specific compliance burdens. Each segmentation axis carries distinct margin profiles and capital intensity requirements that shape supplier positioning.
Type:
The use-case spectrum spans single-use export economics to multi-turn rental fleets with embedded sensor networks.
- Wooden:Southern yellow pine and Pacific Northwest hardwood stringers dominate domestic freight corridors. Food and beverage distributors in Texas and Ohio warehouse clusters consume these at highest velocity where single-use economics outweigh retrieval logistics.
- Plastic:High-density polyethylene platforms with RFID embedding command premium positioning in pharmaceutical cold chains. FDA sanitation mandates in protein and dairy processing facilities are displacing porous wood where washdown protocols apply.
- Metal:Steel and aluminum configurations serve automotive and heavy machinery applications requiring load ratings exceeding 5,000 pounds. Weight penalties restrict air freight substitution despite durability advantages.
- Composite:Engineered fiber-plastic blends capture electronics export packaging where ISPM-15 exemption eliminates heat treatment compliance costs.
Established volume favors wooden; emerging adoption favors plastic.
Size:
Dimensional standardization determines forklift fleet compatibility and trailer cube utilization across customer tiers.
- Standard:The 48-by-40-inch GMA specification anchors domestic grocery and retail replenishment networks. Amazon and Walmart distribution centers in California and the Southeast standardize procurement around this footprint to maximize trailer density.
- Custom:Non-standard footprints serve specialized manufacturing equipment and irregular product geometries. Automotive component suppliers in Michigan and Ohio commission these for just-in-time sequencing operations.
- Euro:The 1200-by-800-millimeter dimension facilitates transatlantic freight consolidation for exporters serving European distribution hubs.
- Half:Reduced footprints support retail display stocking and last-mile delivery vehicles where full-size platforms exceed space constraints.
Standard dimensions capture procurement scale; custom formats capture margin premium.
Distribution Channel:
Channel structure reflects buyer scale concentration and inventory velocity requirements across end-use segments.
- Direct Sales:Mill-direct relationships dominate mega-contracts with C.H. Robinson and XPO Logistics in the Ohio-Pennsylvania corridor. These arrangements compress distributor margins while securing volume commitments.
- Wholesalers:Regional distributors serve mid-market manufacturers lacking procurement scale for direct mill negotiation. Inventory pooling reduces lead time exposure for seasonal demand spikes.
- Retailers:Hardware and industrial supply chains offer spot purchasing for small-volume shippers with irregular replenishment patterns.
- Online:Digital procurement platforms emerge for standardized specifications where immediate price transparency outweighs relationship-based sourcing.
Direct channels concentrate volume leverage; wholesaler networks retain fragmentation service.
Application:
Sector-specific compliance regimes and handling intensity create divergent material performance requirements.
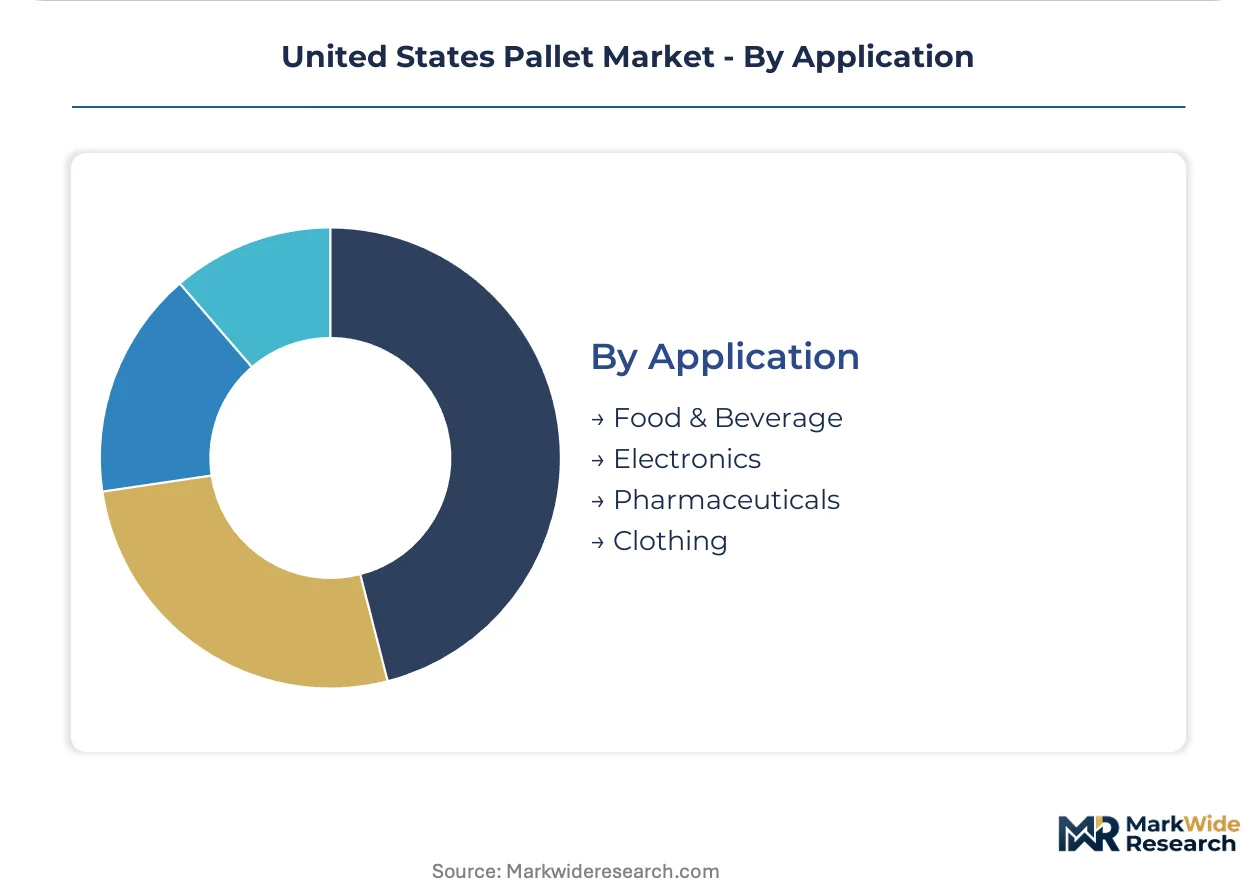
- Food & Beverage:Protein and dairy processors face USDA and FDA sanitation mandates accelerating plastic fleet conversion. Kroger bottlers in the Midwest pilot RFID-tagged platforms for inventory velocity optimization.
- Electronics:Export-bound shipments favor composite or heat-treated wood to satisfy ISPM-15 phytosanitary requirements. Dimensional stability protects high-value components from moisture damage.
- Pharmaceuticals:Cold chain integrity demands sensor-embedded plastic pallets with real-time temperature tracking. Automated storage systems require dimensional precision within tight tolerances.
- Clothing:Apparel distribution centers prioritize lightweight construction for cube-out trailer optimization. Seasonal demand volatility favors rental pool flexibility over captive fleet ownership.
Food and beverage anchors procurement volume; pharmaceuticals drive technology premium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure spending and state-level extended producer responsibility frameworks are redirecting pallet procurement toward reusable platforms with documented lifecycle accountability across major warehouse corridors.
Texas
Amazon and Walmart distribution centers in Dallas-Fort Worth and Houston consume pallet volumes exceeding traditional retail replenishment cycles. EPA sustainable materials management priorities favor pooled rental models with environmental product declarations over single-use wood. The I-35 warehouse corridor from San Antonio to Dallas anchors procurement scale for e-commerce fulfillment networks.
California
Extended producer responsibility legislation and packaging waste rules are accelerating plastic pallet conversion in protein and dairy processing facilities. FDA sanitation mandates displace porous wood where USDA washdown protocols apply. The Inland Empire distribution cluster east of Los Angeles standardizes 48-by-40-inch procurement to maximize trailer density for Pacific Rim exports.
Ohio
C.H. Robinson and XPO Logistics negotiate direct mill relationships for captive pallet supply in the Ohio-Pennsylvania corridor. OSHA workplace safety standards influence maximum stack heights and slip-resistant surface mandates in Cleveland and Columbus warehouse networks. Third-party logistics providers concentrate purchasing power into regional mega-contracts that bypass traditional distributor channels.
Illinois
Kroger bottlers in the Midwest pilot RFID-tagged platforms for inventory velocity optimization. Remanufactured wooden pallet networks offer cost-advantaged positioning against virgin material procurement in Chicago-area closed-loop supply chains. The I-55 distribution spine connects Great Lakes manufacturing to Mississippi River freight corridors.
Pennsylvania
3PL market share exceeds forty percent of total pallet throughput in Philadelphia and Pittsburgh warehouse networks. Direct-to-warehouse procurement channels compress traditional distributor margins while securing volume commitments. Appalachian hardwood stringer supply feeds regional food and beverage distributors where single-use economics prevail.
United States Pallet Market Key Industry Players
On the supply side, the industry is bifurcated between pooled rental network operators and asset-owning manufacturers with captive fiber supply. Consolidation pressures concentrate volume leverage into national accounts, while regional recyclers defend position through closed-loop logistics. Three archetypes dominate: rental pool coordinators with national coverage, vertically integrated lumber millers, and remanufacturing specialists. Competitive moves center on backward integration into raw material sourcing and direct-to-warehouse channel compression.
Within the rental network tier, Brambles Limited exemplifies pooled asset coordination without owning every node. UFP Industries anchors the integrated manufacturing archetype through upstream control over Pacific Northwest and Southern yellow pine supply. Kamps Pallets occupies the remanufacturing specialist position, serving cost-sensitive buyers in Midwest closed-loop supply chains.
| Leading Market Players |
|---|
| PalletOne |
| Elkhart Plastics |
| Brambles Limited (CHEP) |
| New Pig |
| Kamps Pallets |
| Rehrig Pacific Company |
| Meridian |
| Action Pak |
| UFP Industries |
| Others |
Cost & Logistics Intelligence
The I-35 warehouse corridor from San Antonio to Dallas transmits freight cost volatility directly into pallet procurement spreads, with Southern yellow pine supply concentration in the Southeast and Pacific Northwest enabling mill operators to extract premium pricing for certified heat-treated stock while e-commerce fulfillment centers in Texas and Ohio face divergent landed cost structures based on proximity to fiber sources.
Pricing Analysis
Certification level creates the primary spread across the United States Pallet Market, with ISPM-15 heat-treated and FDA-grade plastic platforms commanding substantial premiums over untreated softwood units. Pricing stratifies across premium RFID-embedded plastic fleets, standard GMA-specification hardwood, and economy-grade remanufactured softwood recovered from Midwest closed-loop networks. Cost compression in the economy tier is intensifying because recycled fiber supply expansion outpaces demand growth from small-volume shippers. Third-party logistics providers with mega-contract leverage exhibit the lowest price sensitivity, while independent food distributors in fragmented wholesale channels face the highest procurement cost exposure.
Supply Chain Analysis
ISPM-15 phytosanitary export controls limit untreated wood pallet flows into European and Asia-Pacific destinations, forcing compliance investment that reshapes domestic manufacturing allocation. Raw material supply draws from Southern yellow pine belt sawmills in Georgia and Alabama, Pacific Northwest Douglas fir operations in Oregon and Washington, and imported high-density polyethylene resin for plastic platform production. Single-source vulnerability concentrates in Appalachian hardwood stringer supply for food-grade applications. Distribution runs through direct mill relationships for national account volume, regional wholesaler networks for mid-market coverage, and spot retail channels for emergency replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Pallet Market operates as a substitution defense challenge where plastic platform durability and RFID traceability threaten traditional wooden fleet economics. Incumbents must navigate material substitution pressure from sensor-embedded alternatives while defending position in commodity softwood segments.
For Market Incumbents: Harden backward integration into captive lumber milling across the Pacific Northwest and Southern yellow pine belts to secure fiber cost position against volatile spot markets. Expand closed-loop retrieval infrastructure in Midwest warehouse corridors to defend margin position against remanufacturing specialists. Plastic pallet rental networks with embedded sensor capabilities represent the primary substitution threat requiring fleet modernization investment.
For New Entrants and Emerging Players: Remanufactured pallet services in the Ohio-Pennsylvania corridor represent the most penetrable entry point given fragmented recycler consolidation and 3PL procurement concentration. California extended producer responsibility implementation creates white-space for reusable platform providers with environmental product declaration certification. Go-to-market execution should anchor on direct-to-warehouse channel relationships bypassing traditional distributor markups.
For Investors and Strategic Acquirers: Regional recyclers with established closed-loop logistics in Midwest manufacturing belts offer acquisition exposure to pallet circularity economics. Long-term viability favors asset-light pool coordinators over capital-intensive sawmill operators given sustainability procurement tailwinds. Monitor California packaging waste rule enforcement velocity as inflection indicator for national plastic fleet conversion acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fiber Supply | UFP Industries secures Southern yellow pine cost position against weather-driven volatility. |
| RFID Fleet Digitization | Pharmaceutical cold chain adoption enables real-time inventory velocity optimization. |
| Closed-Loop Retrieval Network Expansion | Kamps Pallets defends margin position through Midwest remanufacturing density. |
| Environmental Product Declaration Certification | EPA federal procurement preference redirects volume toward verified sustainable platforms. |
| Direct-to-Warehouse Channel Compression | C.H. Robinson mega-contracts bypass distributor margins in Ohio-Pennsylvania corridor. |
Research Approach
A spread of perspectives from pallet rental fleet managers, lumber mill procurement directors, 3PL warehouse operations leads, and FDA compliance officers converged on the working assumptions shaping this analysis. Primary fieldwork combined structured interviews with secondary validation through USDA sanitation guidance documents, EPA sustainable materials management frameworks, SEC 10-K filings from listed pallet manufacturers, and customs trade data capturing hardwood import flows. Bottom-up volume modeling triangulated against top-down industry association estimates to constrain forecast variance.
Demand-supply-balance dynamics across material type, dimensional standard, distribution channel, and end-use application anchored the analytical framework throughout the projection horizon. Segmentation dimensions modeled include wooden versus plastic versus composite material science, standard GMA versus custom versus Euro dimensions, direct versus wholesale versus retail channel economics, and food and beverage versus pharmaceutical versus electronics application requirements. CAGRs derived from historical consumption velocity patterns adjusted for e-commerce fulfillment center expansion rates and regulatory compliance cost trajectories. Forecast inputs incorporated Southern yellow pine lumber futures pricing and RFID hardware cost decline curves.
Practitioners should monitor California extended producer responsibility implementation pace, EPA sustainable procurement threshold adjustments, and ISPM-15 enforcement intensity at major ports for early signals of forecast deviation. Material shifts in federal packaging waste legislation or lumber tariff structures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Corrugated Pallet Wrap Market
Pallets Packaging
PUR Shippers Market
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
Pallet Labeler Market
Pallets Packaging
Germany Pallets Market
Pallets Packaging
Pallet Pooling Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
Pallet Collar Market
Pallets Packaging
Pallets Market
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Block Pallets Market
Pallets Packaging
GCC Pallet Market
Pallets Packaging
Palletizer Market