
 Pallet Wrappers Market | 2026-2036
Pallet Wrappers Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Wrappers Market Analytics
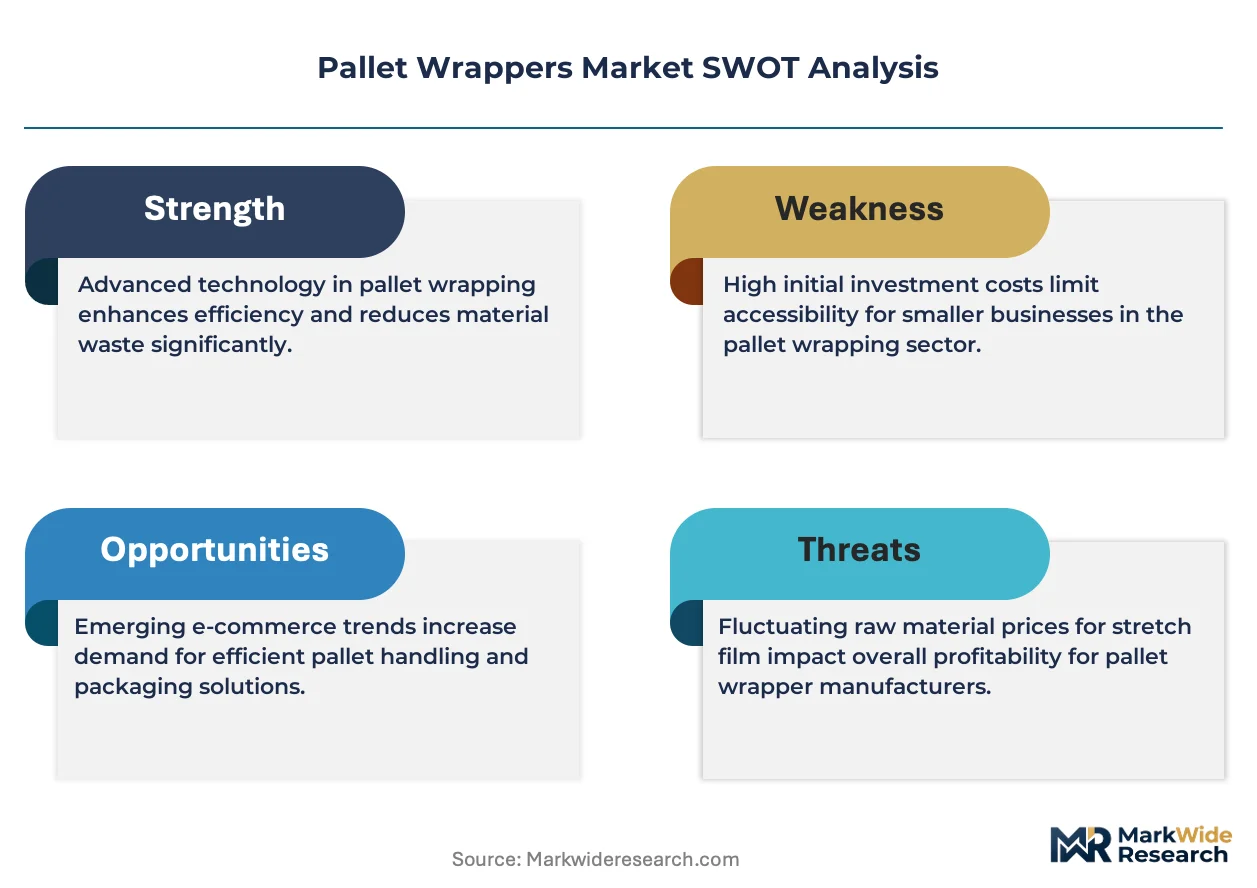
The split between premium and commodity tiers is hardening in the pallet wrappers space. High-throughput rotary systems with integrated weighing and corner-board placement now command fundamentally different procurement cycles than entry-level semi-automatic turntables. Robopac leverages its Italian engineering base to dominate European rotary installations with extended warranty programs. Highlight Industries anchors North American demand through specialized orbital wrapping technology for irregular loads.
Pallet wrappers are machines that apply stretch film, shrink film, or strapping around palletized loads to secure goods during transport and storage, typically achieving pre-stretch ratios of 200-300 percent to optimize material usage and load containment. Their primary purpose is to reduce product damage, improve warehouse safety, and enable unitized handling across supply chains. Automatic systems lead in revenue contribution due to labor substitution economics, while semi-automatic units sustain volume leadership among small and mid-size distributors with intermittent throughput needs. Stretch film technology occupies the dominant share of installed bases, though hybrid systems that combine film wrapping with strapping are gaining traction in beverage and building materials logistics.
FDA regulations govern film materials in food-contact applications, while OSHA standards shape operator-guarding requirements on automatic lines in US facilities. The EU Green Deal and REACH compliance are forcing material suppliers to validate recycled-content films without sacrificing cling and puncture resistance. Stakeholders must monitor how dual carbon goals in China and extended producer responsibility frameworks in Europe redirect capital toward film-thinning R&D and equipment retrofit cycles.
Market Dynamics
Film-thinning mandates under the EU F-Gas Regulation and REACH compliance are compressing material specifications across installed equipment bases, forcing simultaneous retrofit cycles and chemistry validation that reshape capital deployment timelines.
Growth Catalysts
- Automated throughput scaling:Food and beverage distribution centers in Germany are installing rotary systems with integrated weighing to meet e-commerce fulfillment velocity targets.
- EU Green Deal film specifications:Recyclable thin-gauge mandates are accelerating equipment replacement cycles as converters validate new material compatibility.
- Stuttgart-Düsseldorf industrial clustering:Equipment testing grounds in these German manufacturing corridors accelerate European rollout validation for new system architectures.
Market Restraints
- Petrochemical feedstock volatility:Stretch film resin costs fluctuate with crude oil derivatives, compressing converter margins and delaying equipment purchases.
- European supply concentration:Italian engineering bases dominate rotary system manufacturing, creating geographic single-source exposure for warranty and service continuity.
- Pre-stretch ratio ceiling:Current mechanical systems max out near 300 percent pre-stretch, limiting further material optimization without motor and gearing redesign.
Strategic Opportunities
- Orbital wrapping penetration:Irregular load applications in North American building materials logistics remain underpenetrated by specialized orbital technology.
- Hybrid system convergence:Combining stretch film with automated strapping opens beverage and construction verticals previously served by separate equipment lines.
- Extended producer responsibility frameworks:European EPR schemes create capital allocation toward retrofit-compatible equipment designs that accommodate future material streams.
Industry Challenges
- Mechatronics technician scarcity:Automated rotary systems require specialized maintenance skills that outpace vocational training pipeline output in industrial regions.
- Legacy integration complexity:Warehouse management system connectivity demands custom middleware development for semi-automatic turntable retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Wrappers Market |
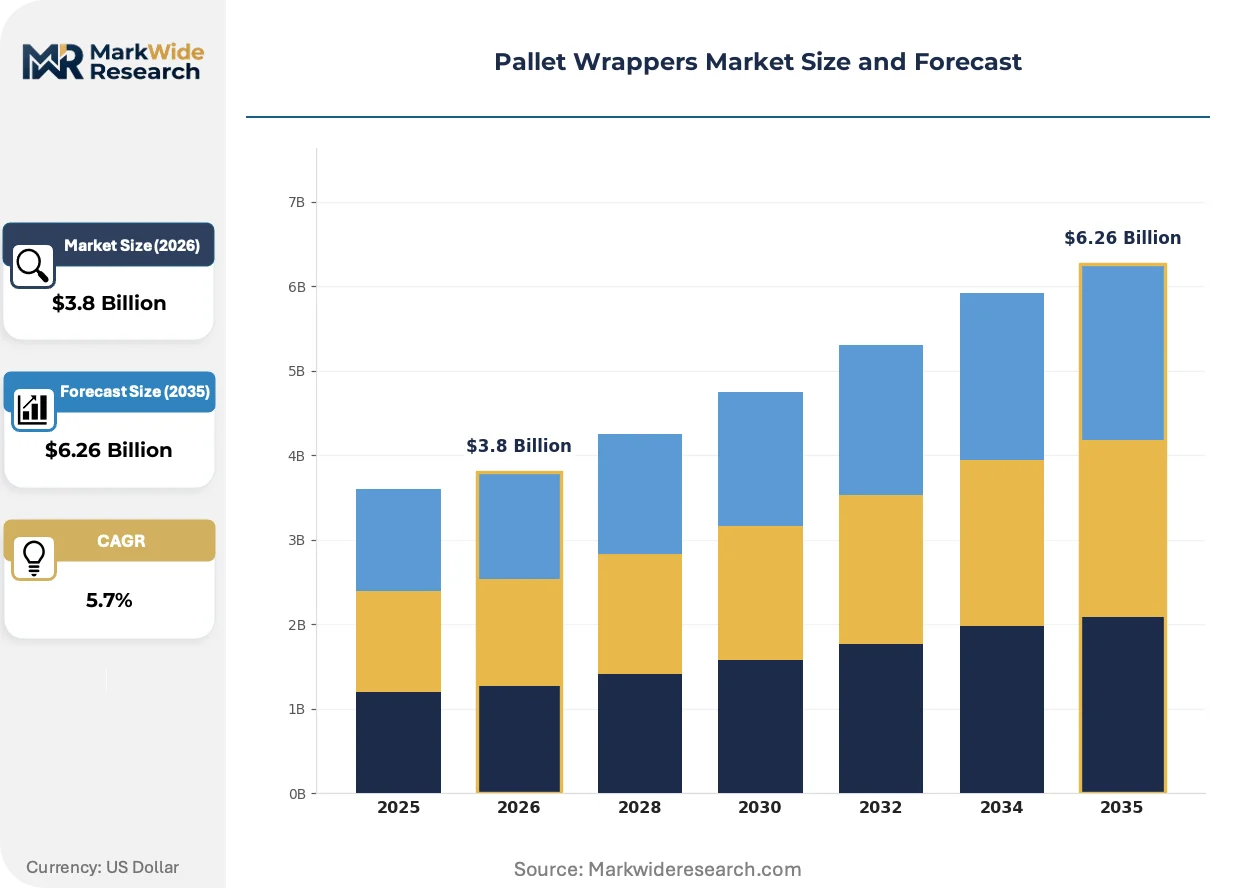
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic, Semi-Automatic, Manual, Rotary End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Technology: Stretch Film, Shrink Film, Hybrid, Strapping Packaging Material: Plastic, Paper, Metal, Others |
| Companies Covered | Highlight Industries, Robopac, Kaufman Engineered Systems, Vestil Manufacturing Corp., PACKWAY INC., Crown Packaging Corp, Orion Packaging Systems LLC, Fhope Packaging Machinery Co., Ltd., Advance Lifts, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Wrappers Market Evolving Landscape
Machine vision and predictive maintenance modules are embedding into wrapping line architectures, shifting competitive differentiation from mechanical reliability to data-enabled uptime guarantees and remote service models.
Vision-guided corner-board placement is automating load stabilization for irregular pallet configurations. Third-party logistics operators in the Netherlands are deploying these systems at throughput rates previously requiring manual intervention. The technology is automating quality consistency previously dependent on operator judgment, compressing labor variance in high-velocity facilities.
REACH substance restrictions and F-Gas phasedown schedules are mandating film chemistry reformulation without performance degradation. European converters must validate recycled-content cling and puncture resistance under compressed timelines. Food-contact applications face the tightest validation windows as EFSA reviews accumulate.
Leasing and equipment-as-a-service models are displacing capital purchase structures among mid-size distributors. German automotive component suppliers now specify uptime-based contracts with bundled film supply. This procurement evolution concentrates vendor relationships around integrated service capabilities rather than discrete equipment transactions.
Pallet Wrappers Market Segmentation
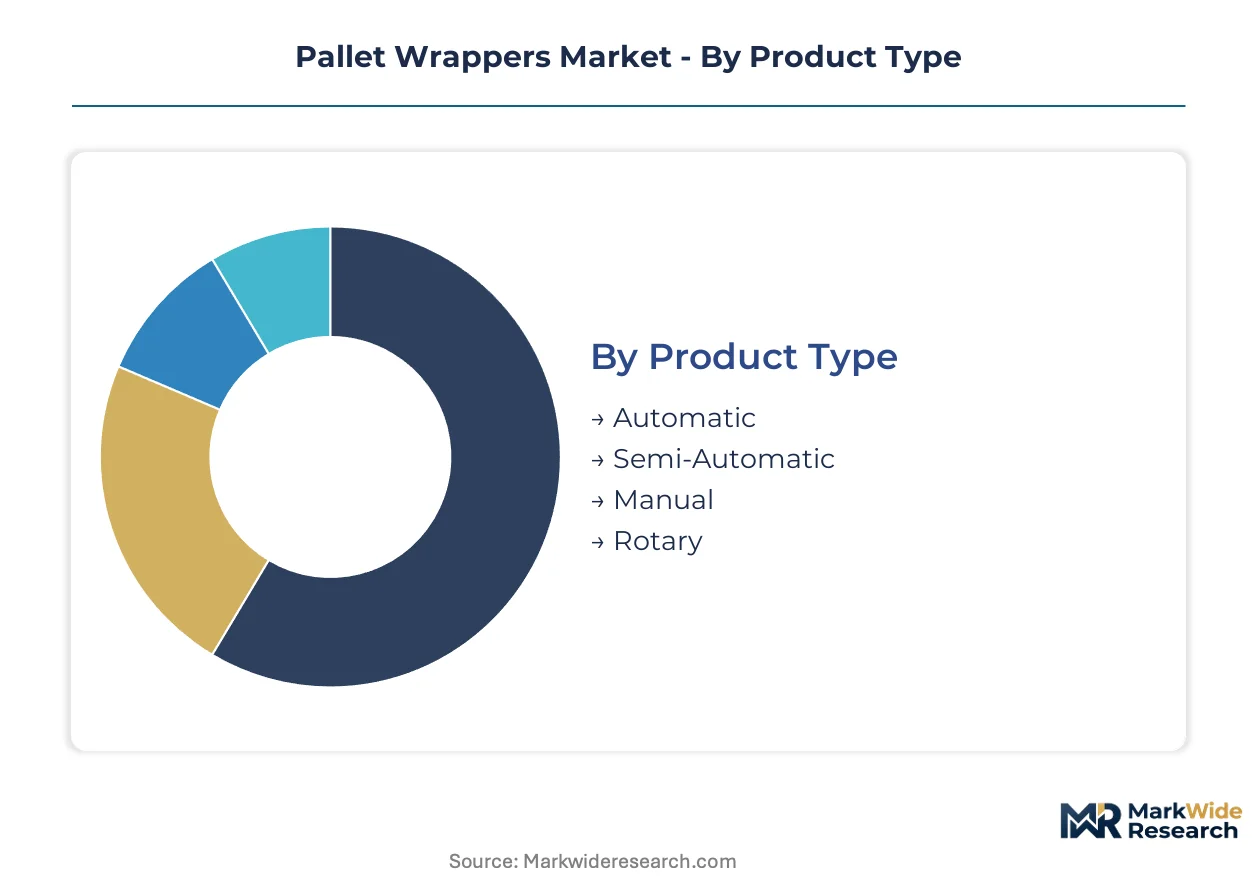
Pallet wrapper segmentation separates integrated production-line systems from standalone warehouse units. Equipment buyers select architectures based on throughput velocity, labor substitution economics, and film chemistry compatibility mandates.
Product Type:
Rotary and automatic systems embed directly into conveyor-fed production lines, while semi-automatic and manual units operate as standalone stations requiring operator intervention for load positioning and cycle initiation.
- Automatic:Conveyor-integrated architectures with powered film carriages achieve 200-300 percent pre-stretch ratios without operator presence. German automotive component suppliers specify these for just-in-sequence lines where palletizing speed matches assembly takt time.
- Rotary:Turntable systems rotate pallet loads while stationary film dispensers apply wrap layers. Food and beverage distribution centers in the Netherlands deploy vision-guided rotary units for mixed-SKU pallets where load configuration varies shipment-to-shipment.
- Semi-Automatic:Operator-activated systems require manual load placement and film attachment. Mid-size third-party logistics operators in Belgium favor these for seasonal volume spikes where capital deployment flexibility outweighs labor cost.
- Manual:Hand-held dispensers with mechanical brake tensioning serve low-throughput applications. Small craft breweries in Denmark use these for export pallet volumes below fifty units weekly.
Rotary systems lead volumes today; automatic architectures are gaining share fastest.
End User:
End-use segmentation tracks contamination sensitivity, regulatory exposure, and throughput consistency requirements across vertical supply chains.
- Food & Beverage:FDA and EFSA compliance demands validate film chemistries for direct and indirect food contact. German dairy cooperatives specify stainless-steel construction and washdown-rated enclosures for cold-chain distribution.
- Pharmaceuticals:Serialization integration and tamper-evident wrapping satisfy EU MDR and US FDA track-and-trace mandates. Swiss contract packaging organizations deploy cleanroom-compatible rotary systems for temperature-sensitive biologics.
- Consumer Goods:High-SKU variability drives demand for quick-change film specifications. French cosmetics distributors prioritize orbital wrapping for irregularly shaped promotional displays.
- Electronics:Electrostatic discharge protection and VCI film compatibility protect semiconductor shipments. Dutch electronics logistics hubs specify ionization bars and conductive film paths for chip pallet movements.
Food and beverage leads volumes today; pharmaceutical end-use is expanding most quickly.
Technology:
Technology selection balances material efficiency, load geometry accommodation, and downstream handling compatibility.
- Stretch Film:Linear low-density polyethylene formulations achieve elastic recovery for load containment. Italian equipment manufacturers dominate pre-stretch carriage engineering for European converter bases.
- Hybrid:Combined stretch film and strapping systems stabilize beverage pallets for multi-modal transport. Austrian brewing conglomerates specify these for rail-truck interchanges where lateral shifting risk concentrates.
- Shrink Film:Heat-applied polyethylene or polyolefin creates unitized protection for weather-sensitive goods. Norwegian seafood exporters use shrink systems for frozen pallet exports to Asian markets.
- Strapping:Polypropylene or steel banding secures heavy building materials where film puncture risk exceeds containment value. German construction supply distributors deploy automated strapping for brick and tile pallet loads.
Stretch film leads volumes today; hybrid configurations are climbing the fastest.
Packaging Material:
Material segmentation reflects EU Green Deal recyclability mandates and feedstock cost volatility exposure.
- Plastic:Linear low-density polyethylene and metallocene grades dominate stretch applications. REACH substance restrictions are forcing rapid validation of recycled-content resins without cling degradation.
- Paper:Kraft and corrugated corner boards supplement film wrapping for edge protection. Swedish furniture retailers specify paper-based stabilization to meet extended producer responsibility scoring.
- Metal:Steel strapping secures extreme-weight loads in metallurgy and construction verticals. Polish steel distributors specify galvanized banding for outdoor storage corrosion resistance.
- Others:Bio-based films and textile strapping serve niche sustainability certifications. Finnish pulp and paper producers trial cellulose-derived stretch alternatives for closed-loop supply chains.
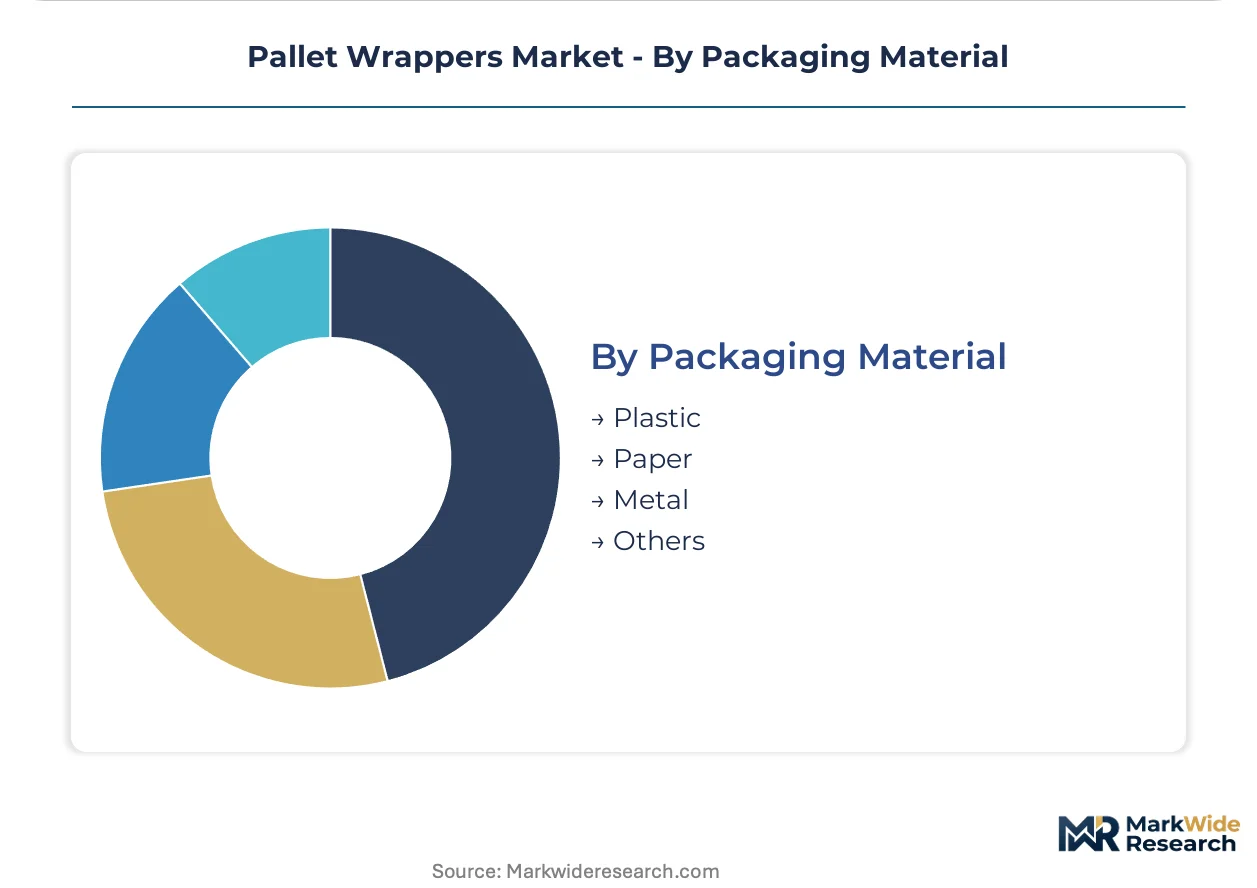
Plastic leads volumes today; paper-based alternatives are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled mechatronics technicians cluster around Stuttgart and Düsseldorf, anchoring European equipment validation and service networks for rotary system deployments.
Germany
Automotive component suppliers in Baden-Württemberg specify just-in-sequence rotary systems matching assembly takt times. The EU F-Gas Regulation mandates film-thinning compatibility testing at Stuttgart-area facilities. Industrial packaging corridors around Düsseldorf serve as European rollout validation grounds for new pre-stretch architectures.
United States
Third-party logistics operators in the Midwest deploy semi-automatic units for seasonal volume flexibility. OSHA standards govern operator-guarding requirements on automatic lines across Michigan and Ohio distribution hubs. Chicago-area beverage distributors anchor North American demand for hybrid stretch-and-strap configurations.
Netherlands
Rotterdam port logistics operators install vision-guided corner-board placement systems for mixed-SKU pallet throughput. REACH compliance deadlines force accelerated recycled-content film validation at converter facilities near the port. Third-party logistics campuses in Venlo test automated wrapping lines for e-commerce fulfillment velocity.
Italy
Engineering-intensive rotary system manufacturers concentrate pre-stretch carriage development in Emilia-Romagna. CE marking requirements shape equipment export certification workflows from Bologna-area production bases. Robopac anchors European warranty and service continuity from its Italian engineering headquarters.
China
Dual carbon goals redirect capital toward film-thinning R&D at Shanghai and Shenzhen equipment testing facilities. The Ministry of Ecology and Environment enforces emissions benchmarks on stretch film resin production. Yangtze River Delta manufacturing clusters validate retrofit-compatible designs for domestic converter bases.
Pallet Wrappers Market Competitive Landscape
Top-tier vendors anchor European rotary installations with extended warranty programs, while mid-tier fabricators compete on semi-automatic flexibility for seasonal distributors. The vendor base separates into engineering-intensive specialists, scale-driven mass producers, and regional service integrators. M&A activity concentrates on mechatronics capability acquisition, while geographic expansion targets underpenetrated North American orbital wrapping applications.
Among North American specialists, Highlight Industries occupies a position exemplifying orbital technology expertise for irregular load geometries. Italian engineering heritage anchors Robopac within the premium rotary tier. Chinese fabricators including Fhope Packaging Machinery Co., Ltd. represent scale-driven production archetypes serving cost-sensitive distributor segments.
| Leading Market Players |
|---|
| Highlight Industries |
| Robopac |
| Kaufman Engineered Systems |
| Vestil Manufacturing Corp. |
| PACKWAY INC. |
| Crown Packaging Corp |
| Orion Packaging Systems LLC |
| Fhope Packaging Machinery Co., Ltd. |
| Advance Lifts, Inc. |
| Others |
Value Network & Pricing Analysis
EU Green Deal thin-gauge film mandates force equipment buyers to validate new material chemistries before procurement, compressing supplier qualification timelines and concentrating pricing power among vendors with integrated testing capabilities.
Pricing Analysis
Bundled equipment-as-a-service contracts are displacing unbundled capital purchases across mid-size distributor segments. Three-tier pricing structure across premium, standard, and economy levels separates extended warranty rotary systems from basic semi-automatic turntables and manual dispensers. Cost compression in entry-level tiers is intensifying because Chinese fabricators are scaling production of simplified architectures. Small craft breweries and seasonal logistics operators exhibit highest price sensitivity, while German automotive suppliers prioritize uptime guarantees over acquisition cost.
Supply Chain Analysis
Dual-sourcing requirements from European distributors mandate multi-supplier qualification for pre-stretch carriages and control systems, fragmenting component procurement across Italian engineering houses and Chinese scale producers. Manufacturing gravity centers on Italy for rotary system engineering, China for cost-sensitive fabrications, and Germany for validation testing. Production draws from linear low-density polyethylene resins, servo motors, and machine vision modules. Single-source vulnerability concentrates in Italian pre-stretch carriage supply. Distribution runs through regional equipment integrators with localized service capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pallet wrapper margins are expanding through film-thinning R&D amortization across installed bases and premium-tier shift toward uptime-based service contracts.
For Market Incumbents: Extend warranty and remote service capabilities to lock in German automotive and Dutch logistics accounts against emerging orbital wrapping specialists. Backward integration into machine vision modules reduces dependency on third-party sensor suppliers. Capacity expansion in Stuttgart-Düsseldorf corridors accelerates European validation cycles for new pre-stretch architectures. For New Entrants and Emerging Players: Regional integrators with beverage industry relationships represent the most penetrable channel partnership for hybrid stretch-and-strap system introduction. North American building materials logistics remains underpenetrated by specialized orbital technology. White-space capture requires demonstrating irregular load containment performance against established rotary alternatives. For Investors and Strategic Acquirers: Asymmetric upside sits with mechatronics capability acquisition targets serving automated rotary maintenance demand. Long-term viability over the next decade hinges on retrofit-compatible equipment designs accommodating recycled-content film streams. Watch for inflection in European extended producer responsibility framework enforcement as capital allocation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Machine Vision Integration | Automated corner-board placement reduces labor variance in Dutch high-velocity facilities. |
| Film-Thinning R&D Partnership | Collaborative chemistry validation accelerates EU Green Deal compliance timelines for converters. |
| Extended Warranty Programs | Italian engineering bases leverage service continuity to dominate European rotary installations. |
| Orbital Technology Licensing | North American building materials penetration requires specialized load geometry expertise. |
| Equipment-as-a-Service Launch | German automotive suppliers now specify uptime-based contracts with bundled film supply. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down equipment installation tracking forms the analytical core of this study. Primary interviews with maintenance directors at German automotive plants, procurement leads at Dutch third-party logistics operators, aftermarket service heads at Italian equipment manufacturers, and plant engineers at Belgian distribution centers combined with secondary validation from SEC filings, customs and trade data, CE marking certification databases, and industry association equipment shipment reports. Triangulation across these sources ensures coverage of both demand-side procurement patterns and supply-side production capacity.
Historical trendline analysis of rotary and automatic system deployment rates, semi-automatic unit placements, and manual equipment retention informed the projection framework across the analysis window. Segmentation dimensions modeled include product architecture, end-use vertical, wrapping technology, and packaging material chemistry. CAGRs were derived from curve-fitting observed installation velocities against macroeconomic indicators and regulatory phase-in schedules. Forecast inputs incorporated EU F-Gas Regulation compliance deadlines and Chinese dual carbon goal implementation pacing.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility and mechatronics technician training pipeline expansion. Deviation in REACH substance restriction timelines or recycled-content film performance validation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Collar Market
Pallets Packaging
Presswood Pallets Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
France Pallets Market
Pallets Packaging
Foldable and Collapsible Pallets Market
Pallets Packaging
Pallet Displays Market
Pallets Packaging
Wooden Pallets Market
Pallets Packaging
Paper Pallet Market
Pallets Packaging
GCC Pallet Market
Pallets Packaging
Pallets Market
Pallets Packaging
Global Wood Pallet Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Europe Lumber Pallet Market
Pallets Packaging
India Pallets Market
Pallets Packaging
Pallet Wraps Market
Pallets Packaging
Palletizer Market